
 Cell Separation Bead Market | 2026-2036
Cell Separation Bead Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Separation Bead Market Insights
The EU Green Deal's push for sustainable bioprocessing is repositioning how European pharmaceutical firms source separation materials. Thermo Fisher Scientific leverages its reagent-instrument bundling to dominate clinical-grade bead supply chains. Miltenyi Biotec anchors its position through proprietary magnetic column technology paired with bead chemistry. Danaher Corporation competes across the workflow via its Life Sciences platform, integrating bead reagents with automated cell sorting instruments.
Cell separation beads are spherical microparticles, typically 1-50 micrometers in diameter, composed of magnetic cores, polystyrene matrices, or glass substrates with surface functionalization for antibody, streptavidin, or protein binding. These beads enable selective capture and release of target cell populations through affinity-based or magnetic separation protocols, serving critical roles in immunology research, stem cell processing, and cell therapy manufacturing. Magnetic beads command the largest revenue share due to their compatibility with automated high-throughput platforms, while functionalized beads represent the fastest-expanding category as multiplexed surface chemistries enable simultaneous positive and negative selection. Among end users, biotechnology companies sustain the steepest procurement growth as CAR-T and gene editing pipelines multiply their need for clinical-scale separation.
The FDA enforces Current Good Manufacturing Practice standards for cell therapy reagents, compelling bead suppliers to validate lot-to-lot consistency and endotoxin limits. The EMA's Advanced Therapy Medicinal Products framework similarly dictates traceability and sterility benchmarks for European suppliers. ISO 13485 quality management certification has become a baseline threshold for market access across both jurisdictions. Stakeholders must monitor how evolving cell therapy regulatory pathways in the United States and Europe will recalibrate bead purity specifications and supplier qualification timelines.
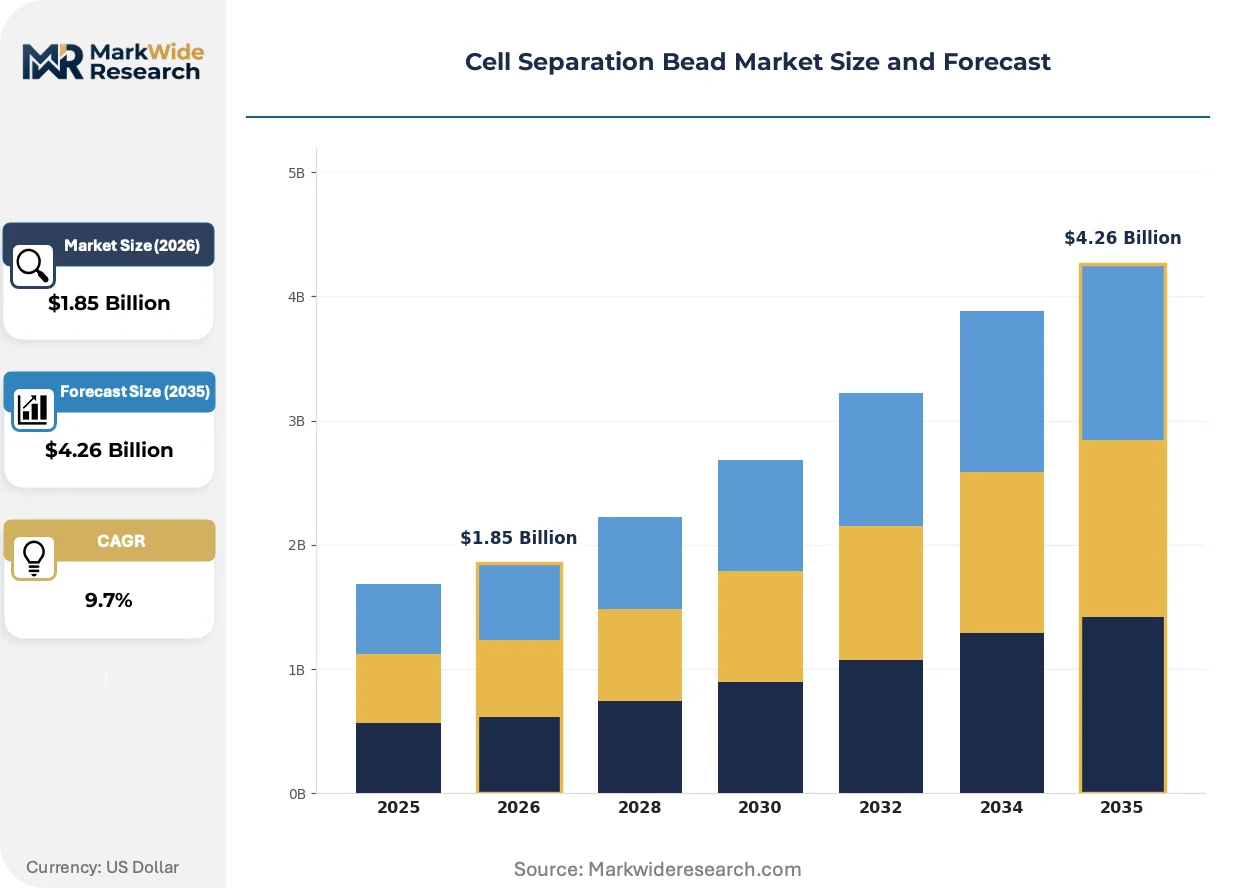
Market Dynamics
The FDA's tightening Current Good Manufacturing Practice standards for cell therapy reagents are compressing supplier qualification timelines and forcing bead manufacturers to validate lot-to-lot consistency at unprecedented granularity.
Growth Catalysts
- CAR-T Manufacturing Scale-Up:Commercial cell therapy pipelines are multiplying demand for clinical-grade magnetic beads capable of processing billions of cells per batch.
- ISO 13485 Certification Mandates:Quality management certification has become a non-negotiable threshold for market access across US and European jurisdictions.
- Automated Platform Integration:Magnetic bead compatibility with high-throughput cell sorting instruments is accelerating adoption in biotechnology manufacturing workflows.
Market Restraints
- Superparamagnetic Iron Oxide Supply Concentration:Raw material sourcing for magnetic bead cores concentrates among a limited set of chemical suppliers, creating input vulnerability.
- Endotoxin Validation Costs:FDA-mandated endotoxin testing for each production lot imposes fixed compliance burdens that disproportionately constrain smaller bead manufacturers.
- Glass Substrate Obsolescence:Polystyrene and magnetic matrices are displacing glass-based beads in affinity separation applications due to superior surface functionalization chemistry.
Strategic Opportunities
- India Cell Therapy Manufacturing:CDSCO's evolving Advanced Therapy Medicinal Products framework creates early-mover advantage for GMP-grade bead suppliers establishing local production.
- Multiplexed Surface Chemistry:Simultaneous positive and negative selection capabilities are opening new application white space in gene editing workflows.
- EU Green Deal Bioprocessing:Sustainable separation material sourcing requirements are repositioning procurement criteria for European pharmaceutical firms.
Industry Challenges
- GMP Compliance Talent Scarcity:Qualified personnel capable of navigating FDA and EMA cell therapy reagent guidelines remain concentrated among incumbent suppliers.
- Legacy Instrument Integration:Bead chemistry optimization for proprietary magnetic column architectures creates technical lock-in that complicates multi-vendor procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Separation Bead Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.26 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Beads, Polystyrene Beads, Glass Beads, Functionalized Beads Application: Cell Isolation, Cell Sorting, Biomolecule Separation, Tissue Engineering End User: Research Laboratories, Clinical Labs, Biotechnology Companies, Pharmaceutical Firms Delivery Mode: Instruments, Reagents, Kits, Others |
| Companies Covered | Thermo Fisher Scientific, Inc., Becton, Dickinson and Company, Danaher Corporation, Merck KGaA, Miltenyi Biotec, STEMCELL Technologies, Inc., Bio-Rad Laboratories, Inc., Agilent Technologies, Inc., Corning Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Separation Bead Market Trends and Innovations
Surface functionalization chemistry is undergoing rapid iteration as multiplexed bead architectures enable simultaneous capture and release protocols that were previously sequential.
Next-generation streptavidin-coated magnetic beads are modularizing cell separation workflows by decoupling capture chemistry from magnetic separation hardware. Biotechnology companies manufacturing CAR-T therapies are adopting these architectures fastest, integrating them into automated processing lines. This modularity is compressing the traditional vendor lock-in that paired specific bead chemistries with proprietary instrument platforms.
REACH regulation updates governing nanomaterial classification are recalibrating how European bead suppliers characterize and register sub-50-micrometer particles. The ECHA's evolving substance evaluation framework is extending compliance timelines for novel surface chemistries. Functionalized bead categories face the steepest documentation burdens, prompting some suppliers to prioritize established antibody-binding chemistries over experimental conjugates.
Biotechnology procurement teams are consolidating vendor relationships around reagent-instrument bundles that guarantee interoperability. The previous model of sourcing beads, columns, and sorters separately is retreating fastest among mid-scale cell therapy manufacturers. This concentration is most visible in the United States, where Boston and San Diego biotech clusters have standardized on integrated workflow contracts.
Cell Separation Bead Market Segmentation
Cell separation bead procurement patterns diverge sharply across product architectures, therapeutic applications, and end-user scale. Understanding these segment boundaries clarifies where GMP-grade specifications command premium positioning versus where research-grade materials suffice.
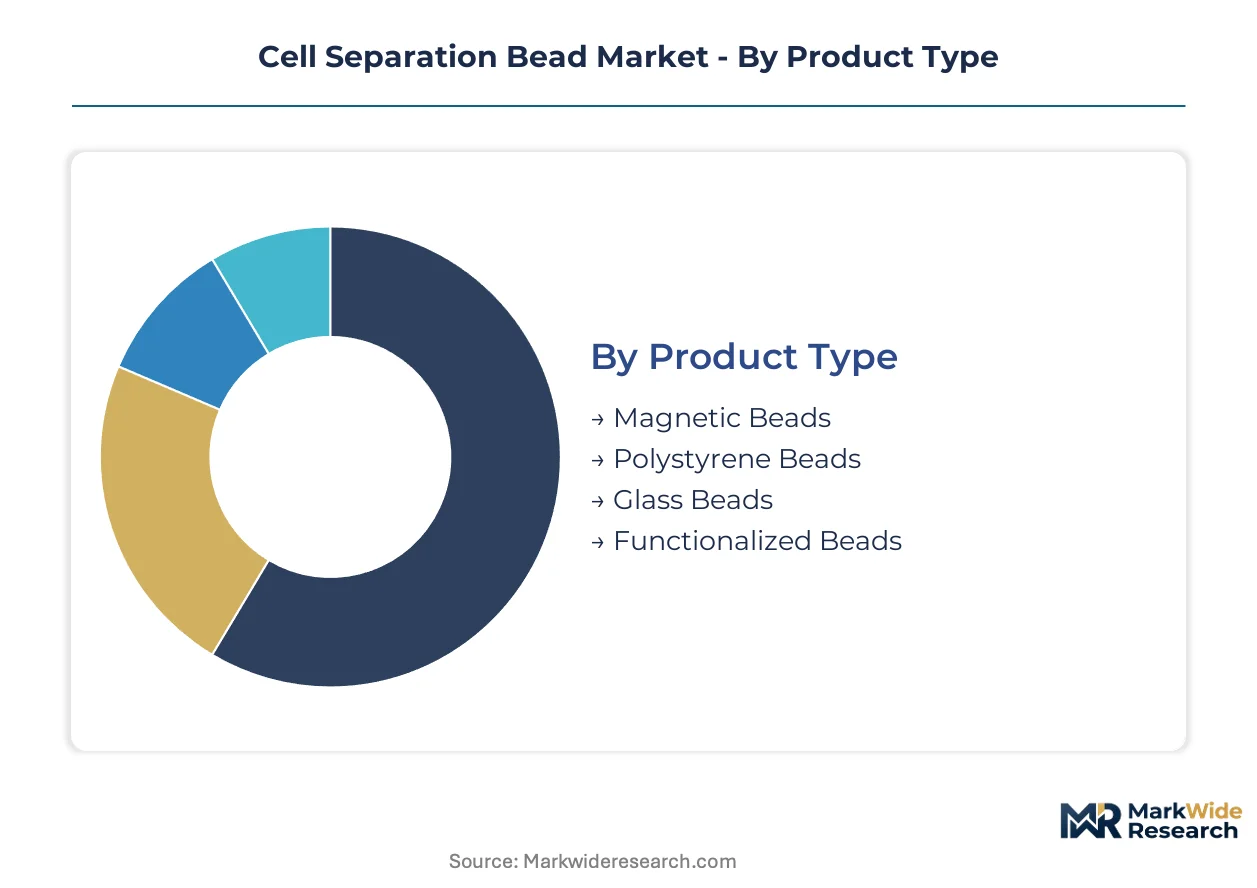
Product Type:
Magnetic core composition and surface functionalization chemistry define performance ceilings for automated workflows.
- Magnetic Beads:Superparamagnetic iron oxide cores coated with dextran or polymer matrices enable rapid separation under external magnetic fields. Demand concentrates in United States biotechnology manufacturing, where CAR-T producers require batch consistency across billion-cell processing runs.
- Functionalized Beads:Antibody-conjugated, streptavidin-coated, and protein-binding surface chemistries support multiplexed capture protocols. European pharmaceutical procurement teams prioritize these for gene editing workflows under EU Green Deal sustainable sourcing mandates.
- Polystyrene Beads:Hydrophobic polymer matrices suit hydrophobic interaction chromatography and basic affinity separations in research settings.
- Glass Beads:Silica-based substrates retain niche use in nucleic acid binding applications where surface charge density matters.
Mature deployment sits with magnetic architectures. Newer deployment is concentrated in functionalized surface chemistries.
Application:
Clinical versus research use cases impose divergent purity and documentation requirements on bead specifications.
- Cell Isolation:Positive and negative selection protocols for T cells, stem cells, and tumor-infiltrating lymphocytes demand clinical-grade endotoxin validation. Biotechnology companies in Boston and San Diego drive procurement volume for immunotherapy manufacturing.
- Cell Sorting:High-throughput fluorescence-activated and magnetic-activated sorting integrates bead-based pre-enrichment steps. Academic medical centers combine these workflows with downstream genomic analysis.
- Biomolecule Separation:Protein and nucleic acid purification applications favor polystyrene and glass substrates where magnetic separation adds unnecessary cost.
- Tissue Engineering:Scaffold seeding and organoid construction use beads for temporary cell positioning before enzymatic release.
Volume concentration favors cell isolation. Fastest application expansion is occurring in cell sorting for automated manufacturing lines.
End User:
Regulatory exposure and procurement scale create distinct customer tiers with incompatible vendor qualification timelines.
- Biotechnology Companies:Cell therapy developers require ISO 13485-certified bead lots with full traceability documentation. FDA pre-approval inspection readiness dictates supplier selection above price considerations.
- Pharmaceutical Firms:Large-scale gene therapy manufacturing operations negotiate multi-year reagent supply agreements with embedded instrument interoperability guarantees.
- Research Laboratories:Academic and government labs prioritize catalog breadth and rapid delivery over GMP documentation.
- Clinical Labs:Hospital-based cell processing units operate under CLIA guidelines with moderate regulatory burden between research and commercial manufacturing.
Procurement sophistication peaks with biotechnology companies. Price sensitivity concentrates in research laboratory segments.
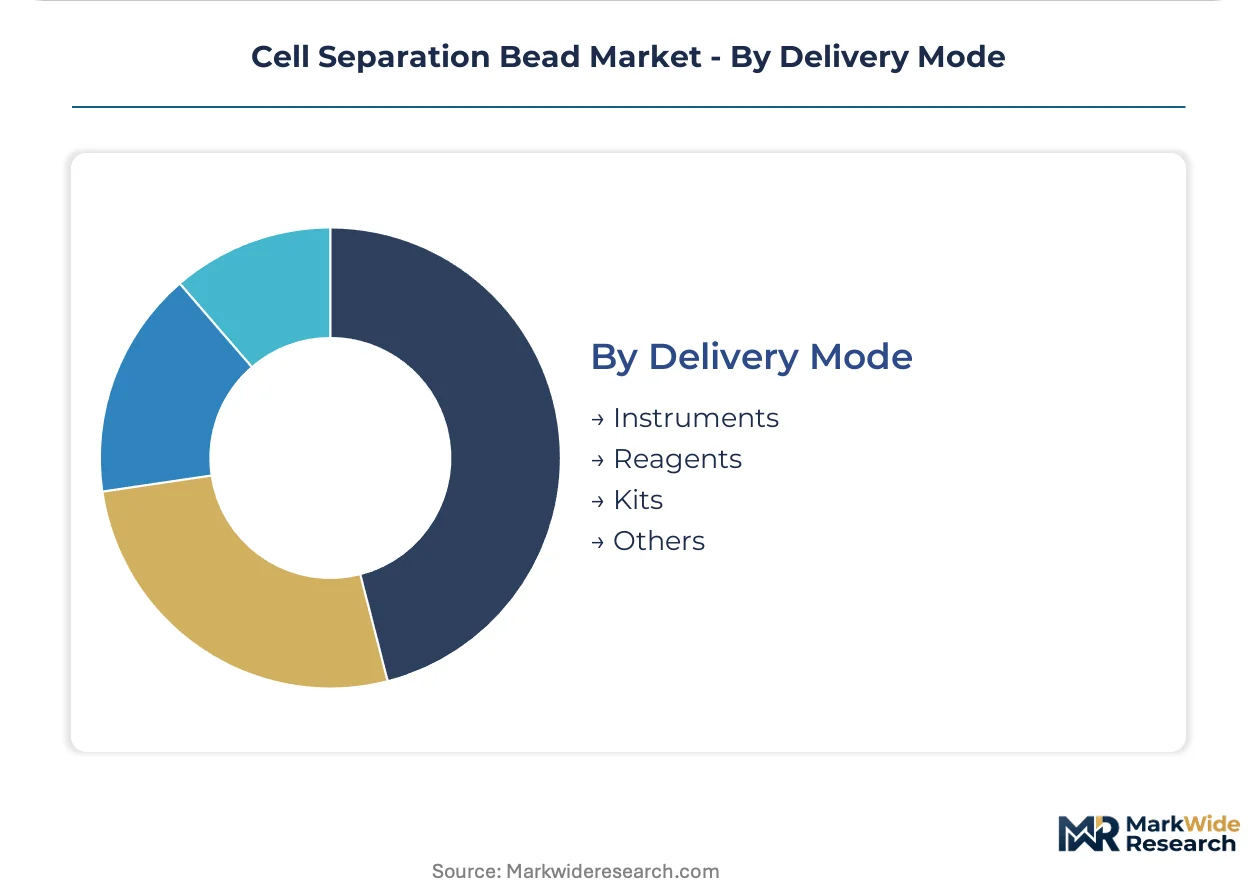
Delivery Mode:
Packaging and integration depth determine workflow friction and total cost of ownership calculations.
- Reagents:Bulk bead suspensions in standard buffer formulations allow maximum protocol flexibility for established manufacturing operations.
- Kits:Pre-validated buffer sets, column consumables, and protocol cards accelerate deployment for new therapeutic programs.
- Instruments:Automated magnetic separation platforms bundle proprietary bead chemistries, creating technical lock-in that simplifies vendor management.
- Others:Custom conjugation services and OEM supply arrangements serve specialized research applications.
Standardized procurement flows through reagent channels. Bundled instrument adoption is climbing fastest among mid-scale manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston and San Diego biotech clusters anchor the highest concentration of GMP-grade cell separation bead procurement worldwide, driven by commercial CAR-T manufacturing scale-up and FDA pre-approval inspection timelines.
United States
FDA Current Good Manufacturing Practice standards for cell therapy reagents compress supplier qualification timelines for biotechnology companies. The agency's evolving guidance on cell and gene therapy products tightens endotoxin limits and lot-to-lot consistency validation. Boston's Seaport District and San Diego's Torrey Pines corridor host the steepest procurement growth as cell therapy developers establish commercial manufacturing lines.
Germany
EMA Advanced Therapy Medicinal Products framework dictates traceability and sterility benchmarks for bead suppliers serving European pharmaceutical firms. REACH regulation updates governing nanomaterial classification extend compliance timelines for novel surface chemistries. The Rhine-Main biotech cluster around Frankfurt and Heidelberg concentrates demand for ISO 13485-certified functionalized beads in gene editing workflows.
India
CDSCO's evolving Advanced Therapy Medicinal Products framework creates early-mover positioning for GMP-grade bead suppliers establishing local production. The regulator's quality management certification requirements align with international standards for cell therapy reagents. Hyderabad's Genome Valley and Bengaluru's Electronic City biotech parks attract procurement investment as contract development organizations expand cell therapy manufacturing capacity.
Japan
PMDA guidelines for regenerative medicine products impose documentation requirements on separation material suppliers comparable to FDA and EMA standards. METI initiatives support domestic bioprocessing infrastructure development for cell therapy commercialization. The Kanto region around Tokyo and the Kansai corridor anchored by Osaka concentrate pharmaceutical firm procurement of clinical-grade magnetic beads.
Switzerland
Swissmedic's quality management requirements for advanced therapy medicinal products align bead supplier qualification with EMA benchmarks while maintaining distinct national certification pathways. The regulator's inspection protocols emphasize lot release documentation for critical reagents. Basel's pharmaceutical corridor hosts concentrated procurement as gene therapy developers integrate bead-based separation into automated manufacturing workflows.
Cell Separation Bead Market Competitive Landscape
The competitive structure tilts toward integrated workflow bundling among incumbent life sciences conglomerates. Three to five diversified reagent-instrument platforms command the clinical-grade segment, while specialized bead chemistry developers occupy research and custom conjugation niches. Market consolidation concentrates procurement decision-making around multi-year supply agreements with embedded interoperability guarantees. Dominant competitive moves include strategic partnerships between bead manufacturers and automated cell sorting platform developers, plus geographic expansion into emerging cell therapy manufacturing jurisdictions.
Among diversified life sciences platforms, Thermo Fisher Scientific, Danaher Corporation, and Miltenyi Biotec exemplify contrasting archetypes. Thermo Fisher leverages reagent-instrument bundling to dominate clinical-grade supply chains. Danaher competes across workflows via integrated life sciences platforms. Miltenyi anchors positioning through proprietary magnetic column technology paired with bead chemistry. These three represent the spectrum from broad portfolio diversification to specialized workflow integration.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Becton, Dickinson and Company |
| Danaher Corporation |
| Merck KGaA |
| Miltenyi Biotec |
| STEMCELL Technologies, Inc. |
| Bio-Rad Laboratories, Inc. |
| Agilent Technologies, Inc. |
| Corning Incorporated |
| Others |
Pricing and Supply Chain Analysis
FDA-mandated endotoxin validation for clinical-grade magnetic beads is compressing supplier margins and forcing raw material sourcing into certified chemical networks that command premium positioning. This specification tightening propagates through procurement contracts as biotechnology companies prioritize lot-to-lot consistency over unit cost in CAR-T manufacturing workflows.
Pricing Analysis
Yield-guaranteed throughput pricing anchors clinical-grade magnetic bead contracts, with biotechnology companies paying premiums for validated billion-cell batch performance. Pricing stratifies across GMP-certified, ISO 13485-compliant, and research-grade tiers, with certification level and volume scale as primary differentiation drivers. Cost compression in research-grade polystyrene beads is intensifying because glass substrate obsolescence has flooded secondary markets with displaced inventory. Academic laboratories exhibit highest price sensitivity, while cell therapy developers treat endotoxin documentation as non-negotiable.
Supply Chain Analysis
ISO 13485 certification gating concentrates qualified bead manufacturing in the United States, Germany, and Japan, where FDA, EMA, and PMDA alignment creates mutual recognition efficiencies. Superparamagnetic iron oxide cores, dextran coating polymers, and streptavidin conjugates constitute critical input dependencies. Single-source vulnerability in superparamagnetic iron oxide supply creates structural risk for magnetic bead producers. Distribution runs through direct reagent contracts with biotechnology manufacturers, with kit bundling gaining share among mid-scale cell therapy developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multiplexed surface chemistry architectures are displacing legacy single-capture bead protocols, compressing the vendor lock-in that previously protected incumbent positions. This transition phase rewards suppliers who modularize surface functionalization from magnetic separation hardware.
For Market Incumbents: Cement workflow bundling advantages by integrating next-generation streptavidin-coated beads with automated cell sorting platforms. Threat from modular bead architectures that decouple chemistry from hardware demands defensive certification investments in ISO 13485 lot-to-lot validation capabilities. Channel control through multi-year reagent supply agreements with embedded instrument interoperability guarantees represents the critical defensive lever.
For New Entrants and Emerging Players: The mid-tier pricing gap between premium GMP-certified beads and economy research-grade materials offers entry positioning for ISO 13485-compliant specialists. India cell therapy manufacturing expansion under CDSCO's evolving framework presents the most penetrable geography. Custom conjugation services for gene editing workflows offer a specific go-to-market angle that bypasses incumbent instrument lock-in.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized bead chemistry developers possessing validated surface functionalization IP given accelerating procurement consolidation around reagent-instrument bundles. Long-term viability over the coming decade hinges on regulatory pathway alignment across FDA, EMA, and emerging CDSCO frameworks. Acquisition targets should demonstrate ISO 13485 certification with documented lot release protocols. The signal to watch as inflection indicator is CDSCO's finalization of GMP equivalence recognition for imported clinical-grade beads.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | FDA pre-approval inspection readiness secures biotechnology procurement contracts above price competition. |
| Modular Surface Chemistry Development | Streptavidin-coated architectures decouple capture chemistry from Miltenyi magnetic column lock-in. |
| India Local Production Establishment | CDSCO's evolving ATMP framework rewards early GMP-grade bead suppliers with qualification timeline advantages. |
| Automated Platform Integration Partnership | Thermo Fisher's reagent-instrument bundling model demonstrates procurement consolidation trajectory. |
| Sustainable Sourcing Certification | EU Green Deal bioprocessing mandates reposition European pharmaceutical procurement criteria. |
Research Methodology
Document review covered FDA guidance documents, EMA Advanced Therapy Medicinal Products framework updates, CDSCO regulatory circulars, and ISO 13485 certification databases, complemented by interviews with cell therapy manufacturing executives, regulatory affairs specialists at bead suppliers, biotechnology procurement managers, and academic laboratory directors. Secondary validation drew from SEC 10-K filings of diversified life sciences platforms, clinical trial registration databases, and customs trade data for superparamagnetic iron oxide imports. Bottom-up bead volume estimates were triangulated against top-down cell therapy manufacturing capacity projections.
Cross-referencing historical procurement patterns against expert panel input anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include bead core composition, surface functionalization chemistry, therapeutic application, end-user regulatory exposure, and regional certification cluster. CAGRs were derived from weighted capacity expansion timelines and therapeutic pipeline advancement rates. Forecast inputs incorporated CAR-T manufacturing scale-up trajectories and evolving FDA endotoxin limit specifications.
Inputs from regulatory filing databases and supplier certification records were available through the study window; gaps in real-time biotechnology procurement contract terms introduce uncertainty bands around price trajectory assumptions. Forecasts reflect documented qualification timelines and supplier concentration patterns. A model refresh is warranted upon material change in FDA cell therapy reagent guidance or CDSCO GMP equivalence recognition protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Genetic Analyzer Systems Market
Biotechnology Equipment
Global Life Science Reagents Market
Biotechnology Equipment
US Cell Culture Media Market
Biotechnology Equipment
Cell Culture Protein Surface Coating Market
Biotechnology Equipment
Rocking Bioreactors Market
Biotechnology Equipment
Laboratory Andrology Equipment Market
Biotechnology Equipment
Global Polymerase Chain Reaction (PCR) Consumables Market
Biotechnology Equipment
Global Bioprocess Container Market
Biotechnology Equipment
Cellbag Bioreactor Chambers Market
Biotechnology Equipment
Cryopreservation Equipment Market
Biotechnology Equipment
Global Life Sciences Tools Market
Biotechnology Equipment
Biobanking Equipment Market
Biotechnology Equipment
Biomaterial Tester Market
Biotechnology Equipment
Plant Genotyping Equipment Market
Biotechnology Equipment
Biobank Equipment Market
Biotechnology Equipment
Global Photobiostimulation Devices Market