
 Global Biotechnology Market | 2026-2036
Global Biotechnology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biotechnology Market Analysis
Specialized biologics manufacturing talent is reorganizing competitive dynamics across the Global Biotechnology Market. Amgen Inc. leverages its deep protein engineering expertise to sustain leadership in therapeutic biologics. Novartis AG anchors its position through advanced cell and gene therapy platforms. F. Hoffmann-La Roche Ltd dominates diagnostic innovation, extending its influence from research tools into clinical decision support.
Biotechnology applies living organisms, cellular components, and biomolecular processes to develop products with defined specifications such as monoclonal antibody purity exceeding 95% and viral vector titers measured in particles per milliliter. Its primary purpose spans drug discovery, agricultural trait engineering, and industrial biocatalysis. Biopharmaceuticals capture the dominant margin pool as complex protein therapies command premium pricing, while genomics segments are expanding fastest as CRISPR-based platforms move from research into regulated therapeutic applications. Diagnostic tools remain mature with stable revenue but lower growth velocity compared to emerging biomaterials for regenerative medicine.
FDA accelerated approval pathways and EMA adaptive licensing frameworks are reshaping how biotech products reach patients, compressing traditional phase timelines while demanding stronger real-world evidence commitments. China's NMPA has aligned its biologics review standards with ICH guidelines, opening market access for multinational innovators. ISO 13485 and GMP standards govern manufacturing quality across jurisdictions, creating compliance barriers that favor firms with established quality systems. Stakeholders must monitor how gene therapy reimbursement negotiations evolve as payers confront single-treatment cures with multi-million-dollar price tags.
Market Dynamics
Gene therapy manufacturing capacity constraints are compressing competitive timelines as sponsors race to secure viral vector production slots before regulatory submissions. Contract development organizations with GMP-certified gene therapy suites command 18-24 month booking lead times, forcing strategic decisions about in-house build versus outsourced supply.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses phase 3 timelines for breakthrough therapies, enabling earlier revenue recognition for sponsors with strong biomarker data. Oncology and rare disease applications dominate the queue.
- CRISPR Platform Expansion:Base editing and prime editing variants are opening therapeutic targets previously inaccessible to first-generation nucleases. Sickle cell and beta-thalassemia programs validate the clinical translation.
- Boston-Cambridge Cluster:Concentrated venture deployment and Harvard-MIT talent pipelines sustain the region's dominance in preclinical-stage biologics innovation. The density reduces founder recruitment friction.
Market Restraints
- Plasmid DNA Supply:Viral vector manufacturing depends on high-quality plasmid inputs produced by a concentrated supplier base in North America and Europe. Capacity expansion lags demand growth by 3-4 years.
- EMA Adaptive Licensing:The framework demands extensive real-world evidence commitments that extend post-approval cost obligations. Smaller sponsors face liquidity strain from prolonged evidence generation.
- Allogeneic Cell Therapy:Off-the-shelf approaches threaten autologous CAR-T economics by promising manufacturing scale and pricing compression. Autologous players must defend logistical advantages.
Strategic Opportunities
- India CDMO Expansion:The country's national pharmaceutical regulator has harmonized biologics standards with ICH guidelines, opening inspection pathways for export-oriented manufacturing. Cost structures undercut Western facilities by 40-60%.
- Continuous Bioprocessing:Perfusion cell culture integrated with continuous capture chromatography promises 3-5x productivity gains over batch platforms. Early adopters are securing process patents.
- EU Green Deal Alignment:Biotech facilities with renewable energy sourcing and solvent recycling systems qualify for preferential financing under the EU taxonomy. Sustainability credentials are becoming tender requirements.
Industry Challenges
- Cell Therapy Manufacturing Scientists:The specialized workforce combining GMP compliance with living-cell handling remains scarce. Training programs require 18-24 months to produce production-ready staff.
- ISO 13485 Certification Timelines:In vitro diagnostic companion devices for personalized therapies face 12-18 month quality system audits. Parallel device-drug development programs struggle to synchronize submissions.
- Legacy ERP Integration:Biotech sponsors acquiring manufacturing assets confront data architecture mismatches between R&D systems and commercial-scale MES platforms. Migration risks batch record integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biotechnology Market |
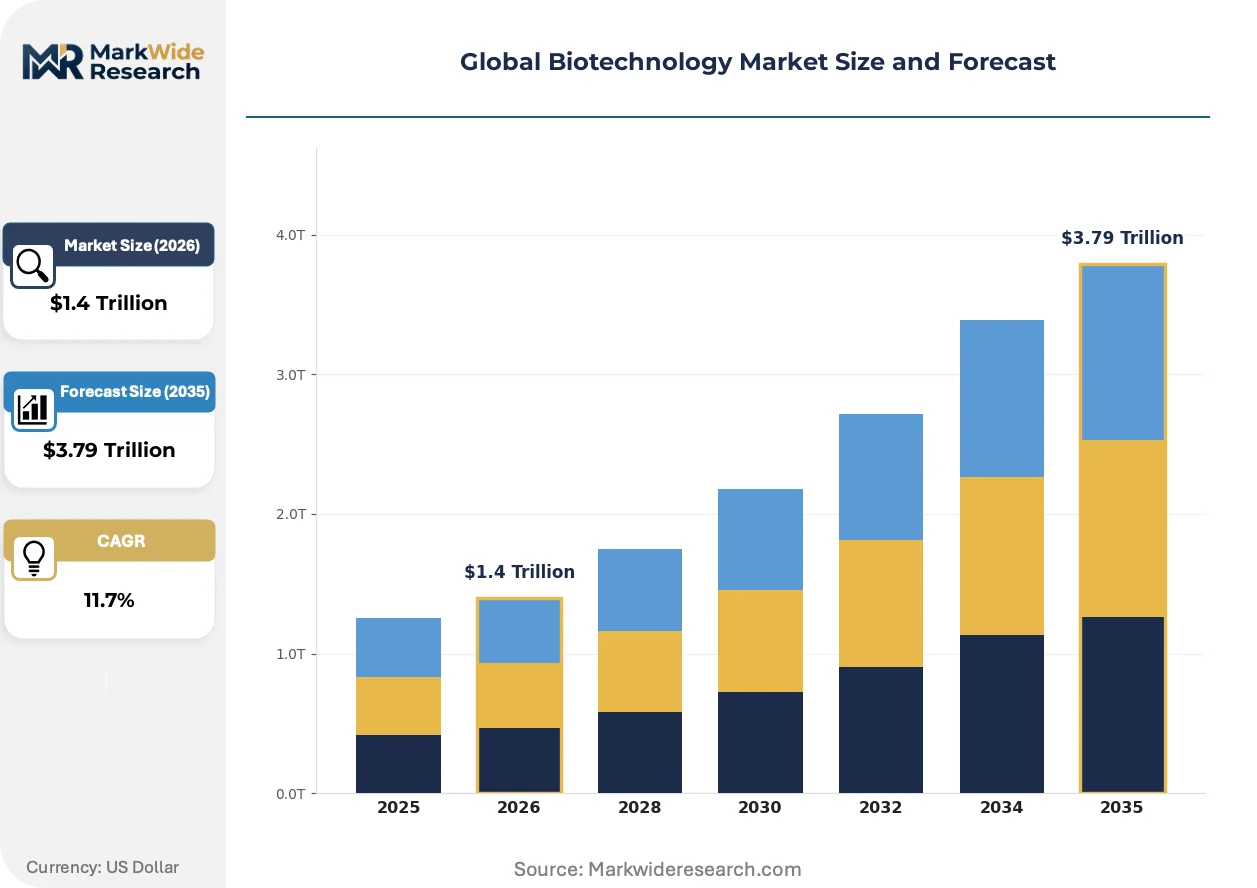
| Market Size in 2026 | $1.4 Trillion |
| Market Size in 2035 | $3.79 Trillion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopharmaceuticals, Diagnostic Tools, Biomaterials, Biofuels Application: Therapeutics, Agriculture, Environmental, Industrial End User: Pharmaceutical Companies, Research Institutes, Contract Manufacturing Organizations, Biotechnology Firms Technology: Genomics, Proteomics, Cell Culture, Fermentation |
| Companies Covered | F. Hoffmann-La Roche Ltd, Amgen Inc., Novartis AG, AstraZeneca, Gilead Sciences Inc., Bristol-Myers Squibb, Sanofi, Biogen, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biotechnology Market Emerging Trajectories
Artificial intelligence is penetrating target identification and patient stratification workflows, compressing discovery timelines while raising computational infrastructure requirements. The shift demands new partnerships between biotech sponsors and specialized AI vendors.
Machine learning models trained on proteomic and genomic datasets are displacing traditional high-throughput screening as the primary engine for lead identification. Mid-cap biotechs with limited chemistry resources adopt cloud-based platforms to access capabilities previously requiring internal structural biology teams. The technology is displacing legacy small-molecule discovery economics by reducing wet-lab validation burden.
China's NMPA has implemented priority review channels for innovative biologics developed domestically, accelerating approval timelines for sponsors with local clinical data. Multinational innovators must now run parallel China-specific trials to capture market access benefits. Oncology and rare disease therapies receive the bulk of designations, reshaping global development program geography.
Payers are unbundling gene therapy reimbursement from traditional pharmacy benefit structures, creating separate budget silos for single-administration curative treatments. Hospital systems in Germany and the United States negotiate outcomes-based contracts with mortality and morbidity milestones. This procurement evolution is concentrating initial commercial launches at centers with established real-world data collection infrastructure.
Global Biotechnology Market Segmentation
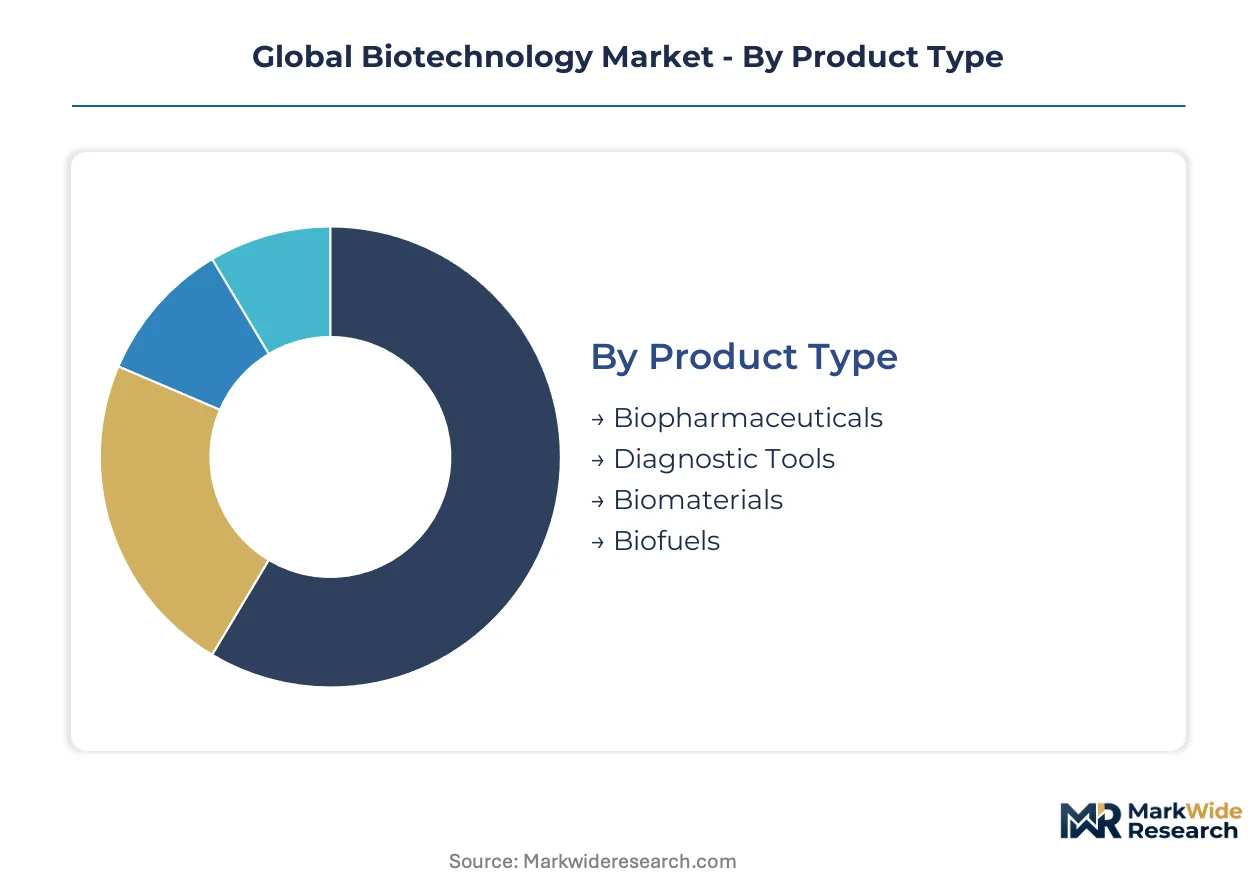
Biotechnology market segmentation reveals how value pools concentrate across distinct technical domains and customer workflows. Product types diverge sharply in margin structure, while application areas separate high-growth therapeutic platforms from mature industrial biocatalysis. Understanding these divisions exposes where capital deployment and regulatory attention are concentrating.
Product Type:
Channel distribution varies dramatically across product categories, with biopharmaceuticals flowing through specialized cold-chain logistics and diagnostic tools penetrating clinical laboratories through distributor networks.
- Biopharmaceuticals:Complex protein therapeutics and gene therapies manufactured under GMP conditions command premium pricing through hospital and specialty pharmacy channels. Demand concentrates in the United States, Germany, and China as these markets build reimbursement frameworks for single-administration curative treatments.
- Diagnostic Tools:In vitro diagnostic platforms and companion diagnostic assays enable patient stratification for personalized therapies. Research tool demand clusters in the Boston-Cambridge corridor and Basel region, driven by proximity to pharmaceutical R&D headquarters.
- Biomaterials:Engineered scaffolds and regenerative matrices for tissue repair applications.
- Biofuels:Industrial-scale fermentation products and advanced bio-based fuels for transportation and energy sectors.
Biopharmaceuticals dominate installed base. Diagnostic Tools is where expansion concentrates.
Application:
Cost tier separation distinguishes high-investment therapeutic development from lower-margin environmental remediation contracts.
- Therapeutics:Drug discovery and clinical development programs targeting oncology, rare diseases, and autoimmune conditions absorb the majority of venture capital deployment. FDA accelerated approval pathways and EMA adaptive licensing frameworks compress development timelines for breakthrough therapies.
- Agriculture:Trait engineering for crop yield enhancement and pest resistance leverages CRISPR platforms moving from research into regulated field trials. Brazil and Argentina anchor commercial adoption as these countries scale biotech soybean and corn cultivation.
- Environmental:Bioremediation and waste treatment applications using microbial consortia.
- Industrial:Biocatalysis for chemical synthesis and enzyme-based manufacturing processes.
Therapeutics commands the highest R&D intensity. Agriculture is climbing the fastest as gene editing regulatory clarity improves.
End User:
Customer type determines procurement sophistication, with pharmaceutical companies running complex supplier qualification programs and research institutes prioritizing technical collaboration.
- Pharmaceutical Companies:Large-cap sponsors with integrated discovery-through-commercialization capabilities drive demand for novel modalities including cell and gene therapies. Internal manufacturing buildouts compete with outsourced supply strategies.
- Contract Manufacturing Organizations:CDMOs with GMP-certified viral vector suites and continuous bioprocessing capabilities capture outsourced production from sponsors lacking internal capacity. Booking lead times now extend 18-24 months for gene therapy manufacturing slots.
- Research Institutes:Academic and government laboratories conducting foundational biological research.
- Biotechnology Firms:Venture-backed development-stage companies advancing platform technologies.
Pharmaceutical Companies dominate installed base. Contract Manufacturing Organizations is where expansion concentrates.
Technology:
Supply concentration in enabling technologies creates competitive bottlenecks, with genomics platform providers and specialized cell culture media suppliers commanding pricing power.
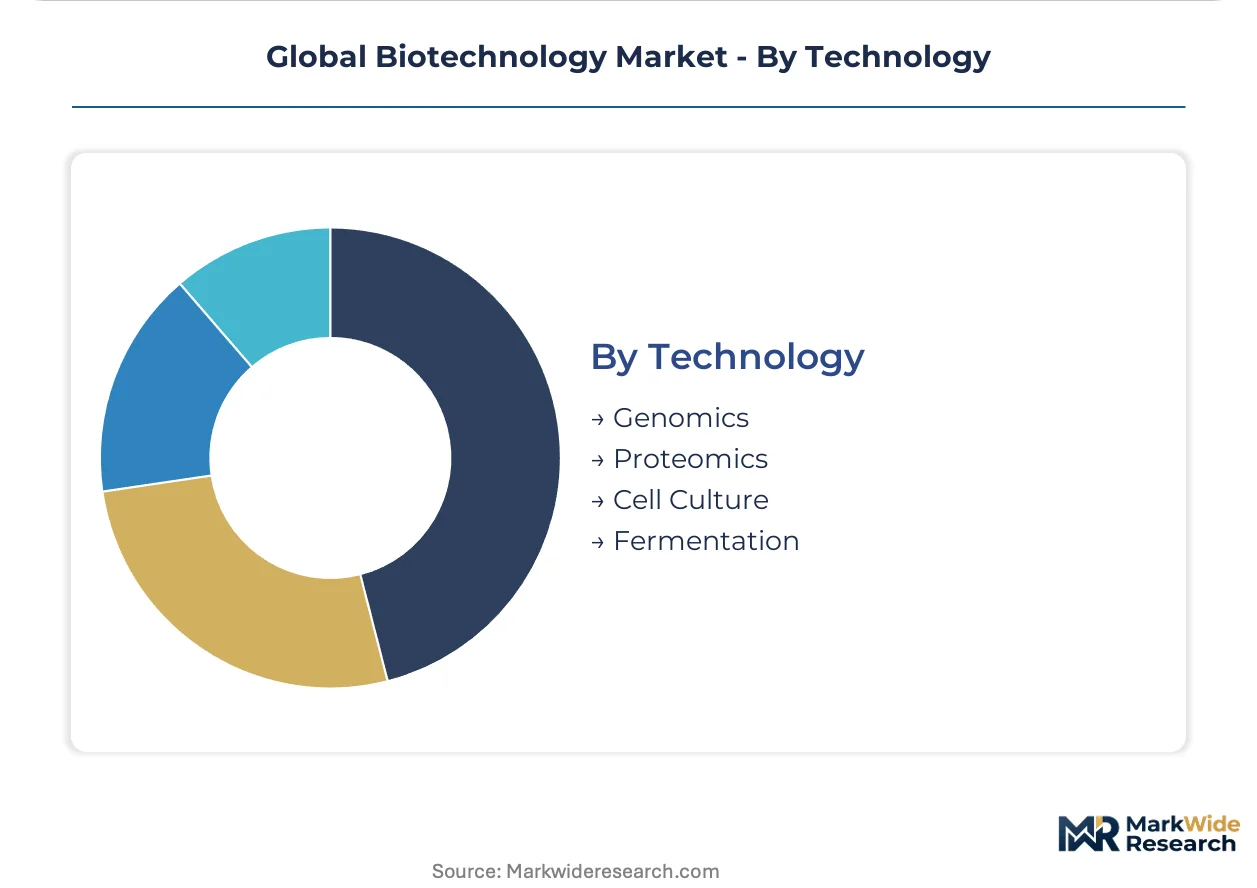
- Genomics:CRISPR-based editing platforms, next-generation sequencing, and synthetic biology tools enable target identification and therapeutic development. Base editing and prime editing variants are opening therapeutic targets previously inaccessible to first-generation nucleases.
- Cell Culture:Mammalian expression systems and perfusion bioreactor technologies support biologics manufacturing scale-up. Perfusion cell culture integrated with continuous capture chromatography promises 3-5x productivity gains over batch platforms.
- Proteomics:Mass spectrometry and protein characterization workflows for biomarker discovery.
- Fermentation:Microbial production systems for enzymes, biofuels, and small-molecule precursors.
Genomics dominates installed base. Cell Culture is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for gene therapies concentrates in the United States and Germany, where single-administration curative treatments command multi-million-dollar reimbursement rates unavailable in price-controlled jurisdictions. China's NMPA priority review channels and India's emerging CDMO cost advantages are redrawing competitive geography across development and manufacturing stages.
United States
FDA accelerated approval pathways compress phase 3 timelines for breakthrough oncology and rare disease therapies, enabling earlier revenue recognition for sponsors with strong biomarker data. The IRA's drug pricing provisions are reshaping negotiation dynamics for small-molecule portfolios while biologics retain protected status. The Boston-Cambridge corridor sustains dominance in preclinical-stage biologics innovation through concentrated venture deployment and Harvard-MIT talent pipelines.
Germany
Hospital systems negotiate outcomes-based contracts for gene therapies with mortality and morbidity milestones, creating procurement concentration at centers with established real-world data collection infrastructure. The EU Green Deal qualifies biotech facilities with renewable energy sourcing for preferential financing under the EU taxonomy. The Rhine-Main and Munich clusters anchor cell and gene therapy manufacturing buildouts serving EMA adaptive licensing frameworks.
China
NMPA priority review channels for innovative biologics developed domestically accelerate approval timelines for sponsors with local clinical data, forcing multinational innovators to run parallel China-specific trials. Dual carbon goals from MEE pressure facilities toward renewable energy transitions. The Yangtze River Delta biotech corridor concentrates viral vector manufacturing capacity and CRISPR platform development.
India
CDSCO harmonization of biologics standards with ICH guidelines opens inspection pathways for export-oriented manufacturing, with cost structures undercutting Western facilities by 40-60%. The PLI scheme for pharmaceuticals incentivizes domestic production of critical starting materials. Hyderabad and Bengaluru clusters are scaling GMP-certified gene therapy suites and continuous bioprocessing capabilities.
Switzerland
Swissmedic alignment with EMA standards enables parallel submission strategies while maintaining independent regulatory authority for domestic market access. Basel's pharmaceutical R&D headquarters density drives research tool demand and companion diagnostic development. The country's specialized workforce in GMP compliance and living-cell handling commands premium compensation as training programs require 18-24 months to produce production-ready staff.
Global Biotechnology Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the Global Biotechnology Market. Large-cap integrated sponsors with discovery-through-commercialization capabilities compete against specialized CDMOs with GMP-certified viral vector suites and contract research organizations with AI-enabled target identification platforms. The structure rewards scale in biologics manufacturing while preserving niches for precision medicine specialists. Dominant competitive moves include capacity expansion in gene therapy manufacturing slots and strategic partnerships between biotech sponsors and specialized AI vendors.
Within the integrated pharmaceutical tier, F. Hoffmann-La Roche Ltd, Amgen Inc., and Novartis AG exemplify divergent strategic positioning. The Swiss-incorporated entity anchors diagnostic innovation extending from research tools into clinical decision support. The California-based corporation leverages deep protein engineering expertise in therapeutic biologics. The Basel-headquartered AG concentrates on advanced cell and gene therapy platforms. Each occupies a distinct vector of technology leadership rather than competing directly on identical capabilities.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Amgen Inc. |
| Novartis AG |
| AstraZeneca |
| Gilead Sciences Inc. |
| Bristol-Myers Squibb |
| Sanofi |
| Biogen |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Viral vector manufacturing scale economies concentrate pricing power among GMP-certified facilities with confirmed production slots, compressing margins for sponsors locked into 18-24 month booking lead times while elevating cost floors for late entrants. This capacity scarcity draws from plasmid DNA supply bottlenecks in North America and Europe, tethering biologics price structures to upstream nucleic acid production constraints.
Pricing Analysis
Configured-to-order pricing for patient-specific autologous cell therapies commands substantial premiums over standardized allogeneic platforms. Value-based contracts with mortality milestones dominate gene therapy reimbursement in Germany and the United States, while cost-plus models persist for commoditized diagnostic reagents. Price differentiation stems from GMP certification tier and customization depth. Cost compression in viral vector manufacturing is intensifying because CDMOs in India undercut Western facilities by 40-60%. Research institutes exhibit highest price sensitivity; hospital systems with outcomes-based contracts show lowest.
Supply Chain Analysis
Plasmid DNA production capacity in the United States, Germany, and Switzerland anchors viral vector manufacturing throughput for gene therapy sponsors. High-grade fetal bovine serum, chemically defined media, and single-use bioreactor bags constitute critical inputs with concentrated supplier bases. Single-source vulnerability in plasmid suppliers exposes programs to 3-4 year capacity expansion lags. Distribution runs through specialized cold-chain logistics networks serving hospital and specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
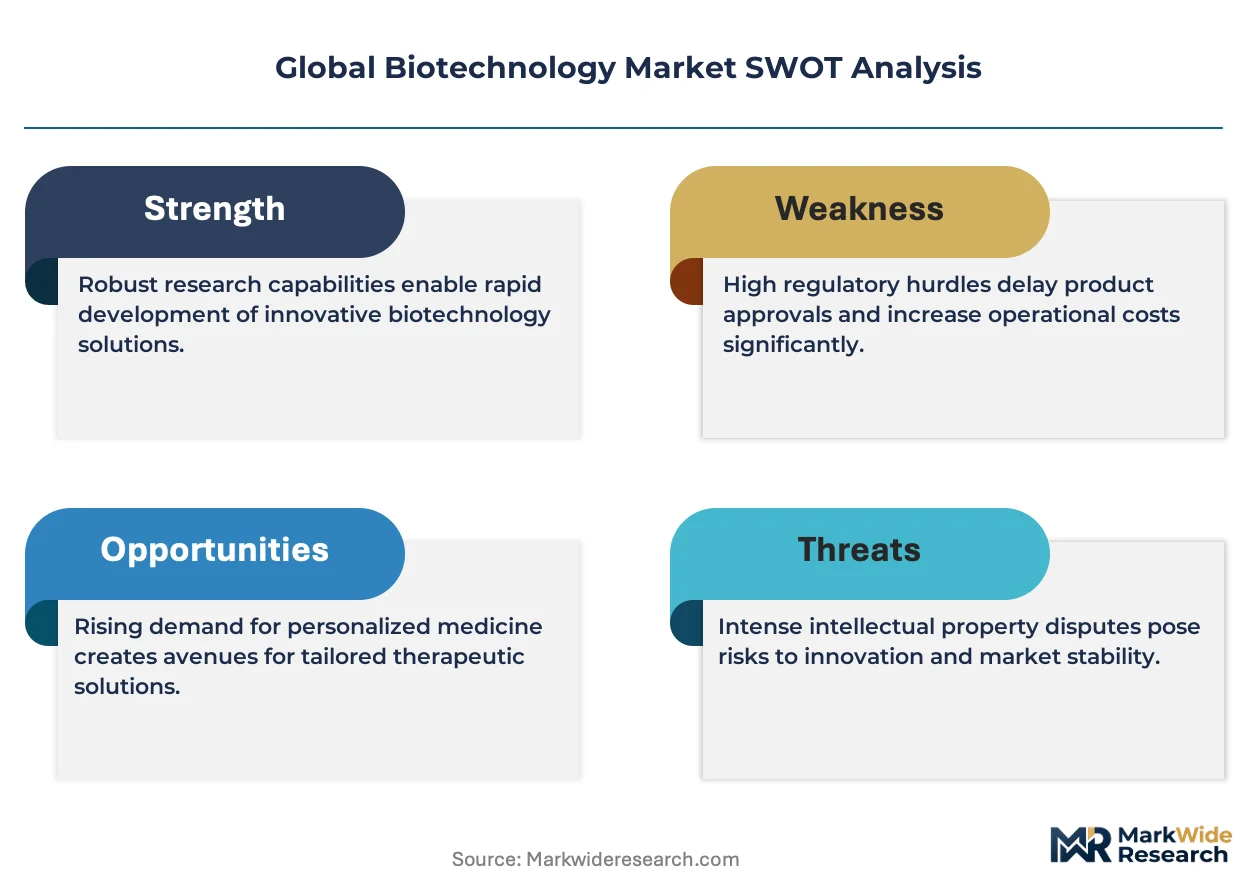
The Global Biotechnology Market functions as a defensive-moat arena where regulatory entrenchment creates formidable barriers—FDA and EMA accelerated approval frameworks demand multi-year evidence generation commitments that newcomers cannot replicate.
For Market Incumbents: Shield market position by securing captive plasmid DNA supply through backward integration into nucleic acid manufacturing, and accelerate ISO 13485 certification timelines for companion diagnostic platforms. Allogeneic cell therapy entrants threaten autologous economics; incumbents must defend logistical advantages through manufacturing automation investments. For New Entrants and Emerging Players: CDSCO harmonization with ICH guidelines opens the fastest regulatory pathway for export-oriented manufacturing in India. White-space concentrates in continuous bioprocessing capabilities and AI-enabled target identification platforms serving mid-cap sponsors lacking internal structural biology teams. A cloud-based SaaS partnership model with established CDMOs offers viable go-to-market positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-technology specialists with validated CRISPR editing variants and established GMP quality systems. Long-term viability hinges on reimbursement negotiation capabilities for single-administration curative treatments. Acquisition targets should demonstrate real-world evidence infrastructure and payer relationships. The signal to watch is gene therapy pricing outcomes in German hospital outcomes-based contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval compresses phase 3 timelines for breakthrough oncology therapies. |
| Manufacturing Scale-Up | Perfusion cell culture integrated with continuous capture chromatography promises 3-5x productivity gains. |
| Strategic Partnership | AI vendor alliances compress discovery timelines for mid-cap sponsors lacking internal capabilities. |
| Backward Integration | Captive plasmid DNA production insulates sponsors from 18-24 month CDMO booking lead times. |
| Reimbursement Strategy | Outcomes-based contracts with mortality milestones concentrate procurement at German hospital systems. |
Methodological Framework
Desk research of FDA and EMA submission databases, ClinicalTrials.gov protocols, and formulary reimbursement records preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Primary fieldwork combined with secondary validation across customs trade data, SEC 10-K filings, and CDSCO inspection reports. Bottom-up segment sizing triangulated against top-down market estimates.
Variance decomposition across product type, application, end user, technology, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectory modeling. Forecast inputs incorporated viral vector manufacturing capacity utilization rates and CRISPR platform clinical translation milestones.
Decision-makers should treat outputs as directional under stable regulatory harmonization assumptions; material deviation in FDA or EMA approval timelines would warrant model refresh. Practitioners should keep alternative scenarios live as gene therapy reimbursement negotiations and allogeneic cell therapy competitive dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Low Endotoxin Gelatin Market
Biotechnology Equipment
Global Single-Use Bioreactor Market
Biotechnology Equipment
Global Automated Biochemical Analyzer Market
Biotechnology Equipment
North America Life Science Tools Market
Biotechnology Equipment
Global Plant Cell Culture Equipment Market
Biotechnology Equipment
Global Viral RNA Extraction Kit Market
Biotechnology Equipment
Biologic Imaging Reagents Market
Biotechnology Equipment
Global Large Molecule Bioanalytical Technologies Market
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
Bioreactors Accessories Market
Biotechnology Equipment
Cellular Localization Kits Market
Biotechnology Equipment
Plant Genotyping Equipment Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
In-Vitro Fertilization (IVF) Microscopes Market
Biotechnology Equipment
Global Bovine Serum Albumin Market
Biotechnology Equipment
Global DNA/RNA Extraction Kit Market