
 Transfection Reagents Market | 2026-2036
Transfection Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Transfection Reagents Market Outlook
Switzerland is rewriting the competitive map for transfection reagents as Lonza Group extends its biologics manufacturing footprint with integrated reagent supply chains. Thermo Fisher Scientific Inc. leverages its Fisher Scientific distribution arm to control channel access across North American research institutes. Promega Corporation differentiates through specialized reagent formulations for protein production workflows, while QIAGEN anchors its position with sample-to-insight automation that bundles transfection chemistry.
Transfection reagents are formulated compounds—typically cationic lipids, polymers, or calcium phosphate suspensions—that facilitate nucleic acid entry into eukaryotic cells by overcoming membrane barriers and endosomal escape limitations. Their primary purpose is to enable gene expression, silencing, or editing in laboratory and clinical manufacturing settings. Lipid-based reagents dominate current revenue pools due to their efficiency in hard-to-transfect cell lines, while viral vectors command premium positioning in gene therapy applications where stable integration is required. Electroporation instruments compete for share in clinical-grade cell therapy manufacturing, though chemical transformation persists as the workhorse for routine plasmid delivery.
The FDA regulates transfection reagents used in gene therapy as ancillary materials under chemistry, manufacturing, and controls guidelines, while the EMA's ATMP framework shapes compliance costs for European developers. ISO 10993 biocompatibility standards and REACH chemical safety obligations further constrain formulation choices for suppliers serving clinical markets. Stakeholders must monitor how evolving gene therapy commercialization timelines reshape reagent demand from research-grade to GMP-compliant specifications.
Market Dynamics
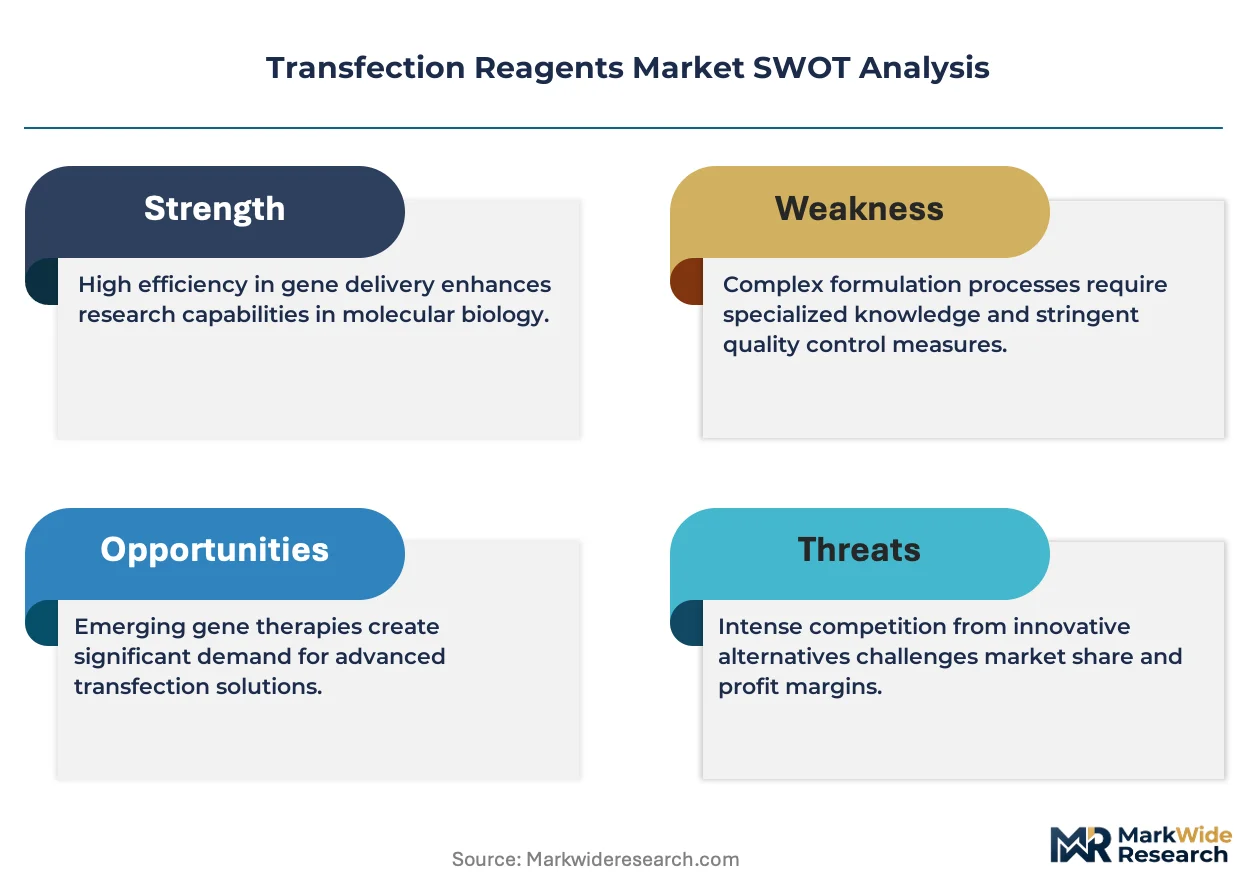
The transition from research-grade to GMP-compliant specifications is compressing supplier margins while elevating technical barriers for new entrants serving cell therapy manufacturing workflows.
Growth Catalysts
- ATMP Framework Acceleration:The EMA's streamlined advanced therapy medicinal product pathways reduce clinical trial initiation timelines for European gene therapy developers, expanding demand for validated reagent formulations.
- Biologics Manufacturing Expansion:Contract development and manufacturing organizations in Switzerland and Singapore are building captive reagent production capabilities to secure supply chains for viral vector programs.
- CRISPR Editing Proliferation:Ribonucleoprotein complex delivery protocols require specialized lipid nanoparticle formulations, creating pull-through demand for next-generation transfection chemistries in academic and industrial research settings.
Market Restraints
- Cationic Lipid Supply Concentration:Three specialty chemical manufacturers control over 80% of pharmaceutical-grade lipid precursor output, exposing reagent formulators to input cost volatility and allocation risk.
- ISO 10993 Testing Burden:Biocompatibility validation for clinical-grade reagents adds 18-24 months to product development cycles, constraining portfolio refresh rates for mid-sized suppliers.
- Electroporation Substitution:Clinical-scale electroporation systems from MaxCyte and Lonza are capturing share in CAR-T manufacturing where process closure requirements favor physical over chemical transfection methods.
Strategic Opportunities
- India CDMO Emergence:The country's PLI scheme for pharmaceuticals is attracting gene therapy manufacturing investment, creating demand for cost-optimized reagent supply without GMP premium pricing.
- In Vivo Gene Editing:Liver-targeted lipid nanoparticle formulations for base editing applications represent an untapped application segment with distinct formulation requirements from ex vivo cell therapy workflows.
- Automated Liquid Handling Integration:Reagent suppliers bundling chemistry with validated automation protocols on Tecan and Hamilton platforms can capture workflow-level value rather than commodity chemical margins.
Industry Challenges
- Process Analytical Technology Implementation:Gene therapy manufacturers demand real-time quality attribute monitoring for ancillary materials, requiring reagent suppliers to develop novel spectroscopic or chromatographic release assays.
- Cross-Contamination Control:Multi-product CDMO facilities require dedicated reagent manufacturing suites or single-use formulation systems, complicating capacity planning and capital deployment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transfection Reagents Market |
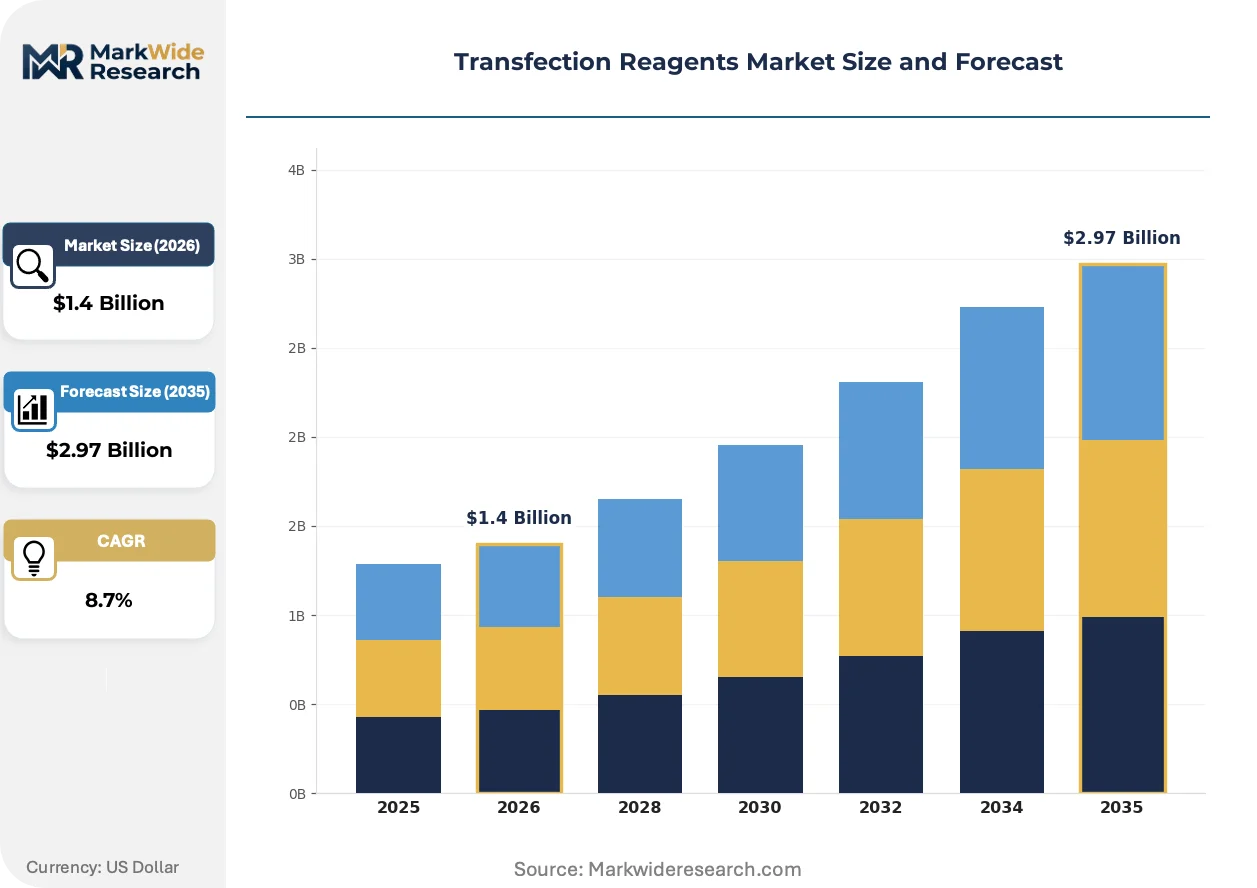
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Reagents, Biologics, Lipid-Based Reagents, Viral Vectors Delivery Method: Electroporation, Microinjection, Viral Transduction, Chemical Transformation End User: Academic Research Institutes, Pharmaceutical Companies, Biotechnology Firms, Diagnostic Laboratories Application: Gene Therapy, Protein Production, RNA Interference, Vaccine Development |
| Companies Covered | Thermo Fisher Scientific Inc., Promega Corporation, QIAGEN, Bio-Rad Laboratories Inc., Merck KGaA, Lonza Group, Polyplus-transfection SA, MaxCyte Inc., Mirus Bio LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transfection Reagents Market Strategic Shifts
Synthetic lipid chemistry and regulatory science are converging to redefine performance benchmarks for nucleic acid delivery systems across research and clinical manufacturing environments.
Next-generation ionizable lipids are collapsing the efficiency gap between hard-to-transfect primary cells and established immortalized lines. Academic labs at MIT and Stanford are adopting these materials for organoid gene editing workflows. The technology is collapsing the historical segmentation between research-grade and clinical-prep reagent portfolios as single formulations satisfy both use cases.
REACH chemical safety obligations are forcing reformulation of legacy cationic lipid structures containing persistent organic pollutants. The European Chemicals Agency's 2023 substance evaluation roadmap has flagged several quaternary ammonium compounds used in commercial reagents. Suppliers serving EU gene therapy developers are accelerating substitution programs for biodegradable lipid alternatives ahead of authorization sunset dates.
Consolidated procurement through group purchasing organizations is displacing direct institutional purchasing at major research universities. The University of California system and Ivy League consortiums now negotiate master service agreements covering transfection reagents alongside sequencing and cell culture media. This shift is most visible in the United States, where endowment-backed institutions leverage collective volume to extract performance guarantees and technical support commitments from suppliers.
Transfection Reagents Market Segmentation
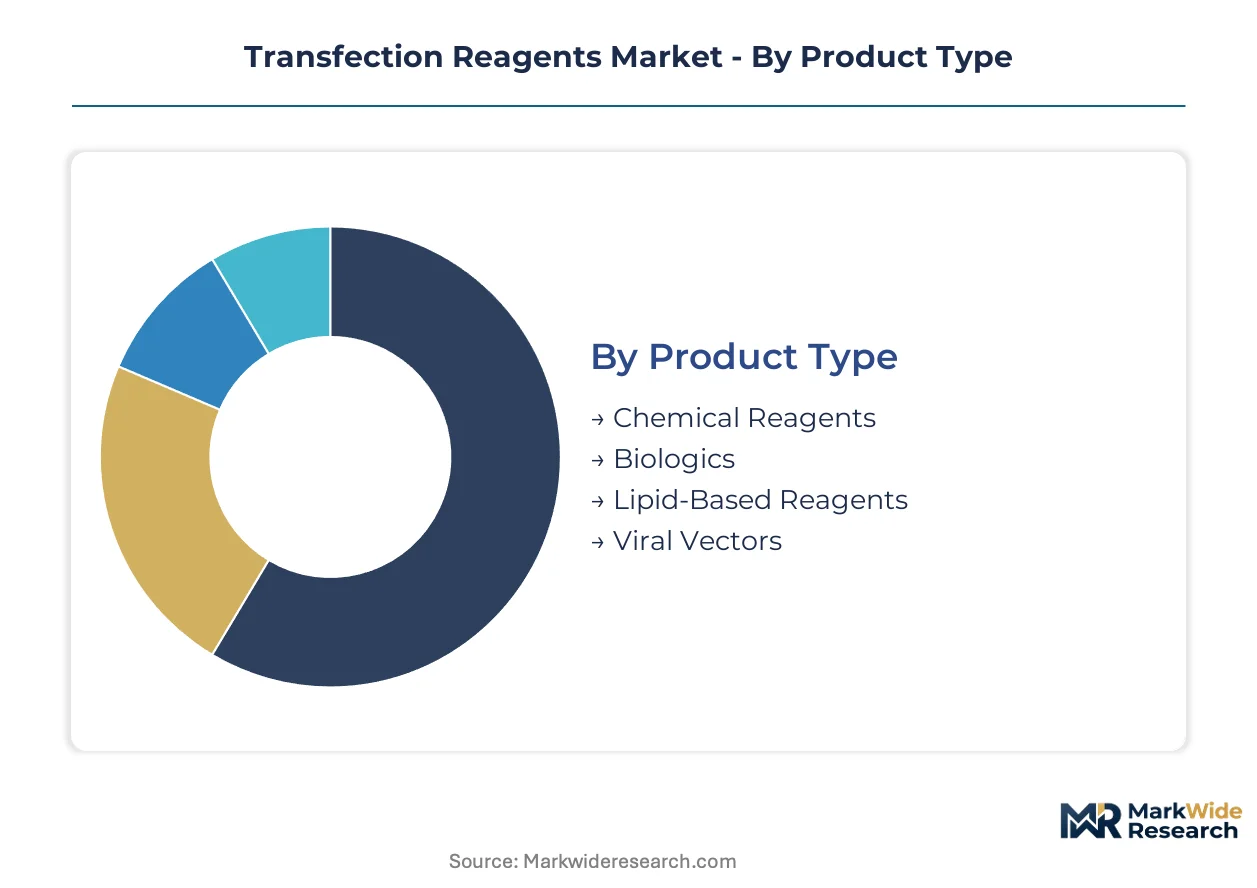
Transfection reagents serve divergent workflows spanning exploratory research through commercial gene therapy manufacturing. Segment boundaries reflect technical performance requirements, regulatory compliance tiers, and automation compatibility rather than simple chemical classification.
Product Type:
Use-case spectrum spans transient protein expression in academic labs to stable genomic integration in clinical cell therapy.
- Lipid-Based Reagents:Ionizable and cationic lipid formulations encapsulate nucleic acids into nanoparticles that fuse with cell membranes. Demand concentrates in CAR-T manufacturing workflows at Lonza's Switzerland facilities and Thermo Fisher's Massachusetts operations, where FDA chemistry, manufacturing, and controls guidelines for ancillary materials drive formulation standardization.
- Viral Vectors:Adeno-associated and lentiviral delivery systems achieve stable chromosomal integration for gene therapy applications. Procurement clusters at CDMOs in Singapore and Switzerland serving EMA advanced therapy medicinal product frameworks, with supply constrained by ISO 10993 biocompatibility validation timelines.
- Chemical Reagents:Calcium phosphate and DEAE-dextran suspensions remain standard for routine plasmid delivery in academic settings.
- Biologics:Peptide-based and cell-penetrating protein formulations address specialized delivery challenges for ribonucleoprotein complexes.
The dominant share belongs to Lipid-Based Reagents, while Viral Vectors is closing the gap fastest.
Delivery Method:
Cost tier separation distinguishes capital-intensive physical methods from consumable-driven chemical approaches.
- Chemical Transformation:Lipid and polymer-based reagents enable scalable, automation-compatible nucleic acid delivery without specialized equipment. Pharmaceutical companies in Boston and San Francisco biotech clusters favor these methods for high-throughput screening, where per-sample cost and process closure requirements outweigh absolute efficiency metrics.
- Electroporation:Electrical pulse systems create transient membrane pores for direct cytoplasmic entry. Lonza and MaxCyte systems capture share in clinical-grade manufacturing where GMP compliance and elimination of chemical residuals take priority, particularly at CDMOs serving FDA-regulated gene therapy sponsors.
- Viral Transduction:Engineered viral particles achieve tissue-specific targeting and persistent expression in dividing and non-dividing cells.
- Microinjection:Direct physical delivery into individual cells serves embryo engineering and single-cell research applications.
Chemical Transformation retains volume leadership, though Electroporation is expanding most quickly in commercial manufacturing.
End User:
Customer type determines specification tier, with research-grade formulations diverging sharply from GMP-validated products.
- Pharmaceutical Companies:Integrated drug developers and gene therapy sponsors procure validated reagents under long-term supply agreements. Procurement at Novartis, Roche, and emerging biotechs concentrates on Switzerland and Massachusetts, where EMA and FDA regulatory convergence around ancillary material guidelines shapes technical requirements.
- Biotechnology Firms:Venture-backed developers of cell therapies and gene editing platforms demand flexible supply with rapid scale-up pathways. Singapore and Switzerland CDMO partnerships are accelerating, with India's PLI scheme attracting manufacturing investment that requires cost-optimized reagent sourcing.
- Academic Research Institutes:University labs prioritize catalog availability and technical support over regulatory documentation.
- Diagnostic Laboratories:Clinical reference labs utilize transfection for assay development and quality control applications.
Pharmaceutical Companies command the largest procurement volumes, while Biotechnology Firms are gaining share fastest.
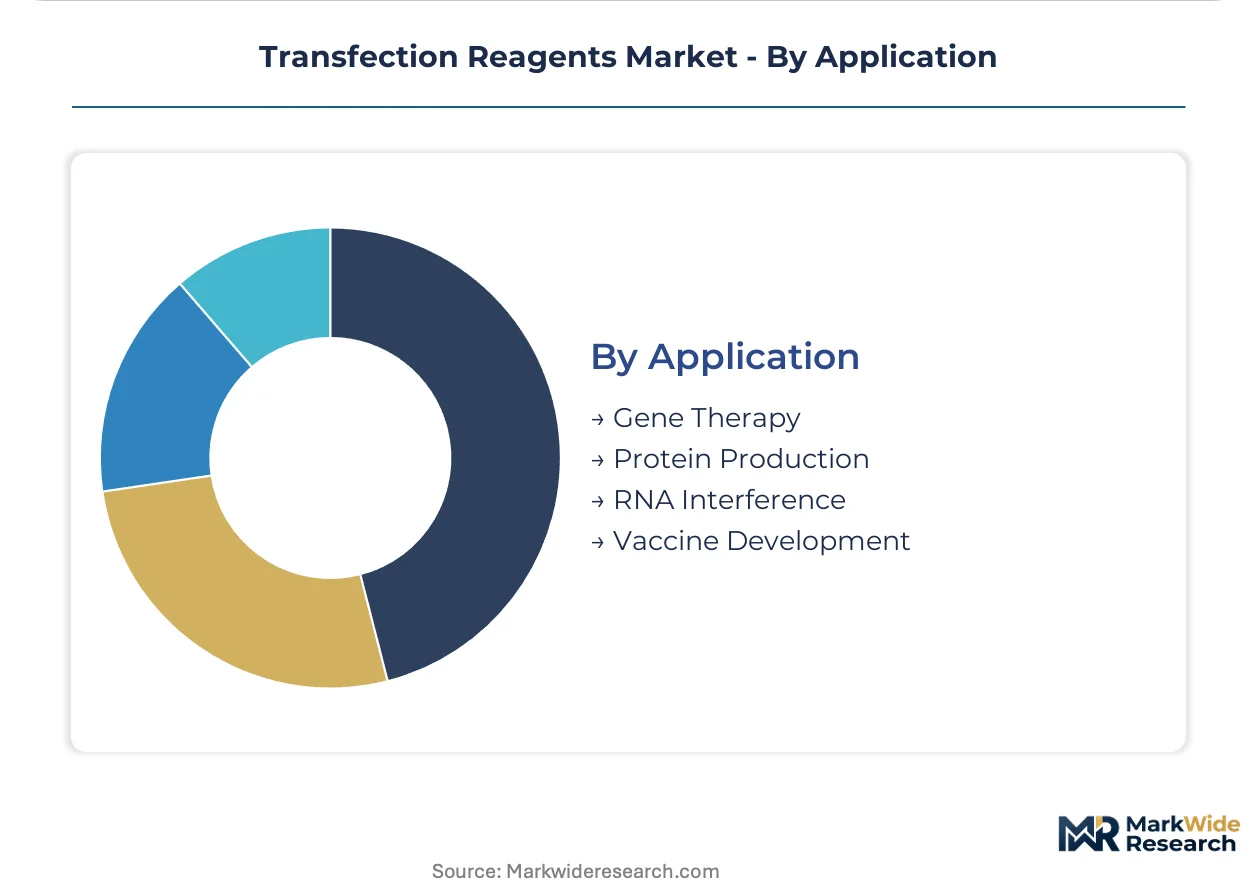
Application:
Application maturity varies from established protein production workflows to emerging in vivo gene editing protocols.
- Gene Therapy:Ex vivo cell modification and in vivo nucleic acid delivery for inherited disease treatment. Manufacturing demand clusters at CDMOs in Switzerland, Singapore, and emerging Indian facilities, where EMA ATMP framework acceleration and FDA streamlined pathways are compressing development timelines.
- Protein Production:Transient expression systems for recombinant biologics and viral antigen manufacturing. Academic and industrial labs at MIT, Stanford, and contract manufacturers leverage established lipid formulations for rapid, high-yield expression without stable cell line development.
- RNA Interference:Small interfering RNA and microRNA delivery for gene silencing studies and therapeutic development.
- Vaccine Development:mRNA and DNA vaccine antigen delivery, including lipid nanoparticle formulations for infectious disease and oncology applications.
Gene Therapy represents the largest addressable value pool, while Vaccine Development is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA chemistry, manufacturing, and controls guidelines for ancillary materials anchor the United States as the dominant geography for transfection reagent procurement. Pharmaceutical companies and CDMOs cluster in biotech hubs where regulatory convergence with EMA standards accelerates commercial gene therapy timelines.
United States
Boston and San Francisco biotech clusters drive concentrated demand for GMP-compliant lipid formulations. FDA streamlined pathways for cell and gene therapy reduce clinical trial initiation barriers, expanding validated reagent procurement. Massachusetts and California facilities of Thermo Fisher Scientific anchor North American supply chain infrastructure.
Switzerland
Lonza Group's biologics manufacturing footprint integrates captive reagent production for viral vector programs. Swissmedic alignment with EMA ATMP frameworks ensures regulatory continuity for European gene therapy developers. Basel and Visp facilities concentrate contract manufacturing demand for lipid nanoparticle formulations.
Singapore
CDMOs serving Asia-Pacific gene therapy sponsors require ISO 10993-validated reagent supply chains with regional redundancy. The country's national pharmaceutical regulator maintains equivalence with FDA and EMA biocompatibility standards. Tuas Biomedical Park attracts manufacturing investment from multinational biologics developers.
Germany
REACH chemical safety obligations and ECHA substance evaluation roadmaps force reformulation of legacy cationic lipid structures. Heidelberg and Munich academic institutes adopt next-generation ionizable lipids for organoid gene editing workflows. Baden-Württemberg chemical manufacturers supply biodegradable lipid alternatives ahead of authorization sunset dates.
India
The PLI scheme for pharmaceuticals attracts gene therapy manufacturing investment requiring cost-optimized reagent sourcing without GMP premium pricing. CDSCO regulatory pathways for advanced therapy products are converging toward ICH standards. Hyderabad and Bengaluru biotech clusters emerge as procurement hubs for research-grade formulations.
Transfection Reagents Market Competitive Environment
Integrated life science conglomerates and specialized reagent formulators split the market across research-grade and clinical-manufacturing tiers. Supplier concentration remains moderate, with five to eight entities controlling formulation IP and distribution channels. Vertically integrated chemical suppliers and research-tool distributors represent the dominant strategic archetypes. Capacity expansion in Switzerland and Singapore and strategic partnerships for automated liquid handling integration constitute the primary competitive moves.
Among Switzerland-based biologics specialists, Lonza Group exemplifies vertical integration into captive reagent supply for viral vector manufacturing. Thermo Fisher Scientific Inc. anchors the research-tool distributor archetype through channel control across North American academic and pharmaceutical procurement. Promega Corporation occupies a position within the specialized formulation tier, representing differentiation through workflow-specific chemistry bundles.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Promega Corporation |
| QIAGEN |
| Bio-Rad Laboratories Inc. |
| Merck KGaA |
| Lonza Group |
| Polyplus-transfection SA |
| MaxCyte Inc. |
| Mirus Bio LLC |
| Others |
Value Chain & Pricing Dynamics
Cationic lipid supply concentration among three specialty chemical manufacturers exposes reagent formulators to allocation risk that simultaneously widens pricing spreads between GMP-validated and research-grade tiers and forces backward integration into captive lipid production. This input bottleneck reshapes procurement economics as CDMOs in Switzerland and Singapore absorb premium pricing for pharmaceutical-grade precursors while academic buyers face catalog price volatility.
Pricing Analysis
Geographic price spreads separate North American GMP-compliant formulations from cost-optimized Asian supply by a factor reflecting ISO 10993 validation burden and REACH compliance overhead. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with pharmaceutical companies locking long-term offtake agreements while academic institutes negotiate spot catalog terms. Cost compression in research-grade segments intensifies as India's PLI scheme attracts manufacturing investment requiring stripped-down reagent sourcing. Biotechnology firms exhibit highest price sensitivity due to venture funding cycles, whereas integrated pharmaceutical developers prioritize supply security over unit economics.
Supply Chain Analysis
Export control regimes on dual-use lipid nanoparticle chemistry constrain technology flows from United States and European Union to emerging manufacturing hubs in India and Southeast Asia. Manufacturing concentrates in Switzerland, Singapore, and Massachusetts, with raw material dependencies on German specialty chemical outputs, Chinese ionizable lipid precursors, and Indian peptide synthesis capabilities. Single-source vulnerability pervades pharmaceutical-grade cationic lipid supply, where three manufacturers control precursor output. Distribution runs through Fisher Scientific channel networks for research-grade products and direct long-term agreements for clinical manufacturing tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electroporation systems from MaxCyte and Lonza threaten chemical transfection incumbents in CAR-T manufacturing, forcing reagent suppliers to defend substitution risk through performance differentiation and workflow integration.
For Market Incumbents: Harden formulation IP positions around next-generation ionizable lipids that collapse efficiency gaps between primary cells and immortalized lines, while securing captive supply agreements with the three dominant cationic lipid precursor manufacturers to mitigate allocation risk. Capacity addition in Singapore and Switzerland reinforces proximity to CDMO clusters where GMP validation requirements create switching costs. For New Entrants and Emerging Players: Build out automated liquid handling integration partnerships with Tecan and Hamilton platforms to capture workflow-level value rather than commodity chemical margins, targeting India's emerging CDMO market where PLI incentives attract gene therapy manufacturing without demanding full GMP premium positioning. Cost-optimized reagent supply for research-grade applications in Hyderabad and Bengaluru biotech clusters offers the most penetrable entry point. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized formulation players with validated automation protocols and regional regulatory expertise over pure chemical commodity suppliers. Acquisition targets should demonstrate ISO 10993 validation capabilities and established CDMO relationships. The signal to watch is FDA and EMA convergence timelines on ancillary material guidelines, which would accelerate demand for dual-jurisdiction-compliant reagent portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Next-Generation Lipid Formulation Development | MIT and Stanford organoid workflows drive adoption of ionizable lipids that bridge research and clinical applications. |
| Automated Liquid Handling Integration | Tecan and Hamilton platform bundling captures workflow value beyond commodity chemical margins. |
| India CDMO Supply Partnership | PLI scheme attracts gene therapy manufacturing requiring cost-optimized reagent sourcing without GMP premiums. |
| REACH Compliance Reformulation | ECHA substance evaluation roadmaps force substitution of quaternary ammonium compounds with biodegradable alternatives. |
| Captive Lipid Precursor Supply | Backward integration into cationic lipid production mitigates concentration risk among three dominant specialty chemical manufacturers. |
Study Parameters
A spread of perspectives from gene therapy manufacturing executives, regulatory affairs specialists at CDMOs, academic lab directors, and procurement managers at group purchasing organizations converged on the working assumptions underpinning this analysis. Secondary validation drew from FDA chemistry manufacturing and controls guidelines, EMA advanced therapy medicinal product framework documentation, ISO 10993 biocompatibility standards, and REACH substance evaluation roadmaps. Bottom-up reagent volume estimates from CDMO facilities triangulated against top-down pharmaceutical R&D spending allocations.
Demand-supply balance modeling across the analysis window integrated product type segmentation by lipid-based reagents, viral vectors, and chemical formulations with end-user tiers spanning pharmaceutical companies, biotechnology firms, and academic institutes. CAGRs derived from capacity expansion announcements, regulatory pathway acceleration timelines, and CRISPR editing proliferation rates. Forecast inputs included EMA ATMP framework implementation pace and FDA streamlined cell and gene therapy review timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by electroporation system manufacturers or synthetic lipid chemistry disruptors would shift outcomes. Material shifts in cationic lipid precursor supply consolidation or REACH authorization sunset schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
Cell and Tissue Culture Supplies Market
Biotechnology Equipment
Global Recombinant Cell Culture Supplements Market
Biotechnology Equipment
Plant Phenotyping Equipment Market
Biotechnology Equipment
Rocking Bioreactors Market
Biotechnology Equipment
Global Cryostat Microbiome Equipment Market
Biotechnology Equipment
Global Latex Agglutination Test Kits Market
Biotechnology Equipment
Analytical Instrumentation in Life Science Market
Biotechnology Equipment
Biologic Imaging Reagents Market
Biotechnology Equipment
Measurement Technologies in Downstream Processing Market
Biotechnology Equipment
Genetic Analyzer Systems Market
Biotechnology Equipment
Global Competent Cells Market
Biotechnology Equipment
Lab Scale Bioreactors Market
Biotechnology Equipment
Global Life Science Reagents Market
Biotechnology Equipment
Botanical Extraction Equipment Market
Biotechnology Equipment
Bioreactors Accessories Market