
 PCR Consumables Market | 2026-2036
PCR Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
PCR Consumables Market Insights
The capital-intensity divergence between high-throughput platform specialists and niche reagent suppliers is unwinding competitive stability across the PCR consumables landscape. Thermo Fisher Scientific leverages integrated instrument-consumable ecosystems to sustain pricing power in research laboratories. Bio-Rad Laboratories anchors its position through specialized digital PCR workflows that differentiate from conventional qPCR offerings. QIAGEN N.V. competes by extending automation-compatible consumable formats that reduce manual handling errors in clinical settings.
PCR consumables comprise single-use laboratory articles including reaction tubes, microplates, pipette tips, and barrier-grade plastics engineered for thermal cycling compatibility between negative twenty degrees Celsius and ninety-five degrees Celsius, designed to prevent nucleic acid contamination during amplification procedures. Reagents and plastic consumables represent the largest product segments where scale economies favor manufacturers with captive resin sourcing and injection-molding capacity. Diagnostic testing applications command premium positioning due to stringent lot-release requirements, while genetic research applications in academic institutions exhibit higher price sensitivity and fragmented procurement patterns.
The FDA regulates in vitro diagnostic consumables through premarket notification pathways, while ISO 13485 quality management standards govern manufacturing consistency for clinical-grade products. The EPA oversees environmental testing applications where PCR consumables support pathogen detection in water and soil matrices. Stakeholders must monitor evolving harmonization between FDA guidance and international standards as cross-border supply chains face escalating documentation requirements for traceability and sterility assurance.
Market Dynamics
Instrument-consumable bundling is concentrating purchasing power among platform-integrated suppliers while fragmenting standalone reagent vendors into price-competitive niches. Thermal cycling plastics face mounting specification pressure as digital PCR workflows demand higher purity barriers and lower binding surfaces.
Growth Catalysts
- Infectious disease surveillance mandates:The FDA's expanded oversight of laboratory-developed tests drives validation-standard upgrades across clinical consumable portfolios. Diagnostic laboratories in the United States are scaling molecular testing volumes to meet pathogen monitoring requirements.
- Domestic biopharmaceutical infrastructure:China's genetic research investment accelerates demand for automation-compatible consumable formats. Government funding for precision medicine initiatives is reshaping procurement specifications toward high-throughput compatibility.
- ISO 13485 harmonization:Quality management standardization across clinical-grade manufacturing enables cross-border supply chain expansion. Manufacturers achieving dual FDA-ISO certification capture premium positioning in regulated diagnostic segments.
Market Restraints
- Medical-grade resin concentration:Polypropylene supply for thermal cycling applications concentrates among petrochemical complexes in the Gulf Coast region. Price volatility in specialty polymer feedstocks compresses margin structures for injection-molding specialists lacking captive resin sourcing.
- Platform lock-in effects:Proprietary consumable formats tied to specific thermal cycler architectures create switching costs that fragment addressable markets. Standalone reagent suppliers face volume limitations without instrument ecosystem integration.
- Substitute amplification technologies:Isothermal amplification methods in point-of-care settings reduce qPCR consumable demand for rapid pathogen detection. LAMP and CRISPR-based diagnostics compete for infectious disease screening volumes.
Strategic Opportunities
- Environmental testing expansion:EPA-mandated pathogen monitoring in water matrices creates demand for field-deployable PCR consumable kits. Municipal utilities require standardized collection and amplification workflows for regulatory compliance sampling.
- Cell-free DNA applications:Liquid biopsy development in oncology research opens premium consumable segments requiring ultra-low DNA binding surfaces. Specialized microplate formats command price multiples over standard diagnostic plastics.
- Direct-to-consumer channel development:At-home genetic testing normalization enables consumable suppliers to bypass traditional distributor markups. E-commerce fulfillment of sample collection and stabilization kits is restructuring last-mile delivery economics.
Industry Challenges
- Cleanroom manufacturing scale-up:Clinical-grade consumable production requires ISO Class 7-8 environments that demand specialized HVAC and personnel protocols. Facility qualification timelines extend 18-24 months for new market entrants.
- Lot-release documentation complexity:FDA 21 CFR Part 820 compliance for in vitro diagnostic accessories necessitates end-to-end traceability systems. Sterility assurance and endotoxin testing protocols create bottlenecks in high-volume production scheduling.
- Automation integration engineering:Robotic liquid handling systems impose dimensional tolerances and barcode readability standards that legacy consumable designs fail to meet. Retrofitting existing molds for automation compatibility requires substantial capital reinvestment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PCR Consumables Market |
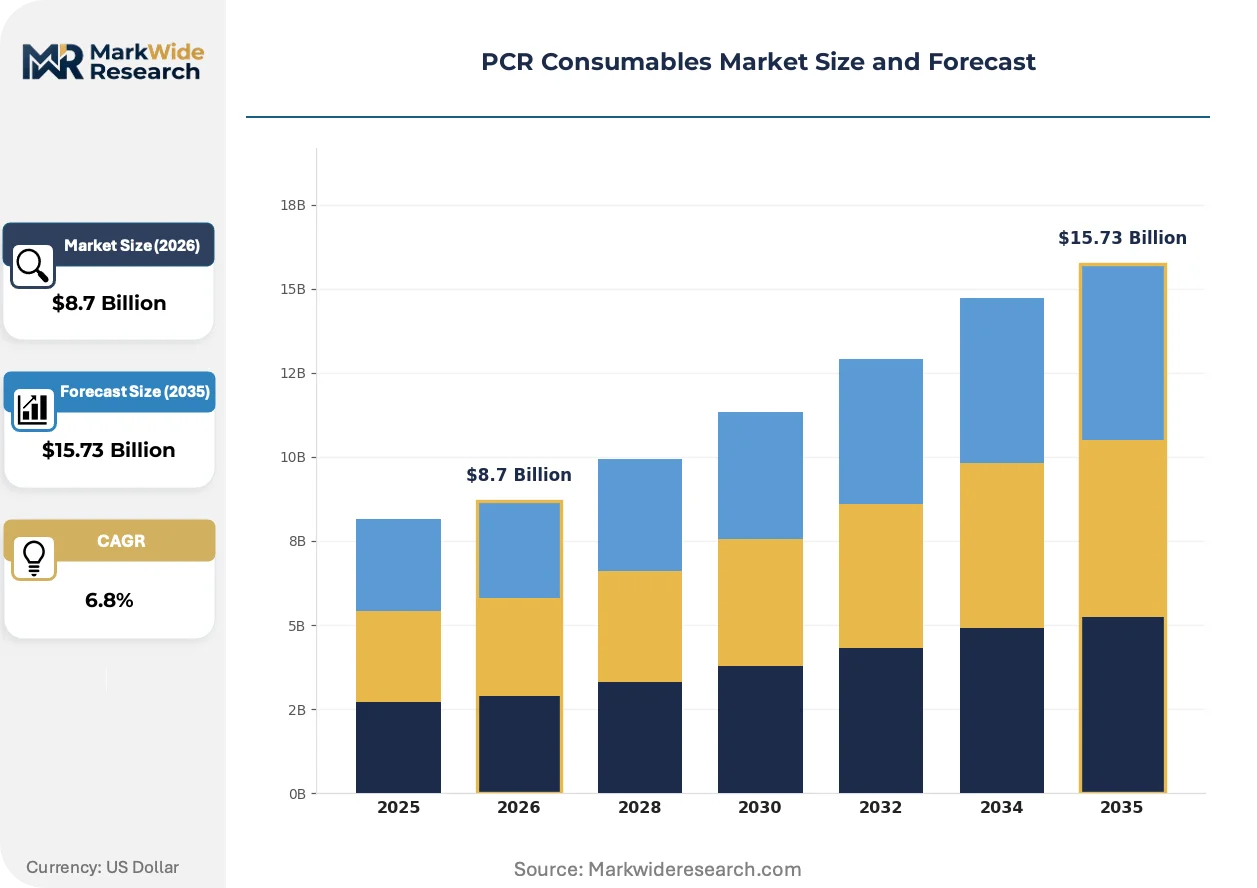
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Primers, Enzymes, Plastic Consumables End User: Research Laboratories, Clinical Laboratories, Academic Institutions, Pharmaceutical Companies Application: Diagnostic Testing, Genetic Research, Biopharmaceutical Development, Environmental Testing Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Thermo Fisher Scientific, Inc., Bio-Rad Laboratories, Inc., F. Hoffmann-La Roche Ltd., QIAGEN N.V., Agilent Technologies, Inc., Merck KGaA, Danaher Corporation, Abbott Laboratories, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCR Consumables Market Trends and Innovations
Workflow digitization and materials science advances are compressing reaction volumes while elevating contamination control standards across research and clinical settings. Suppliers are repositioning around platform-native consumable architectures that capture recurring revenue streams.
Polymerase-engineered hot-start formulations are displacing antibody-mediated activation methods in qPCR reagent portfolios. Contract research organizations in North America and Western Europe are adopting these modified enzymes for multiplexed assay development. The shift is compressing reaction optimization timelines while reducing non-specific amplification artifacts that plague high-complexity genetic screening panels.
The FDA's finalized guidance on laboratory-developed test oversight is tightening quality system documentation requirements for consumable suppliers serving CLIA-certified laboratories. Manufacturers must now maintain design history files and risk management documentation comparable to in vitro diagnostic device standards. High-complexity clinical laboratories in the United States are demanding supplier audit rights and batch-specific performance data that research-grade vendors struggle to provide.
Consolidated procurement through group purchasing organizations is concentrating contract negotiation leverage among multi-hospital systems and academic consortia. Distributor intermediaries face margin compression as direct manufacturer relationships offer volume-tiered pricing and technical support integration. The purchasing pattern shift is most visible in United States academic medical centers where centralized research operations procurement is displacing departmental-level ordering autonomy.
PCR Consumables Market Segmentation
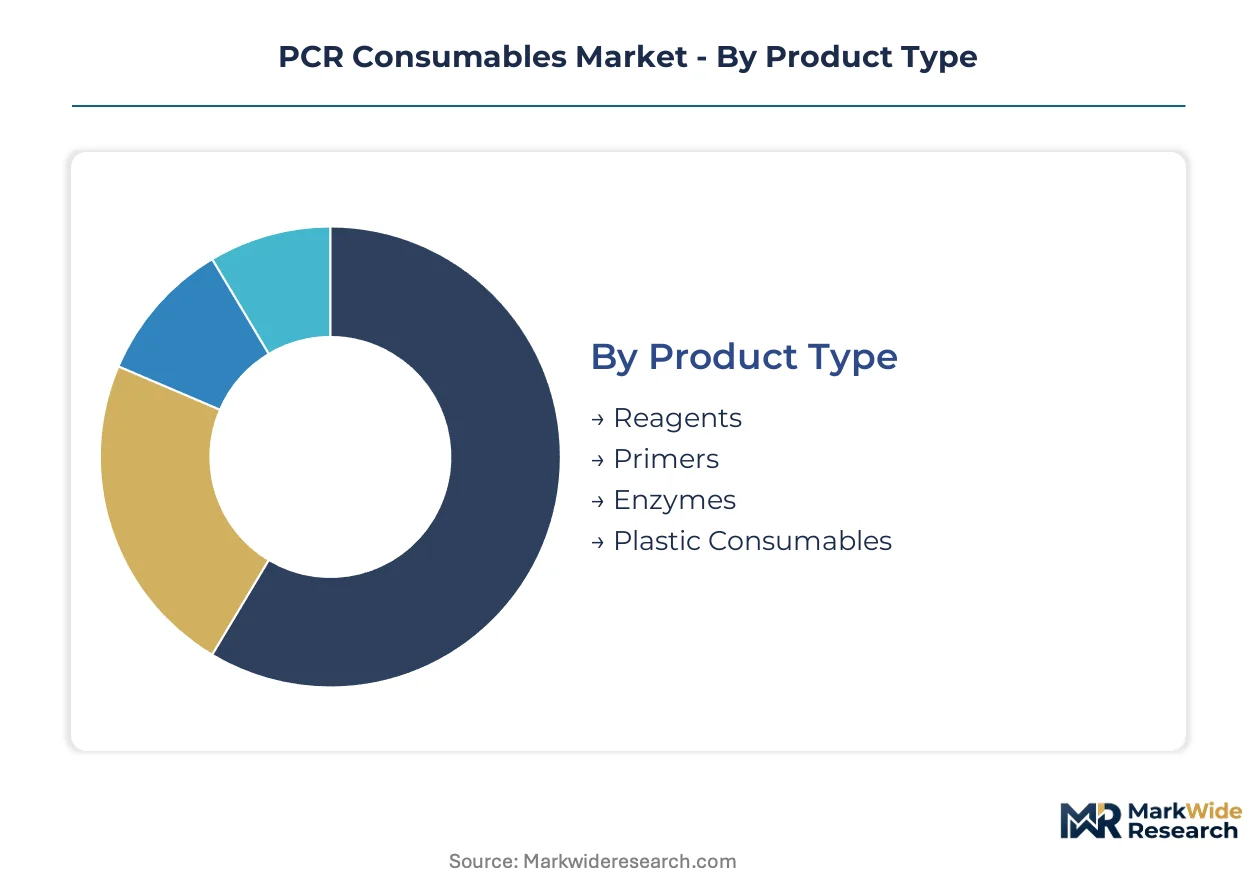
PCR consumables segmentation reveals how regulatory intensity, automation requirements, and end-use specialization fragment procurement patterns across research and clinical environments. Suppliers must align product portfolios with the distinct validation standards and volume economics governing each segment cluster.
Product Type:
FDA 21 CFR Part 820 and ISO 13485 quality management requirements create divergent compliance burdens across consumable categories, with clinical-grade plastics facing sterility assurance protocols that research-grade reagents bypass.
- Reagents:Polymerase-engineered hot-start formulations and master mix solutions dominate clinical diagnostic workflows. Demand concentrates in United States CLIA-certified laboratories where FDA oversight of laboratory-developed tests mandates validated lot-release documentation.
- Plastic Consumables:Polypropylene reaction tubes, microplates, and barrier-grade plastics engineered for thermal cycling between negative twenty degrees Celsius and ninety-five degrees Celsius. China's biopharmaceutical infrastructure expansion drives automation-compatible format adoption requiring dimensional tolerances for robotic liquid handling.
- Primers:Custom oligonucleotide synthesis for gene-specific amplification in research settings.
- Enzymes:Thermostable DNA polymerases and reverse transcriptases supporting qPCR and RT-PCR workflows.
Established volume favors plastic consumables; emerging adoption favors enzyme-engineered reagent portfolios.
End User:
Procurement centralization through group purchasing organizations is restructuring purchasing power concentration, with multi-hospital systems and academic consortia displacing departmental-level ordering autonomy.
- Clinical Laboratories:High-complexity molecular diagnostic facilities requiring FDA-compliant consumables with end-to-end traceability systems. United States infectious disease surveillance mandates are scaling testing volumes while tightening supplier audit requirements.
- Pharmaceutical Companies:Biopharmaceutical development operations in China and Western Europe demand high-throughput compatible consumable formats for genetic screening and cell-free DNA applications. Government funding for precision medicine initiatives is reshaping procurement specifications.
- Research Laboratories:Academic and contract research organizations with fragmented procurement patterns and higher price sensitivity.
- Academic Institutions:Budget-constrained environments where centralized research operations procurement is consolidating previously decentralized purchasing.
Margin concentration sits with clinical laboratories; volume expansion is climbing the fastest among pharmaceutical company accounts.
Application:
Application-specific performance requirements determine consumable grade selection, with diagnostic testing commanding premium positioning due to stringent lot-release protocols that genetic research applications circumvent.
- Diagnostic Testing:Infectious disease screening and molecular pathology requiring clinical-grade consumables with endotoxin testing and sterility assurance. United States laboratories are scaling volumes to meet pathogen monitoring mandates while EPA-regulated environmental testing creates field-deployable kit demand.
- Genetic Research:Academic gene expression studies and population genomics with lower regulatory barriers and price-sensitive procurement. China's domestic genetic research infrastructure investment is accelerating demand for automation-compatible microplate formats.
- Biopharmaceutical Development:Cell-free DNA and liquid biopsy applications requiring ultra-low DNA binding surfaces.
- Environmental Testing:EPA-mandated pathogen detection in water and soil matrices supporting municipal utility compliance sampling.
Revenue stability favors diagnostic testing; technology transition is gaining share fastest in biopharmaceutical development.
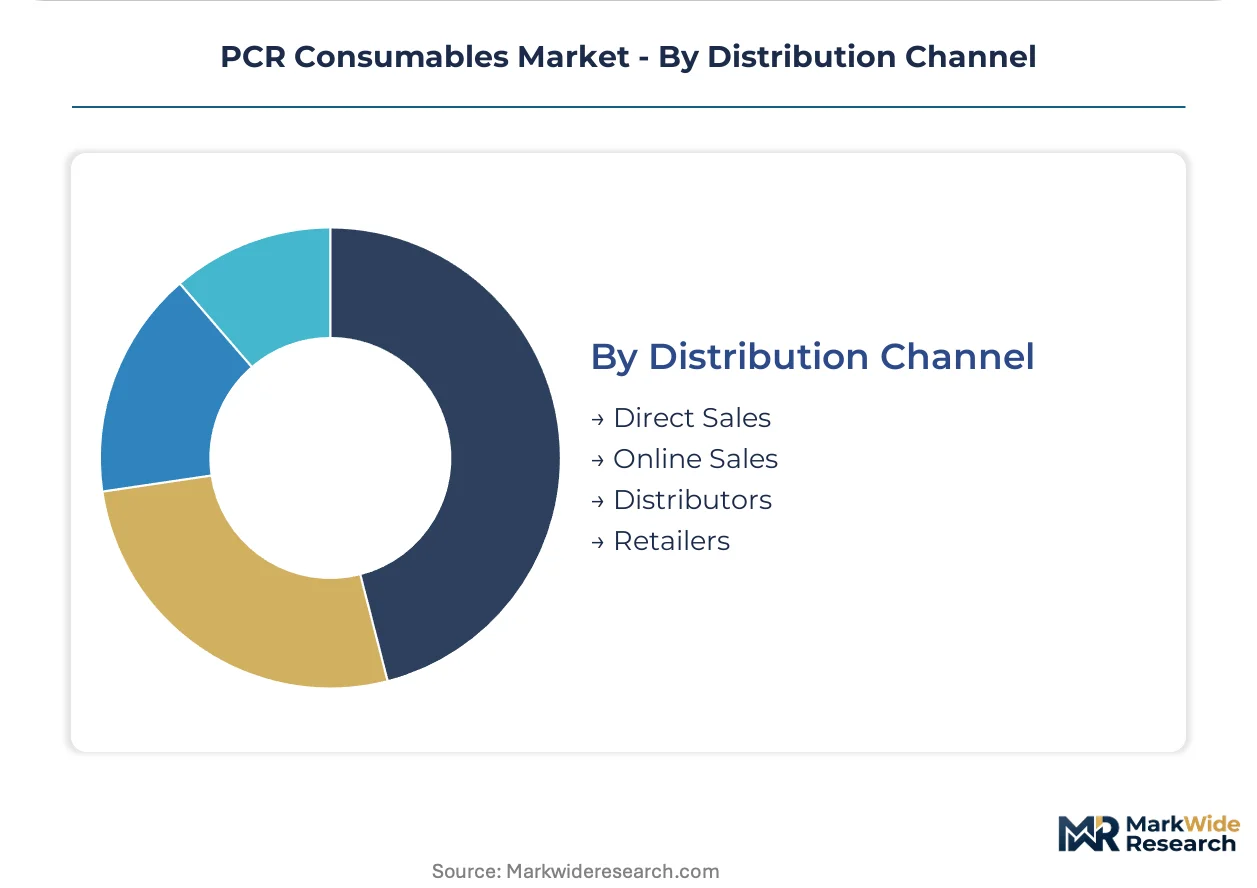
Distribution Channel:
Channel economics reflect the tension between technical support integration and margin preservation, with direct manufacturer relationships capturing volume-tiered pricing advantages that distributor intermediaries struggle to match.
- Direct Sales:Manufacturer relationships offering technical support integration and volume-tiered pricing for high-throughput clinical and pharmaceutical accounts. Consolidated procurement through group purchasing organizations is concentrating contract negotiation leverage in United States academic medical centers.
- Distributors:Multi-line intermediaries facing margin compression as direct channels expand. Established relationships with smaller research laboratories and academic institutions provide access to fragmented demand.
- Online Sales:E-commerce fulfillment of sample collection and stabilization kits is restructuring last-mile delivery economics for direct-to-consumer genetic testing.
- Retailers:Limited channel presence concentrated in educational supply and general laboratory equipment.
Relationship depth favors direct sales; channel expansion is steepest through online platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PCR consumables trade flows reflect divergent manufacturing capacity and diagnostic demand across major economies. The United States maintains a structural import reliance for specialized thermal cycling plastics while exporting enzyme formulations to clinical markets in Western Europe and Asia-Pacific.
United States
Infectious disease surveillance mandates from the FDA are scaling molecular diagnostic testing volumes in CLIA-certified laboratories. The EPA's pathogen monitoring requirements for water matrices create parallel demand for field-deployable consumable kits. The Boston-Cambridge biotech corridor anchors domestic reagent development, with specialized polymerase formulations shipping to pharmaceutical accounts nationwide.
Germany
Precision medicine initiatives from the Federal Ministry of Health are accelerating automation-compatible consumable procurement in academic medical centers. The EU Medical Device Regulation (MDR) harmonizes quality standards across diagnostic supply chains serving cross-border laboratory networks. The Rhine-Main region concentrates injection-molding capacity for clinical-grade polypropylene consumables serving Western European diagnostic laboratories.
China
Domestic biopharmaceutical infrastructure expansion is reshaping procurement specifications toward high-throughput compatible formats. NMPA oversight of in vitro diagnostic consumables tightens documentation requirements for imported reagents while favoring local manufacturers. The Yangtze River Delta biotech cluster in Shanghai-Suzhou anchors genetic research investment, with government funding accelerating automation adoption in precision medicine facilities.
Japan
Aging-population infectious disease screening programs from METI are sustaining diagnostic consumable demand in municipal health centers. PMDA quality management standards for clinical-grade plastics exceed ISO 13485 baselines, creating certification barriers for non-domestic suppliers. The Kansai region around Osaka maintains specialized mold-making expertise for ultra-low DNA binding surface technologies serving liquid biopsy research.
India
CDSCO's phased implementation of medical device rules is formalizing import registration requirements for PCR consumables serving private diagnostic chains. Government biotechnology parks in Genome Valley and Bengaluru are attracting contract research organizations with centralized consumable procurement specifications. Maharashtra's pharmaceutical manufacturing belt is developing backward integration into medical-grade resin compounding for thermal cycling applications.
PCR Consumables Market Competitive Landscape
Concentration sits with integrated life science conglomerates that control instrument-consumable ecosystems. The vendor base stratifies across three tiers: platform-native suppliers capturing recurring revenue through proprietary formats, independent reagent specialists competing on validation documentation, and regional injection-molding contractors serving price-sensitive research accounts. Dominant competitive moves include strategic partnerships for automation compatibility certification and geographic expansion through distributor acquisition in high-growth Asian markets.
Among diversified laboratory technology conglomerates, Thermo Fisher Scientific, Inc. and Danaher Corporation exemplify the platform-integration archetype that binds consumable demand to installed instrument bases. Bio-Rad Laboratories, Inc. occupies a distinct position within the specialized digital PCR workflow segment, representing the technology-differentiation strategy that competes outside conventional qPCR commodity dynamics. These three entities anchor the competitive structure without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Bio-Rad Laboratories, Inc. |
| F. Hoffmann-La Roche Ltd. |
| QIAGEN N.V. |
| Agilent Technologies, Inc. |
| Merck KGaA |
| Danaher Corporation |
| Abbott Laboratories |
| Promega Corporation |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month facility qualification timelines for ISO Class 7-8 cleanrooms concentrate supply-side leverage among established manufacturers while compressing pricing flexibility for new entrants seeking clinical-grade positioning. This lead-time barrier reinforces incumbent pricing power in FDA-regulated diagnostic segments while fragmenting research-grade markets among regional injection-molding contractors.
Pricing Analysis
The customization-premium spread between configured-to-order automation-compatible microplates and standard thermal cycling tubes spans three-tier pricing structure across premium, standard, and economy levels. Clinical-grade consumables with ISO 13485 certification and endotoxin testing command substantial premiums over research-grade alternatives, while volume-scale tiering through group purchasing organizations concentrates negotiation leverage among multi-hospital systems. Cost compression in standard polypropylene consumables intensifies because Gulf Coast petrochemical supply concentration exposes molders to resin price volatility. Academic institutions exhibit highest price sensitivity due to fragmented procurement and budget constraints, whereas CLIA-certified diagnostic laboratories prioritize validation documentation over unit cost.
Supply Chain Analysis
The United States and Germany anchor clinical-grade enzyme formulation and precision mold-making respectively, while China scales domestic injection-molding capacity for automation-compatible formats. Medical-grade polypropylene feedstock draws from Gulf Coast petrochemical complexes, with specialized hot-start polymerase enzymes sourced from Boston-Cambridge biotech corridors. Single-source vulnerability concentrates in thermal cycling plastic resin supply, where specialty polymer compounding lacks geographic diversification. Distribution runs through direct manufacturer relationships for high-throughput clinical accounts, with distributor intermediaries serving fragmented research laboratory demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against isothermal amplification substitution in point-of-care settings, where LAMP and CRISPR-based diagnostics erode conventional qPCR consumable volumes. Substitution defense requires platform-ecosystem reinforcement and workflow integration investments.
For Market Incumbents: Fortify instrument-consumable bundling through automation compatibility certification, locking in recurring revenue streams that standalone reagent vendors cannot replicate. Pursue backward integration into medical-grade resin compounding to insulate margin structures from Gulf Coast petrochemical volatility. Digital PCR workflow specialization offers differentiation against commodity qPCR price erosion. For New Entrants and Emerging Players: Anchor in EPA-mandated environmental testing applications, where field-deployable PCR consumable kits for water matrix pathogen detection lack established supplier relationships. Municipal utility compliance sampling represents penetrable white-space with standardized procurement specifications. Direct-to-consumer genetic testing channels enable e-commerce fulfillment bypassing traditional distributor markups. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to divest non-core consumable portfolios, particularly standalone reagent lines lacking instrument ecosystem integration. Five-to-ten-year viability hinges on automation compatibility and dual FDA-ISO certification positioning. Monitor NMPA localization requirements in China as inflection indicator for import-dependent supplier vulnerability.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Compatibility Certification | Robotic liquid handling integration secures high-throughput clinical and pharmaceutical accounts against commodity competitors. |
| Dual FDA-ISO Certification Investment | Quality management harmonization enables cross-border supply chain expansion into regulated diagnostic segments. |
| Backward Integration into Resin Compounding | Captive medical-grade polypropylene supply insulates margin structures from Gulf Coast petrochemical price volatility. |
| Direct-to-Consumer Channel Development | E-commerce fulfillment of sample collection kits restructures last-mile delivery economics for at-home genetic testing. |
| Digital PCR Workflow Specialization | Ultra-low DNA binding surface technologies command premium positioning in liquid biopsy and cell-free DNA applications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with laboratory directors, GPO contracts managers, biomedical engineers, and diagnostic procurement leads; and secondary validation through FDA 510(k) filings, ISO 13485 certification databases, EPA environmental testing protocols, and customs trade records for thermal cycling plastics. Bottom-up demand modeling across end-user segments triangulated against top-down supply-side capacity assessments for injection-molding and enzyme formulation.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across product type, end-user category, application area, and distribution channel, with regional regulatory cluster overlays for FDA, EU MDR, NMPA, and PMDA jurisdictions. CAGRs derived from historical volume trajectories, capacity expansion announcements, and infectious disease surveillance mandate scaling. Forecast inputs incorporated CLIA-certified laboratory testing volume trends and precision medicine government funding allocations.
Underlying assumptions cover sustained infectious disease surveillance investment, stable medical-grade resin supply, and continued platform lock-in effects, with deviation risk concentrated in isothermal amplification technology substitution and regulatory harmonization delays. Recalibration cycles align with material shifts in FDA laboratory-developed test guidance and NMPA import registration requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Robotic Arms in Laboratories Market
Biotechnology Equipment
Micro-Bioreactors Market
Biotechnology Equipment
Automated Cell Culture Systems Market
Biotechnology Equipment
Global Transfection Technologies Market
Biotechnology Equipment
Plant Phenotyping Equipment Market
Biotechnology Equipment
Lab Automation for in-Vitro Diagnostics Market
Biotechnology Equipment
Global Recombinant Cell Culture Supplements Market
Biotechnology Equipment
Global Bioreactor Market
Biotechnology Equipment
Airlift Bioreactors Market
Biotechnology Equipment
Single Use Bioprocessing Market
Biotechnology Equipment
Histology Equipment Market
Biotechnology Equipment
In-Vitro Fertilization (IVF) Microscopes Market
Biotechnology Equipment
Laboratory Shakers Market
Biotechnology Equipment
Automated Cell Culture Equipment Market
Biotechnology Equipment
Fluorescence Immunoassay Analyzers Market
Biotechnology Equipment
Global Biological Safety Cabinets Market