
 Histology Equipment Market | 2026-2036
Histology Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Histology Equipment Market Intelligence
A shift from single-vendor procurement to multi-vendor ecosystems for automated systems is pivoting purchasing decisions in large hospital networks. Leica Biosystems Nussloch GmbH specializes in high-throughput automated stainers and digital pathology scanners. Thermo Fisher Scientific Inc. competes with a broad portfolio spanning tissue processors to microtomes. Roche Diagnostics International Ltd leverages its strong position in companion diagnostics to drive instrument placement in clinical settings.
Histology equipment includes instruments for preparing biological tissue for microscopic analysis. These devices perform critical functions like processing, embedding, and sectioning tissue into micron-thin slices for pathological review. Among product types, automated tissue processors and stainers lead in adoption by diagnostic laboratories. The shift to digital technology accelerates demand for high-throughput slide scanners, which constitute the fastest-growing segment.
Market access is governed by stringent regulatory frameworks for medical devices. The US FDA's 510(k) clearance pathway, Europe's In Vitro Diagnostic Regulation (IVDR), and China's NMPA approvals dictate design and quality system requirements. These regulations ensure clinical performance and patient safety. Stakeholders must now focus on integrating artificial intelligence into digital pathology workflows to enhance diagnostic accuracy and efficiency.
Market Dynamics
The central force shaping the histology equipment market is the industrialization of the pathology laboratory. This is driven by the dual pressures of rising cancer diagnostic volumes and a persistent shortage of skilled pathologists, compelling a structural shift toward automation and digital workflows.
Growth Catalysts
- Public Health Initiatives:National cancer screening programs, particularly in China, are expanding public diagnostic infrastructure, directly fueling demand for high-throughput tissue processors and stainers to manage increased testing loads.
- Digital Pathology Adoption:The transition to digital slide scanners enables remote case review, workload balancing, and the application of AI-based image analysis, which enhances diagnostic consistency and efficiency in large pathology networks.
- Companion Diagnostics Expansion:The growth of personalized medicine and companion diagnostics requires precise, standardized tissue staining to identify biomarkers, increasing the clinical necessity for advanced automated staining systems in oncology.
Market Restraints
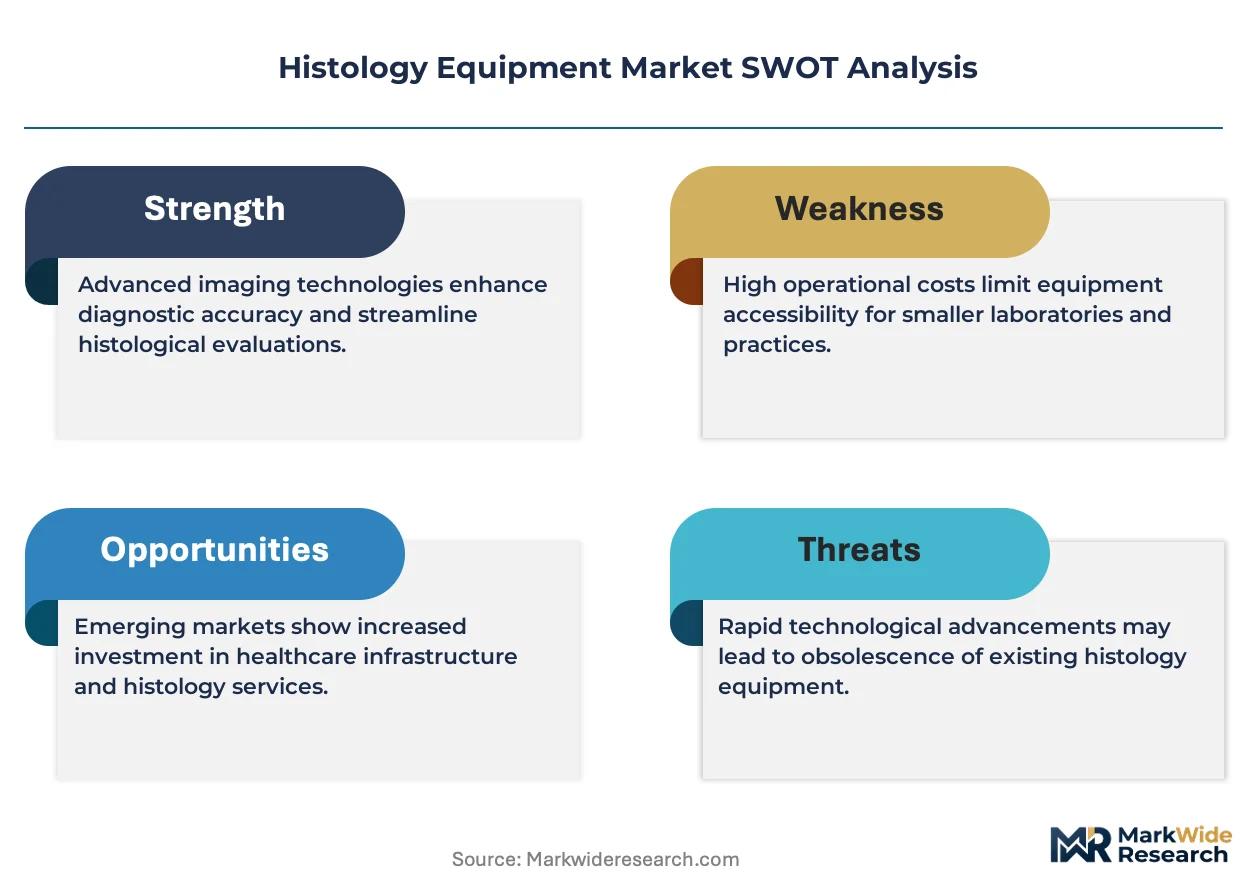
- High Capital Expenditure:The significant upfront investment required for fully automated histology systems and digital pathology scanners creates a substantial adoption barrier for smaller independent laboratories and hospitals in emerging economies.
- Regulatory Compliance Burden:Navigating the stringent and divergent requirements of the US FDA's 510(k) pathway, Europe's IVDR, and China's NMPA adds considerable cost and time to product development and market entry.
- Data Management Infrastructure:Digital pathology generates massive data files, requiring significant investment in high-capacity storage servers, robust networking, and secure IT infrastructure, which can exceed the cost of the scanner itself.
Strategic Opportunities
- AI-Powered Diagnostic Tools:Integrating artificial intelligence and machine learning algorithms with digital pathology scanners offers a significant opportunity to develop computer-aided detection and quantification tools that improve diagnostic accuracy and pathologist productivity.
- Geographic Expansion:Markets in Latin America, such as Brazil, and Southeast Asia represent untapped regions where modernizing healthcare infrastructure and a growing middle class create new demand for basic and automated histology instruments.
- CRO and Pharma Services:Expanding instrument placement within contract research organizations (CROs) for preclinical toxicology studies and drug development presents a key growth vector beyond the core clinical diagnostics segment.
Industry Challenges
- Specialized Talent Scarcity:A shortage of histotechnologists and pathologists trained in digital pathology workflows and computational analysis creates an operational bottleneck, limiting the effective utilization of advanced automated systems.
- Interoperability and Standardization:A lack of standardized file formats for digital slides across different scanner manufacturers complicates the integration of multi-vendor systems and hinders the development of universal third-party analysis applications.
- Legacy System Integration:Connecting new automated histology platforms with existing, often proprietary, Laboratory Information Systems (LIS) in hospitals is a complex and resource-intensive challenge for IT departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Histology Equipment Market |
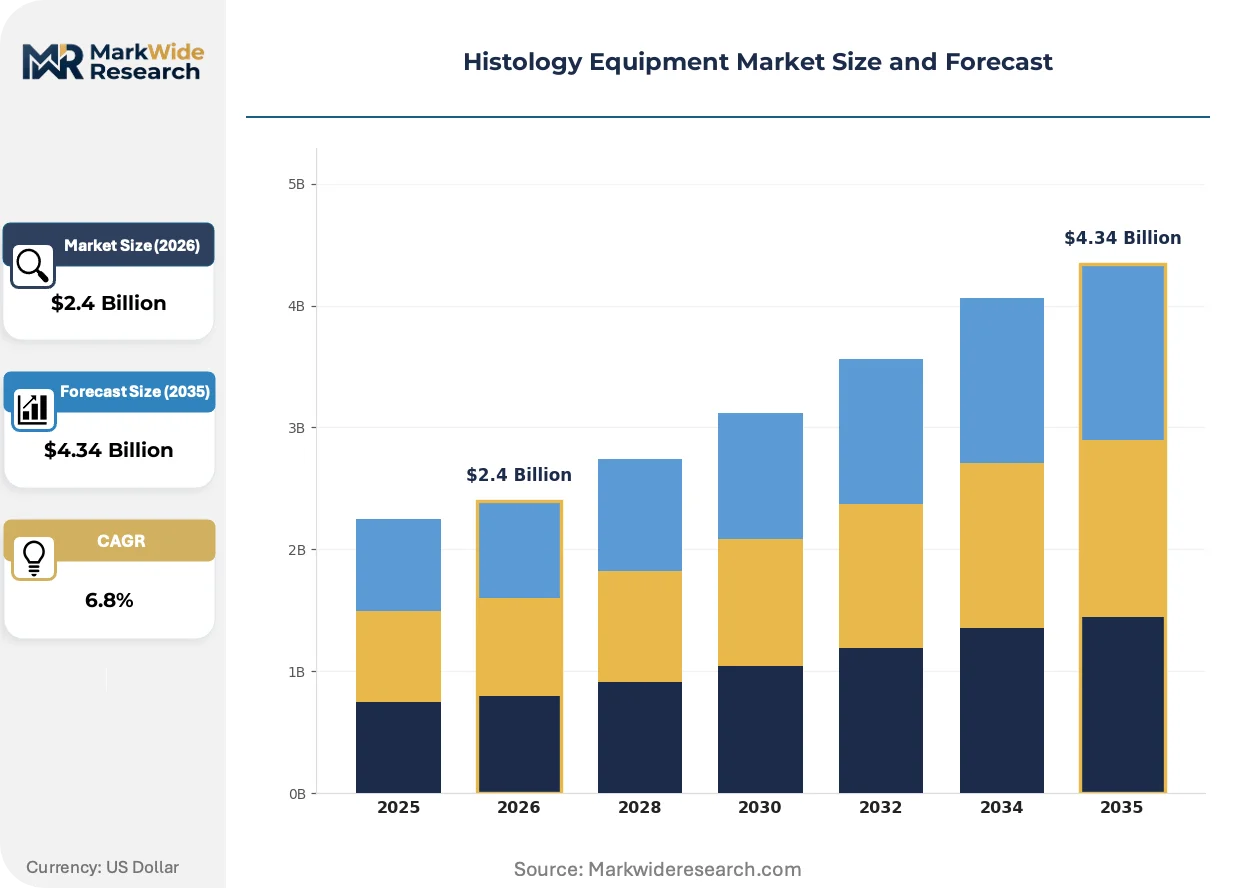
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microtomes, Stainers, Tissue Processors, Embedding Stations Application: Diagnostic Laboratories, Research Institutions, Clinical Settings, Pharmaceutical Companies End User: Hospitals, Academic Institutions, Contract Research Organizations, Pathology Labs Technology: Optical, Automated, Digital, Manual |
| Companies Covered | Danaher, Sakura Finetechnical Company Ltd., Thermo Fisher Scientific Inc., BioGenex Laboratories Inc, Hologic Inc., Roche Diagnostics International Ltd, Leica Biosystems Nussloch GmbH, StatLab Medical Products Inc., Agilent Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Histology Equipment Market Strategic Shifts & Innovations
The evolution of histology equipment is marked by a decisive pivot from standalone analog instruments to interconnected, data-centric ecosystems. This transformation redefines laboratory workflows, emphasizing throughput, standardization, and the extraction of quantitative data from tissue samples for clinical and research applications.
Digital slide scanning technology converts physical glass slides into high-resolution whole-slide images. Large-scale diagnostic laboratories and pharmaceutical research centers are the primary adopters, driven by the need to streamline workflows and facilitate remote collaboration among specialists. This shift from physical to digital media is electrifying the pathology field, enabling the application of computational analysis and artificial intelligence at an unprecedented scale.
Europe's In Vitro Diagnostic Regulation (IVDR) imposes more rigorous requirements on manufacturers for clinical evidence, risk management, and post-market surveillance. This regulatory shift increases the compliance burden for all histology equipment, extending development timelines and costs. The automated stainer and digital scanner segments are most impacted, as vendors must now generate more extensive performance validation data to obtain and maintain CE marking for clinical use.
A notable behavioral change involves large hospital networks moving away from single-vendor, sole-source contracts for their entire histology instrument suite. These organizations now favor a best-of-breed procurement strategy, integrating tissue processors, stainers, and scanners from different specialized vendors to optimize performance. This trend is most visible in North American and European healthcare systems, disrupting traditional bundled sales models and promoting greater interoperability.
Histology Equipment Market Segmentation
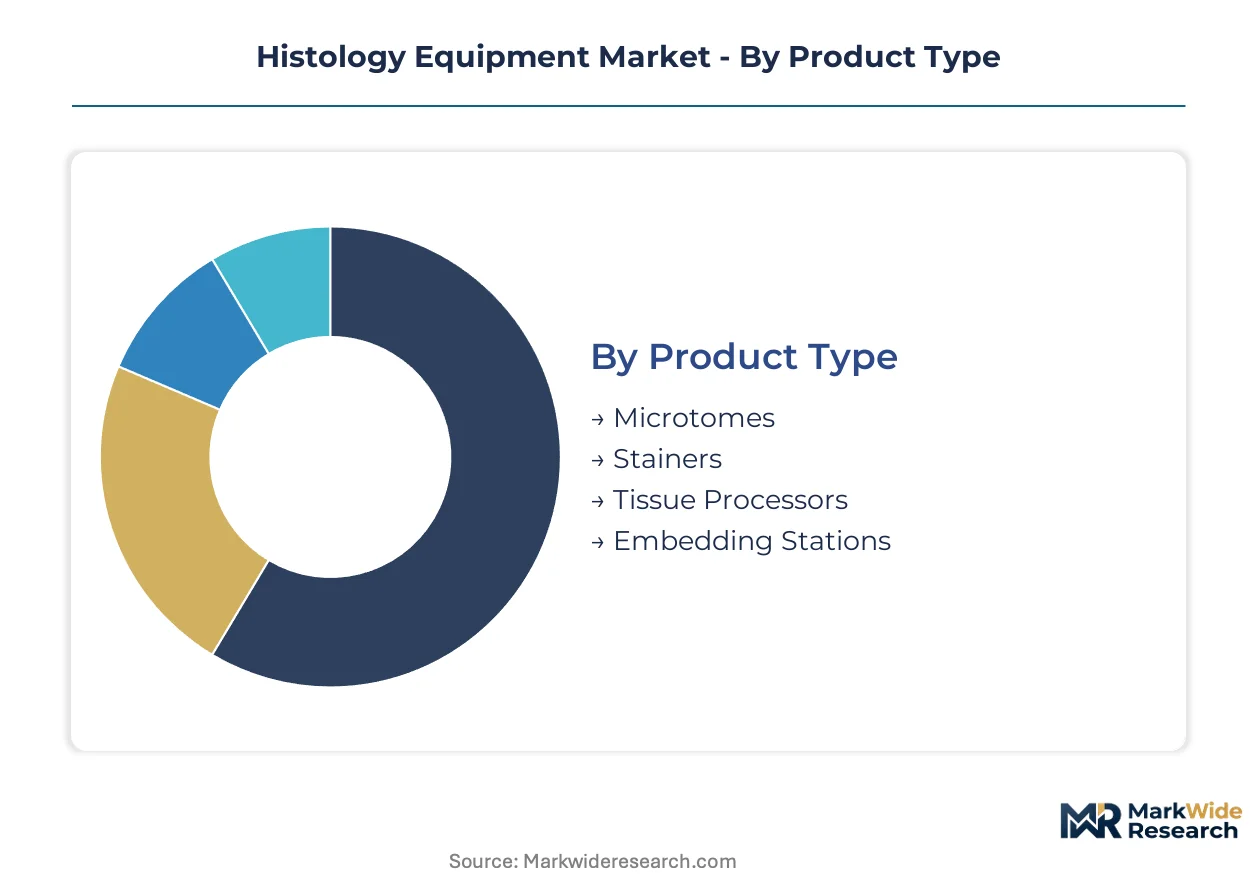
The histology equipment market's segmentation highlights the diverse functional requirements and technological advancements driving product development and adoption across various clinical and research settings. Understanding these segments is crucial for identifying specific demand patterns and strategic investment areas within the diagnostics industry.
Product Type:
The product type segmentation highlights how instruments range from standalone units to components integrated within broader automated pathology workflows.
- Stainers:Automated stainers apply reagents to tissue sections for microscopic examination, crucial for biomarker identification and diagnostic accuracy. Demand concentrates in diagnostic laboratories for cancer screening, driven by the need for standardized, high-throughput processing.
- Tissue Processors:Tissue processors fix, dehydrate, and infiltrate tissue samples with paraffin, preparing them for embedding and subsequent sectioning. Clinical settings and large pathology laboratories drive demand for these automated systems to handle increasing diagnostic volumes.
- Microtomes:Microtomes precisely cut paraffin-embedded tissue blocks into extremely thin sections for slide preparation, essential for detailed histological analysis.
- Embedding Stations:Embedding stations orient processed tissue samples into paraffin blocks, forming the foundational step for subsequent sectioning and microscopic review.
Automated tissue processors lead volumes today; stainers are gaining share fastest.
Application:
Application segments reflect distinct operational scales and workflow requirements for histology equipment across various user environments.
- Diagnostic Laboratories:These laboratories perform routine and specialized pathological analyses, relying on histology equipment for high-volume tissue processing and slide preparation. Demand is high in regions like China due to expanding public health initiatives and cancer screening programs.
- Clinical Settings:Hospitals and clinics use histology instruments for rapid diagnosis and patient management, integrating them into their pathology departments. The expansion of personalized medicine and companion diagnostics drives instrument placement in these environments.
- Research Institutions:Academic and government research centers utilize histology equipment for basic science, disease modeling, and drug discovery studies.
- Pharmaceutical Companies:Pharmaceutical companies employ histology tools for preclinical toxicology, drug efficacy testing, and biomarker identification in drug development pipelines.
Diagnostic laboratories represent the largest segment; clinical settings are expanding most quickly.
End User:
End-user segments differentiate based on the maturity of their pathology infrastructure and their investment capacity for advanced histology systems.
- Hospitals:Hospital pathology departments serve as primary end-users, requiring histology equipment for patient diagnostics and surgical pathology. Large hospital networks are shifting towards multi-vendor procurement strategies for automated systems.
- Pathology Labs:Independent and networked pathology laboratories specialize in high-volume diagnostic testing, necessitating efficient and automated histology workflows. These labs increasingly adopt digital pathology to manage caseloads and enable remote review.
- Academic Institutions:Universities and medical schools utilize histology equipment for teaching, fundamental research, and training future pathologists.
- Contract Research Organizations:CROs employ histology instruments for preclinical studies and drug development services for pharmaceutical and biotechnology clients.
Hospitals constitute the largest end-user group; Contract Research Organizations are climbing the fastest.
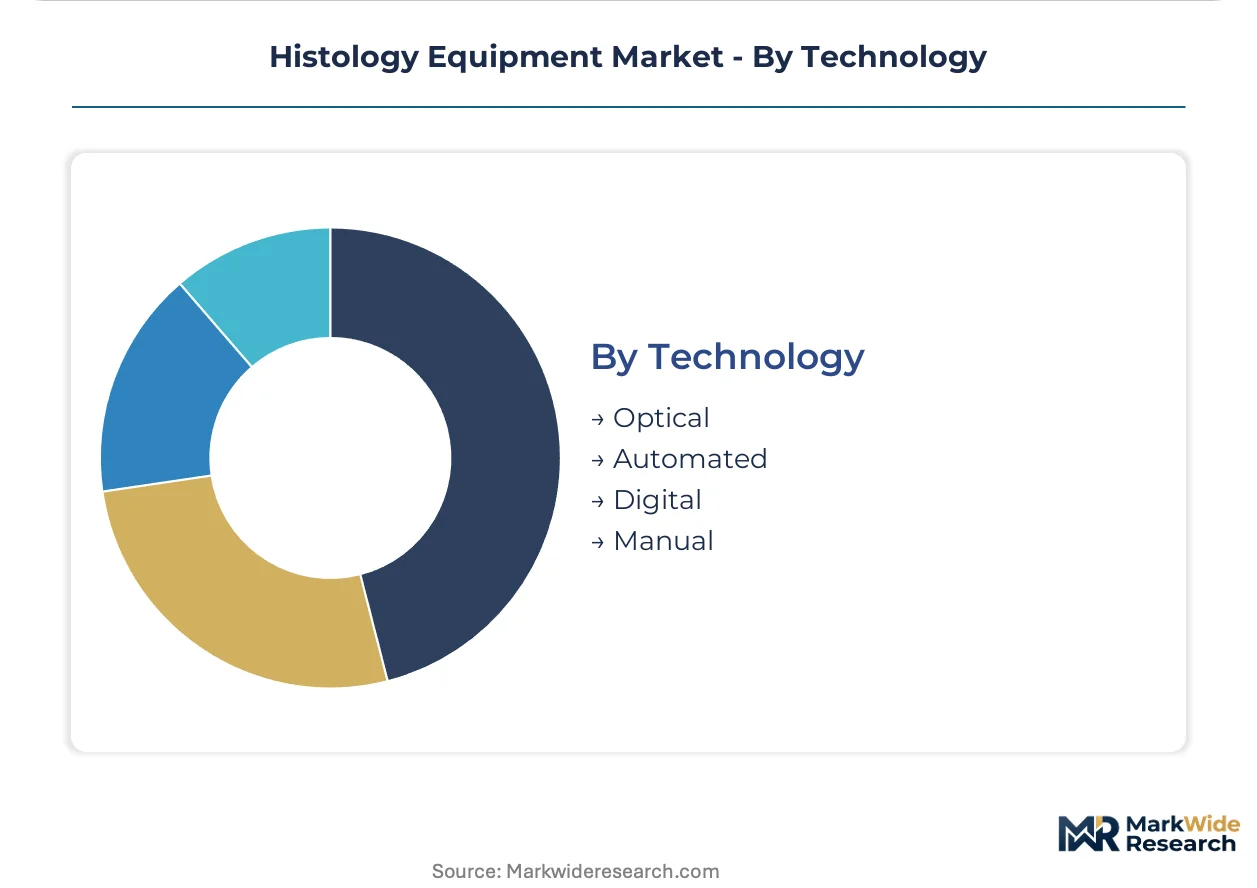
Technology:
Technology segments reflect the varying levels of automation and data integration available, influencing supplier specialization and market concentration.
- Automated:Automated systems perform multiple histology steps with minimal human intervention, enhancing throughput and standardization. These technologies are crucial for industrializing pathology laboratories facing rising cancer diagnostic volumes.
- Digital:Digital pathology involves whole-slide imaging and software for image analysis, facilitating remote diagnostics and AI integration. High-throughput slide scanners represent the fastest-growing segment within this technological shift.
- Optical:Optical technology primarily refers to traditional light microscopy used for visual examination of stained tissue slides.
- Manual:Manual methods involve labor-intensive, hands-on techniques for tissue processing, embedding, and sectioning, often used in smaller laboratories or for specialized procedures.
Optical technologies maintain a foundational presence; digital technologies show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's expanding public health initiatives, particularly national cancer screening programs, significantly influence the global histology equipment market. These programs drive demand for advanced diagnostic infrastructure and high-throughput instruments. Regional dynamics reflect varied healthcare investment levels and regulatory landscapes across major economies.
China
Demand for high-throughput tissue processors and stainers is strong in China, fueled by expanding public health initiatives. The NMPA's stringent approval processes ensure device quality and clinical performance. Major diagnostic laboratories in cities like Shanghai and Beijing are rapidly adopting automated systems to manage increasing testing volumes.
United States
The United States market is characterized by a strong emphasis on personalized medicine and digital pathology adoption. The US FDA's 510(k) clearance pathway governs market access for new histology devices. Large hospital networks in regions such as the Boston-Cambridge biotech cluster are implementing AI-powered diagnostic tools to enhance pathologist productivity.
Germany
Germany represents a mature market with a focus on advanced automation and precision instruments, influenced by Europe's In Vitro Diagnostic Regulation (IVDR). The IVDR imposes rigorous requirements for clinical evidence and post-market surveillance. Medical technology hubs in Bavaria and Baden-Württemberg lead in developing sophisticated automated stainers and digital slide scanners.
Brazil
Brazil offers significant growth opportunities for basic and automated histology instruments due to modernizing healthcare infrastructure. ANVISA regulations guide the approval and commercialization of medical devices within the country. Public and private hospitals in São Paulo and Rio de Janeiro are investing in equipment to improve diagnostic capabilities.
India
India's market expansion is driven by a growing middle class and increasing investment in healthcare infrastructure. The CDSCO regulates medical device imports and manufacturing, ensuring product safety and efficacy. Diagnostic chains and research institutions in metropolitan areas like Mumbai and Bangalore are upgrading their pathology laboratories.
Histology Equipment Market Key Industry Players
Global majors compete with regional champions across technology innovation and market access strategies within the histology equipment sector. The market exhibits a tiered structure, with a few large integrated providers alongside numerous specialized instrument manufacturers. Strategic archetypes include comprehensive solution providers, automation specialists, and digital pathology innovators. Dominant competitive moves involve portfolio diversification and strategic partnerships to integrate digital workflows.
Specialists in high-throughput automation include Leica Biosystems Nussloch GmbH, known for its advanced stainers and digital pathology scanners. Thermo Fisher Scientific Inc. occupies a broad position, offering a wide portfolio from tissue processors to microtomes. Roche Diagnostics International Ltd leverages its strong companion diagnostics presence to drive instrument placement in clinical settings.
| Leading Market Players |
|---|
| Danaher |
| Sakura Finetechnical Company Ltd. |
| Thermo Fisher Scientific Inc. |
| BioGenex Laboratories Inc |
| Hologic Inc. |
| Roche Diagnostics International Ltd |
| Leica Biosystems Nussloch GmbH |
| StatLab Medical Products Inc. |
| Agilent Technologies Inc. |
| Others |
Cost & Logistics Intelligence
Histology equipment has a clear performance gap between manual/optical technologies and automated/digital systems. This gap drives distinct pricing models and influences the specialized supply chains for high-precision components.
Pricing Analysis
Input cost fluctuations for specialized optics and high-precision mechanical parts directly influence histology equipment pricing. A three-tier pricing structure across premium, standard, and economy levels prevails, differentiated by automation level and regulatory clearance. Pricing softness runs through the standard segment due to regional competition. Smaller independent laboratories exhibit the highest price sensitivity, whereas large hospital networks prioritize comprehensive service agreements.
Supply Chain Analysis
Direct sales forces and specialized distributors primarily manage histology equipment placement in global markets. Supply for advanced optical components and precision robotics concentrates in Germany, Japan, and the United States. The industry relies on specialized optics and microprocessors. Single-source vulnerability for advanced imaging sensors represents a significant supply chain risk. Large hospital networks often procure directly from manufacturers for integrated solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The histology equipment market presents a geographic-arbitrage opportunity, particularly given the lower manufacturing costs in Asian economies compared to the stringent regulatory compliance burdens in Europe.
For Market Incumbents:
Lock in existing customer bases by expanding integrated digital pathology ecosystems. Acquire specialized AI software firms to counter emerging digital pathology startups. Deepen vertical integration into high-precision component manufacturing to control quality and cost. Invest heavily in R&D for advanced AI algorithms to maintain a performance edge against new entrants.
For New Entrants and Emerging Players:
A price-point gap exists between premium automated systems and basic manual equipment, creating entry points. Target mid-tier diagnostic laboratories in Southeast Asia and independent pathology labs in Latin America. Focus on automated stainers for routine diagnostics, offering cloud-based digital pathology platforms with subscription models. Emphasize ease of use and lower total cost of ownership for market penetration.
For Investors and Strategic Acquirers:
Consolidation pressure builds where fragmented digital pathology solutions hinder interoperability in large hospital networks. The market offers long-term growth opportunities over the next decade. Target vertically integrated mid-cap specialists in digital pathology with strong software capabilities. The signal to watch is increased regulatory clarity for AI-powered diagnostic tools from bodies like the US FDA or Europe's EMA.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Software Acquisition | Bolsters diagnostic accuracy and efficiency for existing digital pathology platforms. |
| Geographic Market Entry | Expands reach into underserved regions like Latin America with modernizing healthcare infrastructure. |
| Interoperability Partnerships | Addresses industry challenges by integrating multi-vendor systems and standardizing data formats. |
| Cloud Platform Development | Facilitates remote diagnostics and AI-based image analysis for pathology laboratories. |
| Regulatory Compliance Investment | Ensures market access and accelerates product development under stringent frameworks like Europe's IVDR. |
Research Approach
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region. Interviews included pathologists, histotechnologists, medical device procurement managers, and R&D directors. Secondary validation drew from regulatory filings with the US FDA and China's NMPA, academic publications, and industry association reports. This approach enabled bottom-up and top-down triangulation of market data.
Rate-of-change decomposition informed the market forecast across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end user, technology, and regional regulatory environment. Compound Annual Growth Rates derived from historical trends and projected adoption rates. Key inputs included cancer incidence rates and diagnostic laboratory expansion plans.
Caveats apply where unforeseen regulatory changes or rapid AI integration could materially shift the outlook. Forecasts reflect current assumptions regarding technological evolution and market adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
US Cell Culture Media Market
Biotechnology Equipment
Cellular Localization Kits Market
Biotechnology Equipment
Bioreactors Accessories Market
Biotechnology Equipment
Fluidized-Bed Bioreactors Market
Biotechnology Equipment
Tissue Processor Equipment Market
Biotechnology Equipment
Global Viral RNA Extraction Kit Market
Biotechnology Equipment
Global Plant Cell Culture Equipment Market
Biotechnology Equipment
PCR Master Mix Market
Biotechnology Equipment
Global DNA/RNA Extraction Kit Market
Biotechnology Equipment
Single-Use Bioprocess Sensor Calibration and Validation Test Systems Market
Biotechnology Equipment
Life Science Instrumentation Market
Biotechnology Equipment
Cryogenic Vial Rack Market
Biotechnology Equipment
Global Latex Agglutination Test Kits Market
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
Fluorescence Immunoassay Analyzers Market
Biotechnology Equipment
Cell and Tissue Culture Supplies Market