
 Global Flu Vaccine Market | 2026-2036
Global Flu Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flu Vaccine Market Analysis
Bioprocess engineering talent is bifurcating the competitive landscape as cell-culture and mRNA expertise outpaces traditional egg-based vaccine manufacturing skills. Sanofi leverages its integrated European and US manufacturing network to sustain quadrivalent supply continuity across multiple continents. CSL Limited anchors Southern Hemisphere demand through its established influenza franchise and seasonal strain-matching capabilities. Moderna competes with mRNA platform adaptability that shortens strain-update cycles relative to conventional approaches.
Flu vaccines are sterile biological preparations containing inactivated viruses, live attenuated strains, or recombinant hemagglutinin proteins formulated to induce protective antibody responses against predicted seasonal influenza strains; manufacturers cultivate candidate vaccine viruses in embryonated eggs or mammalian cell lines before purification, inactivation, and standardization to specified antigen content per dose. Quadrivalent formulations now dominate commercial portfolios as health authorities in multiple countries have shifted from trivalent to four-strain coverage. Recombinant vaccines represent the fastest-expanding product category among structural segments, driven by shorter production timelines and elimination of egg-adaptation mutations that can compromise strain match. The elderly age group commands concentrated R&D investment due to immunosenescence and the clinical priority of reducing hospitalization burden in this population.
FDA strain selection recommendations and EMA marketing authorization requirements shape annual formulation decisions and manufacturing timelines for suppliers serving Western markets. WHO Global Influenza Surveillance and Response System coordinates hemisphere-specific strain recommendations that national regulators in China, India, and Japan translate into local labeling and procurement specifications. China's NMPA and India's CDSCO have tightened post-marketing surveillance obligations for imported and domestically produced vaccines, elevating quality-system investments for market participants. Stakeholders must monitor cell-culture capacity buildouts and mRNA technology transfer agreements as these manufacturing transitions reshape supplier rankings and procurement contract structures.
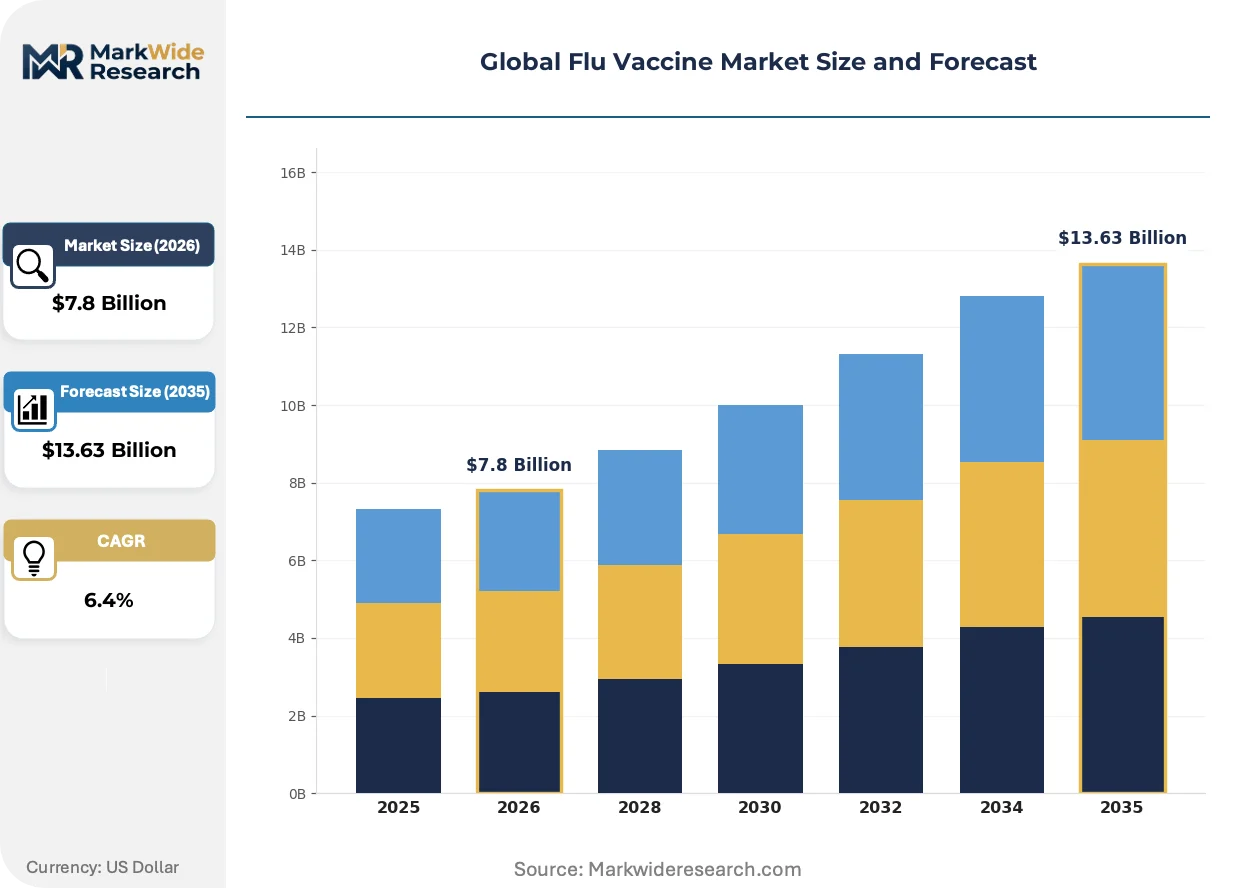
Market Dynamics
Cell-culture and recombinant manufacturing platforms are redrawing supplier capabilities as egg-based production loses regulatory preference and procurement contracts increasingly specify non-egg formulations.
Growth Catalysts
- Pediatric schedule expansion:National immunization programs in India and China now mandate annual influenza vaccination for school-age populations, broadening the addressable patient base beyond traditional elderly and high-risk cohorts.
- WHO strain coordination:The Global Influenza Surveillance and Response System accelerates hemisphere-specific recommendations, compressing the formulation-to-distribution timeline and reducing inventory obsolescence risk for manufacturers.
- Cell-culture capacity:Mammalian cell-line production eliminates egg-adaptation mutations that compromise strain match fidelity, satisfying EMA and FDA quality standards that now penalize antigenic drift in final formulations.
Market Restraints
- Embryonated egg supply concentration:Specialist poultry farming operations in the United States and Europe control the majority of pathogen-free egg supply, creating single-source vulnerability for manufacturers maintaining hybrid production footprints.
- Recombinant protein input costs:Baculovirus vector systems and insect cell substrates carry higher per-dose material costs than conventional egg-based cultivation, compressing margins in price-sensitive procurement environments.
- Strain-matching uncertainty:Antigenic drift between vaccine composition and circulating viruses reduces real-world effectiveness, undermining payer confidence and complicating value-based reimbursement negotiations.
Strategic Opportunities
- Universal vaccine platforms:Hemagglutinin stalk-targeting immunogens and mosaic nanoparticle constructs promise multi-season protection, potentially collapsing the annual reformulation cycle that constrains manufacturer economics.
- Adjuvanted formulations for immunosenescence:MF59 and AS03 adjuvant systems address antibody response decline in elderly populations, opening premium pricing tiers in Japan and Western European markets with aging demographics.
- Direct-to-pharmacy distribution:Bypassing centralized public health procurement through retail pharmacy networks captures patient convenience preference and reduces seasonal campaign logistics complexity.
Industry Challenges
- Bioprocess engineering scarcity:Cell-culture scale-up expertise and mRNA formulation science outpace traditional vaccine manufacturing training pipelines, forcing compensation inflation for qualified technical personnel.
- Post-marketing surveillance compliance:China's NMPA and India's CDSCO have intensified pharmacovigilance reporting requirements, extending regulatory affairs headcount needs and documentation burdens for market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flu Vaccine Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inactivated Vaccine, Live Attenuated Vaccine, Recombinant Vaccine, Quadrivalent Vaccine End User: Hospitals, Clinics, Pharmacies, Individuals Age Group: Children, Adults, Elderly, Pregnant Women Distribution Channel: Direct Sales, Wholesale, Retail, Online |
| Companies Covered | Sanofi, GSK plc, CSL Limited, AstraZeneca plc, Moderna, Inc., BIKEN Co., Ltd., Abbott Laboratories, SINOVAC Biotech Ltd., Viatris Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flu Vaccine Market Emerging Trajectories
mRNA platform adaptability is compressing strain-update timelines and enabling pandemic-response manufacturing repurposing that egg-based infrastructure cannot match.
Recombinant hemagglutinin production is fragmenting the supplier landscape as baculovirus-insect cell systems permit modular manufacturing scale without dedicated embryonated egg supply chains. Hospital systems and retail pharmacy chains in the United States are accelerating adoption of these formulations where formulary committees prioritize strain-match fidelity. The technology is fragmenting procurement concentration as regional biomanufacturing facilities achieve regulatory qualification without legacy egg-supply dependencies.
EMA's marketing authorization requirements for quadrivalent formulations now mandate four-strain immunogenicity data that exceeds former trivalent submission standards, extending clinical development timelines and documentation burdens. Manufacturers serving European markets must demonstrate non-inferiority across all four recommended strains simultaneously, elevating trial complexity and statistical powering requirements. Pediatric and elderly indication expansions face the steepest compliance costs as these populations require separate safety and immunogenicity cohorts.
Retail pharmacy chains are capturing seasonal vaccination volume from traditional physician office settings as convenience-seeking patients prioritize extended hours and walk-in accessibility over established provider relationships. CVS Health and Walgreens in the United States, plus Boots and LloydsPharmacy in the United Kingdom, now administer the majority of adult doses in their respective markets. This channel migration pressures manufacturer contracting strategies as pharmacy buyers consolidate purchasing power and demand differentiated margin structures compared to public health procurement entities.
Global Flu Vaccine Market Segmentation
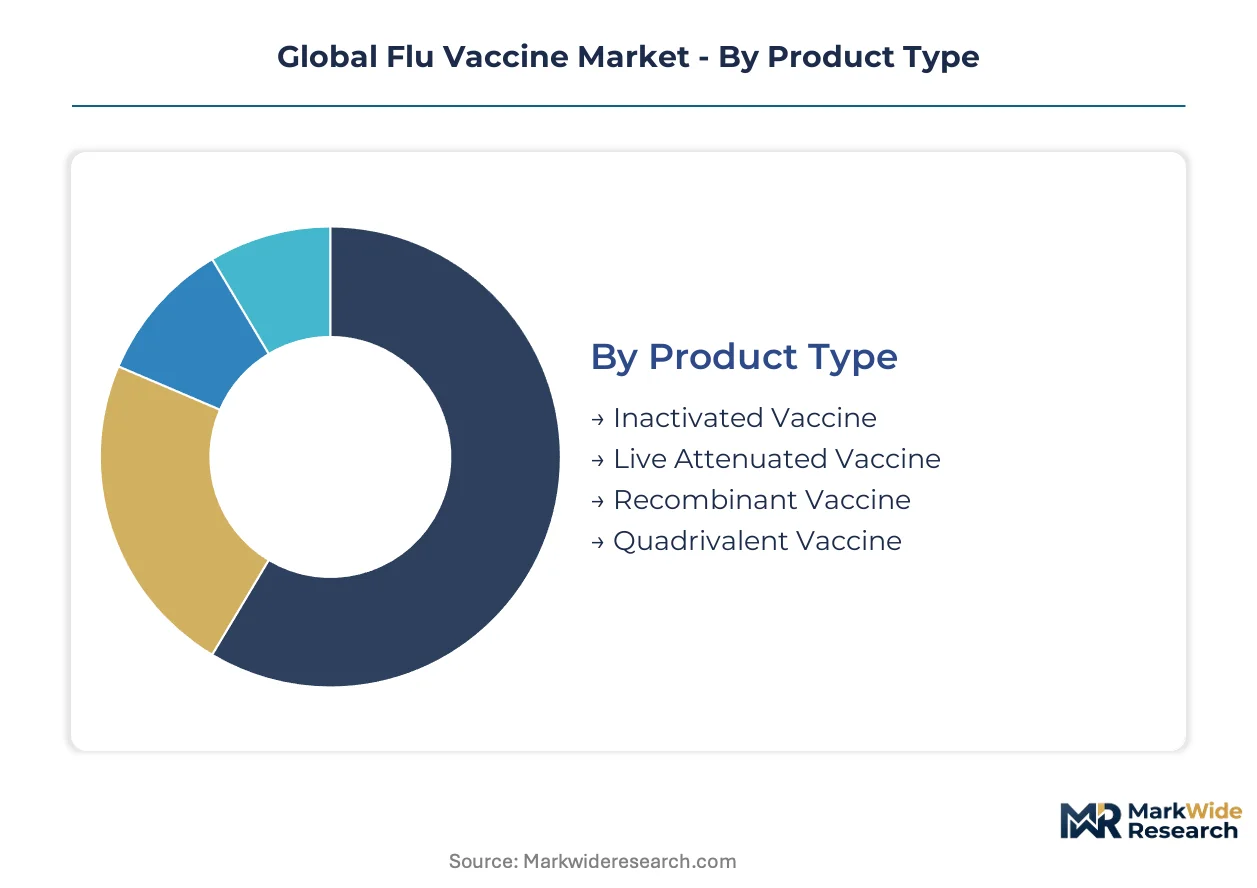
Flu vaccine manufacturers configure product portfolios across four intersecting dimensions. Each segmentation layer determines pricing power, regulatory pathway complexity, and channel access requirements.
Product Type:
Margin pools concentrate in recombinant and quadrivalent formulations as health authorities penalize egg-adaptation drift and procurement contracts specify four-strain coverage.
- Inactivated Vaccine:Virions chemically or physically inactivated to destroy replication capacity while preserving immunogenic surface antigens. Demand concentrates in pediatric programs across India and China where established cold chains support distribution.
- Recombinant Vaccine:Baculovirus vector systems express purified hemagglutinin proteins without egg-culture mutations. United States hospital systems prioritize these formulations where formulary committees value strain-match fidelity over per-dose cost.
- Live Attenuated Vaccine:Temperature-sensitive viral strains replicate poorly in human airways yet stimulate mucosal immunity. Preferred for needle-averse populations in retail pharmacy settings.
- Quadrivalent Vaccine:Four-strain formulations now dominate commercial portfolios as national immunization programs complete trivalent-to-quadrivalent transitions.
The dominant share belongs to quadrivalent formulations, while recombinant vaccines are closing the gap fastest.
End User:
Volume concentration tracks immunization campaign architecture, with procurement centralization determining contract scale and margin structure.
- Hospitals:Acute care facilities administer high-risk patient doses and manage inpatient vaccination protocols. United States health systems leverage GPO purchasing power to extract price concessions.
- Clinics:Physician offices retain elderly and chronic disease patient relationships despite volume migration to retail channels. Reimbursement complexity limits growth.
- Pharmacies:CVS Health and Walgreens capture convenience-seeking adults through extended-hour access and walk-in availability. Channel share is climbing fastest.
- Individuals:Out-of-pocket purchases in private clinics and travel medicine settings command premium pricing with minimal procurement friction.
Pharmacies hold the dominant volume position, while hospital systems maintain the steepest contract values per dose.
Age Group:
Commercial investment intensity varies with immunosenescence burden and regulatory evidence requirements for label expansion.
- Children:School-age mandates in India and China broaden addressable base beyond traditional risk groups. Pediatric trials require separate safety cohorts.
- Adults:Working-age population coverage depends on employer-sponsored programs and occupational health mandates with variable uptake.
- Elderly:Adjuvanted formulations target antibody response decline. Japan and Western European markets with aging demographics sustain premium pricing tiers.
- Pregnant Women:Maternal immunization programs in Brazil and United Kingdom leverage transplacental antibody transfer to protect neonates.
The elderly segment commands dominant R&D investment, while pediatric mandates are expanding the addressable population most quickly.
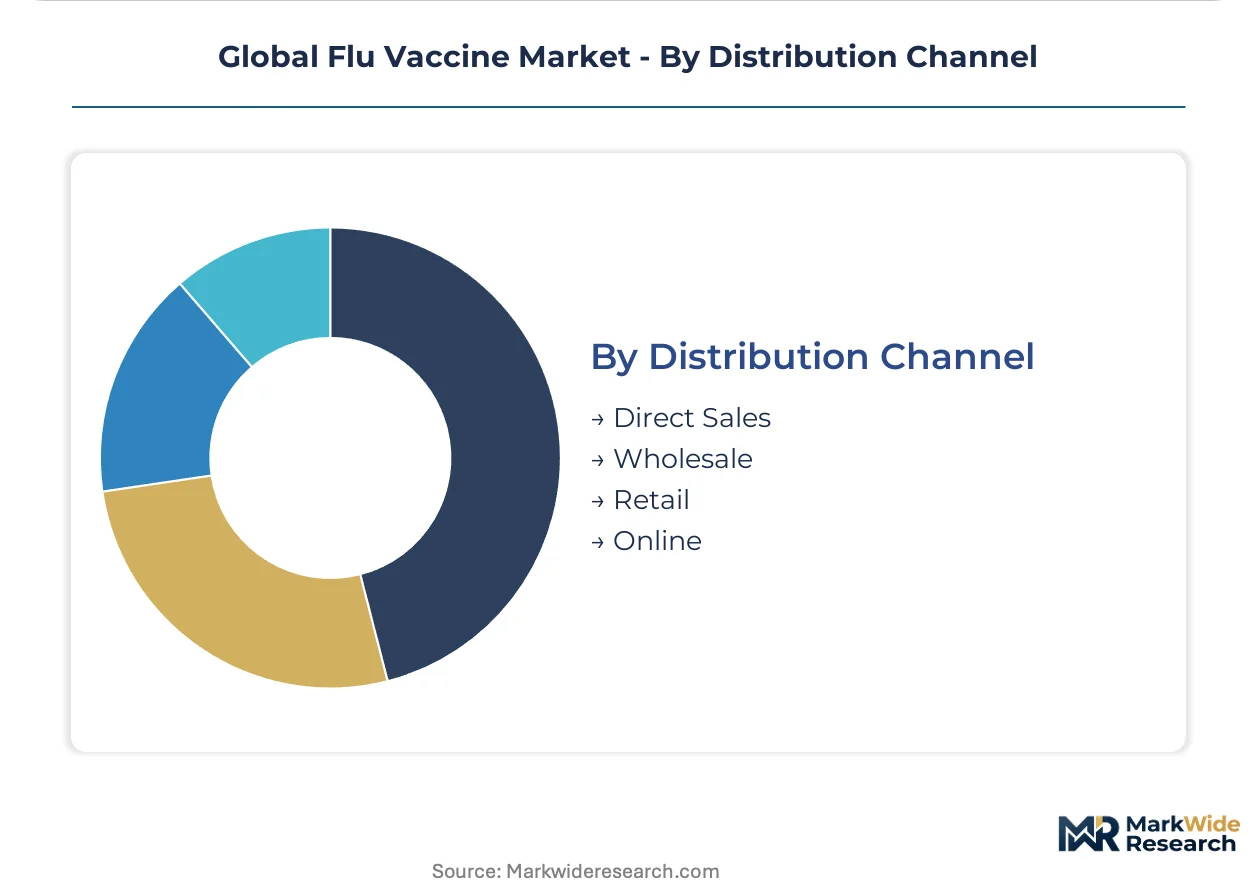
Distribution Channel:
Channel selection determines working capital intensity and seasonal inventory risk exposure.
- Direct Sales:Manufacturer-to-institution contracts for national immunization programs minimize intermediaries. India's Universal Immunization Program procures through this channel.
- Wholesale:Distributor networks manage cold-chain logistics for fragmented clinic and pharmacy accounts. Margin compression is acute.
- Retail:Pharmacy chains consolidate purchasing power and demand differentiated terms. United Kingdom Boots and LloydsPharmacy administer majority of adult doses.
- Online:Appointment scheduling platforms and direct-to-consumer shipment of voucher systems emerging in urban China markets.
Wholesale retains dominant infrastructure share, while retail direct contracting is gaining volume fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA strain selection recommendations anchor Western Hemisphere manufacturing timelines, while China's NMPA and India's CDSCO reshape procurement specifications for the world's largest addressable populations.
United States
Pediatric schedule expansion and employer-sponsored immunization programs drive dose volume. FDA quadrivalent formulation requirements and post-marketing surveillance obligations elevate compliance costs for market entrants. Manufacturing clusters in Pennsylvania and North Carolina concentrate cell-culture capacity buildouts as egg-based production loses procurement preference.
China
National immunization program expansion into school-age populations broadens the addressable base beyond traditional elderly cohorts. NMPA tightened pharmacovigilance reporting requirements and local labeling specifications for imported vaccines. Yangtze River Delta biomanufacturing hubs attract technology transfer agreements as domestic producers scale recombinant protein platforms.
India
Universal Immunization Program procurement through direct sales channels concentrates volume in public sector contracts. CDSCO intensified post-marketing surveillance for domestically produced and imported formulations. Hyderabad and Pune clusters house expanding fill-finish capacity serving Southern Hemisphere demand cycles.
Japan
Aging demographics sustain premium pricing for adjuvanted formulations targeting immunosenescence. PMDA marketing authorization requirements mandate elderly-specific safety and immunogenicity cohorts. Tokyo-Osaka pharmaceutical corridors concentrate R&D investment for next-generation platforms.
Germany
EMA marketing authorization requirements for quadrivalent formulations extend clinical development timelines. Hospital system GPO purchasing power extracts price concessions through centralized procurement. Bavaria and North Rhine-Westphalia anchor European distribution networks managing cold-chain logistics for fragmented pharmacy accounts.
Global Flu Vaccine Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with manufacturing scale and strain-matching capabilities determining contract access. European and US-based multinationals leverage established influenza franchises across multiple continents, while platform-technology specialists compress reformulation timelines. Two strategic archetypes dominate: integrated biopharmaceutical conglomerates with captive egg and cell-culture networks, and mRNA platform operators repurposing pandemic-response infrastructure. Competitive moves concentrate on cell-culture capacity expansion and technology licensing agreements that transfer manufacturing expertise to regional partners.
Within the integrated conglomerate tier, Sanofi and GSK plc occupy positions exemplifying quadrivalent supply continuity across European and US manufacturing networks. CSL Limited anchors Southern Hemisphere demand through seasonal strain-matching capabilities. Moderna, Inc. represents the platform-technology archetype, with mRNA adaptability shortening strain-update cycles relative to conventional approaches.
| Leading Market Players |
|---|
| Sanofi |
| GSK plc |
| CSL Limited |
| AstraZeneca plc |
| Moderna, Inc. |
| BIKEN Co., Ltd. |
| Abbott Laboratories |
| SINOVAC Biotech Ltd. |
| Viatris Inc. |
| Others |
Supply Flow & Price Mechanics
Cell-culture platform substitution for egg-based production redraws supply geography toward Pennsylvania and North Carolina manufacturing clusters while compressing per-dose economics through elimination of embryonated egg supply dependencies. Procurement contracts specifying non-egg formulations now command price premiums as strain-match fidelity becomes a formulary selection criterion in United States hospital systems.
Pricing Analysis
Long-term offtake agreements with national immunization programs anchor volume pricing for standard quadrivalent formulations, while spot purchasing through retail pharmacy chains captures convenience premiums for recombinant and adjuvanted products. Price differentiation hinges on manufacturing platform certification—FDA-approved cell-culture batches command tier separation from egg-based alternatives—and volume scale, with India's Universal Immunization Program extracting concessions through centralized procurement. Cost compression in recombinant protein inputs is intensifying because baculovirus vector substrate expenses outpace conventional cultivation economics. Public health procurement entities exhibit the steepest price sensitivity, whereas elderly-targeted adjuvanted formulations sustain premium tolerance in Japan and Western European markets.
Supply Chain Analysis
Pathogen-free embryonated egg supply from specialist poultry farming operations in the United States and Europe constitutes a chokepoint that constrains hybrid manufacturing footprints and elevates single-source vulnerability for manufacturers maintaining legacy production. Active pharmaceutical ingredients and baculovirus vector systems draw from United States, China, and South Korean biomanufacturing bases, with fill-finish capacity concentrating in India and Germany. Regulatory restriction risk intensifies as China's NMPA and India's CDSCO tighten post-marketing surveillance obligations for imported formulations. Distribution runs through wholesale networks managing cold-chain logistics for fragmented clinic and pharmacy accounts, though retail direct contracting is gaining volume fastest through CVS Health and Walgreens consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
mRNA platform adaptability represents a technological inflection that collapses strain-update timelines and enables pandemic-response manufacturing repurposing, positioning the market for sustained disruption as cell-culture and recombinant protein platforms displace legacy egg-based infrastructure.
For Market Incumbents: Consolidate cell-culture capacity advantages through backward integration into mammalian cell-line substrate production, securing supply continuity as embryonated egg dependencies become a competitive liability. Lock in long-term offtake agreements with national immunization programs in India and China before procurement specifications harden around non-egg formulations, defending margin position against platform-technology specialists compressing reformulation economics.
For New Entrants and Emerging Players: Lead with recombinant protein platform specialization targeting United States hospital formulary committees that prioritize strain-match fidelity over per-dose cost, capturing white-space share as integrated conglomerates defend legacy egg-based positions. Penetrate Southern Hemisphere seasonal demand cycles through technology transfer partnerships with regional biomanufacturing facilities in Australia and Brazil, bypassing captive egg-supply chain barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed cell-culture specialists possessing qualified mammalian production infrastructure but lacking global distribution scale. The five-to-ten year viability window favors platform-technology operators with mRNA formulation science capabilities over legacy egg-dependent franchises. Monitor WHO strain recommendation timing precision as an inflection indicator—compression in formulation-to-distribution timelines signals platform adaptability premiums materializing.
| Strategic Initiative | Industry Significance |
|---|---|
| Cell-Culture Capacity Expansion | Sanofi and GSK plc are scaling Pennsylvania and North Carolina facilities to capture quadrivalent contract specifications. |
| mRNA Technology Licensing | Moderna's platform adaptability shortens strain-update cycles relative to conventional egg-based approaches. |
| Adjuvanted Formulation Development | MF59 and AS03 systems address immunosenescence in Japan's aging demographic, sustaining premium pricing tiers. |
| Direct-to-Pharmacy Distribution | CVS Health and Walgreens consolidation captures convenience-seeking adults through extended-hour access models. |
| Pediatric Indication Expansion | School-age mandates in India and China broaden addressable base beyond traditional elderly risk cohorts. |
Methodological Framework
Operator-level perspectives from bioprocess engineering directors, regulatory affairs leads at FDA and EMA, hospital formulary committee members, and national immunization program procurement officers anchored the qualitative base. Secondary validation drew from FDA strain selection filings, EMA marketing authorization submissions, WHO Global Influenza Surveillance and Response System recommendations, and national procurement database disclosures. Bottom-up demand modeling across pediatric, adult, elderly, and pregnant women cohorts triangulated with top-down manufacturing capacity assessments to ensure statistical consistency.
Sensitivity analysis tested forecast robustness across regulatory approval timeline scenarios, manufacturing platform transition speeds, and strain-matching effectiveness assumptions over the projection horizon. Segmentation dimensions modeled included product type, end-user channel, age group, distribution mechanism, and regional regulatory cluster. CAGRs were derived from volume-demand elasticity functions calibrated to historical immunization campaign uptake patterns and procurement contract expansion trajectories. Industry-specific inputs incorporated cell-culture capacity buildout schedules and mRNA technology transfer agreement execution timelines.
Forecasts assume regulatory continuity in FDA, EMA, NMPA, and CDSCO regimes; material policy shifts around post-marketing surveillance obligations or strain recommendation protocols would require re-modeling. Practitioners should keep alternative scenarios live as pediatric schedule expansion rates and cell-culture platform adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Vaccine Production Market
Biopharmaceuticals
South Korea Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Theranostics Market
Biopharmaceuticals
Global Vaccine Conjugate Market
Biopharmaceuticals
Insulin API Market
Biopharmaceuticals
Global Infertility Drugs Market
Biopharmaceuticals
Conjugated Estrogen Market
Biopharmaceuticals
Pruritus Therapeutics Market
Biopharmaceuticals
Penicillin G Acylase Market
Biopharmaceuticals
Amphotericin B Market
Biopharmaceuticals
Antibody Discovery Market
Biopharmaceuticals
HIV Market
Biopharmaceuticals
Bioidentical Hormones Market
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
Sezary Syndrome Market