
 Taiwan Data Center Physical Security Market | 2026-2036
Taiwan Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Data Center Physical Security Market Insights
Buyer concentration in Taiwan's data center physical security sector is broadening as cloud providers and financial institutions diversify beyond traditional telecom operators. Axis Communications AB leverages its video analytics specialization to serve hyperscale campuses in Taoyuan. Bosch Sicherheitssysteme GmbH anchors its position through integrated intrusion detection systems tailored to tier-III facility standards. Schneider Electric competes on power-security convergence, bundling physical access with electrical infrastructure monitoring.
Taiwan Data Center Physical Security encompasses layered protection systems—biometric access control, video surveillance with thermal imaging, perimeter intrusion detection, and environmental monitoring—engineered to maintain operational continuity of facilities housing compute, storage, and network infrastructure. These systems typically operate across redundancy tiers with response thresholds measured in milliseconds for critical alarm escalation. Surveillance cameras and access control systems dominate solution spending as operators prioritize real-time threat visibility and credential-based entry governance. Installation activity skews toward new construction and upgrade projects rather than retrofit work, reflecting Taiwan's pipeline of purpose-built facilities designed to native security specifications.
Taiwan's Ministry of Digital Affairs enforces critical infrastructure designation for major data center operators, mandating physical security audits and incident reporting protocols that elevate compliance-grade system procurement. The National Communications Commission layers telecom-specific requirements on facilities serving 5G core networks and submarine cable landing stations. Stakeholders must weigh the trade-off between integrated platform consolidation and modular best-of-breed architectures as facility complexity escalates.
Market Dynamics
Hyperscale cloud construction across northern Taiwan is compressing procurement cycles and forcing security vendors to synchronize installation timelines with electrical and mechanical infrastructure rollouts. This coordination imperative is restructuring supplier relationships and technical specifications across the island's data center pipeline.
Growth Catalysts
- NCC Critical Infrastructure Mandates:Taiwan's National Communications Commission requires physical security audits for telecom-linked facilities, creating compliance-grade procurement pull for tier-III certified systems.
- Hyperscale Campus Clustering:Cloud providers are consolidating multiple facilities in Taoyuan Science Park, generating concentrated demand for perimeter and access control at single geographic nodes.
- AI-Enabled Video Analytics:Thermal imaging combined with machine learning algorithms is reducing false alarm rates, accelerating replacement of legacy analog surveillance in new construction.
Market Restraints
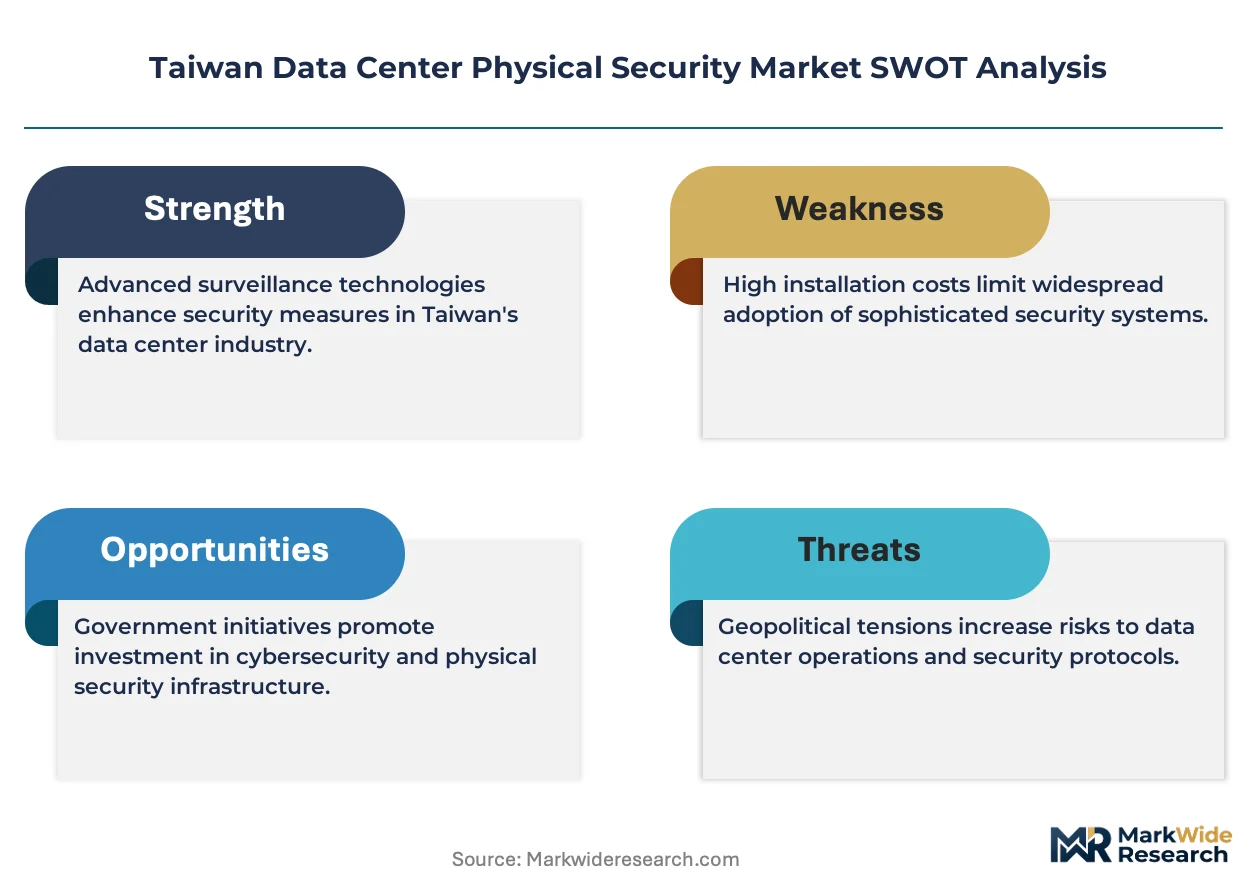
- Specialized Technician Scarcity:Biometric system calibration and integrated platform commissioning require certified integrators, creating installation bottlenecks during peak construction windows.
- Import Dependency for Optical Components:Thermal camera sensors and precision lenses concentrate supply in Japanese and German manufacturing bases, exposing projects to currency and logistics volatility.
- Legacy System Interoperability Friction:Existing telecom data centers operate on proprietary access control protocols that resist integration with modern IP-based security platforms.
Strategic Opportunities
- Central Taiwan Greenfield Development:Taichung and Changhua counties are attracting secondary data center investments where security specifications can be designed natively without retrofit constraints.
- Converged Physical-Cyber Monitoring:Unified platforms correlating badge access logs with network intrusion events are creating new procurement categories beyond traditional siloed purchasing.
- Ministry of Digital Affairs Incident Reporting:Mandatory breach disclosure protocols are elevating demand for audit-trail systems with immutable logging capabilities.
Industry Challenges
- Multi-Vendor Platform Integration:Operators sourcing best-of-breed access control, video management, and intrusion detection face commissioning complexity when unifying disparate APIs and data formats.
- Tier-III Certification Timelines:Uptime Institute and TIA-942 compliance verification for integrated security systems extends project schedules, compressing vendor margin on fixed-price contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Data Center Physical Security Market |
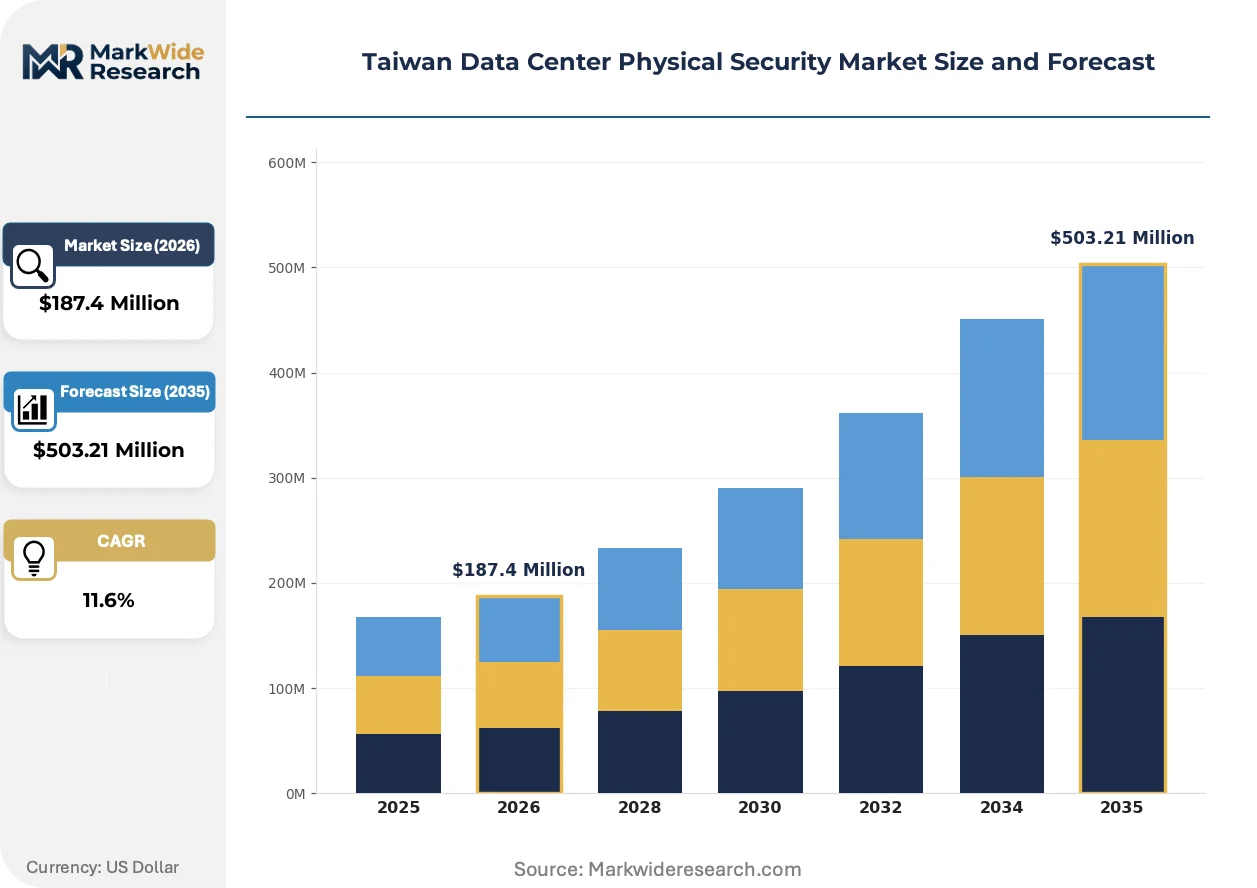
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Access Control Systems, Surveillance Cameras, Intrusion Detection Systems, Perimeter Security End User: Telecommunications, Financial Services, Cloud Providers, Government Agencies Deployment: On-Premises, Managed Services, Hybrid Solutions, Remote Monitoring Installation: New Construction, Upgrades, Retrofit Projects, Maintenance Services |
| Companies Covered | Axis Communications AB, ABB Ltd, Bosch Sicherheitssysteme GmbH, Johnson Controls, Honeywell International Inc., Siemens AG, Schneider Electric, Cisco Systems Inc., HID Global Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Data Center Physical Security Market Trends and Innovations
Security architecture in Taiwanese data centers is pivoting from perimeter-focused designs to layered zero-trust physical access models. This shift demands continuous authentication and real-time behavioral analytics rather than single-point credential validation.
Edge-based video analytics with on-camera processing is overtaking centralized server architectures for threat detection. Hyperscale operators in Taoyuan are deploying cameras with embedded GPUs to reduce bandwidth load and latency for critical alarm escalation. This distributed intelligence is compressing response thresholds from seconds to milliseconds for perimeter breach scenarios.
Taiwan's Ministry of Digital Affairs has designated data centers as critical infrastructure under national security frameworks, mandating physical security audits and incident reporting protocols. Operators must now document access logs and environmental anomalies to national authorities, elevating procurement priority for systems with immutable audit trails and encrypted data transmission.
Buyers are consolidating vendor relationships to reduce integration risk on complex campuses. Financial institutions and cloud providers in Taipei are awarding multi-year service contracts bundling hardware, software, and maintenance to single integrators rather than fragmenting procurement across specialized suppliers. This concentration favors vendors with end-to-end platform capabilities and local technical presence.
Taiwan Data Center Physical Security Market Segmentation
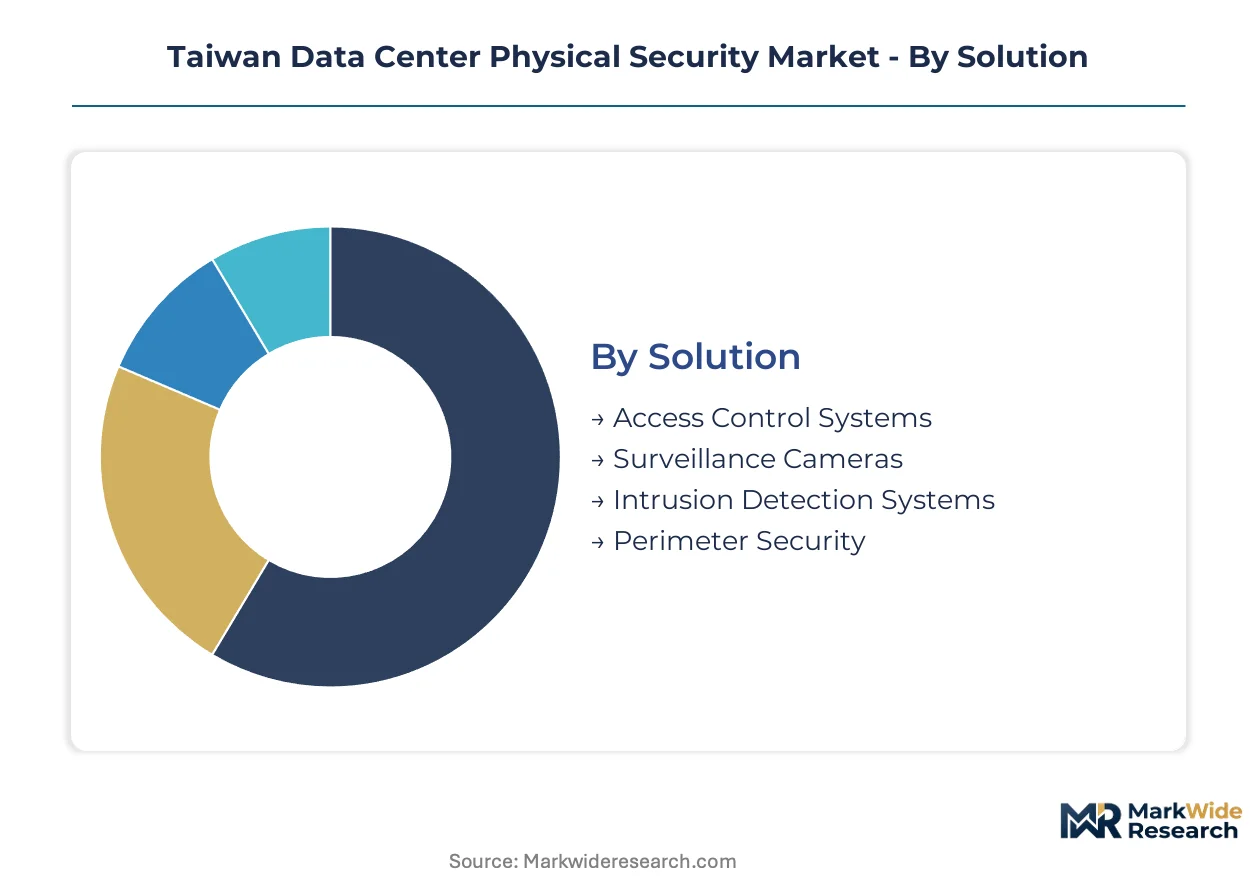
Taiwan's data center security procurement splits across solution types, end-user requirements, and deployment models that reflect the island's concentrated hyperscale construction pipeline. Understanding these segment boundaries clarifies where compliance mandates intersect with technical specifications and vendor selection criteria.
Solution:
Upgrade cycles in Taiwanese facilities are accelerating as legacy analog systems reach end-of-life against NCC critical infrastructure mandates.
- Access Control Systems:Biometric credentialing with multi-factor authentication dominates new Taoyuan hyperscale campuses. Financial institutions in Taipei prioritize systems with immutable audit trails to satisfy Ministry of Digital Affairs incident reporting protocols.
- Surveillance Cameras:Thermal imaging arrays with embedded GPU processing enable edge-based analytics without centralized server bottlenecks. Cloud providers deploy these for millisecond-response perimeter monitoring at Taoyuan Science Park clusters.
- Intrusion Detection Systems:Integrated sensor networks combining seismic, infrared, and microwave detection for tier-III facility certification.
- Perimeter Security:Electrified fencing and buried cable systems protecting multi-building campuses from coordinated physical breaches.
Surveillance Cameras sits at the top of the volume ranking, with Access Control Systems climbing the fastest.
End User:
Customer concentration varies sharply by compliance exposure and facility scale across northern Taiwan's development corridors.
- Cloud Providers:Hyperscale operators in Taoyuan demand converged physical-cyber platforms with API-native integration. Their procurement bundles hardware, software, and multi-year maintenance into single-vendor contracts to reduce commissioning risk on complex campuses.
- Telecommunications:NCC-mandated audits for 5G core and submarine cable facilities drive compliance-grade system replacement. Legacy proprietary protocols create friction during IP-platform migrations.
- Financial Services:Banks and insurers in Taipei prioritize audit-trail immutability and encrypted transmission for regulatory examination readiness.
- Government Agencies:Ministry of Digital Affairs critical infrastructure designation elevates procurement priority for systems with national security-grade certification.
Cloud Providers command the largest project scale, while Financial Services shows the steepest expansion trajectory for audit-compliance upgrades.
Deployment:
Operational model selection tracks facility complexity and in-house technical capacity across Taiwan's operator base.
- On-Premises:Fully owned and operated security infrastructure with dedicated NOC staffing. Dominant among tier-III certified facilities requiring millisecond alarm response.
- Managed Services:Third-party monitoring and maintenance contracts reducing fixed overhead. Cloud providers favor this for secondary facilities outside core Taoyuan clusters.
- Hybrid Solutions:Split architecture with on-site hardware and cloud-based analytics. Emerging preference for edge-camera processing with centralized log aggregation.
- Remote Monitoring:Off-site SOC oversight via encrypted connectivity. Limited adoption due to latency requirements for critical alarm escalation.
On-Premises retains dominant share, though Hybrid Solutions is gaining adoption fastest among new greenfield developments.
Installation:
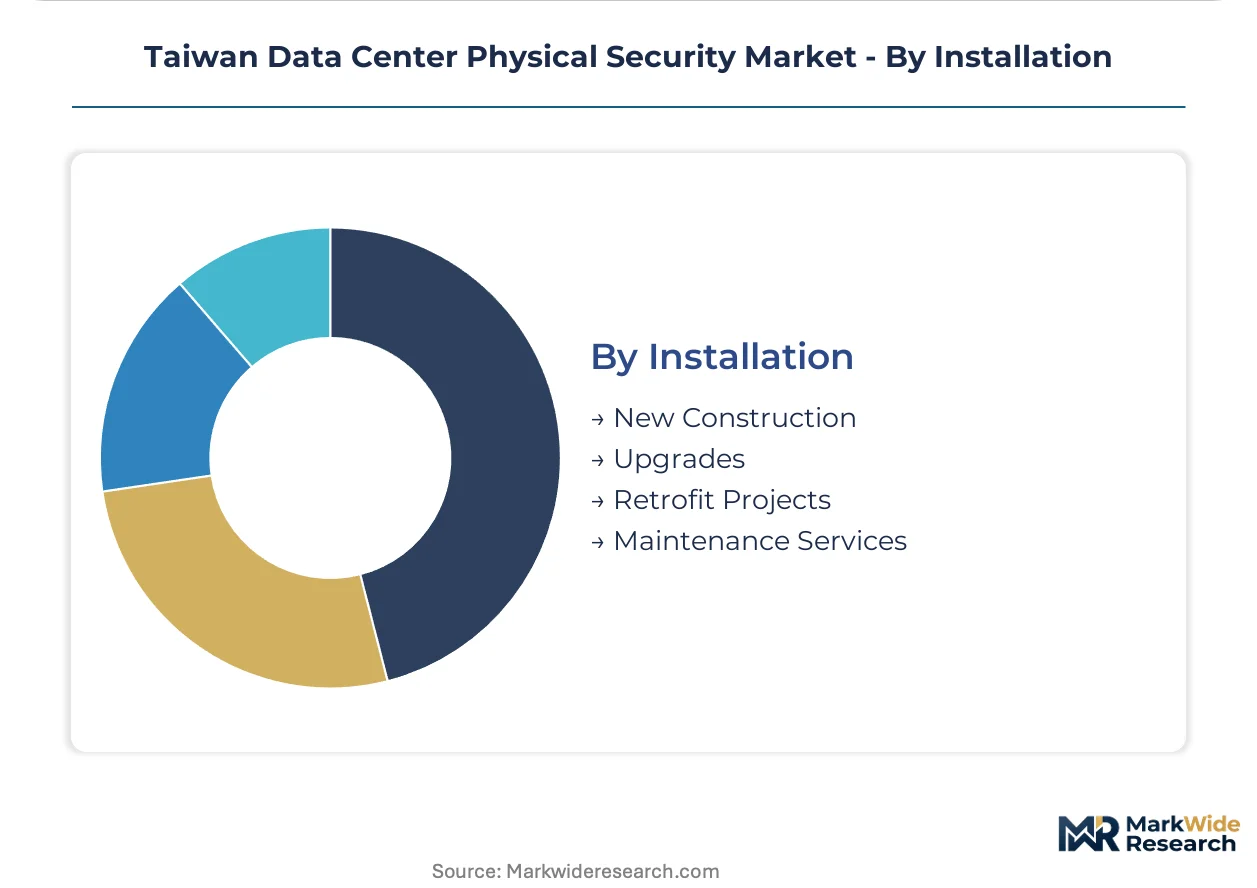
Project type distribution reflects Taiwan's construction pipeline skew toward purpose-built facilities rather than legacy retrofits.
- New Construction:Native security specification integration during electrical and mechanical infrastructure rollout. Dominates Taoyuan Science Park and emerging Taichung developments.
- Upgrades:Partial system replacement addressing compliance gaps or technology obsolescence. Concentrated in Taipei telecom facilities facing NCC audit deadlines.
- Retrofit Projects:Legacy facility adaptation with constrained infrastructure compatibility. Limited volume due to Taiwan's young data center stock.
- Maintenance Services:Ongoing calibration, firmware updates, and preventive hardware replacement. Expanding as installed base matures.
New Construction leads absolute volume, with Maintenance Services expanding most quickly as early hyperscale facilities exit warranty periods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's hyperscale construction pipeline outpaces Taiwan's in absolute facility count, yet Taiwan's security procurement intensity per square meter exceeds regional peers due to critical infrastructure mandates. South Korea's cloud sector concentrates in Seoul's digital valleys with comparable compliance pressures.
Taipei and Taoyuan
Hyperscale campuses at Taoyuan Science Park drive tier-III security specification adoption. The Ministry of Digital Affairs enforces critical infrastructure audits with incident reporting protocols. Taipei financial institutions prioritize audit-trail immutability for regulatory examination readiness.
Taichung and Changhua
Greenfield developments in Central Taiwan escape retrofit constraints of legacy facilities. National Communications Commission telecom-linked mandates apply to emerging submarine cable landing stations. Changhua's emerging data center zones attract secondary cloud investments with native security architecture.
South Korea
Seoul Capital Area hyperscale operators demand converged physical-cyber monitoring platforms. The Korea Communications Commission imposes facility protection standards for 5G core infrastructure. Pangyo Techno Valley clusters drive concentrated procurement for integrated access control systems.
Japan
Tokyo-Osaka corridor data centers face METI energy efficiency standards intersecting with physical security requirements. The Ministry of Economy, Trade and Industry designates certain facilities as critical infrastructure. Osaka's emerging cloud zones adopt thermal imaging surveillance for perimeter monitoring.
Singapore
Financial services data centers in Singapore's central business district prioritize encrypted transmission for cross-border audit compliance. The Infocomm Media Development Authority mandates cybersecurity certification with physical security components. Tuas data center park developments integrate native biometric access specifications.
Taiwan Data Center Physical Security Market Competitive Landscape
European producers anchor the integrated platform tier; Asian specialists hold positions in video analytics and edge processing. Market structure tilts toward consolidation as hyperscale operators reduce vendor fragmentation through bundled procurement. Three archetypes dominate: end-to-end platform integrators, video analytics specialists, and power-security convergence providers. Competitive moves center on multi-year service contract capture and tier-III certification pre-integration.
Within the video analytics tier, Axis Communications AB exemplifies specialization in thermal imaging arrays with embedded processing. Bosch Sicherheitssysteme GmbH occupies a position among integrated intrusion detection providers serving compliance-grade installations. Schneider Electric anchors the power-security convergence archetype, representing vendors bundling physical access with electrical infrastructure monitoring. These three firms illustrate the strategic positioning required to capture procurement from cloud providers consolidating vendor relationships.
| Leading Market Players |
|---|
| Axis Communications AB |
| ABB Ltd |
| Bosch Sicherheitssysteme GmbH |
| Johnson Controls |
| Honeywell International Inc. |
| Siemens AG |
| Schneider Electric |
| Cisco Systems Inc. |
| HID Global Corporation |
| Others |
Pricing and Supply Chain Analysis
Edge-based video analytics with embedded GPU processing is compressing hardware cost curves while concentrating procurement leverage among hyperscale operators in Taoyuan Science Park. This technology shift simultaneously reduces per-camera server infrastructure demands and elevates volume concentration, reshaping supplier pricing power across Taiwan's data center security pipeline.
Pricing Analysis
Capacity additions in Taoyuan are reshaping price floors for tier-III certified systems as cloud providers consolidate multi-year service contracts. Three-tier pricing structure across premium certification, standard compliance, and economy retrofit levels dominates procurement, with Ministry of Digital Affairs audit-grade specifications commanding substantial premiums. Cost compression in standard-tier access control is intensifying because NCC-mandated upgrade deadlines compress vendor margins on fixed-price contracts. Cloud providers exhibit lowest price sensitivity due to bundled procurement scale, while legacy telecom facilities face highest budget constraints during IP-platform migrations.
Supply Chain Analysis
Tier-III certification pre-integration requirements gate supplier qualification, filtering vendor pools before commercial engagement. Thermal camera sensors and precision optical components concentrate manufacturing in Japan and Germany, exposing Taiwanese projects to currency and logistics volatility. Supply chains draw from German precision lens producers, Japanese semiconductor fabs, and domestic system integrators for final commissioning. Single-source vulnerability persists for embedded GPU modules used in edge-analytics cameras. Distribution runs through certified security integrators with NCC-recognized commissioning credentials rather than direct manufacturer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan's data center security market functions as a geographic-arbitrage play where Central Taiwan greenfield developments escape the retrofit cost premiums and legacy protocol constraints burdening Taipei telecom facilities.
For Market Incumbents: Deploy certification pre-integration investments to lock in Taoyuan hyperscale campus contracts before competitors achieve Uptime Institute verification. Axis Communications AB and Bosch Sicherheitssysteme GmbH should deepen backward integration into thermal sensor supply to mitigate Japanese component currency exposure. Schneider Electric must anchor power-security convergence offerings against emerging pure-play security vendors targeting electrical infrastructure monitoring adjacencies.
For New Entrants and Emerging Players: Capture Changhua county greenfield specifications where native security architecture eliminates retrofit friction and legacy protocol conversion costs. Taichung secondary cloud investments represent the most penetrable geography, with submarine cable landing station security offering specialized entry points. A go-to-market angle emphasizing converged physical-cyber monitoring platforms with API-native integration addresses cloud provider vendor consolidation preferences.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier system integrators because NCC certification requirements create sticky customer relationships and recurring maintenance revenue streams. Long-term viability hinges on exposure to Taiwan's critical infrastructure designation expansion rather than commodity surveillance hardware. The signal to watch is Ministry of Digital Affairs incident reporting protocol expansion to secondary facility tiers, which would accelerate audit-trail system replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Converged physical-cyber monitoring addresses cloud provider vendor consolidation mandates in Taoyuan. |
| Certification Pre-Integration | Tier-III Uptime Institute verification accelerates procurement timelines for hyperscale campus contracts. |
| Backward Integration | In-house thermal sensor production reduces Japanese component currency exposure for Taiwanese projects. |
| Geographic Expansion | Changhua greenfield developments escape retrofit constraints and legacy protocol conversion premiums. |
| Strategic Partnership | Electrical infrastructure bundling with physical access systems captures Schneider Electric's convergence positioning. |
Research Methodology
Bottom-up facility deployment modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with data center security directors, NCC compliance officers, system integrators, and hyperscale procurement leads combined with secondary validation against Taiwan's National Communications Commission filings, Ministry of Digital Affairs critical infrastructure designations, Uptime Institute certification databases, and customs import records for thermal camera components. Triangulation across these sources ensures segment-level precision.
Historical trendline analysis of security system procurement intensity per square meter across northern Taiwan's construction pipeline established baseline growth patterns. The forecast framework models solution type, end-user vertical, deployment model, and installation project category dimensions across the projection horizon. CAGRs derive from facility completion schedules correlated with NCC audit mandate deadlines and hyperscale cloud expansion commitments. Edge-analytics adoption curves and tier-III certification penetration rates serve as key forecast inputs.
Underlying measurement precision varies by segment; new construction and cloud provider verticals carry tighter precision than retrofit projects and government agency procurement due to visibility into announced facility developments. Forecasts reflect assumptions about NCC enforcement consistency, hyperscale construction timeline adherence, and thermal component supply chain stability. A model refresh is warranted upon material change in Ministry of Digital Affairs critical infrastructure designation scope or NCC audit protocol expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Vietnam Data Center Physical Security Market
Data Center Infrastructure
Blade Server Market
Data Center Infrastructure
Data Center Transfer Switches and Switchgears Market
Data Center Infrastructure
United Kingdom Data Center Physical Security Market
Data Center Infrastructure
Indonesia Data Center Rack Market
Data Center Infrastructure
Middle East and Africa Containerized Data Center Market
Data Center Infrastructure
Data Center Transformation Market
Data Center Infrastructure
Netherlands Data Center Market
Data Center Infrastructure
Austria Data Center Physical Security Market
Data Center Infrastructure
Switzerland Data Center Server Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
Data Center Outsourcing and Infrastructure Utility Services Market
Data Center Infrastructure
Global Containerized Data Center Market
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
Asia-Pacific Data Center Infrastructure Management Market
Data Center Infrastructure
Data Center Power Solutions Market