
 Airflow Management Equipment Market | 2026-2036
Airflow Management Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Airflow Management Equipment Market Outlook
The transition from static ductwork to sensor-driven adaptive ventilation is tilting engineering priorities across the sector. Schneider Electric leverages its building management software stack to integrate airflow hardware with real-time energy analytics. Carrier Global Corporation anchors its position through deep manufacturing scale in commercial HVAC components. Daikin Industries differentiates via proprietary inverter-driven variable refrigerant flow systems that pair with advanced diffuser arrays.
Airflow management equipment encompasses mechanical devices and control systems that regulate air distribution, pressure, and velocity within enclosed environments, typically operating across pressure differentials of 0.1 to 2.5 inches water gauge depending on application criticality. These systems serve to maintain thermal comfort, contaminant containment, and energy efficiency in facilities ranging from semiconductor cleanrooms to vertical farms. Diffusers and dampers command the largest installed base due to universal deployment across HVAC infrastructure, while smart controls represent the fastest-expanding margin pool as building automation penetration deepens. Data centers and clean rooms drive premium specification requirements, pulling demand toward higher-precision variable air volume configurations with embedded IoT feedback loops.
ASHRAE standards, the EU F-Gas Regulation, and China's GB 50189 energy code collectively tighten thermal performance thresholds and refrigerant phase-down timelines, forcing equipment upgrades and redesigns across major construction markets. Compliance with these frameworks now determines product eligibility for public procurement and green building certification programs. Stakeholders must track evolving minimum efficiency performance standards and refrigerant transition schedules to anticipate replacement cycle timing and specification shifts.
Market Dynamics
The EU F-Gas Regulation's refrigerant phase-down mandates are compressing replacement cycles and forcing equipment redesigns across data center and industrial HVAC installations worldwide.
Growth Catalysts
- Hyperscale Data Center Expansion:Operators in China, the United States, and Germany are commissioning multi-megawatt facilities requiring precision cooling infrastructure with embedded IoT feedback loops.
- EU F-Gas Regulation:This framework bans higher-GWP refrigerants and mandates leak detection systems, compelling facility managers to upgrade legacy fixed-speed equipment to variable refrigerant flow configurations.
- AI-Driven Predictive Maintenance:Machine learning algorithms analyzing sensor data from diffuser arrays and dampers now enable preemptive component replacement before thermal excursions damage semiconductor wafers.
Market Restraints
- Copper and Aluminum Price Volatility:Heat exchanger and ductwork fabrication costs fluctuate with London Metal Exchange pricing, squeezing margins for mid-tier equipment assemblers.
- Compressor Supply Concentration:High-efficiency inverter-driven compressor manufacturing clusters in Japan and South Korea create single-source vulnerabilities for European and North American system integrators.
- Refrigerant Transition Friction:Compatibility gaps between next-generation low-GWP refrigerants and existing seal materials delay certification timelines and strand installed base upgrade investments.
Strategic Opportunities
- Vertical Farm Integration:Controlled-environment agriculture operators in the Netherlands and Singapore seek pressure-independent variable air volume systems optimized for humidity-sensitive crop zones.
- India's PLI Scheme for HVAC Components:Production-linked incentives for domestic manufacturing of compressors and heat exchangers attract foreign joint ventures seeking tariff-advantaged export platforms.
- Digital Twin Convergence:Building information modeling software vendors are partnering with airflow hardware manufacturers to offer physics-simulated commissioning services reducing field calibration labor.
Industry Challenges
- Controls Systems Integration Talent:Facility engineering teams lack BACnet and Modbus protocol expertise to configure multi-vendor building automation networks, extending project commissioning timelines.
- Cleanroom ISO 14644-1 Certification:Semiconductor fabs require third-party validation of particle count performance across diffuser arrays, adding six to twelve weeks to equipment acceptance protocols.
- Legacy Pneumatic Control Retrofit Complexity:Aging hospital and university buildings with 1980s-era pneumatic damper actuators resist cost-effective upgrades to electronic direct digital control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airflow Management Equipment Market |
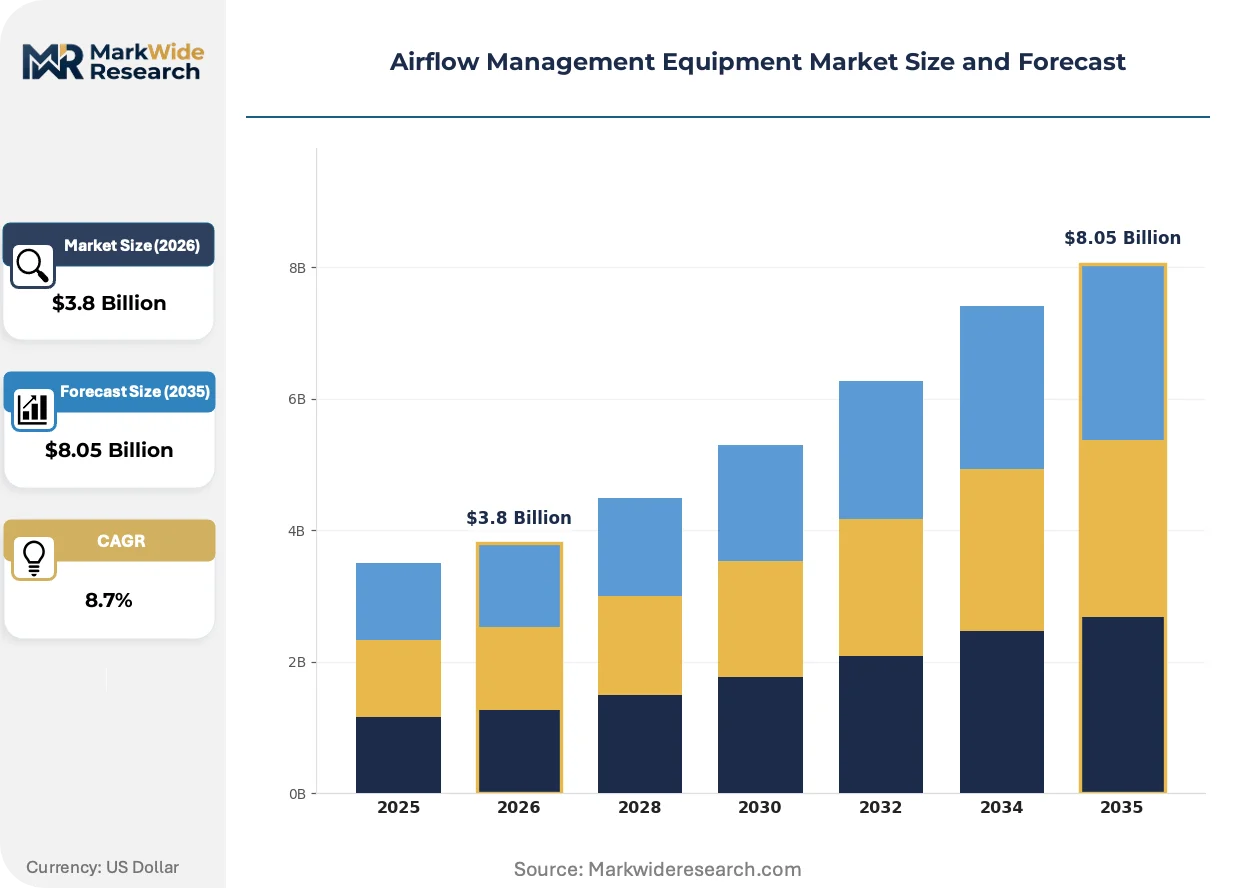
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diffusers, Grilles, Louvers, Dampers End User: Manufacturing Facilities, Data Centers, Commercial Buildings, Residential Units Technology: Variable Air Volume, Constant Air Volume, Ductless Systems, Smart Controls Application: HVAC Systems, Clean Rooms, Industrial Processes, Greenhouses |
| Companies Covered | Schneider Electric, Carrier Global Corporation, Upsite Technologies, Daikin Industries, Trane Technologies, Eaton Corporation, Subzero Engineering, Greenheck Fan Corporation, Kingspan Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airflow Management Equipment Market Strategic Shifts
Computational fluid dynamics software and additive manufacturing are compressing product development cycles while enabling geometries impossible with traditional sheet metal stamping methods.
Computational fluid dynamics simulation platforms now model thermal stratification and contaminant dispersion before physical prototyping. Data center operators in Northern Virginia and Frankfurt specify diffuser arrays validated through digital wind tunnel analysis, reducing field commissioning failures. This capability is collapsing the traditional separation between HVAC design engineering and construction-phase airflow balancing.
The EU F-Gas Regulation's 2024 service ban on virgin HFC refrigerants above specified GWP thresholds forces equipment redesigns. Manufacturers must validate new compressor lubricant chemistries and elastomer compatibility matrices. Semiconductor cleanroom operators in Ireland and the Netherlands face accelerated depreciation schedules as they retire non-compliant precision cooling assets ahead of original replacement plans.
Outcome-based facility performance contracts now tie contractor compensation to measured energy intensity metrics rather than equipment installation milestones. University and hospital facility managers in California and Massachusetts favor vendors assuming operational risk for thermal comfort and indoor air quality outcomes. This model compresses vendor margins during warranty periods but extends revenue streams through ten-year service agreements.
Airflow Management Equipment Market Segmentation
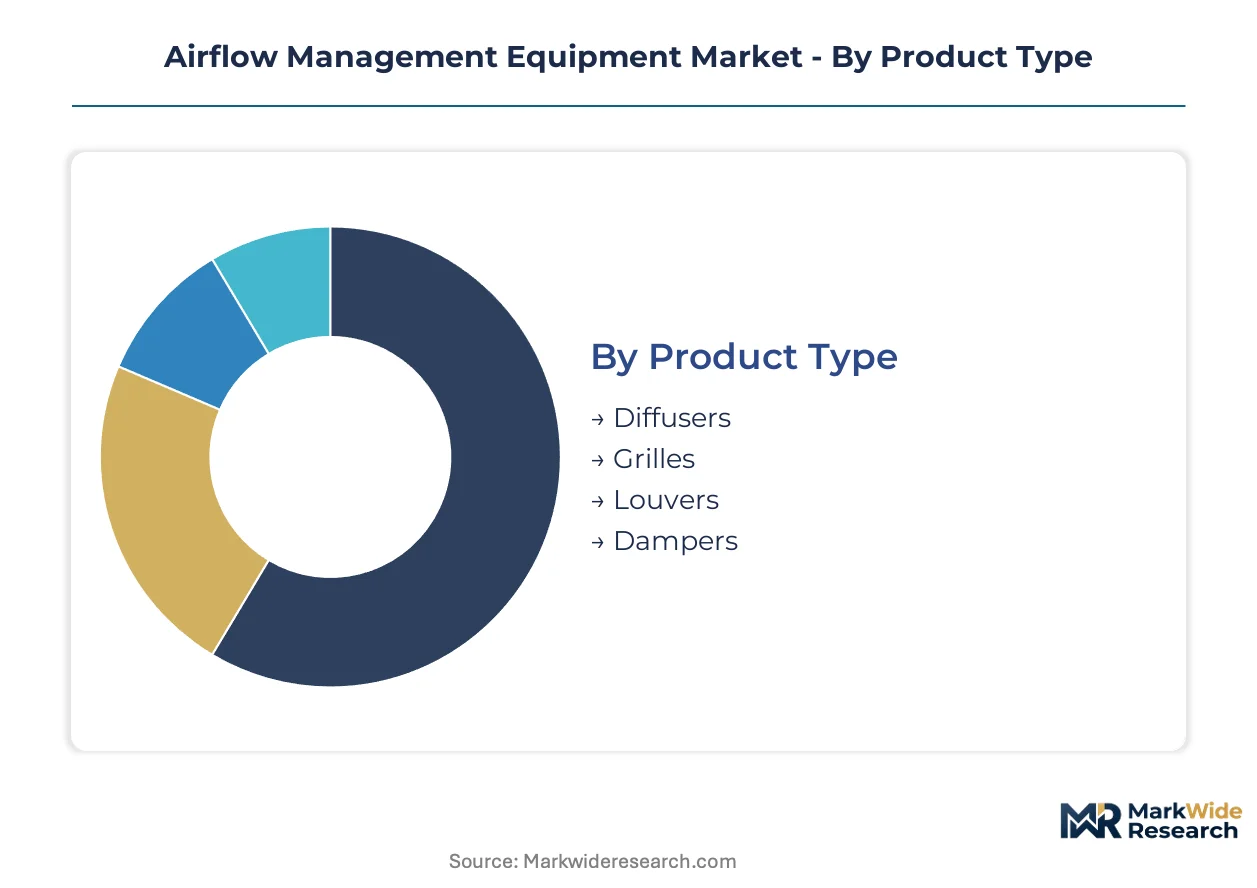
Airflow management equipment segments by product type, end user, technology, and application. Each dimension carries distinct specification requirements, replacement cycles, and margin structures that shape procurement patterns across construction and industrial markets.
Product Type:
Diffusers and dampers turn over fastest in retrofit cycles, while grilles and louvers persist longer in building envelopes. Replacement frequency correlates with filter change intervals and pressure cycling intensity.
- Diffusers:Ceiling-mounted distribution devices with adjustable blades or perforated faces that control throw patterns and mixing. Data center operators in Northern Virginia and Frankfurt specify diffuser arrays validated through computational fluid dynamics simulation, reducing field commissioning failures and thermal stratification risks.
- Dampers:Motorized or manual flow control devices operating across pressure differentials up to 2.5 inches water gauge. Manufacturing facilities in Germany and the United States deploy fire-rated and smoke control dampers to satisfy building code requirements and insurance underwriting conditions.
- Grilles:Fixed or removable protective covers for supply and return openings. Residential and light commercial applications in China favor stamped steel grilles with powder-coated finishes for cost-sensitive new construction.
- Louvers:Rain-resistant exterior intake and exhaust devices with angled blades. Industrial process buildings in the Netherlands integrate louvers with bird screens and insect barriers for vertical farm ventilation systems.
Diffusers anchor the volume base while smart-enabled dampers gain share at the steepest rate.
End User:
Cost tiers separate mission-critical precision cooling from commodity comfort conditioning. Specification stringency and service contract attachment rates vary dramatically across these customer types.
- Data Centers:Hyperscale facilities require pressure-independent variable air volume configurations with embedded IoT feedback loops. Operators in China, the United States, and Germany commission multi-megawatt installations with real-time thermal mapping and predictive maintenance integration.
- Manufacturing Facilities:Semiconductor fabs and pharmaceutical plants demand ISO 14644-1 validated particle containment. Cleanroom installations in Ireland and the Netherlands face accelerated depreciation schedules as EU F-Gas Regulation compliance forces equipment replacement ahead of original plans.
- Commercial Buildings:Office and retail spaces prioritize energy recovery and demand-controlled ventilation. California and Massachusetts facility managers favor outcome-based performance contracts tying vendor compensation to measured energy intensity metrics.
- Residential Units:Single-family and multi-family housing drives volume through standard ducted and ductless mini-split systems. India's production-linked incentive scheme for HVAC components attracts foreign joint ventures seeking tariff-advantaged export platforms for this price-sensitive segment.
Commercial buildings generate the largest installed base while data centers command the highest specification premiums.
Technology:
Volume concentrates in mature constant air volume architectures, but margin expansion follows the shift toward adaptive, sensor-driven control platforms.
- Variable Air Volume:Systems modulate supply airflow based on zone-level thermal demand. Singapore and Netherlands vertical farm operators seek pressure-independent configurations optimized for humidity-sensitive crop zones with tight dewpoint control.
- Smart Controls:BACnet and Modbus networked devices with machine learning analytics. Data center operators deploy algorithms analyzing sensor data from diffuser arrays to enable preemptive component replacement before thermal excursions damage semiconductor wafers.
- Constant Air Volume:Fixed airflow delivery regardless of zone load, common in legacy installations. Aging hospital and university buildings with pneumatic damper actuators resist cost-effective upgrades to electronic direct digital control architectures.
- Ductless Systems:Mini-split and variable refrigerant flow configurations for retrofit and space-constrained applications. Japan and South Korea manufacturing clusters dominate inverter-driven compressor supply, creating single-source vulnerabilities for European and North American system integrators.
Constant air volume retains the deepest installed base while smart controls climb the fastest.
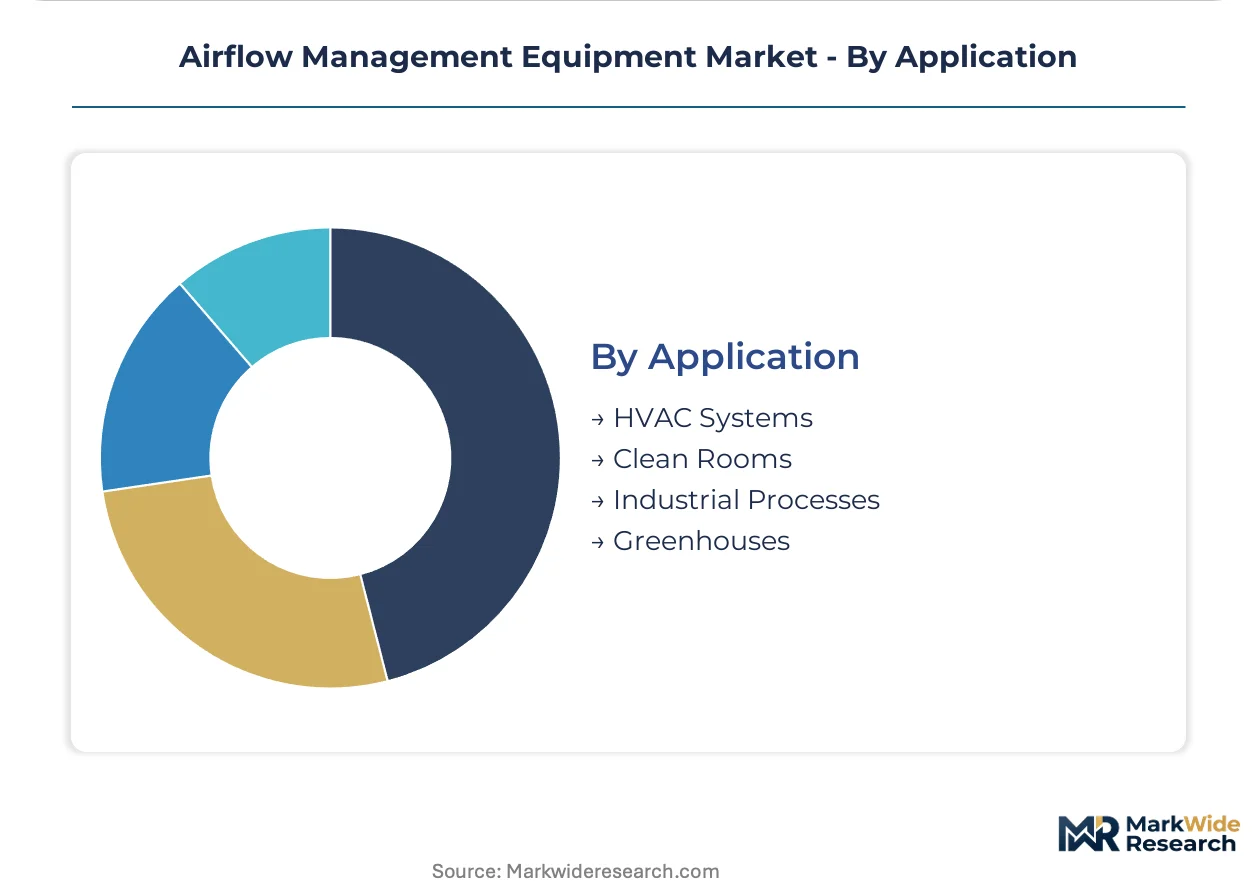
Application:
Application context determines pressure class, filtration grade, and control precision requirements. Clean rooms and industrial processes pull specification upward, while residential HVAC anchors volume.
- HVAC Systems:General heating, ventilation, and air conditioning for comfort and basic indoor air quality. China's GB 50189 energy code tightens thermal performance thresholds, forcing equipment upgrades across new construction and major renovation.
- Clean Rooms:Contaminant-controlled environments for semiconductor, pharmaceutical, and biotechnology manufacturing. Third-party validation of particle count performance across diffuser arrays adds six to twelve weeks to equipment acceptance protocols.
- Industrial Processes:Specialized ventilation for chemical handling, coating operations, and combustion exhaust. EPA and OSHA exposure limit compliance drives specification of high-temperature and corrosion-resistant damper materials.
- Greenhouses:Controlled-environment agriculture requiring humidity management and CO2 enrichment. Netherlands operators integrate variable air volume systems with building automation for crop-specific climate zones.
HVAC systems dominate unit shipments while clean room applications capture the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center operators and semiconductor fabs concentrate procurement power across five national markets. Facility engineering teams in these countries specify pressure-independent variable air volume configurations with embedded IoT feedback loops. Regulatory pressure from energy efficiency mandates accelerates replacement cycles unevenly across geographies.
United States
Hyperscale operators in Northern Virginia and Dallas-Fort Worth commission multi-megawatt facilities requiring precision cooling infrastructure. EPA refrigerant management rules and OSHA exposure limits shape equipment specifications for industrial process ventilation. Data center clusters in Phoenix and Atlanta drive demand for diffuser arrays validated through computational fluid dynamics simulation.
China
GB 50189 energy code enforcement tightens thermal performance thresholds across new construction and major renovation projects. MIIT industrial policy supports domestic manufacturing of inverter-driven compressors and heat exchangers. Yangtze River Delta and Pearl River Delta data center construction pulls specification toward smart-enabled damper systems with BACnet integration.
Germany
EU F-Gas Regulation phase-down mandates force equipment redesigns and accelerated depreciation schedules for precision cooling assets. REACH compliance requirements influence elastomer and lubricant selection in compressor systems. Frankfurt and Munich data center clusters specify pressure-independent configurations with real-time thermal mapping capabilities.
Netherlands
Vertical farm operators in Westland and North Holland seek humidity-sensitive crop zone ventilation with tight dewpoint control. ECHA chemical safety frameworks shape materials selection for corrosion-resistant damper applications. Eindhoven semiconductor fabs require ISO 14644-1 validated particle containment across diffuser arrays.
India
PLI scheme incentives for HVAC component manufacturing attract foreign joint ventures seeking tariff-advantaged export platforms. BIS certification requirements establish minimum efficiency performance standards for commercial building installations. Maharashtra and Karnataka data center construction drives demand for variable refrigerant flow configurations with embedded leak detection systems.
Airflow Management Equipment Market Competitive Environment
Channel-controlling players compete with product-specialist players across three discernible tiers. Integrated building management vendors leverage software stack penetration to bundle airflow hardware with energy analytics contracts. Component-scale manufacturers anchor mid-market positioning through heat exchanger and damper fabrication scale. Pure-play airflow specialists defend niche positions in data center containment and cleanroom validation services. Dominant competitive moves include strategic partnerships with building information modeling software vendors and geographic expansion through production-linked incentive jurisdictions.
Within the integrated systems tier, Schneider Electric and Carrier Global Corporation exemplify channel-controlling archetypes that bundle hardware with long-term service agreements. Daikin Industries occupies a position among inverter-driven compressor specialists with proprietary variable refrigerant flow integration. These three anchors represent divergent strategic postures: software-led building automation convergence, manufacturing-scale HVAC component supply, and refrigerant system technology leadership.
| Leading Market Players |
|---|
| Schneider Electric |
| Carrier Global Corporation |
| Upsite Technologies |
| Daikin Industries |
| Trane Technologies |
| Eaton Corporation |
| Subzero Engineering |
| Greenheck Fan Corporation |
| Kingspan Group |
| Others |
Value Chain & Pricing Dynamics
Japan and South Korea manufacturing clusters for inverter-driven compressors concentrate upstream supply power, anchoring margin pools in downstream system integration and software-enabled service contracts for data center and cleanroom operators.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation for copper and aluminum inputs dominate heat exchanger and ductwork procurement. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14644-1 validated cleanroom configurations from commercial building commodity equipment. Pricing pressure stems from commodity metal volatility squeezing mid-tier assemblers. Residential buyers in India exhibit highest price sensitivity, while semiconductor fabs accept premium positioning for mission-critical precision cooling.
Supply Chain Analysis
Foxconn, Flex, and Jabil hold contract-manufacturing capacity for electronic control modules and IoT-enabled damper actuators. Component fabrication concentrates in China, Germany, and the United States for sheet metal stamping and motor assembly. Raw material draws from copper cathode, aluminum coil, and rare-earth magnet supply chains. Single-source vulnerability runs through Japanese and South Korean compressor specialists. Distribution runs through HVAC wholesalers, direct OEM channels, and building automation integrators serving commercial and industrial end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Airflow management equipment is approaching a platform-economics inflection as BACnet and Modbus interoperability standards enable software-led building automation convergence, shifting value capture from hardware margins to recurring energy analytics contracts.
For Market Incumbents: Insulate installed base relationships through backward integration into compressor manufacturing and captive heat exchanger supply. Acquire smart controls specialists to deepen building management software penetration before emerging IoT-native entrants displace legacy damper and diffuser hardware with sensor-embedded alternatives. Prioritize certification investment in EU F-Gas Regulation compliance to accelerate competitor stranded asset exposure. For New Entrants and Emerging Players: Build out vertical farm ventilation portfolios in the Netherlands and Singapore where pressure-independent variable air volume demand outpaces established HVAC vendor coverage. Target India's PLI scheme jurisdictions for tariff-advantaged compressor and heat exchanger manufacturing. Lead with digital twin commissioning partnerships to differentiate from incumbent field calibration labor models. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with ISO 14644-1 validation capabilities and established semiconductor fab relationships, as cleanroom specification premiums sustain margin resilience across replacement cycles. Monitor EU F-Gas Regulation refrigerant phase-down enforcement velocity as inflection signal for accelerated depreciation-driven equipment refresh demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive supply of inverter-driven components reduces exposure to Japan and South Korea single-source concentration. |
| Smart Controls Platform Integration | BACnet-enabled damper arrays with machine learning analytics extend vendor relationships into ten-year service agreements. |
| Digital Twin Commissioning Partnership | Physics-simulated CFD validation collapses field calibration labor for data center diffuser deployments in Northern Virginia. |
| EU F-Gas Regulation Compliance Certification | Low-GWP refrigerant validation positions equipment for accelerated replacement cycles in Ireland and Netherlands semiconductor fabs. |
| PLI Scheme Manufacturing Expansion | Tariff-advantaged production in Maharashtra and Karnataka serves price-sensitive residential and commercial building segments. |
Study Parameters
Desk research of ASHRAE technical standards, EU F-Gas Regulation implementation guidance, and MIIT industrial policy documents preceded structured interviews with data center facility engineers, cleanroom validation specialists, HVAC procurement managers, and building automation integrators. Primary fieldwork across China, Germany, and the United States captured specification trends and replacement cycle timing. Secondary validation drew from customs trade databases, SEC equipment supplier filings, and national energy code enforcement records. Bottom-up equipment shipment analysis triangulated against top-down construction spending forecasts.
Assumptions held fixed include EU F-Gas Regulation phase-down timelines, GB 50189 energy code enforcement intensity, and copper-aluminum price band continuity. Variables stress-tested encompass hyperscale data center capex cycles, semiconductor fab construction delays, and refrigerant transition friction. Segmentation modeling spanned product type, end user criticality tier, technology architecture, and application pressure class. CAGRs derived from installed base turnover analysis and new construction penetration curves. Industry-specific inputs included ISO 14644-1 certification lag times and vertical farm climate zone specification evolution.
Stress conditions across London Metal Exchange pricing volatility, EU regulatory enforcement velocity, and India PLI scheme uptake rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology substitution pacing and regional construction cycle synchronization. Quarterly review of hyperscale data center permitting activity and semiconductor fab equipment depreciation schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Brazil Data Center Market
Data Center Infrastructure
Next Generation Data Center Market
Data Center Infrastructure
Data Center Solutions Market
Data Center Infrastructure
Saudi Arabia Data Center Rack Market
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
Middle East Data Center Power Market
Data Center Infrastructure
South Africa Data Center Rack Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
Hyper-Converged Systems Market
Data Center Infrastructure
Russia Data Center Market
Data Center Infrastructure
Global Mega Data Center Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
Italy Data Center Power Market
Data Center Infrastructure
Japan Data Center Market
Data Center Infrastructure
Netherlands Data Center Physical Security Market
Data Center Infrastructure
Switzerland Data Center Server Market