
 South Africa Data Center Power Market | 2026-2036
South Africa Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Data Center Power Market Insights
Aftermarket service revenue is narrowing as original equipment manufacturers tighten control over spare parts and remote diagnostics. Schneider Electric SE leverages its integrated power management software to capture recurring service contracts. Eaton Corp PLC anchors its position through local assembly of medium-voltage switchgear. Cummins Inc competes on diesel generator reliability for financial services uptime requirements.
South Africa data center power encompasses the generation, conditioning, distribution, and backup systems that ensure continuous electrical supply to server facilities, typically operating at voltage levels from 400V to 11kV with power densities exceeding 15 kW per rack. These systems prevent downtime for cloud computing, banking, and telecommunications infrastructure. Uninterruptible Power Supply and Power Distribution Units command the most mature margin pools, while Renewable Energy and Hybrid Solutions represent the fastest-growing power source categories as load-shedding pressures intensify. Hyperscale Data Centers absorb the largest capital allocations, though Edge Data Centers are gaining traction in secondary cities.
South Africa's carbon tax regime, administered by the National Treasury, elevates operating costs for diesel-dependent facilities and accelerates solar-plus-battery procurement. NERSA's electricity pricing determinations and the Department of Mineral Resources and Energy's embedded generation thresholds reshape how facilities source grid versus self-generated power. Stakeholders must weigh captive renewable investment against wheeling agreements as municipal tariff restructuring proceeds.
Market Dynamics
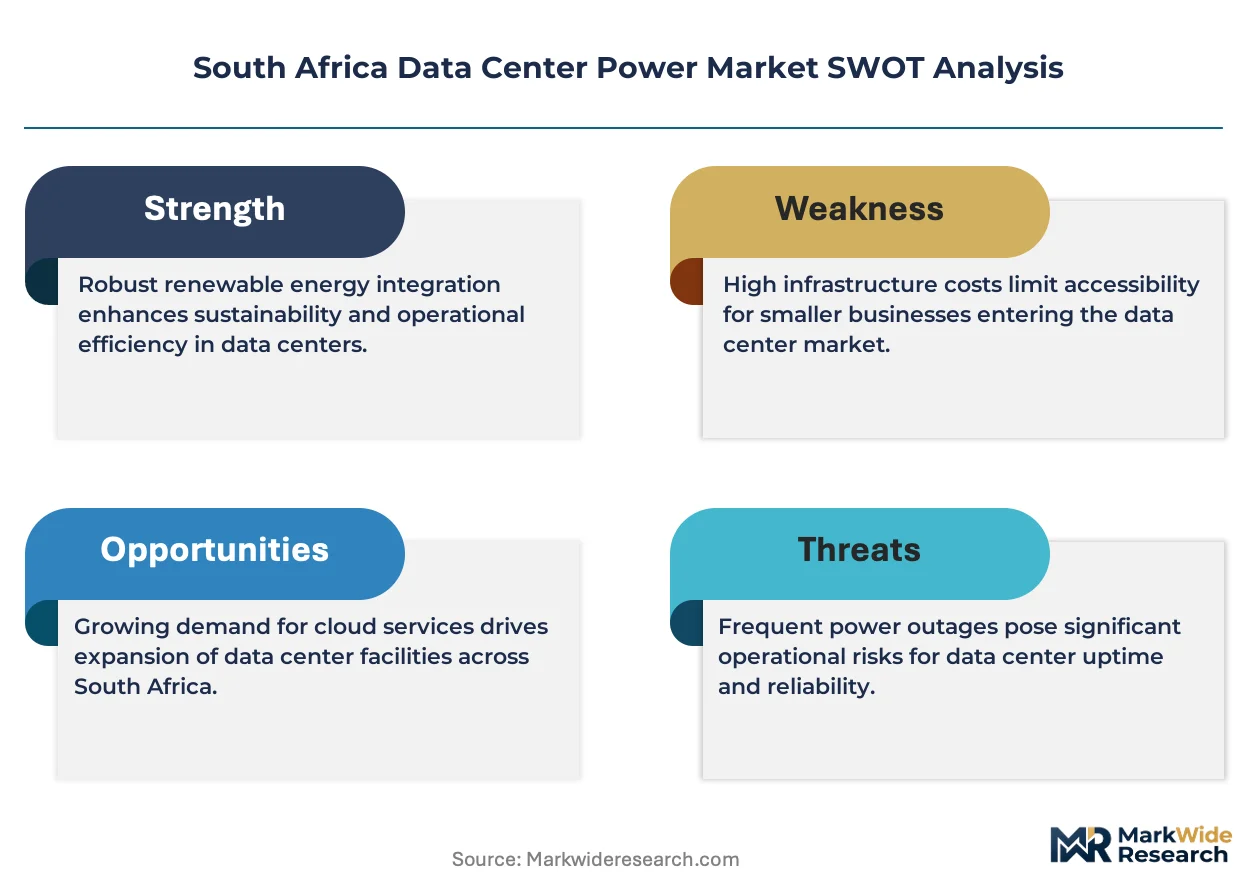
Load-shedding frequency is forcing facility operators to rearchitect power supply around captive generation, with diesel-to-solar hybrid transitions now the dominant capital allocation priority across Gauteng and Western Cape provinces.
Growth Catalysts
- Carbon Tax Act:The National Treasury's escalating carbon levy on diesel combustion pushes operators toward solar-plus-battery configurations, accelerating procurement timelines for renewable integration.
- Hyperscale expansion:Cloud service providers are scaling Johannesburg and Cape Town campuses, concentrating demand for 11kV distribution infrastructure and modular UPS systems.
- Embedded generation liberalization:NERSA's revised licensing thresholds permit facilities to self-generate up to 100MW without full regulatory approval, unlocking captive solar deployment.
Market Restraints
- Lithium-ion supply concentration:Battery cell sourcing depends on East Asian manufacturers, exposing procurement to shipping bottlenecks and currency volatility.
- Grid interconnection queues:Municipal utility connection backlogs in Ekurhuleni and Tshwane delay commissioning timelines by 18-24 months for new facilities.
- Diesel price volatility:Generator fuel costs track Brent crude movements, compressing operating margins for facilities lacking renewable backup.
Strategic Opportunities
- Free State edge deployment:Secondary cities including Bloemfontein show underpenetrated colocation demand with lower land and power costs than primary metros.
- Green hydrogen pilot integration:Fuel cell backup systems offer longer-duration resilience than batteries, with the Department of Science and Innovation funding demonstration projects.
- Wheeling agreement expansion:Revised municipal tariff structures enable facilities to purchase renewable energy from remote solar farms via grid transmission.
Industry Challenges
- Medium-voltage engineering scarcity:Local expertise in 11kV switchgear design and commissioning remains concentrated among aging specialists, constraining project velocity.
- Hybrid system integration complexity:Synchronizing solar inverters, battery management systems, and diesel generators demands specialized controls engineering that outpaces training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Data Center Power Market |
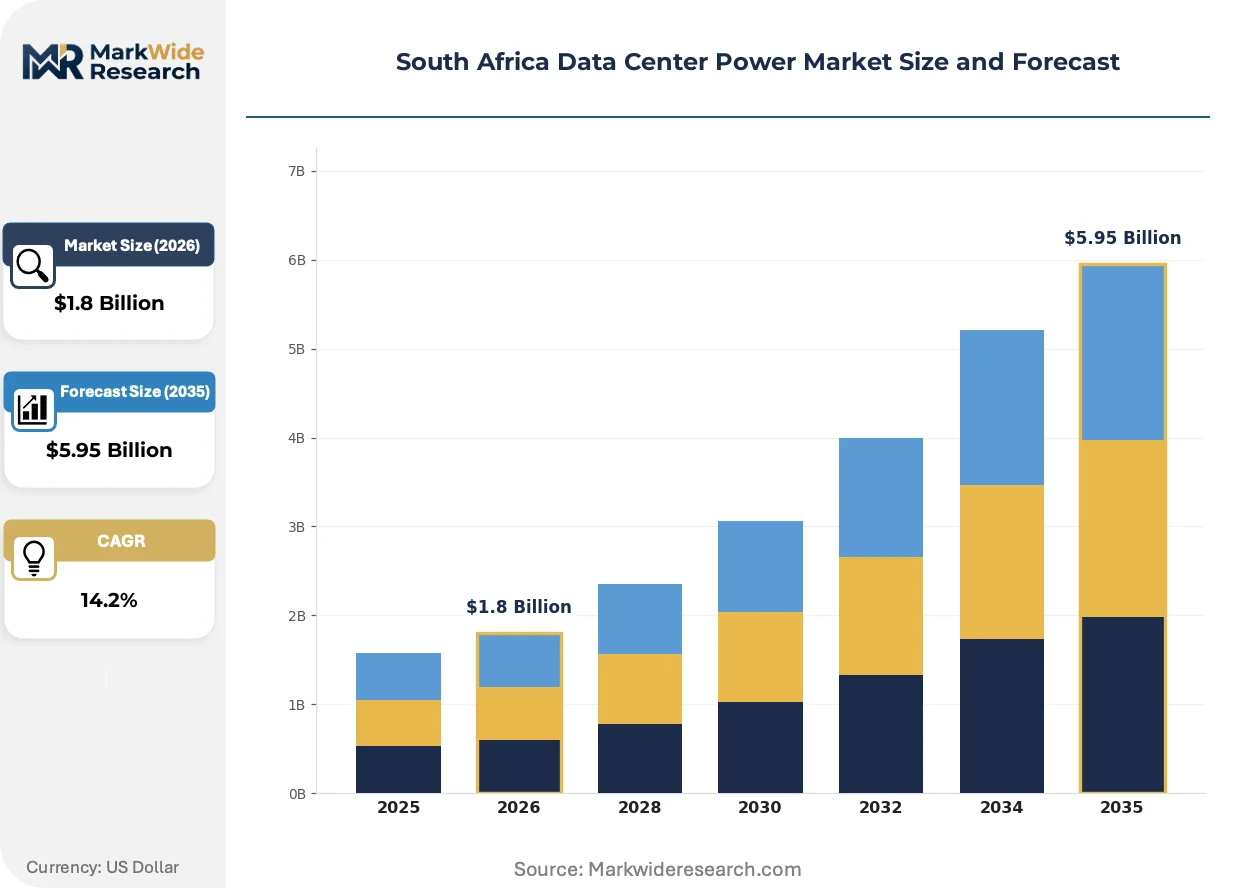
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Renewable Energy, Diesel Generators, Grid Power, Hybrid Solutions Data Center Type: Colocation Centers, Enterprise Data Centers, Hyperscale Data Centers, Edge Data Centers Facility Size: Small Scale, Medium Scale, Large Scale, Mega Scale Infrastructure Type: Cooling Systems, Uninterruptible Power Supply, Racks, Power Distribution Units |
| Companies Covered | ABB Ltd, Eaton Corp PLC, Schneider Electric SE, Vertiv Holdings Co Class A, Cummins Inc, Aggreko ZA, Legrand SA, Delta Electronics, Master Power Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Data Center Power Market Trends and Innovations
Digital infrastructure operators are reconfiguring power architectures around software-defined control, with virtualization of energy management emerging as the decisive operational differentiator for uptime-critical facilities.
Software-defined power management is virtualizing physical switching and load balancing functions into centralized control planes. Hyperscale operators in Johannesburg are deploying these platforms to orchestrate multi-source generation in real time. This virtualization is compressing response times to grid disturbances from seconds to milliseconds, reducing reliance on mechanical transfer switches.
NERSA's electricity pricing methodology revisions are restructuring how facilities evaluate grid versus self-supply economics. The regulator's inclining block tariffs penalize high-consumption users, accelerating solar-plus-storage adoption among colocation providers. Western Cape facilities are responding by oversizing rooftop arrays to export surplus generation during daylight hours.
Power purchase agreements with independent renewable developers are displacing traditional utility contracts as the preferred procurement mechanism. Enterprise buyers in financial services are contracting directly with solar farms in Northern Cape to secure fixed-price electrons. This shift is most visible among Tier III-certified facilities seeking carbon neutrality timelines aligned with parent-company sustainability commitments.
South Africa Data Center Power Market Segmentation
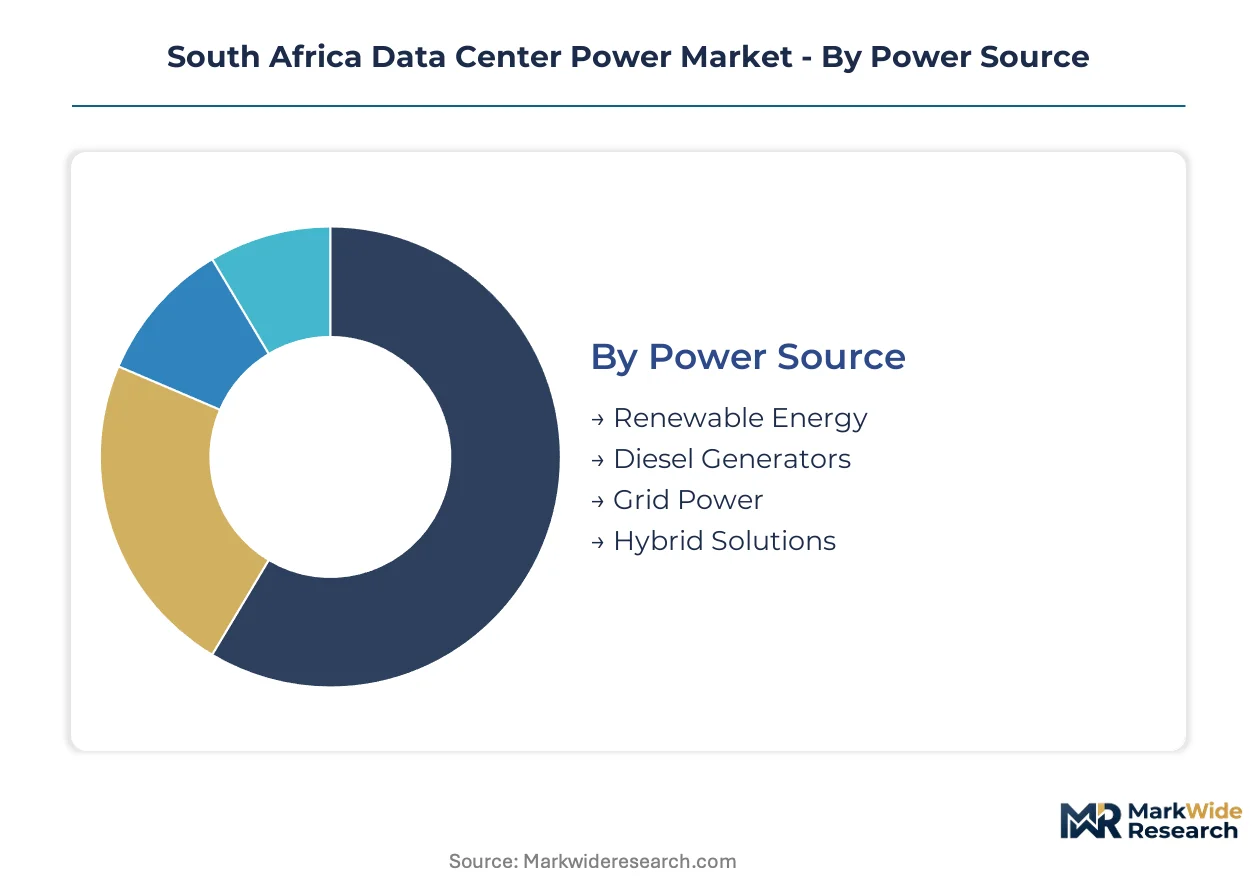
Power architecture decisions in South African data centers diverge sharply across facility types and scale tiers. Load-shedding intensity and carbon tax exposure create asymmetric incentives that reshape segment prioritization for operators in Gauteng and Western Cape provinces.
Power Source:
Facilities span diesel-reliant legacy designs through fully renewable microgrids, with hybrid architectures now dominating new capital deployment.
- Hybrid Solutions:Solar-plus-battery systems synchronized with grid and diesel backup dominate new hyperscale construction. NERSA's embedded generation thresholds accelerate adoption among Johannesburg operators seeking tariff arbitrage.
- Renewable Energy:Captive solar arrays and wheeling agreements from Northern Cape solar farms supply Tier III-certified facilities. Carbon tax liabilities on diesel combustion redirect procurement toward direct renewable contracting.
- Diesel Generators:Caterpillar and Cummins units provide synchronous backup for financial services uptime requirements. Fuel price volatility compresses margins for operators lacking renewable transition timelines.
- Grid Power:Municipal utility supply from Eskom and metropolitan distributors remains primary for legacy facilities. Interconnection queues in Ekurhuleni and Tshwane extend commissioning timelines.
The dominant share belongs to Hybrid Solutions, while Renewable Energy is closing the gap fastest.
Data Center Type:
Customer concentration and certification requirements stratify power architecture investment across ownership models.
- Hyperscale Data Centers:Cloud service providers operating 10MW-plus campuses in Johannesburg and Cape Town demand 11kV distribution infrastructure and modular UPS at 15-plus kW per rack densities.
- Colocation Centers:Multi-tenant facilities balance diverse tenant SLA requirements through redundant power architectures. Western Cape operators oversize rooftop solar to export surplus generation.
- Enterprise Data Centers:Captive banking and telecommunications facilities prioritize diesel reliability for core transaction processing. Carbon neutrality commitments accelerate solar-plus-storage retrofits.
- Edge Data Centers:Secondary city deployments in Bloemfontein and Gqeberha exploit lower land costs with containerized power modules. Underpenetrated demand drives modular UPS procurement.
Hyperscale Data Centers command the largest capital allocations, though Edge Data Centers are expanding most quickly.
Facility Size:
Power density and redundancy architecture scale non-linearly with facility footprint and rack count.
- Mega Scale:50MW-plus campuses require dedicated substations and medium-voltage switchgear with N-plus-one redundancy across all power paths.
- Large Scale:10-50MW facilities standardize on 11kV distribution with lithium-ion battery energy storage systems for 15-minute ride-through.
- Medium Scale:1-10MW operations deploy modular UPS and captive solar with grid-tie inverters for peak shaving.
- Small Scale:Sub-1MW edge and enterprise closets rely on line-interactive UPS and portable diesel generators for load-shedding resilience.
Mega Scale facilities absorb disproportionate engineering talent, while Medium Scale projects are multiplying fastest.
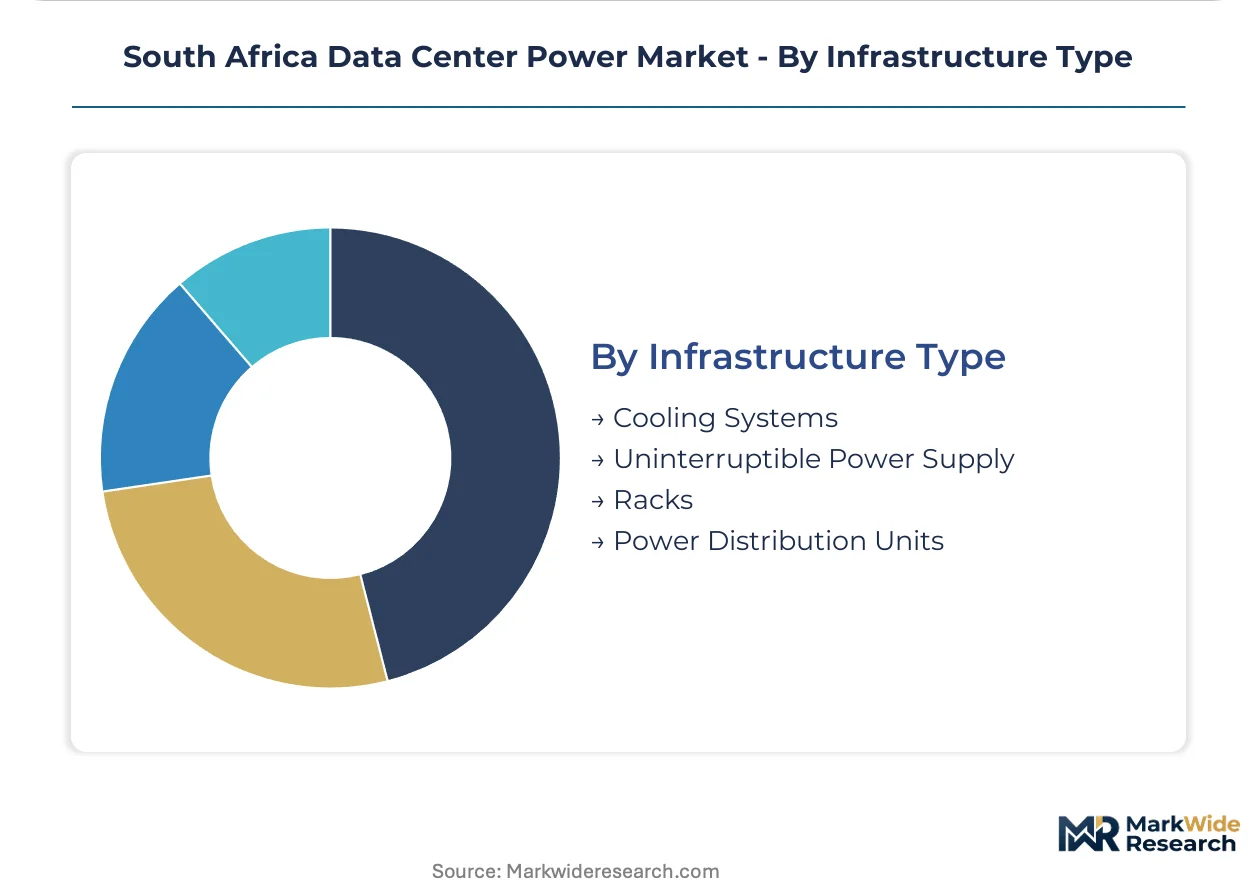
Infrastructure Type:
Margin pools concentrate in power conditioning and distribution equipment where uptime certification requirements sustain pricing premiums.
- Uninterruptible Power Supply:Double-conversion online systems with lithium-ion battery integration protect hyperscale loads. Software-defined power management virtualizes switching functions for millisecond response.
- Power Distribution Units:Intelligent rack-level PDUs with outlet-level metering dominate colocation deployments. Remote monitoring capabilities support SLA verification for multi-tenant environments.
- Cooling Systems:Precision air handlers and liquid cooling infrastructure draw power from shared electrical buses. Heat rejection loads shape transformer sizing and backup generator selection.
- Racks:Enclosed cabinet systems with integrated busway connections standardize power delivery at 15-plus kW densities. Hot-aisle containment drives airflow management power budgets.
Uninterruptible Power Supply captures the deepest margin pools, while Power Distribution Units are gaining share fastest through metering monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Gauteng province demonstrate the highest price sensitivity to grid instability, while Western Cape operators absorb premium costs for renewable certification. Load-shedding frequency creates divergent investment timelines across provinces.
Gauteng
Johannesburg and Tshwane hyperscale campuses drive concentrated demand for 11kV distribution infrastructure. NERSA's embedded generation thresholds permit self-generation up to 100MW without full regulatory approval. Ekurhuleni municipal interconnection queues extend commissioning timelines by 18-24 months for new facilities.
Western Cape
Cape Town colocation providers oversize rooftop solar arrays to export surplus generation during daylight hours. The National Treasury's escalating carbon levy on diesel combustion accelerates solar-plus-battery procurement. Atlantis and Stellenbosch industrial zones attract edge data center deployment with lower land costs than primary metros.
KwaZulu-Natal
Durban's undersea cable landing points position the province for latency-sensitive financial services infrastructure. The Department of Mineral Resources and Energy's wheeling agreement frameworks enable remote renewable sourcing. Richards Bay industrial corridor offers captive solar deployment with port logistics advantages.
Eastern Cape
Gqeberha secondary city deployments exploit containerized power modules for underpenetrated colocation demand. Municipal tariff restructuring proceeds slower than in primary metros, preserving diesel-dependent legacy architectures. Coega Special Economic Zone incentives attract modular UPS procurement for edge facilities.
Free State
Bloemfontein shows emerging demand for disaster recovery sites with lower operational costs than Johannesburg. The Department of Science and Innovation funds green hydrogen pilot integration for fuel cell backup systems. Mangaung metropolitan area offers land cost arbitrage for medium-scale facilities seeking tariff arbitrage.
South Africa Data Center Power Market Competitive Landscape
Capability concentration sits with integrated power management specialists; scale advantage sits with diversified electrical equipment conglomerates. The vendor base stratifies across three tiers: global technology platforms with software-defined architectures, regional assembly operations with local switchgear expertise, and captive rental providers with mobile generation fleets. Strategic moves center on tightening spare parts control to capture recurring service contracts and localizing medium-voltage switchgear assembly to circumvent import lead times.
Within the integrated platform tier, Schneider Electric SE and Eaton Corp PLC exemplify divergent approaches to market position. Schneider Electric SE leverages software-defined power management to anchor recurring revenue streams. Eaton Corp PLC occupies a position emphasizing local assembly capabilities for medium-voltage infrastructure. Cummins Inc represents the reliability-focused archetype serving financial services uptime requirements through diesel generator specialization.
| Leading Market Players |
|---|
| ABB Ltd |
| Eaton Corp PLC |
| Schneider Electric SE |
| Vertiv Holdings Co Class A |
| Cummins Inc |
| Aggreko ZA |
| Legrand SA |
| Delta Electronics |
| Master Power Technologies |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in East Asian lithium-ion cell manufacturing is compressing battery module pricing while extending payment terms for South African integrators, simultaneously tightening supplier discipline and shifting procurement leverage toward buyers with volume commitments.
Pricing Analysis
Aftermarket service contracts and spare parts availability anchor lifetime value capture for power equipment vendors. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and uptime SLA requirements. Cost compression in the standard tier is intensifying because original equipment manufacturers are restricting third-party service access. Financial services operators demonstrate the lowest price sensitivity due to regulatory uptime mandates, while edge facility developers in secondary cities prioritize capital efficiency over redundancy specifications.
Supply Chain Analysis
Contract manufacturing for UPS and power distribution units concentrates with Delta Electronics and regional assembly operations in China and Taiwan. Battery cell sourcing draws from South Korean and Japanese manufacturers, with inverter components resting on semiconductor supply from Taiwan. Single-source vulnerability in IGBT and MOSFET procurement exposes lead time volatility for medium-voltage switchgear projects. Distribution runs through authorized distributor networks and direct enterprise sales channels serving Johannesburg and Cape Town hyperscale campuses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medium-voltage engineering talent scarcity constrains project velocity across Gauteng and Western Cape provinces, creating asymmetric returns for stakeholders who secure commissioning expertise before competitors.
For Market Incumbents: Insulate recurring revenue streams by tightening spare parts control and embedding remote diagnostics software into power management platforms. Vertical integration into local switchgear assembly mitigates import lead time exposure from East Asian component suppliers. Certification investment in Tier III and Tier IV design standards preserves pricing premiums against modular competitors. For New Entrants and Emerging Players: Build out captive solar engineering capabilities to capture procurement arbitrage from NERSA's embedded generation thresholds. Free State edge deployments offer the most penetrable geography, with Bloemfontein land costs running below Johannesburg metro premiums. Direct power purchase agreement origination with Northern Cape solar developers provides a differentiated go-to-market angle for financial services buyers seeking fixed-price renewable supply. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated power management platforms with software-defined control architectures. Long-term viability across the analysis window favors vendors with captive service networks and localized medium-voltage assembly capabilities. Acquisition targets should demonstrate established relationships with Ekurhuleni and Tshwane municipal utilities to circumvent interconnection queue delays. The signal to watch is NERSA licensing threshold adjustments that could accelerate or constrain captive generation deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Local Switchgear Assembly Expansion | Eaton Corp PLC's Gauteng facility reduces import lead times for 11kV distribution projects. |
| Software-Defined Power Management Launch | Schneider Electric SE's EcoStruxure platform virtualizes switching functions for millisecond grid response. |
| Solar-Plus-Battery Procurement Partnership | Western Cape colocation providers oversize rooftop arrays to export surplus generation via municipal wheeling. |
| Green Hydrogen Pilot Integration | Department of Science and Innovation funding supports fuel cell backup demonstrations in Free State edge facilities. |
| Remote Diagnostics Platform Deployment | Cummins Inc's digital service contracts capture recurring revenue from financial services uptime requirements. |
Research Methodology
A standing panel of data center facility directors, EPC contractors, NERSA regulatory affairs specialists, and municipal utility interconnection managers provided ongoing calibration across the primary research phase. Secondary validation drew from Eskom integrated reports, Department of Mineral Resources and Energy policy circulars, NERSA electricity pricing determinations, and hyperscaler capital expenditure disclosures. Bottom-up project pipeline analysis triangulated against top-down equipment shipment tracking from major suppliers.
Scenario-bracketing framed the analytical approach, with load-shedding frequency bands and carbon tax escalation paths tested across the projection horizon. Segmentation dimensions modeled include power source category, facility scale tier, data center type, and infrastructure component. CAGRs were derived from installed capacity buildout trajectories and equipment replacement cycles specific to lithium-ion battery energy storage systems and medium-voltage switchgear.
Stress conditions across lithium supply contract volatility, rand-dollar exchange rate movement, and municipal tariff restructuring pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding NERSA embedded generation threshold stability and Eskom grid reliability trajectories. Quarterly review of interconnection queue lengths, battery cell shipping rates, and carbon tax amendment proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
France Data Center Construction Market
Data Center Infrastructure
Canada Data Center Server Market
Data Center Infrastructure
Germany Data Center Physical Security Market
Data Center Infrastructure
Philippines Data Center Physical Security Market
Data Center Infrastructure
Indonesia Data Center Power Market
Data Center Infrastructure
Ireland Data Center Market
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
Scientific Data Management System Market
Data Center Infrastructure
North America Data Center Infrastructure Management Market
Data Center Infrastructure
Colocation Edge Data Center Market
Data Center Infrastructure
Germany Data Center Construction Market
Data Center Infrastructure
Global Telecommunication Equipment Cabinet and Racks Market
Data Center Infrastructure
Ireland Data Center Rack Market
Data Center Infrastructure
Next Generation Data Center Market
Data Center Infrastructure
China Data Center Rack Market
Data Center Infrastructure
France Data Center Rack Market