
 RFID Smart Cabinet Market | 2026-2036
RFID Smart Cabinet Market Size, Share, and Industry Trends Forecast 2026-2036
RFID Smart Cabinet Market Outlook
Aluminum alloy framing is repositioning steel-reinforced cabinet construction across mid-tier product lines, trimming unit weight and shipping costs. Terso Solutions leverages cloud-native architecture to anchor its position in pharmaceutical cold-chain tracking. LogiTag Systems specializes in RFID-enabled surgical supply management, sustaining R&D intensity in passive tag integration. WaveMark competes through Cardinal Health's distribution reach, occupying premium health system accounts with enterprise-scale deployments.
RFID smart cabinets are enclosed storage systems equipped with radio-frequency identification readers, antenna arrays, and sensor networks that authenticate users and track item-level inventory without manual scanning. These units typically operate at ultra-high frequency ranges and integrate with enterprise resource planning platforms to automate replenishment, expiration monitoring, and chain-of-custody documentation for high-value assets. Trolley cabinets lead healthcare deployment due to mobility requirements in operating suites and emergency departments, while cloud-based solutions represent the fastest-expanding deployment category as facilities prioritize remote analytics and multi-site inventory visibility. Passive RFID technology dominates unit economics in cost-sensitive installations, though active RFID commands margin pools in temperature-sensitive pharmaceutical applications where real-time location granularity justifies higher tag costs.
The FDA enforces Unique Device Identification rules that mandate item-level traceability for medical devices, directly expanding demand for cabinet systems capable of automated UDI capture and audit logging. The EU Medical Device Regulation imposes similar post-market surveillance obligations, requiring European healthcare providers to maintain verifiable usage records that RFID infrastructure satisfies. Stakeholders must weigh interoperability commitments against proprietary ecosystem lock-in as health system procurement shifts toward platform-agnostic specifications.
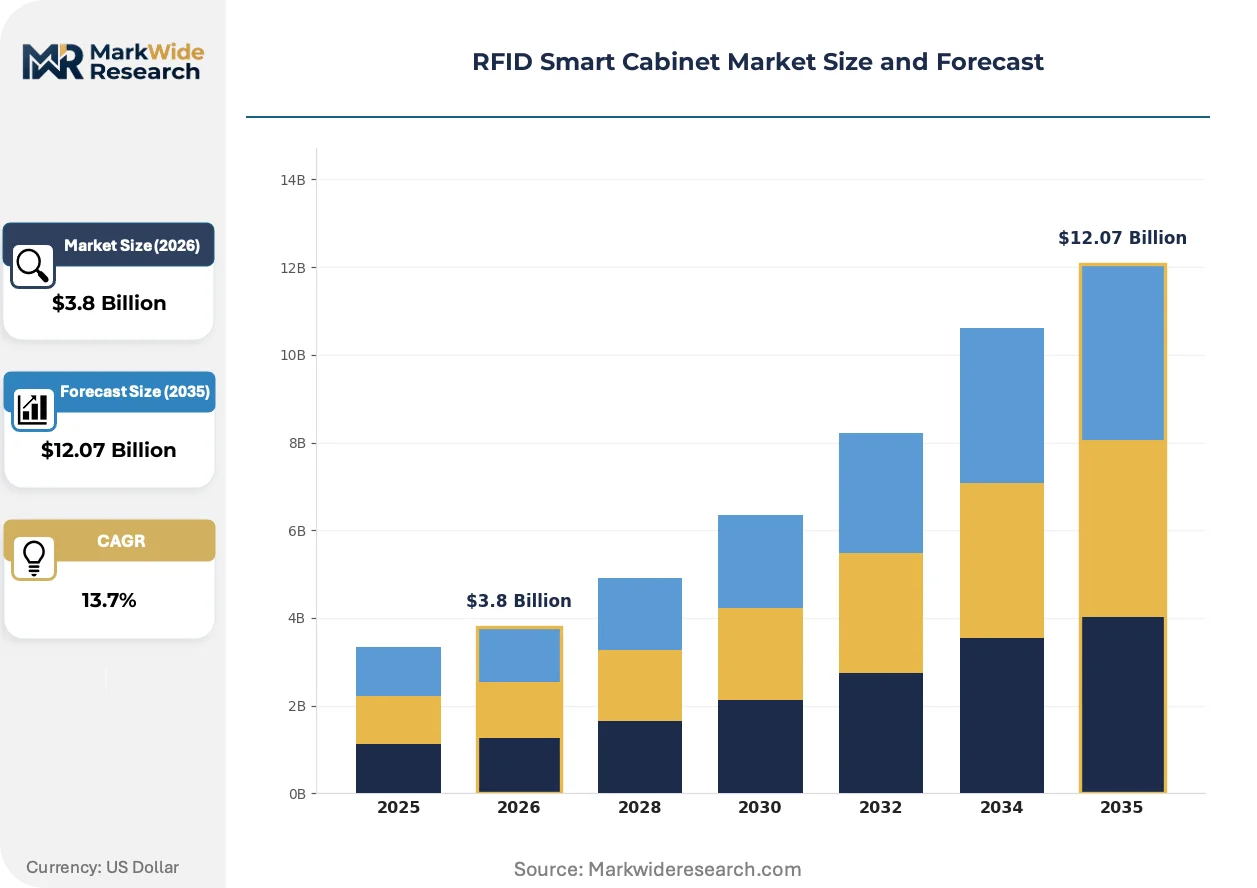
Market Dynamics
Health system consolidation is compressing procurement cycles and favoring enterprise-scale RFID cabinet deployments that span multiple facilities under unified inventory visibility platforms.
Growth Catalysts
- FDA Unique Device Identification mandate:The regulation compels hospitals to maintain item-level traceability logs for implantable medical devices, creating mandatory demand for automated cabinet systems that capture UDI data without manual entry.
- Cloud-native architecture migration:Healthcare IT departments are prioritizing SaaS-based inventory platforms that enable remote multi-site analytics, reducing on-premise infrastructure burden while expanding real-time visibility across distributed pharmacy networks.
- Operating suite mobility requirements:Trolley-mounted RFID cabinets address point-of-care consumption tracking in surgical and emergency settings where fixed installations cannot serve workflow patterns.
Market Restraints
- Active RFID tag cost structure:Temperature-sensitive pharmaceutical tracking requires battery-powered tags at 15-50x the unit cost of passive alternatives, limiting deployment to high-value cold-chain assets.
- Steel-aluminum raw material volatility:Cabinet framing materials face commodity price swings that compress mid-tier manufacturer margins and complicate long-term contract pricing.
- Interoperability friction from proprietary protocols:Vendor-specific reader architectures create integration barriers with existing enterprise resource planning systems, extending deployment timelines.
Strategic Opportunities
- EU Medical Device Regulation post-market surveillance:The MDR's usage-record requirements create regulatory tailwind for RFID infrastructure among European hospitals still operating manual tracking systems.
- Biologics and cell therapy expansion:Temperature-controlled gene therapy products require chain-of-custody documentation that active RFID cabinets with integrated environmental sensors can automate.
- India's hospital infrastructure modernization:Private hospital chains in Mumbai, Delhi, and Bangalore are importing automated pharmacy systems to meet accreditation standards for medical tourism.
Industry Challenges
- RFID systems integration talent scarcity:Healthcare IT departments lack personnel trained in ultra-high frequency antenna configuration and middleware deployment, forcing reliance on vendor professional services.
- Legacy barcode infrastructure coexistence:Hybrid environments requiring parallel RFID and barcode workflows increase training burden and error rates during transition periods.
- Electromagnetic interference in clinical settings:Surgical equipment and imaging devices create signal noise that degrades read accuracy, demanding site-specific antenna tuning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RFID Smart Cabinet Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.07 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lockers, Shelving Units, Trolley Cabinets, Tool Cabinets End User: Healthcare Facilities, Manufacturing Plants, Retail Stores, Libraries Deployment: On-Premises, Cloud-Based Solutions, Hybrid Systems, Mobile Applications Technology: Active RFID, Passive RFID, NFC, Bluetooth |
| Companies Covered | Terso Solutions, LogiTag Systems, WaveMark (Cardinal Health), Mobile Aspects, SATO Holdings Corporation, Solstice Medical, Stanley Healthcare, Nexess, Impinj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RFID Smart Cabinet Market Strategic Shifts
Sensor fusion and edge computing are transforming RFID cabinets from passive inventory repositories into active decision nodes that trigger automated replenishment and expiration alerts without human intervention.
Ultra-high frequency RFID reader modules with integrated environmental sensors are unifying temperature, humidity, and motion detection within single hardware enclosures. Hospital pharmacies in the United States are adopting these consolidated units for vaccine and biologic storage. This convergence is compressing the vendor landscape by eliminating separate sensor network contracts and reducing cabling infrastructure.
The EU Medical Device Regulation's post-market surveillance obligations are mandating verifiable usage records for implantable devices. European healthcare providers must maintain audit trails that manual systems cannot satisfy. High-value orthopedic and cardiovascular implant categories are driving first-wave cabinet installations in Germany, France, and the Netherlands.
Consolidated purchasing through group purchasing organizations is compressing vendor negotiation cycles and unbundling after-sales service contracts from hardware acquisition. Health systems in the United States are demanding standalone software licensing that permits multi-vendor hardware environments. This procurement evolution is most visible among IDN-affiliated hospitals seeking to standardize analytics dashboards across acquired facilities.
RFID Smart Cabinet Market Segmentation
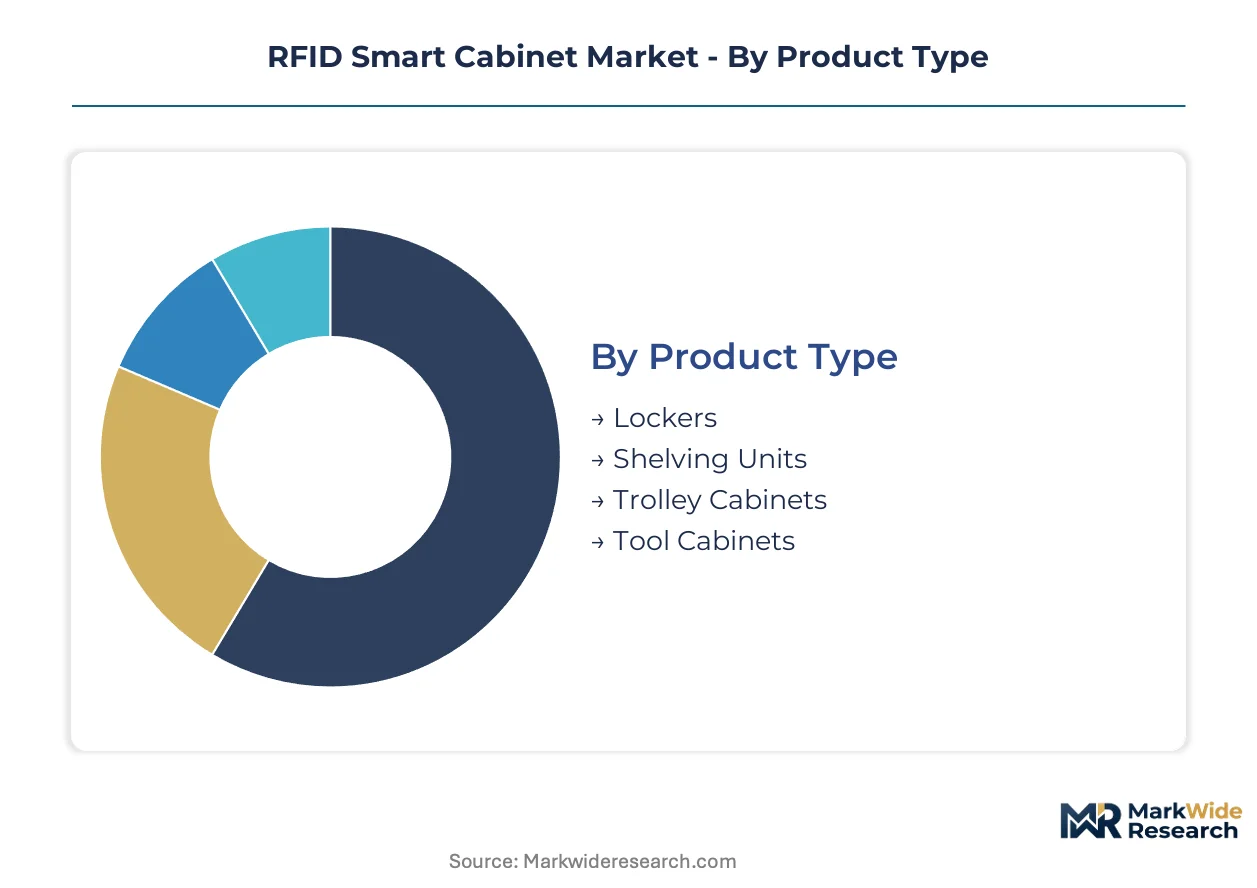
RFID smart cabinet segmentation reveals divergent hardware requirements across temperature-controlled pharmaceutical storage, mobile surgical workflows, and fixed industrial inventory systems. Each category demands distinct reader configurations, antenna densities, and software integration architectures that reshape procurement criteria and vendor selection.
Product Type:
Buyer differentiation in product type hinges on mobility requirements versus fixed infrastructure investment cycles, with surgical departments prioritizing wheeled configurations and pharmacies favoring stationary high-density storage.
- Trolley Cabinets:Mobile units with integrated battery systems and shock-resistant reader arrays serve operating suites and emergency departments where point-of-care consumption tracking is mandatory. United States health systems are standardizing these across IDN-affiliated surgical centers to enable inter-facility asset pooling and reduce implant inventory redundancy.
- Lockers:Compartmentalized access-control systems authenticate individual users through biometric or badge-based entry, creating audit trails for controlled substances and high-value implants. Hospital pharmacies in Germany and France are deploying these for EU Medical Device Regulation compliance, capturing item-level UDI data at the moment of dispensing.
- Shelving Units:Fixed installations with overhead antenna arrays provide high-density storage for bulk pharmaceutical inventory and medical device consignment stock.
- Tool Cabinets:Industrial-grade enclosures with reinforced framing serve manufacturing plants and maintenance facilities for calibrated instrument tracking.
Trolley cabinets lead volumes today; cloud-connected locker systems are gaining share fastest.
End User:
End-user segmentation reflects divergent regulatory exposure, with healthcare facilities facing FDA and EMA traceability mandates while industrial buyers prioritize asset utilization metrics over chain-of-custody documentation.
- Healthcare Facilities:Hospitals and ambulatory surgery centers deploy cabinets for implantable device tracking, pharmaceutical inventory, and specimen management. United States health systems are consolidating procurement through group purchasing organizations, demanding enterprise-scale deployments with unified analytics dashboards across acquired facilities.
- Manufacturing Plants:Industrial facilities track calibrated tools, work-in-progress components, and maintenance equipment through RFID-enabled storage. Automotive and aerospace manufacturers in Japan and Germany are integrating these systems with manufacturing execution platforms to enforce tool accountability and prevent foreign object damage incidents.
- Retail Stores:Specialty retailers deploy cabinets for high-value electronics, luxury goods, and controlled-access merchandise.
- Libraries:Academic and public institutions automate media and equipment lending through self-service RFID checkout systems.
Healthcare facilities dominate revenue concentration; manufacturing plants are expanding deployment most rapidly.
Deployment:
Deployment mode selection separates capital-constrained buyers seeking minimal IT infrastructure from multi-site organizations requiring centralized visibility across distributed inventories.
- Cloud-Based Solutions:SaaS platforms with browser-based analytics dashboards eliminate on-premise server requirements and enable remote multi-site inventory visibility. United States hospital pharmacies are prioritizing these configurations to reduce IT maintenance burden and accelerate deployment across acquired facilities in health system consolidation scenarios.
- On-Premises:Locally hosted systems with dedicated server infrastructure serve facilities with strict data residency requirements or limited internet connectivity. Defense and government healthcare facilities in the United States mandate these configurations for cybersecurity compliance.
- Hybrid Systems:Architectures combining edge processing with cloud analytics balance real-time responsiveness and centralized reporting.
- Mobile Applications:Smartphone and tablet interfaces extend cabinet functionality for remote inventory queries and approval workflows.
On-premises systems retain installed base leadership; cloud-based solutions are climbing the fastest.
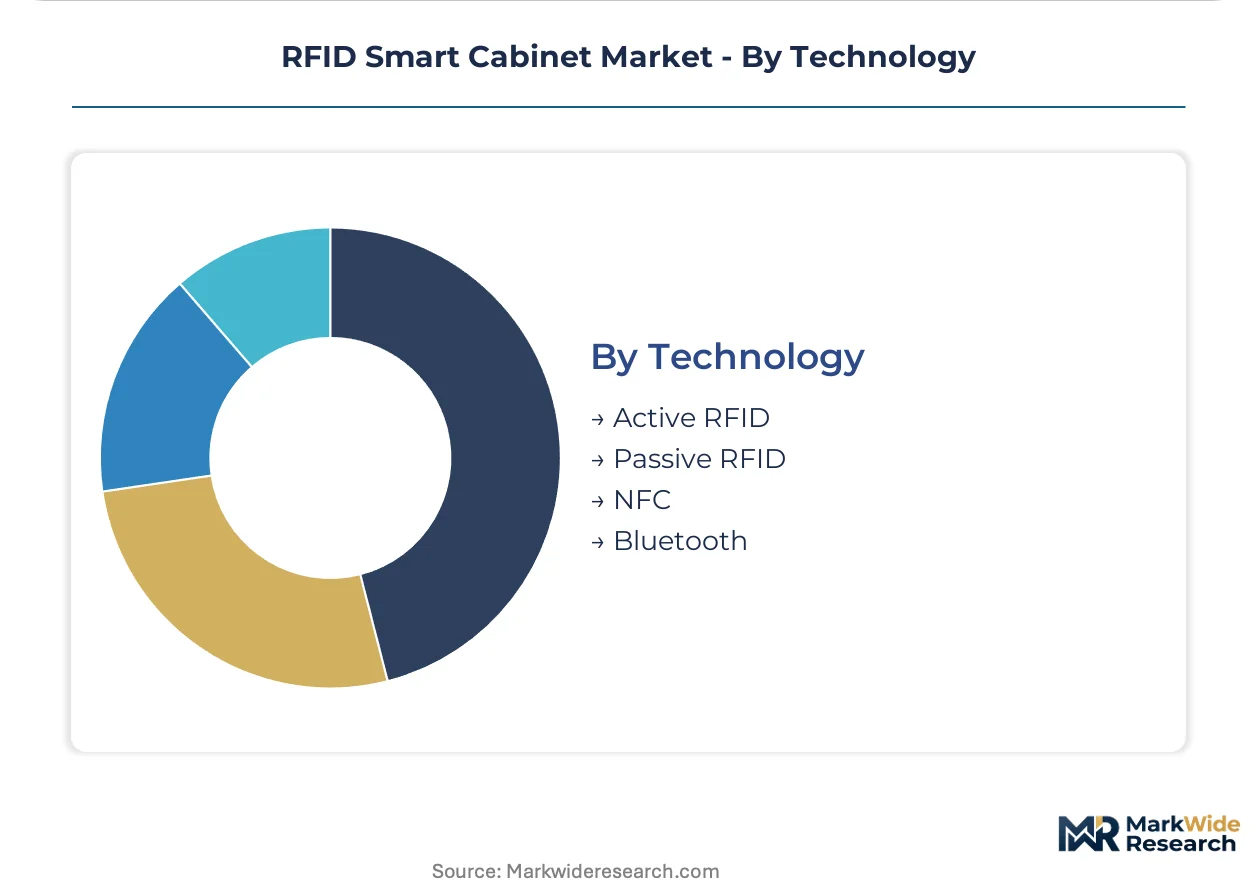
Technology:
Technology selection divides cost-sensitive high-volume applications from mission-critical cold-chain tracking where real-time location granularity justifies premium tag economics.
- Passive RFID:Battery-free tags powered by reader electromagnetic fields dominate unit economics in cost-sensitive installations. Standard ultra-high frequency configurations serve pharmaceutical inventory and implant tracking in United States hospitals where read ranges of 3-5 meters satisfy workflow requirements.
- Active RFID:Battery-powered tags with embedded sensors enable real-time location tracking and environmental monitoring for temperature-sensitive biologics. Cell therapy manufacturers and specialty pharmacies are deploying these for gene therapy products requiring continuous cold-chain documentation.
- NFC:Near-field communication enables tap-to-authenticate user interactions and short-range item verification.
- Bluetooth:Low-energy beacons support proximity-based location services and smartphone integration.
Passive RFID commands unit volume leadership; active RFID with integrated sensors is expanding most quickly in pharmaceutical cold-chain applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems in the United States are consolidating procurement through group purchasing organizations, compressing vendor negotiation cycles and accelerating enterprise-scale RFID cabinet deployments across multi-facility networks.
United States
FDA Unique Device Identification mandates compel hospitals to maintain automated traceability logs for implantable devices. Health system consolidation across the Southeast and Midwest is standardizing analytics dashboards across acquired facilities. IDN-affiliated surgical centers in Texas and Florida are deploying trolley-mounted cabinets for inter-facility asset pooling.
Germany
EU Medical Device Regulation post-market surveillance obligations require verifiable usage records for high-value orthopedic and cardiovascular implants. The country's national pharmaceutical regulator enforces strict chain-of-custody documentation standards. Hospital pharmacies in Bavaria and North Rhine-Westphalia are installing locker systems with integrated UDI capture capabilities.
France
ANSM oversight of medical device traceability is tightening documentation requirements for implantable products. The country's national data protection authority imposes strict audit logging standards for patient-linked inventory systems. Healthcare clusters in Île-de-France and Auvergne-Rhône-Alpes are deploying biometric-access lockers for controlled substance management.
India
Private hospital chains in Mumbai, Delhi, and Bangalore are importing automated pharmacy systems to meet accreditation standards for medical tourism. CDSCO medical device regulations are expanding traceability requirements for imported implants. CDSCO's phased UDI implementation is driving first-wave cabinet adoption among tertiary care centers in Maharashtra and Karnataka.
Japan
PMDA pharmaceutical traceability standards require temperature-controlled documentation for biologics and cell therapies. METI industrial digitization incentives support RFID infrastructure deployment in manufacturing-linked healthcare facilities. Medical device distributors in Kanto and Kansai regions are integrating cabinet systems with existing hospital information platforms.
RFID Smart Cabinet Market Competitive Environment
Global majors compete with regional champions across enterprise-scale deployments versus specialized workflow solutions. The vendor landscape organizes into three tiers: cloud-native platform providers, hardware-focused fabricators, and distribution-backed systems integrators. Consolidated purchasing through group purchasing organizations is compressing vendor margins. Strategic partnerships between hardware manufacturers and healthcare IT platforms are displacing standalone cabinet sales.
Within the cloud-native platform tier, Terso Solutions exemplifies architecture-first positioning. LogiTag Systems and WaveMark occupy positions spanning hardware integration and enterprise distribution reach. These three anchors represent divergent strategic bets on software subscription models versus channel-driven hardware deployment.
| Leading Market Players |
|---|
| Terso Solutions |
| LogiTag Systems |
| WaveMark (Cardinal Health) |
| Mobile Aspects |
| SATO Holdings Corporation |
| Solstice Medical |
| Stanley Healthcare |
| Nexess |
| Impinj |
| Others |
Value Chain & Pricing Dynamics
Aluminum alloy framing costs propagate through RFID smart cabinet manufacturing tiers, with commodity volatility in steel-aluminum pricing compressing margins for mid-tier fabricators serving cost-sensitive hospital pharmacies while premium cold-chain suppliers pass active RFID sensor costs to biologics manufacturers.
Pricing Analysis
Input-cost pass-through from raw material markets shapes tiered pricing structures across the industry. Three-tier pricing separates enterprise cloud-native deployments with integrated analytics from standard fixed-installation units and economy passive-RFID configurations. Price differentiation hinges on FDA UDI compliance certification and after-sales service bundling. Pricing pressure stems from group purchasing organization consolidation demanding unbundled software licensing. Hospital pharmacies exhibit highest price sensitivity; cell therapy manufacturers show lowest sensitivity due to regulatory documentation requirements.
Supply Chain Analysis
Domestic-content mandates in India's medical device procurement are reshaping sourcing patterns for cabinet assembly operations. Manufacturing concentrates in China, Germany, and the United States for reader module fabrication, antenna array production, and final system integration. Component dependencies include ultra-high frequency chips, environmental sensors, and aluminum extrusion framing. Supply chain risk centers on single-source vulnerability for specialized RFID reader chipsets. Distribution runs through medical device distributors and group purchasing organization channels to health system procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RFID smart cabinet demand is shifting toward premium specifications as FDA UDI mandates and EU MDR traceability requirements harden compliance thresholds, elevating quality-certified suppliers above commodity competitors.
For Market Incumbents: Hedge against margin erosion from cloud-native platform competition by deepening backward integration into reader module manufacturing and securing exclusive distribution agreements with Cardinal Health-tier logistics networks. Invest in FDA 21 CFR Part 11 validation certification to defend against software-only entrants targeting compliance-sensitive pharmaceutical cold-chain accounts.
For New Entrants and Emerging Players: Begin with India's private hospital modernization wave, where CDSCO UDI implementation creates first-mover windows among Mumbai and Bangalore tertiary centers lacking incumbent relationships. Target manufacturing plant asset tracking as an adjacent vertical with lighter regulatory barriers and faster procurement cycles than healthcare.
For Investors and Strategic Acquirers: Roll-up economics work for cloud-native platform specialists because health system consolidation demands unified multi-site inventory visibility that fragmented hardware vendors cannot deliver. Acquire targets with existing FDA-validated software stacks and hospital pharmacy reference accounts. Watch for inflection when group purchasing organizations begin mandating API-first architecture specifications in RFP language.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | SaaS architectures reduce hospital IT infrastructure burden while enabling multi-site analytics across IDN networks. |
| FDA 21 CFR Part 11 Validation | Electronic signature compliance opens pharmaceutical cold-chain accounts with strict audit documentation requirements. |
| Active RFID Sensor Integration | Embedded temperature monitoring captures gene therapy chain-of-custody data for cell therapy manufacturers. |
| Group Purchasing Organization Partnership | Standardized contracts with Premier or Vizient accelerate enterprise-scale deployments across affiliated facilities. |
| EU MDR Compliance Certification | UDI capture capabilities satisfy post-market surveillance obligations for orthopedic and cardiovascular implant tracking. |
Study Parameters
Direct dialogue with hospital pharmacy directors, biomedical equipment specialists, GPO contracts managers, and RFID systems integrators grounded the qualitative assessment, cross-referenced against FDA UDI guidance documents, EU MDR implementation notices, hospital procurement databases, and medical device distributor financial disclosures. Bottom-up and top-down triangulation validated segment-level assumptions.
Analytical lenses combined bottom-up unit economics modeling with top-down healthcare IT spending allocation analysis across the projection horizon. Segmentation dimensions included product mobility tier, deployment architecture, RFID technology class, and end-user regulatory exposure. CAGRs derived from healthcare capital expenditure trajectories and medical device traceability mandate implementation timelines. Forecast inputs incorporated health system consolidation velocity and cloud-native software adoption curves.
Several conditions sit outside the modeled scope, including hypothetical delays in FDA UDI enforcement, geopolitical disruptions to aluminum supply chains, and breakthroughs in computer vision-based inventory tracking. Forecasts reflect documented assumptions about regulatory implementation schedules and hospital capital budget availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Micro Location Technology Market
Sensors
Refrigeration Monitoring Market
Sensors
Lidar in Construction Market
Sensors
Traffic Sensor Market
Sensors
IO Link Market
Sensors
Smart Pest Monitoring Management System Market
Sensors
Temperature Data Loggers Market
Sensors
Location-Based Ambient Intelligence Market
Sensors
Digital Compass (E-Compass) Market
Sensors
Industrial Barcode Scanners Market
Sensors
Vision Positioning System Market
Sensors
Global Equipment Monitoring Market
Sensors
Wireless Synchronized Clocks Market
Sensors
Terrestrial Laser Scanning System Market
Sensors
Gesture Recognition in Retail Market
Sensors
Beacon Technology Market