
 France Data Center Server Market | 2026-2036
France Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
France Data Center Server Market Insights
Direct server procurement channels in France are fragmenting as hyperscale cloud commitments pull volume away from traditional distributor relationships. Hewlett Packard Enterprise leverages its manufacturing presence in Grenoble to sustain short-lead-time delivery for domestic enterprises. Dell Inc. competes through vertical integration into firmware and management software layers. Huawei Technologies navigates restricted access to certain public-sector tenders while maintaining channel control through European partnership structures.
France data center servers are compute nodes engineered to operate continuously in controlled environments, typically rated for ambient temperatures between 18°C and 27°C and equipped with redundant power supplies to ensure 99.999% uptime for mission-critical workloads. Their primary purpose is to host applications, store data, and manage network traffic for enterprises and service providers. Rack servers dominate volume shipments among product types due to standardization and density advantages in multi-tenant facilities. Edge computing deployments within the technology dimension represent the fastest-expanding configuration as latency-sensitive applications proliferate across manufacturing and autonomous systems. Managed service providers among end users capture expanding margin pools by bundling hardware with operational management and compliance services.
ANSSI certification requirements and EU CSRD sustainability disclosure rules shape server procurement specifications across French public and regulated private sectors. CE marking and REACH substance restrictions govern material composition and market access for imported equipment. Stakeholders must monitor evolving EU energy efficiency labeling frameworks and sovereign cloud accreditation criteria to anticipate qualification barriers and sourcing advantages.
Market Dynamics
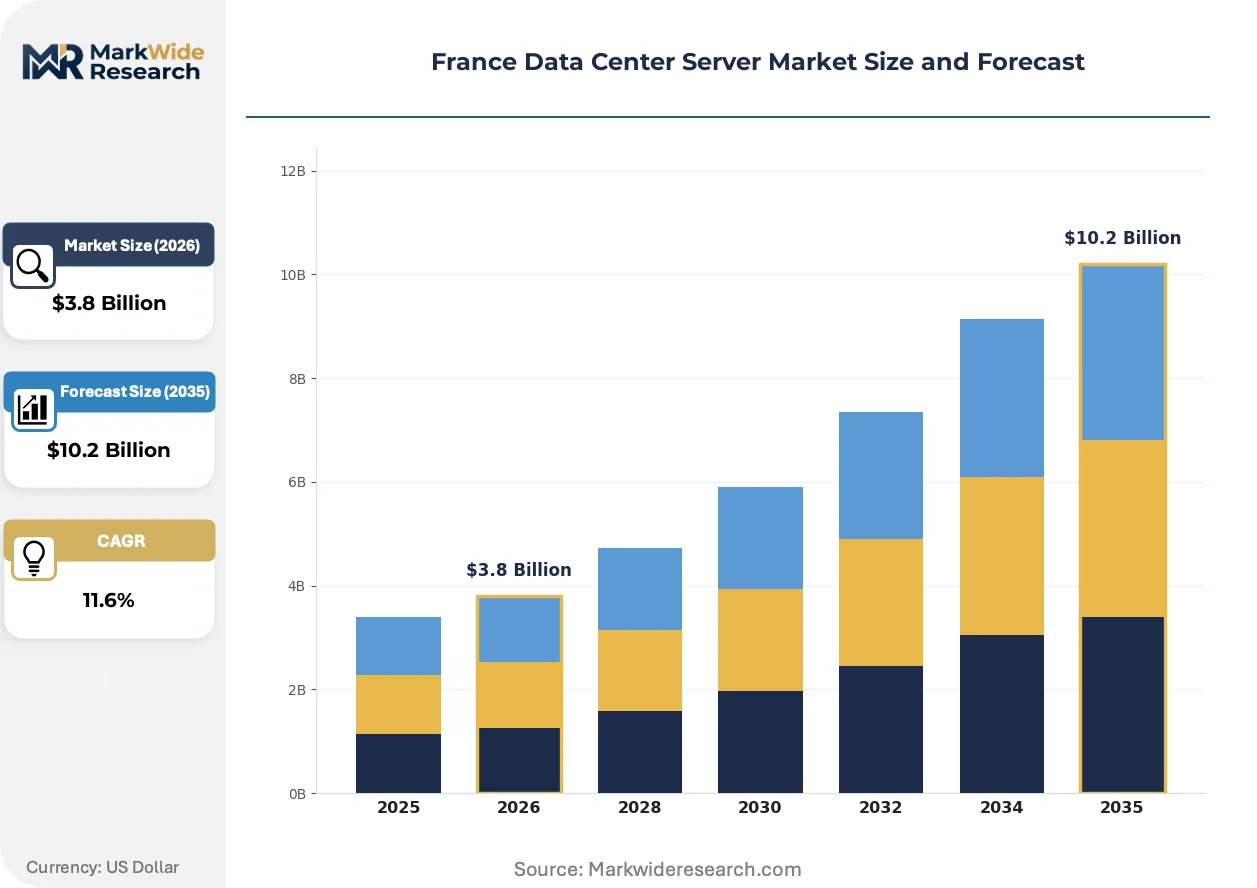
France's data center server market is being restructured by sovereign cloud mandates under ANSSI guidance, which are fragmenting procurement channels and forcing vendors to rebuild certification pathways for public-sector access.
Growth Catalysts
- Real-time financial workloads:French banking and insurance institutions are expanding server deployments to support low-latency transaction processing and fraud detection systems.
- EU AI Act compliance infrastructure:Enterprises are procuring dedicated compute nodes to host high-risk AI applications under the Act's risk-classification framework.
- Edge manufacturing demand:Automotive and aerospace producers in the Paris-Saclay corridor are installing localized servers for predictive maintenance and quality control.
Market Restraints
- Semiconductor input volatility:Advanced GPU and AI accelerator supply remains concentrated with TSMC and NVIDIA, creating lead-time uncertainty for French system integrators.
- Energy cost structure:Electricity prices in France, though partially shielded by nuclear baseload, still compress margins for power-intensive high-density rack deployments.
- REACH substance restrictions:The ECHA framework limits certain flame retardants and rare earth processing methods, constraining motherboard and chassis material sourcing.
Strategic Opportunities
- Marseille interconnection expansion:The Mediterranean cable landing hub offers underexploited capacity for submarine-connected edge facilities serving African and Middle Eastern traffic.
- CSRD sustainability disclosure:The EU mandate creates first-mover advantage for vendors offering lifecycle carbon accounting and circular hardware take-back programs.
- Quantum-classical convergence:Hybrid architectures combining traditional x86 nodes with quantum processing units are opening pilot procurement windows in research institutions.
Industry Challenges
- ANSSI certification timelines:The SecNumCloud and CSPN qualification processes extend sales cycles by 12-18 months for vendors targeting classified workloads.
- Legacy system integration friction:Mainframe-dependent financial institutions face architectural complexity when migrating core banking functions to distributed server environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Data Center Server Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Modular Servers End User: Large Enterprises, SMEs, Public Sector, Managed Service Providers Technology: Virtualization, Cloud Computing, Edge Computing, Hyperconvergence Application: Data Storage, Computing, Networking, Disaster Recovery |
| Companies Covered | Dell Inc., Hewlett Packard Enterprise, International Business Machines (IBM) Corporation, Cisco Systems Inc., Kingston Technology Company Inc., Huawei Technologies, Lenovo Group, Supermicro Computer, Inspur Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Data Center Server Market Trends and Innovations
Compute architectures in France are converging around sovereign deployment models, liquid cooling adoption, and procurement frameworks that bundle hardware with operational compliance.
Immersion and direct-to-chip liquid cooling is hybridizing thermal management strategies in French multi-tenant facilities. Colocation operators in the Paris region are retrofitting legacy air-cooled halls with dielectric fluid systems to accommodate 100kW+ GPU racks. This hybrid approach is compressing the payback period for high-density deployments while preserving existing real estate investments.
ANSSI's SecNumCloud qualification framework is mandating architectural modifications for cloud-adjacent server deployments. The regulation requires physical sovereignty guarantees, encryption key localization, and personnel vetting that disqualifies standard global hyperscale configurations. Regulated French healthcare and defense sectors are responding by procuring through accredited domestic operators rather than direct international cloud contracts.
Server procurement in France is consolidating around managed service wrappers that absorb compliance liability. Large enterprises are displacing direct hardware purchases with multi-year agreements where vendors own depreciation risk and guarantee uptime-plus-certification outcomes. This pattern is most visible in banking, where CAC 40 institutions now specify operational SLAs over raw compute specifications in tender documents.
France Data Center Server Market Segmentation
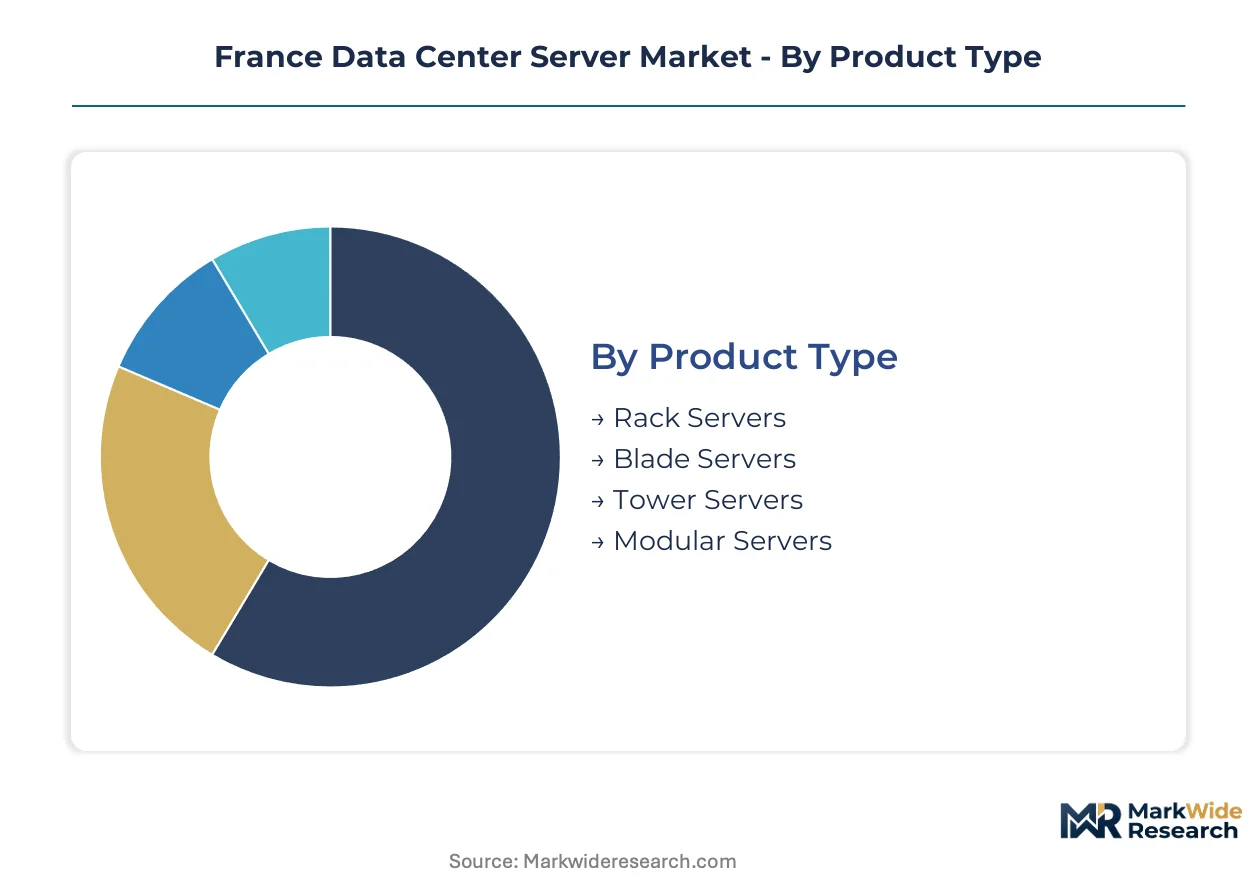
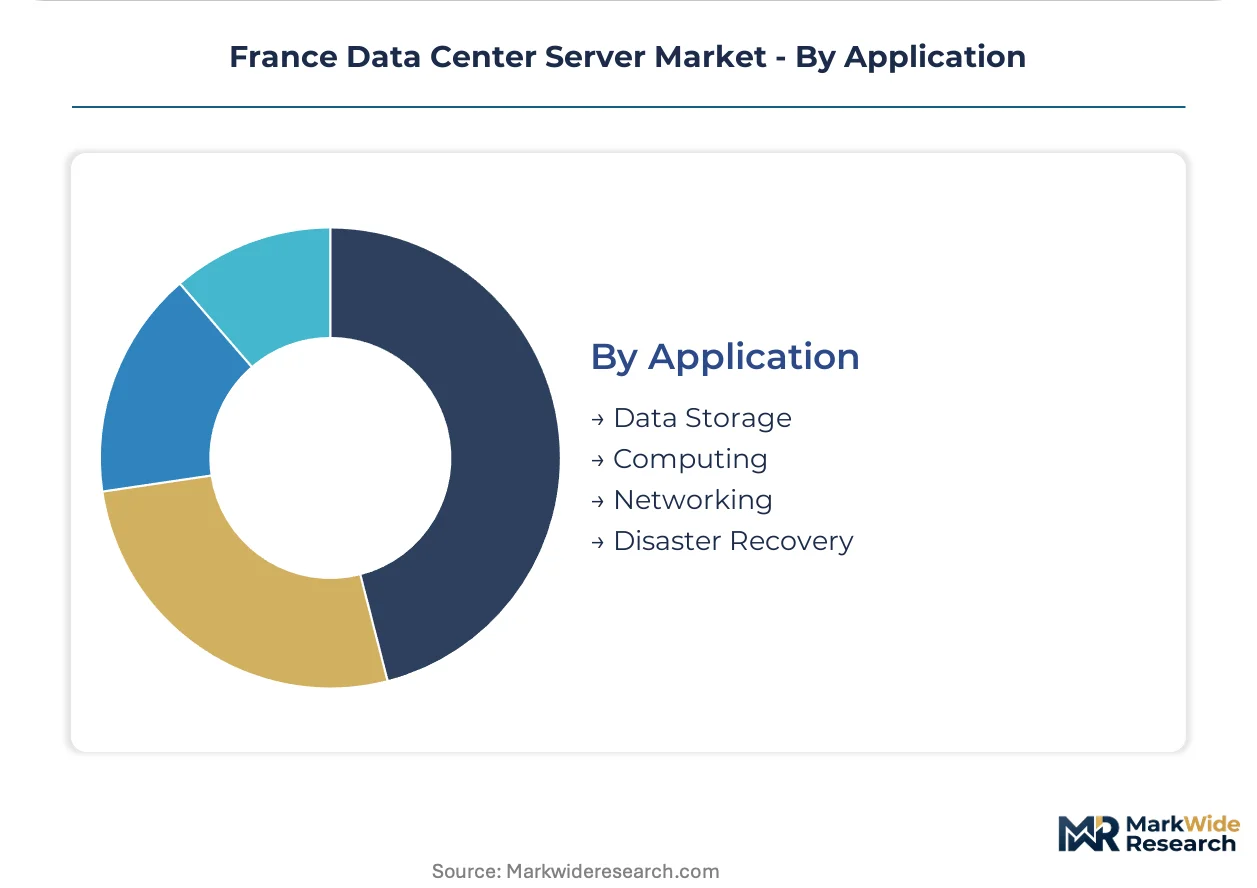
Server procurement patterns in France diverge sharply across customer scale, workload type, and compliance exposure. Understanding these fault lines clarifies where vendor investments in certification, cooling density, and service bundling will yield returns.
Product Type:
Cost tier determines procurement channel and margin structure for French server buyers.
- Rack Servers:Standardized 19-inch form factors dominate volume shipments into multi-tenant colocation facilities across the Paris-Saclay corridor. Financial services firms specify these for core banking workloads where density and hot-swappability outweigh customization needs.
- Blade Servers:Shared chassis architectures consolidate power and cooling infrastructure for high-density deployments. Managed service providers in Marseille's interconnection hubs favor blade configurations to maximize tenant revenue per square meter while meeting ANSSI physical sovereignty requirements.
- Tower Servers:Standalone vertical enclosures serve distributed branch offices and small-scale edge sites where rack infrastructure is unavailable.
- Modular Servers:Disaggregated compute, storage, and networking sleds allow workload-specific resource pooling for research institutions piloting quantum-classical hybrid architectures.
Rack servers command the established base. The steepest expansion runs through modular configurations.
End User:
Customer type dictates compliance burden and contract structure in the French market.
- Large Enterprises:CAC 40 banking and insurance groups procure through multi-year operational leases where vendors assume depreciation risk and guarantee uptime-plus-certification outcomes. These buyers specify SecNumCloud-qualified configurations for classified workloads.
- SMEs:Mid-market manufacturers and professional services firms purchase through domestic distributors with shorter replacement cycles and lighter ANSSI exposure.
- Public Sector:Central government and defense agencies mandate CSPN and SecNumCloud qualifications that extend sales cycles by 12-18 months.
- Managed Service Providers:Accredited domestic operators capture expanding margin pools by bundling hardware with operational management, compliance liability absorption, and circular hardware take-back programs.
Large enterprises command the established base. The steepest expansion runs through managed service providers.
Technology:
Deployment architecture determines physical footprint and thermal design power requirements.
- Virtualization:Hypervisor-based workload consolidation remains standard for legacy enterprise data centers seeking to extend existing x86 infrastructure lifecycles.
- Cloud Computing:Hyperscale-adjacent configurations are fragmenting as ANSSI sovereign cloud mandates disqualify standard global deployments for regulated healthcare and defense sectors.
- Edge Computing:Localized compute nodes for latency-sensitive applications are proliferating across automotive and aerospace manufacturing sites in the Paris-Saclay corridor for predictive maintenance and quality control.
- Hyperconvergence:Software-defined storage-compute-networking stacks simplify procurement for SMEs lacking specialized infrastructure teams.
Virtualization commands the established base. The steepest expansion runs through edge computing.
Application:
Workload purpose shapes server specification priorities and redundancy requirements.
- Data Storage:Capacity-optimized configurations with dense drive bays serve backup and archival workloads for French insurance groups subject to CNIL data retention mandates.
- Computing:CPU and GPU-intensive nodes support real-time transaction processing and fraud detection systems for banking institutions.
- Networking:Traffic management appliances with specialized NICs and DPU offload capabilities handle interconnection hub demands in Marseille.
- Disaster Recovery:Geographically distributed failover clusters meet regulatory continuity requirements for critical national infrastructure operators.
Computing workloads command the established base. The steepest expansion runs through disaster recovery configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANSSI certification requirements anchor procurement decisions across French metropolitan areas, with server deployment patterns diverging sharply between sovereign-cloud corridors and industrial edge zones.
Île-de-France
Paris-Saclay hosts the densest concentration of financial services compute infrastructure, with CAC 40 banks expanding real-time transaction processing capacity. CNIL data retention mandates shape storage procurement specifications for insurance groups headquartered in La Défense. Colocation operators in Saint-Denis and Aubervilliers retrofit legacy facilities with liquid cooling to accommodate GPU-intensive AI training clusters.
Provence-Alpes-Côte d'Azur
Marseille's submarine cable landing stations drive interconnection hub demand for traffic management appliances with DPU offload capabilities. Managed service providers capture margin pools by bundling hardware with SecNumCloud-qualified operational management. Edge facilities serving African and Middle Eastern traffic routes expand along the Aix-Marseille corridor.
Auvergne-Rhône-Alpes
Grenoble's semiconductor manufacturing heritage sustains short-lead-time server delivery for domestic enterprises. Automotive suppliers in Lyon deploy localized compute nodes for predictive maintenance on assembly lines. REACH substance restrictions constrain motherboard sourcing for chassis assembled in regional fabrication facilities.
Hauts-de-France
Nuclear baseload proximity attracts power-intensive high-density rack deployments near Lille and Douai. Hyperscale cloud commitments fragment traditional distributor relationships in this historically industrial corridor. Cold climate advantages reduce mechanical cooling loads for training workloads requiring sustained GPU utilization.
France Data Center Server Market Competitive Landscape
Integrated systems vendors and component specialists split the market between full-stack solution delivery and modular configuration flexibility. The vendor base concentrates around three strategic archetypes: multinational enterprises with European manufacturing footprints, Asia-Pacific scale fabricators competing on cost efficiency, and domestic operators leveraging sovereign cloud accreditation. Competitive positioning hinges on ANSSI certification timelines and backward integration into firmware layers.
Within the multinational tier, Dell Inc. and Hewlett Packard Enterprise anchor premium positioning through vertical control over management software stacks. Huawei Technologies occupies a distinct channel position, navigating restricted public-sector tender access through European partnership structures while maintaining supply continuity for commercial segments. These three exemplify how certification pathway investments and geographic manufacturing presence determine procurement eligibility under France's sovereign cloud framework.
| Leading Market Players |
|---|
| Dell Inc. |
| Hewlett Packard Enterprise |
| International Business Machines (IBM) Corporation |
| Cisco Systems Inc. |
| Kingston Technology Company Inc. |
| Huawei Technologies |
| Lenovo Group |
| Supermicro Computer |
| Inspur Group |
| Others |
Pricing and Supply Chain Analysis
Underutilized GPU foundry capacity in Taiwan is compressing lead-time premiums for French system integrators while simultaneously eroding pricing power for domestic distributors holding legacy air-cooled inventory. This capacity dynamic rewards buyers with flexible deployment timelines while punishing intermediaries unable to pivot toward liquid-cooled configurations.
Pricing Analysis
Paris-Saclay corridor pricing runs 15-20% above Marseille interconnection hubs due to density premiums and ANSSI certification overhead. Three-tier pricing structure across SecNumCloud-qualified, CE-marked standard, and uncertified economy levels dominates procurement frameworks. Cost compression in the economy tier is intensifying because hyperscale cloud commitments pull volume away from traditional channels. SMEs exhibit highest price sensitivity, while CAC 40 institutions prioritize uptime-plus-certification outcomes over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for French server assemblers sourcing motherboards and AI accelerators. Manufacturing concentrates in Taiwan, China, and South Korea for advanced semiconductors, with chassis fabrication anchored in regional European facilities. The supply chain draws from NVIDIA GPUs, DDR5 memory modules, and liquid cooling components as critical inputs. Single-source vulnerability around TSMC advanced node production creates qualification bottlenecks for SecNumCloud deployments. Distribution runs through accredited domestic operators for regulated sectors and direct distributor relationships for commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France data center server market represents a high-growth disruption as sovereign cloud mandates under ANSSI guidance fragment procurement channels and force architectural recertification across the installed base.
For Market Incumbents: Insulate core banking relationships by accelerating SecNumCloud qualification timelines and securing captive supply of liquid-cooled chassis from Grenoble-area fabrication partners. Threat from Huawei's European partnership structures demands backward integration into firmware layers to preserve margin pools in managed service contracts. For New Entrants and Emerging Players: Pursue Marseille edge facility opportunities serving African and Middle Eastern submarine cable traffic, where ANSSI physical sovereignty requirements remain less stringent than Paris-Saclay financial workloads. White-space exists in CSRD-compliant circular hardware take-back programs for mid-market manufacturers lacking internal sustainability accounting capabilities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed service providers bundling hardware with operational management and compliance liability absorption. Long-term viability favors accredited domestic operators with established CSPN qualification pathways over pure hardware distributors facing margin compression. Signal to watch: SecNumCloud accreditation backlog at ANSSI indicating demand inflection for qualified infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| SecNumCloud Qualification Acceleration | ANSSI accreditation unlocks public-sector and defense procurement channels previously restricted to domestic operators. |
| Liquid Cooling Infrastructure Retrofit | Dielectric fluid systems accommodate 100kW+ GPU racks in legacy Paris-region colocation facilities. |
| CSRD-Compliant Circular Hardware Program | Lifecycle carbon accounting and take-back services differentiate vendors under EU sustainability disclosure mandates. |
| Marseille Edge Facility Expansion | Submarine-connected compute nodes capture African and Middle Eastern traffic with lower latency than Paris-Saclay routing. |
| Firmware Layer Vertical Integration | In-house management software development preserves margin pools as hyperscale cloud commitments fragment distributor relationships. |
Research Methodology
A standing panel of data center operations directors, ANSSI certification consultants, financial services IT procurement leads, and colocation facility engineers provided ongoing calibration across primary interview rounds. Secondary validation drew from ANSSI SecNumCloud qualification registries, EU CSRD sustainability disclosure filings, hyperscaler capex disclosures, and French customs import records for server components. Bottom-up shipment estimates triangulated against top-down infrastructure investment tracking across the Paris-Saclay corridor and Marseille interconnection hubs.
Scenario-bracketing anchored the analytical framework across the projection horizon, modeling demand trajectories under varying ANSSI enforcement intensities and GPU supply availability assumptions. Segmentation dimensions included product type, end-user scale, deployment architecture, and application workload, with additional granularity around certification tier and cooling density. CAGRs were derived from slope-consistent growth rate analysis applied to validated base-year estimates, incorporating real-time financial workload expansion and edge computing proliferation as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in eurozone interest rate policy, electricity price volatility, or semiconductor trade restrictions would shift the trajectory. Forecasts reflect documented assumptions around regulatory enforcement timelines and supply chain normalization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Ireland Data Center Power Market
Data Center Infrastructure
Los Angeles Data Center Market
Data Center Infrastructure
Switzerland Data Center Power Market
Data Center Infrastructure
Green Data Center Market
Data Center Infrastructure
Data Center Construction Market
Data Center Infrastructure
Middle East Data Center Rack Market
Data Center Infrastructure
Middle East Data Center Physical Security Market
Data Center Infrastructure
Data Center As a Service Market
Data Center Infrastructure
Data Center Power Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Data Center Transformation Market
Data Center Infrastructure
Asia-Pacific Data Center Infrastructure Management Market
Data Center Infrastructure
Malaysia Data Center Storage Market
Data Center Infrastructure
Brazil Data Center Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
Europe Data Center Colocation Market