
 Malaysia Data Center Networking Market | 2026-2036
Malaysia Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Data Center Networking Market Insights
Financial services is recalibrating the buyer profile for Malaysia data center networking equipment as digital banking licenses multiply. Cisco Systems Inc. dominates enterprise routing with deep channel partnerships across Kuala Lumpur and Penang. Arista Networks differentiates through high-density switching platforms optimized for cloud-scale deployments in Cyberjaya. Huawei Technologies Co., Ltd. competes aggressively on price-performance metrics for government and telecom infrastructure tenders.
Data center networking encompasses the switching, routing, and security fabric interconnecting compute and storage resources within facilities operating at speeds from 10 Gbps to 800 Gbps per port, with latency budgets below 10 microseconds for high-frequency trading and AI workloads. Switches command the largest product category spend as spine-leaf architectures replace three-tier designs in new builds. Cloud-based deployment models are expanding fastest among telcos and IT service providers seeking operational flexibility without capital intensity. Managed services capture expanding margin pools as enterprises outsource network operations to specialists with certified engineering benches.
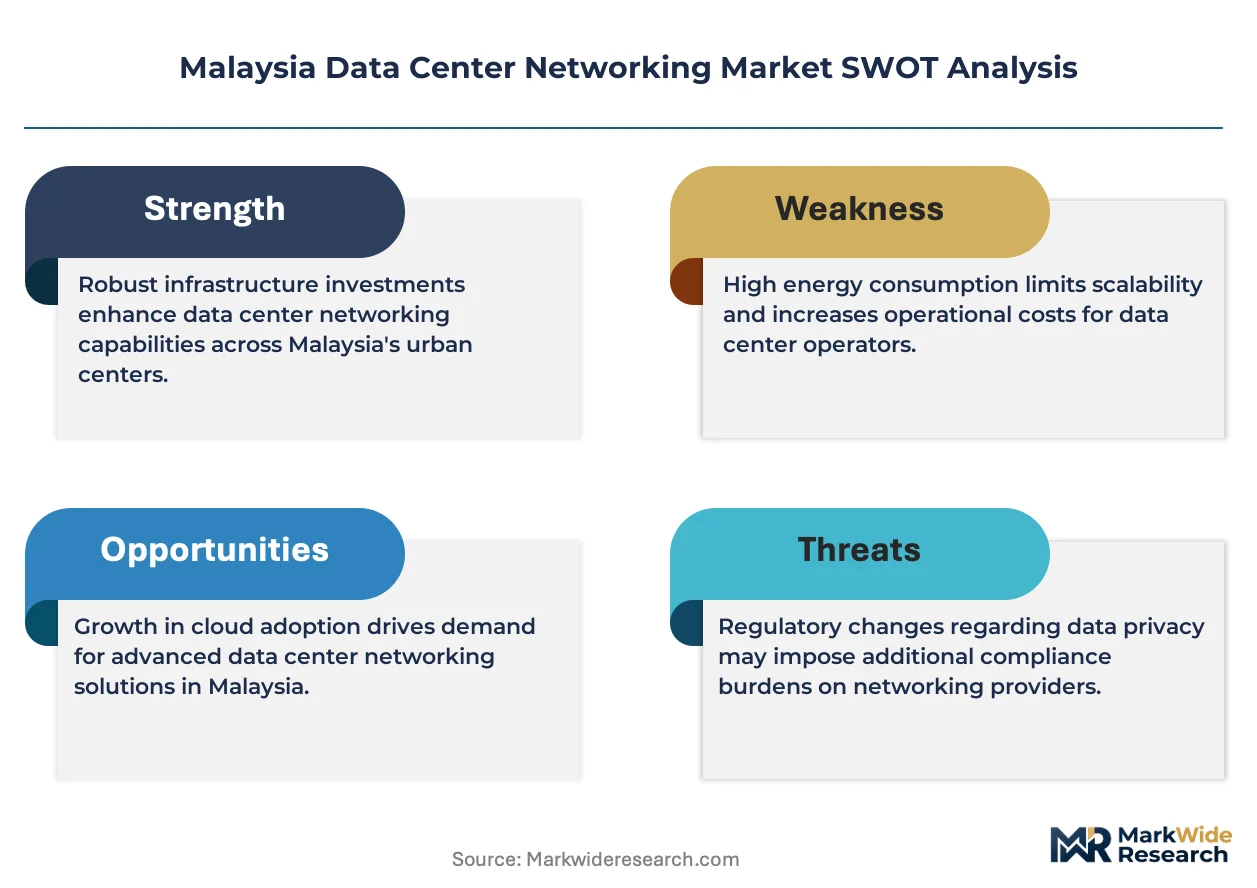
Malaysia's Personal Data Protection Act enforcement by the Personal Data Protection Commissioner mandates encrypted transit and access logging, pushing upgrades to next-generation firewalls. BIS-equivalent equipment certification through the country's communications regulator ensures interoperability standards for imported networking hardware. Stakeholders must weigh sovereign data requirements against cloud economics when selecting hybrid versus on-premises routing architectures.
Market Dynamics
Spine-leaf architecture migration is compressing hardware refresh cycles across Penang and Cyberjaya facilities as AI training clusters demand sub-10-microsecond latency fabrics. This topological shift is forcing wholesale replacement of legacy three-tier switching stacks rather than incremental upgrades.
Growth Catalysts
- Cloud First Policy:Malaysia's federal mandate for public-sector cloud adoption is driving sovereign data center construction in Putrajaya and Cyberjaya. Government tenders now specify domestic network termination points.
- Digital Banking Licenses:Bank Negara Malaysia's issuance of virtual banking permits is expanding financial services demand for encrypted low-latency interconnects in the Klang Valley.
- AI Inference Clusters:Deployment of GPU-based training infrastructure at 800 Gbps port speeds is accelerating spine-leaf fabric upgrades in hyperscale colocation facilities.
Market Restraints
- Import Certification Delays:BIS-equivalent equipment approval through the Malaysian Communications and Multimedia Commission extends hardware deployment timelines by 4-8 months for non-pre-certified vendors.
- Specialized Engineering Talent Scarcity:Certified network architects with 800 Gbps design experience command premium wages, constraining facility expansion speed in Iskandar Puteri.
- Power Infrastructure Bottlenecks:Grid interconnection queues for 100+ MW facilities in Greater Kuala Lumpur exceed 18 months, capping near-term supply growth.
Strategic Opportunities
- Johor Corridor Expansion:Iskandar Puteri's proximity to Singapore's saturated market positions Malaysia for spillover hyperscale demand from Chinese and American cloud operators.
- Managed Security Services:Personal Data Protection Act compliance complexity is opening recurring revenue streams for network operations outsourcing to certified local engineering benches.
- Submarine Cable Landings:New cable systems terminating in Tanjung Pandan and Mersing create edge interconnection nodes requiring distributed switching infrastructure.
Industry Challenges
- Legacy IPv4 Address Exhaustion:Enterprise facilities in Penang struggle with dual-stack IPv6 migration, complicating hybrid cloud routing architectures.
- Cross-Border Data Flow Friction:PDPA restrictions on personal data transfer outside Malaysia complicate multi-region network designs for e-commerce platforms with Singapore headquarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Data Center Networking Market |
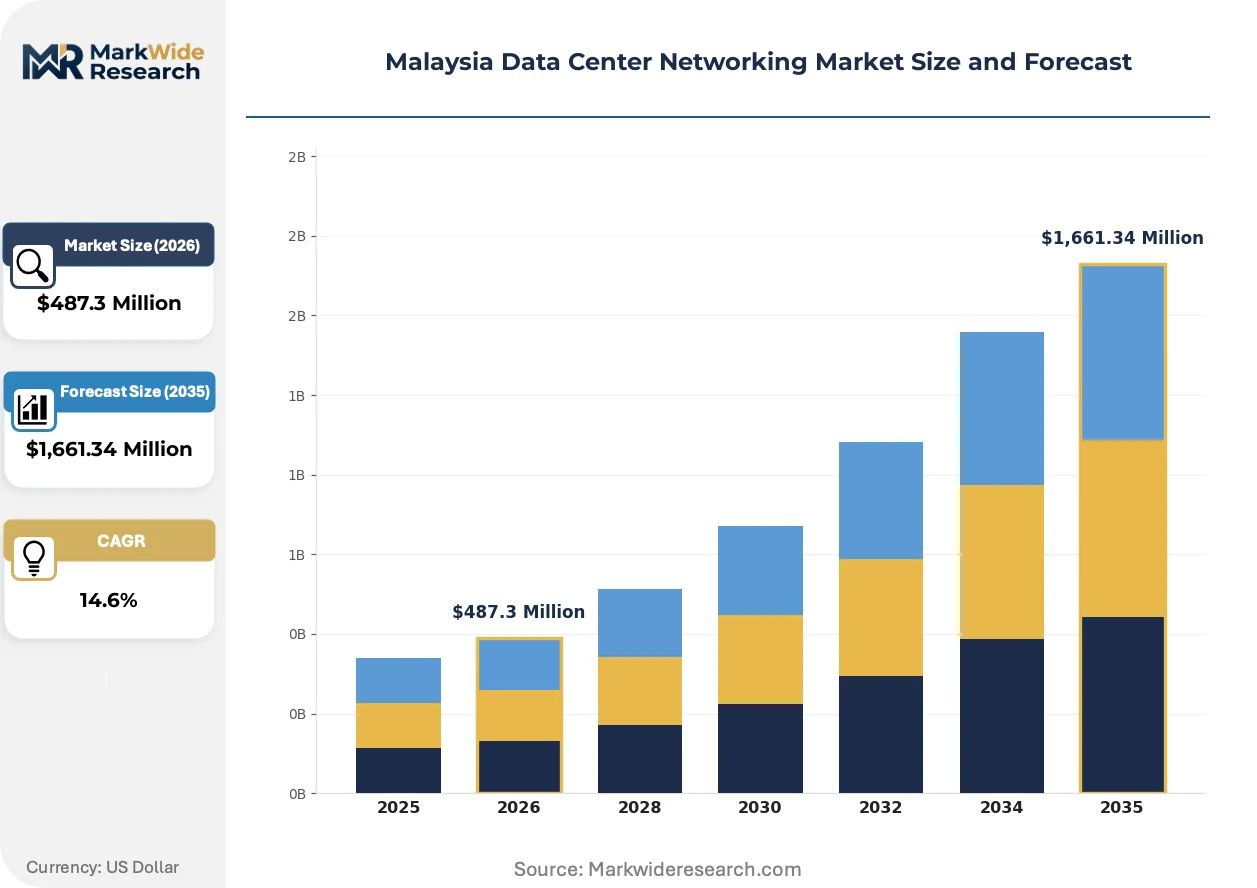
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Firewalls, Load Balancers Service Type: Consulting, Managed Services, Maintenance, Installation Deployment Model: On-Premises, Cloud-Based, Hybrid, Colocation End User: Enterprises, Telecommunication Providers, IT Service Providers, Government Agencies |
| Companies Covered | Cisco Systems Inc., Arista Networks Inc., H3C Technologies Co., Ltd., VMware Inc., Huawei Technologies Co., Ltd., Juniper Networks, Extreme Networks, Nokia Corporation, Broadcom Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Data Center Networking Market Trends and Innovations
Software-defined networking controllers are displacing hardware-centric management planes across Malaysian facilities. This control-layer shift is collapsing operational complexity while enabling real-time traffic engineering for latency-sensitive workloads.
Intent-based networking is unifying policy enforcement across multi-vendor switching fabrics in Cyberjaya hyperscale deployments. Financial services operators are adopting these platforms fastest to automate compliance verification under PDPA audit requirements. The technology is compressing provisioning intervals from weeks to hours while reducing misconfiguration incidents that previously triggered regulatory scrutiny.
Malaysia's Personal Data Protection Commissioner is intensifying enforcement of encrypted transit mandates for cross-facility replication. Network operators must now deploy MACsec or equivalent link-layer encryption on all inter-data center circuits. Financial services and healthcare verticals in Kuala Lumpur are responding by prioritizing switches with hardware-accelerated encryption over performance-optimized alternatives.
Consumption-based networking procurement is displacing traditional capital purchase models among mid-market enterprises in Penang and Johor. Managed service providers are capturing this shift through subscription offerings bundling hardware, software, and operational support. Telcos with certified engineering benches are winning these contracts fastest, leveraging existing fiber infrastructure to deliver integrated network-as-a-service packages.
Malaysia Data Center Networking Market Segmentation
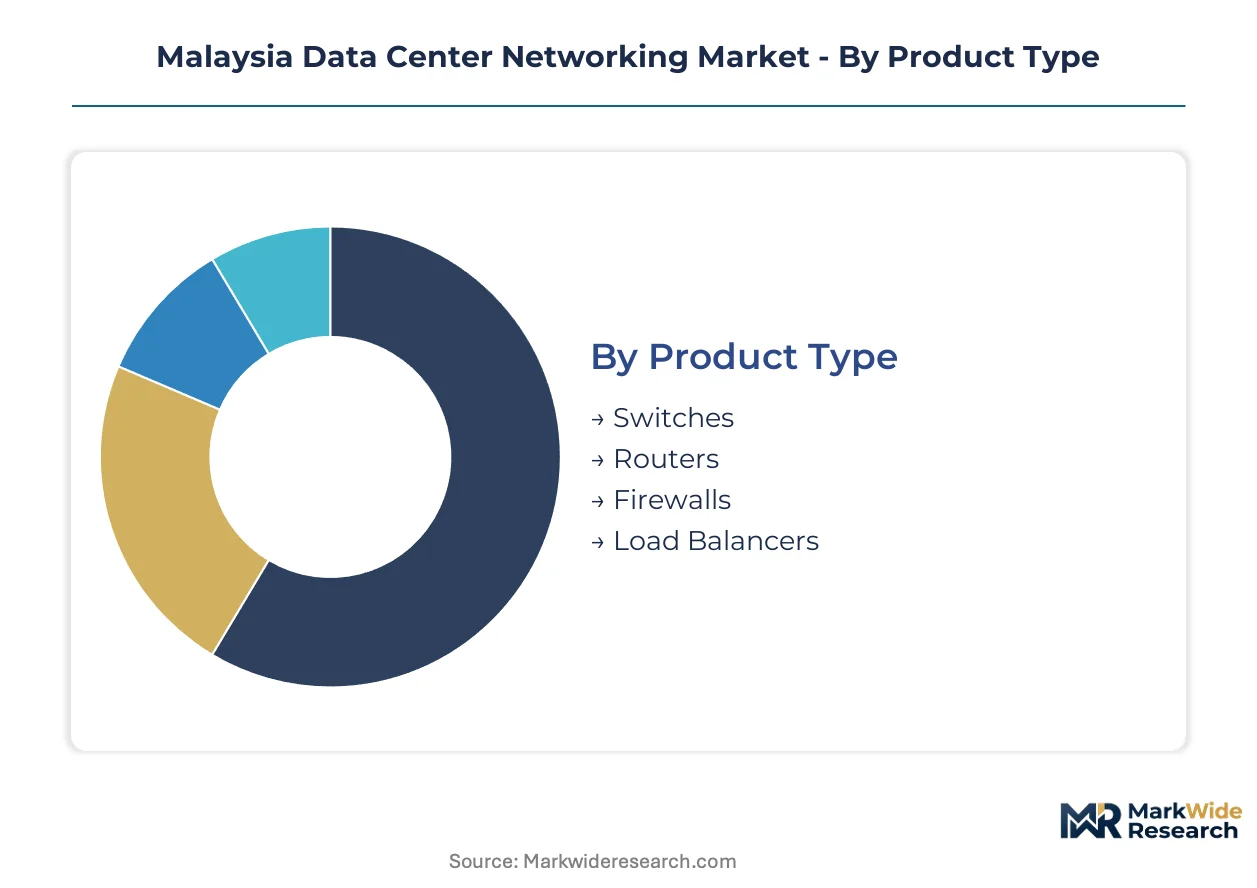
Malaysia data center networking procurement patterns diverge sharply by capital structure and operational control. Facility operators weigh upfront hardware expenditure against recurring service commitments when architecting network fabrics for AI training clusters and financial services workloads.
Product Type:
Capital intensity peaks with switching platforms requiring 800 Gbps port density and sub-10-microsecond latency specifications.
- Switches:Spine-leaf architectures demand high-density switching fabrics with 400-800 Gbps port speeds. Financial services operators in the Klang Valley prioritize these for low-latency digital banking infrastructure. This segment absorbs the bulk of installed capacity; Routers is expanding most quickly.
- Routers:Border gateway and core routing platforms handle inter-facility traffic across Cyberjaya and Iskandar Puteri. Government Cloud First mandates specify domestic termination points, concentrating demand in sovereign data center builds.
- Firewalls:Next-generation platforms with hardware-accelerated encryption satisfy PDPA transit mandates for cross-facility replication.
- Load Balancers:Application delivery controllers distribute traffic across distributed compute nodes in hyperscale colocation environments.
Switches command the largest procurement volumes; Firewalls is gaining share fastest under intensified encryption enforcement.
Service Type:
Revenue predictability varies by contract structure, with multi-year managed services agreements offering the steadiest cash flow profiles.
- Managed Services:Network operations outsourcing captures expanding margin pools as enterprises seek certified engineering benches without captive hiring. Telcos with fiber infrastructure dominate these contracts in Penang and Johor.
- Consulting:Architecture design and compliance advisory services address PDPA audit preparation and spine-leaf migration planning for legacy three-tier facilities.
- Maintenance:Hardware refresh and firmware update contracts ensure continued BIS-equivalent certification for imported equipment.
- Installation:Physical deployment and commissioning services face bottlenecks from 800 Gbps-certified engineer scarcity in Iskandar Puteri.
Managed Services locks in the longest revenue visibility; Consulting is climbing the fastest as compliance complexity deepens.
Deployment Model:
Control over physical infrastructure determines latency budgets and data sovereignty posture for regulated workloads.
- Colocation:Hyperscale facilities in Cyberjaya and the Klang Valley offer pre-built network fabrics with cross-connect ecosystems. Chinese and American cloud operators drive expansion here.
- On-Premises:Captive data centers persist among financial institutions with strict PDPA custody requirements and sub-10-microsecond latency needs.
- Cloud-Based:Telcos and IT service providers favor this model for operational flexibility without capital intensity.
- Hybrid:Split architectures complicate routing design where PDPA restricts personal data transfer outside Malaysia.
Colocation holds the largest footprint; Cloud-Based is scaling fastest among mid-market enterprises shedding capital expenditure.
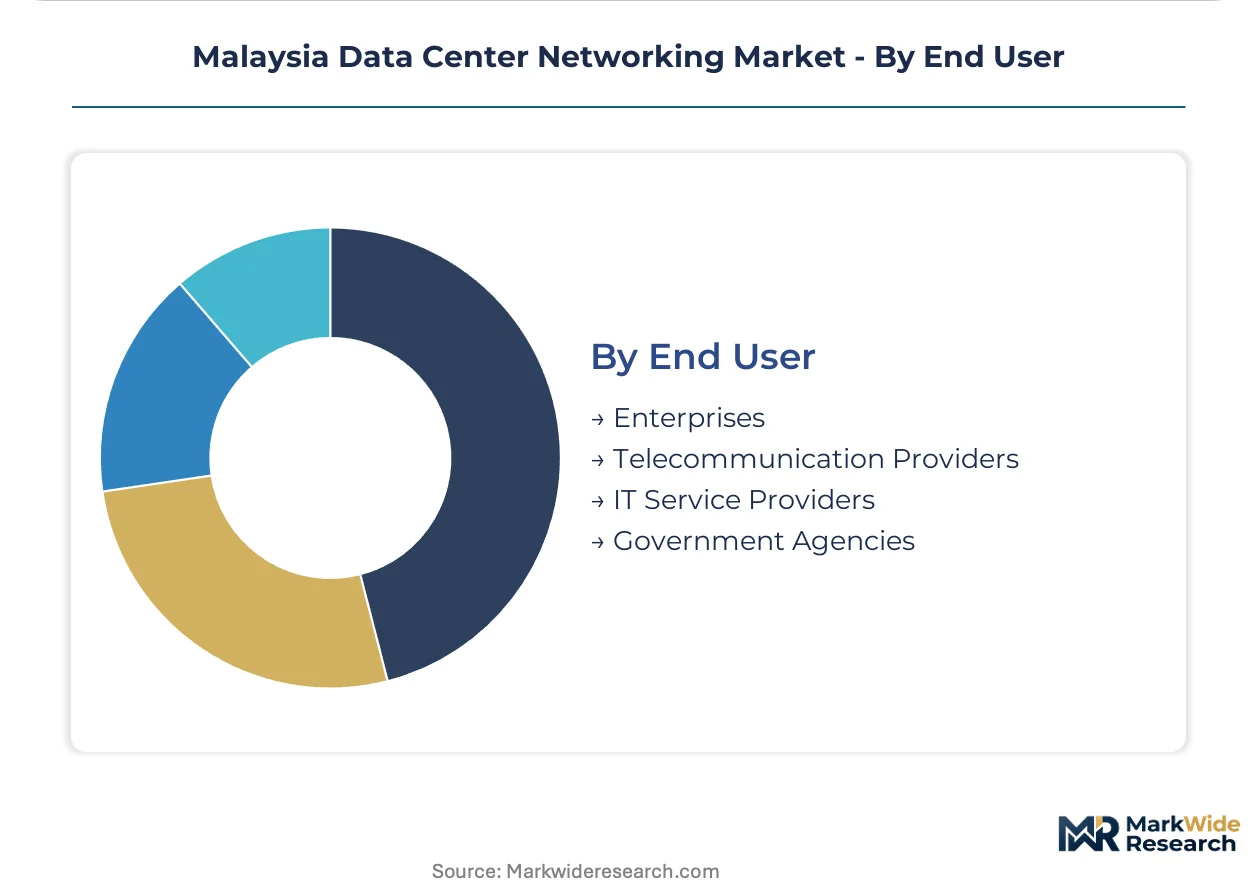
End User:
Procurement sophistication correlates with regulatory exposure and workload latency sensitivity.
- Enterprises:Financial services and e-commerce platforms in Greater Kuala Lumpur drive encrypted low-latency interconnect demand. Digital banking license holders specify sub-10-microsecond fabrics.
- Telecommunication Providers:Carriers with submarine cable landings in Tanjung Pandan and Mersing require distributed switching infrastructure for edge interconnection nodes.
- IT Service Providers:Channel partners aggregate mid-market demand through consumption-based networking procurement models.
- Government Agencies:Cloud First policy compliance mandates sovereign data center construction in Putrajaya with domestic network termination requirements.
Enterprises deploy the most port capacity; Government Agencies is expanding fastest under federal cloud migration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's Multimedia Super Corridor tax incentives and MSC status designation have concentrated data center investment across the Klang Valley and Cyberjaya, creating specialized infrastructure zones that anchor regional networking demand.
Greater Kuala Lumpur
Financial services operators and digital banking licensees drive encrypted low-latency interconnect procurement across the Klang Valley corridor. Bank Negara Malaysia's regulatory sandbox framework mandates domestic data residency for virtual banks. Hyperscale colocation facilities in Cyberjaya and Petaling Jaya absorb the majority of spine-leaf switching deployments.
Iskandar Puteri
Chinese and American cloud operators are expanding footprint to capture spillover demand from Singapore's capacity-constrained market. The Johor state investment promotion agency offers pioneer status incentives for data center construction exceeding 100 MW capacity. Specialized engineering talent scarcity constrains deployment speed despite land and power availability.
Penang
Semiconductor and electronics manufacturing clusters generate captive demand for edge networking infrastructure. The state's industrial zone status under Malaysia's national investment promotion framework attracts captive data center builds. Telcos with fiber infrastructure dominate managed services contracts for mid-market enterprises shedding capital expenditure.
Putrajaya
Federal Cloud First policy mandates concentrate sovereign data center construction in the administrative capital. Government tenders specify domestic network termination points and BIS-equivalent equipment certification through the Malaysian Communications and Multimedia Commission. Civil service digitization programs drive router and firewall procurement for secure inter-agency connectivity.
East Coast Corridor
Submarine cable landings at Tanjung Pandan and Mersing create distributed edge interconnection nodes requiring switching infrastructure. The national digital infrastructure plan designates these landing points as priority zones for international bandwidth expansion. Telecommunication providers with cable consortium memberships are deploying distributed switching for latency-optimized traffic routing.
Malaysia Data Center Networking Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise routing consolidating around established channel networks while cloud-scale switching remains more contested. The vendor landscape organizes into three tiers: global networking incumbents with full-stack portfolios, cloud-native specialists with software-optimized hardware, and price-competitive challengers targeting government and telecom tenders. Competitive intensity manifests through channel partnership expansion, certified engineering bench investments, and consumption-based procurement model development.
Within the global incumbent tier, Cisco Systems Inc. and Arista Networks Inc. occupy differentiated positions—Cisco anchoring enterprise routing through established Kuala Lumpur and Penang channel partnerships, Arista representing cloud-scale switching specialization optimized for Cyberjaya hyperscale deployments. Huawei Technologies Co., Ltd. sits within the price-competitive challenger archetype, competing aggressively on price-performance metrics for government and telecom infrastructure tenders subject to BIS-equivalent certification requirements.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Arista Networks Inc. |
| H3C Technologies Co., Ltd. |
| VMware Inc. |
| Huawei Technologies Co., Ltd. |
| Juniper Networks |
| Extreme Networks |
| Nokia Corporation |
| Broadcom Inc. |
| Others |
Pricing and Supply Chain Analysis
Certified 800 Gbps network architects concentrated in Cyberjaya and Penang drive pricing-tier spreads across Malaysia's data center networking market, with labor-cost differentials between Klang Valley specialists and Johor-based engineers widening premium-mid-economy pricing differentiation by fifteen to twenty percent.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement, with premiums commanding spot inventory for sub-90-day deployment against discounts for standard 6-month lead-time orders. Three-tier pricing structure across premium, standard, and economy levels reflects BIS-equivalent certification grade and after-sales service bundling. Cost compression in economy-tier switching runs through aggressive Huawei competition for government tenders. Mid-market enterprises in Penang exhibit highest price sensitivity; financial services operators in Kuala Lumpur prioritize encryption performance over unit cost.
Supply Chain Analysis
Workforce availability constraints in Taiwan, China, and South Korea anchor switch silicon fabrication capacity, with 800 Gbps ASIC foundry slots booked twelve to eighteen months forward. Supply draws from advanced packaging substrates in Japan, passive optical components in China, and precision connectors in Germany. Single-source vulnerability concentrates in TSMC's 7nm and 5nm networking chip production. Distribution runs through authorized distributors in Kuala Lumpur with direct fulfillment from Singapore regional hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's data center networking market represents a consolidation play as BIS-equivalent certification barriers and specialized engineering bench requirements force sub-scale systems integrators toward exit.
For Market Incumbents: To counter Arista's cloud-scale switching encroachment in Cyberjaya hyperscale facilities, Cisco must deepen channel control through certified engineering bench investments in Penang and Johor while accelerating hardware-accelerated encryption R&D to satisfy PDPA audit requirements. For New Entrants and Emerging Players: Capture managed services white space among mid-market enterprises in Iskandar Puteri shedding capital expenditure, with consumption-based network-as-a-service offerings bundling fiber infrastructure from telco partnerships. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated managed service providers given Cloud First policy acceleration, with long-term viability hinging on sovereign data center construction momentum; watch government tender award velocity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Engineering Bench Expansion | Captures margin pools in PDPA compliance outsourcing to telcos with fiber infrastructure. |
| Hardware-Accelerated Encryption Development | Satisfies MACsec mandates from Malaysia's Personal Data Protection Commissioner for financial services. |
| Johor Corridor Presence Establishment | Positions for spillover hyperscale demand from Singapore's capacity-constrained market. |
| Managed Security Services Launch | Opens recurring revenue streams through subscription network operations for mid-market enterprises. |
| Submarine Cable Landing Partnership | Secures distributed switching contracts at Tanjung Pandan and Mersing edge interconnection nodes. |
Research Methodology
Multi-period observation of hyperscaler capex disclosures, government tender awards, and BIS-equivalent certification timelines anchored the trend analysis, supplemented by interviews with data center facility operators, network engineering directors, channel distribution managers, and procurement leads at financial services institutions. Secondary validation drew from Malaysian Communications and Multimedia Commission regulatory filings, MCMC equipment certification databases, Bank Negara Malaysia digital banking license records, and submarine cable consortium announcements. Bottom-up port shipment aggregation and top-down infrastructure investment tracking provided triangulation.
Input-output matrices modeled switch, router, and firewall procurement flows across deployment models and end-user verticals throughout the forecast period. Segmentation dimensions included product type, service type, deployment model, and end-user category with regional production cluster overlays. CAGRs derived from facility pipeline tracking, power interconnection queue analysis, and AI training cluster deployment announcements across the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to grid interconnection clearance timelines and 800 Gbps engineering talent pipeline development. Material deviation in government Cloud First budget allocation or Personal Data Protection Commissioner enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
UAE Data Center Server Market
Data Center Infrastructure
Global Micro Mobile Data Center Market
Data Center Infrastructure
Norway Data Center Rack Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
North America Green Data Center Market
Data Center Infrastructure
Israel Data Center Rack Market
Data Center Infrastructure
UAE Data Center Construction Market
Data Center Infrastructure
Global Telecommunication Equipment Cabinet and Racks Market
Data Center Infrastructure
Hong Kong Data Center Rack Market
Data Center Infrastructure
Thailand Data Center Rack Market
Data Center Infrastructure
Mini Data Center Market
Data Center Infrastructure
Micro Data Center Market
Data Center Infrastructure
Retail Colocation Market
Data Center Infrastructure
Data Terminal Market
Data Center Infrastructure
Belgium Data Center Power Market
Data Center Infrastructure
Data Center Transfer Switches and Switchgears Market