
 Green Data Center Market | 2026-2036
Green Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Green Data Center Market Analysis
European hyperscale construction is restructuring supply timelines for sustainable data hall components. Schneider Electric dominates industrial power and cooling systems for these projects. Microsoft leverages long-term renewable power purchase agreements to sustain carbon-negative operations across its Nordic and Dutch facilities. Google anchors its competitive position through proprietary liquid cooling patents and direct seawater cooling deployments in Finland and Belgium.
A green data center denotes a facility engineered to minimize environmental impact through energy-efficient infrastructure, renewable power sourcing, and advanced thermal management, typically targeting power usage effectiveness ratios below 1.2 through liquid cooling, free air cooling, or heat recovery systems. Its primary commercial purpose is to deliver compute, storage, and network services at reduced carbon intensity for cloud providers, enterprises, and government clients bound by emissions disclosures. Liquid cooling represents the fastest-expanding technology segment as GPU-density racks exceed air-cooling thresholds in AI training facilities. Managed services capture widening margin pools as operators outsource certification compliance, carbon accounting, and continuous efficiency tuning rather than building in-house capabilities. Colocation deployment maintains structural leadership in Europe and Asia where real estate scarcity and permitting complexity favor multi-tenant models over greenfield enterprise builds.
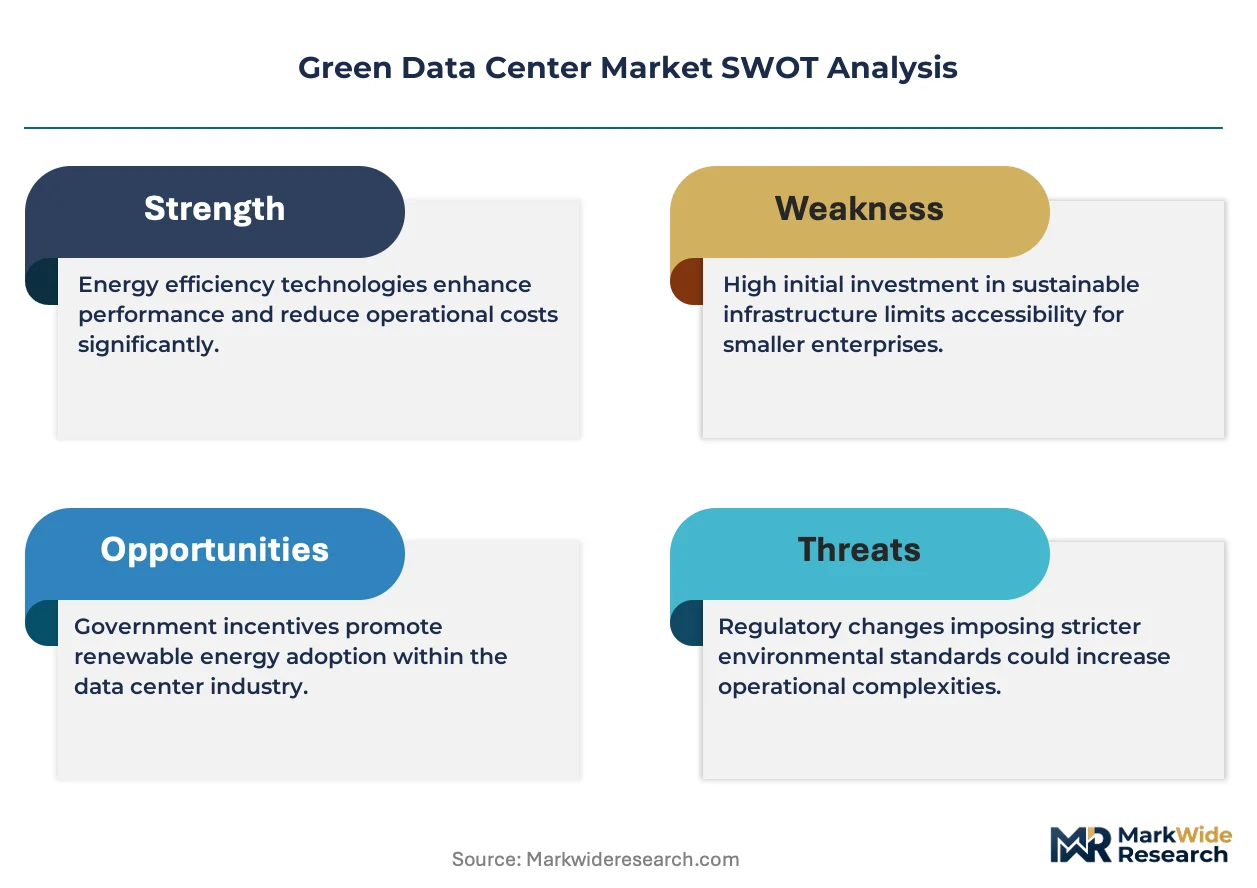
The EPA's ENERGY STAR certification and the EU Energy Efficiency Directive shape facility design standards and disclosure obligations across the two largest demand regions. ISO 50001 energy management standards and the EU Green Deal taxonomy define eligible green investments and access to sustainable finance instruments for facility developers. Stakeholders must monitor evolving carbon border adjustments and locality-specific renewable energy certificate regimes to secure long-term operational compliance and cost predictability.
Market Dynamics
Liquid cooling infrastructure is compressing facility design cycles as GPU rack densities breach legacy thermal thresholds, forcing operators to choose between air-cooling retrofits and complete rebuilds.
Growth Catalysts
- EU Energy Efficiency Directive:Mandatory disclosure of power usage effectiveness ratios drives certified green builds across German, Dutch, and Nordic facilities.
- Hyperscale cloud expansion:Microsoft and Google sustain carbon-negative commitments through long-term renewable power purchase agreements in Finland and Belgium.
- Heat recovery systems:District heating integration in Frankfurt and Amsterdam clusters converts waste thermal output into municipal revenue streams.
Market Restraints
- Copper and rare-earth magnet volatility:Liquid cooling manifolds and high-efficiency motor assemblies face input cost swings from concentrated Chinese refining.
- Permitting density caps:Frankfurt's cluster concentration triggers municipal moratoriums on new grid connections.
- Air-cooling residual demand:Enterprise colocation tenants with mixed-density workloads delay full liquid conversion.
Strategic Opportunities
- ISO 50001 certification services:Managed compliance providers capture margin pools as operators outsource continuous efficiency tuning.
- Direct seawater cooling:Finnish and Belgian coastal deployments eliminate chiller energy draw entirely.
- Carbon accounting software:Real-time emissions tracking tools penetrate underpenetrated mid-tier colocation portfolios.
Industry Challenges
- Thermal-fluid engineering scarcity:Specialized technicians for dielectric coolant maintenance command premium wages across Nordic construction sites.
- Legacy facility retrofit complexity:Raised-floor air-cooling infrastructure requires complete demolition for immersion tank installation.
- Renewable certificate verification:Cross-border guarantee of origin tracking demands redundant auditing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Data Center Market |
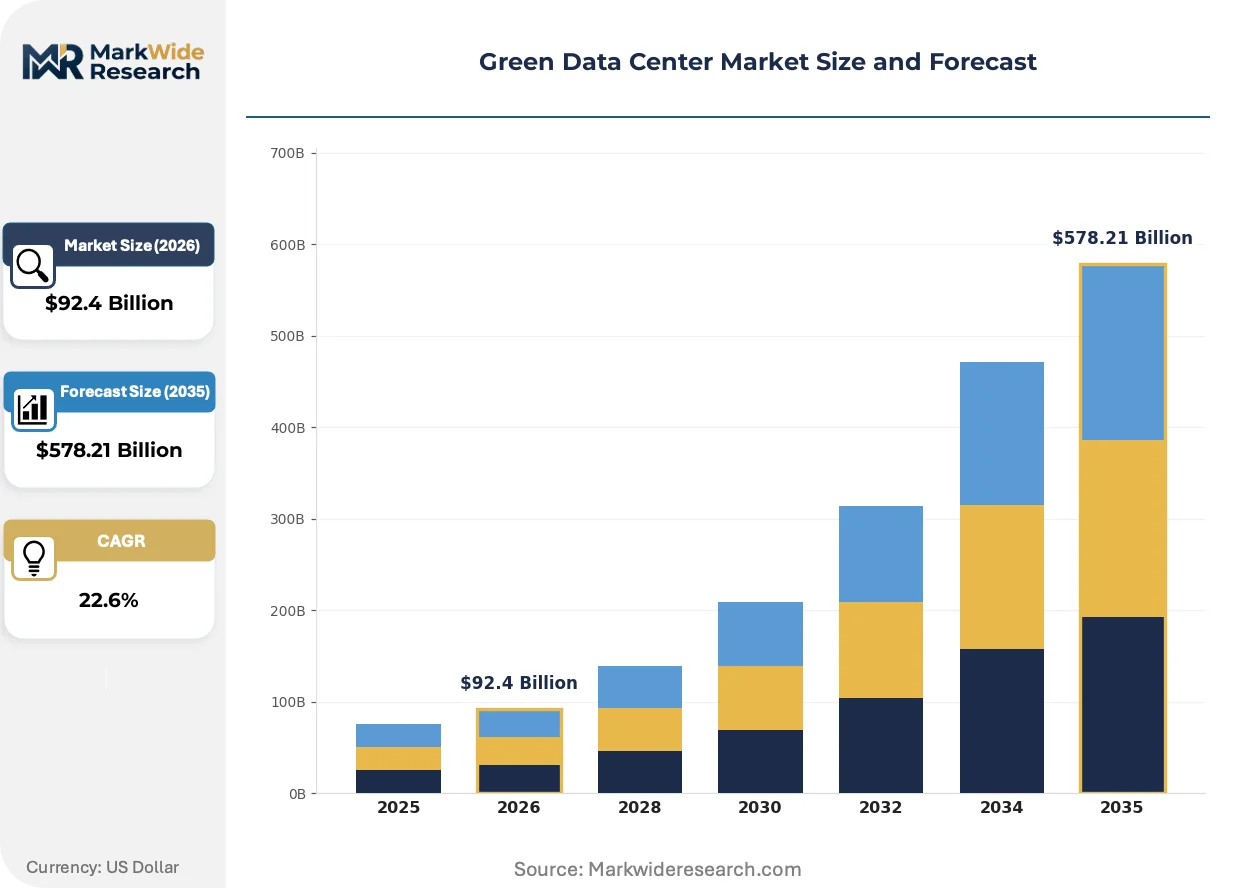
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $578.21 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Virtualization, Energy Efficient Hardware, Renewable Energy Integration, Liquid Cooling Service Type: Consulting, Managed Services, Design Services, Maintenance Services End User: IT Service Providers, Telecom Companies, Government Agencies, Educational Institutions Deployment: On-Premises, Colocation, Hybrid Cloud, Dedicated Hosting |
| Companies Covered | QTS Realty Trust, Microsoft, Equinix, Google, Amazon Web Services, Digital Realty, Compass Datacenters, Schneider Electric, Vantage Data Centers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Data Center Market Emerging Trajectories
Facility architecture is bifurcating between air-cooled legacy retrofits and purpose-built liquid-cooled halls, with thermal management patents becoming the primary competitive moat.
Direct-to-chip liquid cooling is absorbing thermal loads from NVIDIA H100 and Blackwell GPU clusters exceeding 100kW per rack. Hyperscale operators in Finland and the Netherlands deploy this technology at scale. The shift is absorbing capital budgets previously allocated to mechanical refrigeration expansion.
The EPA's ENERGY STAR certification tightens operational disclosure thresholds for US-based facilities above 500kW capacity. Operators must submit verified power usage effectiveness data annually. Colocation providers in Virginia and Texas accelerate third-party auditing to maintain tenant eligibility.
Consumption-based billing models replace flat-rate power contracts in European multi-tenant facilities. Tenants pay per actual kWh drawn rather than provisioned capacity. This pattern concentrates in German and Dutch markets where carbon intensity pricing varies hourly.
Green Data Center Market Segmentation
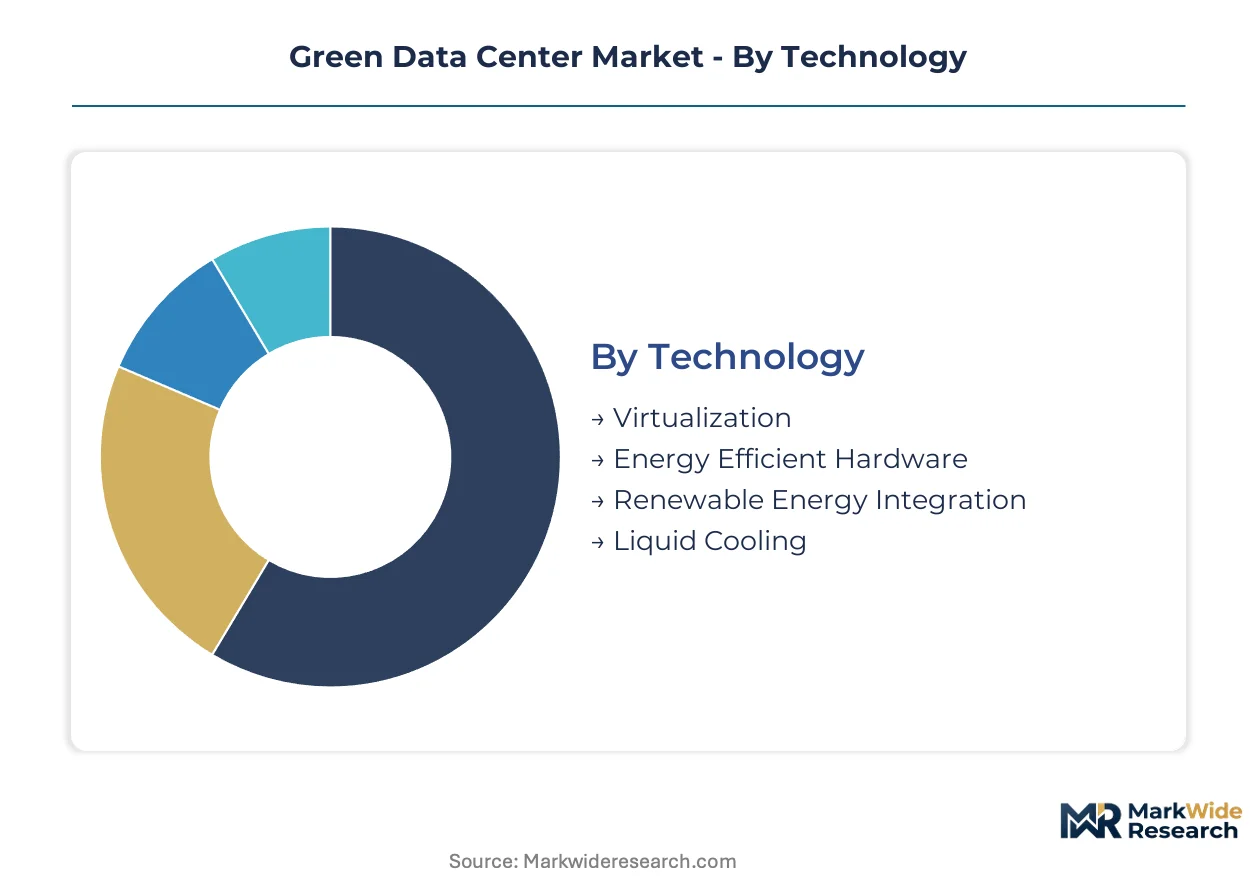
Segmentation in green data centers reveals how infrastructure choices cascade into operational economics and compliance posture. Buyers sort across technology readiness, capital intensity, and regulatory exposure rather than uniform efficiency metrics.
Technology:
Buyers differentiate by thermal density tolerance and retrofit feasibility versus new-build economics.
- Liquid Cooling:Direct-to-chip and immersion systems handle GPU racks exceeding 100kW through dielectric fluids or water-glycol loops. Finnish and Belgian coastal facilities deploy this at scale for AI training clusters where air-cooling fails. Heat recovery integration in Frankfurt and Amsterdam converts waste output into district heating revenue.
- Renewable Energy Integration:Long-term power purchase agreements and on-site solar or wind coupled with battery storage anchor carbon-negative operations. Microsoft and Google sustain Nordic and Dutch facilities through this approach, with hourly carbon intensity pricing in German and Dutch markets driving procurement sophistication.
- Virtualization:Software-defined resource pooling compresses server counts and idle power draw across enterprise fleets.
- Energy Efficient Hardware:Low-power processors and solid-state storage reduce baseline consumption in legacy air-cooled halls.
Volume sits with Energy Efficient Hardware retrofits; growth tilts toward Liquid Cooling as rack densities breach thermal thresholds.
Service Type:
Procurement patterns split between one-time capital projects and recurring operational partnerships.
- Managed Services:Continuous efficiency tuning, ISO 50001 compliance maintenance, and real-time carbon accounting outsourced to specialized providers. German and Dutch operators favor this model as EU Energy Efficiency Directive disclosure obligations intensify.
- Consulting:Front-end feasibility studies for certification pathways and renewable energy procurement strategy. Demand concentrates in Virginia and Texas where EPA ENERGY STAR thresholds tighten for facilities above 500kW.
- Design Services:Architectural and engineering specification for liquid-cooled or free-air cooling builds.
- Maintenance Services:Scheduled and predictive upkeep for cooling infrastructure and power distribution.
Revenue pools deepest in Managed Services; margin expansion is steepest in Consulting as certification complexity rises.
End User:
Risk tolerance and capital access separate hyperscale self-builders from multi-tenant dependent organizations.
- IT Service Providers:Cloud and managed hosting operators with mixed-density workloads spanning legacy air-cooled and new liquid-cooled infrastructure. These buyers prioritize colocation flexibility in Frankfurt and Amsterdam where permitting caps constrain greenfield expansion.
- Telecom Companies:Edge and core network facilities with 24/7 uptime requirements and distributed footprints. Nordic operators leverage direct seawater cooling for submarine cable landing stations.
- Government Agencies:Public sector facilities bound by procurement mandates for ENERGY STAR or ISO 50001 certification.
- Educational Institutions:Research computing centers with episodic GPU-intensive workloads and limited operational staff.
Contract value concentrates with IT Service Providers; fastest uptake is occurring among Government Agencies as disclosure mandates harden.
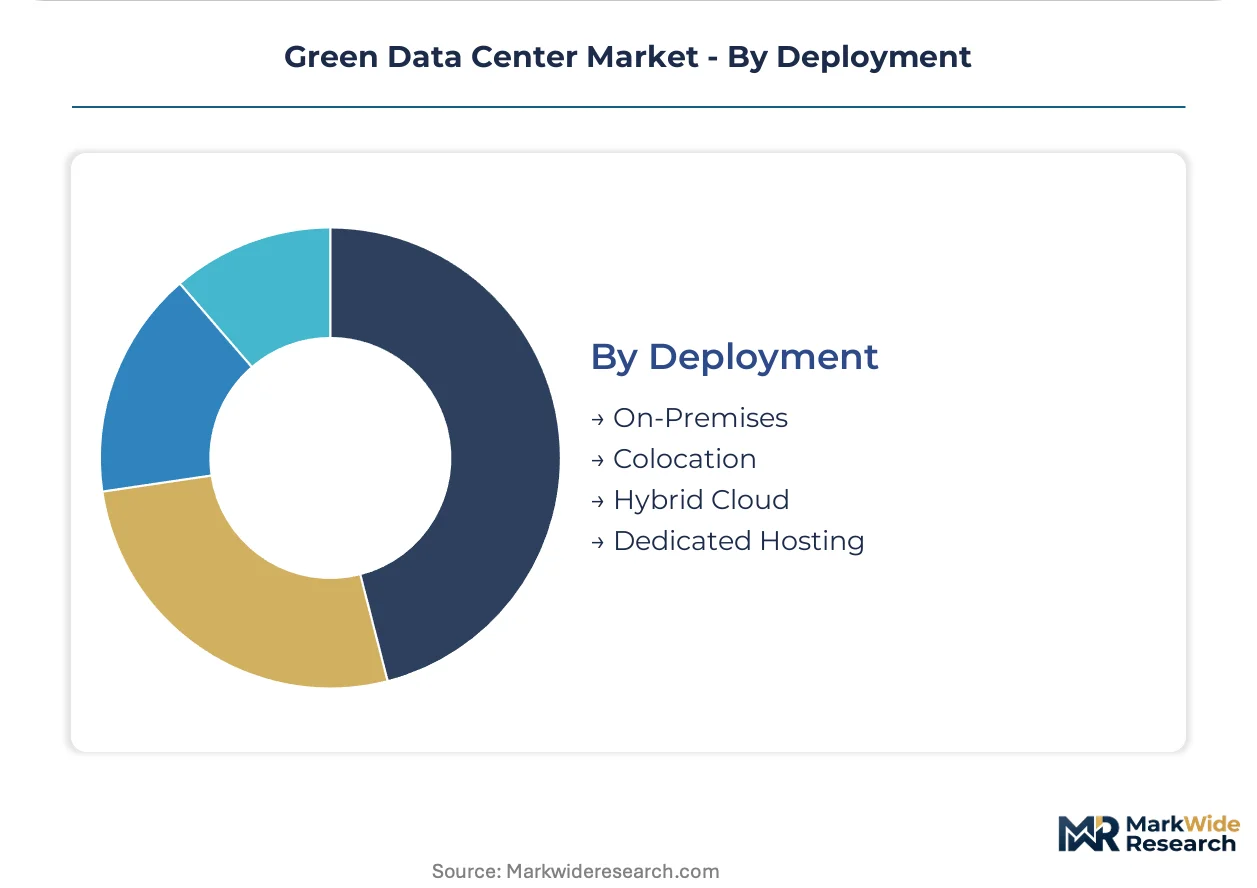
Deployment:
Real estate control and operational sovereignty drive the fundamental architecture choice.
- Colocation:Multi-tenant facilities where operators aggregate certification compliance and renewable procurement across diverse tenants. This model dominates Europe and Asia where land scarcity and permitting complexity favor shared infrastructure over enterprise builds.
- Hybrid Cloud:Workload portability across owned and leased capacity with unified carbon accounting. Enterprises in Germany and the Netherlands adopt this to balance sovereignty requirements with flexibility.
- On-Premises:Single-tenant facilities with full capital ownership and custom thermal design.
- Dedicated Hosting:Single-tenant capacity within multi-tenant facilities, blending control with outsourced facility management.
Installed base favors Colocation; fastest expansion is occurring in Hybrid Cloud as carbon accounting tools mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's cluster density anchors European hyperscale construction, pulling liquid cooling component supply chains from Chinese rare-earth refineries and German precision manufacturing hubs.
Germany
Frankfurt's data hall concentration drives district heating integration projects that convert waste thermal output into municipal revenue streams. The EU Energy Efficiency Directive mandates power usage effectiveness disclosure, tightening operational standards for facilities above 500kW capacity. Bavaria and North Rhine-Westphalia host secondary clusters where permitting moratoriums on new grid connections are forcing operators toward brownfield retrofits.
United States
Virginia's Northern Virginia data center corridor concentrates hyperscale cloud expansion with carbon-negative commitments through long-term renewable power purchase agreements. EPA ENERGY STAR certification thresholds tighten annually for facilities above 500kW, requiring verified operational data submission. Texas maintains secondary concentration in Dallas-Fort Worth where flat-rate power contracts are shifting toward consumption-based billing models.
Finland
Direct seawater cooling deployments eliminate chiller energy draw entirely for AI training clusters exceeding 100kW per rack. National renewable energy integration targets support Microsoft's carbon-negative operations across Nordic facilities. Helsinki anchors submarine cable landing stations where telecom operators leverage coastal thermal management for 24/7 uptime requirements.
Netherlands
Amsterdam's cluster density favors multi-tenant colocation models over greenfield enterprise builds due to real estate scarcity and permitting complexity. Hourly carbon intensity pricing drives procurement sophistication for cloud operators sustaining Dutch facilities. The Hague hosts regulatory compliance service providers capturing margin pools from ISO 50001 certification outsourcing.
Belgium
Coastal deployments near Antwerp and Ghent combine direct seawater cooling with proprietary liquid cooling patents for GPU-intensive workloads. Google's thermal management intellectual property anchors competitive positioning in this sub-region. Flanders maintains concentration of dielectric fluid maintenance technicians commanding premium wages across construction sites.
Green Data Center Market Vendor Landscape
Global majors compete with regional champions across thermal management technology and renewable energy procurement sophistication. The vendor base stratifies between integrated infrastructure conglomerates, hyperscale cloud operators with captive facility portfolios, and specialized colocation providers aggregating multi-tenant compliance. Three archetypes dominate: full-stack industrial equipment suppliers, cloud-native self-builders with long-term power purchase agreements, and multi-tenant facility operators outsourcing certification maintenance. Capacity expansion and strategic partnerships represent the dominant competitive moves, with operators securing rare-earth magnet supply chains and district heating integration agreements.
Within the hyperscale self-builder tier, Microsoft and Google exemplify carbon-negative operational models through Nordic renewable energy anchoring. Among integrated infrastructure suppliers, Schneider Electric occupies a position spanning industrial power distribution and advanced cooling systems for certified green builds. QTS Realty Trust represents the specialized colocation archetype, aggregating compliance and procurement sophistication across multi-tenant facilities in supply-constrained European markets.
| Leading Market Players |
|---|
| QTS Realty Trust |
| Microsoft |
| Equinix |
| Amazon Web Services |
| Digital Realty |
| Compass Datacenters |
| Schneider Electric |
| Vantage Data Centers |
| Others |
Supply Flow & Price Mechanics
Copper and rare-earth magnet costs cascade through liquid cooling manifold pricing tiers, with Chinese refining concentration compressing margins for European and North American facility operators while German precision manufacturing commands premium positioning for high-efficiency motor assemblies.
Pricing Analysis
Service-bundling separates certified green builds from commodity colocation, with ISO 50001 compliance maintenance and real-time carbon accounting unbundled as managed service add-ons in German and Dutch markets. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and renewable energy sourcing rigor, with hyperscale cloud operators least price-sensitive due to carbon-negative commitment mandates. Cost compression in mid-tier colocation intensifies because air-cooling residual demand delays full liquid conversion, forcing operators to absorb retrofit complexity without commensurate rate premiums.
Supply Chain Analysis
Regional distribution centers for dielectric fluids and cooling infrastructure concentrate in Germany, the Netherlands, and Belgium, with hub-and-spoke patterns radiating to Nordic construction sites where thermal-fluid engineering scarcity inflates last-mile logistics costs. Chinese rare-earth refining and German precision manufacturing anchor upstream component flows, while copper volatility and concentrated magnet sourcing tether pricing predictability to geopolitical trade corridors. Single-source vulnerability in dielectric coolant formulation exposes operators to input cost swings. Distribution runs through Schneider Electric's industrial power systems and specialized HVAC component networks serving hyperscale construction timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permitting moratoriums on new grid connections in Frankfurt and Bavaria constrain capacity expansion, propping pricing power for brownfield retrofit specialists with existing infrastructure access.
For Market Incumbents: Cement market position through captive control over rare-earth magnet supply chains and district heating integration agreements in Frankfurt and Amsterdam clusters. Acquire ISO 50001 certification service capabilities before disclosure mandates harden across EU member states. Liquid cooling patent portfolios represent the critical defensive lever against hyperscale self-builders with proprietary thermal management intellectual property. For New Entrants and Emerging Players: Enter via mid-tier colocation portfolios in supply-constrained German secondary markets where permitting caps favor brownfield retrofits over greenfield construction. Target educational institution research computing centers with episodic GPU-intensive workloads and limited operational staff for managed services penetration. Carbon accounting software integration offers the most penetrable go-to-market angle for technology-native entrants lacking physical infrastructure assets. For Investors and Strategic Acquirers: Municipal moratoriums lifting in Frankfurt is the leading indicator that brownfield retrofit capacity will command acquisition premiums across the next investment cycle. Vertically integrated facility operators with district heating revenue streams and renewable power purchase agreement pipelines represent the optimal target archetype. Watch for thermal-fluid engineering wage inflation in Nordic construction sites as the leading signal of supply-side constraint intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captive sourcing from Chinese refining networks insulates German and Nordic facility operators from input cost volatility. |
| District Heating Integration Partnership | Frankfurt and Amsterdam municipal revenue-sharing agreements convert waste thermal output into secondary income streams. |
| ISO 50001 Certification Service Acquisition | Managed compliance capabilities capture margin pools as EU Energy Efficiency Directive disclosure obligations intensify. |
| Direct Seawater Cooling Deployment | Finnish and Belgian coastal installations eliminate chiller energy draw entirely for AI training clusters. |
| Liquid Cooling Patent Portfolio Expansion | Proprietary thermal management intellectual property anchors competitive positioning against hyperscale self-builders. |
Methodological Framework
Document review covered facility operator capex disclosures, EU regulatory filings, and hyperscale cloud sustainability reports, complemented by interviews with data center engineering directors, renewable energy procurement specialists, municipal planning officers in Frankfurt and Amsterdam, and thermal-fluid systems technicians across Nordic construction sites. Secondary validation drew from EPA ENERGY STAR certification databases, EU Energy Efficiency Directive implementation records, and ISO 50001 registrar statistics. Bottom-up project pipeline analysis and top-down market sizing triangulated volume estimates across the analysis window.
Segmentation outputs reflect technology, service type, end user, and deployment model dimensions modeled across the projection horizon, with deployment architecture and real estate control patterns as industry-specific forecast inputs. CAGRs were derived from facility construction pipeline tracking and renewable energy procurement velocity indicators without reliance on single-source estimates.
Revisions become necessary when municipal permitting moratoriums extend beyond current assumption sets, rare-earth export restrictions materialize, or carbon border adjustment mechanisms alter renewable certificate verification economics. Forecasts reflect documented assumptions about grid interconnection timelines and district heating infrastructure maturation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Power Market
Data Center Infrastructure
Fault Tolerant Servers Market
Data Center Infrastructure
UK Data Center Rack Market
Data Center Infrastructure
Thailand Data Center Physical Security Market
Data Center Infrastructure
South America Data Center Market
Data Center Infrastructure
France Data Center Power Market
Data Center Infrastructure
Philippines Data Center Server Market
Data Center Infrastructure
Europe Data Center Physical Security Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
North America Data Center Construction Market
Data Center Infrastructure
UAE Data Center Server Market
Data Center Infrastructure
Europe Data Center Rack Market
Data Center Infrastructure
Global Data Center RFID Market
Data Center Infrastructure
Data Center Virtualization Market
Data Center Infrastructure
Indonesia Data Center Power Market
Data Center Infrastructure
Norway Data Center Market