
 New Zealand Data Center Rack Market | 2026-2036
New Zealand Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Data Center Rack Market Insights
Data center technician and electrical trades capacity is reorganizing procurement timelines across New Zealand, with lead times for certified rack installations stretching beyond historical norms. Schneider Electric SE leverages its Pacific distribution network to sustain availability of enclosed rack systems for enterprise buyers. Rittal GmbH & Co.KG anchors the premium segment through precision thermal management integration. Vertiv Group Corp. competes on modular installation architectures suited to Wellington's seismic design requirements.
A data center rack is a standardized metal frame designed to house, organize, and protect computing equipment such as servers, switches, and power distribution units, typically measured in rack units where one U equals 1.75 inches of vertical space. These structures provide structural support, cable management pathways, and airflow optimization essential for maintaining operational reliability in dense computing environments. Enclosed rack configurations command margin premiums in the New Zealand market due to dust filtration and security compliance demands from financial services end users. Open frame designs lead volume shipments among colocation providers seeking maximum cooling efficiency and rapid equipment access. Cloud service providers drive fastest growth in modular installation deployments, favoring factory-integrated rack-and-power assemblies that compress on-site construction schedules.
New Zealand's Commerce Commission oversees telecommunications infrastructure competition, while the Ministry for the Environment administers National Environmental Standards that constrain data center location and noise emissions. The Building Code, enforced by the Ministry of Business, Innovation and Employment, mandates seismic resilience standards that directly influence rack anchoring specifications and structural load calculations. Stakeholders must monitor submarine cable capacity expansions and renewable energy grid interconnection timelines as these infrastructure variables determine where rack density investments achieve acceptable total cost of ownership thresholds.
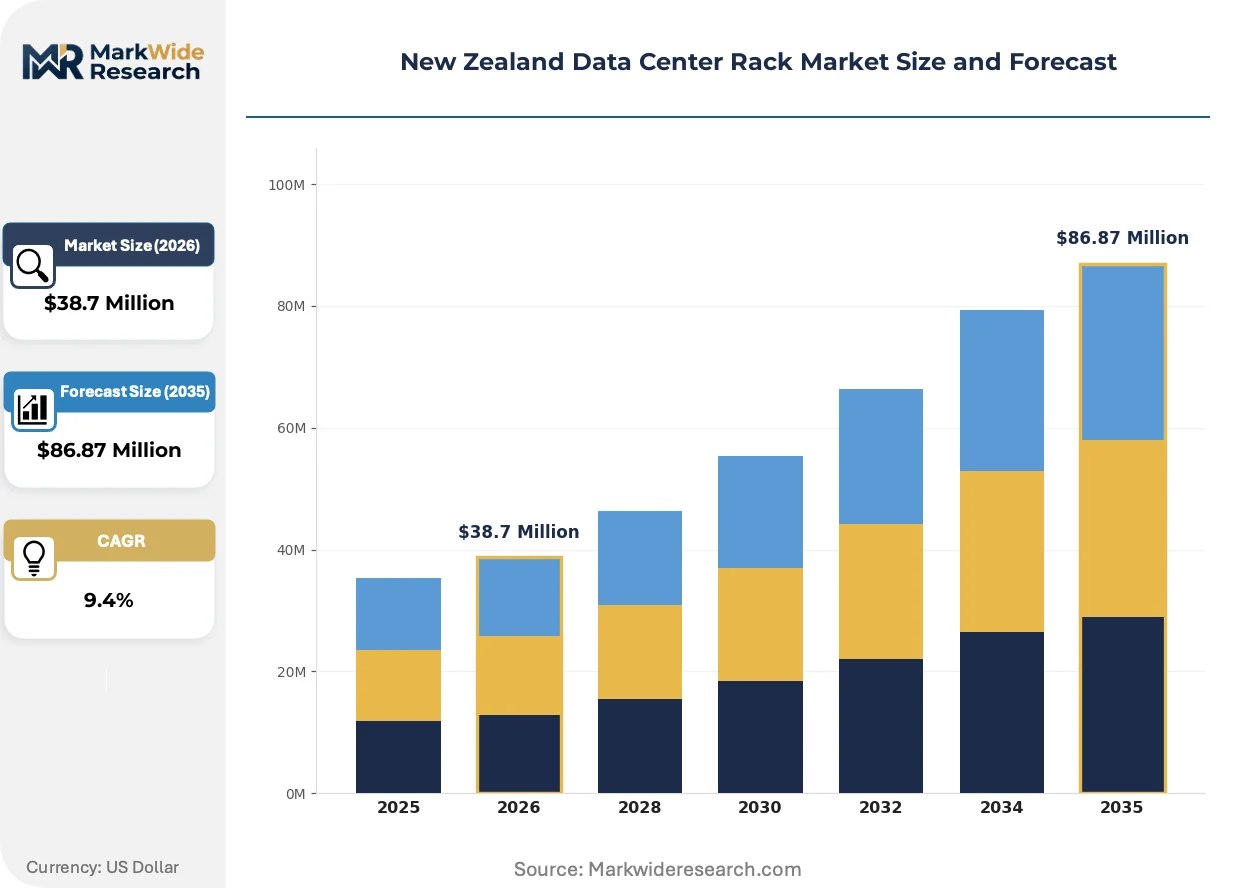
Market Dynamics
Seismic compliance mandates from New Zealand's Building Code are compressing procurement timelines and forcing rack manufacturers to redesign anchoring systems before products enter the Auckland-Wellington corridor. This structural pressure cascades through installation scheduling, certified technician availability, and factory pre-assembly requirements.
Growth Catalysts
- Submarine cable landings:The Southern Cross NEXT and Hawaiki Nui cables are expanding international bandwidth into Auckland's hyperscale corridor. Cloud operators are pre-positioning rack infrastructure to capture latency-sensitive workloads.
- National Environmental Standards for Telecommunications Facilities:This framework accelerates rack standardization by mandating uniform noise and emissions thresholds. Colocation providers upgrade to compliant enclosed systems to secure faster permitting.
- Financial services compliance:Banking and insurance sectors require dust-filtered, access-controlled rack configurations. Premium enclosed cabinets with integrated biometric locks command sustained preference from Wellington's institutional buyers.
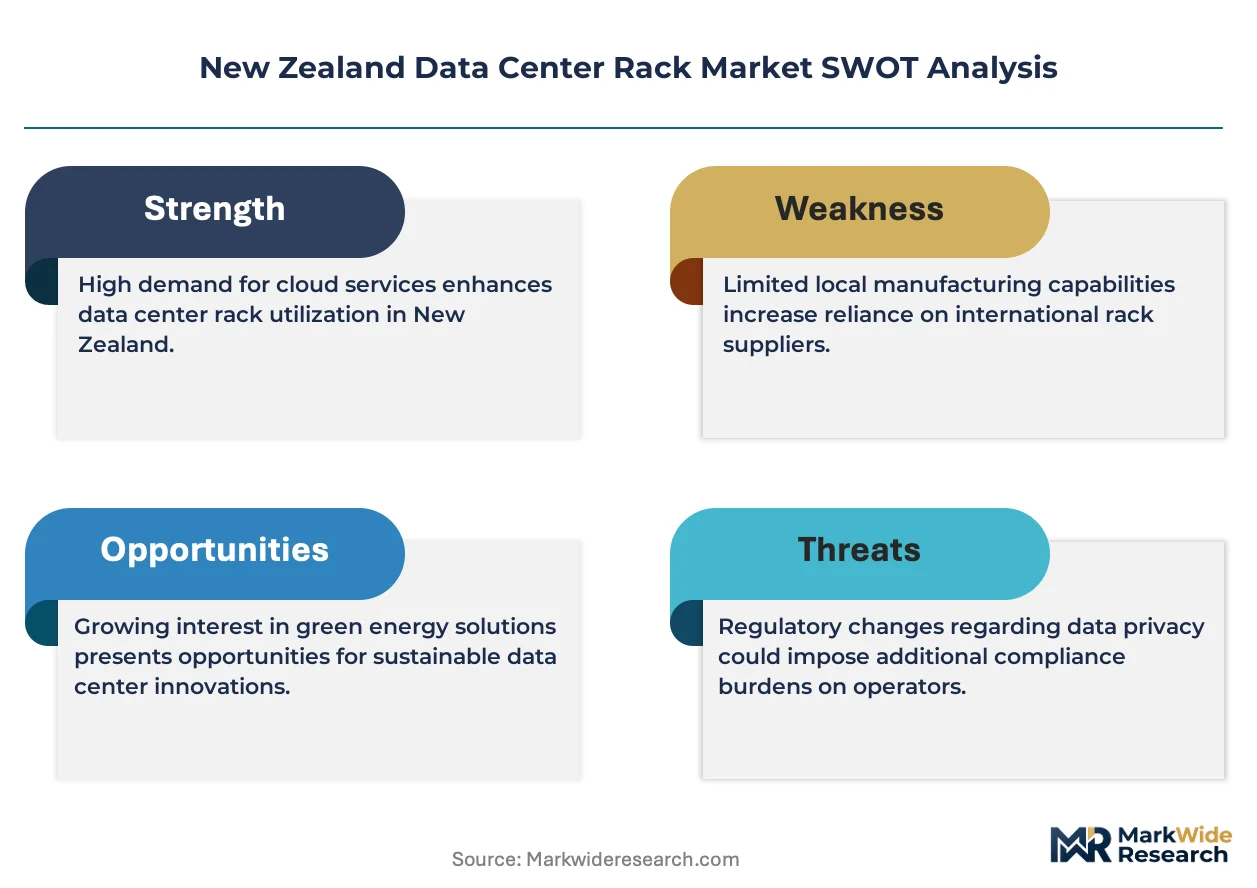
Market Restraints
- Certified electrical trades shortage:New Zealand's data center technician pipeline cannot match installation demand. Lead times for certified rack-and-power assemblies now stretch twelve to sixteen weeks beyond historical norms.
- Seismic steel specification costs:Building Code requirements for Zone 3 structural resilience add material premiums to rack anchoring systems. These specifications flow through to final installed costs without equivalent price elasticity in buyer budgets.
- Limited domestic manufacturing:Rack fabrication concentrates in Australian and Southeast Asian facilities. Currency volatility and shipping container availability inject margin uncertainty into landed cost calculations.
Strategic Opportunities
- Christchurch edge deployment:South Island data center development remains underpenetrated relative to Auckland-Wellington concentration. Submarine cable branching units and renewable hydroelectric access create viable secondary cluster conditions.
- Modular factory integration:Pre-integrated rack, power, and cooling assemblies compress on-site construction schedules. Cloud operators value this convergence for rapid capacity scaling without expanding certified technician headcount.
- MBIE seismic resilience grants:Ministry of Business, Innovation and Employment funding for infrastructure hardening subsidizes premium rack anchoring upgrades. Equipment vendors can bundle grant application support into enterprise sales cycles.
Industry Challenges
- Certified technician pipeline gaps:Electrical trades registration through the Electrical Workers Registration Board cannot scale to meet concurrent hyperscale construction timelines. Installation quality risks emerge when projects compress schedules.
- Legacy DCIM integration friction:Existing data center infrastructure management platforms in established facilities require custom API development to monitor next-generation smart rack power distribution units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Data Center Rack Market |
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $86.87 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame, Enclosed Rack, Wall-Mounted Rack, Chassis End User: Enterprises, Colocation Providers, Cloud Service Providers, Telecom Operators Size: 1U, 2U, 3U, 4U Installation: On-Premises, Off-Site, Hybrid, Modular |
| Companies Covered | Schneider Electric SE, Eaton Corporation, Rittal GmbH & Co.KG, Hewlett Packard Enterprise, Vertiv Group Corp., Black Box Corporation, Dell Inc., nVent Electric PLC, Nitto Kogyo Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Data Center Rack Market Trends and Innovations
Intelligent power distribution and thermal monitoring are migrating from separate subsystems into unified rack-level platforms. This convergence is compressing commissioning timelines and altering how facility operators specify capital equipment.
Factory-integrated rack-and-power assemblies are supplanting field-built configurations in New Zealand's hyperscale deployments. Cloud operators specify these pre-tested systems to eliminate on-site electrical termination and commissioning delays. The structural consequence is a shift in vendor selection criteria toward manufacturing integration depth rather than distribution network breadth.
New Zealand's National Environmental Standards for Telecommunications Facilities are tightening noise emissions thresholds for data center equipment. Rack manufacturers must redesign fan and airflow architectures to maintain thermal performance at reduced acoustic output. Financial services facilities in Wellington's dense urban core face the most acute compliance pressure and are accelerating replacement cycles.
Consumption-based power billing is altering procurement relationships between colocation operators and their enterprise tenants. Tenants now demand granular rack-level energy monitoring to align operational expenditure with actual compute load. Auckland's largest multi-tenant facilities are responding by unbundling power from space leases and installing smart PDUs as standard infrastructure.
New Zealand Data Center Rack Market Segmentation
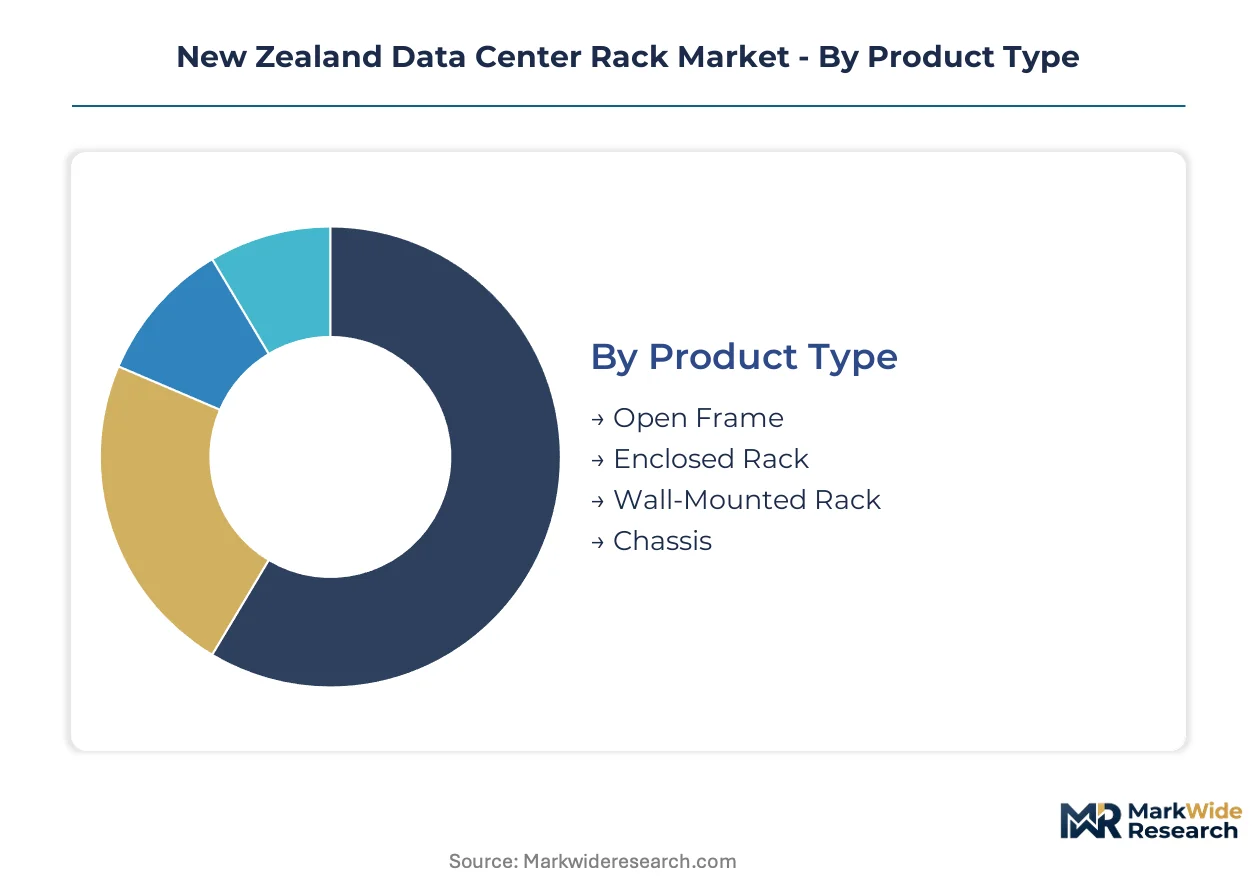
New Zealand's data center rack market segments along four critical dimensions that shape procurement patterns across Auckland's hyperscale corridor and Wellington's institutional clusters. Product architecture, end-user requirements, size specifications, and installation modality each create distinct competitive arenas with divergent margin profiles and technical compliance burdens.
Product Type:
Auckland's hyperscale developments favor open frame configurations for cooling efficiency, while Wellington's dense urban financial districts drive enclosed rack specifications for noise compliance under National Environmental Standards.
- Open Frame:Metal skeleton structures without side panels or doors maximize airflow and enable rapid equipment access. Colocation providers across Auckland's hyperscale corridor specify these for thermal performance in high-density compute zones where cooling efficiency outweighs physical security concerns.
- Enclosed Rack:Fully enclosed cabinets with lockable doors, side panels, and integrated cable management pathways. Wellington's banking and insurance sectors mandate these configurations for dust filtration and biometric access control compliance, accepting material cost premiums for regulatory assurance.
- Wall-Mounted Rack:Compact vertical enclosures designed for space-constrained edge deployments and branch office infrastructure. Christchurch's emerging South Island edge clusters utilize these for distributed processing nodes with limited floor loading capacity.
- Chassis:Integrated structural frames with pre-installed power distribution and cooling subsystems. Factory-integrated chassis assemblies reduce on-site electrical termination requirements, compressing installation timelines where certified technician availability constrains project delivery.
Open frame configurations command volume leadership in Auckland's hyperscale corridor. The steepest expansion trajectory runs through enclosed rack systems as National Environmental Standards tighten noise emissions thresholds.
End User:
Procurement scale and technical specification authority vary dramatically across end-user categories, with cloud operators driving modular integration requirements and enterprises prioritizing seismic compliance documentation.
- Enterprises:Private data center operators in financial services, healthcare, and government sectors. Wellington's institutional buyers emphasize Building Code seismic resilience certification and integrated physical security, often retaining specification control through direct vendor relationships rather than contractor intermediaries.
- Colocation Providers:Multi-tenant facility operators leasing rack space to enterprise customers. Auckland's largest colocation campuses standardize on open frame configurations with unbundled power metering to support consumption-based billing models demanded by enterprise tenants.
- Cloud Service Providers:Hyperscale operators deploying dedicated infrastructure for public cloud workloads. These buyers specify factory-integrated rack-and-power assemblies to eliminate field commissioning dependencies and compress capacity scaling timelines.
- Telecom Operators:National carriers expanding edge computing presence alongside core network infrastructure. Telecom procurement emphasizes wall-mounted and compact chassis solutions for cellular base station co-location and fixed-wireless access point aggregation.
Colocation providers anchor the established installed base. Cloud service providers are gaining share fastest through pre-integrated procurement models that bypass certified technician bottlenecks.
Size:
Rack unit height specifications correlate directly with compute density requirements and thermal management complexity, with larger form factors concentrating in machine learning and high-performance computing deployments.
- 1U:Single rack unit enclosures for network switches, patch panels, and shallow-depth servers. Network infrastructure layers in Auckland's hyperscale facilities utilize 1U configurations for maximum port density in limited vertical space.
- 2U:Dual rack unit enclosures accommodating standard-depth servers with redundant power supplies. Enterprise server consolidation projects across Wellington's financial district standardize on 2U as the baseline compute form factor.
- 3U:Triple rack unit configurations for storage arrays and GPU-accelerated compute nodes. Machine learning training clusters in Auckland's cloud campuses specify 3U enclosures to accommodate accelerator card thermal loads and NVMe storage density.
- 4U:Maximum standard height for high-capacity storage systems and specialized compute appliances. Video rendering farms and scientific computing facilities utilize 4U configurations where thermal mass and component spacing override vertical space efficiency.
2U specifications dominate enterprise refresh cycles. 3U configurations are expanding most quickly as AI inference workloads proliferate across Auckland's cloud infrastructure.
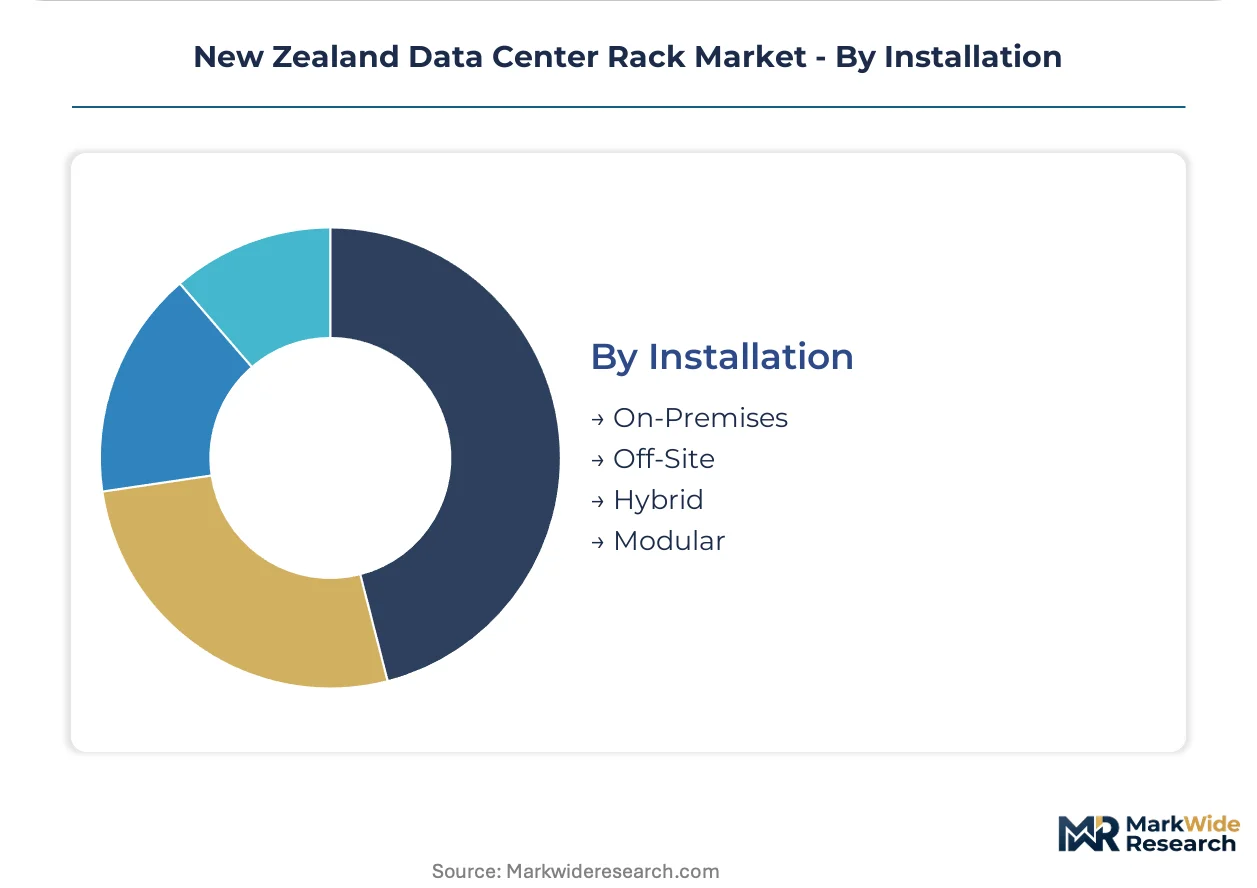
Installation:
Installation modality determines supply chain configuration and margin capture, with modular approaches restructuring vendor relationships toward manufacturing integration depth.
- On-Premises:Traditional field-assembled rack installations within enterprise-owned facilities. Wellington's institutional data centers continue on-premises deployment for sovereign control over physical infrastructure and direct Building Code compliance accountability.
- Off-Site:Rack infrastructure deployed in third-party colocation or cloud facilities with remote management. Enterprises migrating from owned facilities to colocation favor off-site installation for capital efficiency and operational flexibility.
- Hybrid:Split deployments combining on-premises critical workloads with off-site burst capacity. Financial services firms in Auckland and Wellington utilize hybrid installation to maintain transactional system proximity while leveraging cloud elasticity for analytics workloads.
- Modular:Factory-pre-integrated rack, power, and cooling assemblies delivered as complete units. Cloud service providers specify modular installation to eliminate on-site electrical termination and compress commissioning schedules where certified technician availability constrains project velocity.
On-premises installation retains the established base. Modular approaches are climbing the fastest as hyperscale operators restructure procurement toward manufacturing integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand's data center rack consumption diverges sharply from neighboring Australia, with seismic compliance and submarine cable proximity overriding pure scale economics in procurement decisions. Auckland's hyperscale corridor absorbs high-density open frame systems for cloud workloads, while Wellington's financial district prioritizes enclosed configurations for noise and security compliance.
Auckland Region
Hyperscale cloud operators and international submarine cable landings drive rack density investments across Auckland's northern corridor. The Ministry for the Environment's National Environmental Standards for Telecommunications Facilities mandate uniform noise thresholds, accelerating enclosed rack upgrades in mixed-use zones. Whenuapai and Drury industrial precincts concentrate new facility construction where Southern Cross NEXT cable connectivity meets land availability.
Wellington Region
Financial services and government data centers dominate Wellington's institutional demand for dust-filtered, biometric-secured rack configurations. The Building Code's seismic Zone 3 requirements, enforced by the Ministry of Business, Innovation and Employment, add material premiums to rack anchoring specifications. The central business district's dense urban core faces acute noise compliance pressure under National Environmental Standards.
Canterbury Region
Christchurch's emerging South Island edge cluster leverages renewable hydroelectric access and lower land costs for distributed computing nodes. The Commerce Commission oversees telecommunications infrastructure competition frameworks that enable secondary market entry. Canterbury's industrial periphery attracts wall-mounted and compact chassis deployments for cellular base station co-location.
Waikato Region
Hamilton's logistics and agricultural technology sectors generate mid-market demand for hybrid on-premises and off-site rack installations. The Electrical Workers Registration Board certifies technician capacity that supports regional project timelines. Huntly's proximity to national grid interconnection points enables power-intensive compute deployments with favorable renewable energy profiles.
New Zealand Data Center Rack Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure where manufacturing depth determines hyperscale access. The upper tier captures premium margins through factory-integrated rack-and-power assemblies that compress commissioning schedules. Mid-tier specialists compete on regional distribution velocity and seismic compliance documentation. Dominant competitive moves include manufacturing integration depth investments and grant-aligned sales bundling for public sector procurement.
Among European-headquartered industrial fabricators, Rittal GmbH & Co.KG and Schneider Electric SE exemplify contrasting strategic positions within the premium segment. Rittal occupies a position anchored in precision thermal management integration, while Schneider leverages Pacific distribution network scale for enterprise availability. Vertiv Group Corp., with its US-based corporate structure, represents the modular architecture specialization required for Wellington's seismic design constraints. These three entities collectively illustrate how geographic origin and manufacturing integration depth map to distinct competitive vectors in this market.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Eaton Corporation |
| Rittal GmbH & Co.KG |
| Hewlett Packard Enterprise |
| Vertiv Group Corp. |
| Black Box Corporation |
| Dell Inc. |
| nVent Electric PLC |
| Nitto Kogyo Corporation |
| Others |
Pricing and Supply Chain Analysis
Factory-integrated rack-and-power assemblies displacing field-built configurations simultaneously concentrate procurement leverage with Australian and Southeast Asian manufacturers while compressing margin capture for distribution-dependent vendors. This substitution dynamic restructures landed cost calculations as currency volatility and container availability inject uncertainty into buyer budgeting cycles.
Pricing Analysis
Long-term offtake agreements dominate hyperscale procurement, with cloud service providers locking factory capacity for pre-integrated chassis assemblies to bypass certified technician bottlenecks. Price differentiation rests on seismic certification grade and manufacturing integration depth, with Zone 3 Building Code compliance commanding material premiums. Cost compression in standard open frame configurations intensifies as colocation providers consolidate volume and squeeze distributor margins. Enterprise financial services buyers exhibit lowest price sensitivity, prioritizing biometric security integration and dust filtration over unit economics.
Supply Chain Analysis
Australia and Southeast Asian fabrication hubs anchor rack production for the New Zealand market, with Chinese steel mills feeding raw material inputs. Supply chains draw from cold-rolled steel, precision sheet metal, and integrated power distribution components. Single-source vulnerability concentrates in seismic anchoring hardware certified to Ministry of Business, Innovation and Employment specifications. Distribution runs through Pacific logistics networks with Schneider Electric and Vertiv maintaining regional inventory buffers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory-integrated rack platforms are restructuring competitive economics around interoperability standards, as cloud operators demand unified API compatibility across power, cooling, and infrastructure management subsystems.
For Market Incumbents: Secure manufacturing integration depth in Australian fabrication facilities to defend against modular assembly competitors compressing commissioning timelines. Invest in Electrical Workers Registration Board certification programs to alleviate technician pipeline constraints threatening installation quality. Channel control through direct enterprise relationships in Wellington's financial district preserves premium pricing power against distributor disintermediation. For New Entrants and Emerging Players: Anchor in Christchurch's emerging South Island edge cluster where submarine cable branching units and renewable hydroelectric access create viable secondary market conditions. Target wall-mounted and compact chassis segments underserved by hyperscale-focused incumbents. Partner with regional electrical contractors holding MBIE seismic resilience grant relationships to accelerate sales cycles. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors manufacturing-integrated mid-caps over distribution-heavy legacy players. Acquisition targets should demonstrate captive fabrication capacity and Building Code certification depth rather than pure scale. Monitor submarine cable capacity expansion announcements as inflection indicators for rack density investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Integration | Captive fabrication in Australian facilities compresses lead times and insulates against currency volatility. |
| Seismic Certification Investment | Zone 3 Building Code compliance opens Wellington institutional procurement to premium enclosed rack systems. |
| Technician Pipeline Development | Electrical Workers Registration Board partnerships alleviate installation bottlenecks constraining project velocity. |
| Grant-Aligned Sales Bundling | MBIE resilience funding integration accelerates enterprise sales cycles in public sector procurement. |
| Platform Interoperability | Unified API standards across power and cooling subsystems capture cloud operator specification authority. |
Research Methodology
Cross-validation between primary fieldwork with data center operators and secondary analysis of submarine cable development databases anchors the qualitative findings. Stakeholder interviews encompassed facility engineering directors, electrical contractors certified through the Electrical Workers Registration Board, procurement leads at colocation providers, and cloud infrastructure planners. Secondary sources included Building Code compliance filings with the Ministry of Business, Innovation and Employment, National Environmental Standards documentation, customs import records for rack and power distribution equipment, and hyperscaler capital expenditure disclosures. Bottom-up installation volume estimates triangulated against top-down facility capacity projections.
Sensitivity analysis tested forecast outputs against variables including certified technician availability scaling, seismic steel specification cost trajectories, and submarine cable landing timelines. Segmentation dimensions modeled encompass product architecture, end-user category, rack unit height, and installation modality alongside regional regulatory cluster differentiation. CAGRs were derived from installation volume trends correlated with cloud operator facility announcements and renewable energy grid interconnection schedules.
Material uncertainties — certified electrical trades pipeline expansion, currency volatility in Australian dollar-denominated supply contracts, and National Environmental Standards enforcement intensity — sit outside the modeled envelope. Forecasts reflect assumptions about continued hyperscale investment concentration in Auckland's corridor and sustained Building Code seismic resilience requirements. Recalibration cycles align with material shifts in submarine cable capacity, renewable energy grid interconnection, and technician certification throughput.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Spain Data Center Power Market
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
Europe Data Center Power Market
Data Center Infrastructure
Global Data Center RFID Market
Data Center Infrastructure
Data Terminal Market
Data Center Infrastructure
Europe Data Center Server Market
Data Center Infrastructure
Hong Kong Data Center Power Market
Data Center Infrastructure
France Data Center Storage Market
Data Center Infrastructure
Singapore Data Center Rack Market
Data Center Infrastructure
Nigeria Data Center Market
Data Center Infrastructure
Switchgear for Data Centers Market
Data Center Infrastructure
Fiber Management Systems Market
Data Center Infrastructure
South Korea Data Center Rack Market
Data Center Infrastructure
Data Center Containment Solution Market
Data Center Infrastructure
Server Station Market
Data Center Infrastructure
Ireland Data Center Physical Security Market