
 Brazil Data Center Market | 2026-2036
Brazil Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Data Center Market Analysis
Certified data center engineering talent is redrawing competitive boundaries across Brazil's facility expansion pipeline. ODATA leverages its hyperscale-ready campuses near São Paulo to anchor wholesale colocation contracts with international cloud operators. Ascenty sustains dominance through captive fiber networks linking its campuses to submarine cable landing stations. Scala Data Centers specializes in sustainable design, operating facilities that target PUE benchmarks below industry averages for tropical climates.
A data center constitutes a dedicated facility housing computing infrastructure with controlled environmental parameters including precision cooling maintaining temperatures between 18°C and 27°C, redundant power systems with tiered uptime classifications, and physical security protocols for continuous digital service delivery. Colocation services capture the largest revenue pool as enterprises divest owned facilities, while edge computing deployments represent the fastest structural expansion as latency-sensitive applications require distributed nodes in Brazilian state capitals. Cloud services segments command premium pricing through managed security layers and hybrid orchestration tools.
ANATEL governs telecommunications infrastructure licensing that dictates fiber interconnection rights between facilities, while ABNT NBR standards establish electrical and fire safety baselines for facility certification. ANVISA oversight of pharmaceutical data residency requirements creates specialized demand for certified local hosting among healthcare enterprises. Stakeholders must monitor regulatory developments around data localization mandates and renewable energy sourcing obligations that will determine site selection economics and customer contract structures.
Market Dynamics
ANATEL's fiber licensing reforms are compressing interconnection timelines between São Paulo hyperscale clusters and submarine cable landing stations, redrawing facility location economics across Southeast Brazil.
Growth Catalysts
- Data Localization Mandates:Brazil's national data protection framework requires financial and healthcare enterprises to maintain primary data storage within sovereign territory. This compels foreign cloud operators to establish certified local presence rather than serving Brazilian users from international nodes.
- Hyperscale Campus Concentration:Santana de Parnaíba anchors a corridor of contiguous land parcels with redundant substations and dual fiber paths. Developers secure 10-15 year power purchase agreements at industrial tariffs unavailable in metropolitan cores.
- Edge Computing Latency Requirements:Autonomous vehicle testing zones and industrial IoT deployments in Campinas and Porto Alegre require sub-10 millisecond response times. Distributed micro-facilities address this gap where centralized hyperscale infrastructure cannot.
Market Restraints
- Copper and Aluminum Input Volatility:Busbar and electrical distribution systems constitute 18-22% of facility construction costs. Price swings in London Metal Exchange contracts compress developer margins during 24-36 month build cycles.
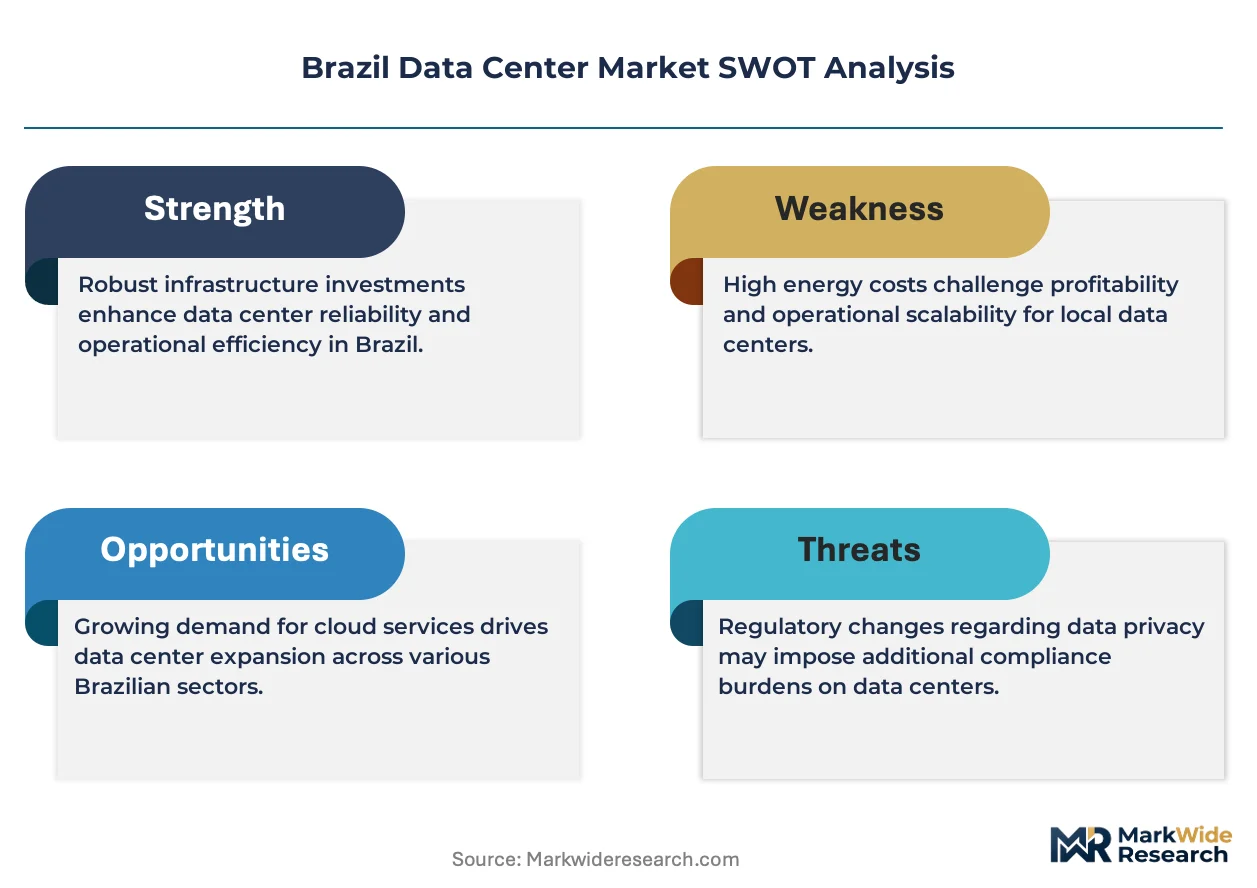
- Tropical Climate Cooling Load:Ambient temperatures exceeding 30°C for 4-6 months annually force mechanical refrigeration redundancy. This elevates power usage effectiveness baselines above temperate-climate equivalents, constraining sustainability certifications.
- Submarine Cable Concentration Risk:Four landing stations near Fortaleza handle 70% of Brazil's international bandwidth. Geological or security incidents at these nodes would cascade through dependent data center clusters.
Strategic Opportunities
- Northeast Corridor Expansion:Fortaleza and Recife offer underutilized fiber backbones from transatlantic cable landings. Developers can capture latency-sensitive African and European routing demand at 40-60% lower land costs than São Paulo state.
- Liquid Cooling Technology Convergence:Direct-to-chip and immersion systems address tropical thermal constraints while enabling 50+ kilowatt rack densities. Early adopters secure premium pricing from high-performance computing tenants.
- Renewable Energy Certificate Arbitrage:Brazil's regulated power market allows facility operators to source hydroelectric generation credits. This satisfies emerging corporate sustainability mandates without on-site solar capital expenditure.
Industry Challenges
- Certified Engineering Talent Scarcity:Uptime Institute and TIA-942 accredited professionals number fewer than 400 across Brazil. Competition for these credentials inflates staffing costs and extends commissioning timelines.
- Legacy Electrical Infrastructure Integration:Many enterprise-owned facilities in Rio de Janeiro and Belo Horizonte operate on 208V/60Hz architectures. Retrofitting for 415V/3-phase hyperscale standards requires complete distribution replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Data Center Market |
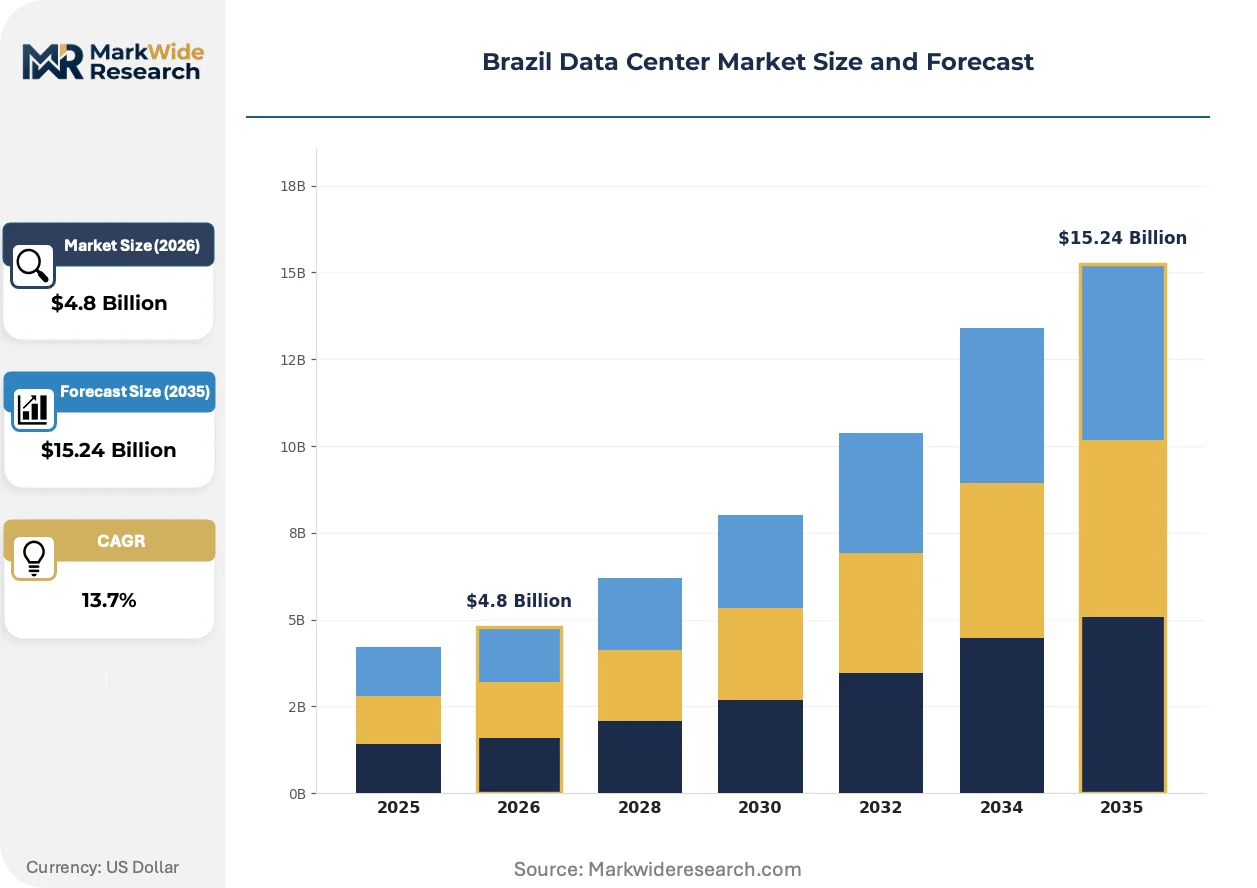
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Managed Hosting, Cloud Services, Disaster Recovery Technology: Cooling Systems, Power Distribution, Server Hardware, Virtualization End User: Enterprises, Government, Telecom Providers, IT Services Deployment: On-Premises, Off-Premises, Hybrid, Edge Computing |
| Companies Covered | ODATA (Aligned Data Centers), Microsoft Corporation, Ascenty (Digital Realty), HostDime, CloudHQ, Scala Data Centers, Elea Data Centers, Vivo (Telefônica Brasil), Equinix, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Data Center Market Emerging Trajectories
Cooling technology is fragmenting competitive positioning among Brazilian facility operators as tropical thermal loads force divergence from temperate-climate design templates.
Direct liquid cooling is fragmenting traditional air-cooled architectures in high-density deployments. Hyperscale tenants deploying GPU clusters for artificial intelligence training now specify 30-50 kilowatt racks that exceed conventional perimeter cooling capacity. This technology compression is enabling specialist engineering firms to capture premium contracts from generalist mechanical contractors who lack thermal design expertise.
ANATEL's infrastructure sharing mandates require dominant fiber owners to lease dark fiber to competing data center operators at regulated rates. This industrial consequence accelerates campus interconnection in São Paulo's ABC Paulista industrial zone while compressing captive network advantages previously held by vertically integrated developers. Wholesale colocation providers benefit most, as they can now secure diverse path redundancy without constructing proprietary fiber plant.
Enterprise procurement patterns are compressing contract durations from traditional five-year terms toward 24-36 month structures with embedded expansion options. Financial services buyers in São Paulo and Curitiba demand modular capacity commitments that align with regulatory capital allocation cycles. This behavioral shift is visible most acutely among mid-tier banks divesting owned facilities, who prioritize operational flexibility over long-term rate locks.
Brazil Data Center Market Segmentation
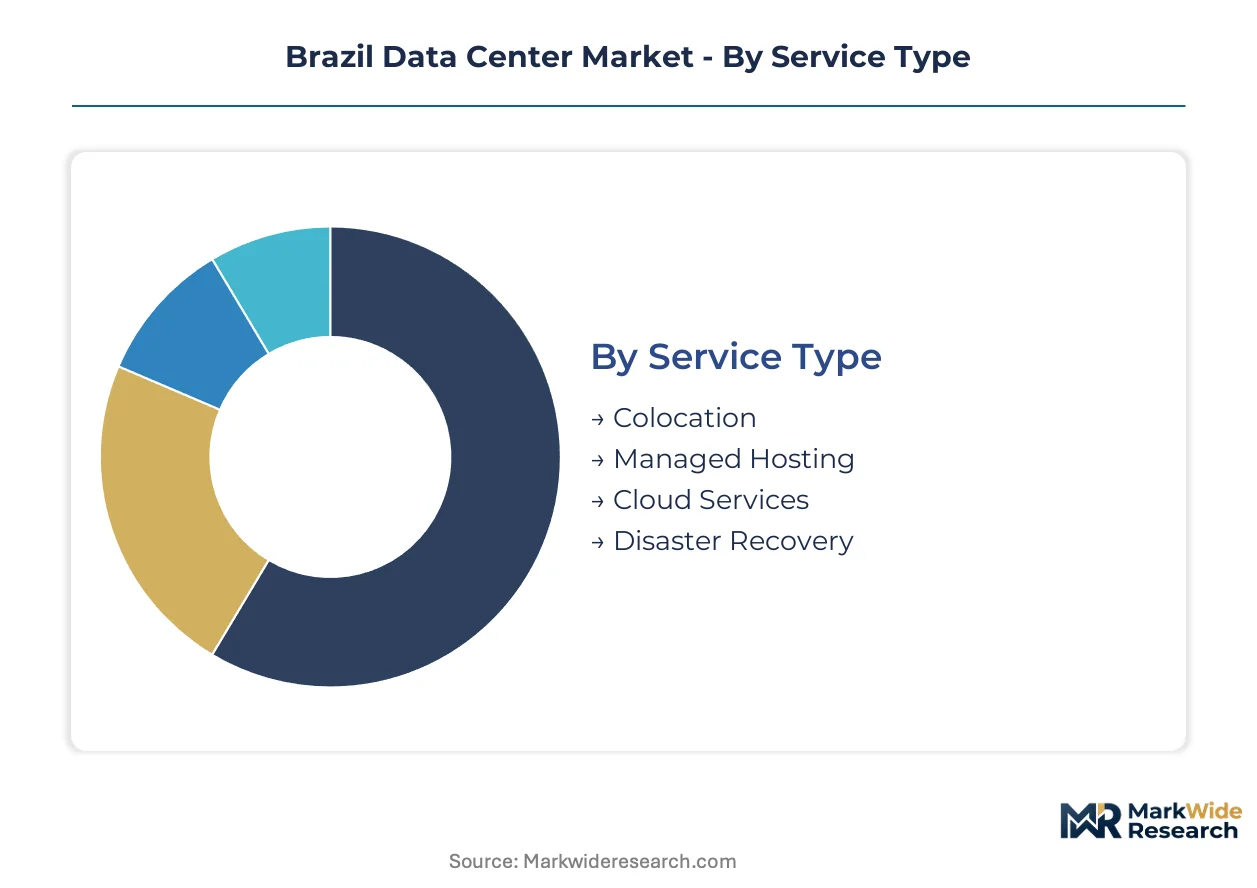
Brazil's data center market segments along operational, technical, and customer dimensions that determine facility investment priorities and contract structures. Understanding these divisions reveals where infrastructure capital concentrates and which service models capture premium pricing in ANATEL-regulated telecommunications markets.
Service Type:
Margin pools concentrate in recurring revenue services with long contract durations and low customer churn.
- Colocation:Wholesale and retail space leasing with power and cooling guarantees. Financial institutions in São Paulo drive demand as divestment of owned facilities accelerates. ANATEL's fiber licensing reforms compress interconnection costs for multi-tenant environments.
- Cloud Services:Managed infrastructure with hybrid orchestration and security layers. Brazilian banks and healthcare enterprises require local presence to satisfy data localization mandates. Premium pricing reflects compliance certification overhead.
- Managed Hosting:Dedicated server administration with SLAs covering uptime and security patching. Mid-market enterprises in Curitiba and Porto Alegre favor this model for capital efficiency.
- Disaster Recovery:Secondary site replication and failover orchestration. ANVISA pharmaceutical data residency rules create specialized demand for certified healthcare backup facilities.
Colocation holds installed capacity. Cloud Services is rotating up the share rankings.
Technology:
Cost tiers separate commodity mechanical systems from specialized thermal engineering that commands design premiums.
- Cooling Systems:Precision HVAC and emerging liquid cooling architectures. Tropical climate loads exceeding 30°C ambient for extended periods force mechanical redundancy and elevate PUE baselines. Direct-to-chip systems enable 50+ kilowatt rack densities for GPU clusters.
- Power Distribution:Uninterruptible power supplies, switchgear, and busbar distribution. Copper and aluminum input volatility compresses developer margins during 24-36 month construction cycles. Santana de Parnaíba campuses secure 10-15 year industrial power purchase agreements.
- Server Hardware:Compute, storage, and networking equipment procurement. Hyperscale tenants increasingly supply own racks, reducing provider capital intensity.
- Virtualization:Software-defined compute and storage abstraction layers. Multi-tenant resource pooling improves utilization rates in wholesale colocation environments.
Power Distribution absorbs construction capital. Cooling Systems is climbing the fastest as density requirements intensify.
End User:
Volume concentration varies sharply between regulated industries with compliance-driven procurement and technology sectors with latency-sensitive workloads.
- Enterprises:Banking, healthcare, and retail organizations migrating from owned facilities. Data localization mandates compel foreign multinationals to establish certified Brazilian presence rather than serving from international nodes.
- Telecom Providers:Network operators requiring edge nodes for 5G backhaul and content delivery. Campinas and Porto Alegre autonomous vehicle testing zones demand sub-10 millisecond response times.
- Government:Federal and state agencies with sovereign data requirements. Procurement cycles extend commissioning timelines compared to commercial contracts.
- IT Services:Systems integrators and managed service providers reselling capacity to downstream clients. Contract flexibility demands compress traditional five-year terms toward 24-36 month structures.
Enterprises anchor committed revenue. Telecom Providers is gaining share fastest as edge deployment accelerates.
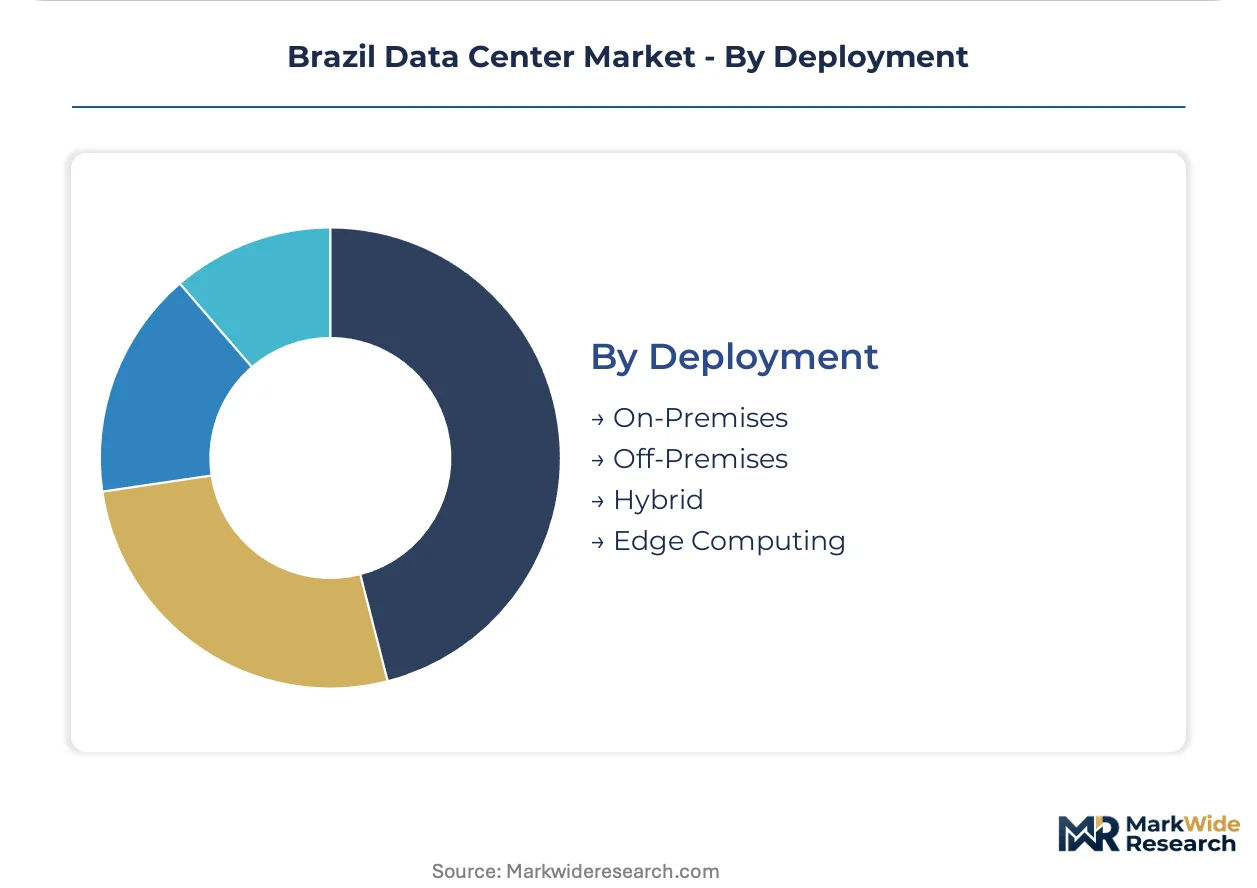
Deployment:
Customer type determines infrastructure location preference, with financial services favoring proximity to São Paulo fiber clusters while industrial IoT distributes across state capitals.
- Hyperscale Facilities:Purpose-built campuses exceeding 10 megawatts with redundant substations. Santana de Parnaíba anchors Southeast Brazil's corridor of contiguous land parcels with dual fiber paths.
- Edge Computing:Distributed micro-facilities in Brazilian state capitals addressing latency-sensitive applications. Industrial IoT deployments and autonomous vehicle zones require localized processing unavailable from centralized infrastructure.
- On-Premises:Enterprise-owned facilities in Rio de Janeiro and Belo Horizonte operating legacy 208V/60Hz architectures. Retrofitting for 415V/3-phase hyperscale standards requires complete distribution replacement.
- Hybrid:Workload orchestration across owned, colocation, and cloud resources. Financial services buyers prioritize operational flexibility over long-term rate locks.
Hyperscale Facilities hold committed power allocations. Edge Computing is expanding most quickly as latency requirements fragment infrastructure geography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo commands pricing premiums of 40-60% over Northeast Brazil, yet Fortaleza and Recife offer underutilized fiber backbones at substantially lower land costs. This asymmetry is redrawing facility location economics across the country.
São Paulo
Financial institutions and hyperscale cloud operators drive concentrated demand in the Santana de Parnaíba corridor. ANATEL's fiber licensing reforms compress interconnection timelines between campuses and submarine cable landing stations. Developers secure 10-15 year industrial power purchase agreements unavailable in metropolitan cores.
Minas Gerais
Belo Horizonte hosts legacy enterprise-owned facilities operating on 208V/60Hz architectures requiring complete distribution replacement. ABNT NBR electrical standards govern retrofit compliance timelines. The state capital's industrial IoT deployments are fragmenting infrastructure geography toward edge computing nodes.
Rio de Janeiro
Enterprise divestment of owned facilities accelerates wholesale colocation procurement from mid-tier banks and retail conglomerates. ANVISA pharmaceutical data residency requirements create specialized demand for certified healthcare backup facilities. Legacy electrical infrastructure constraints limit hyperscale conversion economics.
Rio Grande do Sul
Porto Alegre autonomous vehicle testing zones demand sub-10 millisecond response times that centralized infrastructure cannot satisfy. Distributed micro-facilities address this latency gap. State capital edge deployments represent the fastest structural expansion outside Southeast Brazil.
Ceará
Fortaleza anchors four submarine cable landing stations handling 70% of Brazil's international bandwidth. Transatlantic fiber landings offer latency-sensitive African and European routing demand. Geological concentration risk at these nodes cascades through dependent data center clusters.
Brazil Data Center Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across Brazil's facility expansion pipeline. The market structures around three tiers: hyperscale-ready campus developers, vertically integrated fiber owners, and sustainable design specialists. Strategic moves concentrate on captive fiber network construction and liquid cooling technology adoption for tropical thermal constraints. M&A activity targets engineering talent acquisition and renewable energy certificate portfolio assembly.
Within the hyperscale-ready tier, ODATA and Scala Data Centers exemplify competing positioning strategies. Ascenty represents vertically integrated infrastructure control. These three anchors occupy distinct competitive positions: wholesale colocation scale, sustainable design specialization, and captive network dominance.
| Leading Market Players |
|---|
| ODATA (Aligned Data Centers) |
| Microsoft Corporation |
| Ascenty (Digital Realty) |
| HostDime |
| CloudHQ |
| Scala Data Centers |
| Elea Data Centers |
| Vivo (Telefônica Brasil) |
| Equinix |
| Others |
Supply Flow & Price Mechanics
Twenty-four to thirty-six month construction lead times for hyperscale facilities in Southeast Brazil concentrate pricing power with developers holding secured substations and power purchase agreements in Santana de Parnaíba, while buyers without long-term allocations face spot-market premiums for available capacity.
Pricing Analysis
São Paulo commands pricing premiums of 40-60% over Northeast Brazil due to fiber density and financial services concentration. Three-tier pricing structure across premium certified, standard colocation, and economy remote hosting levels separates buyers by compliance requirements and latency sensitivity. Pricing pressure stems from copper and aluminum input volatility compressing developer margins during build cycles. Mid-tier banks divesting owned facilities exhibit highest price sensitivity, while hyperscale cloud operators securing wholesale blocks demonstrate lowest.
Supply Chain Analysis
China and the United States anchor server hardware and precision cooling equipment manufacturing for Brazilian facility deployments. Copper busbar, aluminum electrical distribution, and diesel generator sets constitute critical input dependencies. Single-source vulnerability concentrates in precision HVAC compressors sourced from limited global suppliers. Distribution runs through ANATEL-licensed fiber operators and specialized data center construction contractors with tropical climate expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward financial institutions consolidating procurement through wholesale colocation contracts, as enterprise divestment of owned facilities concentrates volume with fewer decision-makers negotiating multi-megawatt blocks.
For Market Incumbents: Compound hyperscale campus advantages by securing additional contiguous land parcels with redundant substations before ANATEL's fiber licensing reforms fully commoditize interconnection access. Invest in liquid cooling engineering capabilities to capture premium pricing from GPU cluster tenants as tropical thermal constraints force technology divergence. Threat of emerging sustainable design specialists requires rapid certification investment to defend positioning. For New Entrants and Emerging Players: Differentiate on latency arbitrage by targeting Fortaleza and Recife edge deployments serving African and European routing demand at substantially lower land costs than São Paulo state. White-space exists in pharmaceutical-certified disaster recovery facilities addressing ANVISA data residency requirements. Go-to-market through direct engagement with healthcare procurement committees bypasses incumbent channel control. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure consolidation play because certified engineering talent scarcity and renewable energy certificate portfolio assembly create durable moats for scaled operators. Acquisition targets should exhibit captive fiber networks or Uptime Institute accredited commissioning capabilities. Signal to watch is ANATEL regulatory shifts around data localization mandate expansion beyond financial and healthcare sectors.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Technology Adoption | Direct-to-chip systems enable 50+ kilowatt rack densities for GPU clusters in tropical climates. |
| Renewable Energy Certificate Portfolio Assembly | Hydroelectric credit sourcing satisfies corporate sustainability mandates without on-site solar capital expenditure. |
| Captive Fiber Network Construction | Dark fiber ownership to submarine cable landing stations reduces interdependency on ANATEL-regulated leasing. |
| Certified Engineering Talent Acquisition | Uptime Institute and TIA-942 accredited professionals number fewer than 400 across Brazil, creating staffing bottlenecks. |
| Hyperscale Campus Expansion in Northeast Corridor | Fortaleza and Recife offer 40-60% lower land costs with underutilized transatlantic fiber backbones. |
Methodological Framework
A spread of perspectives from hyperscale facility developers, ANATEL regulatory affairs specialists, financial services IT procurement directors, and precision cooling equipment manufacturers converged on the working assumptions driving capacity and pricing forecasts. Primary fieldwork combined structured interviews with secondary validation through ANATEL licensing databases, ABNT NBR electrical standard filings, and hyperscaler capital expenditure disclosures. Bottom-up facility-level capacity aggregation triangulated against top-down demand segmentation by service type and end-user industry.
Segmentation dimensions modeled include service type, cooling technology architecture, deployment scale tier, and regional fiber accessibility across the analysis window. CAGRs were derived from installed base evolution and committed power allocation pipelines rather than demand-side extrapolation alone. Forecast inputs incorporated ANATEL infrastructure reform implementation timelines and tropical climate cooling load coefficients affecting power usage effectiveness baselines.
Decision-makers should treat outputs as directional under sustained data localization enforcement and copper price stability assumptions; material deviation in regulatory stringency or commodity volatility would warrant model refresh. Recalibration cycles align with material shifts in ANATEL licensing frameworks and renewable energy sourcing obligation developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Indonesia Data Center Power Market
Data Center Infrastructure
Saudi Arabia Data Center Power Market
Data Center Infrastructure
Shanghai Data Center Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
Europe Data Center Construction Market
Data Center Infrastructure
Germany Data Center Physical Security Market
Data Center Infrastructure
Los Angeles Data Center Market
Data Center Infrastructure
Global Terminal Management System Market
Data Center Infrastructure
Converged Infrastructure Management Market
Data Center Infrastructure
Vietnam Data Center Physical Security Market
Data Center Infrastructure
Global Software-Defined Data Center Market
Data Center Infrastructure
Asia-Pacific Data Center Infrastructure Management Market
Data Center Infrastructure
Converged Infrastructure Market
Data Center Infrastructure
Belgium Data Center Rack Market
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
United States Data Center Market