
 Middle East Data Center Physical Security Market | 2026-2036
Middle East Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Data Center Physical Security Market Insights
Saudi Arabia's sovereign-backed data center buildout is realigning supplier priorities across the Gulf. Johnson Controls International leverages its building automation heritage to anchor integrated physical-cyber security suites for hyperscale campuses. Honeywell International Inc competes through deep fire and life safety integration with access control portfolios. Schneider Electric specializes in energy-efficient security infrastructure that reduces operational overhead for desert-climate facilities.
Middle East data center physical security encompasses perimeter barriers, biometric access control, video surveillance with analytics, and intrusion detection systems engineered to protect critical IT infrastructure from unauthorized physical access, environmental threats, and deliberate sabotage. These systems typically operate across redundant layers with mean-time-between-failures exceeding 50,000 hours to ensure continuous protection of facilities housing petabyte-scale storage and sub-10-millisecond latency networks. Surveillance Systems and Access Control represent the largest value pools given their centrality to tier III and tier IV certification requirements, while Biometric Systems and Video Analytics are expanding fastest as operators replace card-based credentials with palm-vein and facial recognition platforms. The Hybrid deployment model is gaining share as operators blend on-premises command centers with cloud-based monitoring for distributed portfolios across multiple Gulf Cooperation Council jurisdictions.
The UAE's Telecommunications and Digital Government Regulatory Authority and Saudi Arabia's National Cybersecurity Authority are mandating physical security audits as a condition for data center licensing, directly shaping procurement specifications for barrier ratings and biometric accuracy thresholds. Compliance with ISO 27001 physical security annexes and local civil defense codes is becoming a non-negotiable gate for operators serving government and BFSI end users. Stakeholders must monitor how evolving national data sovereignty frameworks will redefine cross-border facility standards and supplier qualification criteria.
Market Dynamics
Hyperscale cloud operators across Saudi Arabia and the UAE are consolidating procurement authority for physical security systems, compressing vendor selection cycles from twelve months to under six months as sovereign wealth-backed data center clusters demand integrated perimeter-to-server-room protection suites.
Growth Catalysts
- PDPL Compliance Mandates:Saudi Arabia's Personal Data Protection Law requires biometric access logging for all facilities processing citizen data, forcing Tier III and Tier IV operators to upgrade legacy card-based systems before licensing renewal deadlines.
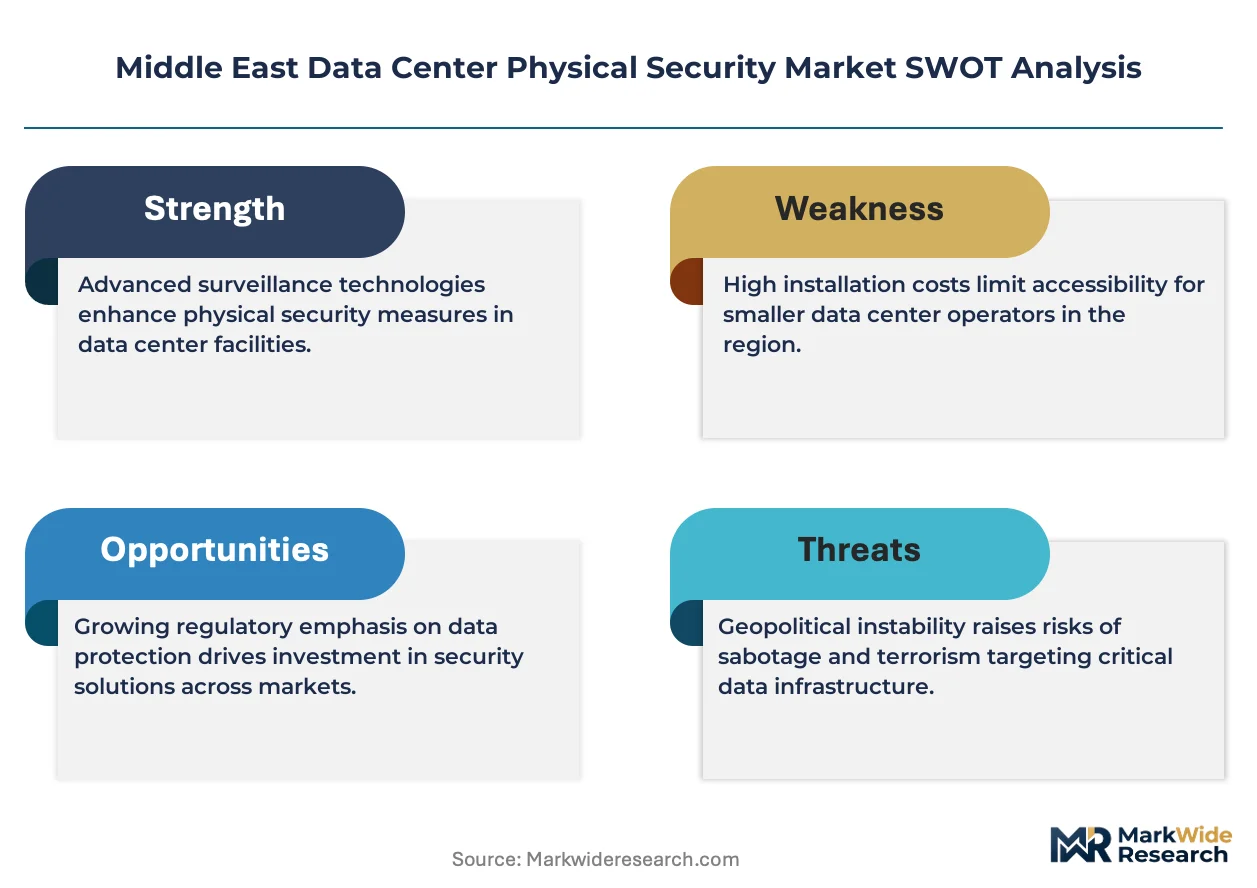
- Desert Climate Engineering:Thermal-hardened video analytics and dust-sealed intrusion sensors are becoming standard specifications as operators build in ambient temperatures exceeding 50°C, creating pull for specialized environmental enclosures.
- Neom and Qiddiya Clusters:Giga-project data center zones in northwest Saudi Arabia are pre-specifying multi-layered physical security architectures, concentrating demand for integrated command-and-control platforms in a single procurement corridor.
Market Restraints
- Import Dependency for Biometric Sensors:Palm-vein and facial recognition hardware relies on concentrated supply from East Asian component manufacturers, exposing operators to shipping delays and currency volatility in AED and SAR terms.
- Skills Bottleneck in Systems Integration:Certified technicians capable of commissioning redundant intrusion detection across 100,000+ square meter campuses command premium wages, inflating deployment timelines for hyperscale footprints.
- Civil Defense Code Fragmentation:Divergent barrier rating requirements between Dubai's Civil Defence and Saudi Arabia's General Directorate of Civil Defence force suppliers to maintain multiple product SKUs for adjacent markets.
Strategic Opportunities
- Kuwait and Bahrain Greenfield Builds:Underpenetrated data center markets in Manama and Kuwait City lack established security vendor relationships, opening first-mover positioning for integrated physical-cyber platform providers.
- Edge Facility Micro-Security:5G-driven edge data centers in secondary UAE emirates require compact, autonomous perimeter protection without on-site guards, creating demand for AI-powered surveillance trailers and solar-powered barriers.
- ISO 27001 Certification Services:Physical security audit preparation is becoming a bundled offering as operators seek single-source accountability for certification gaps in access control documentation and video retention protocols.
Industry Challenges
- Integration Complexity with Building Management Systems:Johnson Controls and Honeywell legacy HVAC platforms use proprietary protocols that conflict with modern IP-based security networks, requiring expensive middleware development for unified dashboards.
- Tier IV Certification Timelines:Uptime Institute's physical security annex reviews add four to six months to facility commissioning, compressing revenue recognition windows for construction contractors and security integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Data Center Physical Security Market |
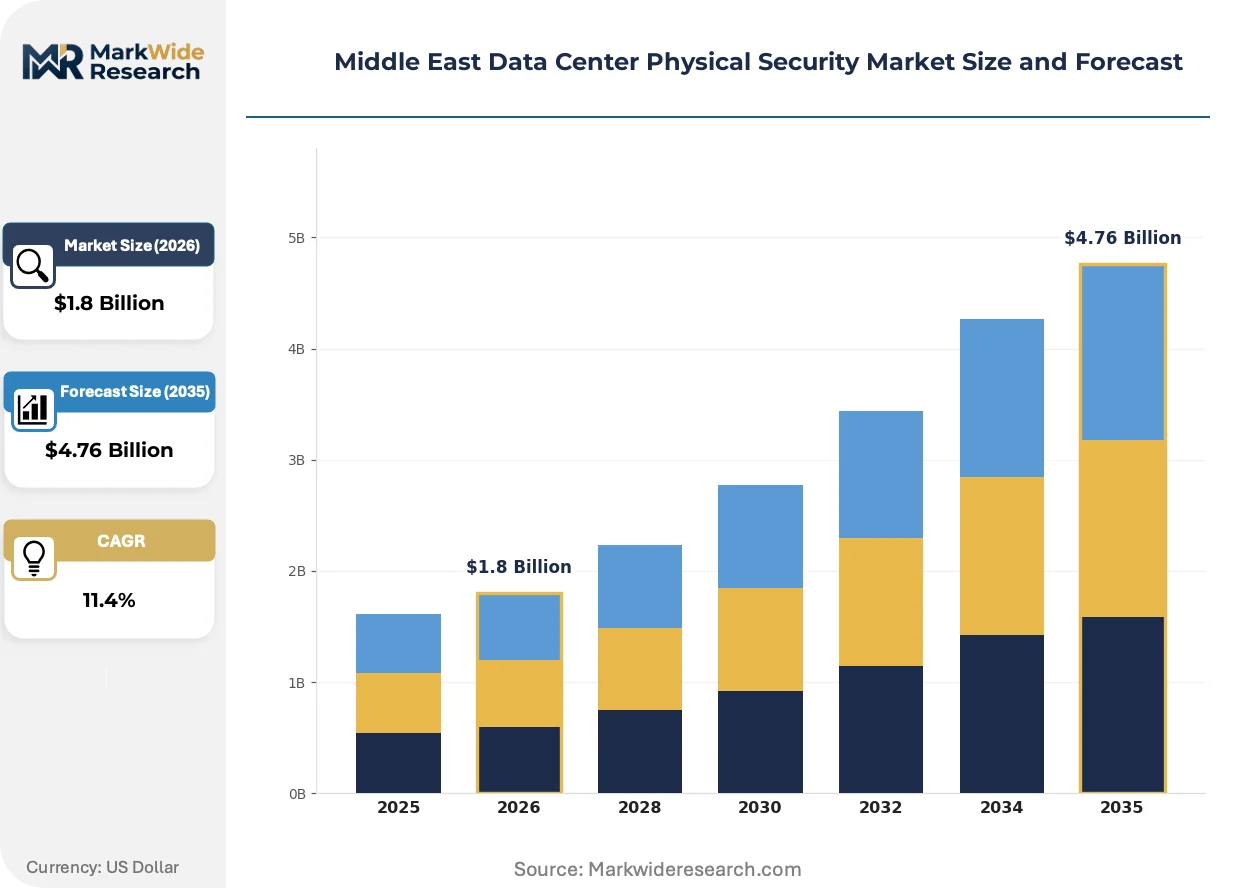
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Security Solution Type: Access Control, Surveillance Systems, Alarms, Barrier Systems Deployment Model: On-Premises, Hybrid, Managed Security, Cloud-Based End User Category: Telecommunication, Government, BFSI, IT Services Technology Type: Biometric Systems, RFID, Video Analytics, Integrated Systems |
| Companies Covered | Honeywell International Inc, Johnson Controls International, Axis Communications AB, BIOS Middle East Group, Schneider Electric, Securitas Technology, Siemens AG, Pacific Control Systems, Bosch Sicherheitssysteme GmbH, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Data Center Physical Security Market Trends and Innovations
Edge computing architectures and sovereign data localization mandates are fragmenting security command structures across distributed facility portfolios, forcing a architectural pivot from centralized guard stations to autonomous perimeter intelligence.
Software-defined physical security is decentralizing control plane functions from on-premises servers to containerized microservices running at the network edge. Hyperscale operators in Riyadh and Dubai are deploying these architectures to eliminate single points of failure across multi-site portfolios. This topology is decentralizing procurement decisions from corporate headquarters to individual facility managers who specify edge-hardened appliances.
Saudi Arabia's National Cybersecurity Authority now mandates physical security audit documentation as a prerequisite for critical infrastructure operator licensing, binding facility commissioning to government inspection timelines. Operators must demonstrate 90-day video retention and biometric false-accept rates below 0.001% to obtain operational permits. Tier IV aspirants in Riyadh's King Abdullah Financial District are front-loading these compliance costs into construction budgets to avoid licensing delays.
Security-as-a-service contracting is displacing capital purchase models for mid-sized colocation operators in Abu Dhabi and Jeddah. These buyers now prefer monthly per-rack fees covering hardware, monitoring, and maintenance rather than seven-year depreciation cycles. The shift is most visible among BFSI tenants who demand operational expenditure treatment for compliance-driven security upgrades without balance sheet impact.
Middle East Data Center Physical Security Market Segmentation
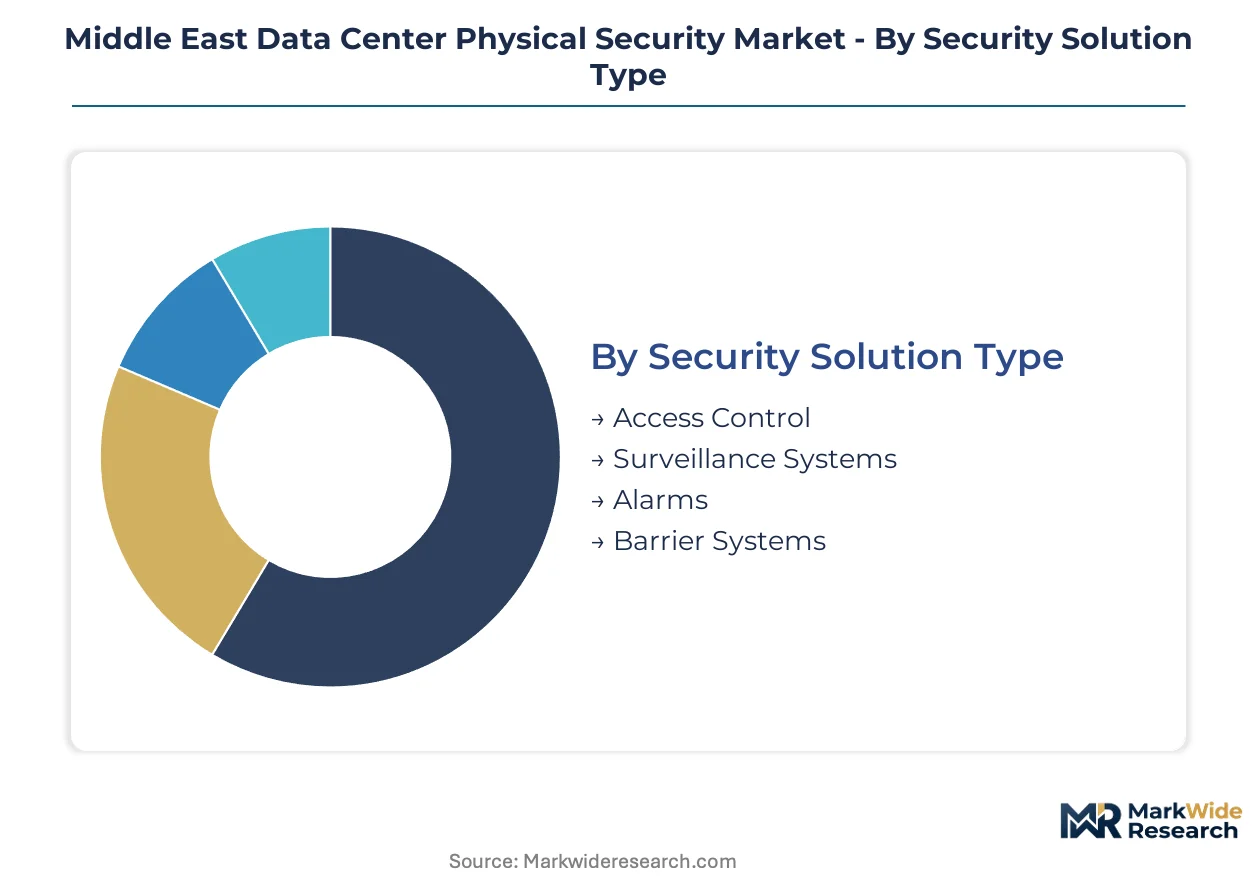
Segmentation in the Middle East data center physical security market reveals how procurement specifications diverge between hyperscale cloud campuses and sovereign wealth-backed facilities. Understanding these divides helps suppliers align engineering resources with the compliance and climate pressures reshaping Riyadh and Dubai procurement cycles.
Security Solution Type:
Standardization dominates perimeter barriers and intrusion alarms, while access control and surveillance systems require heavy customization for tier III and tier IV certification pathways.
- Access Control:Multi-factor biometric authentication with palm-vein and facial recognition platforms. Demand concentrates in Riyadh's King Abdullah Financial District where PDPL mandates force Tier III operators to replace legacy card systems before licensing renewal deadlines.
- Surveillance Systems:Thermal-hardened video analytics with 90-day retention protocols. Dubai's sovereign wealth-backed clusters drive procurement for dust-sealed enclosures rated above 50°C ambient operation.
- Alarms:Redundant intrusion detection with mean-time-between-failures exceeding 50,000 hours for continuous protection of petabyte-scale storage facilities.
- Barrier Systems:K-rated vehicle barriers and pedestrian turnstiles engineered to civil defense specifications diverging between Saudi Arabia's General Directorate of Civil Defence and Dubai Civil Defence.
Most installed capacity flows through Surveillance Systems. Expansion is steepest in Access Control as biometric logging becomes a licensing prerequisite.
Deployment Model:
Capital intensity separates on-premises and hybrid architectures from managed and cloud-based alternatives, with BFSI tenants increasingly favoring operational expenditure treatment.
- On-Premises:Dedicated command centers with redundant servers for sub-10-millisecond latency networks. Tier IV aspirants in Neom and Qiddiya pre-specify these architectures to avoid single points of failure.
- Hybrid:Blended on-premises command centers with cloud-based monitoring for distributed portfolios across multiple Gulf Cooperation Council jurisdictions. Abu Dhabi and Jeddah colocation operators favor this model for compliance-driven upgrades without balance sheet impact.
- Managed Security:Monthly per-rack fees covering hardware, monitoring, and maintenance displacing seven-year depreciation cycles for mid-sized operators.
- Cloud-Based:Containerized microservices running at the network edge, decentralizing control plane functions for multi-site hyperscale portfolios.
Hybrid deployments carry the heaviest current investment. Managed Security is climbing the fastest as security-as-a-service contracts displace capital purchase models.
End User Category:
Compliance stringency varies sharply across this category, with government and BFSI segments facing audit mandates that IT services and telecommunication providers escape.
- Government:Facilities processing citizen data require biometric access logging and 90-day video retention under Saudi Arabia's National Cybersecurity Authority licensing prerequisites.
- BFSI:Financial institutions demand ISO 27001 physical security annex compliance with false-accept rates below 0.001% for biometric systems.
- Telecommunication:5G-driven edge data centers in secondary UAE emirates require compact autonomous perimeter protection without on-site guards.
- IT Services:Hyperscale cloud operators consolidating procurement authority for integrated perimeter-to-server-room protection suites.
Government facilities anchor current procurement volume. BFSI is gaining share fastest as audit preparation services bundle with security hardware.
Technology Type:
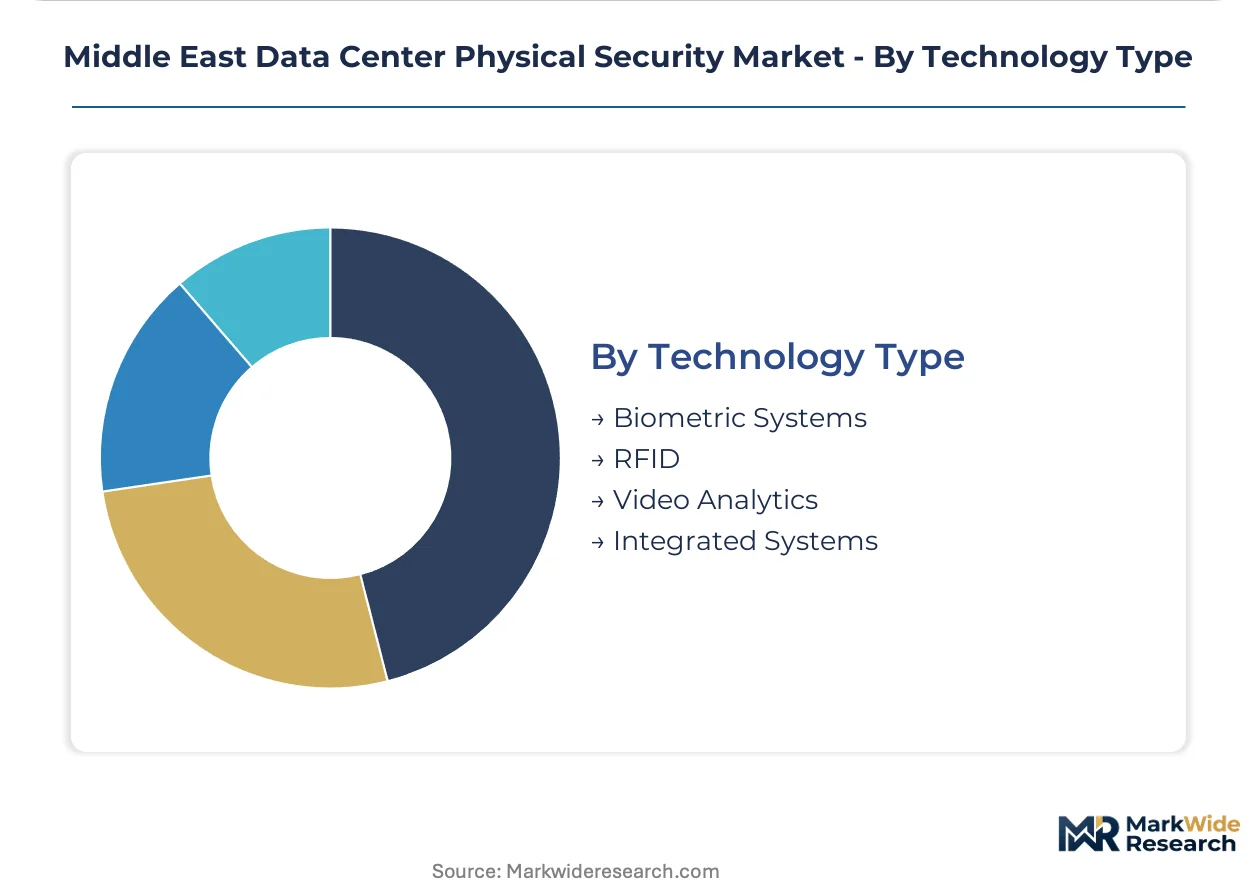
Integration complexity separates legacy RFID and standalone biometric systems from unified platforms that merge video analytics with access control.
- Biometric Systems:Palm-vein and facial recognition platforms replacing card-based credentials. Import dependency on East Asian component manufacturers creates supply vulnerability for Saudi and UAE operators.
- Integrated Systems:Unified command-and-control platforms merging HVAC, fire safety, and security networks. Johnson Controls and Honeywell legacy building automation heritage anchors this segment for hyperscale campuses.
- Video Analytics:AI-powered surveillance with thermal hardening for desert climate operation.
- RFID:Legacy card-based credentials facing forced obsolescence under PDPL biometric mandates.
Integrated Systems dominate installed base. Biometric Systems show the steepest expansion trajectory as operators replace card-based credentials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing facility investment maps across the Gulf. Operators migrate toward jurisdictions with faster licensing timelines and harmonized civil defense codes, compressing procurement cycles for integrated security platforms.
Saudi Arabia
Neom and Qiddiya giga-projects are pre-specifying multi-layered physical security architectures for data center zones. The National Cybersecurity Authority mandates biometric access logging and 90-day video retention as licensing prerequisites. Riyadh's King Abdullah Financial District concentrates Tier IV aspirants front-loading compliance costs to avoid commissioning delays.
United Arab Emirates
Dubai's sovereign wealth-backed clusters drive procurement for dust-sealed surveillance enclosures rated above 50°C ambient operation. The Telecommunications and Digital Government Regulatory Authority requires physical security audits for data center licensing. Abu Dhabi colocation operators favor hybrid deployment models to convert capital expenditure into operational expenditure treatment.
Qatar
Financial sector data localization requirements are stimulating greenfield facility construction in Doha's Lusail district. The national communications regulator enforces critical infrastructure protection standards for facilities processing citizen financial data. New entrant operators lack established vendor relationships, opening first-mover positioning for integrated platform providers.
Kuwait
Underpenetrated data center capacity in Kuwait City lacks incumbent security vendor lock-in. The central bank's data governance circulars are tightening physical access requirements for financial institutions. Planned sovereign wealth-backed technology zones are specifying redundant intrusion detection systems for hyperscale footprints.
Bahrain
Manama's emerging fintech hub is attracting regional cloud operators seeking Gulf Cooperation Council jurisdictional diversification. The national cybersecurity framework mandates physical security documentation for critical infrastructure classification. Secondary market status enables faster procurement decisions without legacy system migration burdens.
Middle East Data Center Physical Security Market Competitive Landscape
North American building automation conglomerates anchor one tier; European industrial technology specialists hold integrated energy-security positioning. The vendor base stratifies across three tiers: full-stack building systems integrators, standalone security hardware manufacturers, and regional systems integration services. Two dominant competitive moves are reshaping positioning: technology licensing partnerships to bypass import dependency for biometric sensors, and strategic capacity expansion into underpenetrated Kuwaiti and Bahraini markets.
Within the building systems integrator tier, Johnson Controls International and Honeywell International Inc exemplify archetypes leveraging HVAC and fire safety heritage to anchor physical-cyber security suites. Schneider Electric occupies a position specializing in energy-efficient security infrastructure for desert-climate facilities. These three companies represent contrasting approaches to the convergence of operational technology and physical security networks across hyperscale campuses.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Johnson Controls International |
| Axis Communications AB |
| BIOS Middle East Group |
| Schneider Electric |
| Securitas Technology |
| Siemens AG |
| Pacific Control Systems |
| Bosch Sicherheitssysteme GmbH |
| Others |
Pricing and Supply Chain Analysis
Tier IV certification premiums bifurcate procurement budgets from Tier III commodity specifications, concentrating supplier pricing power in Riyadh's King Abdullah Financial District while compressing margins for standardized perimeter hardware across secondary Gulf markets. This divergence feeds directly into sourcing strategies: premium-tier buyers accept extended lead times for biometric sensors with sub-0.001% false-accept rates, while price-sensitive operators in Kuwait and Bahrain prioritize locally warehoused barrier systems with faster civil defense approval cycles.
Pricing Analysis
Distributor margins of 15-22% separate direct hyperscale contracts from channel-mediated colocation sales. Project-based pricing dominates integrated command-and-control platforms, while security-as-a-service contracts convert capital expenditure into monthly per-rack operational expenditure for Abu Dhabi and Jeddah mid-tier operators. Price differentiation hinges on ISO 27001 certification bundling and thermal-hardening specifications for 50°C ambient operation. Cost compression in standardized barrier systems intensifies as Saudi and UAE domestic assembly facilities expand capacity. Government and BFSI segments show lowest price sensitivity given compliance-driven procurement mandates; IT services providers exhibit highest elasticity, delaying upgrades until licensing deadlines force action.
Supply Chain Analysis
Saudi Arabia's Local Content and Government Procurement Authority mandates are reshaping sourcing patterns, requiring 30% domestic value-add for critical infrastructure security contracts. Palm-vein and facial recognition hardware concentrates in South Korea and Japan; thermal-hardened video analytics enclosures originate from German and US industrial suppliers. Raw material dependencies include rare-earth magnets for biometric sensor motors, aluminum extrusions for desert-rated enclosures, and specialized optical glass for thermal imaging lenses. Single-source vulnerability concentrates in East Asian component manufacturers, exposing operators to shipping delays and currency volatility in AED and SAR terms. Distribution runs through Dubai-based regional hubs serving Saudi Arabia, UAE, Qatar, and Bahrain with 48-hour fulfillment windows for emergency replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East data center physical security market functions as a stable compounder anchored by irreversible regulatory mandates: Saudi Arabia's National Cybersecurity Authority and the UAE's Telecommunications and Digital Government Regulatory Authority have embedded physical security audits as licensing prerequisites, ensuring replacement demand cycles regardless of macroeconomic volatility.
For Market Incumbents: Deepen vertical integration into biometric sensor assembly to bypass East Asian import dependency and compress commissioning timelines for hyperscale campuses. Expand certified technician training capacity in Riyadh and Dubai to capture premium deployment margins currently lost to skills bottlenecks. Defend against emerging European specialists by anchoring ISO 27001 certification services as bundled offerings that lock in multi-year maintenance contracts. For New Entrants and Emerging Players: Capture first-mover positioning in Kuwait City and Manama where incumbent vendor relationships remain underdeveloped and procurement decisions lack legacy system migration burdens. Target 5G edge facility micro-security in secondary UAE emirates with solar-powered autonomous surveillance trailers and compact barrier systems designed for guardless operation. Lead with security-as-a-service contracting to convert capital-averse colocation operators into recurring revenue streams without balance sheet impact. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional systems integrators lack scale to meet hyperscale procurement consolidation timelines. The 5-10 year viability window favors platforms with integrated physical-cyber capabilities and established civil defense code relationships across multiple Gulf Cooperation Council jurisdictions. Acquisition targets should demonstrate certified technician pipelines and technology licensing partnerships that reduce biometric hardware import exposure. Monitor Saudi Arabia's Local Content and Government Procurement Authority enforcement intensity as the signal for domestic assembly facility valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Hardware Localization Partnership | Technology licensing with South Korean component manufacturers reduces Saudi import dependency and accelerates civil defense approval cycles. |
| Certified Technician Academy Expansion | Training capacity in Riyadh and Dubai captures premium deployment margins currently lost to systems integration skills bottlenecks. |
| ISO 27001 Audit Service Bundling | Certification preparation services lock BFSI and government clients into multi-year hardware maintenance and software update contracts. |
| Edge Facility Micro-Security Platform Launch | AI-powered surveillance trailers address 5G-driven demand in secondary UAE emirates without on-site guard requirements. |
| Kuwait and Bahrain Greenfield Market Entry | First-mover positioning in underpenetrated markets avoids incumbent vendor displacement costs and legacy system migration burdens. |
Research Methodology
Direct dialogue with data center facility managers, physical security systems integrators, civil defense compliance officers, and hyperscale cloud procurement leads grounded this analysis in operational reality. Secondary validation drew from Saudi National Cybersecurity Authority licensing guidelines, UAE Telecommunications and Digital Government Regulatory Authority audit protocols, Uptime Institute Tier certification documentation, and Gulf Cooperation Council customs trade data for security hardware imports. Bottom-up facility counts and top-down sovereign wealth fund capital deployment tracking were triangulated to anchor market sizing.
Bottom-up modeling aggregated individual facility security capital expenditure profiles across deployment model, tier certification aspiration, and end-user compliance stringency. Top-down verification cross-referenced hyperscale operator announced capacity pipelines against estimated per-megawatt physical security allocation norms. Segmentation dimensions included security solution type, deployment architecture, end-user category, and technology integration complexity. CAGRs were derived from facility commissioning timelines and regulatory-driven replacement cycle compression observed in PDPL-mandated biometric access control upgrades.
Regulatory enforcement intensity variations, East Asian component supply disruptions, and civil defense code harmonization failures across Saudi Arabia and the UAE are the dominant revision risks that could accelerate or delay procurement recognition. Forecasts reflect documented assumptions regarding sovereign wealth fund commitment continuity and hyperscale operator market entry pacing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
France Data Center Rack Market
Data Center Infrastructure
Germany Data Center Physical Security Market
Data Center Infrastructure
Asia-Pacific Hyperscale Data Center Market
Data Center Infrastructure
Global Data Center Rack Server Market
Data Center Infrastructure
Long Term Data Retention Solutions Market
Data Center Infrastructure
Data Center Rack Power Distribution Unit Market
Data Center Infrastructure
Indonesia Data Center Construction Market
Data Center Infrastructure
Norway Data Center Construction Market
Data Center Infrastructure
Global Micro Mobile Data Center Market
Data Center Infrastructure
Canada Data Center Rack Market
Data Center Infrastructure
Composable Infrastructure Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
Data Center Virtualization Market
Data Center Infrastructure
Middle East Data Center Market
Data Center Infrastructure
Data Center Fabric Market