
 Nigeria Data Center Physical Security Market | 2026-2036
Nigeria Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Data Center Physical Security Market Insights
Project finance tied to power purchase agreements and equipment leasing is fragmenting capital deployment across Nigeria's data center security sector. Schneider Electric SE leverages its integrated power and security portfolio to anchor large-scale facility contracts in Lagos. Axis Communications AB competes through video analytics specialization, while Hikvision Digital Technology sustains cost advantages in surveillance hardware for modular deployments.
Nigeria data center physical security encompasses perimeter barriers, biometric authentication, video surveillance, and environmental threat detection designed to protect critical IT infrastructure from unauthorized physical access and operational disruption. Systems typically integrate IP cameras with analytics engines, card readers, and intrusion sensors operating across layered security zones. Surveillance Systems dominates procurement volumes as banks and government agencies mandate 24/7 visual monitoring, while Biometric Access represents the fastest-growing technology segment as fingerprint and facial recognition replace legacy card systems. Colocation Centers concentrate margin pools where operators bundle physical security into premium service tiers.
The Central Bank of Nigeria issues data center resilience directives that mandate physical access controls for financial institutions, while the Nigeria Communications Commission enforces infrastructure protection standards for telecom-linked facilities. BIS-equivalent certification requirements from the Standards Organisation of Nigeria shape product eligibility for government contracts. Stakeholders must monitor how evolving national cybersecurity frameworks integrate physical and logical security compliance obligations.
Market Dynamics
The Central Bank of Nigeria's cashless policy mandates are compressing procurement timelines for Tier III facilities, forcing simultaneous upgrades to power infrastructure and layered physical security systems rather than sequential deployment.
Growth Catalysts
- CBN Cybersecurity Directives:The Central Bank of Nigeria mandates physical access controls for all financial data centers, compelling Lagos and Abuja banks to harden perimeter barriers and biometric authentication layers.
- Colocation Premium Tiering:Data center operators in Lagos State bundle multi-zone surveillance and facial recognition into premium service contracts, attracting foreign cloud providers seeking compliant hosting.
- Facial Recognition Maturation:Nigerian banks are replacing legacy card readers with facial recognition terminals at mantrap entrances, reducing tailgating incidents while accelerating throughput during shift changes.
Market Restraints
- Import Duty Volatility:Fluctuating tariffs on IP cameras and biometric sensors from Asian manufacturing hubs inflate total cost of ownership for modular deployments outside Lagos.
- Skilled Installer Scarcity:Certified systems integrators capable of commissioning multi-vendor security platforms concentrate in Lagos and Abuja, leaving Port Harcourt and Kano facilities dependent on fly-in technicians.
- Generator Dependency:Unreliable grid power forces security system designers to overspecify UPS capacity, diverting capital from analytics software toward power conditioning hardware.
Strategic Opportunities
- Rivers State Industrial Zones:New oil and gas data processing clusters near Port Harcourt lack hardened security infrastructure, creating first-mover advantage for integrated physical-logical security providers.
- Standards Organisation of Nigeria Certification:BIS-equivalent product certification requirements for government contracts favor local assembly partnerships, reducing import lead times for surveillance hardware.
- AI-Video Convergence:Behavioral analytics engines layered onto existing camera networks enable threat pre-detection without forklift infrastructure replacement, opening retrofit revenue in legacy Tier II facilities.
Industry Challenges
- Integration Complexity:Financial institutions running 15-year-old access control databases face data migration failures when connecting to modern biometric APIs, requiring parallel system operation during transition windows.
- Certification Bottlenecks:SON product approval timelines stretch to eight months for facial recognition terminals, delaying revenue recognition on signed contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Data Center Physical Security Market |
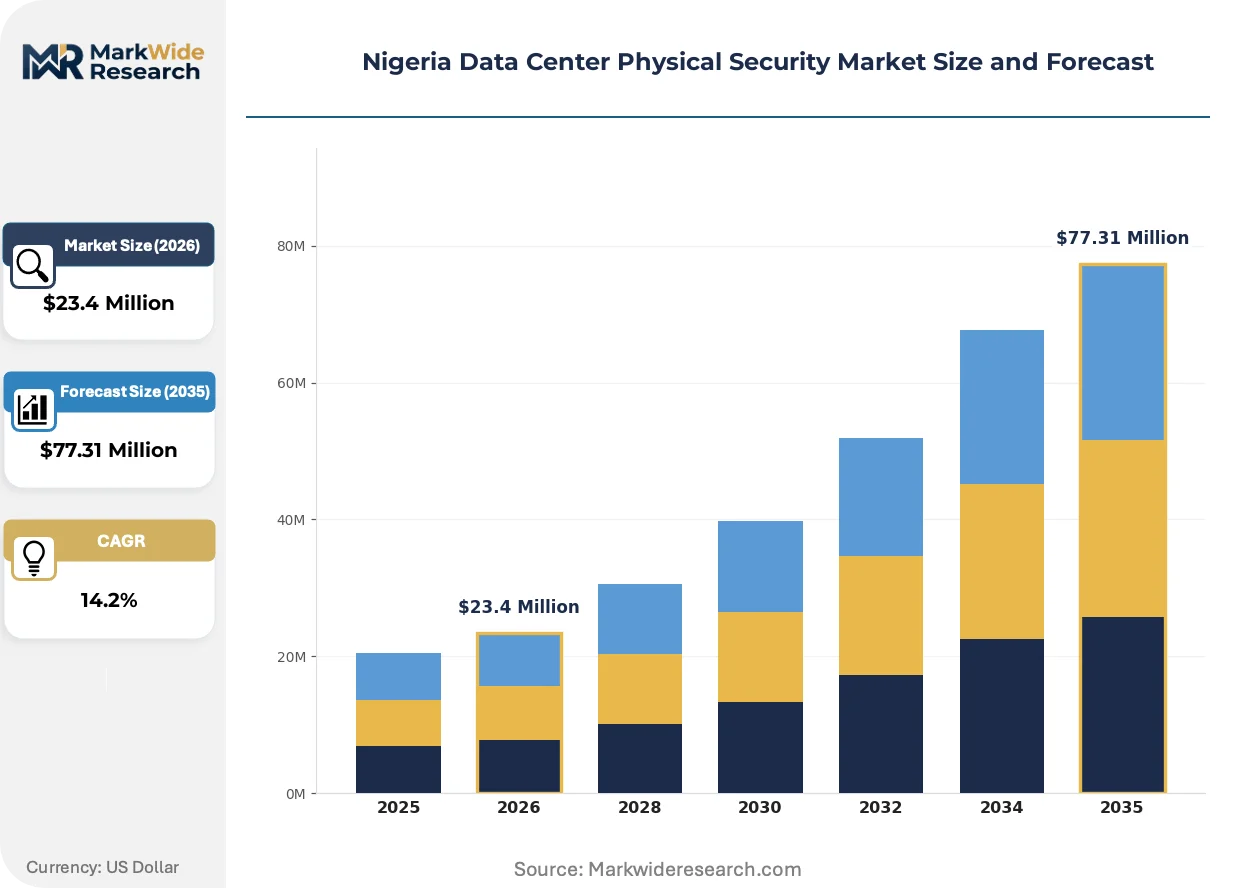
| Market Size in 2026 | $23.4 Million |
| Market Size in 2035 | $77.31 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Security Type: Surveillance Systems, Access Control, Perimeter Security, Fire Safety Infrastructure Type: Modular Data Centers, Large Scale Facilities, Tier III Facilities, Colocation Centers Technology: Biometric Access, Video Analytics, Intrusion Detection, Environmental Monitoring End User: Government, Education, Finance, Healthcare |
| Companies Covered | Axis Communications AB, Bosch Sicherheitssysteme GmbH, Schneider Electric SE, Assa Abloy AB, Suprema Inc., Hikvision Digital Technology, Dahua Technology, Johnson Controls International, Siemens AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Data Center Physical Security Market Trends and Innovations
Video analytics engines are compressing the distinction between surveillance and access control, enabling Nigerian data centers to reduce vendor count while tightening security zone granularity. Three developments dominate procurement conversations.
Edge-based facial recognition is collapsing the architecture of data center entry systems. These terminals process biometric templates locally rather than transmitting raw images to central servers. Tier III facilities in Lagos are adopting them at mantrap chokepoints to eliminate network latency during authentication. The technology is collapsing the traditional separation between physical security and identity management functions, forcing CISOs to consolidate budget authority.
The Central Bank of Nigeria's data center resilience directives are tightening physical-logical security coupling requirements. Banks must now demonstrate that access log anomalies trigger automatic logical session termination. This regulatory pressure is accelerating demand for unified security platforms that share event data across previously siloed systems. Tier II facilities attempting certification upgrades represent the most affected segment, often engaging consultants to map compliance gaps.
Consumption patterns among Nigerian banks are pivoting toward security-as-a-service models that transfer capex to colocation operators. Rather than owning and depreciating biometric infrastructure, financial institutions now specify performance metrics in hosting contracts. This shift is visible most acutely among mid-tier banks in Abuja, where compliance pressures outstrip internal technical staffing capacity. Operators responding with bundled offerings capture longer contract tenures and higher switching costs.
Nigeria Data Center Physical Security Market Segmentation
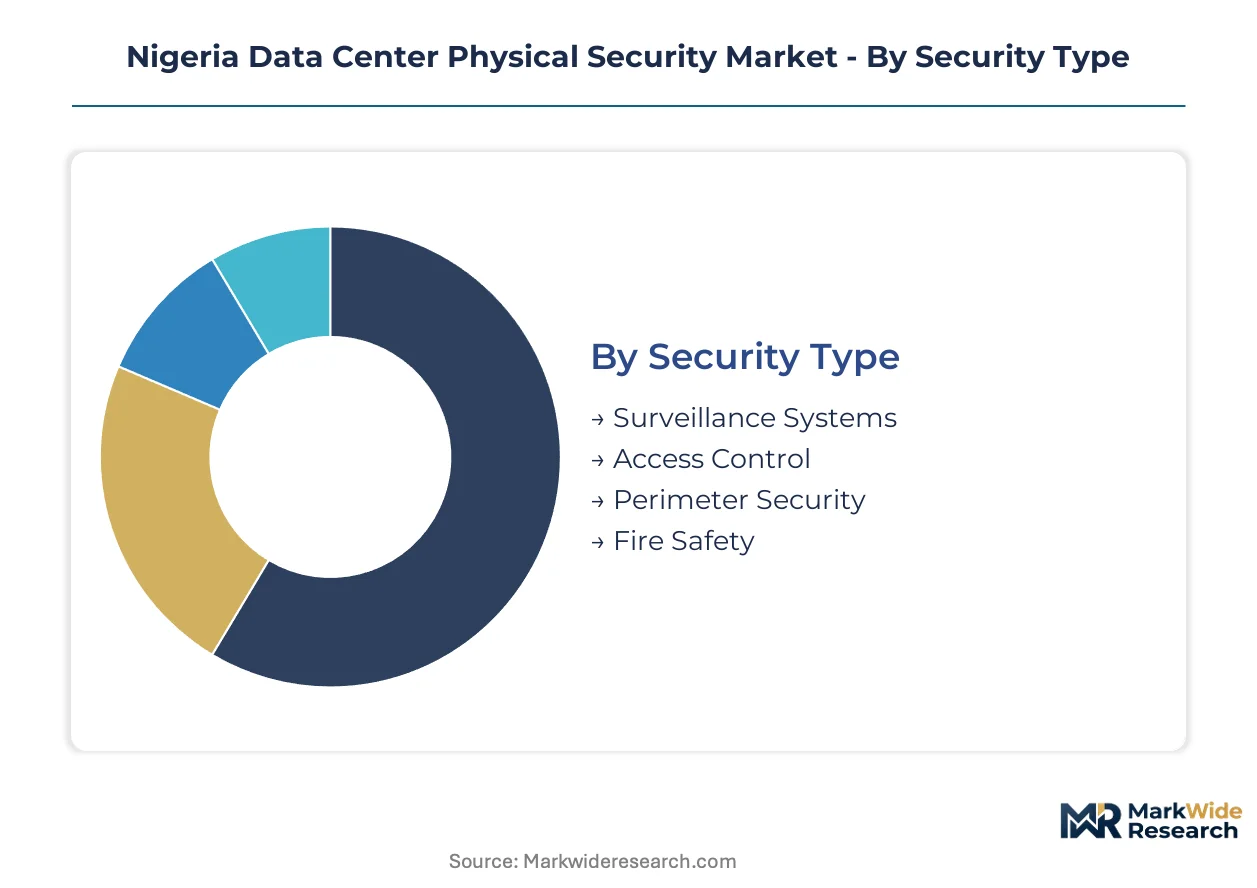
Physical security procurement in Nigerian data centers fragments across four structural dimensions. Each category reflects distinct maintenance cycles, specification requirements, and buyer decision-making authority that shape vendor engagement strategies.
Security Type:
After-sales service intensity varies sharply across security layers, with surveillance systems demanding continuous calibration and perimeter installations requiring episodic structural maintenance.
- Surveillance Systems:IP camera networks with edge-based analytics engines dominate procurement volumes across Lagos Tier III facilities. Financial institutions in Abuja mandate 24/7 visual monitoring with centralized command center integration, compressing installation timelines.
- Access Control:Biometric readers and card-based entry systems anchor mantrap configurations at facility perimeters. Colocation operators bundle multi-factor authentication into premium service tiers, capturing longer contract tenures from mid-tier banks.
- Perimeter Security:Bollards, fencing, and vehicle barriers protect against forced entry.
- Fire Safety:Suppression systems and early detection sensors safeguard critical infrastructure.
Surveillance Systems holds the largest share; momentum sits with Access Control.
Infrastructure Type:
Facility scale determines security architecture complexity, with modular deployments favoring standardized kits and hyperscale sites requiring custom-engineered zone layering.
- Colocation Centers:Multi-tenant facilities in Lagos State absorb the bulk of integrated security procurement. Operators competing for foreign cloud provider contracts differentiate through facial recognition bundling and compliance certification support.
- Tier III Facilities:Certified uptime infrastructure demands redundant security zones with failover authentication paths. The Central Bank of Nigeria's resilience directives compel banks to harden these facilities with biometric-logical security coupling.
- Modular Data Centers:Prefabricated units deploy rapid-security kits for edge locations.
- Large Scale Facilities:Hyperscale campuses require perimeter-to-rack security orchestration.
Colocation Centers command the deepest vendor relationships; Tier III Facilities face the steepest compliance-driven expansion trajectory.
Technology:
Technology maturity curves separate proven deployments from experimental pilots, with video analytics sitting at inflection between early adoption and mainstream procurement.
- Biometric Access:Fingerprint and facial recognition terminals are displacing legacy card readers at mantrap entrances. Nigerian banks prioritize throughput acceleration during shift changes while reducing tailgating incidents.
- Video Analytics:Behavioral detection engines enable threat pre-detection on existing camera networks. Retrofit opportunities in legacy Tier II facilities bypass forklift infrastructure replacement.
- Intrusion Detection:Sensor networks and alarm systems provide perimeter breach notification.
- Environmental Monitoring:Temperature, humidity, and leak detection sensors protect equipment integrity.
Biometric Access leads deployment volume; Video Analytics is climbing the fastest.
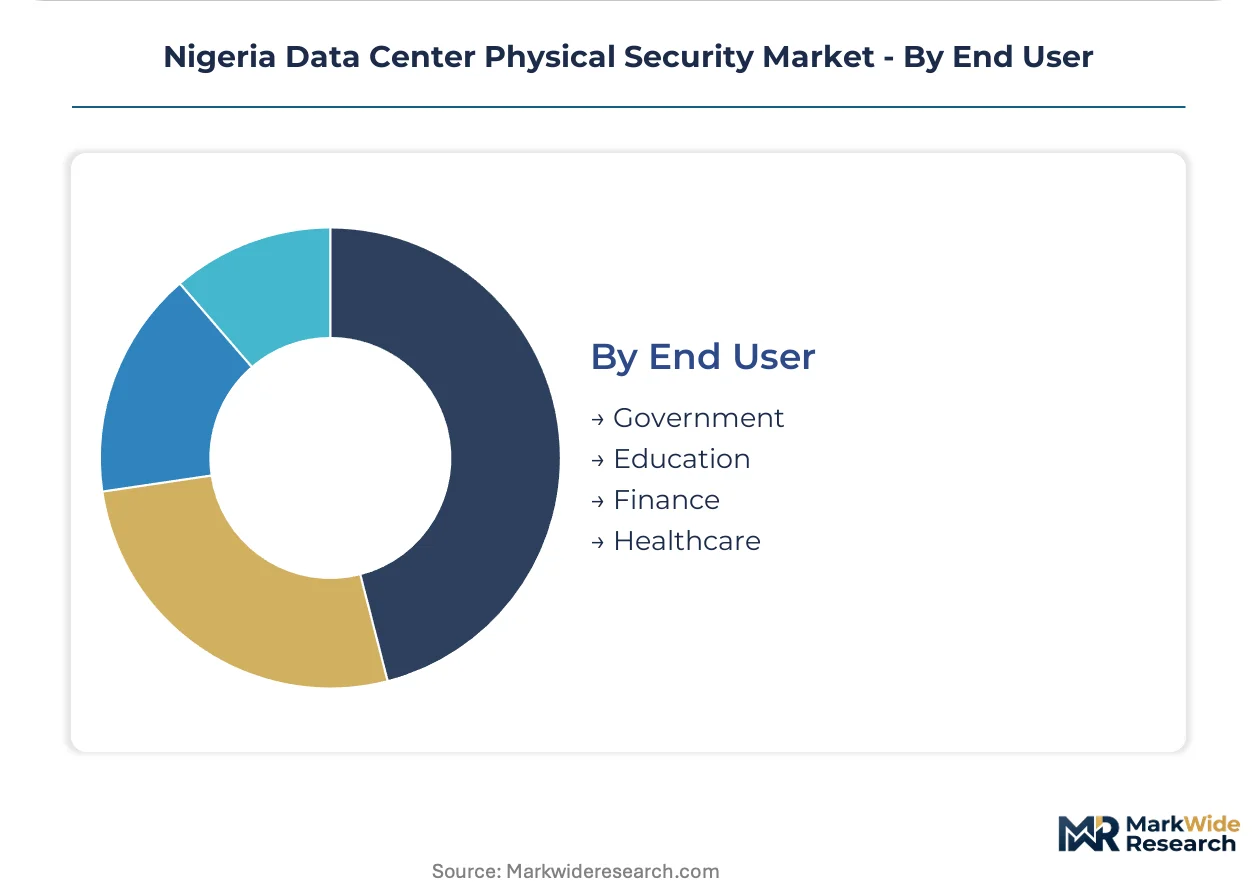
End User:
Buyer sophistication and compliance pressure create distinct procurement patterns across institutional categories.
- Finance:Banks and insurance carriers face the most stringent physical access mandates from the Central Bank of Nigeria. Cashless policy acceleration forces simultaneous power and security upgrades rather than sequential deployment.
- Government:Federal and state agencies require BIS-equivalent certification through the Standards Organisation of Nigeria. Eight-month product approval timelines for facial recognition terminals delay revenue recognition on signed contracts.
- Healthcare:Medical data protection needs drive patient-record facility hardening.
- Education:University research data centers represent emerging demand with lighter compliance burdens.
Finance captures the highest security spend per rack; Government contracts carry the longest sales cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Lagos State where colocation operators bundle premium security tiers, while Port Harcourt and Kano facilities absorb 15-20% cost premiums due to skilled installer scarcity and fly-in technician dependency.
Lagos State
Financial institutions and foreign cloud providers anchor demand for Tier III facilities with multi-zone surveillance and facial recognition mantraps. The Central Bank of Nigeria's cybersecurity directives compel banks to harden perimeter barriers and biometric authentication layers simultaneously. Lekki and Ikoyi clusters absorb the bulk of integrated security procurement as colocation operators compete for compliant hosting contracts.
Federal Capital Territory
Abuja hosts government data centers requiring BIS-equivalent certification through the Standards Organisation of Nigeria for all facial recognition terminals. Federal agencies mandate eight-month product approval timelines that delay revenue recognition on signed security contracts. The Garki and Wuse districts concentrate Tier II facility upgrades attempting certification compliance.
Rivers State
Oil and gas data processing clusters near Port Harcourt lack hardened security infrastructure, creating first-mover advantage for integrated physical-logical security providers. Generator dependency forces UPS overspecification that diverts capital from analytics software toward power conditioning hardware. Onne and Trans Amadi industrial zones represent greenfield deployment opportunities.
Kano State
Import duty volatility on IP cameras and biometric sensors from Asian manufacturing hubs inflates total cost of ownership for modular deployments in this northern hub. Certified systems integrators capable of commissioning multi-vendor security platforms remain scarce, forcing facility operators into maintenance contracts with Lagos-based technicians. Dawanau and Sharada industrial districts drive modest Tier II facility expansion.
Nigeria Data Center Physical Security Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying surveillance hardware and biometric sensors. The vendor base separates into three strategic archetypes: integrated power-security conglomerates anchoring large-scale facility contracts, video analytics specialists competing on behavioral detection capabilities, and cost-optimized surveillance hardware fabricators serving modular deployments. Dominant competitive moves include local assembly partnerships to reduce import lead times and AI-video convergence offerings that enable retrofit revenue in legacy facilities.
Among the integrated platform tier, Schneider Electric SE leverages its power portfolio to anchor Lagos facility contracts, while Axis Communications AB exemplifies the video analytics specialization archetype. Hikvision Digital Technology occupies the cost-optimized hardware position for surveillance deployments. These three anchors represent distinct competitive vectors: power-security integration, analytics-driven differentiation, and volume-scale manufacturing efficiency.
| Leading Market Players |
|---|
| Axis Communications AB |
| Bosch Sicherheitssysteme GmbH |
| Schneider Electric SE |
| Assa Abloy AB |
| Suprema Inc. |
| Hikvision Digital Technology |
| Dahua Technology |
| Johnson Controls International |
| Siemens AG |
| Others |
Pricing and Supply Chain Analysis
Undercapacity among certified systems integrators in Port Harcourt and Kano compresses pricing power toward Lagos-based operators, while import duty volatility on Asian-manufactured biometric sensors forces procurement teams to front-load inventory commitments and absorb working capital strain.
Pricing Analysis
Configured-to-order pricing for integrated mantrap systems with facial recognition terminals commands a 40-50% premium over standard surveillance kit deployments. The dominant structure runs project-based with hardware-software bundling, where certification grade from the Standards Organisation of Nigeria and geographic delivery cost to northern states drive price differentiation. Pricing pressure stems from generator dependency forcing UPS overspecification that diverts budget from analytics software. Mid-tier banks in Abuja exhibit highest price sensitivity as compliance pressures outstrip internal technical staffing capacity.
Supply Chain Analysis
Tariff exposure between Nigeria and Asian manufacturing hubs dominates supply chain risk calculations for biometric sensor procurement. Hardware concentration centers on China, South Korea, and Taiwan for IP cameras, facial recognition terminals, and intrusion detection sensors. Component dependencies include CMOS image sensors, edge AI processors, and specialized biometric algorithm chipsets. Single-source vulnerability runs through Hikvision and Dahua for cost-optimized surveillance hardware. Distribution runs through Lagos-based systems integrators who bundle installation and maintenance into project contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified technicians capable of commissioning multi-vendor security platforms across Nigeria's northern and eastern regions creates structural bottlenecks that reshape competitive positioning for vendors with fly-in service capabilities.
For Market Incumbents: Build switching-cost moats through long-term maintenance contracts that lock in colocation center operators across Lagos State. Anchor large-scale facility contracts by integrating power infrastructure expertise with layered physical security deployment, compressing vendor count for Tier III facility upgrades. Defend against emerging video analytics specialists by embedding behavioral detection engines into existing camera network retrofits. For New Entrants and Emerging Players: Rivers State oil and gas data processing clusters near Port Harcourt offer the most penetrable geography for integrated physical-logical security providers lacking established Lagos presence. Target greenfield deployments in Onne and Trans Amadi industrial zones where generator dependency has delayed security hardening. Enter through AI-video convergence offerings that enable threat pre-detection without forklift infrastructure replacement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across Tier III certification upgrade projects as biometric-logical security coupling mandates from the Central Bank of Nigeria force simultaneous infrastructure deployment. Acquisition targets should display local assembly partnerships that reduce Standards Organisation of Nigeria certification lead times. Monitor facial recognition terminal approval velocity as the signal indicating regulatory friction easing or tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Partnership | Reduces SON certification lead times from eight months for facial recognition hardware. |
| AI-Video Convergence Offering | Enables retrofit revenue in legacy Tier II facilities without infrastructure replacement. |
| Power-Security Integration | Captures simultaneous CBN-mandated upgrades diverting capital from standalone vendors. |
| Colocation Premium Tiering | Bundles multi-zone surveillance into contracts attracting foreign cloud providers. |
| Certification Support Service | Differentiates operators competing for BIS-equivalent government contract eligibility. |
Research Methodology
A spread of perspectives from data center operations directors, security systems integrators, financial institution compliance officers, and Standards Organisation of Nigeria certification specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through Central Bank of Nigeria cybersecurity directives, Nigeria Communications Commission infrastructure standards, and customs import records for surveillance hardware. Bottom-up facility counts triangulated against top-down security spend estimates from financial sector disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include security type, infrastructure tier, technology maturity curve, and end-user compliance intensity. CAGRs derived from facility expansion pipelines weighted by procurement timing compression from regulatory mandates. Industry-specific inputs incorporated generator dependency ratios and skilled technician density by state.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese surveillance hardware manufacturers or rapid SON certification streamlining would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Nigeria Data Center Market
Data Center Infrastructure
Next Generation Data Center Market
Data Center Infrastructure
Malaysia Data Center Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
United States Data Center Power Market
Data Center Infrastructure
Data Center Monitoring Systems Market
Data Center Infrastructure
North America Data Center Construction Market
Data Center Infrastructure
Fiber Management Systems Market
Data Center Infrastructure
Saudi Arabia Data Center Rack Market
Data Center Infrastructure
Global Edge Data Center Market
Data Center Infrastructure
South Korea Data Center Rack Market
Data Center Infrastructure
Italy Data Center Construction Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
Saudi Arabia Data Center Construction Market
Data Center Infrastructure
Thailand Data Center Physical Security Market