
 Canada Data Center Market | 2026-2036
Canada Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Data Center Market Insights
Liquid cooling infrastructure is reconfiguring thermal management architectures across Canadian facilities. Vantage Data Centers leverages direct-to-chip cooling to sustain density thresholds beyond traditional air-based limits. Compass Datacenters anchors its modular build program in Ontario's industrial corridor, competing on deployment velocity against conventional stick-built timelines. eStruxture differentiates through bilingual operations and Quebec's low-carbon grid access.
A data center is a dedicated facility housing compute, storage, and networking equipment with controlled environmental parameters—typically maintaining temperatures between 18°C and 27°C and humidity at 40–60% RH—to ensure continuous availability of digital services for enterprise and consumer applications. Colocation services capture the largest revenue pool as enterprises divest owned assets, while high power and ultra high power tiers represent the fastest-expanding segments driven by GPU clusters for generative AI training. Managed services within hybrid deployments concentrate margin pools where operators bundle connectivity with workload orchestration.
Health Canada and the Office of the Privacy Commissioner of Canada shape facility standards through data residency requirements for healthcare and personal information, while the Canadian Environmental Protection Act and provincial carbon pricing frameworks enforce emissions accountability on diesel backup and construction materials. The Canadian Radio-television and Telecommunications Commission influences interconnection economics through wholesale broadband regulations. Stakeholders must weigh Quebec's hydroelectric advantage against British Columbia's seismic risks and Ontario's land scarcity when committing to decade-long power contracts.
Market Dynamics
GPU-intensive generative AI training workloads are compressing deployment timelines and forcing power density thresholds beyond legacy air-cooled designs across Canadian facilities.
Growth Catalysts
- Carbon pricing acceleration:The Greenhouse Gas Pollution Pricing Act penalizes diesel backup and construction emissions, redirecting investment toward Quebec's hydroelectric grid.
- Health data residency mandates:Health Canada requirements for healthcare information storage sustain demand for sovereign Canadian facilities over cross-border alternatives.
- Hyperscale corridor concentration:Montreal's fiber and power infrastructure density attracts clustered deployments that reduce interconnection costs for cloud service providers.
Market Restraints
- Liquid cooling supply bottlenecks:Specialized coolant distribution units and cold plate manufacturers face 18-24 month lead times, throttling density upgrades.
- Ontario land scarcity:Industrial zoned parcels within 50km of Toronto's fiber core trade at premiums that erode project IRRs against Quebec alternatives.
- Seismic engineering costs:British Columbia's fault line requirements add structural steel and isolation base costs absent in Prairie province builds.
Strategic Opportunities
- Edge node dispersion:Underpenetrated Atlantic Canada markets present first-mover positioning for low-latency gaming and autonomous vehicle processing.
- Heat reuse integration:District heating partnerships with municipal utilities in Calgary and Edmonton monetize waste thermal output.
- Indigenous joint ventures:Crown land access agreements with First Nations in Northern Ontario unlock greenfield sites with direct hydro connections.
Industry Challenges
- Electrical trades shortage:Medium-voltage switchgear technicians and high-voltage cable splicers command wage premiums that extend commissioning schedules.
- Permitting timeline variability:Provincial environmental assessment processes for diesel generator installations range from 8 months in Alberta to 22 months in Quebec.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Data Center Market |
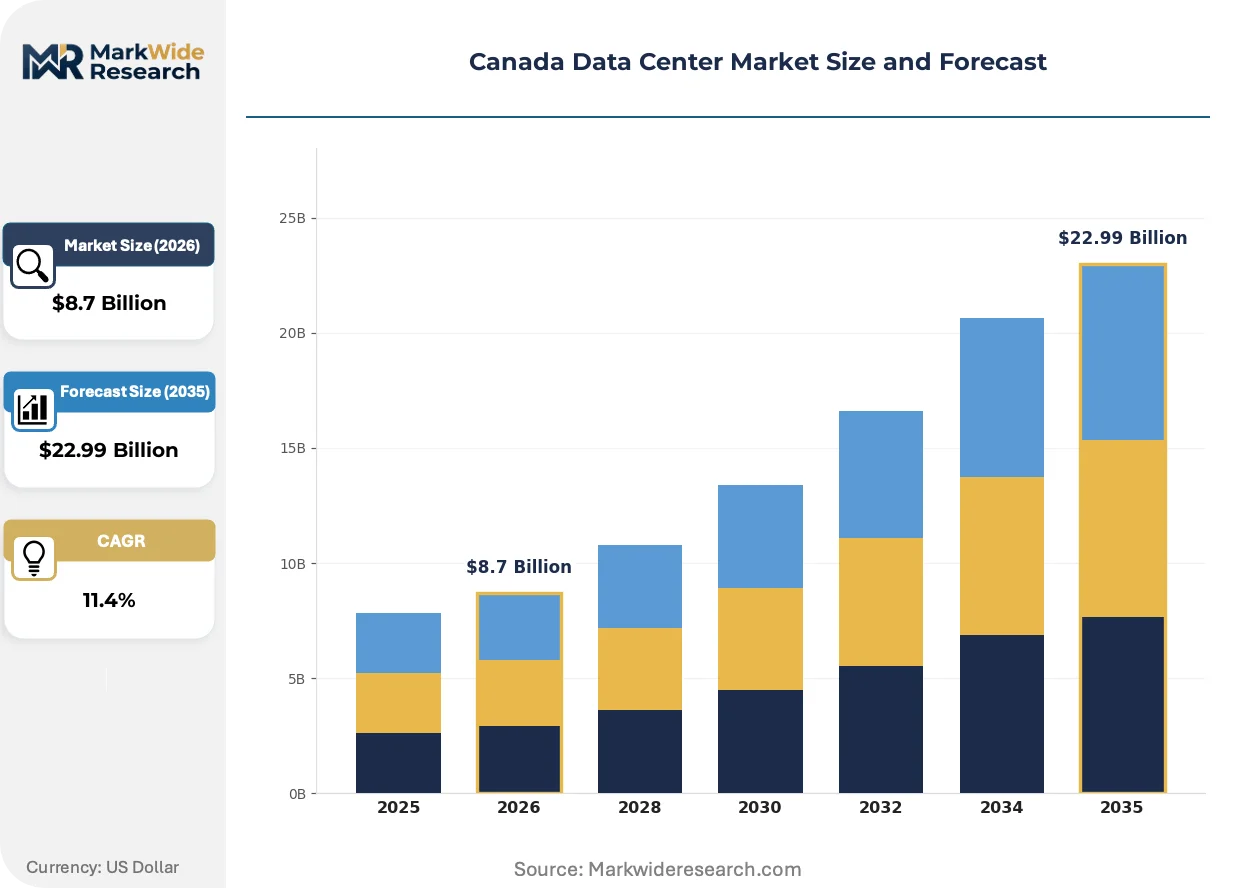
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Managed Services, Cloud Services, Disaster Recovery Deployment: On-Premises, Hybrid, Multi-Cloud, Private Cloud End User: Financial Services, Healthcare, Telecom, Government Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Vantage Data Centers, Cologix, Compass Datacenters, Equinix, eStruxture, Digital Realty, O'Leary Ventures, Beacon AI Centers, Hut 8, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Data Center Market Trends and Innovations
Computational density requirements and carbon accountability are converging to reconfigure thermal, power, and deployment architectures across Canadian data center construction.
Direct-to-chip liquid cooling is virtualizing traditional perimeter CRAC-based thermal management. Hyperscale operators in the Montreal corridor are specifying coolant distribution networks at rack level to sustain 50kW+ GPU densities. This architecture is virtualizing the mechanical penthouse model that dominated 2010s facility design.
The Canadian Environmental Protection Act enforcement priorities are tightening construction material sourcing and diesel backup runtime allowances. Facility operators must now document embodied carbon in structural steel and concrete to provincial regulators. Quebec-based projects gain compliance advantage through hydroelectricity certificates that offset backup generator emissions calculations.
Enterprise procurement of capacity is fragmenting from wholesale floor leases toward fractional megawatt subscriptions with burst provisions. Financial services and media verticals in Toronto are negotiating 18-month commit structures with 30-day exit clauses rather than traditional 5-7 year terms. This flexibility premium concentrates among cloud-adjacent colocation providers with software-defined provisioning layers.
Canada Data Center Market Segmentation
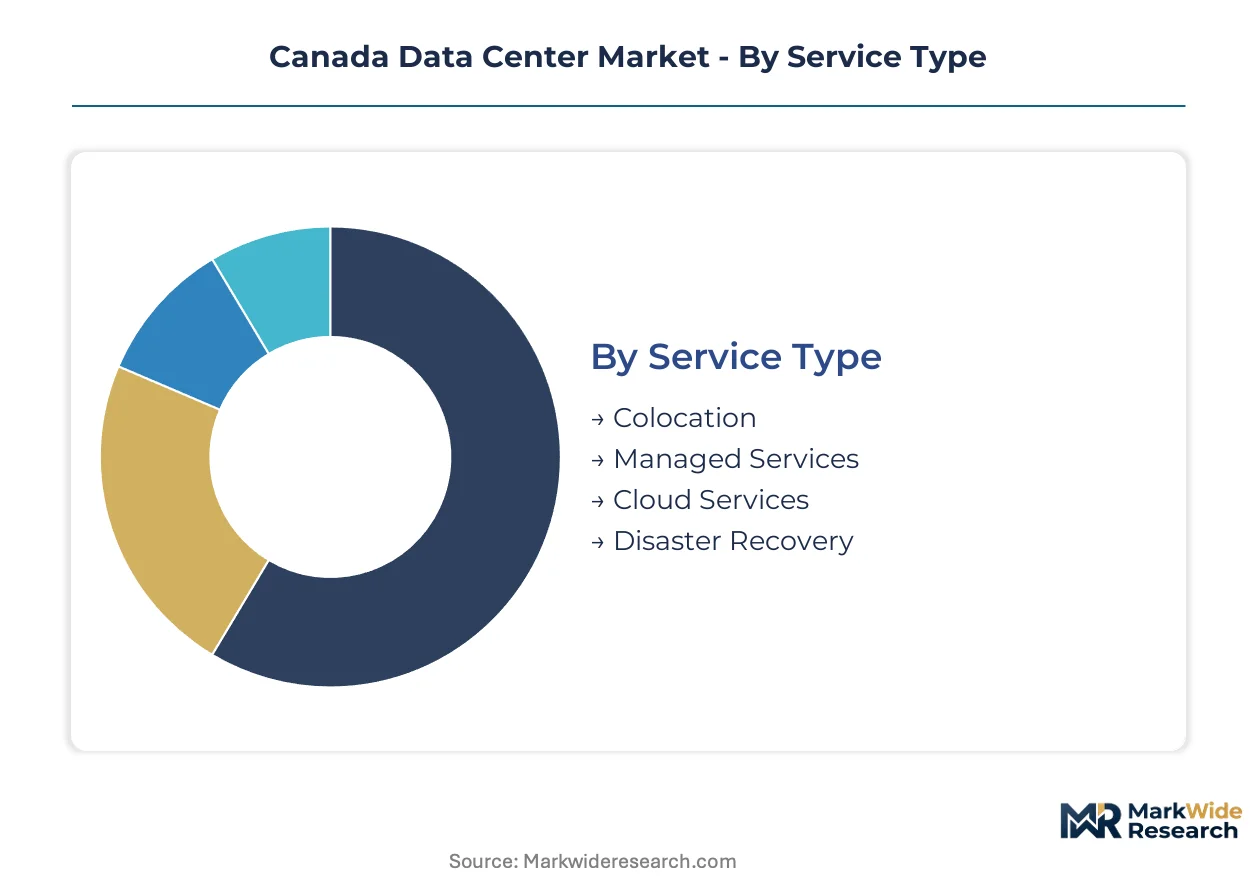
Canadian data center procurement patterns fragment across service models, infrastructure ownership structures, and workload density requirements. Each segmentation dimension reveals distinct margin pools and competitive positioning strategies for operators navigating Quebec's hydroelectric advantage against Ontario's latency-sensitive financial services demand.
Service Type:
Colocation absorbs wholesale floor commitments from enterprises divesting owned assets, while cloud and managed services capture hybrid orchestration premiums.
- Colocation:Wholesale and retail cage configurations dominate revenue concentration as financial services and media enterprises exit capital-intensive facility ownership. Toronto and Montreal corridor operators compete on cross-connect density and cloud on-ramp proximity.
- Managed Services:Hybrid workload orchestration bundled with connectivity commands margin premiums where providers integrate VMware and Kubernetes layers. Healthcare verticals in Ontario favor this model to satisfy Health Canada residency mandates without internal infrastructure teams.
- Cloud Services:Hyperscale provider availability zones anchor demand in the Montreal corridor.
- Disaster Recovery:Secondary site requirements from prairie oil and gas operators sustain Calgary and Edmonton deployments.
Established volume favors colocation; emerging adoption favors managed services.
Deployment:
Ownership economics and data sovereignty requirements distribute workloads across four architectural models with divergent capital intensity profiles.
- Hybrid:Split workloads between on-premises retention and cloud burst capacity dominate enterprise procurement in Toronto's financial district. Canadian banks specify this architecture to maintain core ledger control while tapping GPU clusters for risk modeling.
- Multi-Cloud:Distribution across AWS, Azure, and Google Cloud regions concentrates among SaaS vendors seeking redundancy against single-provider outages. Vancouver media technology firms deploy this model to serve Asia-Pacific latency requirements.
- On-Premises:Crown corporations and defense contractors retain full ownership for classified workloads.
- Private Cloud:Single-tenant dedicated infrastructure satisfies Quebec healthcare data residency rules.
Hybrid deployments absorb the largest committed capacity; multi-cloud configurations are climbing the fastest.
End User:
Vertical-specific compliance burdens and latency tolerances shape facility selection criteria across four demand concentrations.
- Financial Services:Toronto-based banks and insurance carriers drive sub-10 millisecond requirements to co-located trading infrastructure. The Office of the Superintendent of Financial Institutions mandates operational resilience standards that favor redundant fiber paths through downtown core facilities.
- Healthcare:Provincial health authorities and private diagnostic chains sustain Quebec and Ontario demand under Health Canada data residency enforcement. Personal health information storage restrictions block cross-border alternatives for patient record systems.
- Telecom:5G edge node deployments from national carriers concentrate in Vancouver and Toronto metro rings.
- Government:Federal cloud-first policies redirect departmental workloads to certified facilities in Ottawa and Gatineau.
Financial services anchor committed megawatts; healthcare verticals are gaining share fastest.
Power Rating:
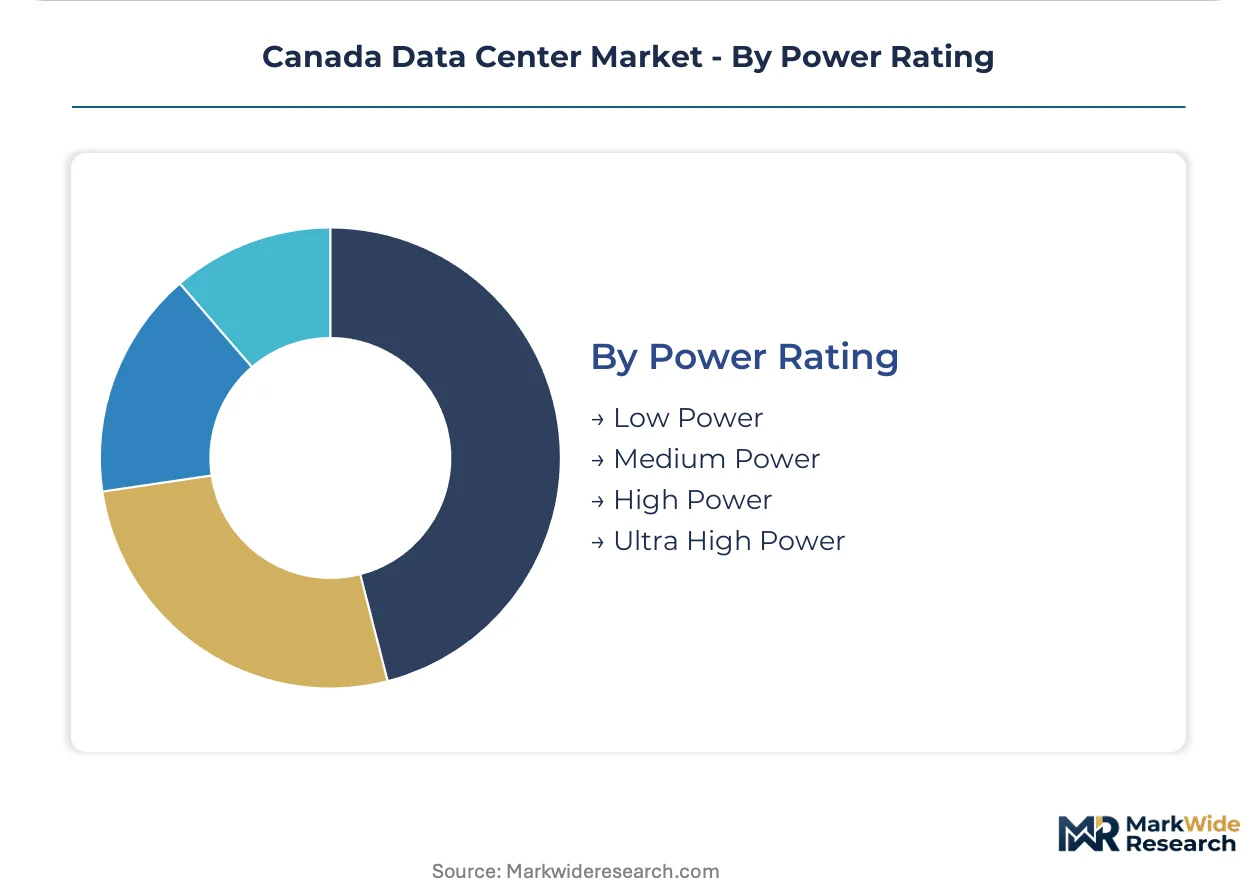
GPU cluster density thresholds are reclassifying legacy tiering systems as air-cooled designs hit thermal limits.
- Ultra High Power:Direct-to-chip liquid cooling sustains 50kW+ rack densities for generative AI training clusters in Montreal hyperscale builds. Vantage Data Centers and Compass Datacenters specify this tier exclusively for cloud service provider anchor tenants.
- High Power:15-30kW air-cooled configurations serve enterprise AI inference and HPC workloads where liquid cooling capital exceeds budget cycles. Calgary energy sector simulation demand concentrates in this tier.
- Medium Power:Traditional enterprise virtualization and storage arrays populate the majority of existing floor space.
- Low Power:Edge node and network function virtualization requirements sustain distributed small-footprint deployments.
Medium power retains the largest installed base; ultra high power is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's data center capacity expansion generates substantial capital equipment imports while domestic construction and engineering services flow westward to British Columbia and eastward to Atlantic markets. The interprovincial trade balance tilts toward Quebec and Ontario as primary build locations.
Ontario
Toronto's financial district drives sub-10 millisecond latency requirements for co-located trading infrastructure. The Office of the Superintendent of Financial Institutions mandates operational resilience standards that favor redundant fiber paths through downtown core facilities. Industrial zoned parcels within 50km of Toronto's fiber core trade at premiums that erode project IRRs against Quebec alternatives.
Quebec
Montreal's fiber and power infrastructure density attracts clustered hyperscale deployments that reduce interconnection costs for cloud service providers. The Greenhouse Gas Pollution Pricing Act penalizes diesel backup and construction emissions, redirecting investment toward Quebec's hydroelectric grid. Vantage Data Centers and Compass Datacenters specify direct-to-chip liquid cooling exclusively for cloud service provider anchor tenants in this corridor.
British Columbia
Vancouver media technology firms deploy multi-cloud architectures to serve Asia-Pacific latency requirements. The Canadian Environmental Protection Act enforcement priorities tighten construction material sourcing and diesel backup runtime allowances. Seismic engineering requirements add structural steel and isolation base costs absent in Prairie province builds.
Alberta
Calgary and Edmonton sustain disaster recovery demand from prairie oil and gas operators requiring secondary sites. Provincial environmental assessment processes for diesel generator installations range from 8 months in Alberta to 22 months in Quebec. District heating partnerships with municipal utilities in Calgary and Edmonton monetize waste thermal output from data center operations.
Atlantic Canada
Underpenetrated Atlantic Canada markets present first-mover positioning for low-latency gaming and autonomous vehicle processing. Health Canada requirements for healthcare information storage sustain demand for sovereign Canadian facilities over cross-border alternatives. Crown land access agreements with First Nations in Northern Ontario unlock greenfield sites with direct hydro connections.
Canada Data Center Market Competitive Landscape
On the supply side, the industry is consolidating around hyperscale specialists and regional platform operators with distinct capital deployment strategies. Tier-one operators compete on power contract duration and interconnection density, while mid-market players differentiate through deployment velocity and vertical-specific compliance capabilities. Strategic archetypes include hydroelectric-powered Quebec specialists, modular build specialists in Ontario's industrial corridor, and edge-focused regional platforms. Dominant competitive moves center on decade-long power contract commitments and liquid cooling infrastructure partnerships with GPU cluster operators.
Among hyperscale specialists, Vantage Data Centers, Compass Datacenters, and eStruxture occupy distinct positioning vectors. Vantage Data Centers exemplifies the ultra-high-density liquid cooling archetype with direct-to-chip thermal management for GPU clusters. Compass Datacenters represents the modular deployment velocity model with factory-built components competing against conventional stick-built timelines. eStruxture anchors the bilingual Quebec specialist position leveraging low-carbon grid access and provincial data residency requirements.
| Leading Market Players |
|---|
| Vantage Data Centers |
| Cologix |
| Compass Datacenters |
| Equinix |
| eStruxture |
| Digital Realty |
| O'Leary Ventures |
| Beacon AI Centers |
| Hut 8 |
| Others |
Pricing and Supply Chain Analysis
Chinese-manufactured liquid cooling components and Taiwanese server motherboard production concentrate upstream capacity, feeding margin pools to hyperscale operators in Quebec's Montreal corridor who command premium pricing for carbon-compliant, high-density deployments.
Pricing Analysis
Cloud service provider anchor tenants anchor pricing structures around long-term power contracts with hydroelectric-backed carbon offsets. Price differentiation stems from certification tier under the Greenhouse Gas Pollution Pricing Act and liquid cooling readiness for GPU densities above 50kW per rack. Cost compression in retail colocation tiers is intensifying because enterprise buyers fragment commitments into fractional megawatt subscriptions with burst provisions. Financial services buyers in Toronto exhibit lowest price sensitivity due to latency mandates, while prairie oil and gas operators drive hardest bargain on disaster recovery secondary sites.
Supply Chain Analysis
Foxconn, Quanta, and Wistron hold dominant contract manufacturing capacity for liquid-cooled server infrastructure destined for Canadian hyperscale builds. Component sourcing draws from China for coolant distribution units, Taiwan for advanced thermal management chipsets, and the United States for medium-voltage switchgear. Single-source vulnerability concentrates in cold plate and manifold manufacturing where 18-24 month lead times throttle density upgrades. Distribution runs through direct OEM relationships with Vantage Data Centers, Compass Datacenters, and eStruxture, bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperscale cloud availability zones in US border states threaten to displace Canadian sovereign capacity unless operators defend through carbon-compliant density advantages and data residency enforcement.
For Market Incumbents: Build decade-long hydroelectric power contract moats with Hydro-Québec and BC Hydro to lock in carbon pricing arbitrage against diesel-dependent competitors. Anchor liquid cooling infrastructure partnerships with NVIDIA and AMD cluster operators before supply bottlenecks widen. Vertical integration into modular factory-built components, following Compass Datacenters' Ontario industrial corridor model, compresses deployment velocity against conventional stick-built timelines. For New Entrants and Emerging Players: Pursue Atlantic Canada edge node dispersion where sub-10 millisecond gaming and autonomous vehicle processing demand outstrips supply. Crown land access agreements with First Nations in Northern Ontario unlock greenfield sites with direct hydro connections absent in saturated Toronto and Vancouver metro rings. Bilingual operations capability opens Quebec healthcare and provincial government verticals where eStruxture has established incumbent position. For Investors and Strategic Acquirers: Capital is best deployed toward hydroelectric-powered Quebec specialists with existing Health Canada certification pathways and direct-to-chip liquid cooling operational maturity. Long-term viability across the analysis window hinges on carbon pricing regime durability and GPU cluster density migration from air-cooled legacy facilities. Watch for diesel generator permitting timeline compression in Alberta as signal of regulatory arbitrage opportunity against Quebec's 22-month environmental assessment processes.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Hydroelectric Power Contracting | Locks in carbon pricing arbitrage under the Greenhouse Gas Pollution Pricing Act against diesel-dependent competitors. |
| Liquid Cooling Infrastructure Partnership | Secures direct-to-chip thermal management capacity for 50kW+ GPU densities ahead of 18-24 month supply bottlenecks. |
| First Nations Crown Land Joint Venture | Unlocks greenfield sites in Northern Ontario with direct hydro connections unavailable in saturated Toronto fiber core. |
| Health Canada Certification Pathway Investment | Captures healthcare data residency mandates that block cross-border alternatives for patient record systems. |
| Modular Factory-Built Deployment Program | Compresses commissioning schedules against conventional stick-built timelines in Ontario's land-scarce industrial corridor. |
Research Methodology
Cross-validation between hyperscaler capex disclosures and provincial utility interconnection queue data anchors the qualitative findings in this study. Primary interviews with data center development executives, electrical engineering contractors, cloud procurement officers, and Health Canada compliance specialists combined with secondary validation from Canadian Environmental Protection Act enforcement records, CRTC wholesale broadband regulations, and Hydro-Québec power contract announcements. Bottom-up facility-level capacity aggregation triangulates against top-down cloud service provider demand forecasts across the analysis window.
Calibration against historical hyperscale deployment velocity in the Montreal corridor and Toronto financial district latency requirements shapes the analytical framework. Segmentation dimensions modeled include service type, deployment architecture, end-user vertical, and power density tier across the projection horizon. CAGRs derive from facility pipeline tracking, power contract duration analysis, and GPU cluster adoption curves in generative AI training workloads. Carbon pricing trajectory under the Greenhouse Gas Pollution Pricing Act and liquid cooling supply elasticity serve as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Canadian dollar exchange rates, long-term bond yields affecting hyperscaler capital allocation, and provincial carbon price escalation schedules would shift the trajectory. Forecasts reflect documented assumptions on power interconnection timelines, diesel generator permitting pathways, and First Nations consultation protocols. Quarterly review of utility interconnection queue depths, liquid cooling component lead times, and Health Canada enforcement priorities is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
Chennai Data Center Market
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
United Kingdom Data Center Physical Security Market
Data Center Infrastructure
China Data Center Server Market
Data Center Infrastructure
Netherlands Data Center Physical Security Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Smart Data Center Market
Data Center Infrastructure
Taiwan Data Center Power Market
Data Center Infrastructure
Philippines Data Center Physical Security Market
Data Center Infrastructure
South Africa Data Center Rack Market
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
Israel Data Center Server Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
Indonesia Data Center Market
Data Center Infrastructure
Spain Data Center Power Market