
 Data Center Equipment Market | 2026-2036
Data Center Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Equipment Market Intelligence
AI-optimized compute architectures is tilting procurement toward high-density server configurations with liquid cooling integration. Dell Technologies leverages its direct supply chain to control fulfillment timelines for enterprise rack systems. Huawei anchors its position through captive silicon design for networking gear. Vertiv specializes in thermal management systems that sustain uptime in facilities exceeding 50 kW per rack.
Data center equipment encompasses the physical infrastructure—servers, storage arrays, networking switches, power distribution units, and environmental control systems—engineered to operate at 99.999% availability with PUE targets below 1.3. These systems form the substrate for enterprise IT, cloud services, and telecommunications exchange. Servers dominate product type revenue due to refresh cycles driven by generative AI training clusters. Modular cooling within the technology dimension captures the fastest expansion as heat densities render traditional CRAC units inadequate. Hybrid installation models concentrate margin pools by blending capital ownership with operational flexibility.
The EPA Energy Star program and OSHA electrical safety standards constrain power supply design and facility worker protection protocols in the United States. The EU F-Gas Regulation phases down refrigerants used in precision cooling, forcing equipment redesign toward water-based and dielectric fluid alternatives. Stakeholders must monitor thermal design power trajectories of next-generation GPUs against the lead times for compatible cooling infrastructure deployment.
Market Dynamics
Generative AI training clusters are forcing rack power densities past 50 kW, rendering traditional air-cooled infrastructure obsolete and compressing deployment timelines for liquid-cooled systems.
Growth Catalysts
- EU Energy Efficiency Directive:Mandatory PUE reporting below 1.3 for new facilities accelerates precision cooling retrofits across Frankfurt, Amsterdam, and Dublin data center clusters.
- Hyperscale cloud expansion:Amazon Web Services, Microsoft Azure, and Google Cloud are tripling server deployment rates in Northern Virginia and Dallas-Fort Worth to support AI inference workloads.
- Dielectric fluid immersion:Single-phase and two-phase immersion cooling systems are capturing design wins for GPU-heavy training racks exceeding 100 kW per cabinet.
Market Restraints
- Copper and rare earth price volatility:Power distribution busbars and high-efficiency motor windings face input cost swings tied to Chilean mine output and Chinese processing quotas.
- Taiwan semiconductor concentration:Advanced networking ASICs and server-class GPUs depend on TSMC fabrication, creating single-point vulnerability for equipment lead times.
- F-Gas Regulation phase-down:The EU's refrigerant quota system forces immediate engineering pivots away from hydrofluorocarbon-based precision cooling units before 2030 compliance deadlines.
Strategic Opportunities
- India data center buildout:Mumbai, Chennai, and Hyderabad are attracting hyperscale investment under the government's data center infrastructure status and renewable energy purchase mandates.
- Modular prefabricated data centers:Factory-integrated power and cooling modules are compressing site deployment from 18 months to under 6 months for edge and enterprise buyers.
- ISO 50001 energy management certification:Enterprise colocation providers are differentiating through audited efficiency credentials that unlock green bond financing and corporate ESG procurement preferences.
Industry Challenges
- Thermal engineering talent scarcity:Computational fluid dynamics specialists and liquid cooling system integrators command premium compensation, constraining vendor scaling velocity.
- Legacy DCIM integration friction:Brownfield facilities running 10-year-old infrastructure management platforms face protocol incompatibility with AI-optimized workload orchestration tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Equipment Market |
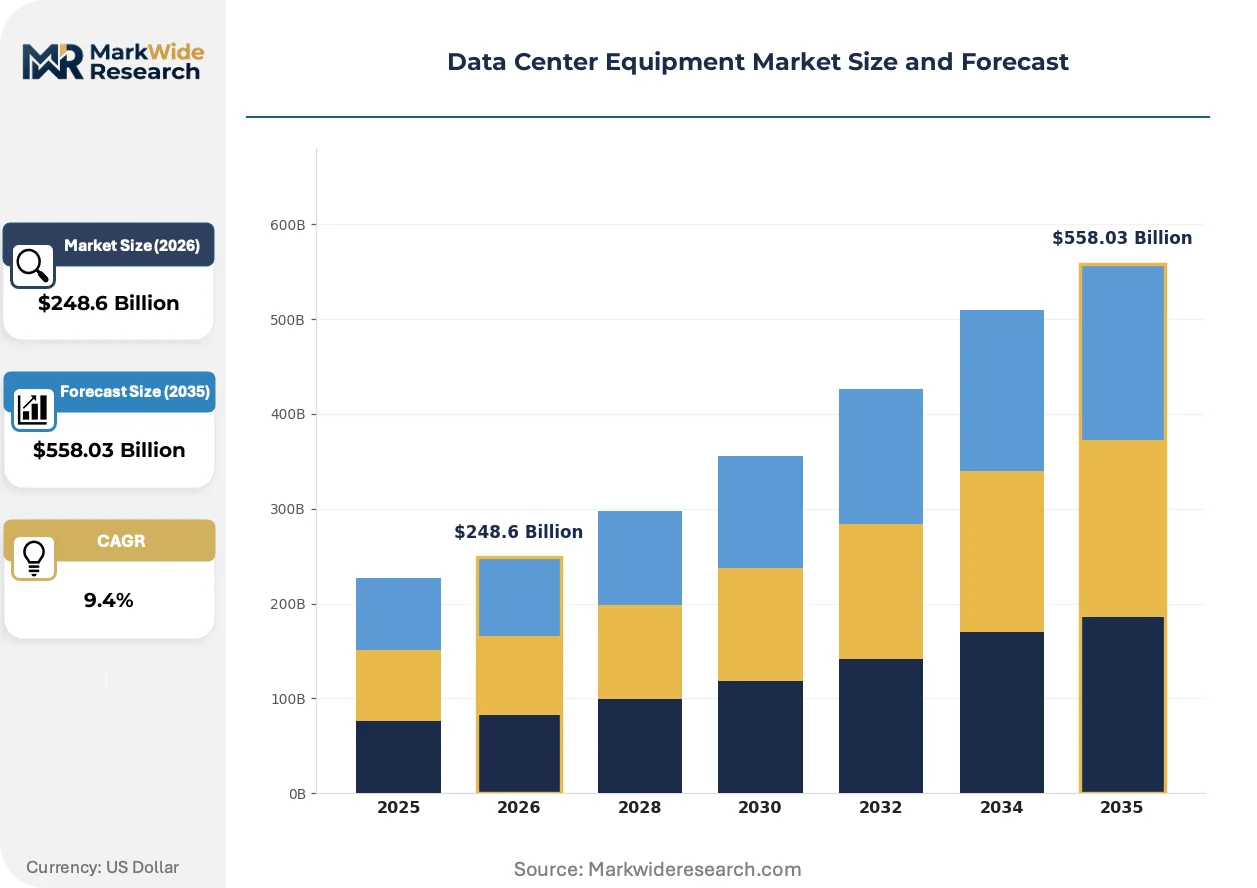
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $558.03 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Servers, Switches, Racks, Routers Technology: Hyperconverged Infrastructure, Virtualization, Blade Servers, Modular Cooling End User: Telecom, MSSPs, Public Sector, E-Commerce Installation: On-Premises, Colocation, Cloud-Based, Hybrid |
| Companies Covered | Hewlett Packard Enterprise, NPOD, Schneider Electric, APC, Liebert, Vertiv, Huawei, Stulz, Dell Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Equipment Market Strategic Shifts & Innovations
Liquid cooling architectures are collapsing the thermal design assumptions that governed three decades of data center engineering, while regulatory pressure on refrigerants and energy intensity forces simultaneous equipment and operational overhauls.
Direct-to-chip cold plate systems are collapsing the thermal resistance stack between high-TDP processors and ambient heat rejection loops. Hyperscale operators in the United States and Nordic countries are deploying these systems at 40% of new AI training facilities. The technology is collapsing the distinction between facility cooling and server thermal design, forcing joint engineering between real estate developers and semiconductor vendors.
The EU F-Gas Regulation mandates an 80% phase-down of hydrofluorocarbon refrigerants by 2030 from 2015 baseline levels. Equipment manufacturers are redesigning precision cooling units around water-glycol loops and dielectric fluid immersion tanks to maintain cooling capacity. German and French data center operators face the steepest retrofit obligations given their installed base of legacy CRAC units.
Enterprise buyers are consolidating vendor relationships from fragmented best-of-breed server, storage, and networking suppliers toward vertically integrated rack-scale system providers. Financial services and healthcare verticals in the United States are driving this concentration through standardized SKU procurement and single-source accountability for 99.999% uptime SLAs. The shift compresses evaluation cycles and elevates thermal performance guarantees over component-level specifications.
Data Center Equipment Market Segmentation
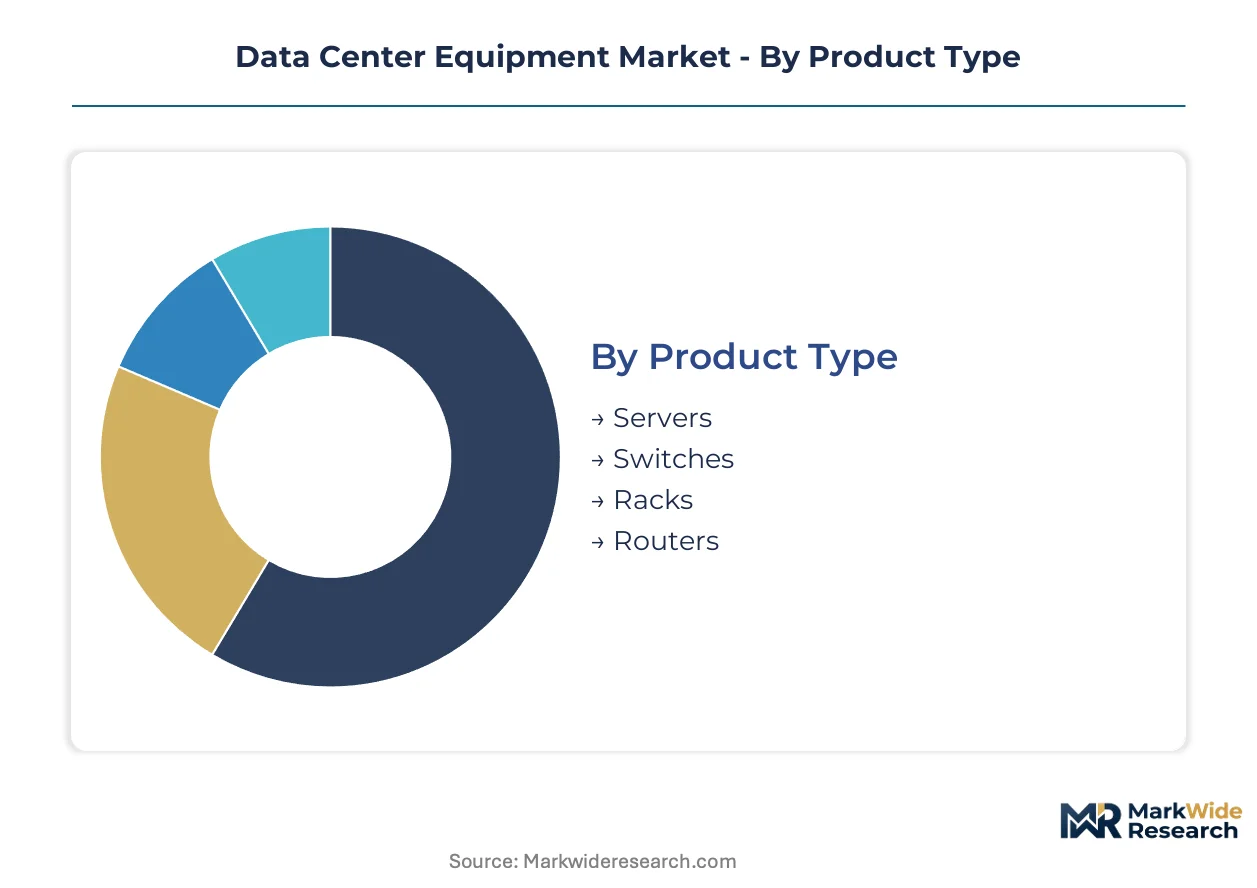
Segmentation in data center equipment reveals how procurement patterns diverge across workload types and infrastructure ownership models. Understanding these divisions exposes where capital concentrates and which technology transitions command premium pricing.
Product Type:
After-sales service intensity varies sharply across physical equipment categories, with thermal and power subsystems demanding recurring maintenance contracts while passive structures require minimal ongoing vendor engagement.
- Servers:High-density GPU-accelerated nodes and general-purpose x86 units form the compute substrate for AI training and enterprise virtualization. Demand clusters in Northern Virginia hyperscale campuses and Dallas-Fort Worth AI inference facilities driven by generative AI workload expansion.
- Switches:Spine-leaf fabric architectures and high-radix Ethernet switches manage east-west traffic in distributed training clusters. Financial services and cloud providers in the United States prioritize 400G/800G port densities with sub-microsecond latency guarantees.
- Racks:Enclosure systems integrate cable management, power busbars, and mounting rails for standardized equipment housing.
- Routers:Edge-facing and core network devices handle inter-facility and internet peering traffic with deep buffer architectures.
By volume, Servers lead. By growth pace, Switches supporting AI network fabrics are ahead.
Technology:
Cost tier stratification separates integrated software-defined platforms from discrete hardware purchases, with premium pricing attached to unified management layers.
- Hyperconverged Infrastructure:Software-defined compute-storage-networking stacks collapse three-tier architectures into x86-based nodes with distributed storage fabrics. Enterprise IT departments in United States healthcare and manufacturing verticals favor HCI for rapid provisioning and reduced operational headcount.
- Modular Cooling:Factory-integrated liquid cooling distribution units and in-rack heat exchangers address thermal loads exceeding 50 kW per cabinet. German and French operators retrofit legacy facilities to meet EU F-Gas Regulation phase-down mandates while supporting NVIDIA H100 GPU deployments.
- Virtualization:Hypervisor and container orchestration software layers abstract physical compute resources into elastic pools.
- Blade Servers:High-density shared infrastructure chassis accommodate multiple half-height or quarter-height server nodes.
By deployment base, Virtualization leads. By expansion velocity, Modular Cooling systems are gaining share fastest.
End User:
Customer type determines procurement scale and customization requirements, with hyperscale buyers dictating rack-scale specifications while smaller entities accept standard SKUs.
- Telecom:Carrier-grade edge and core facilities deploy virtualized network functions on commodity hardware with stringent five-nines availability requirements. 5G standalone core buildouts in India and South Korea drive server refresh cycles with O-RAN compliant configurations.
- MSSPs:Managed security and infrastructure service providers operate multi-tenant facilities requiring logical isolation and rapid tenant onboarding. United States mid-market outsourcing demand concentrates in Phoenix and Atlanta secondary markets with lower power costs.
- Public Sector:Government and defense data centers prioritize supply chain security and domestic assembly requirements.
- E-Commerce:Peak-load retail platforms demand elastic burst capacity with flash storage tiers for transaction processing.
By infrastructure spend, Telecom leads. By growth pace, MSSPs expanding edge presence are climbing the fastest.
Installation:
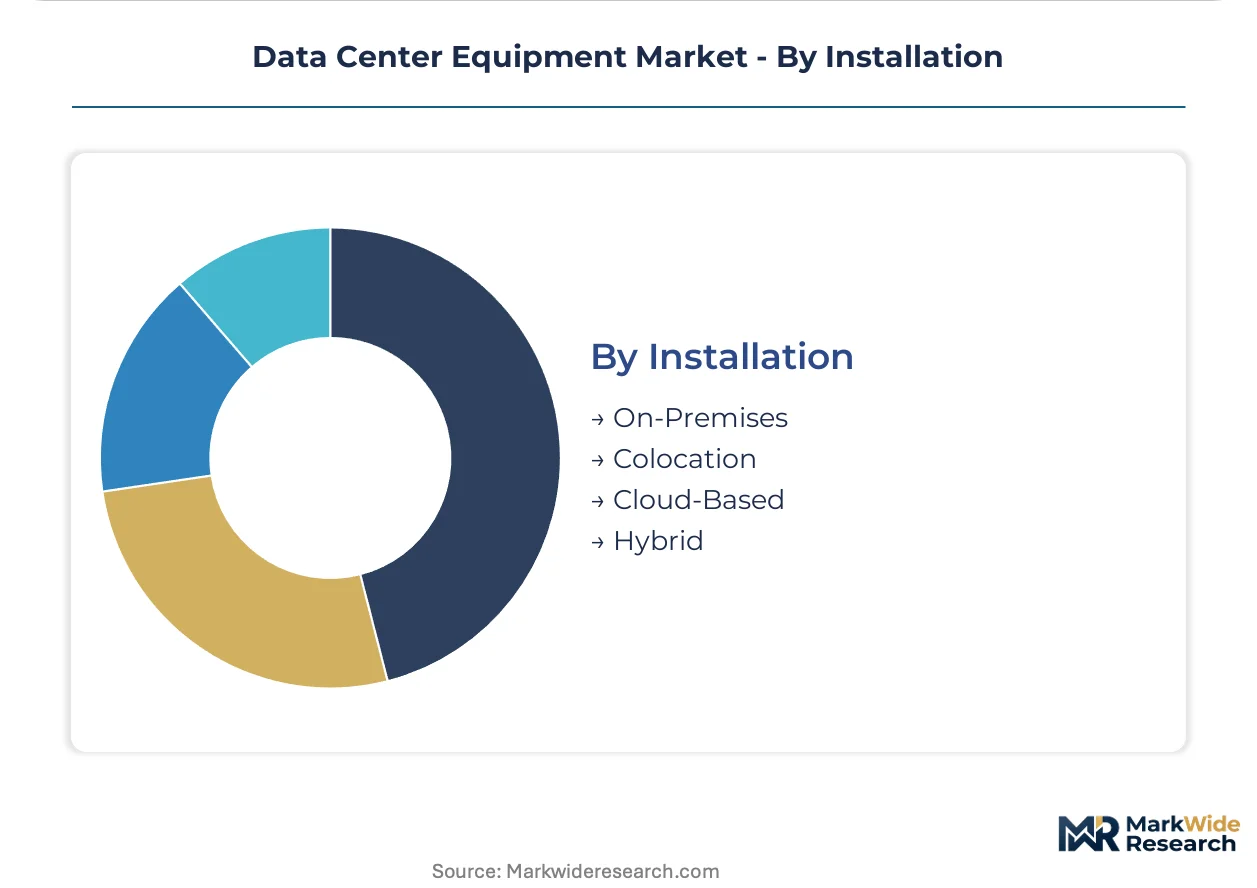
Ownership and operational responsibility models fragment the addressable market between capital-intensive builds and operational expenditure structures.
- Colocation:Wholesale and retail leased space providers supply power, cooling, and physical security while tenants own server equipment. Northern Virginia Ashburn-Dulles corridor and Frankfurt FLAP markets attract enterprise tenants seeking proximity to cloud on-ramps without facility capital burden.
- Hybrid:Workload placement across owned, leased, and public cloud resources demands unified orchestration and consistent networking policies. United States financial services firms pursue hybrid architectures to retain sensitive data on-premises while bursting analytics to cloud.
- On-Premises:Enterprise-owned and operated facilities maintain full control over hardware selection and facility design.
- Cloud-Based:Fully outsourced infrastructure-as-a-service abstracts all physical equipment decisions from the user.
By deployment volume, Colocation leads. By strategic momentum, Hybrid installations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment flows from Taiwanese semiconductor foundries into hyperscale facilities across the United States, Germany, and India. Cloud operators in Northern Virginia and Frankfurt absorb the highest server volumes. Mumbai and Dallas-Fort Worth emerge as secondary absorption nodes for modular cooling systems.
United States
Northern Virginia's Ashburn-Dulles corridor hosts the densest concentration of hyperscale server deployments globally. EPA Energy Star certification requirements shape procurement specifications for power distribution units. Dallas-Fort Worth operators are tripling liquid cooling infrastructure to support GPU clusters exceeding 100 kW per rack.
Germany
Frankfurt's FLAP cluster drives precision cooling retrofits under EU F-Gas Regulation phase-down mandates. The national implementation of the EU Energy Efficiency Directive enforces PUE reporting below 1.3 for new facilities. Bavarian data center operators are replacing hydrofluorocarbon-based CRAC units with water-glycol distribution systems ahead of 2030 deadlines.
India
Mumbai, Chennai, and Hyderabad attract hyperscale investment under the government's data center infrastructure status policy. The Central Electricity Authority mandates renewable energy purchase obligations for large consumers. Telangana's Hyderabad cluster is deploying factory-integrated modular power and cooling modules with six-month deployment cycles.
China
Beijing-Tianjin-Hebei and Yangtze River Delta regions concentrate domestic cloud provider expansion. MIIT regulations govern data localization and cross-border data flow compliance for facility operators. Sichuan-Chongqing leverages hydroelectric power availability to support high-density training clusters with sub-1.2 PUE targets.
United Kingdom
Greater London and Slough corridor facilities serve financial services demand for low-latency connectivity to European markets. The UK implementation of CSRD extends sustainability disclosure requirements to colocation providers. Scotland's cooler ambient temperatures support free-cooling architectures for AI inference workloads.
Data Center Equipment Market Key Industry Players
Channel-controlling players compete with product-specialist players across server, thermal management, and power distribution segments. The vendor base organizes into three tiers: integrated rack-scale system providers, component-specialist manufacturers, and regional assembly houses. Dominant competitive moves include captive silicon design for networking ASICs and backward integration into liquid cooling distribution hardware.
Within the integrated system tier, Dell Technologies and Hewlett Packard Enterprise exemplify vertically structured competitors with direct supply chain control over enterprise rack fulfillment. Vertiv occupies a specialist position in thermal management architectures. Huawei anchors the captive silicon design archetype for networking gear through in-house semiconductor development. These three patterns—integrated systems, thermal specialization, and captive silicon—define the competitive geometry.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| NPOD |
| Schneider Electric |
| APC |
| Liebert |
| Vertiv |
| Huawei |
| Stulz |
| Dell Technologies |
| Others |
Cost & Logistics Intelligence
Taiwanese semiconductor foundry capacity allocation dictates downstream server and networking equipment pricing power, with TSMC fabrication slot scarcity compressing margins for equipment vendors dependent on advanced ASICs and GPUs.
Pricing Analysis
Next-generation AI-optimized servers command substantial premiums over prior-generation air-cooled units, while current-generation GPU-accelerated nodes face cost compression from hyperscale volume procurement. Three-tier pricing structure across premium liquid-cooled, standard air-cooled, and economy refurbished tiers separates enterprise buyers by thermal performance requirements and uptime SLA demands. Pricing pressure stems from hyperscale cloud providers consolidating vendor relationships and demanding rack-scale system accountability. Mid-market colocation tenants exhibit highest price sensitivity due to capital constraints, while financial services firms prioritize thermal guarantees over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates at Foxconn, Quanta, and Wistron for server assembly, with ODMs controlling thermal subsystem integration for liquid-cooled rack deployments. Taiwan, China, and Mexico anchor fabrication and final assembly, drawing from copper Chilean mine output, rare earth Chinese processing quotas, and precision cooling German engineering. Single-source vulnerability at TSMC for advanced networking ASICs and server-class GPUs creates lead time exposure. Distribution runs through direct OEM channels for hyperscale buyers and value-added resellers for enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open compute hardware disaggregation is transforming data center equipment from discrete component markets into interoperable platform ecosystems, with OCP and SONiC standards eroding proprietary vendor lock-in.
For Market Incumbents: Entrench liquid cooling IP through captive heat exchanger design and backward integration into dielectric fluid distribution hardware. Defend rack-scale system margins by embedding thermal performance guarantees into enterprise SLA contracts. OCP-compliant white-box server encroachment from cloud-native entrants threatens component-level pricing power. For New Entrants and Emerging Players: Modular prefabricated edge data centers for Indian secondary cities represent the most penetrable entry point, with six-month deployment cycles compressing incumbent site construction advantages. Factory-integrated power and cooling modules for Telangana and Chennai hyperscale campuses offer white-space capture with minimal field engineering overhead. Partner with domestic Indian EPC contractors to navigate CEA renewable energy compliance and accelerate facility commissioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors thermal management specialists with liquid cooling distribution hardware capabilities and ISO 50001 certification credentials. Long-term viability hinges on capturing recurring service revenue from precision cooling retrofits driven by EU F-Gas Regulation mandates. Monitor hyperscale capex allocation shifts between training and inference workloads as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Liquid Cooling Hardware Development | In-house heat exchanger production secures margin capture from 50+ kW rack deployments. |
| ISO 50001 Certification Investment | Audited efficiency credentials unlock green bond financing for EU facility operators. |
| Modular Prefabricated System Expansion | Factory-integrated power and cooling modules compress site deployment cycles for edge buyers. |
| OCP-Compliant Rack-Scale Design | Open standards compatibility defends hyperscale procurement position against white-box encroachment. |
| India Market Manufacturing Localization | Domestic assembly satisfies government infrastructure status requirements and reduces logistics exposure. |
Research Approach
Desk research of hyperscaler capex disclosures, EPA Energy Star certification databases, and EU regulatory filings preceded structured interviews with data center facility operators, thermal engineering specialists, server procurement managers, and liquid cooling system integrators. Primary fieldwork across Northern Virginia, Frankfurt, and Mumbai clusters validated secondary estimates of equipment deployment velocity. Bottom-up unit shipment analysis triangulated against top-down infrastructure investment tracking.
Assumptions held fixed include EU F-Gas Regulation phase-down timelines and EPA PUE reporting thresholds, while GPU thermal design power trajectories and hyperscale training cluster expansion rates were stress-tested across scenarios. Segmentation modeling incorporated product type, cooling technology tier, installation ownership model, and regional regulatory cluster dimensions. CAGRs derived from equipment replacement cycle analysis and workload density projections across the analysis window.
Practitioners should monitor TSMC capacity allocation announcements and hyperscale inference workload migration patterns for early signals of demand inflection. Forecasts reflect assumptions regarding liquid cooling adoption velocity and EU regulatory enforcement consistency. Quarterly review of GPU TDP roadmaps and precision cooling retrofit backlog data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
US Data Center Rack Market
Data Center Infrastructure
Japan Data Center Power Market
Data Center Infrastructure
Global Data Center RFID Market
Data Center Infrastructure
Denmark Data Center Server Market
Data Center Infrastructure
Russia Data Center Rack Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
Retail Colocation Market
Data Center Infrastructure
Global Datacenter Deployment Spending Market
Data Center Infrastructure
Australia Data Center Market
Data Center Infrastructure
APAC Green Data Center Market
Data Center Infrastructure
India Data Center Construction Market
Data Center Infrastructure
Ireland Data Center Market
Data Center Infrastructure
Brazil Data Center Market
Data Center Infrastructure
Europe Green Data Center Market
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
Poland Data Center Rack Market