
 Canada Data Center Rack Market | 2026-2036
Canada Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Data Center Rack Market Insights
Aluminum is restructuring rack economics as operators seek lighter frames that cut shipping costs and improve thermal conductivity. Schneider Electric SE leverages its integrated power and cooling portfolio to anchor premium rack-plus-PDU bundles. Rittal GMBH & Co.KG sustains its position through German-engineered enclosure standards adapted for North American voltage configurations. Vertiv Group Corp. dominates the high-density segment with liquid-ready rack architectures designed for AI workloads.
A data center rack is a standardized metal frame that houses servers, networking equipment, and power distribution units, typically conforming to 19-inch EIA-310-D specifications for mounting width and 42U to 48U height configurations, engineered to support static loads exceeding 1,500 kg while enabling front-to-rear airflow management for thermal efficiency. Enclosed racks lead product type demand because they satisfy containment requirements for liquid cooling retrofits and particulate-sensitive environments. Co-location providers represent the fastest-growing end user segment as multi-tenant facilities in Montreal and Vancouver scale to serve regional cloud resiliency strategies. Steel remains the volume material despite aluminum's inroads, given its cost advantage at scale and established Canadian mill supply chains.
Health Canada's PMRA and provincial electrical safety authorities enforce grounding and electromagnetic compatibility standards that dictate rack-level bonding and cable management specifications. The Canadian Standards Association certification creates a compliance gate for imported rack systems, favoring manufacturers with established Canadian distribution and testing partnerships. Stakeholders must monitor how provincial carbon intensity requirements for data centers reshape rack specifications for heat recapture integration and energy disclosure compliance.
Market Dynamics
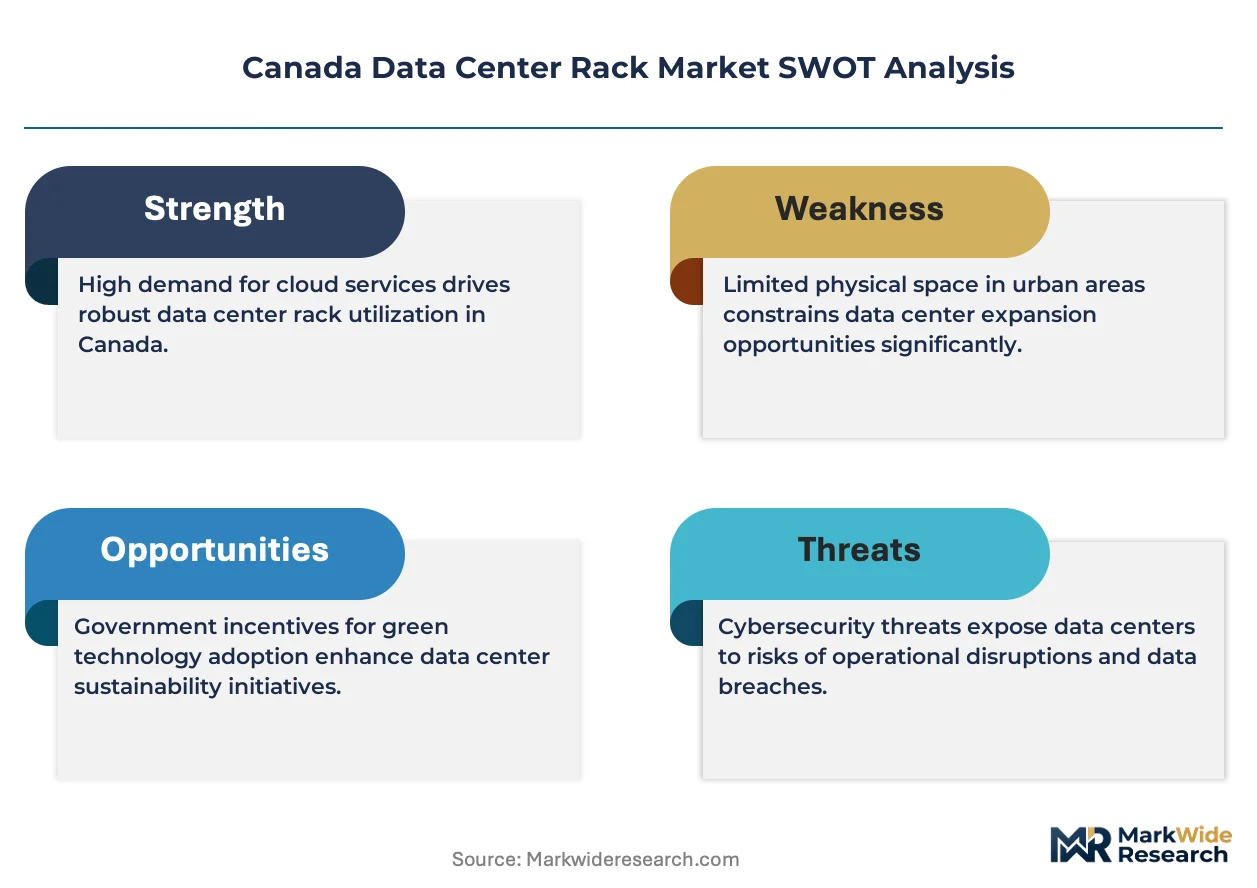
Hyperscale cloud builds in Ontario and Quebec are compressing procurement cycles and forcing rack manufacturers to pre-certify liquid-cooling-ready architectures before Health Canada's PMRA completes its updated electromagnetic compatibility review.
Growth Catalysts
- Provincial carbon intensity mandates:Quebec's hydroelectric grid advantage and Ontario's clean energy targets push operators toward heat-recapture rack designs that qualify for provincial efficiency incentives.
- AI training clusters:Hyperscale facilities in Toronto's Greater Golden Horseshoe corridor demand 48U+ high-density enclosures with integrated busway power distribution for GPU-heavy workloads.
- Co-location resiliency strategies:Multi-tenant providers in Montreal and Vancouver scale redundant facilities to serve regional cloud disaster-recovery requirements, driving standardized rack volume.
Market Restraints
- Steel price volatility:Canadian mill supply chains face input cost pressure from scrap metal fluctuations, squeezing margin on volume rack contracts.
- CSA certification timelines:Canadian Standards Association testing creates 12-16 week import gates for European and Asian manufacturers without established Canadian distribution partnerships.
- Aluminum substitution limits:Structural load requirements above 1,800 kg static capacity restrict aluminum adoption to edge and networking racks, preserving steel dominance in compute-intensive deployments.
Strategic Opportunities
- Western Canada edge buildouts:Calgary and Edmonton sub-markets remain underpenetrated for modular micro-data centers requiring 24U-36U seismic-rated enclosures.
- Health Canada PMRA guideline alignment:Rack manufacturers who pre-validate grounding and bonding specifications gain first-mover advantage as 2026 equipment specifications tighten.
- Liquid cooling convergence:Integration of rear-door heat exchangers with standardized 19-inch EIA-310-D frames creates premium retrofit bundles for existing air-cooled facilities.
Industry Challenges
- Electrical trades specialization:Shortage of technicians certified for high-voltage DC busway integration within rack assemblies extends deployment timelines for hyperscale projects.
- Legacy containment retrofit:Hot-aisle and cold-aisle configurations in facilities built 2015-2019 require structural rack modifications to accommodate liquid cooling manifolds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Data Center Rack Market |
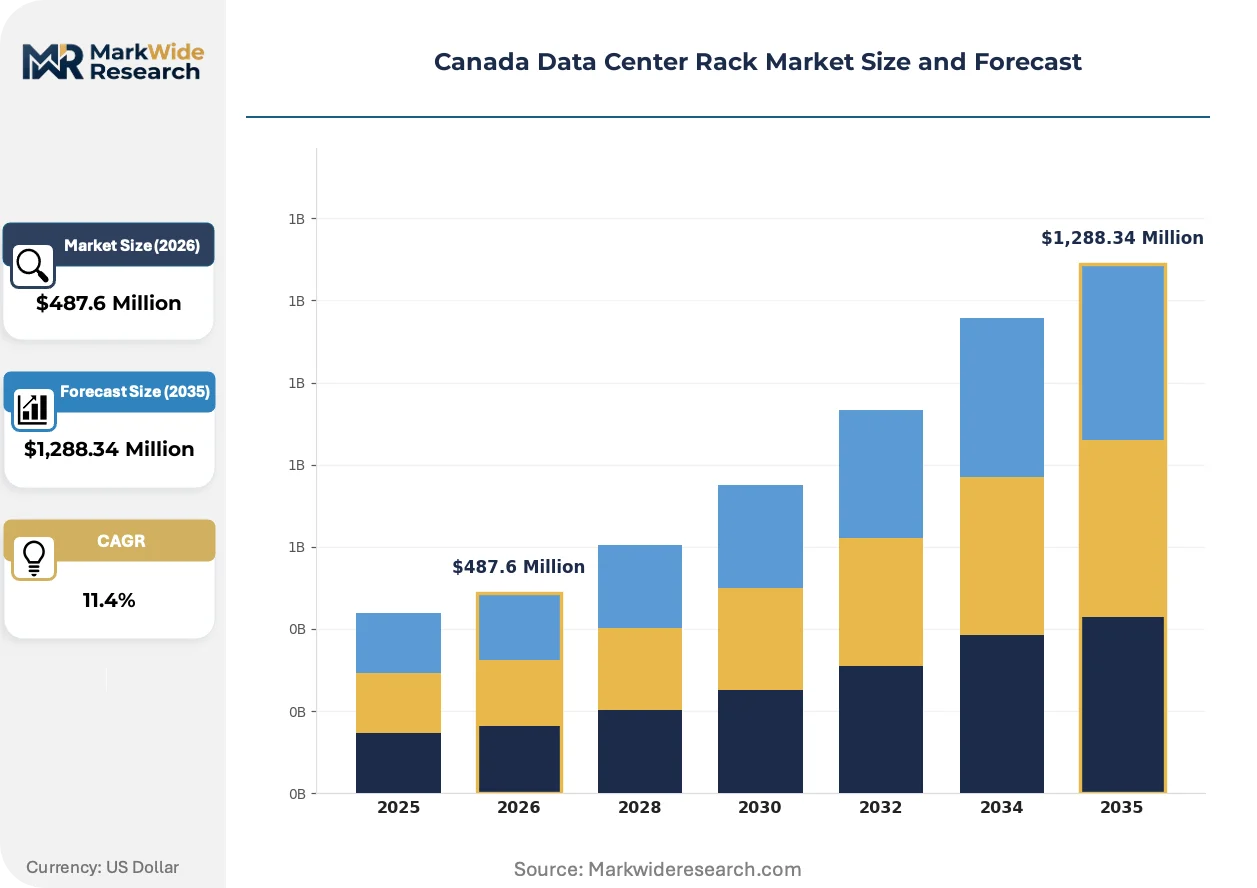
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame Racks, Enclosed Racks, Wall-Mounted Racks, Rack Accessories Material: Steel, Aluminum, Plastic, Wood End User: Cloud Service Providers, Telecom Operators, Enterprises, Co-Location Providers Deployment: On-Premises, Off-Premises, Hybrid, Managed Services |
| Companies Covered | Rittal GMBH & Co.KG, Schneider Electric SE, Vertiv Group Corp., Eaton Corporation plc, Dell Technologies Inc., Hewlett Packard Enterprise, nVent Electric plc, Black Box Corporation, Chatsworth Products, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Data Center Rack Market Trends and Innovations
Liquid-cooling infrastructure is rewriting rack specification sheets as thermal densities exceed 30 kW per enclosure. Manufacturers now engineer for coolant distribution integration at the frame level rather than treating cooling as an aftermarket add-on.
Aluminum extrusion framing is expanding into high-frequency trading and edge compute deployments where weight reduction cuts shipping costs and thermal conductivity improves passive heat dissipation. Financial services operators in Toronto's downtown core specify aluminum 42U racks for rapid floor-loading in leased office conversions. The material shift is expanding into adjacent segments as co-location providers test aluminum for multi-tenant environments with lower static load requirements.
Health Canada's PMRA guidelines are tightening electromagnetic compatibility and grounding standards for data center equipment installations. Rack-level bonding specifications now require documented continuity testing before provincial electrical safety authorities issue occupancy permits. Ontario-based hyperscale builds are responding by specifying factory-tested grounding busbars integrated into enclosure frames, compressing field certification timelines.
Co-location buyers are consolidating vendor relationships and demanding ten-year frame warranties with guaranteed spare parts availability. This procurement compression favors rack manufacturers with Canadian distribution partnerships and domestic inventory staging. Montreal's multi-tenant facilities are most visible in this shift, negotiating volume framework agreements that bundle enclosures with pre-installed vertical PDUs and cable management.
Canada Data Center Rack Market Segmentation
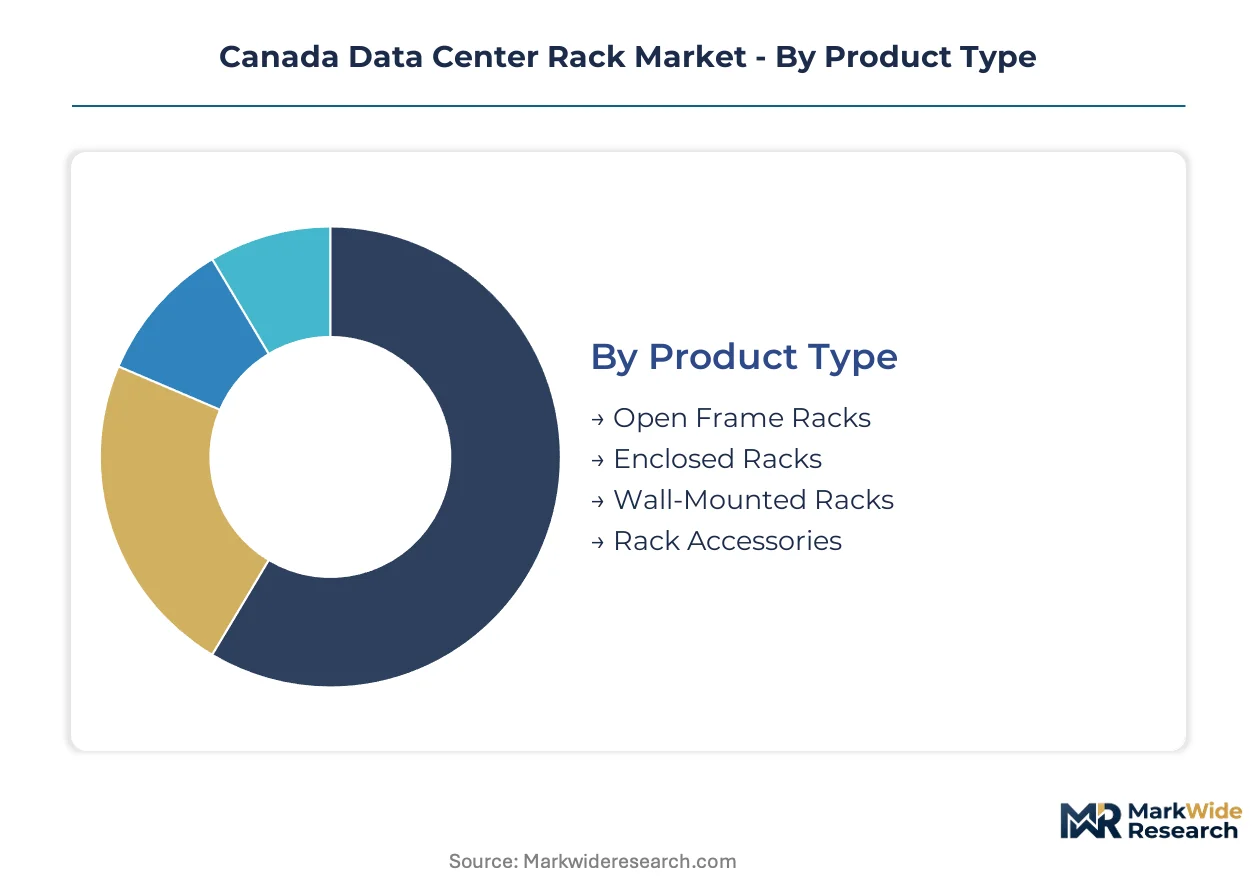
Data center rack procurement in Canada clusters around thermal containment requirements and provincial carbon intensity mandates. Understanding how product specifications, material choices, and deployment models intersect with Health Canada PMRA guidelines reveals where margin concentrates across the value chain.
Product Type:
Supply concentration favors manufacturers with integrated liquid-cooling architectures certified for Ontario and Quebec hyperscale builds.
- Enclosed Racks:Full-height cabinets with sealed containment systems support rear-door heat exchanger integration and particulate-sensitive environments. Toronto's Greater Golden Horseshoe hyperscale facilities specify these for GPU-heavy AI clusters where thermal densities exceed 30 kW per enclosure.
- Open Frame Racks:Four-post skeletal structures without side panels maximize front-to-rear airflow for legacy air-cooled facilities. Montreal co-location providers favor open frames for multi-tenant halls with lower power densities and established hot-aisle containment.
- Wall-Mounted Racks:Compact 12U-18U enclosures serve edge compute nodes in Calgary and Edmonton office conversions where floor space constraints dominate.
- Rack Accessories:Vertical PDUs, cable management arms, and grounding busbars comprise the attach rate ecosystem, with Canadian Standards Association certification driving vendor selection.
Enclosed racks absorb the bulk of installed capacity; wall-mounted racks are expanding most quickly.
Material:
Cost tier differentiation separates volume steel contracts from premium aluminum specifications for weight-sensitive deployments.
- Steel:Cold-rolled carbon steel dominates compute-intensive racks above 1,800 kg static load requirements. Established Canadian mill supply chains in Hamilton and Sault Ste. Marie anchor procurement for hyperscale volume agreements.
- Aluminum:Extruded aluminum framing cuts shipping costs and improves thermal conductivity for edge and networking racks. Financial services operators in downtown Toronto specify aluminum 42U units for rapid deployment in leased facilities.
- Plastic:Reinforced polymer enclosures serve temporary staging and development environments with minimal structural demands.
- Wood:Specialty acoustic-dampening enclosures appear in broadcast and media production data centers with unique sound attenuation requirements.
Steel retains the dominant share of material tonnage; aluminum is climbing the fastest among alternative substrates.
End User:
Customer type determines warranty expectations and spare parts availability terms, with co-location buyers consolidating vendor relationships most aggressively.
- Co-Location Providers:Multi-tenant facilities in Montreal and Vancouver negotiate ten-year frame warranties with guaranteed parts availability. These buyers bundle enclosures with pre-installed vertical PDUs and cable management to compress deployment timelines.
- Cloud Service Providers:Hyperscale operators in Ontario and Quebec demand 48U+ high-density enclosures with integrated busway power distribution for AI training infrastructure.
- Enterprises:Corporate-owned facilities in Calgary and Edmonton favor standardized 42U configurations with hybrid deployment flexibility.
- Telecom Operators:Central office retrofits drive demand for seismic-rated 24U-36U enclosures with NEBS-compliant grounding specifications.
Cloud service providers command the largest single-buyer volumes; co-location providers are gaining share fastest.
Deployment:
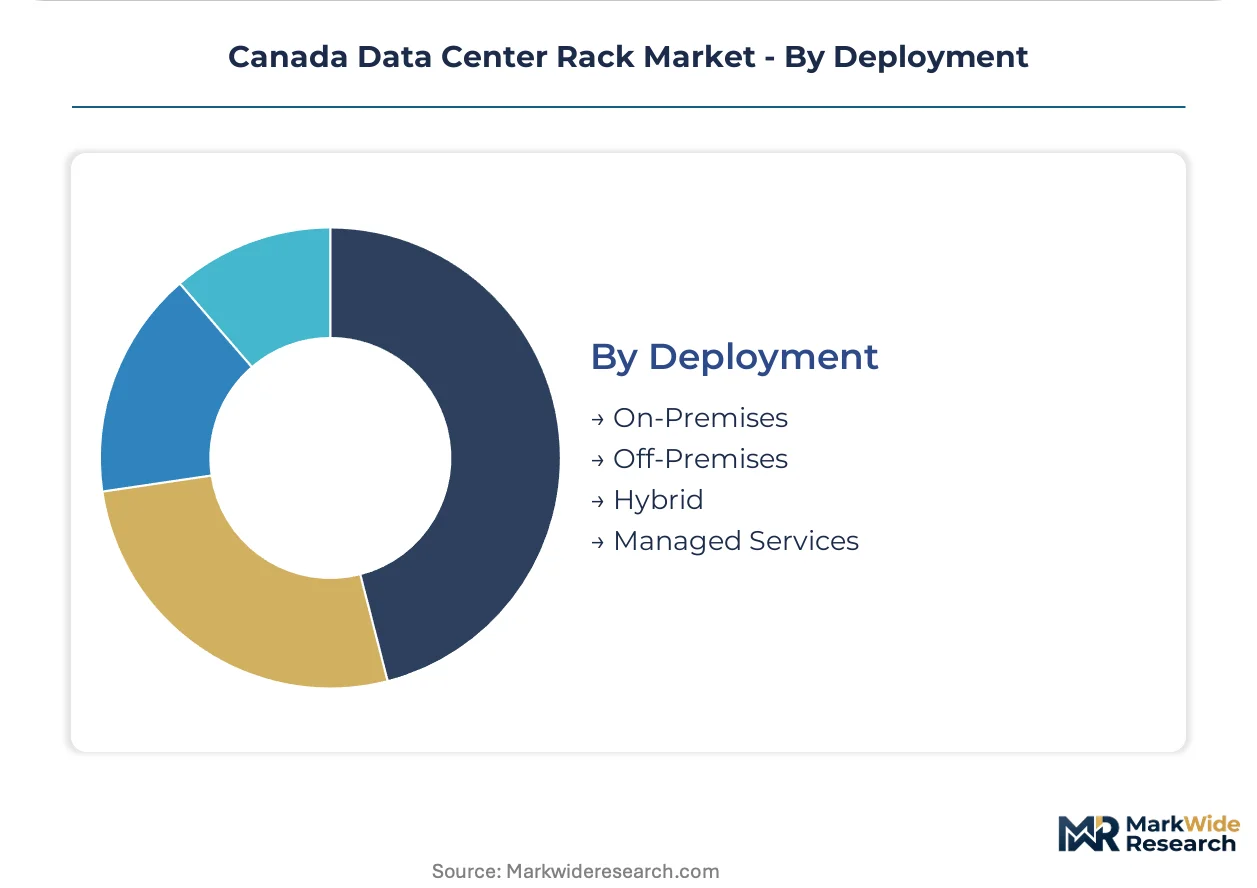
Maturity gradients separate legacy on-premises infrastructure from emerging hybrid architectures requiring modular rack standardization.
- On-Premises:Enterprise-owned facilities in Toronto and Vancouver maintain dedicated rack fleets with customized cable management for legacy application stacks.
- Hybrid:Split workload architectures spanning owned and leased capacity drive demand for standardized 19-inch EIA-310-D frames compatible across provider footprints.
- Off-Premises:Fully outsourced co-location and cloud deployments concentrate procurement decisions with Montreal and Vancouver facility operators.
- Managed Services:Third-party operated infrastructure bundles rack-level monitoring and maintenance into service agreements, favoring manufacturers with Canadian service partnerships.
On-premises deployment retains the largest installed base; hybrid configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's Data Centre Innovation Program accelerates hyperscale clustering in the Greater Golden Horseshoe corridor, where provincial tax credits and hydroelectric proximity concentrate rack procurement decisions.
Ontario
Toronto's Greater Golden Horseshoe corridor hosts hyperscale cloud builds demanding 48U+ liquid-ready enclosures. Health Canada's PMRA electromagnetic compatibility reviews compress procurement timelines for rack manufacturers. Waterloo Region and Ottawa sub-markets expand edge compute nodes serving financial services and government workloads.
Quebec
Montreal's multi-tenant facilities negotiate ten-year frame warranties bundling enclosures with pre-installed vertical PDUs. The province's hydroelectric grid advantage pushes operators toward heat-recapture rack designs qualifying for efficiency incentives. Quebec City and Laval sub-markets scale redundant facilities for regional cloud disaster-recovery requirements.
British Columbia
Vancouver co-location providers consolidate vendor relationships for standardized rack volume serving Asia-Pacific connectivity strategies. Provincial carbon intensity requirements reshape specifications for energy disclosure compliance. Burnaby and Richmond sub-markets attract submarine cable landing stations requiring seismic-rated enclosures.
Alberta
Calgary and Edmonton sub-markets remain underpenetrated for modular micro-data centers requiring 24U-36U seismic-rated enclosures. The province's energy sector diversification drives demand from oil and gas digital transformation projects. Rocky View County and Strathcona County industrial zones anchor emerging edge compute deployments.
Atlantic Canada
Halifax emerges as a subsea cable hub connecting North America to Europe, driving demand for 42U standardized configurations. Provincial economic development authorities target data center investment through customized incentive packages. Moncton and St. John's sub-markets serve regional enterprise and government cloud migration requirements.
Canada Data Center Rack Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated power-cooling portfolios commanding premium positioning in hyperscale procurement. The vendor base organizes around three strategic archetypes: German-engineered enclosure specialists, integrated infrastructure conglomerates, and North American liquid-cooling innovators. Capacity pre-certification and Canadian distribution partnerships represent the dominant competitive moves as Health Canada's PMRA tightens 2026 equipment specifications.
Within the integrated infrastructure tier, Schneider Electric SE anchors premium rack-plus-PDU bundles through its power and cooling portfolio breadth. Rittal GMBH & Co.KG exemplifies German-engineered enclosure standards adapted for North American voltage configurations. Vertiv Group Corp. occupies a position at the high-density segment with liquid-ready rack architectures designed for AI workloads. These three entities represent distinct archetypes competing across Ontario and Quebec hyperscale builds, Montreal co-location facilities, and Western Canada edge deployments.
| Leading Market Players |
|---|
| Rittal GMBH & Co.KG |
| Schneider Electric SE |
| Vertiv Group Corp. |
| Eaton Corporation plc |
| Dell Technologies Inc. |
| Hewlett Packard Enterprise |
| nVent Electric plc |
| Black Box Corporation |
| Chatsworth Products |
| Others |
Pricing and Supply Chain Analysis
Liquid-cooling integration at the frame level is compressing cost economics while concentrating procurement power among manufacturers with pre-certified Health Canada PMRA architectures. This production-method transition simultaneously elevates upfront engineering investments and rewards established Canadian distribution partnerships with volume pricing leverage.
Pricing Analysis
Volume steel contracts anchor the economy tier while premium aluminum specifications and integrated liquid-cooling bundles command margin expansion. Three-tier pricing structure across premium, standard, and economy levels separates CSA-certified liquid-ready enclosures from basic open-frame configurations. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the steel tier is intensifying because Canadian mill supply chains face scrap metal input pressure. Co-location providers exhibit the highest price sensitivity due to ten-year warranty demands, whereas hyperscale cloud operators prioritize thermal performance over unit cost.
Supply Chain Analysis
Cold-rolled carbon steel supply rests on Canadian mill production in Hamilton and Sault Ste. Marie, while aluminum extrusion feeds from US and Chinese specialty metal producers. Raw material dependencies span steel coil, aluminum billet, and copper busbar for power distribution integration. Single-source vulnerability concentrates in CSA certification testing capacity, where 12-16 week import gates constrain European and Asian manufacturers. Distribution runs through direct OEM relationships with hyperscale builders and tier-one electrical distributors serving co-location and enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around pre-certification capabilities as Health Canada PMRA electromagnetic compatibility reviews compress procurement timelines and squeeze out manufacturers lacking Canadian distribution partnerships.
For Market Incumbents: Hedge against aluminum substitution limits by securing long-term steel supply agreements with Hamilton and Sault Ste. Marie mills while building captive liquid-cooling integration capacity. Vertiv Group Corp.'s dominance in high-density AI workloads demonstrates how early busway power distribution investment creates defensive moats. CSA certification pre-validation represents the critical lever for compressing field deployment timelines. For New Entrants and Emerging Players: Capture underpenetrated Western Canada edge buildouts in Calgary and Edmonton where seismic-rated 24U-36U enclosures face limited domestic competition. Modular micro-data center deployments in Rocky View County and Strathcona County industrial zones offer the most penetrable entry point. A go-to-market angle emphasizing factory-tested grounding busbars aligned with Ontario's tightening 2026 equipment specifications bypasses incumbent certification advantages. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated infrastructure conglomerates seeking Canadian distribution footprints. Long-term viability over the coming decade favors manufacturers with domestic inventory staging and established CSA testing partnerships. Watch for Health Canada PMRA guideline finalization as the inflection signal triggering accelerated consolidation among unprepared mid-tier suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| CSA Certification Pre-Validation | Compresses 12-16 week import gates for Ontario and Quebec hyperscale builds. |
| Liquid-Cooling Integration Investment | Captures premium retrofit bundles as Toronto AI clusters exceed 30 kW per enclosure. |
| Canadian Distribution Partnership | Enables ten-year warranty commitments required by Montreal co-location providers. |
| Steel Supply Agreement | Insulates margin from scrap metal volatility in Hamilton and Sault Ste. Marie mills. |
| Heat-Recapture Rack Development | Qualifies for Quebec hydroelectric efficiency incentives and Ontario clean energy targets. |
Research Methodology
Trade publications, hyperscaler capex disclosures, and Canadian Standards Association certification databases formed the secondary backbone, supplemented by customs records tracking steel and aluminum rack imports. Primary interviews with data center facility managers, electrical contractors specializing in high-voltage DC busway integration, procurement leads at co-location providers, and provincial electrical safety authority inspectors validated demand assumptions. Bottom-up installation counts across Toronto's Greater Golden Horseshoe corridor, Montreal multi-tenant facilities, and Vancouver co-location sites were triangulated against top-down market value estimates.
Historical trendline analysis of hyperscale build announcements and provincial incentive program allocations informed the projection framework. Segmentation dimensions modeled include product type, material substrate, end-user archetype, and deployment configuration across the analysis window. CAGRs were derived from weighted average growth rates across Ontario, Quebec, British Columbia, and Alberta sub-markets. Forecast inputs incorporated Health Canada PMRA guideline implementation timelines and provincial carbon intensity mandate enforcement patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to steel price volatility and CSA certification capacity expansion. Projections reflect assumptions regarding hyperscale cloud provider facility commitments and provincial efficiency incentive continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Converged Infrastructure Management Market
Data Center Infrastructure
Middle East Data Center Physical Security Market
Data Center Infrastructure
Global Hyper-Converged Infrastructure Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
Austria Data Center Physical Security Market
Data Center Infrastructure
Middle East Data Center Power Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
Nigeria Data Center Physical Security Market
Data Center Infrastructure
France Data Center Construction Market
Data Center Infrastructure
Ireland Data Center Physical Security Market
Data Center Infrastructure
Sweden Data Center Power Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
Long Term Data Retention Solutions Market
Data Center Infrastructure
Belgium Data Center Market