
 Global Teeth Whitening Product Market | 2026-2036
Global Teeth Whitening Product Market Size, Share, and Industry Trends Forecast 2026-2036
Global Teeth Whitening Product Market Intelligence
The capability gap in global-scale brand marketing is unwinding the competitive advantage once held by smaller, niche players. Procter & Gamble leverages its extensive distribution network and consumer marketing budget to dominate the whitening strips segment. Colgate-Palmolive Company sustains its market position through continuous innovation in whitening toothpaste formulations. In contrast, Ultradent Products specializes in professional-grade systems sold primarily through dental practitioners, differentiating on clinical efficacy rather than mass-market appeal.
Teeth whitening products are cosmetic or therapeutic formulations designed to lighten the shade of natural teeth. These products typically employ active ingredients like carbamide peroxide or hydrogen peroxide at varying concentrations to break down stains on the enamel surface. Whitening toothpaste represents the largest product type by volume, serving as a daily-use entry point for consumers. However, whitening strips and kits, often distributed through online stores and pharmacies, command higher price points and offer more significant efficacy.
Regulatory oversight from bodies like the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) governs peroxide concentration levels in over-the-counter products. In China, the National Medical Products Administration (NMPA) sets stringent registration requirements for cosmetic oral care items, influencing market entry strategies. Navigating the patchwork of regional regulations for active ingredients remains the central challenge for companies seeking to scale new formulations.
Market Dynamics
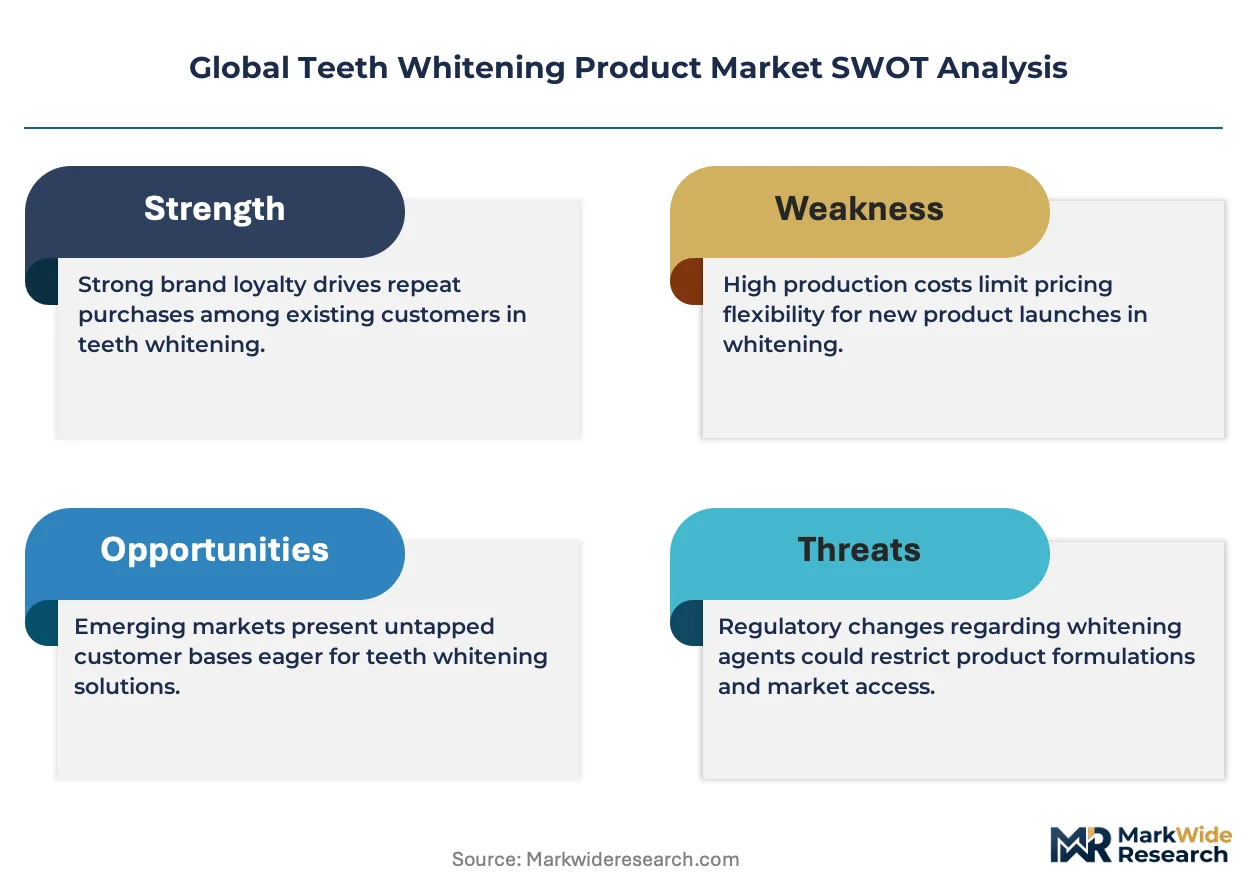
The central dynamic is the global regulatory friction surrounding peroxide concentrations, which is accelerating research into alternative active ingredients like Phthalimidoperoxycaproic Acid (PAP+) to meet consumer demand for sensitivity-free whitening solutions across key markets.
Growth Catalysts
- PAP+ Formulations:Peroxide-free alternatives address widespread consumer concerns about tooth sensitivity and enamel damage, significantly expanding the addressable market to individuals who previously avoided traditional whitening products.
- E-commerce Proliferation:The expansion of direct-to-consumer (DTC) channels through online stores allows challenger brands to bypass traditional retail gatekeepers, reaching a global audience for whitening kits and strips.
- Urbanization in Asia:Rising disposable incomes and a greater focus on personal aesthetics in major metropolitan areas of China and India are spurring higher per-capita spending on cosmetic dental care.
Market Restraints
- Peroxide Concentration Limits:Stringent regulations, such as those enforced by the European Medicines Agency (EMA), cap peroxide levels in over-the-counter products, limiting the whitening efficacy of mass-market formulations compared to professional options.
- Professional Treatment Substitution:High-potency, in-office whitening procedures performed by dental practitioners offer a powerful substitution threat, attracting consumers who prioritize immediate and more dramatic results over at-home convenience.
- Ingredient Sourcing Constraints:The supply chain for novel active ingredients like PAP+ is highly concentrated, creating potential for price volatility and sourcing bottlenecks for manufacturers scaling up production.
Strategic Opportunities
- Latin American Market Development:Markets such as Brazil and Mexico exhibit high cosmetic consciousness but lower penetration of at-home whitening systems, presenting a significant opportunity for market entry and expansion.
- Smart Device Integration:Incorporating LED light activators controlled by smartphone applications into whitening kits provides a pathway for product differentiation, personalized treatment regimens, and enhanced user engagement.
- Subscription-Based Models:Implementing recurring delivery services for whitening toothpaste, mouthwash, and maintenance strips can foster brand loyalty and generate predictable, long-term revenue streams from repeat customers.
Industry Challenges
- Navigating Regulatory Patchworks:Achieving product registration across multiple jurisdictions with differing rules, such as the US FDA and China's NMPA, requires substantial administrative resources and can delay global product launches.
- Counterfeit Product Proliferation:The widespread availability of unregulated and often unsafe counterfeit whitening products on major e-commerce platforms erodes consumer trust in legitimate brands and poses a public health risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Teeth Whitening Product Market |
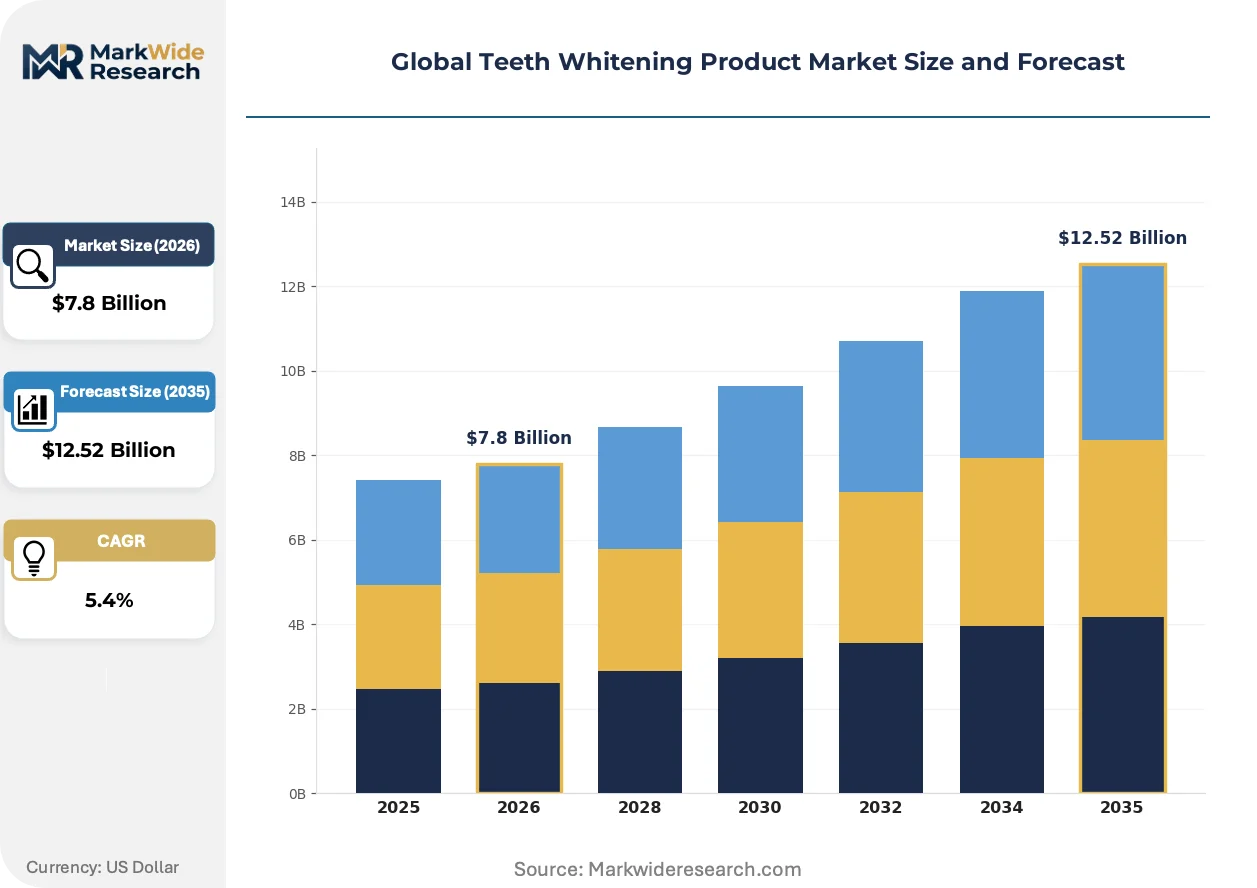
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whitening Toothpaste, Whitening Strips, Whitening Gels, Whitening Kits, Whitening Pens Formulation: Gel, Paste, Powder, Liquid, Foam Sales Channel: Online Stores, Pharmacies, Supermarkets, Specialty Retailers, Dental Clinics End User: Individual Consumers, Dental Practitioners, Beauty Salons, Hygienists |
| Companies Covered | Johnson & Johnson, Unilever, Procter & Gamble, Dentsply Sirona, Ultradent Products, Colgate-Palmolive Company, Philips Oral Healthcare, Church & Dwight, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Teeth Whitening Product Market Strategic Shifts & Innovations
A fundamental shift toward evidence-based cosmetic science is redefining product development, moving beyond basic peroxide bleaching. This evolution prioritizes both clinical efficacy and the mitigation of common side effects like tooth sensitivity and gum irritation.
Phthalimidoperoxycaproic Acid (PAP+) is an organic peroxy acid that whitens teeth through oxidation without releasing the free radicals associated with sensitivity. Challenger brands and direct-to-consumer startups are rapidly adopting PAP+ in their formulations for whitening strips, gels, and pens. This technology is displacing traditional high-concentration carbamide peroxide as the preferred active ingredient for consumers concerned about enamel health.
The European Union's Cosmetic Products Regulation strictly limits over-the-counter teeth whitening products to a maximum of 0.1% hydrogen peroxide. This directive effectively compels manufacturers serving the EU market to either distribute through dental professionals or innovate with non-peroxide alternatives. Consequently, whitening toothpaste and peroxide-free strips are the categories most affected, with brands reformulating products to maintain compliance.
Consumer purchasing behavior is moving from pharmacy-aisle browsing toward influencer-driven discovery on social media platforms like Instagram and TikTok. This trend disrupts the shelf-space dominance of legacy brands in physical retail and creates openings for digitally native brands with strong social proof. This demand-side shift is most pronounced among Millennial and Gen Z demographics in North America and Western Europe.
Global Teeth Whitening Product Market Segmentation
Market segmentation provides a granular view of the diverse channels, product forms, and end-user preferences shaping the global teeth whitening industry. This analysis highlights the distinct dynamics influencing consumer purchasing decisions and professional adoption across various segments. Understanding these differentiations is crucial for strategic market positioning.
Sales Channel:
The distribution landscape for teeth whitening products spans both direct-to-consumer and professional-led channels, each catering to specific customer needs and product types.
- Online Stores:These e-commerce platforms facilitate direct-to-consumer sales, enabling challenger brands to reach a global audience without traditional retail gatekeepers. Demand for whitening kits and strips concentrates here, driven by convenience and competitive pricing.
- Dental Clinics:Professional dental practices serve as a primary outlet for high-potency, in-office whitening procedures and prescription-strength at-home systems. Consumers prioritizing immediate, dramatic results and clinical oversight seek products exclusively through these channels.
- Pharmacies:Retail pharmacies offer over-the-counter whitening toothpastes, gels, and strips, providing accessible options for consumers seeking moderate whitening results.
- Supermarkets:Mass-market whitening toothpastes and basic oral care products are widely available in supermarkets, targeting daily-use consumers at accessible price points.
- Specialty Retailers:Stores focusing on beauty and personal care often stock premium or niche whitening products, appealing to consumers seeking specific formulations or brands.
By volume, whitening toothpastes sold through supermarkets lead. By growth pace, online stores for whitening strips and kits are ahead.
Product Type:
Product types vary significantly, from daily-use oral hygiene items to intensive treatment systems, each designed for different application frequencies and efficacy levels.
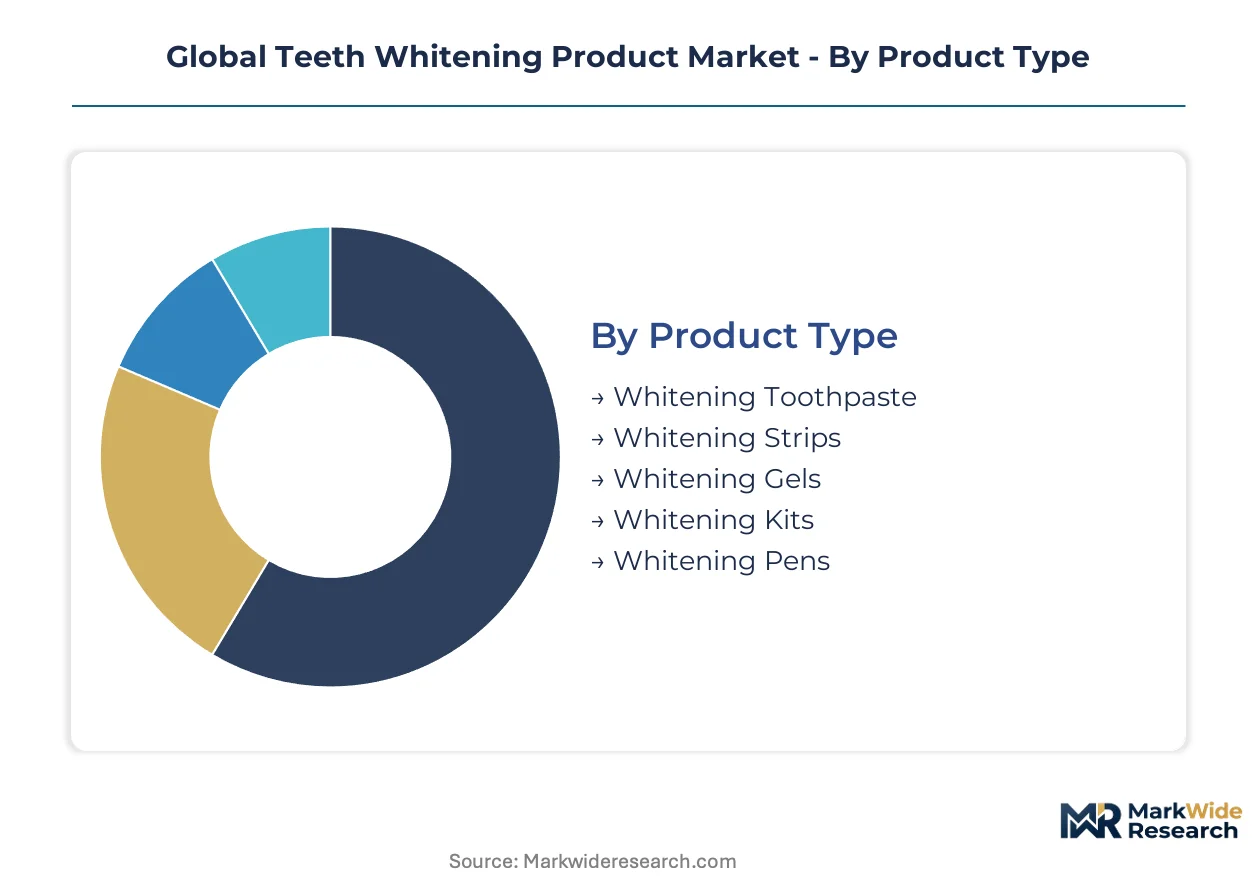
- Whitening Toothpaste:This daily-use formulation incorporates mild abrasives and chemical agents to remove surface stains, serving as a primary entry point for consumers into the whitening category. Its widespread availability through mass retail channels supports its volume dominance.
- Whitening Strips:Thin, flexible strips coated with a whitening agent, typically peroxide, are applied directly to teeth for a specified duration, offering more concentrated treatment than toothpaste. These products command higher price points and deliver more significant efficacy, often distributed online.
- Whitening Gels:These viscous formulations containing active whitening ingredients are applied directly to teeth, often used with custom trays or brush applicators.
- Whitening Kits:Comprehensive kits bundle gels, trays, and sometimes LED light activators, providing a multi-step at-home whitening experience for enhanced results.
- Whitening Pens:Compact, portable pens dispense a small amount of whitening gel for targeted application and on-the-go touch-ups, appealing to convenience-seeking consumers.
Whitening toothpaste accounts for the largest share of product units. Whitening kits and strips are expanding most quickly in revenue terms.
End User:
The teeth whitening market serves a diverse range of end-users, from individual consumers seeking at-home solutions to dental professionals offering in-office treatments.
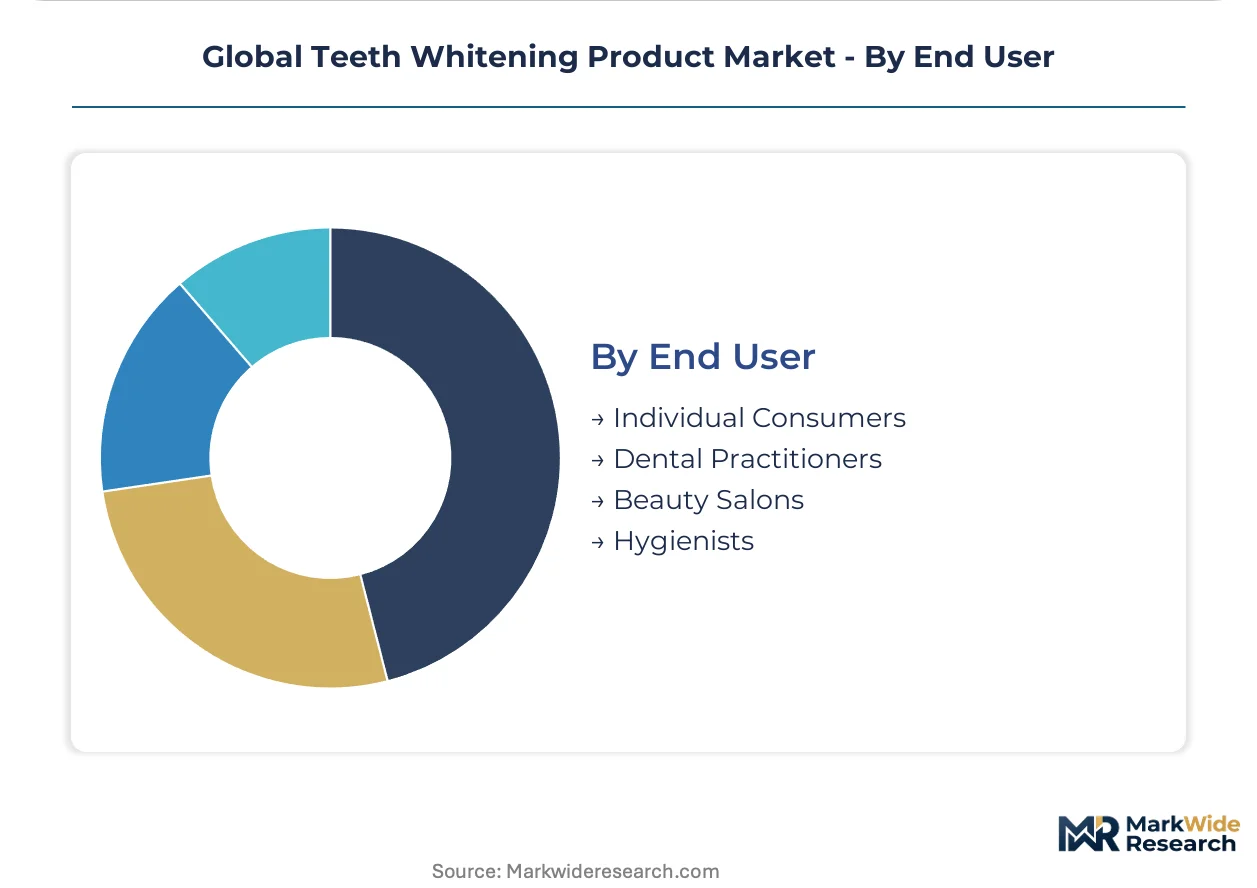
- Individual Consumers:This segment comprises the largest user base, driving demand for convenient, at-home whitening kits, strips, and toothpastes available through retail and online channels. Concerns about tooth sensitivity influence product choices significantly.
- Dental Practitioners:Dentists and orthodontists utilize professional-grade whitening systems for in-office treatments and prescribe higher-concentration at-home kits, differentiating on clinical efficacy and supervised results. Ultradent Products specializes in this distribution model.
- Beauty Salons:Some beauty salons offer cosmetic teeth whitening services, typically using lower-concentration products and non-dental professionals, appealing to a clientele focused on aesthetic enhancements.
- Hygienists:Dental hygienists often recommend and dispense over-the-counter or professional-grade whitening products as part of comprehensive oral care plans.
Demand from individual consumers represents the largest end-user segment. Dental practitioners drive demand for premium, high-efficacy formulations.
Formulation:
Formulation types directly impact product efficacy, application method, and ingredient stability, influencing consumer preference and regulatory compliance.
- Gel:Gels are common in whitening kits, pens, and professional applications, allowing for controlled delivery of active ingredients like hydrogen peroxide or PAP+ onto tooth surfaces. Their viscous nature ensures adherence and prolonged contact.
- Paste:Whitening toothpastes utilize a paste formulation, combining abrasive agents with chemical whiteners for daily oral hygiene. This form offers ease of use and integrates into existing brushing routines.
- Powder:Whitening powders, often charcoal-based or containing baking soda, are typically used by mixing with water or toothpaste, providing an abrasive stain-removal action.
- Liquid:Liquid formulations are found in whitening mouthwashes or rinses, offering a less intensive, complementary whitening effect through regular use.
- Foam:Foaming whitening products provide an alternative application method, often used in trays, designed for even distribution and comfortable wear.
Paste formulations dominate in terms of daily consumer usage. Gel formulations are gaining share fastest due to their versatility in kits and pens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer price sensitivity for teeth whitening products varies significantly, with daily-use options exhibiting higher elasticity compared to premium professional treatments. Consumers in emerging markets often prioritize affordability, while those in developed economies accept higher price points for advanced efficacy or convenience. This demand-elasticity spectrum shapes product development and market entry strategies across diverse geographies.
China
Demand for cosmetic dental care in China is surging due to rising disposable incomes and a strong focus on personal aesthetics. The National Medical Products Administration (NMPA) imposes stringent registration requirements for oral care cosmetics, influencing market entry for new formulations. Major metropolitan areas like Shanghai and Beijing demonstrate high per-capita spending on whitening kits and professional treatments.
India
India's teeth whitening market experiences substantial growth, driven by increasing urbanization and a growing middle class adopting Western beauty standards. The Bureau of Indian Standards (BIS) sets quality benchmarks for cosmetic products, guiding local manufacturing. Cities such as Mumbai and Delhi are key demand hubs, showing increased interest in at-home whitening solutions.
United States
The United States market is influenced by influencer-driven discovery and a strong preference for convenient at-home whitening systems. The US Food and Drug Administration (FDA) regulates peroxide concentrations in over-the-counter products, ensuring consumer safety. Digital-native brands in major tech hubs like Los Angeles and New York leverage e-commerce for direct consumer engagement.
Germany
Germany's market for teeth whitening products is shaped by strict European Union Cosmetic Products Regulation, which limits peroxide levels in over-the-counter offerings. The European Medicines Agency (EMA) oversees pharmaceutical claims, impacting professional-grade product distribution. Urban centers such as Berlin and Munich show consistent demand for peroxide-free alternatives.
Brazil
Brazil presents a significant opportunity for market expansion, characterized by high cosmetic consciousness but lower penetration of advanced at-home whitening systems. The Agência Nacional de Vigilância Sanitária (ANVISA) regulates health products, including dental cosmetics, ensuring product safety. Cities like São Paulo and Rio de Janeiro are key areas for new product launches targeting aesthetic-focused consumers.
Global Teeth Whitening Product Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive structure of the teeth whitening product market. This market exhibits a tiered consolidation, with established oral care giants dominating mass-market segments through extensive distribution. Two strategic archetypes emerge: broad-portfolio consumer goods companies and niche specialists focusing on professional-grade solutions. Geographic expansion into underpenetrated markets and continuous product innovation represent dominant competitive moves for market participants.
At the scale-driven end, Procter & Gamble, a US-based corporation, exemplifies a leader leveraging extensive brand recognition and distribution networks for mass-market penetration, particularly in whitening strips. Colgate-Palmolive Company, another prominent US-based entity, occupies a position focused on continuous innovation within whitening toothpaste formulations and broader oral care. Ultradent Products, Inc., an American manufacturer, anchors the professional-grade segment, specializing in systems sold through dental practitioners, differentiating on clinical efficacy. These companies collectively illustrate the market's segmentation by distribution channel and product focus.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Unilever |
| Procter & Gamble |
| Dentsply Sirona |
| Ultradent Products |
| Colgate-Palmolive Company |
| Philips Oral Healthcare |
| Church & Dwight |
| GlaxoSmithKline |
| Others |
Cost & Logistics Intelligence
The US Food and Drug Administration's (FDA) stringent approval processes gate both supply qualification and price differentiation across the teeth whitening product market. This regulatory oversight influences ingredient sourcing and manufacturing standards, directly impacting final product costs and market positioning.
Pricing Analysis
Recurring purchases of whitening toothpaste and maintenance strips drive lifetime value within the teeth whitening market. Premium-mid-economy pricing differentiation exists across product types, with professional-grade systems commanding the highest price points. Price differentiation stems from clinical efficacy claims and brand premium. Pricing softness stems from the proliferation of counterfeit products and intense competition in the mass-market segment. Individual consumers purchasing through online stores exhibit the highest price sensitivity.
Supply Chain Analysis
Inventory management for novel active ingredients like PAP+ presents significant lead-time challenges for manufacturers. The supply chain for key chemical components, including hydrogen peroxide and carbamide peroxide, primarily concentrates in China and India. Ingredient sourcing concentration for PAP+ creates a structural risk for manufacturers scaling production. Distribution runs through a fragmented network of online stores, retail pharmacies, and dental clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The teeth whitening market is experiencing a platform-economics inflection, driven by the integration of smart device ecosystems and personalized treatment regimens.
For Market Incumbents: Consolidate existing market share through strategic acquisitions of digitally native brands specializing in PAP+ formulations. Invest heavily in R&D for non-peroxide alternatives to mitigate regulatory threats from evolving peroxide concentration limits. Leverage extensive global distribution networks to counter the e-commerce advantage of challenger brands.
For New Entrants and Emerging Players: Personalized regimen tracking and proactive re-ordering services represent a service-layer gap where incumbents under-serve individual consumers. Target the underpenetrated Latin American markets with culturally relevant marketing strategies. Focus on smart device integration for whitening kits, offering a unique value proposition. Utilize influencer-driven discovery on social media platforms for rapid market penetration among Millennial and Gen Z demographics.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across the at-home whitening kit segment, driven by investments in smart device integration and specialized ingredient sourcing. The market offers long-term growth opportunities over the next decade for companies innovating in peroxide-free formulations. Target niche PAP+ formulation specialists with strong direct-to-consumer presence. The signal to watch is regulatory shifts in key markets favoring peroxide-free solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| PAP+ Formulation R&D | Develops sensitivity-free products, expanding the addressable market for cosmetic dental care. |
| Direct-to-Consumer Channel Expansion | Bypasses traditional retail gatekeepers, enabling challenger brands to reach a global audience. |
| Smart Device Integration | Offers product differentiation and personalized treatment regimens, enhancing user engagement. |
| Latin American Market Entry | Captures demand from regions with high cosmetic consciousness and lower penetration rates. |
| Subscription-Based Service Launch | Fosters brand loyalty and generates predictable, long-term revenue streams from repeat customers. |
Research Approach
Operator-level perspectives from dental practitioners, brand managers, regulatory affairs specialists, and e-commerce platform executives anchored the qualitative base for this analysis. This primary research was complemented by extensive secondary validation, drawing from regulatory body guidelines, industry association reports, and published academic studies. The approach utilized both bottom-up and top-down triangulation to ensure comprehensive market sizing.
Sensitivity analysis assessed the impact of varying regulatory scenarios and consumer preference shifts on market trajectories over the projection horizon. Segmentation dimensions modeled included sales channel, product type, end user, formulation, and regional regulatory cluster. Compound annual growth rates were derived from historical data and projected growth drivers. Key industry-specific forecast inputs included peroxide concentration limits and PAP+ adoption rates.
Underlying assumptions cover regulatory stability and continued consumer aesthetic focus, with deviation risk concentrated in unforeseen ingredient sourcing disruptions or rapid shifts in social media trends. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Crack Tooth Syndrome Market
Dental Materials
Global Dental Zirconia Block Market
Dental Materials
Artificial Teeth Market
Dental Materials
Dental Restorative and Regenerative Material Market
Dental Materials
Dental Bonding Agent Market
Dental Materials
Dental Alloys Market
Dental Materials
Remineralizing Gum Market
Dental Materials
Sensitive Toothpaste Market
Dental Materials
Global Zirconia Based Dental Materials Market
Dental Materials
Cold Light Teeth Whitening Kit Market
Dental Materials
Dental Alginate Market
Dental Materials
Dental Cavity Filling Material Market
Dental Materials
Tooth Filling Materials Market
Dental Materials
Global Dental Cements Market
Dental Materials
Charcoal Teeth Whitening Powder Market
Dental Materials
Teeth Whitening Market