
 Charcoal Teeth Whitening Powder Market | 2026-2036
Charcoal Teeth Whitening Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Charcoal Teeth Whitening Powder Market Insights
ISO 22716 certification for cosmetics Good Manufacturing Practices is unwinding the competitive landscape, filtering out unqualified entrants and elevating compliance costs for smaller brands. Procoal leverages its UK manufacturing base to sustain premium positioning across European pharmacy channels. Carbon Coco anchors its growth through social-native marketing and direct-to-consumer distribution in English-speaking markets. Georganics differentiates via plastic-free packaging and zero-waste credentials that resonate with environmentally selective buyers.
Charcoal teeth whitening powder comprises finely milled carbonaceous material, typically activated at temperatures exceeding 600°C to achieve porous surface areas above 500 m²/g for adsorptive stain lift. The product functions primarily as a cosmetic dentifrice adjunct, mechanically and chemically binding surface discoloration from chromogenic foods, beverages, and tobacco without peroxide oxidation. Activated charcoal dominates product type segmentation due to established supply chains and superior porosity metrics, though coconut shell charcoal is gaining fastest as a sustainable feedstock alternative with lower ash content. Among applications, cosmetic whitening commands the largest volume share while sensitivity reduction represents the emerging margin pool, commanding price premiums through formulation complexity with added remineralizing agents.
The FDA regulates charcoal oral products under cosmetic and overlapping drug claim jurisdictions, requiring careful claim substantiation that separates aesthetic whitening from therapeutic dental benefits. REACH compliance across Europe governs trace heavy metal limits in charcoal feedstocks, directly shaping supplier qualification and raw material sourcing decisions. India's BIS and CDSCO frameworks are tightening import standards for activated carbon oral preparations, affecting cross-border brand entry. Stakeholders must monitor evolving classification boundaries between cosmetics and medical devices as regulators scrutinize enamel safety data and abrasive index thresholds.
Market Dynamics
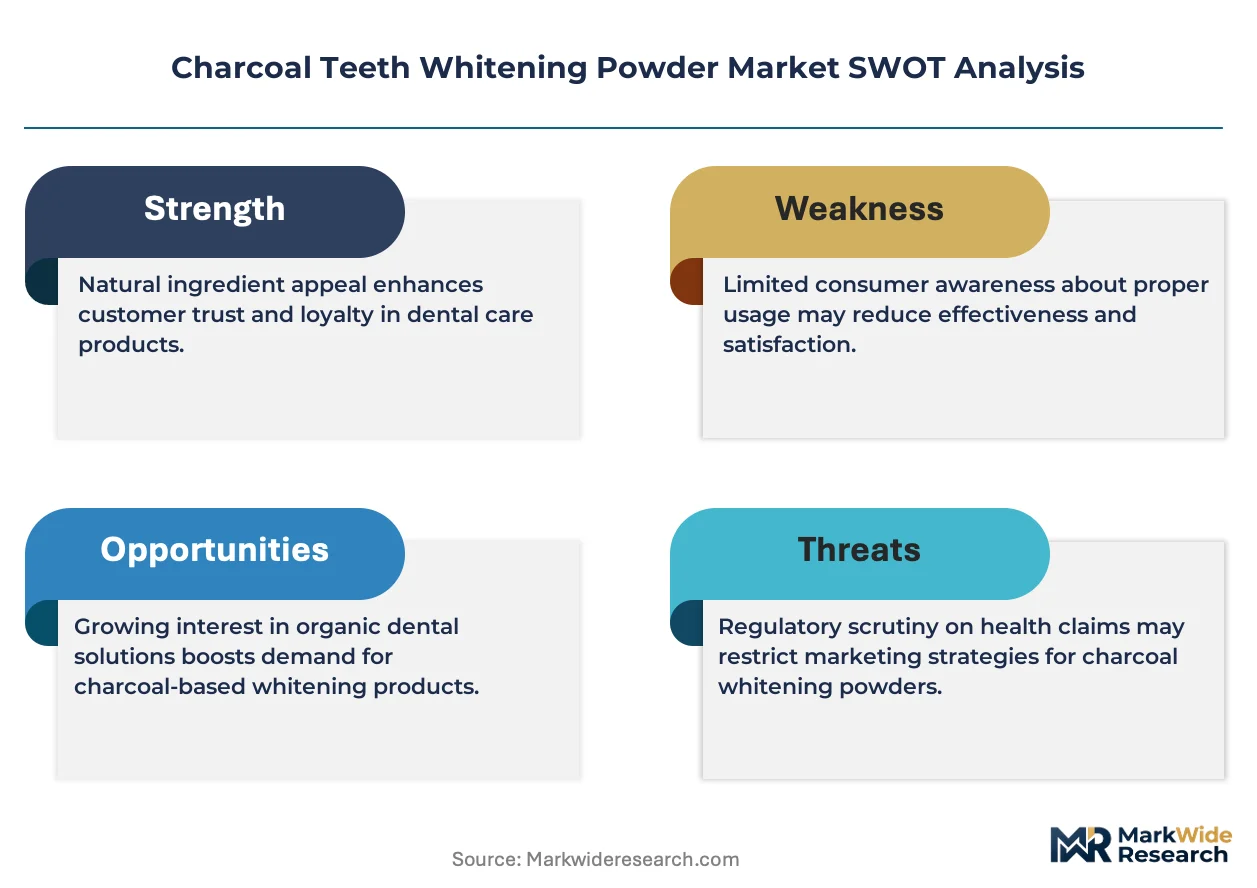
ISO 22716 certification requirements are filtering out unqualified manufacturers and elevating compliance costs, concentrating supply among established producers with verified Good Manufacturing Practices credentials.
Growth Catalysts
- REACH compliance enforcement:European regulators are tightening trace heavy metal limits in charcoal feedstocks, pushing brands toward qualified suppliers and creating competitive moats for compliant manufacturers.
- Coconut shell charcoal feedstock:Sustainable sourcing from agricultural waste streams is displacing petroleum-based activated carbon in premium formulations, attracting environmentally selective buyers.
- Direct-to-consumer channel expansion:Social-native marketing and subscription models in the United States are bypassing traditional pharmacy intermediaries, capturing margin and customer data.
Market Restraints
- Enamel safety scrutiny:FDA and dental association abrasive index thresholds limit formulation flexibility, capping mechanical cleaning efficacy in peroxide-free products.
- Raw material concentration:High-grade activated carbon production clusters in Southeast Asian coconut processing regions, exposing supply chains to climate and logistics volatility.
- Peroxide whitening competition:Hydrogen carbamide systems maintain superior efficacy claims for intrinsic stain removal, constraining charcoal powder to surface-stain cosmetic positioning.
Strategic Opportunities
- Sensitivity-reduction formulations:Remineralizing agent integration with charcoal bases commands price premiums in the therapeutic-adjacent segment, expanding beyond purely cosmetic claims.
- Zero-waste packaging mandates:EU Single-Use Plastics Directive implementation is accelerating demand for plastic-free, refillable container systems in pharmacy and specialty retail channels.
- India regulatory alignment:BIS and CDSCO framework convergence with international standards is opening formal import pathways for certified brands previously confined to gray-market entry.
Industry Challenges
- ISO 22716 audit timelines:Certification backlog at accredited bodies is extending product launch schedules by 8-14 months for new market entrants.
- Claim substantiation documentation:FDA cosmetic-drug boundary enforcement requires legal review of all marketing language, increasing compliance overhead for cross-border sellers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Charcoal Teeth Whitening Powder Market |
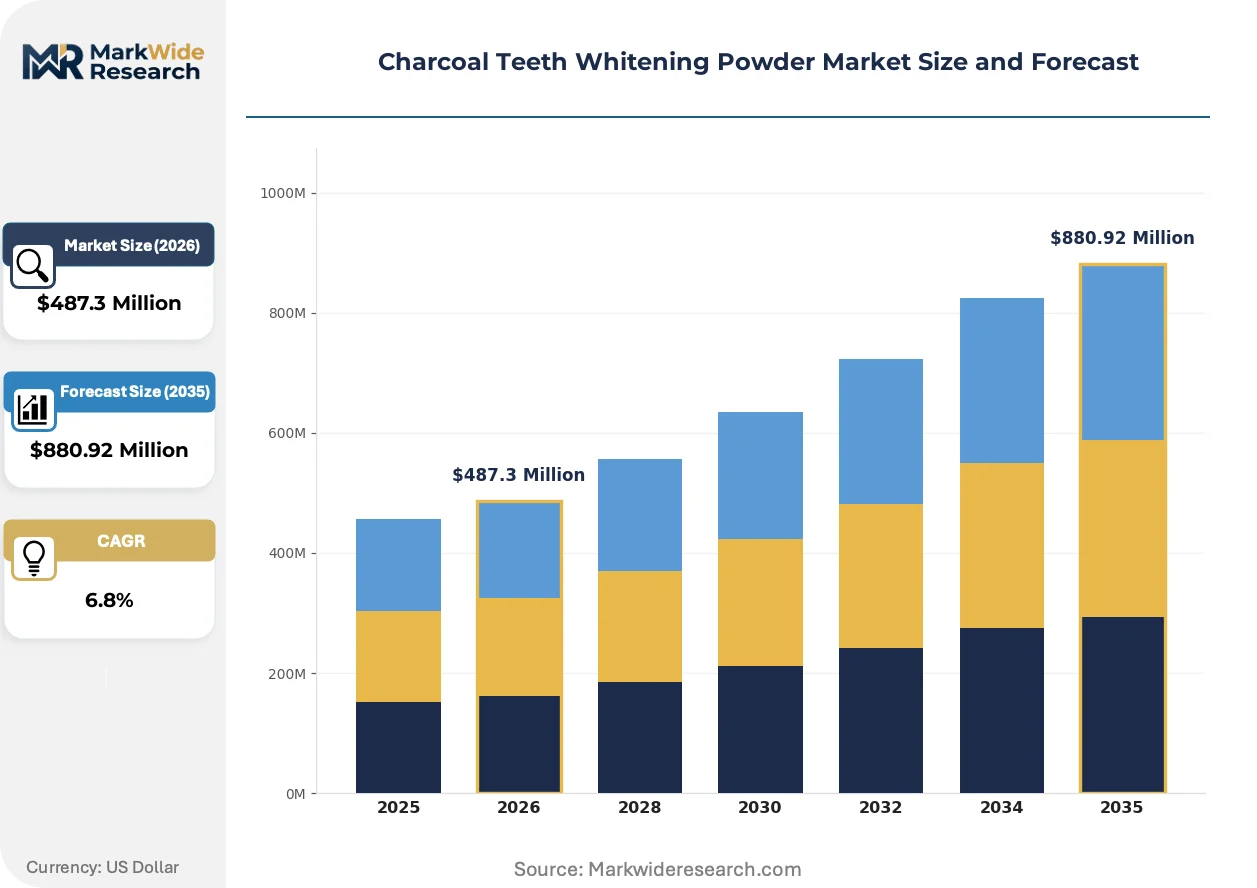
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Charcoal, Bamboo Charcoal, Coconut Shell Charcoal, Walnut Shell Charcoal, Others Application: Daily Oral Care, Cosmetic Whitening, Stain Removal, Fresh Breath, Sensitivity Reduction End User: Dental Clinics, Beauty Salons, Home Users, Natural Product Enthusiasts Distribution Channel: Online Retailers, Pharmacies, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Carbon Coco, Procoal, Georganics, HealthVit, Deyga, Habbits, Apollo Noni, Pro Teeth Whitening Co, TJ Smile Bio-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Charcoal Teeth Whitening Powder Market Trends and Innovations
Formulation science and regulatory classification boundaries are actively reshaping competitive positioning, separating cosmetic dentifrice adjuncts from therapeutic oral care products through evidence requirements and channel access.
Steam-activated coconut shell carbon with surface areas exceeding 800 m²/g is displacing lower-porosity wood-based alternatives in premium formulations. Wellness-focused consumers in English-speaking markets are prioritizing sustainable feedstock provenance over price. This material shift is compressing margins for legacy activated carbon suppliers lacking agricultural waste stream partnerships.
REACH Annex XVII heavy metal thresholds are forcing supplier requalification across European manufacturing bases. ECHA enforcement actions against non-compliant activated carbon imports are redirecting procurement toward certified Southeast Asian processors. German and French pharmacy chains are now requiring batch-specific CoA documentation as a listing prerequisite.
Subscription-based replenishment models are capturing recurring revenue from millennial and Gen Z oral care buyers. Direct-to-consumer brands are disintermediating traditional wholesale pharmacy distribution in the United States and United Kingdom. This channel shift is most visible in urban coastal markets where digital-native purchasing patterns dominate household consumables selection.
Charcoal Teeth Whitening Powder Market Segmentation
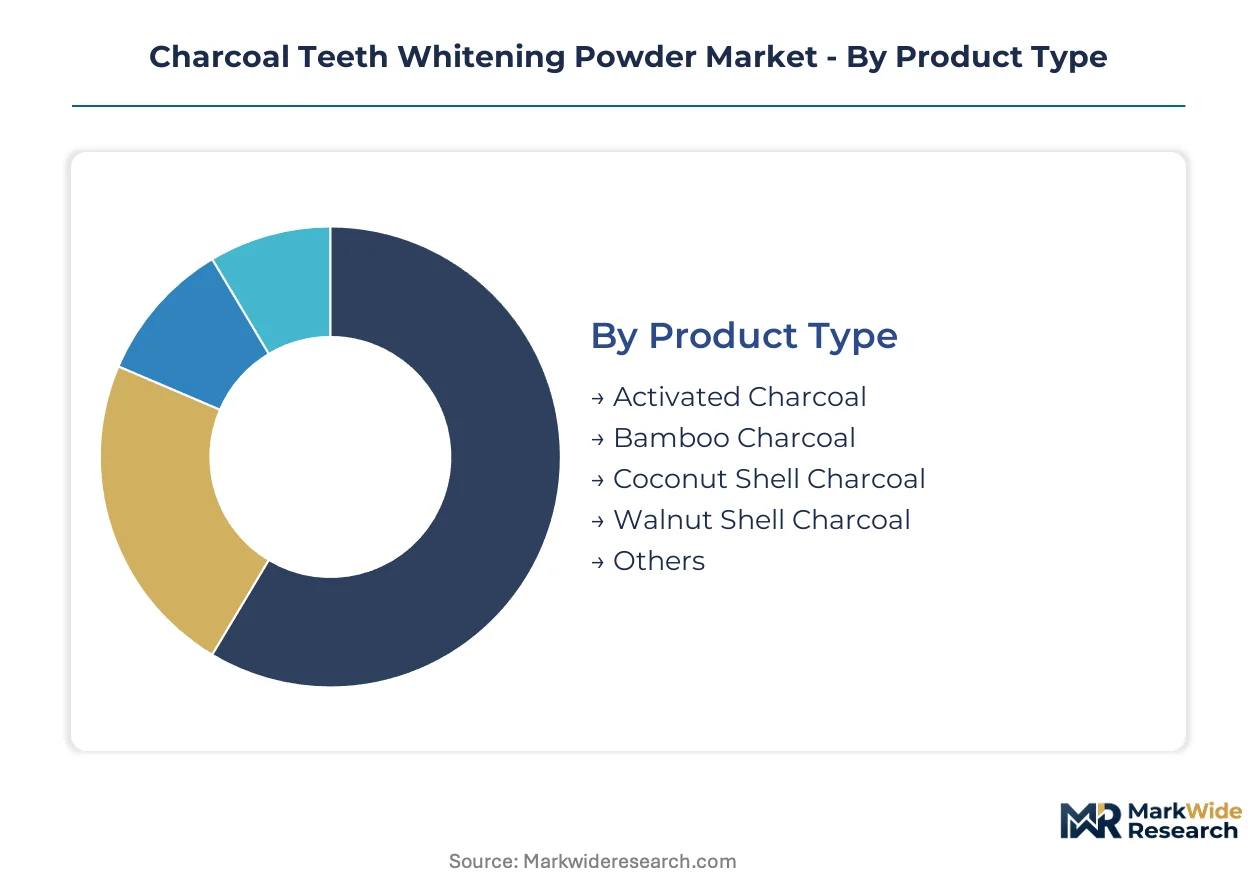
Segmentation in charcoal teeth whitening powder reveals divergent supply chain configurations and regulatory exposure profiles. Product type and application dimensions separate export-dependent feedstock categories from domestically formulated finished goods. Distribution channel choices determine compliance burden intensity and margin capture potential.
Product Type:
Activated charcoal and coconut shell charcoal concentrate production in Southeast Asian coconut processing regions, while bamboo and walnut variants source from domestic agricultural waste streams in China and the United States respectively.
- Activated Charcoal:Steam-activated at temperatures exceeding 600°C to achieve surface areas above 500 m²/g for superior adsorptive stain lift. Demand concentrates in United States direct-to-consumer channels where wellness-focused buyers prioritize established efficacy documentation. FDA cosmetic-drug claim boundaries constrain therapeutic positioning.
- Coconut Shell Charcoal:Agricultural waste-derived feedstock with lower ash content and surface areas exceeding 800 m²/g in premium grades. European pharmacy chains in Germany and France require batch-specific CoA documentation under REACH Annex XVII heavy metal thresholds. Sustainability credentials command price premiums among environmentally selective buyers.
- Bamboo Charcoal:Fast-growing grass species carbonization yields intermediate porosity metrics suitable for mid-tier formulations. Chinese domestic supply dominates raw material availability.
- Walnut Shell Charcoal:Hard-shell agricultural byproduct with abrasive properties requiring careful formulation for enamel safety compliance. United States Great Plains processing clusters provide regional feedstock security.
- Others:Peat-derived and bone char alternatives with limited commercial scale due to religious dietary restrictions and supply inconsistency.
Activated charcoal holds the largest share; momentum sits with coconut shell charcoal.
Application:
Cost tier stratification separates commodity daily oral care from premium sensitivity-reduction formulations with remineralizing agent integration.
- Daily Oral Care:Routine mechanical cleaning adjunct positioned against conventional toothpaste. Volume concentrates in supermarket and pharmacy mass-market channels across English-speaking markets. Price compression from peroxide whitening competition limits margin expansion.
- Cosmetic Whitening:Surface-stain removal focus for chromogenic food and beverage discoloration. United Kingdom and United States urban coastal markets show strongest subscription model adoption. Social-native marketing bypasses traditional wholesale intermediaries.
- Stain Removal:Tobacco and coffee-specific formulation variants with elevated abrasive indices. Dental association scrutiny limits claim substantiation flexibility.
- Fresh Breath:Adsorptive volatile sulfur compound binding with mint oil adjuncts. Lower formulation complexity supports private label proliferation.
- Sensitivity Reduction:Hydroxyapatite or fluoride integration with charcoal bases commands therapeutic-adjacent price positioning. EU pharmacy channel access requires medical device border classification clarity.
Cosmetic whitening dominates volume; sensitivity reduction climbs the fastest on margin expansion.
End User:
Customer type determines channel access rights and professional endorsement requirements, with dental clinics facing the most stringent evidentiary standards.
- Dental Clinics:Professional recommendation-dependent sales requiring clinical safety documentation and abrasive index compliance. German and French markets show strongest formal pharmacy integration.
- Beauty Salons:Cosmetic service augmentation with lower regulatory scrutiny than clinical settings. United States metropolitan spa channels demonstrate recurring purchase potential.
- Home Users:Mass-market self-directed purchasing through digital and retail channels. Subscription retention rates vary sharply by age cohort.
- Natural Product Enthusiasts:Zero-waste packaging and plastic-free credentials drive brand switching behavior. EU Single-Use Plastics Directive accelerates format preference shifts.
Home users command the broadest base; natural product enthusiasts gain share fastest on sustainability mandate alignment.
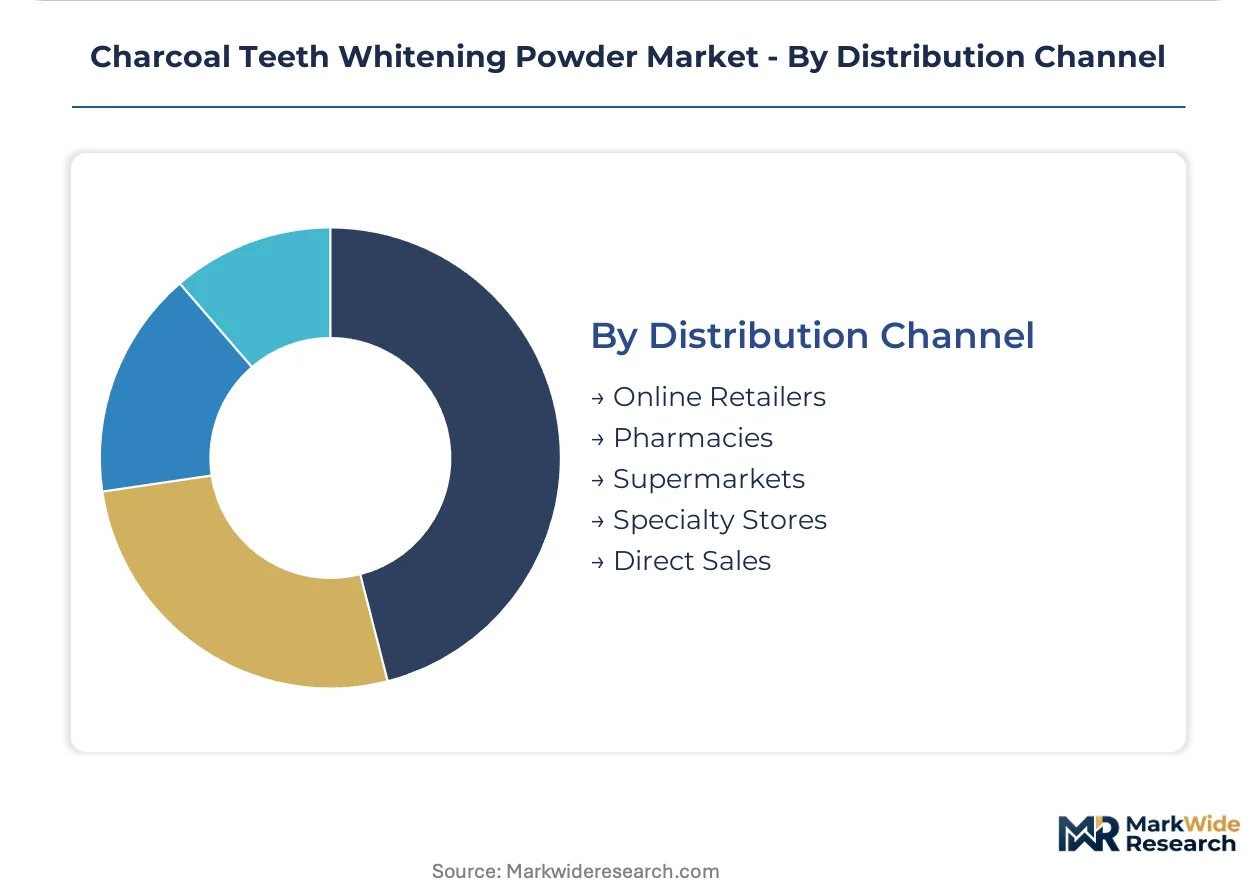
Distribution Channel:
Volume concentration versus margin capture trade-offs separate high-touch specialty retail from automated direct-to-consumer fulfillment.
- Online Retailers:Platform-dependent discovery with algorithmic visibility determining brand success. Amazon and Shopify-native operations dominate United States millennial and Gen Z acquisition.
- Pharmacies:Professional credibility endorsement with ISO 22716 certification and REACH CoA documentation as listing prerequisites. German and French chains enforce batch-specific traceability.
- Supermarkets:Mass-market volume with compressed margins and shelf-space competition against established oral care conglomerates.
- Specialty Stores:Curated wellness positioning with educated staff enabling premium price realization. Urban coastal United States and United Kingdom locations show strongest performance.
- Direct Sales:Subscription replenishment models capturing customer data and recurring revenue. Social-native brand building reduces customer acquisition cost versus paid advertising.
Online retailers hold the largest share; direct sales expands most quickly on margin and data capture advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cosmetic-drug claim boundaries in the United States are reshaping formulation strategies, while REACH Annex XVII enforcement across Europe is redirecting procurement toward certified Southeast Asian processors. Subscription-based replenishment models concentrate in English-speaking urban coastal markets, bypassing traditional pharmacy intermediaries.
United States
Direct-to-consumer brands capture recurring revenue through social-native marketing and subscription models among millennial and Gen Z oral care buyers. FDA oversight of cosmetic oral products requires careful claim substantiation separating aesthetic whitening from therapeutic benefits. Los Angeles and New York metro areas demonstrate strongest digital-native purchasing patterns for wellness-focused consumables.
Germany
Pharmacy chains enforce ISO 22716 certification and batch-specific CoA documentation as listing prerequisites for charcoal oral products. ECHA enforcement actions against non-compliant activated carbon imports redirect procurement toward certified processors. Berlin and Hamburg urban centers show strongest zero-waste packaging preference alignment with EU Single-Use Plastics Directive mandates.
United Kingdom
Wellness-focused consumers prioritize sustainable feedstock provenance over price in premium oral care selections. MHRA alignment with EU regulatory frameworks maintains REACH-equivalent heavy metal thresholds post-Brexit. London and Manchester specialty retail channels demonstrate strongest performance for plastic-free, refillable container systems.
India
BIS and CDSCO framework convergence with international standards opens formal import pathways for certified brands previously confined to gray-market entry. Central government tightening of activated carbon oral preparation import standards affects cross-border brand entry. Maharashtra and Gujarat processing clusters provide regional feedstock security for domestic formulation manufacturers.
Australia
TGA scrutiny of enamel safety data and abrasive index thresholds limits mechanical cleaning efficacy claims in peroxide-free products. Natural product enthusiasts drive brand switching behavior toward zero-waste packaging credentials. Sydney and Melbourne urban coastal markets show strongest subscription retention rates for charcoal-based oral care products.
Charcoal Teeth Whitening Powder Market Competitive Landscape
Listed leaders compete with private specialists across certification and channel access dimensions. The vendor base clusters around three tiers: established pharmacy-channel incumbents with ISO 22716 credentials, direct-to-consumer natives leveraging social marketing, and sustainability-focused specialists commanding premium positioning. Dominant competitive moves include geographic expansion into aligned regulatory jurisdictions and portfolio diversification toward sensitivity-reduction formulations.
Within the sustainability-focused tier, Georganics exemplifies plastic-free packaging and zero-waste credentials that resonate with environmentally selective buyers. Carbon Coco occupies a position among social-native marketers anchoring growth through direct-to-consumer distribution in English-speaking markets. Procoal represents the pharmacy-channel archetype, leveraging UK manufacturing bases to sustain premium positioning across European retail channels.
| Leading Market Players |
|---|
| Carbon Coco |
| Procoal |
| Georganics |
| HealthVit |
| Deyga |
| Habbits |
| Apollo Noni |
| Pro Teeth Whitening Co |
| TJ Smile Bio-Tech |
| Others |
Pricing and Supply Chain Analysis
ISO 22716 certification gates both supplier qualification and price differentiation in charcoal teeth whitening powder, concentrating premium positioning among manufacturers with verified Good Manufacturing Practices credentials while filtering out cost-competitive unqualified entrants from pharmacy channel access.
Pricing Analysis
Certification level creates the primary spread between premium pharmacy-channel positioning and mass-market economy tiers. Three-tier pricing structure separates ISO 22716-certified pharmacy-grade formulations from REACH-compliant standard variants and uncertified economy imports. Cost compression in the economy tier intensifies because of peroxide whitening competition and private label proliferation. Natural product enthusiasts demonstrate the lowest price sensitivity, prioritizing sustainable feedstock provenance and zero-waste packaging credentials over unit cost.
Supply Chain Analysis
Indonesia and the Philippines anchor high-grade activated carbon production through coconut shell processing clusters, while China dominates bamboo charcoal feedstock availability. Southeast Asian agricultural waste streams supply steam-activated carbon with surface areas exceeding 800 m²/g, drawing from coconut husk and shell byproducts. Single-source vulnerability concentrates in climate-exposed coconut processing regions vulnerable to typhoon disruption. Distribution runs through direct-to-consumer fulfillment centers in United States urban coastal markets and certified pharmacy wholesalers in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Charcoal teeth whitening powder sits at a platform-economics inflection where subscription-based replenishment models and social-native discovery ecosystems disintermediate traditional pharmacy intermediaries, rewarding brands that build proprietary customer data assets and recurring revenue infrastructure.
For Market Incumbents: Compound pharmacy channel credibility through ISO 22716 certification maintenance and batch-specific CoA documentation systems that defend against emerging direct-to-consumer entrants. Deepen upstream control over Southeast Asian coconut shell feedstock partnerships to secure supply against climate volatility. Expand into sensitivity-reduction formulations with remineralizing agent integration to capture therapeutic-adjacent margin pools.
For New Entrants and Emerging Players: BIS and CDSCO certification fast-track for India market entry opens formal import pathways previously confined to gray-market channels. Target natural product enthusiasts in EU urban centers with plastic-free, refillable container systems that align with Single-Use Plastics Directive mandates. Anchor go-to-market strategy through TikTok-native content and subscription replenishment models that bypass traditional wholesale pharmacy distribution.
For Investors and Strategic Acquirers: FDA cosmetic-drug claim boundary enforcement reshapes the acquisition landscape, elevating compliance infrastructure value and legal review capabilities as differentiated assets. Long-term viability centers on brands with demonstrated subscription retention and regulatory navigation expertise rather than pure social media follower scale. Watch ECHA enforcement action frequency against non-compliant activated carbon imports as signal for supplier consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22716 Certification Investment | Pharmacy channel access in Germany and France requires batch-specific traceability documentation. |
| Direct-to-Consumer Subscription Launch | Recurring revenue capture from millennial and Gen Z buyers reduces customer acquisition cost versus paid advertising. |
| Sensitivity-Reduction Formulation Development | Hydroxyapatite integration commands therapeutic-adjacent price premiums beyond cosmetic whitening positioning. |
| Southeast Asian Feedstock Partnership | Coconut shell charcoal sourcing with REACH-compliant CoA documentation secures premium European pharmacy listings. |
| Zero-Waste Packaging Repositioning | Plastic-free refillable systems align with EU Single-Use Plastics Directive mandates in urban coastal markets. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers at direct-to-consumer oral care companies, pharmacy chain category buyers, activated carbon procurement leads, and regulatory affairs specialists, then refined through secondary validation against FDA cosmetic-drug guidance documents, ECHA REACH Annex XVII enforcement records, BIS certification databases, and customs trade data for activated carbon imports. Bottom-up demand modeling from subscription retention metrics and pharmacy sell-through data triangulated against top-down market sizing from channel revenue disclosures.
Variance decomposition across product type, application tier, distribution channel, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by price realization in certified versus uncertified tiers. Industry-specific forecast inputs included ISO 22716 certification backlog timelines at accredited bodies and ECHA enforcement action frequency against non-compliant activated carbon imports.
Underlying assumptions cover sustained FDA cosmetic-drug boundary enforcement, REACH Annex XVII heavy metal threshold maintenance, and coconut shell feedstock supply continuity, with deviation risk concentrated in climate disruption to Southeast Asian processing regions and regulatory reclassification between cosmetics and medical devices. Recalibration cycles align with material shifts in ECHA enforcement patterns and FDA abrasive index threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Australia and New Zealand Dental Biomaterials Market
Dental Materials
Toothpaste Market
Dental Materials
Dental Alginate Market
Dental Materials
Dental Bleaching Materials Market
Dental Materials
Dental Fiberglass Posts Market
Dental Materials
Fluoride Mouthwash Market
Dental Materials
Dental Gypsum Market
Dental Materials
Global Teeth Whitening Product Market
Dental Materials
Fluoride Materials Market
Dental Materials
Dental Amalgam Market
Dental Materials
Dental Alloys Market
Dental Materials
Dental Materials for 3D Printing Market
Dental Materials
Dental Wax Market
Dental Materials
Remineralizing Gum Market
Dental Materials
Acrylic Dental Material Market
Dental Materials
Global Dental Membrane and Bone Graft Substitutes Market