
 Dental Cavity Filling Material Market | 2026-2036
Dental Cavity Filling Material Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Cavity Filling Material Market Analysis
Glass ionomer cement is recalibrating cost-performance trade-offs across restorative procedures, displacing amalgam in pediatric and geriatric applications where moisture tolerance and fluoride release matter. Dentsply Sirona leverages its end-to-end digital dentistry ecosystem to lock in recurring material purchases from chairside CAD/CAM users. GC America anchors the glass ionomer segment through proprietary formulations that dominate Asian clinical training curricula. Kerr Corporation competes on shade-matching fidelity in anterior composite systems, a niche where brand loyalty runs deep among cosmetic dentists.
Dental cavity filling material encompasses chemically cured or light-cured substances—typically bis-GMA resin matrices loaded with silica or zirconia fillers at 60-80% by weight—designed to restore structural integrity and occlusal function to carious dentition. Manufacturers achieve clinical viability through controlled polymerization shrinkage below 2% volumetric loss and radiopacity exceeding 3 mm aluminum equivalence for postoperative radiographic assessment. Composite resin commands the largest revenue pool across material types, though glass ionomer posts the fastest growth trajectory as bioactive formulations gain protocol inclusion in pediatric dentistry. Restorative dentistry generates the highest absolute procedure volume among applications, while cosmetic dentistry concentrates margin capture through premium nanohybrid and nanofilled systems.
The FDA regulates dental restorative materials as Class II medical devices under 510(k) premarket notification, enforcing biocompatibility standards aligned with ISO 10993 series testing for cytotoxicity and sensitization. Europe's MDR and REACH frameworks impose additional substance restriction and clinical evidence requirements that filter market access for non-compliant suppliers. Dental clinics and hospital procurement committees must now weigh regulatory divergence between FDA-cleared and CE-marked formulations when standardizing inventory across multinational practice networks, making compliance architecture a core strategic variable for material selection.
Market Dynamics
The FDA's streamlined 510(k) clearance pathways for novel dental restorative materials are compressing product development cycles and accelerating the displacement of amalgam by bioactive alternatives in pediatric and geriatric protocols.
Growth Catalysts
- Bioactive glass ionomer formulations:Pediatric dentistry practices are expanding protocol inclusion of these materials due to superior moisture tolerance and sustained fluoride release in primary dentition restorations.
- China's tier-one city clinic expansion:Private dental chain scaling in Beijing, Shanghai, and Guangzhou is concentrating demand for premium composite systems and chairside CAD/CAM materials.
- ISO 10993 biocompatibility harmonization:Aligned cytotoxicity and sensitization testing standards are reducing regulatory friction for multi-territory product launches.
Market Restraints
- Bis-GMA resin monomer cost volatility:Petrochemical feedstock fluctuations create margin pressure for composite manufacturers operating on fixed-price clinic contracts.
- Amalgam substitution inertia:Rural and price-sensitive markets in India and Southeast Asia continue prioritizing cost-minimized mercury-containing restorations despite phase-down commitments.
- Europe's MDR clinical evidence requirements:Stricter post-market surveillance and substance restriction frameworks under REACH filter market access for non-compliant suppliers.
Strategic Opportunities
- India's underpenetrated secondary cities:Tier-two and tier-three urban centers lack specialized pediatric dentistry infrastructure, creating whitespace for bioactive material protocols.
- Chairside 3D printing convergence:Integration of photopolymerizable resins with intraoral scanning and milling systems enables same-visit restorative workflows.
- Japan's aging dentition mandate:METI-supported geriatric oral health initiatives are redirecting procurement toward moisture-tolerant glass ionomer systems for institutional care.
Industry Challenges
- Polymerization shrinkage control:Achieving sub-2% volumetric loss in high-filler-load nanohybrid composites requires precision manufacturing that strains mid-tier material suppliers.
- Radiopacity certification timelines:Demonstrating 3 mm aluminum equivalence for postoperative radiographic assessment extends FDA 510(k) review cycles for novel filler compositions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Cavity Filling Material Market |
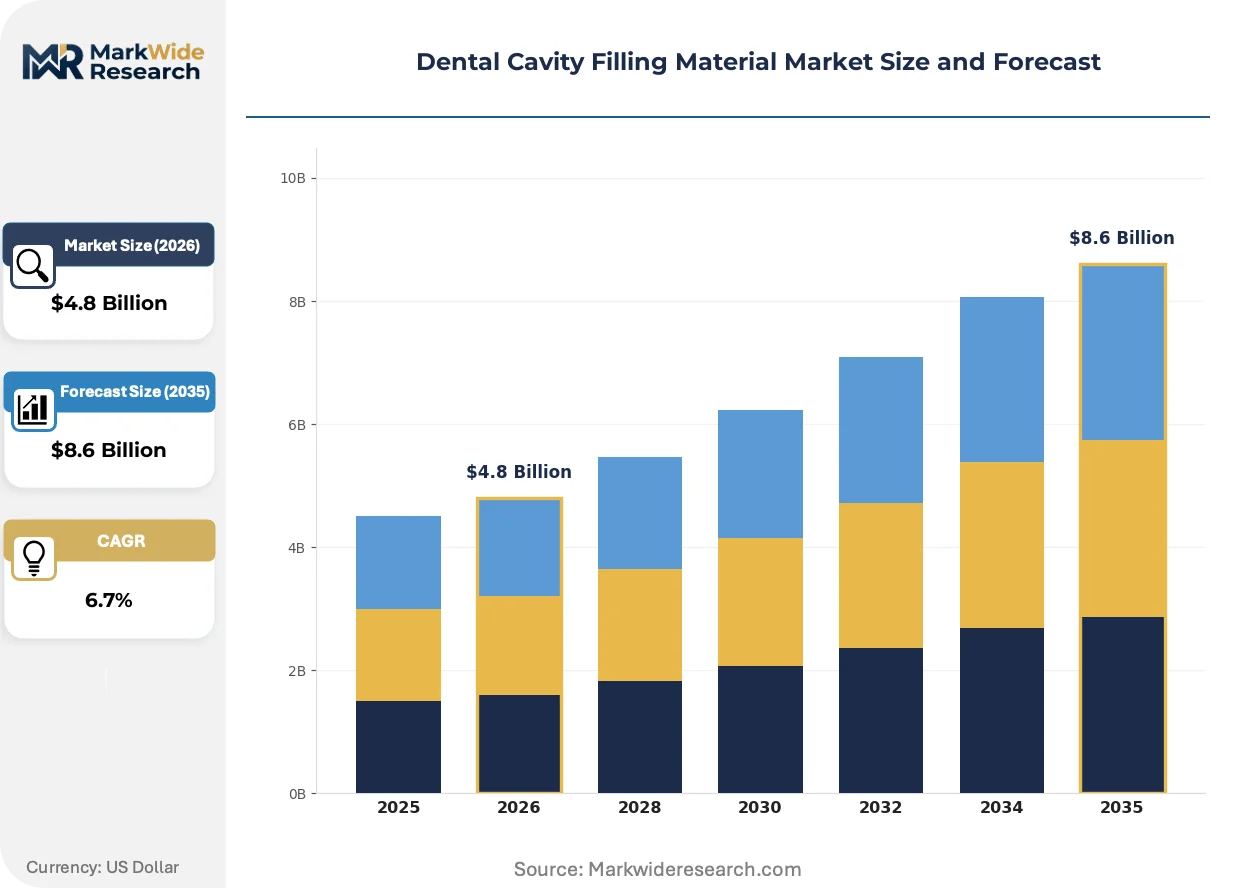
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Acrylic, Composite Resin, Glass Ionomer, Amalgam Application: Pediatric Dentistry, General Dentistry, Cosmetic Dentistry, Restorative Dentistry Distribution Channel: Direct Sales, Online Retail, Dental Distributors, Wholesale Suppliers End User: Dental Clinics, Hospitals, Research Institutions, Educational Facilities |
| Companies Covered | 3M, Dentsply Sirona, GC America, Kerr Corporation, VOCO GmbH, SDI Limited, Coltene Group, Kuraray Noritake Dental, Ivoclar Vivadent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Cavity Filling Material Market Emerging Trajectories
Digital dentistry ecosystems are restructuring how restorative materials reach clinical endpoints, with software-locked material ecosystems and bioactive formulations commanding disproportionate protocol attention.
Chairside CAD/CAM systems are decentralizing restorative material selection away from centralized procurement committees. Individual practitioners operating intraoral scanners and milling units now specify resin blocks and cements without hospital supply chain intermediation. This shift compresses price transparency and locks practices into proprietary material ecosystems.
Europe's MDR substance restriction frameworks are forcing reformulation of conventional composite matrices. Manufacturers must demonstrate clinical evidence for cytotoxicity profiles under stricter post-market surveillance, with nanofilled anterior systems facing heightened scrutiny in France and Germany. CE-marked suppliers are accelerating ISO 10993 testing alignment to preempt regulatory divergence.
Dental clinic procurement in China's tier-one cities is consolidating through chain-level standardization. Private networks in Beijing and Shanghai are mandating uniform material inventories across dozens of locations, displacing individual practitioner autonomy. This concentration favors suppliers offering volume-tiered pricing and integrated digital workflow support.
Dental Cavity Filling Material Market Segmentation
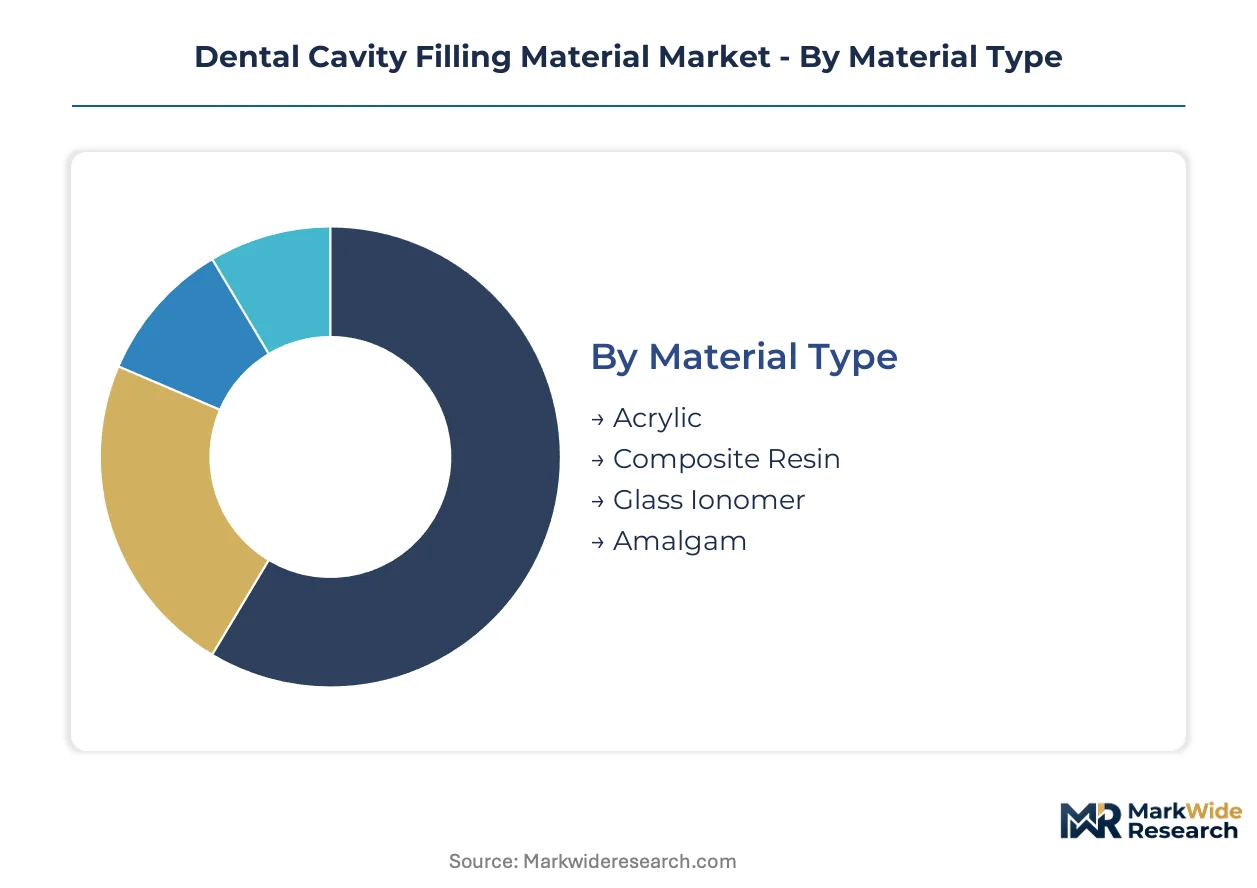
Material composition and clinical setting dictate procurement patterns across dental filling categories. Segmentation reveals where premium formulations command margin versus where volume throughput dominates purchasing decisions.
Material Type:
Volume applications favor cost-optimized formulations while premium niches reward bioactive performance characteristics.
- Composite Resin:Bis-GMA resin matrices loaded with silica or zirconia fillers at 60-80% by weight achieve polymerization shrinkage below 2% volumetric loss. Demand concentrates in China's tier-one private dental chains where chairside CAD/CAM systems lock practices into proprietary resin block ecosystems.
- Glass Ionomer:Bioactive formulations release fluoride ions and tolerate moisture in primary dentition restorations. Pediatric dentistry practices in Japan's institutional geriatric care settings are expanding protocol inclusion fastest as METI-supported oral health initiatives redirect procurement.
- Acrylic:Self-curing polymethyl methacrylate systems serve provisional restoration applications where cost minimization outweighs longevity requirements.
- Amalgam:Mercury-containing alloys persist in India's rural markets and Southeast Asia's price-sensitive clinics despite international phase-down commitments.
Today's leader: Composite Resin. Tomorrow's challenger: Glass Ionomer.
Application:
Procedure volume and margin capture diverge sharply across clinical specialties.
- Restorative Dentistry:Caries treatment generates the highest absolute procedure volume globally. Procurement committees in hospital systems standardize on radiopaque formulations exceeding 3 mm aluminum equivalence for postoperative assessment protocols.
- Cosmetic Dentistry:Anterior shade-matching systems command premium pricing through nanohybrid and nanofilled matrices. France and Germany's MDR substance restrictions are forcing reformulation of conventional composites under heightened nanofiller scrutiny.
- Pediatric Dentistry:Primary dentition protocols prioritize moisture-tolerant materials with sustained fluoride release in Beijing and Shanghai's expanding private clinic chains.
- General Dentistry:Breadth of procedure mix drives inventory complexity, with practitioners balancing cost-performance trade-offs across amalgam substitution timelines.
Restorative Dentistry anchors volume. Cosmetic Dentistry captures margin.
Distribution Channel:
Digital workflow integration is restructuring how materials reach clinical endpoints.
- Dental Distributors:Regional warehousing and same-day delivery networks dominate inventory replenishment for independent practices across India's tier-two cities.
- Direct Sales:Manufacturers bypass intermediaries to serve multinational clinic chains with volume-tiered pricing and integrated CAD/CAM workflow support.
- Online Retail:E-commerce platforms aggregate small-practice demand, compressing price transparency for standard consumables.
- Wholesale Suppliers:Bulk procurement aggregators serve institutional buyers in Japan's geriatric care facilities with standardized glass ionomer inventories.
Dental Distributors retain share. Direct Sales gains fastest.
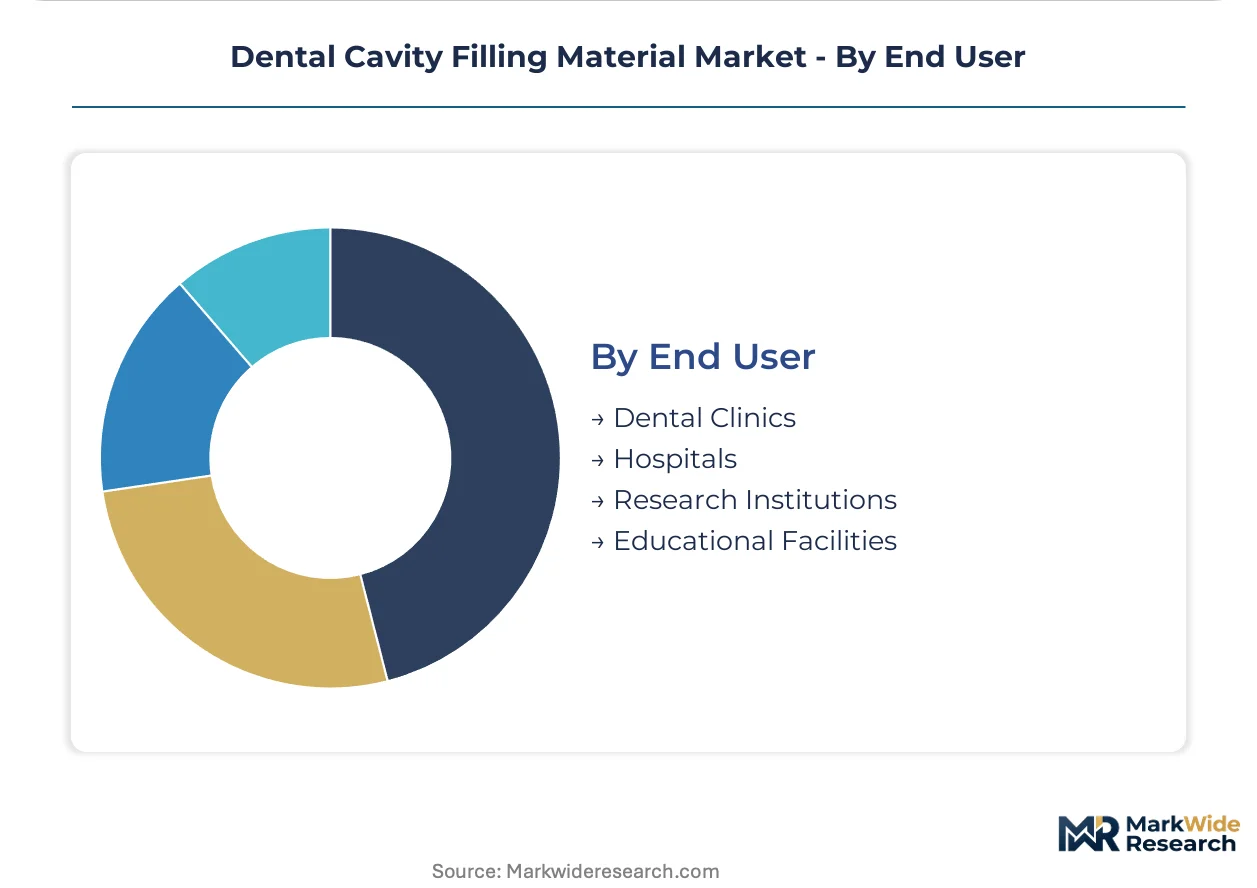
End User:
Procurement autonomy varies with organizational scale and regulatory exposure.
- Dental Clinics:Private chains in China's tier-one cities mandate uniform material inventories across dozens of locations, displacing individual practitioner autonomy.
- Hospitals:Centralized supply committees weigh FDA-cleared versus CE-marked formulations when standardizing across multinational networks.
- Research Institutions:Academic medical centers pilot novel bioactive formulations ahead of regulatory clearance, generating clinical evidence for 510(k) submissions.
- Educational Facilities:Dental schools anchor curriculum-standardized material preferences that persist through graduates' careers, particularly for glass ionomer protocols in Asian training programs.
Dental Clinics concentrate demand. Research Institutions shape tomorrow's standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one cities concentrate procurement volume as private dental chains standardize material inventories across Beijing, Shanghai, and Guangzhou. The FDA's streamlined 510(k) pathways and Europe's MDR substance restrictions create divergent compliance architectures that reshape multinational supplier strategies.
United States
Cosmetic dentistry practices in California and New York Metro drive premium nanohybrid composite demand through chairside CAD/CAM adoption. The FDA regulates restorative materials as Class II devices under 510(k) premarket notification, enforcing ISO 10993 biocompatibility standards. Greater Boston's academic medical centers pilot bioactive formulations ahead of regulatory clearance, generating clinical evidence for submission packages.
Germany
MDR substance restrictions force reformulation of conventional composite matrices under heightened nanofiller scrutiny in France and Germany's premium anterior systems. ECHA's REACH frameworks impose additional clinical evidence requirements that filter market access. Bavaria's industrial dental clusters anchor CE-marked supplier concentration for multi-territory product launches.
China
Beijing and Shanghai's expanding private clinic chains mandate uniform glass ionomer and composite inventories across dozens of locations, displacing individual practitioner autonomy. The country's national medical products regulator accelerates review timelines for innovative restorative materials. Yangtze River Delta manufacturing hubs supply silica and zirconia fillers at scale for domestic resin matrix production.
Japan
METI-supported geriatric oral health initiatives redirect institutional procurement toward moisture-tolerant glass ionomer systems for aging dentition care. The Pharmaceuticals and Medical Devices Agency maintains stringent post-market surveillance that extends certification timelines for novel filler compositions. Kanto region dental schools anchor curriculum-standardized material preferences that persist through graduates' careers.
India
Tier-two and tier-three urban centers lack specialized pediatric dentistry infrastructure, creating whitespace for bioactive material protocol expansion. The Central Drugs Standard Control Organization oversees medical device registration with increasing alignment to international standards. Maharashtra's Mumbai-Pune corridor concentrates dental distributor networks serving independent practices with same-day replenishment logistics.
Dental Cavity Filling Material Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers balance premium cosmetic systems against volume glass ionomer throughput. The market structures around three tiers: multinational conglomerates with end-to-end digital ecosystems, mid-cap specialists with regional formulation expertise, and commodity suppliers serving price-sensitive rural markets. Two strategic archetypes predominate: those locking practices into proprietary material ecosystems through CAD/CAM integration, and those competing on biocompatibility certification speed under divergent FDA-MDR pathways. M&A activity and vertical integration into filler production represent the dominant competitive moves reshaping cost structures.
Among US-based conglomerates, 3M exemplifies the diversified materials archetype spanning industrial and healthcare applications. Dentsply Sirona occupies a position representing digital workflow integration, while GC America anchors the glass ionomer specialization tier with curriculum-embedded formulation expertise. Kerr Corporation sits within the shade-matching fidelity niche where cosmetic dentist brand loyalty concentrates premium capture. These three named entities represent distinct strategic positions rather than exhaustive market coverage.
| Leading Market Players |
|---|
| 3M |
| Dentsply Sirona |
| GC America |
| Kerr Corporation |
| VOCO GmbH |
| SDI Limited |
| Coltene Group |
| Kuraray Noritake Dental |
| Ivoclar Vivadent |
| Others |
Supply Flow & Price Mechanics
Bis-GMA resin monomer costs trace from petrochemical feedstock volatility through fixed-price clinic contracts into margin compression for composite manufacturers serving China's tier-one private dental chains. This input-cost pathway stratifies final material pricing across premium nanohybrid systems, standard hybrid composites, and economy glass ionomer tiers.
Pricing Analysis
Input-cost pass-through from silica and zirconia filler suppliers shapes contract negotiations between manufacturers and multinational clinic networks. Pricing stratifies across premium, standard, and economy tiers based on filler load percentage and ISO 10993 certification completeness. Cost compression in standard composites is intensifying because fixed-price agreements lock suppliers during petrochemical price spikes. Hospital procurement committees show least price sensitivity for radiopaque formulations, while India's rural independent practices exhibit highest sensitivity to per-unit material costs.
Supply Chain Analysis
Dual-sourcing requirements from China's NMPA-qualified manufacturers compel dental material suppliers to qualify secondary filler suppliers in Germany and Japan. Raw material dependencies center on Yangtze River Delta silica processing, South Korean zirconia refining, and US-based photoinitiator production. Single-source vulnerability concentrates in specialty nanofiller grades where European REACH compliance filters supplier pools. Distribution runs through regional dental distributors in India's tier-two cities and direct manufacturer relationships with Beijing and Shanghai clinic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as bioactive glass ionomer protocols displace amalgam across pediatric and geriatric applications, generating recurring material demand from protocol standardization.
For Market Incumbents: Acquire captive filler production capacity to offset petrochemical feedstock volatility threatening fixed-price contract profitability. Lock chain-level procurement through integrated CAD/CAM workflow support in China's tier-one cities. Defend against mid-tier glass ionomer specialists by embedding formulations in Asian dental school curricula. For New Entrants and Emerging Players: Bioactive formulation R&D partnerships with Japanese institutional geriatric care providers offer the most penetrable entry vector. Target India's tier-two and tier-three urban centers where pediatric dentistry infrastructure gaps create whitespace for moisture-tolerant material protocols. Lead with METI-aligned clinical evidence generation to accelerate PMDA qualification timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap glass ionomer specialists lack backward integration into zirconia filler supply. Five-to-ten year viability favors suppliers with dual FDA-MDR certification architectures and curriculum-embedded training relationships. Watch for NMPA accelerated review pathway announcements as inflection indicators for Chinese market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filler Production | Yangtze River Delta silica processing captive supply secures margin against petrochemical volatility. |
| CAD/CAM Workflow Ecosystem Lock-in | Dentsply Sirona's chairside system integration binds Chinese clinic chains to proprietary resin blocks. |
| Dual Certification Architecture Investment | Parallel FDA 510(k) and MDR CE marking reduces regulatory friction for multinational clinic networks. |
| Curriculum Embedding Partnerships | GC America's Asian dental school relationships create graduate-level brand persistence for glass ionomer protocols. |
| Bioactive Formulation Clinical Evidence Program | METI-supported geriatric oral health initiatives redirect Japanese institutional procurement toward moisture-tolerant systems. |
Methodological Framework
Direct dialogue with dental material procurement managers, clinic chain operations directors, biomedical engineers at academic medical centers, and GPO contracts specialists grounds qualitative findings in operational reality. Secondary validation draws from FDA 510(k) premarket notification databases, NMPA medical product registration filings, hospital procurement committee minutes, and ISO 10993 biocompatibility test reports. Bottom-up procedure volume estimates triangulate against top-down manufacturer shipment data across the analysis window.
Bottom-up modeling segments volume and value by material composition, clinical application, distribution channel, and end-user facility type throughout the forecast period. CAGRs derive from procedure growth assumptions tied to pediatric dentistry expansion metrics, geriatric dentition prevalence curves, and CAD/CAM system penetration rates. Forecast inputs incorporate REACH substance restriction timelines and NMPA accelerated review pathway implementation.
The model holds under stable regulatory harmonization between FDA and MDR frameworks; deviation in bilateral trade policy or raw material export restrictions would shift supply-side concentration assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Sensitive Toothpaste Market
Dental Materials
Dental Resins Market
Dental Materials
Global Endodontic Consumables Market
Dental Materials
Global Dental Membrane and Bone Graft Substitutes Market
Dental Materials
Global Dental Bone Void Filler Market
Dental Materials
Global Dental Cements Market
Dental Materials
Asia-Pacific Toothpaste Market
Dental Materials
Dental Alloys Market
Dental Materials
Teeth Whitening Market
Dental Materials
Global Zirconia Based Dental Materials Market
Dental Materials
Dental Gypsum Market
Dental Materials
Dental Fluoride Varnish Market
Dental Materials
Toothpaste Market
Dental Materials
Australia and New Zealand Dental Biomaterials Market
Dental Materials
Fluoride Materials Market
Dental Materials
Nanotechnology Toothpaste Formulations Market