
 Dental Alginate Market | 2026-2036
Dental Alginate Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Alginate Market Outlook
Pharmaceutical-grade alginate certification is unwinding a quality premium across the dental impression supply chain. Septodont leverages its European manufacturing base to sustain consistent batch purity for premium fast-set formulations. GC Corporation anchors Asian distribution through dedicated dental dealer networks. Kerr Corporation differentiates via specialized packaging systems that extend working time precision for complex restorative cases.
Dental alginate is an irreversible hydrocolloid impression material composed primarily of sodium or potassium salts of alginic acid, which react with calcium sulfate to form an elastic gel; it captures oral tissue detail within two to five minutes depending on set speed. Fast-set alginate leads procedural throughput in high-volume dental clinics where chair-time efficiency determines margin pools. Orthodontic application segments show structural momentum as clear aligner workflows multiply preliminary impression requirements. Direct sales channels dominate institutional procurement while online retail captures growing small-practice demand.
FDA oversight of dental device biocompatibility and CE marking under EU MDR govern material composition and patient safety thresholds for alginate formulations entering clinical use. ISO 21563 standards for dental elastomeric impression materials provide additional quality benchmarks that manufacturers must satisfy for international market access. Stakeholders should monitor evolving regulatory harmonization between FDA and notified body requirements as dual certification costs reshape competitive entry barriers.
Market Dynamics
Orthodontic clear aligner workflows are multiplying preliminary impression requirements across high-volume dental clinics, compressing chair-time economics and forcing alginate suppliers to prioritize fast-set formulations with extended working time precision.
Growth Catalysts
- EU MDR compliance mandates:CE marking requirements for dental impression materials under the Medical Device Regulation tighten biocompatibility thresholds, filtering substandard suppliers and consolidating procurement toward certified manufacturers.
- India's National Oral Health Program:Government-funded dental camps in rural districts expand patient access, creating institutional demand for cost-effective alginate in bulk procurement formats.
- Digital impression pre-screening:Intraoral scanner adoption in developed markets generates hybrid workflows where alginate serves as backup verification, sustaining material volume despite optical displacement.
Market Restraints
- Seaweed harvest volatility:Sodium alginate feedstock prices fluctuate with North Atlantic kelp yields and Chilean macroalgae quotas, squeezing margin predictability for formulators.
- Single-source calcium sulfate concentration:High-purity gypsum suppliers cluster in specific mining districts, exposing batch consistency to localized extraction disruptions.
- Polyether and VPS substitution:Vinyl polysiloxane materials capture margin-intensive prosthodontic cases with superior dimensional stability, relegating alginate to price-sensitive preventive applications.
Strategic Opportunities
- Indonesia's dental insurance expansion:Jaminan Kesehatan Nasional coverage extensions into tertiary oral care create reimbursement pathways for impression procedures in Jakarta and Surabaya clinic networks.
- ISO 21563 harmonization:Convergence between FDA biocompatibility protocols and ISO elastomeric standards enables dual-certification efficiency, lowering regulatory entry costs for compliant manufacturers.
- E-commerce direct-to-practice channels:Amazon Business and dental-specific platforms capture small-practice procurement, bypassing traditional dealer markups for standard-set alginates.
Industry Challenges
- Mixing technique standardization:Operator-dependent water-powder ratios produce variable set quality, requiring manufacturer investment in pre-dosed single-use packaging systems.
- Dimensional stability certification timelines:FDA 510(k) clearance for extended-pour formulations demands 24-month clinical validation cycles, delaying premium product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Alginate Market |
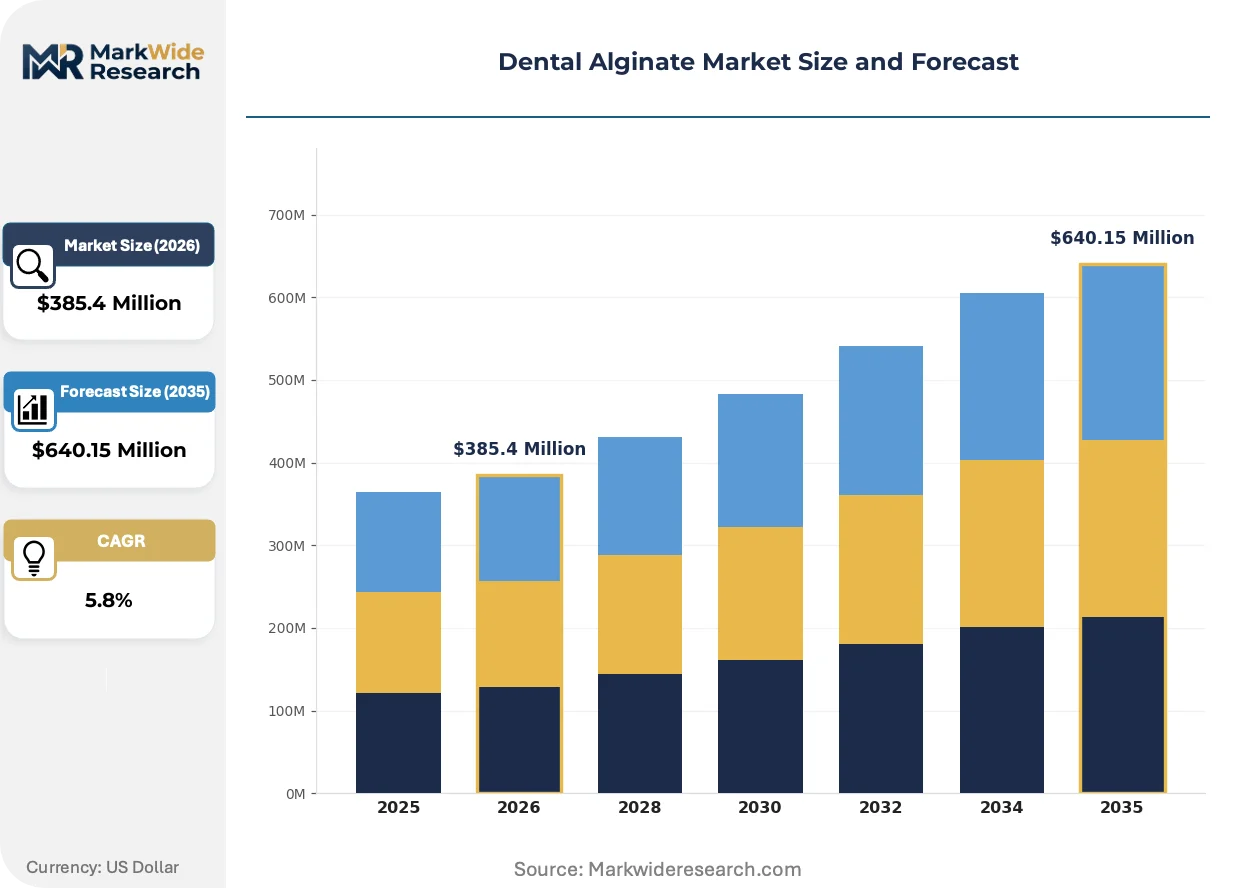
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Set, Fast Set, Flavored, Unflavored Application: Impressions, Orthodontics, Prosthetics, Restorative End User: Dental Clinics, Hospitals, Research Institutions, Laboratories Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Septodont, 3M, Dentsply Sirona, LASCOD, Cavex Holland BV, GC Corporation, Kerr Corporation, Parkell Inc., Zhermack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Alginate Market Strategic Shifts
Material science advances and regulatory harmonization are compressing product development cycles while digital dentistry workflows reshape how alginate fits into impression capture sequences. Three developments warrant particular attention.
Chromogenic indicator systems are fragmenting the fast-set segment by enabling visual set-phase confirmation without time-guessing. High-volume orthodontic chains in Brazil and Mexico deploy these formulations to standardize technician training and reduce remake rates. The technology is fragmenting procurement patterns as group practices specify color-change requirements in tender documents, forcing traditional suppliers to reformulate or exit bid pools.
REACH substance restrictions on boron compounds are compelling European manufacturers to eliminate borax retarders from alginate chemistry. The industrial consequence is accelerated investment in organic acid alternative formulations that maintain working time without SVHC classification. German and French dental distributors now stock boron-free SKUs exclusively, anticipating ECHA sunset date enforcement.
Group purchasing organizations are consolidating procurement authority across multi-location dental service organizations. DSOs in the United States negotiate master supply agreements that specify alginate performance metrics and lock in volume commitments, displacing individual practice autonomy. Texas and Florida-based dental platforms exhibit the most concentrated buying power, extracting 15-20 point discounts from manufacturers desperate for committed offtake.
Dental Alginate Market Segmentation
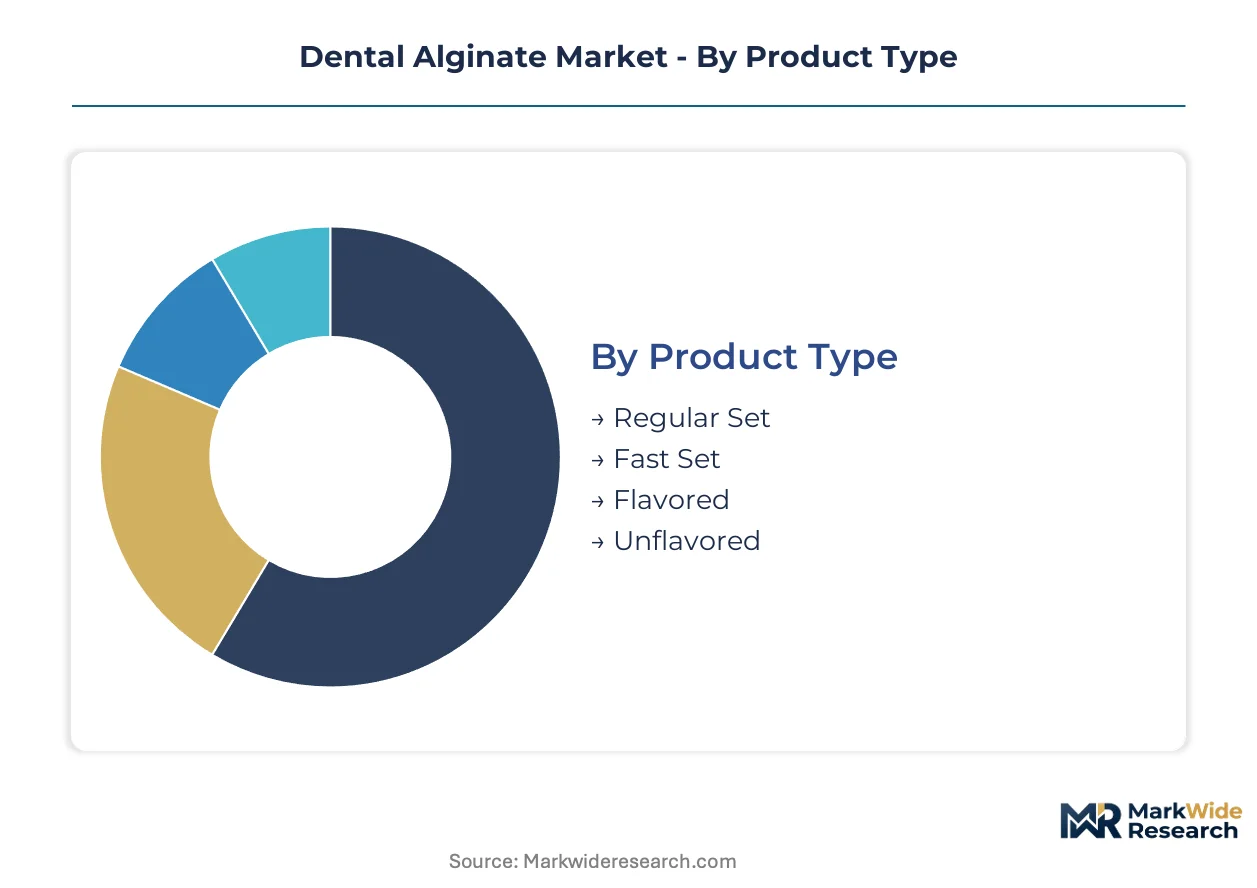
Alginate suppliers calibrate product portfolios across four distinct axes. Each segmentation layer reveals divergent margin structures, procurement authority patterns, and regulatory exposure thresholds that determine competitive positioning.
Product Type:
Margin pools concentrate in formulations that compress chair-time without sacrificing dimensional accuracy.
- Fast Set:Calcium sulfate-rich chemistry delivers gelation within 90-120 seconds. High-volume orthodontic chains in Brazil and Mexico specify fast-set formulations in tender documents to standardize technician throughput and reduce remake rates.
- Regular Set:Standard working time of 2-3 minutes suits general practitioners performing single-unit crown impressions. Cost-conscious procurement in India's National Oral Health Program camps favors this grade for bulk institutional purchasing.
- Flavored:Mint and fruit essences reduce gag reflex incidence in pediatric and geriatric patients. Pediatric dental specialists in Germany and France specify flavored SKUs exclusively for patient compliance protocols.
- Unflavored:Neutral taste profile avoids allergen labeling requirements under REACH substance restrictions. European manufacturers eliminated flavoring compounds to streamline ECHA compliance documentation.
The dominant share belongs to Regular Set, while Fast Set is closing the gap fastest.
Application:
Volume distribution tracks the procedural intensity of each dental specialty.
- Orthodontics:Clear aligner workflows multiply preliminary impression requirements. DSOs in Texas and Florida negotiate master supply agreements specifying alginate performance metrics for orthodontic case starts.
- Impressions:Diagnostic and opposing arch captures remain the foundational use case. General dental clinics in Jakarta and Surabaya generate steady demand through Jaminan Kesehatan Nas reimbursement pathways.
- Prosthetics:Vinyl polysiloxane displacement relegates alginate to preliminary casts and border molding. Prosthodontic laboratories in Japan specify alginate only for non-definitive applications.
- Restorative:Single-unit indirect restorations drive working-time precision requirements. Kerr Corporation's specialized packaging systems target this segment with extended pour-window formulations.
Orthodontics commands the steepest expansion trajectory as aligner case volumes multiply.
End User:
Procurement authority fragments across organizational scale and reimbursement structure.
- Dental Clinics:Independent practices and DSO-affiliated locations represent the core volume node. Amazon Business and dental-specific platforms capture small-practice procurement, bypassing traditional dealer markups.
- Hospitals:Academic medical centers and oral surgery units require FDA 510(k)-cleared formulations for inpatient procedures. Institutional procurement mandates biocompatibility documentation exceeding dental clinic standards.
- Research Institutions:Universities and dental schools drive experimental formulation demand. ISO 21563 validation studies consume specialized alginate batches for elastomeric comparison research.
- Laboratories:Commercial dental labs process alginate impressions into stone casts and digital scans. GC Corporation anchors Asian distribution through dedicated dealer networks serving this channel.
Dental Clinics retain volume leadership, though Hospitals are gaining procurement sophistication fastest.
Distribution Channel:
Channel selection determines pricing transparency and inventory carrying costs.
- Direct Sales:Manufacturers maintain field forces for DSO and hospital system accounts. Septodont leverages its European manufacturing base to sustain consistent batch purity for direct-ship premium formulations.
- Distributors:Regional dental dealers provide technical support and credit terms. German and French distributors now stock boron-free SKUs exclusively, anticipating ECHA sunset date enforcement.
- Online Retail:E-commerce platforms capture price-sensitive small-practice demand. Standard-set alginates move through this channel with minimal value-added services.
- Wholesalers:Bulk aggregators serve rural and secondary market clinics. India's government dental camps source through tender-based wholesale procurement.
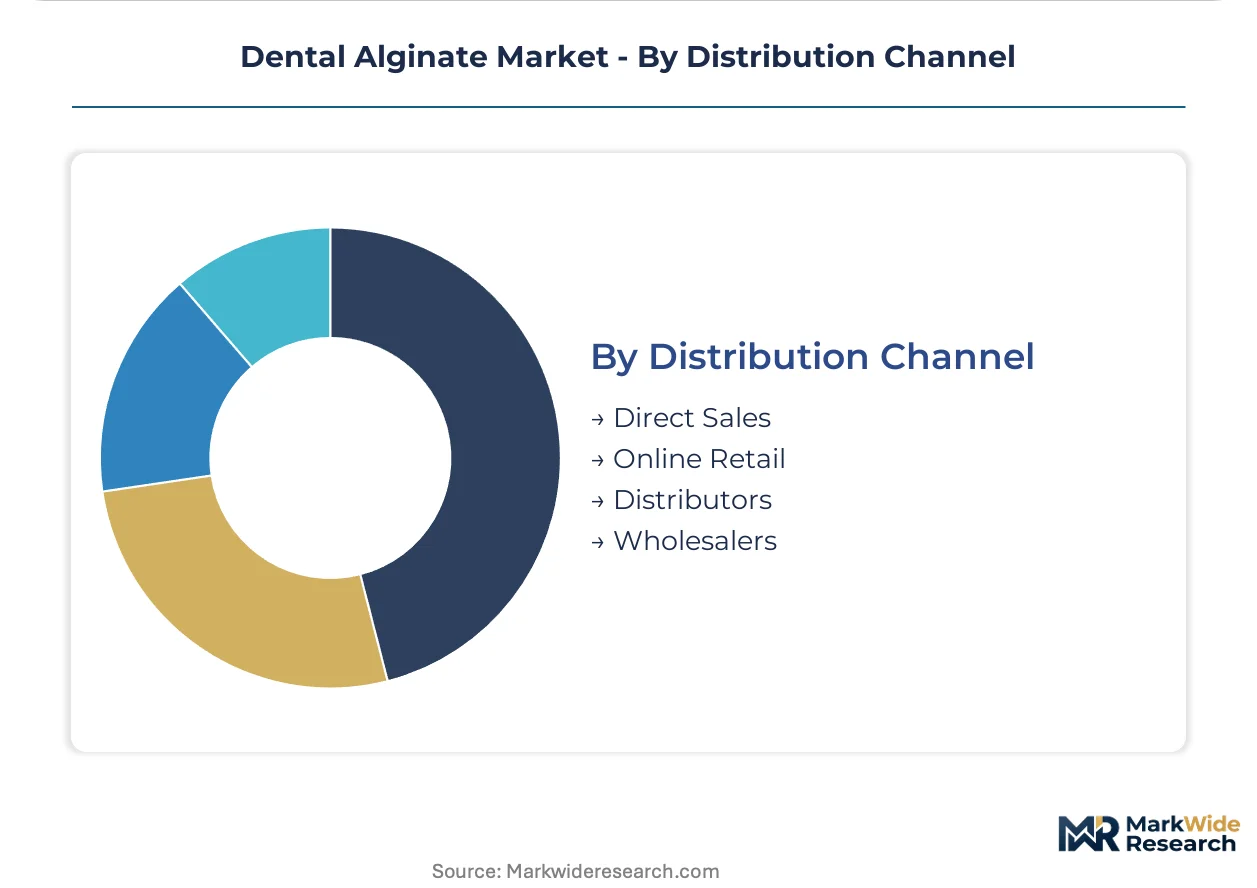
Direct Sales captures the premium tier, while Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity calcium sulfate deposits and established kelp harvesting infrastructure cluster alginate formulation capacity in specific coastal and mining districts. Manufacturing plants locate near both seaweed processing facilities and gypsum extraction sites to minimize feedstock transport costs. Demand dispersion follows government dental program expansion and private clinic network growth across distinct national healthcare systems.
United States
Texas and Florida-based dental service organizations extract steep volume discounts through master supply agreements that lock in multi-year alginate commitments. FDA 510(k) clearance requirements for extended-pour formulations create regulatory entry barriers that favor established manufacturers with clinical validation resources. Chicago and Los Angeles metropolitan areas concentrate orthodontic clear aligner case volumes that multiply preliminary impression requirements.
Germany
REACH substance restrictions on boron compounds force manufacturers to eliminate borax retarders from alginate chemistry, accelerating organic acid alternative formulation investment. German dental distributors now stock boron-free SKUs exclusively, anticipating ECHA sunset date enforcement. Bavaria's dental manufacturing corridor hosts quality-focused formulators serving premium European clinic networks with certified batch purity.
India
The National Oral Health Program funds rural dental camps that generate institutional bulk procurement demand for cost-effective regular-set alginate. CDSCO medical device registration requirements tighten biocompatibility documentation standards for imported impression materials. Mumbai and Delhi dental dealer networks anchor distribution into government procurement channels and private clinic clusters.
Brazil
High-volume orthodontic chains specify chromogenic indicator formulations in tender documents to standardize technician training and reduce remake rates. ANVISA medical device regulations govern alginate import and domestic manufacturing licensing. São Paulo's dental supply distribution hub concentrates procurement authority for South American clinic networks seeking fast-set formulations.
Japan
PMDA pharmaceutical-grade certification requirements sustain quality premiums across the dental impression supply chain. METI industrial standards for medical device materials provide additional compliance benchmarks for international market access. Osaka and Tokyo metropolitan areas concentrate prosthodontic laboratories that specify alginate for preliminary casts while reserving vinyl polysiloxane for definitive applications.
Dental Alginate Market Competitive Environment
Concentration sits with European and North American manufacturers that control premium formulation segments through regulatory certification depth. The vendor base spans three distinct tiers: multinational dental conglomerates with diversified impression material portfolios, regional specialists focused on alginate chemistry optimization, and emerging Asian formulators competing on bulk supply economics. Strategic moves center on boron-free chemistry transition and direct-to-practice e-commerce channel development.
Among established European formulators, Septodont leverages its French manufacturing base to sustain batch purity consistency for premium fast-set formulations, while GC Corporation anchors Asian distribution through dedicated dealer networks. Kerr Corporation occupies a position on the precision-packaging vector with specialized systems targeting complex restorative cases. These three exemplify how geographic manufacturing positioning and channel specialization determine competitive tier placement.
| Leading Market Players |
|---|
| Septodont |
| 3M |
| Dentsply Sirona |
| LASCOD |
| Cavex Holland BV |
| GC Corporation |
| Kerr Corporation |
| Parkell Inc. |
| Zhermack |
| Others |
Value Chain & Pricing Dynamics
Forty-five-day inventory cycles for sodium alginate feedstock concentrate pricing power among coastal formulators with direct seaweed processing access, compressing margin pools for inland competitors forced into spot-market procurement. This lead-time asymmetry separates premium fast-set formulations from economy-grade alternatives.
Pricing Analysis
EU MDR compliance mandates dictate the pricing tier structure across the dental impression supply chain. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth: pharmaceutical-grade batches with ISO 21563 validation command substantial premiums over uncertified imports. Cost compression in the economy tier is intensifying because Indian government tender programs prioritize unit-cost minimization over performance specifications. Price-sensitive buyers cluster in rural dental camps and emerging-market institutional procurement, while premium orthodontic chains in São Paulo and Dallas exhibit minimal price elasticity.
Supply Chain Analysis
Forty-five-day inventory cycles for sodium alginate feedstock expose formulators to North Atlantic kelp harvest volatility and Chilean macroalgae quota fluctuations. Manufacturing gravity centers on France, Germany, and coastal China where seaweed processing infrastructure intersects with high-purity gypsum deposits. Calcium sulfate, potassium alginate, and chromogenic indicator compounds constitute the critical input trio. Single-source concentration in specific mining districts creates vulnerability to localized extraction disruptions. Distribution runs through dedicated dental dealer networks in Asia, direct field forces for DSO accounts in North America, and tender-based wholesale channels for government programs in South Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
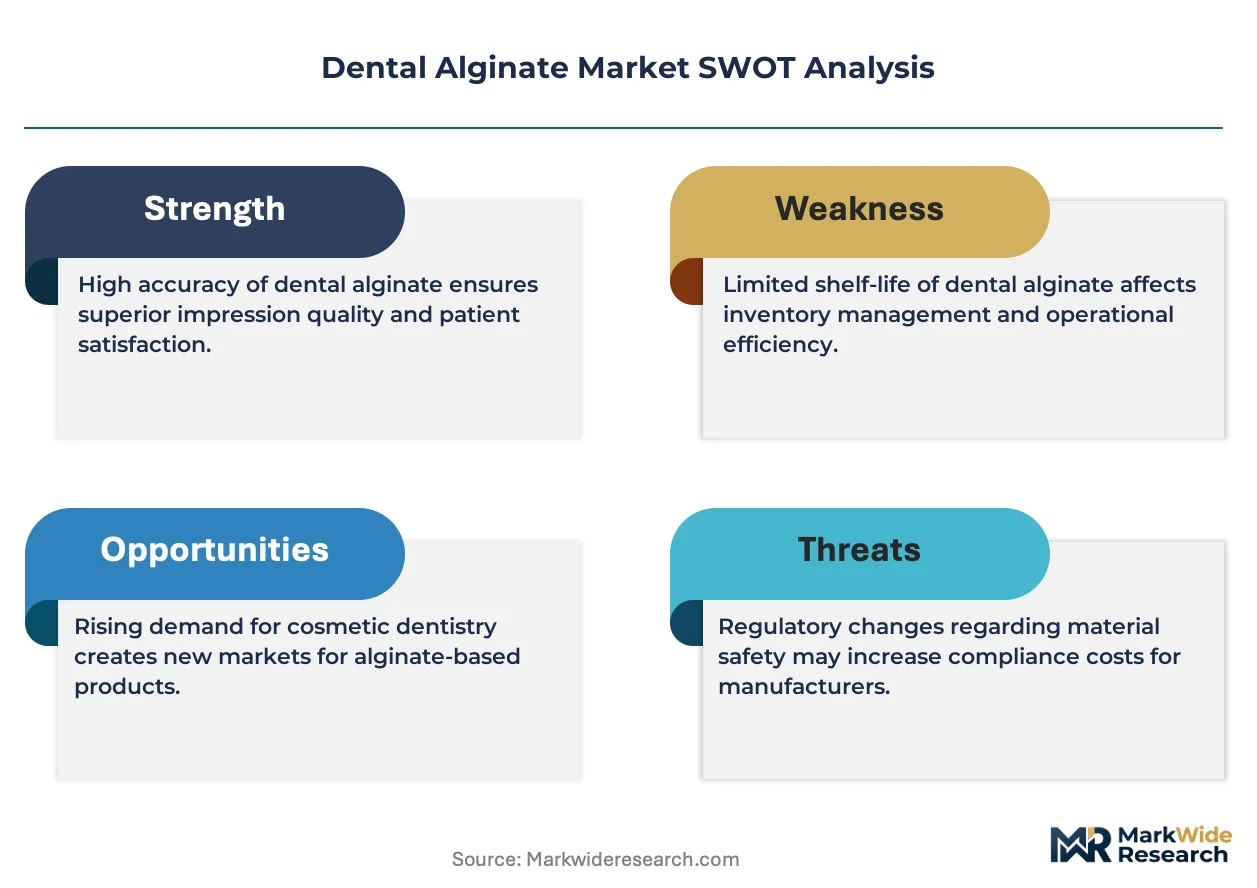
Vinyl polysiloxane displacement threatens alginate's position in definitive prosthodontic applications, forcing incumbents to defend preventive and preliminary impression segments where cost advantages persist.
For Market Incumbents: Shield fast-set formulation leadership through backward integration into boron-free chemistry R&D ahead of ECHA sunset enforcement. Secure multi-year offtake agreements with Texas and Florida DSOs to lock volume commitments against emerging Asian competitors. Prioritize ISO 21563-FDA dual-certification investment to raise regulatory entry barriers for uncertified entrants.
For New Entrants and Emerging Players: CDSCO fast-track registration for regular-set alginate offers the most penetrable entry vector into India's National Oral Health Program tender channels. Target Jakarta and Surabaya clinic networks through Jaminan Kesehatan Nas reimbursement expansion. Deploy e-commerce direct-to-practice platforms to bypass established dealer markups and capture price-sensitive small-practice demand.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory compliance costs and feedstock volatility will filter subscale formulators. Focus acquisition screening on European manufacturers with established boron-free formulations and validated batch purity systems. Monitor intraoral scanner adoption curves as the critical inflection signal—hybrid workflow persistence sustains alginate volume, while optical displacement acceleration compresses addressable market scope.
| Strategic Initiative | Industry Significance |
|---|---|
| Boron-Free Chemistry Transition | ECHA sunset date enforcement compels elimination of borax retarders from alginate formulations. |
| DSO Master Supply Agreements | Texas and Florida dental platforms extract 15-20 point discounts through committed multi-year volume contracts. |
| Chromogenic Indicator Launch | Brazilian orthodontic chains specify color-change formulations to standardize technician training protocols. |
| E-Commerce Channel Development | Amazon Business and dental-specific platforms capture small-practice procurement bypassing dealer markups. |
| Dual-Certification Investment | ISO 21563-FDA convergence lowers regulatory entry costs for compliant manufacturers seeking international access. |
Study Parameters
Initial hypotheses were tested against primary input from dental product procurement managers, orthodontic practice administrators, biomedical engineers at hospital systems, and GPO contracts managers, then refined through secondary validation. Sources included FDA 510(k) filings, EMA MDR submission databases, CDSCO medical device registration records, and customs trade data for sodium alginate feedstock flows. Bottom-up demand modeling from clinic-level procedure volumes was triangulated against top-down manufacturer shipment estimates.
Variance decomposition across product type, application specialty, end-user scale, and distribution channel shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macroeconomic dental expenditure trends. Modeled inputs incorporated clear aligner case start trajectories, government dental program expansion schedules, and intraoral scanner penetration curves by metropolitan market.
Underlying assumptions cover sustained reimbursement pathway stability in Indonesia and India, with deviation risk concentrated in seaweed harvest volatility and REACH substance restriction enforcement timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Asia-Pacific Toothpaste Market
Dental Materials
Dental Putty Market
Dental Materials
Dental Resins Market
Dental Materials
Fluoride Materials Market
Dental Materials
Dental Zirconia Powder Market
Dental Materials
Dental Wax Market
Dental Materials
Dental Bonding Agent Market
Dental Materials
Dental Impression Material Market
Dental Materials
Global Dental Bone Void Filler Market
Dental Materials
Dental Composites Market
Dental Materials
Toothpaste Market
Dental Materials
Fluoride Mouthwash Market
Dental Materials
Dental Fiberglass Posts Market
Dental Materials
Dental Gypsum Market
Dental Materials
Charcoal Teeth Whitening Powder Market
Dental Materials
Oral Bone Implant Material Market