
 Tooth Filling Materials Market | 2026-2036
Tooth Filling Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Tooth Filling Materials Market Analysis
High-viscosity bulk-fill composite standards is bifurcating the premium tier from conventional offerings. 3M leverages its Scotchbond universal adhesive platform to sustain clinical loyalty across North American dental schools. Dentsply Sirona anchors its position through chairside CAD/CAM integration with CEREC-compatible blocks. GC America differentiates via glass ionomer formulations optimized for pediatric minimally invasive protocols.
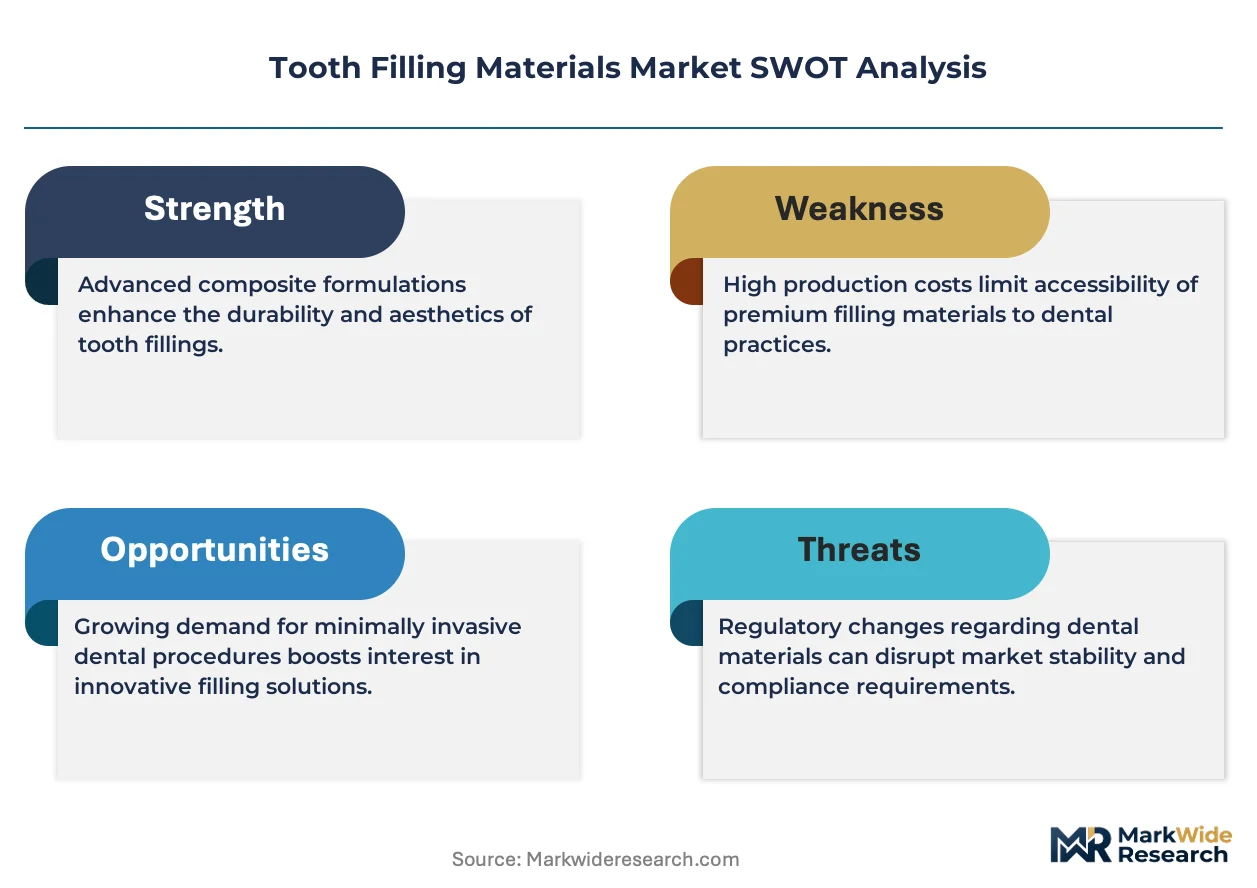
Tooth filling materials encompass restorative biomaterials engineered to replace decayed dental hard tissue, with composite resins typically comprising bis-GMA/TEGDMA resin matrices loaded with silane-treated silica or zirconia fillers at 70-85 weight percent to achieve compressive strengths exceeding 300 MPa. Their primary commercial purpose centers on restoring form and function while matching optical properties of natural dentition across anterior and posterior applications. Composite resins command the dominant value share given their aesthetic versatility and bonding chemistry advances, while glass ionomer segments retain structural importance in pediatric and geriatric cases where moisture tolerance and fluoride release outweigh shear strength requirements. CAD/CAM technology segments show the steepest growth trajectory as milling workflows compress appointment cycles and enable same-day definitive restorations.
The FDA regulates dental restorative materials under 21 CFR 872, requiring premarket notification for permanent implantable devices and biocompatibility per ISO 10993. The EU Medical Device Regulation mandates notified body involvement for Class IIa and above fillings, with CE marking contingent on clinical evaluation reports. ISO 4049 sets polymerization shrinkage and wear resistance benchmarks that manufacturers must document for international market access. Stakeholders should monitor evolving mercury-phaseout legislation across Scandinavian markets and assess hybrid material portfolios against impending biocompatibility standard revisions.
Market Dynamics
High-viscosity bulk-fill composites are compressing appointment cycles while EU MDR biocompatibility protocols force reformulation investments across permanent implant portfolios. Dental clinics face simultaneous pressure to reduce chair time and document clinical safety under tighter notified body scrutiny.
Growth Catalysts
- CAD/CAM chairside workflows:Milling-compatible ceramic blocks enable same-day definitive restorations. German dental practices around Munich and Berlin cluster this capability to capture patient convenience premiums.
- EU MDR Class IIa mandates:Notified body involvement for permanent fillings elevates documentation standards. Manufacturers with existing clinical evaluation reports gain accelerated market access.
- Pediatric minimally invasive protocols:Glass ionomer formulations with fluoride release address moisture tolerance requirements in children's dentistry. GC America's optimized chemistries target this specification.
Market Restraints
- Bis-GMA/TEGDMA monomer volatility:Petrochemical feedstock fluctuations compress margin predictability for composite resin manufacturers. Formulators lack short-term hedging mechanisms against propylene derivative spikes.
- Mercury-phaseout legislation:Scandinavian markets enforce amalgam restrictions that strand existing inventory. Dental clinics in Sweden and Norway face accelerated write-downs on conventional material stocks.
- Polymerization shrinkage limitations:ISO 4049 wear benchmarks constrain filler loading thresholds. Manufacturers sacrifice marginal adaptation performance to meet dimensional stability requirements.
Strategic Opportunities
- Bioactive dentin substitutes:Calcium silicate-based materials with ion release chemistry penetrate geriatric segments. Japanese PMDA pathways for regenerative indications offer faster approval timelines than FDA 510(k) routes.
- Remote consultation platforms:Teledentistry channels extend restorative screening into underserved rural geographies. Australian TGA guidance on asynchronous diagnosis creates regulatory clarity for asynchronous triage.
- Scandinavian mercury-free mandates:National legislation in Denmark and Finland eliminates amalgam competition. Composite and glass ionomer suppliers capture displaced volume without price erosion.
Industry Challenges
- CAD/CAM technician training pipelines:Chairside milling requires digital design competency that conventional dental curricula underemphasize. Practices face 12-18 month skill acquisition cycles before workflow efficiency materializes.
- Biocompatibility testing backlogs:ISO 10993 cytotoxicity and sensitization studies queue at contracted laboratories. Reformulation timelines extend 8-14 months beyond product development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tooth Filling Materials Market |
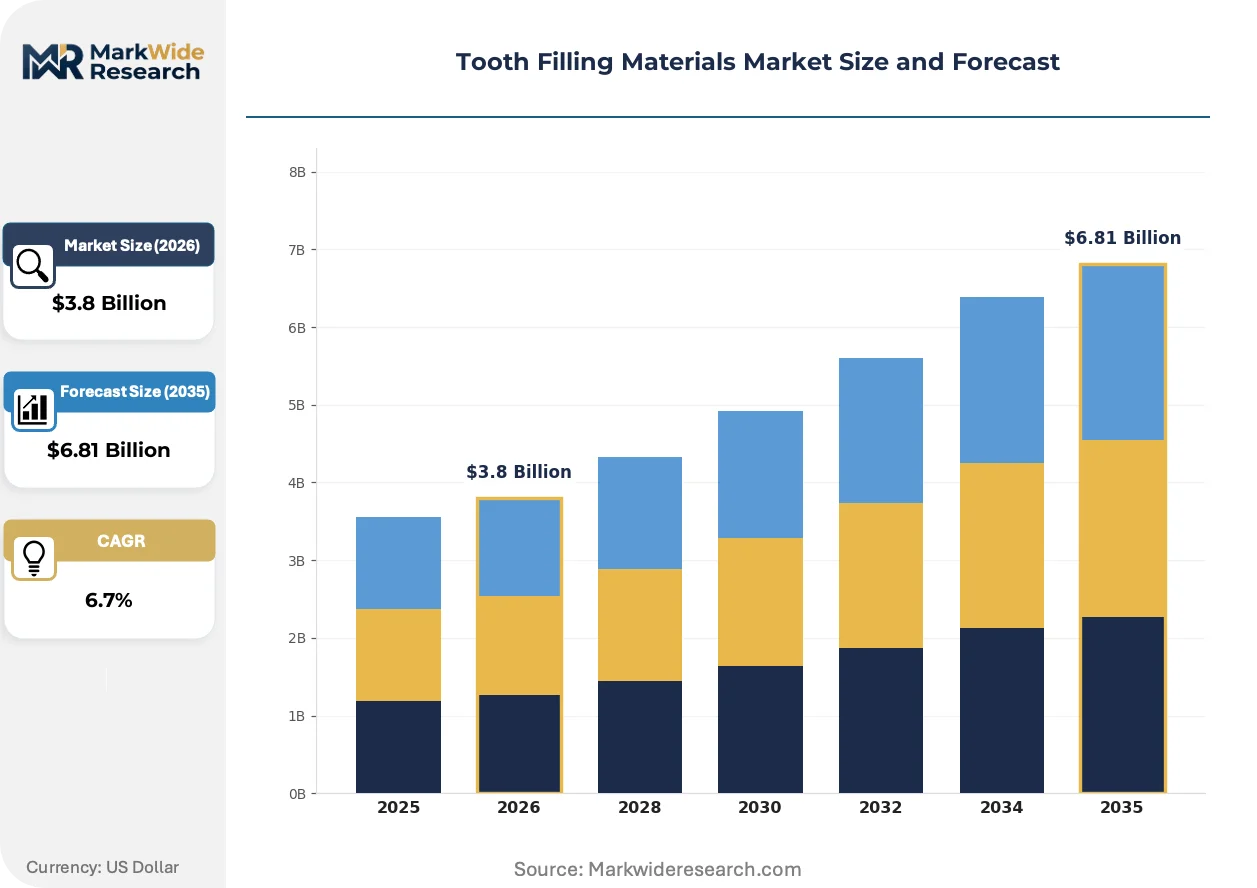
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Resins, Amalgam, Glass Ionomer, Resin Ionomer End User: Dental Clinics, Hospitals, Dental Laboratories, Research Institutes Application: Restorative Dentistry, Preventive Dentistry, Cosmetic Dentistry, Pediatric Dentistry Technology: CAD/CAM, 3D Printing, Laser Curing, Hybrid Materials |
| Companies Covered | 3M, Dentsply Sirona, GC America, Kerr Corporation, VOCO GmbH, SDI Limited, Coltene Whaledent, DenMat Holdings, Kuraray Noritake Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tooth Filling Materials Market Emerging Trajectories
Workflow compression technologies dominate competitive positioning as practices prioritize throughput over incremental material performance gains. Regulatory documentation burdens simultaneously reshape R&D allocation toward compliance automation.
Bulk-fill composite systems with 4-5 mm single-increment cure depths are supplanting incremental layering protocols in posterior restorations. North American dental schools adopt these chemistries for operative training curricula. The shift compresses average appointment duration by eliminating intermediate polymerization steps while maintaining proximal contact integrity.
EU Medical Device Regulation notified body capacity constraints are extending CE marking timelines for Class IIa permanent fillings. Manufacturers redirect clinical evaluation report preparation toward pre-submission dialogue with designated bodies. German dental material suppliers face the steepest documentation burdens given their concentration of premium implantable portfolios.
Patient preference for single-visit definitive restorations is consolidating purchasing authority within practice groups with captive milling capacity. Independent dental laboratories lose posterior crown and inlay volume to chairside production. This channel compression concentrates demand in metropolitan clusters where CAD/CAM equipment density supports same-day service marketing.
Tooth Filling Materials Market Segmentation
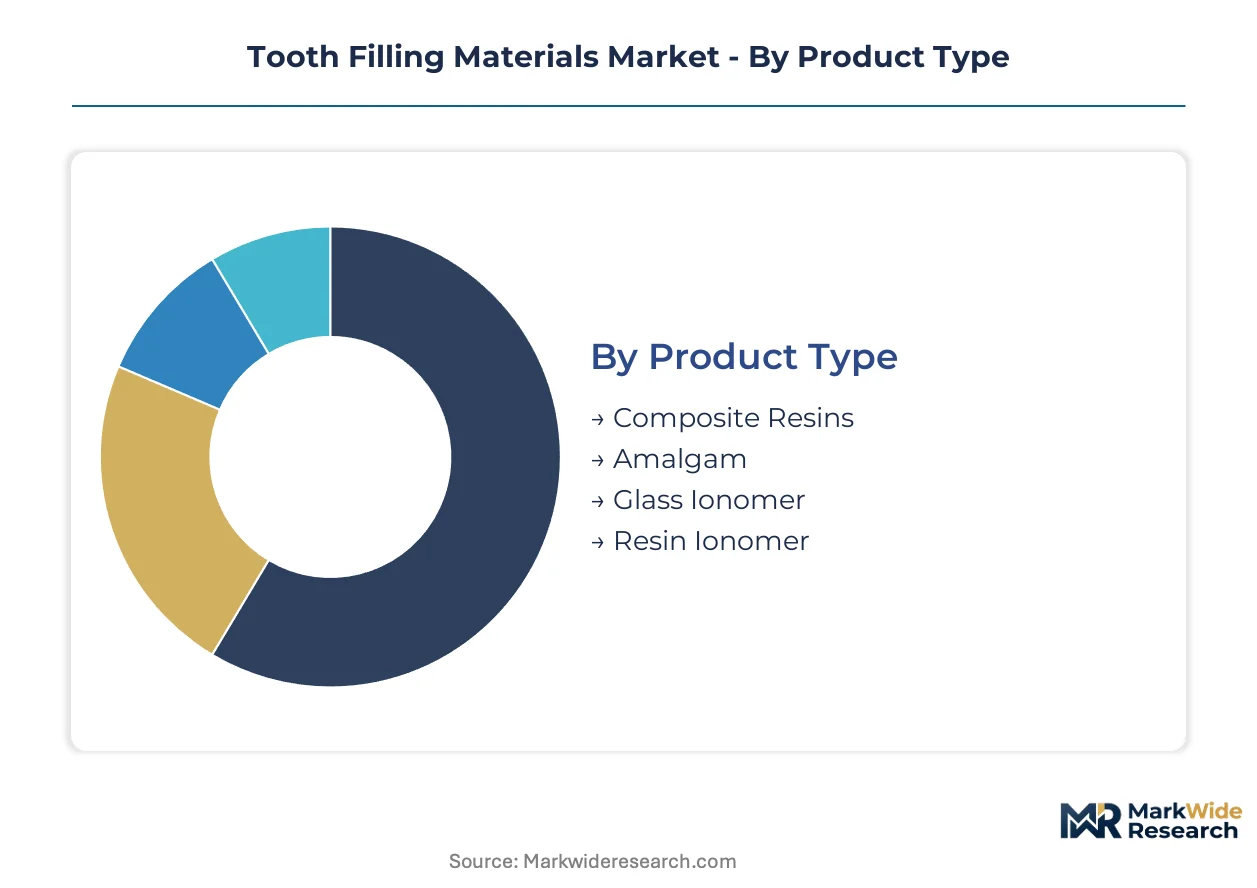
Tooth filling materials segment across material chemistry, clinical setting, therapeutic purpose, and manufacturing technology. Each dimension carries distinct substitution pressures that reshape competitive positioning and procurement priorities.
Product Type:
Amalgam faces the most acute substitution threat from mercury-phaseout mandates across Scandinavian markets, forcing material selection shifts that cascade through procurement patterns.
- Composite Resins:Bis-GMA/TEGDMA matrices loaded with silane-treated silica or zirconia fillers at 70-85 weight percent achieve compressive strengths exceeding 300 MPa. German dental practices cluster around Munich and Berlin favor these for aesthetic versatility in anterior and posterior applications. Demand concentrates where CAD/CAM workflows require shade-matched definitive restorations.
- Glass Ionomer:Acid-base reaction products of fluoroaluminosilicate glass and polyacrylic acid release fluoride ions while tolerating moisture contamination. Pediatric protocols in moisture-challenged environments specify these formulations. GC America has optimized chemistries for minimally invasive children's dentistry where shear strength requirements are secondary.
- Amalgam:Silver-tin-copper alloy dispersed in mercury faces legislative elimination across Denmark, Finland, Sweden, and Norway.
- Resin Ionomer:Hybrid formulations combine composite aesthetics with glass ionomer adhesion and fluoride release.
Composite resins anchors the volume base while CAD/CAM-compatible blocks gain share at the steepest rate.
End User:
Procurement authority concentrates differently across settings, with dental laboratories losing posterior volume to chairside production while research institutes drive next-generation validation.
- Dental Clinics:Independent and group practices purchase directly from distributors, with German metropolitan clusters showing highest CAD/CAM equipment density. Patient preference for single-visit definitive restorations consolidates purchasing authority within practice groups with captive milling capacity.
- Dental Laboratories:Independent labs face channel compression as chairside milling displaces posterior crown and inlay production. Metropolitan equipment density now determines laboratory service radius viability.
- Hospitals:Academic medical centers and trauma facilities procure through centralized supply chains with distinct biocompatibility documentation requirements.
- Research Institutes:University dental schools and materials science departments validate next-generation chemistries. North American dental schools have adopted bulk-fill composite systems for operative training curricula.
Dental clinics anchors the volume base while dental laboratories contract fastest amid chairside displacement.
Application:
Margin structures vary sharply across therapeutic categories, with cosmetic applications commanding premium pricing while pediatric protocols prioritize material tolerance over performance specifications.
- Restorative Dentistry:Caries replacement and structural reconstruction of decayed dental hard tissue represents the core commercial purpose. EU MDR Class IIa mandates elevate documentation standards for permanent implantable devices in this category.
- Cosmetic Dentistry:Shade matching and optical property optimization command pricing premiums. Patient-funded elective procedures concentrate in metropolitan clusters with aesthetic-focused practice positioning.
- Preventive Dentistry:Pit and fissure sealants and prophylactic interventions prioritize fluoride release and ease of application.
- Pediatric Dentistry:Moisture tolerance and fluoride release outweigh shear strength requirements. Glass ionomer formulations dominate where behavioral management limits isolation quality.
Restorative dentistry anchors the volume base while cosmetic dentistry climbs the fastest on patient-funded premium positioning.
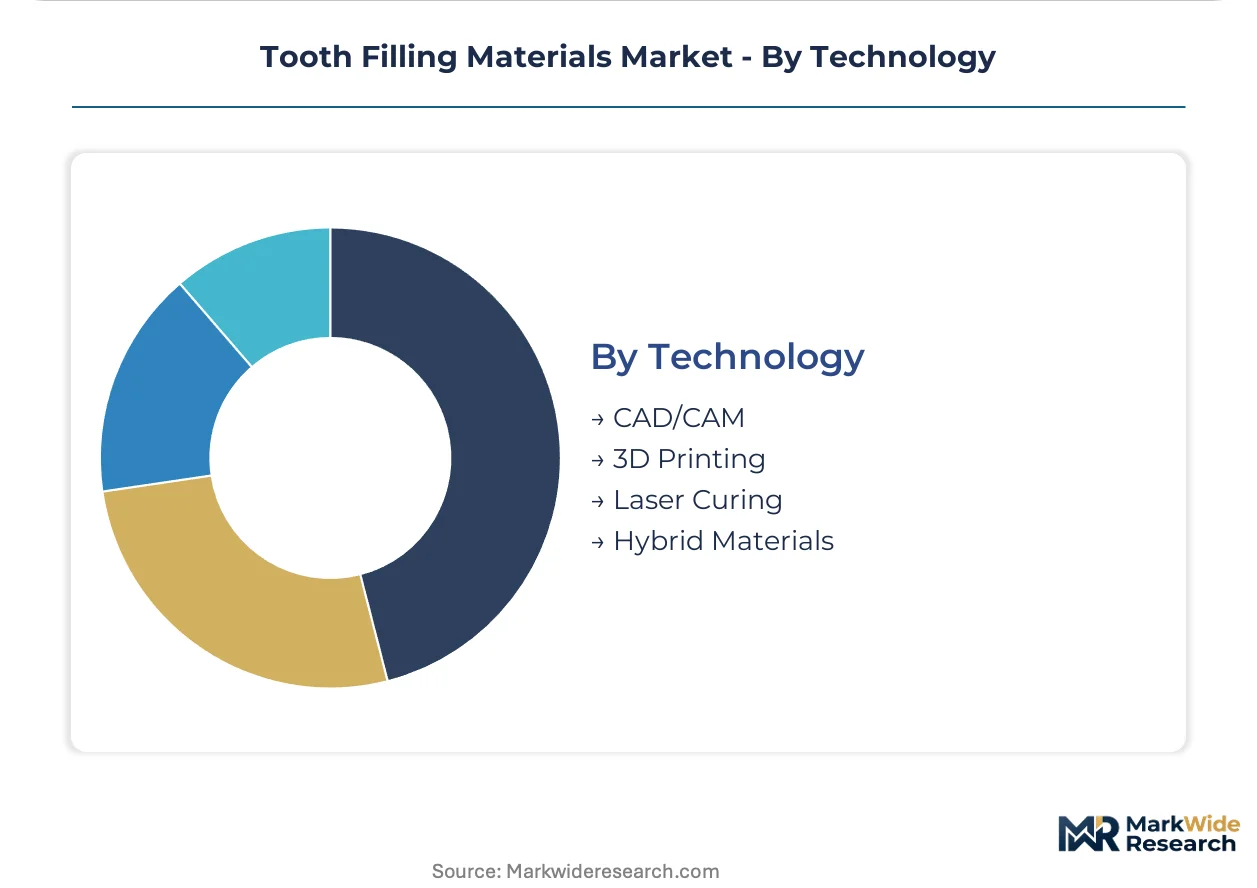
Technology:
Workflow compression technologies reshape competitive positioning as practices prioritize throughput over incremental material performance gains.
- CAD/CAM:Computer-aided design and manufacturing systems mill ceramic blocks into definitive restorations during single appointments. German practices around Munich and Berlin cluster this capability to capture patient convenience premiums. Milling-compatible blocks enable same-day service marketing that displaces laboratory channel volume.
- Laser Curing:High-intensity light sources polymerize composite resins with controlled energy delivery. Bulk-fill systems with 4-5 mm single-increment cure depths compress appointment duration by eliminating intermediate polymerization steps.
- 3D Printing:Additive manufacturing of provisional and definitive restorations from photopolymer resins.
- Hybrid Materials:Multi-phase formulations combining ceramic, resin, and bioactive components.
Laser curing anchors the volume base while CAD/CAM expands most quickly on workflow compression advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a materials trade surplus in dental biomaterials, exporting precision-milled ceramic blocks and adhesive systems to Nordic markets while importing raw monomer feedstocks from petrochemical hubs. Import dependency on bis-GMA precursors creates margin vulnerability during propylene derivative price spikes.
United States
FDA 21 CFR 872 governs premarket notification for permanent implantable dental devices, with ISO 10993 biocompatibility documentation mandatory for market entry. North American dental schools in Boston and San Francisco have adopted bulk-fill composite systems for operative training curricula. Patient preference for single-visit definitive restorations concentrates CAD/CAM equipment in metropolitan clusters.
Germany
EU MDR Class IIa mandates elevate notified body involvement for permanent fillings, with clinical evaluation reports determining CE marking timelines. German practices around Munich and Berlin cluster CAD/CAM capability to capture patient convenience premiums. The country's precision manufacturing base supplies milling-compatible ceramic blocks across European dental markets.
Japan
PMDA pathways for regenerative indications offer faster approval timelines than FDA 510(k) routes for bioactive dentin substitutes. Calcium silicate-based materials with ion release chemistry penetrate geriatric segments in Tokyo and Osaka metropolitan areas. Domestic formulators optimize glass ionomer chemistries for moisture-challenged clinical environments.
Sweden
National mercury-phaseout legislation enforces amalgam restrictions that strand existing inventory and accelerate composite substitution. Dental clinics in Stockholm and Gothenburg face write-downs on conventional material stocks. The Swedish Chemicals Agency (Kemi) monitors residual mercury in dental wastewater under REACH-aligned protocols.
Australia
TGA guidance on asynchronous diagnosis creates regulatory clarity for teledentistry channels extending restorative screening into rural geographies. Sydney and Melbourne dental practice groups consolidate purchasing authority through captive milling capacity. Remote consultation platforms compress specialist referral cycles for underserved populations.
Tooth Filling Materials Market Vendor Landscape
Concentration sits with diversified dental conglomerates holding adhesive platforms and chairside integration capabilities. The vendor base spans multinational materials science divisions, specialized dental equipment manufacturers, and regional formulators with niche pediatric or geriatric positioning. Three archetypes dominate: universal adhesive platform holders, CAD/CAM workflow integrators, and moisture-tolerant formulation specialists. Competitive moves center on clinical evaluation report preparation for EU MDR compliance and chairside milling workflow compression.
Among diversified materials science conglomerates, 3M and Dentsply Sirona exemplify platform-centric positioning. 3M occupies a position within universal adhesive system architecture. Dentsply Sirona sits within CAD/CAM workflow integration. GC America represents specialized formulation expertise in moisture-tolerant chemistries.
| Leading Market Players |
|---|
| 3M |
| Dentsply Sirona |
| GC America |
| Kerr Corporation |
| VOCO GmbH |
| SDI Limited |
| Coltene Whaledent |
| DenMat Holdings |
| Kuraray Noritake Dental |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German milling block manufacturers and Nordic dental distributors lock in both bis-GMA precursor supply and price visibility against propylene derivative volatility. These contracts insulate premium ceramic block portfolios from spot market swings while binding buyers to minimum volume commitments that stabilize manufacturer margins.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in tooth filling materials. Price differentiation rests on ISO 10993 biocompatibility certification tier and CAD/CAM workflow integration depth. Cost compression in economy-grade glass ionomer segments intensifies because Scandinavian mercury-phaseout mandates strand competing amalgam inventory. Pediatric dental clinics exhibit highest price sensitivity, whereas metropolitan German practices with captive milling capacity absorb premium pricing for same-day definitive restoration workflows.
Supply Chain Analysis
Strategic stockpile preferences dominate raw material procurement as manufacturers buffer against petrochemical feedstock volatility and ISO 10993 testing laboratory queue backlogs. Supply concentrates in Germany for precision-milled ceramic blocks, Japan for bioactive dentin substitute formulations, and the United States for universal adhesive platform production. Raw material dependencies draw from Saudi propylene derivatives for bis-GMA monomers, Chinese zirconia for ceramic fillers, and Belgian specialty chemicals for adhesive initiators. Single-source vulnerability in notified body capacity for EU MDR Class IIa CE marking creates approval bottlenecks. Distribution runs through regional dental distributors with direct practice relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as bioactive dentin substitutes with calcium silicate chemistry penetrate geriatric segments and CAD/CAM chairside workflows displace conventional laboratory channel volume.
For Market Incumbents: Compound defensive positioning through backward integration into bis-GMA precursor production and accelerated clinical evaluation report preparation for EU MDR compliance. Bioactive material entrants threaten margin compression in geriatric restorative segments. Vertical integration into petrochemical feedstocks hedges propylene derivative volatility. For New Entrants and Emerging Players: Anchor in Scandinavian mercury-free mandate territories where national legislation eliminates amalgam competition without price erosion. Pediatric minimally invasive protocols present the most penetrable application segment given moisture tolerance requirements that favor specialized glass ionomer formulations. Teledentistry channel partnerships with Australian rural health networks offer asynchronous triage entry points. For Investors and Strategic Acquirers: Capital is best deployed toward CAD/CAM workflow integrators with established CEREC-compatible block portfolios and notified body relationships for accelerated EU market access. Long-term viability favors manufacturers with hybrid material R&D pipelines spanning composite aesthetics and bioactive ion release chemistry. The signal to watch is PMDA approval velocity for regenerative indications relative to FDA 510(k) timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Evaluation Report Preparation | Accelerated CE marking timelines under EU MDR Class IIa mandates secure German market access. |
| Backward Integration into Feedstocks | Captive bis-GMA precursor production hedges margin exposure to Saudi propylene derivative spikes. |
| CAD/CAM Workflow Certification | CEREC-compatible block portfolios capture patient convenience premiums in Munich and Berlin clusters. |
| Bioactive Material R&D Investment | Calcium silicate ion release chemistry penetrates Japanese geriatric segments via faster PMDA pathways. |
| Teledentistry Platform Partnership | TGA-aligned asynchronous diagnosis extends restorative screening into Australian rural geographies. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with dental materials procurement managers, CAD/CAM workflow specialists, pediatric dentistry practitioners, and EU regulatory affairs consultants; and secondary validation through FDA 510(k) filings, EMA clinical evaluation report databases, ISO 10993 biocompatibility study registries, and German dental trade association import statistics. Bottom-up patient volume modeling and top-down materials consumption estimates were triangulated.
Across the projection horizon, the analytical framework segmented tooth filling materials by material chemistry, clinical setting, therapeutic purpose, and manufacturing technology, with additional modeling of CAD/CAM equipment density by metropolitan cluster. CAGRs were derived from patient volume growth trajectories, substitution rate assumptions for mercury-phaseout mandates, and workflow compression technology adoption curves. Forecast inputs incorporated EU MDR notified body capacity constraints and PMDA regenerative indication approval velocity differentials.
Decision-makers should treat outputs as directional under base assumptions of sustained EU MDR implementation timelines and Scandinavian mercury-phaseout enforcement; material deviation would warrant model refresh. Revision becomes warranted when ISO 10993 testing laboratory queue durations or propylene derivative price volatility crosses thresholds that alter manufacturer reformulation investment calculus.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Fluoride-Free Toothpaste Market
Dental Materials
Dental Biomaterials Market
Dental Materials
Global Endodontic Consumables Market
Dental Materials
Charcoal Teeth Whitening Powder Market
Dental Materials
Dental Restorative and Regenerative Material Market
Dental Materials
Crack Tooth Syndrome Market
Dental Materials
Oral Care Chemicals Market
Dental Materials
Dental Fiber Posts Market
Dental Materials
Global Dental Cements Market
Dental Materials
Dental Bleaching Materials Market
Dental Materials
Dental Alloys Market
Dental Materials
Sensitive Toothpaste Market
Dental Materials
Global Dental Adhesive Market
Dental Materials
Global Dental Membrane and Bone Graft Substitutes Market
Dental Materials
Dental Resins Market
Dental Materials
Calcium Hydroxylapatite Fillers Market