
 Cosmetic Ingredients Polymers Market | 2026-2036
Cosmetic Ingredients Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Ingredients Polymers Market Intelligence
A transition from single-source to multi-source procurement for functional polymers is broadening the formulation options available to cosmetic brands. BASF SE leverages its integrated production network to supply a diverse polymer portfolio at scale. The Lubrizol Corporation specializes in high-performance rheology modifiers and film formers for premium skin and hair care. Evonik Industries AG competes with its deep expertise in silicone-based and specialty acrylate polymers for unique sensory effects.
Cosmetic ingredients polymers are macromolecules that provide specific functional benefits in personal care formulations. These materials, either synthetic or naturally derived, modify product texture, stability, and performance on skin and hair. The skin care application remains the dominant end-use sector, consuming a wide range of polymers for creams and lotions. Among product types, advanced film formers and conditioners represent high-value segments driven by innovation in long-wear makeup and hair treatment products.
Ingredient safety and labeling standards are shaped by regulations like the EU's REACH and Cosmetics Regulation, along with directives from the US Food and Drug Administration (FDA). In China, the NMPA enforces strict pre-market approval and testing for new cosmetic ingredients, creating a distinct market access challenge. Future material selection will increasingly balance performance attributes with sustainability criteria, such as biodegradability and renewable sourcing.
Market Dynamics
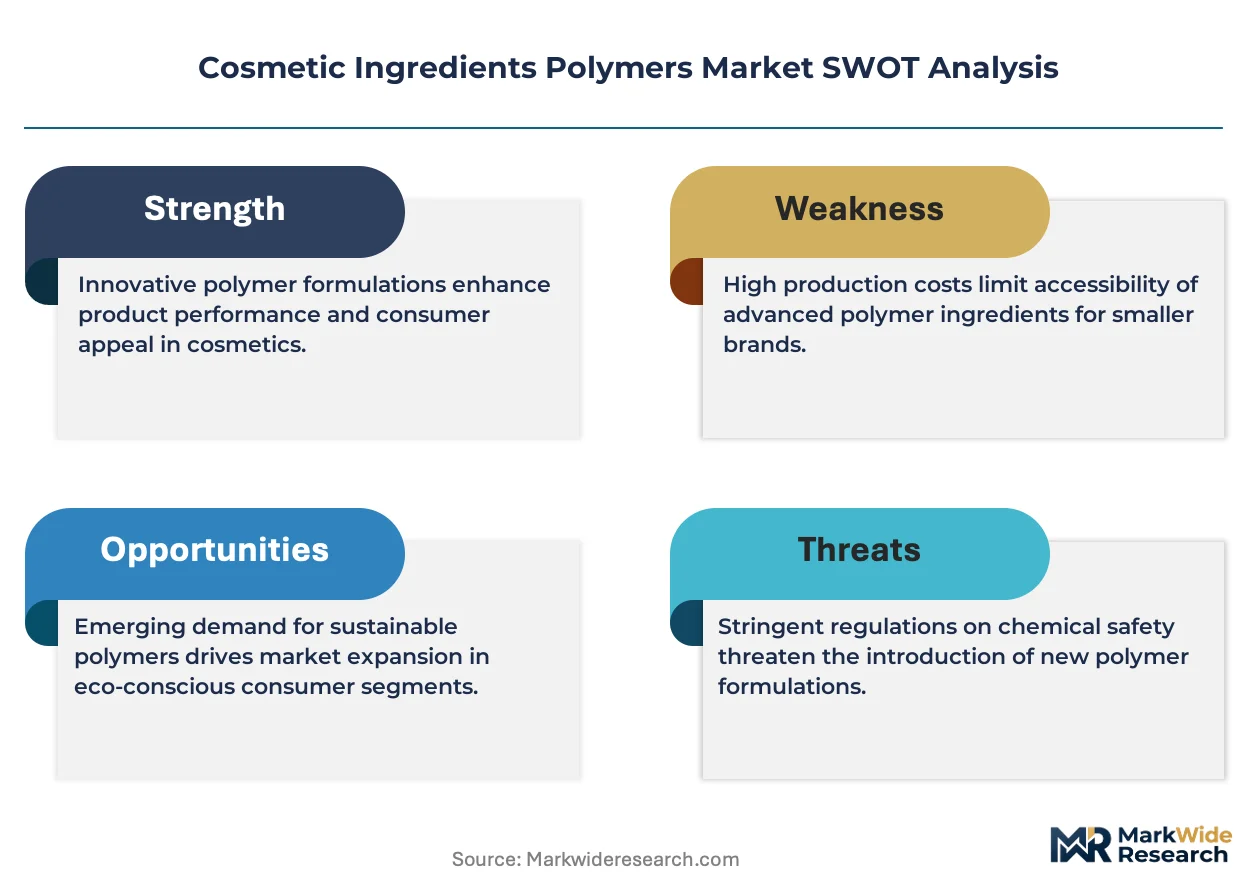
The cosmetic ingredients polymers market is shaped by the fundamental tension between the demand for novel sensory and performance attributes in formulations and the increasing stringency of global chemical safety regulations. This dynamic forces innovation toward materials that satisfy both high-efficacy requirements for skin and hair care and sustainability criteria like biodegradability.
Growth Catalysts
- Advanced Formulations:Demand for high-performance polymers, such as film formers and rheology modifiers, is expanding, driven by innovation in long-wear color cosmetics and targeted hair conditioning treatments that require specific textural and functional properties.
- Geographic Specialization:Sophisticated cosmetics markets, particularly South Korea and France, serve as innovation hubs, where intense R&D activity and discerning consumer preferences accelerate the adoption of novel and premium-priced polymers.
- Clean Beauty Movement:Consumer and brand-led sustainability initiatives are creating demand for naturally derived and biodegradable polymers, such as polysaccharides and proteins, as alternatives to traditional synthetic ingredients in formulations.
Market Restraints
- Regulatory Barriers:China's NMPA pre-market approval system for new cosmetic ingredients creates significant time-to-market delays and high compliance costs, acting as a structural barrier for polymer innovation and market access.
- Feedstock Volatility:The production costs of many synthetic polymers, including acrylates and polyolefins, are directly linked to petrochemical feedstock prices, exposing manufacturers to price volatility in the crude oil market.
- Performance Trade-offs:Biodegradable and natural polymers often present performance trade-offs, such as lower water resistance or shorter shelf stability, compared to their synthetic counterparts, limiting their use in certain high-performance applications.
Strategic Opportunities
- Bio-Based Synthetics:Developing and scaling up production of bio-based polymers that mimic the sensory and performance profiles of silicones offers a significant opportunity to capture share in the premium skin and hair care segments.
- Application Expansion:Adapting specialty rheology modifiers and sensory polymers, traditionally used in luxury skin care, for use in mass-market color cosmetics and advanced sun care formulations represents a key growth vector.
- Emerging Market Penetration:Targeting large cosmetics markets like Brazil and Mexico, where local polymer production is less advanced, provides an opportunity for exporters of specialty functional ingredients to meet rising consumer demand.
Industry Challenges
- Global Compliance Complexity:Navigating the divergent and evolving regulatory landscapes, such as the EU's REACH and the US FDA's directives, requires substantial investment in specialized legal and technical expertise to ensure market access.
- Sustainable Sourcing:Securing a stable, scalable, and traceable supply chain for high-quality raw materials for natural polymers, such as plant-based gums and starches, is a significant operational hurdle for manufacturers.
- Ingredient Validation Cycles:The lengthy and costly process of safety, stability, and efficacy testing for new polymers delays their commercialization and adoption by major cosmetic brands, slowing the pace of innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Ingredients Polymers Market |
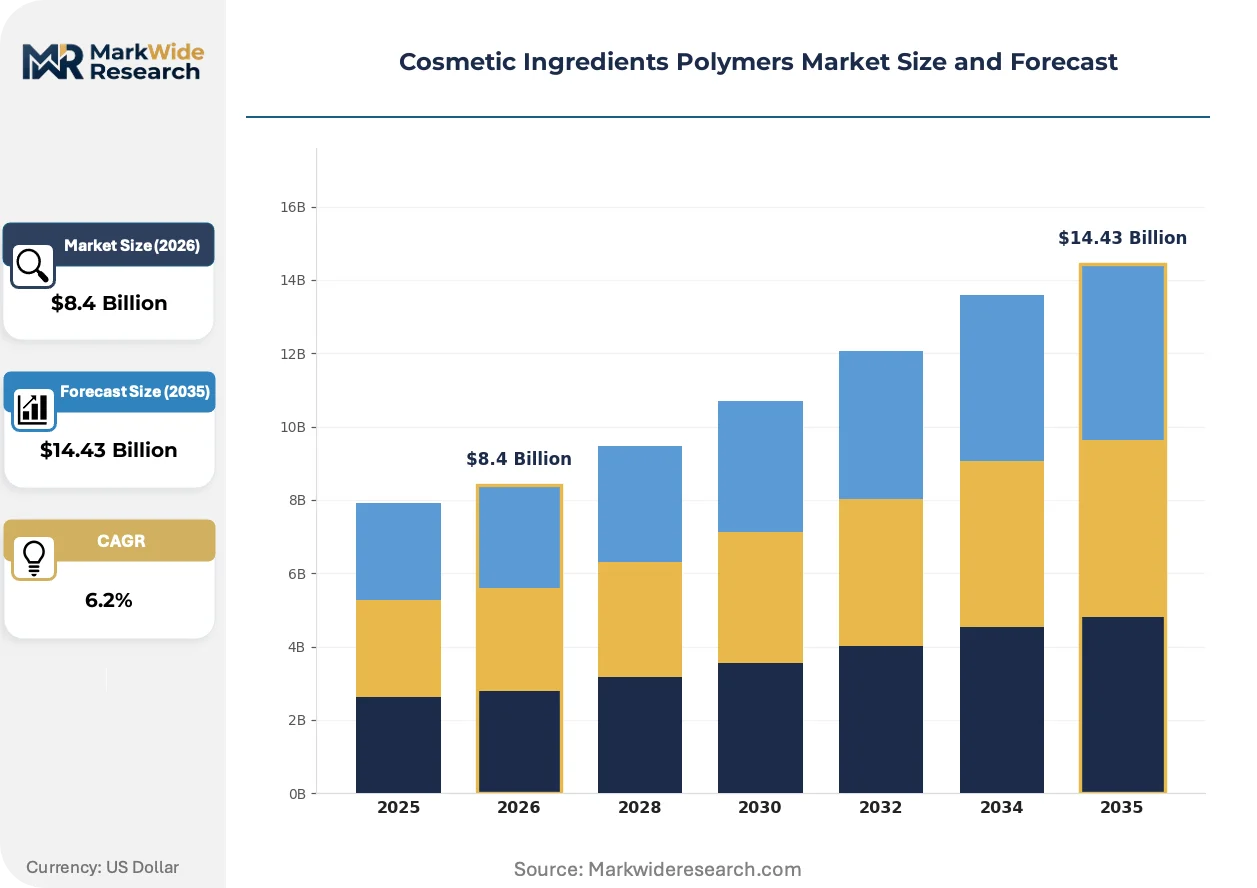
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thickening Agents, Emulsifiers, Film Formers, Conditioners Application: Skin Care, Hair Care, Makeup, Sun Care Form: Liquid, Powder, Gel, Cream Grade: Cosmetic Grade, Industrial Grade, Pharmaceutical Grade, Others |
| Companies Covered | Evonik Industries AG, The Dow Chemical Co, BASF SE, Croda International Plc, Ashland Inc, The Lubrizol Corporation, Clariant AG, Wacker Chemie, Solvay SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Ingredients Polymers Market Strategic Shifts & Innovations
Material science innovation is focused on reconciling the conflicting demands of high performance, regulatory compliance, and environmental sustainability. This effort is yielding a new generation of polymers that offer unique sensory experiences while adhering to stricter safety and biodegradability standards set by regulators and consumers.
Technology and Product Evolution
Bio-fermented polymers, created through microbial processes, deliver unique rheological and conditioning benefits. Premium skin care and "conscious beauty" brands are rapidly adopting these materials to bolster their sustainability claims and offer novel textures. The availability of these advanced biomaterials is rewriting the rules of formulation, enabling the development of products with superior performance and a reduced environmental footprint.
Regulatory and Policy Shifts
The EU's Cosmetics Regulation, in conjunction with REACH, continues to tighten restrictions on substances of concern, including certain polymer residuals and microplastics. This regulatory pressure directly forces material substitution away from legacy synthetic polymers in rinse-off and leave-on products. The hair care and exfoliants segments are most affected, responding by accelerating research into biodegradable alternatives like modified celluloses and starches.
Demand-Side and Behavioral Shifts
A notable shift in formulation strategy involves prioritizing multifunctional polymers over single-purpose ingredients. Cosmetic chemists are increasingly replacing separate thickeners, emulsifiers, and stabilizers with a single, sophisticated polymer that can perform all three functions. This trend is most visible within the mass-market skin care sector in North America, where it streamlines both the formulation process and the procurement of raw materials.
Cosmetic Ingredients Polymers Market Segmentation
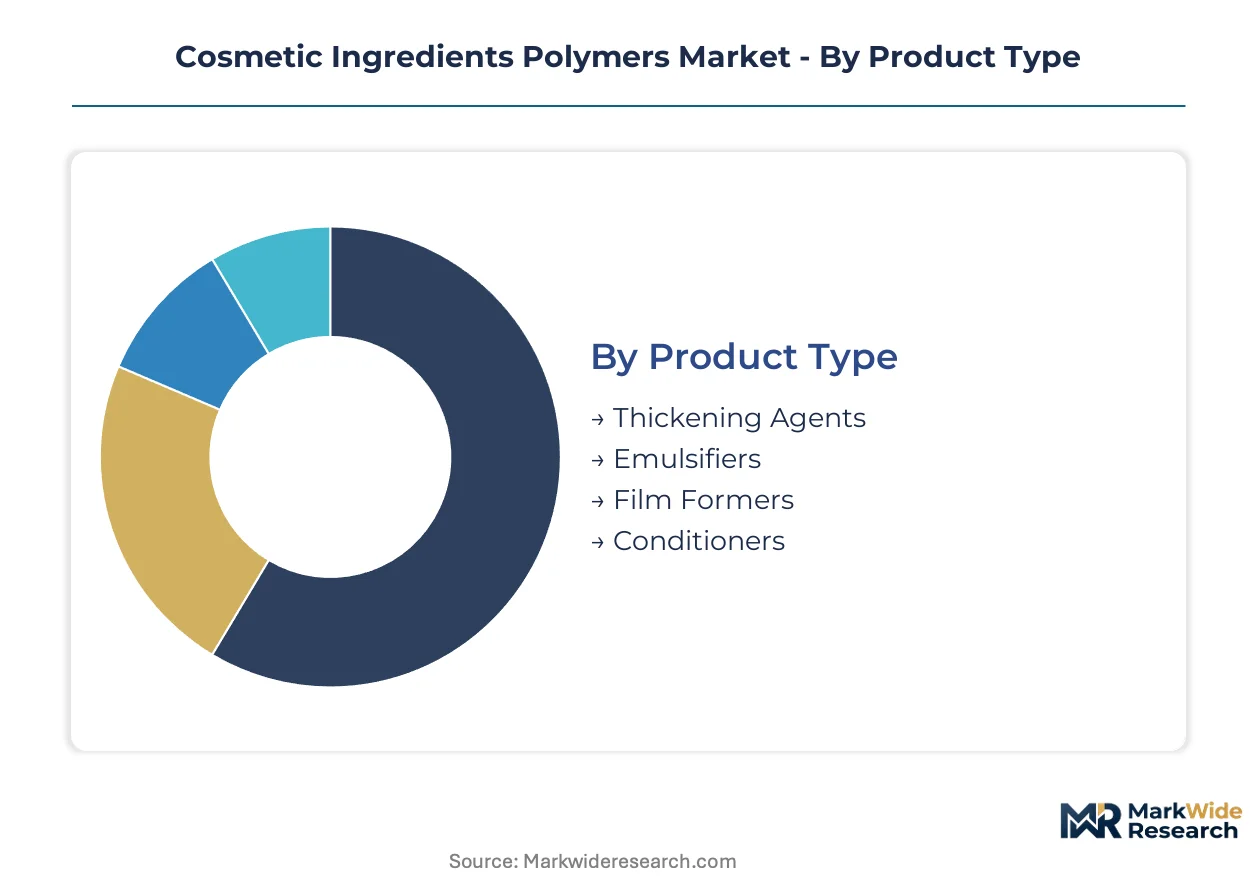
The cosmetic ingredients polymers market segments across various dimensions, reflecting the diverse needs of personal care formulations. Understanding these classifications provides clarity on material selection, performance attributes, and regulatory compliance pathways. Each segment plays a distinct role in shaping product efficacy and consumer experience across different cosmetic applications.
Product Type:
The product type segmentation highlights the fundamental tension between high-volume, cost-effective ingredients and specialized, premium-priced functional polymers. Formulators balance widespread utility with advanced performance requirements for specific cosmetic outcomes.
- Film Formers:These polymers create a thin, flexible, and often water-resistant layer on skin or hair, enhancing product longevity and wear. Demand concentrates in long-wear color cosmetics and sun care formulations, driven by consumer preference for durable performance.
- Conditioners:Designed to improve the tactile properties of hair and skin, these ingredients reduce friction, enhance shine, and provide a smooth feel. Hair care applications, particularly leave-in treatments, drive innovation in novel conditioning agents for improved sensory effects.
- Thickening Agents:These materials increase the viscosity of liquid formulations, providing desired texture and stability. Polysaccharides and synthetic polymers are widely used.
- Emulsifiers:Polymers in this category stabilize oil-in-water or water-in-oil mixtures, preventing phase separation. They are essential for creating stable cosmetic emulsions.
Today's leader: Thickening Agents. Tomorrow's challenger: Film Formers.
Application:
Application focus significantly influences polymer selection, dictating the required performance attributes and formulation complexity for cosmetic products. Each end-use sector presents unique challenges and opportunities for polymer innovation.
- Skin Care:This application segment is the largest consumer of cosmetic polymers, utilizing them for hydration, texture modification, and active ingredient delivery. Creams, serums, and lotions rely on a diverse range of polymers to achieve desired sensory and functional benefits.
- Makeup:Polymers in makeup formulations enhance wear, adhesion, and aesthetic appeal, from foundations to mascaras. Long-wear and transfer-resistant properties are critical drivers for polymer innovation in this segment, especially for color cosmetics.
- Hair Care:Polymers in hair care products provide conditioning, styling, and damage protection benefits. Shampoos and conditioners utilize specific polymers.
- Sun Care:This segment employs polymers to improve water resistance, SPF boosting, and texture of sunscreens. Film formers are important for durable protection.
The largest revenue contributor is Skin Care, while Makeup exhibits the steepest expansion trajectory.
Form:
The physical state of cosmetic polymers influences their ease of incorporation into formulations, storage stability, and processing requirements. Manufacturers choose forms based on formulation compatibility and production efficiency.
- Liquid:Liquid polymers offer ease of dispersion and integration into aqueous or oil-based cosmetic systems. Their fluid nature simplifies handling and dosing in large-scale manufacturing processes, making them highly versatile.
- Powder:Powdered polymers provide excellent stability and can be easily stored, often requiring rehydration or dispersion during formulation. They are frequently used in dry shampoo formulations and pressed cosmetic products.
- Gel:Gel polymers typically form a gel structure upon mixing, offering specific textural and sensory properties. These are common in transparent products.
- Cream:Polymers in cream form are often pre-blended into a base, simplifying the formulation process for cosmetic brands. This is useful for specialty ingredients.
Formulations frequently leverage Liquid polymers for broad utility, with Powder forms gaining traction in specialized applications.
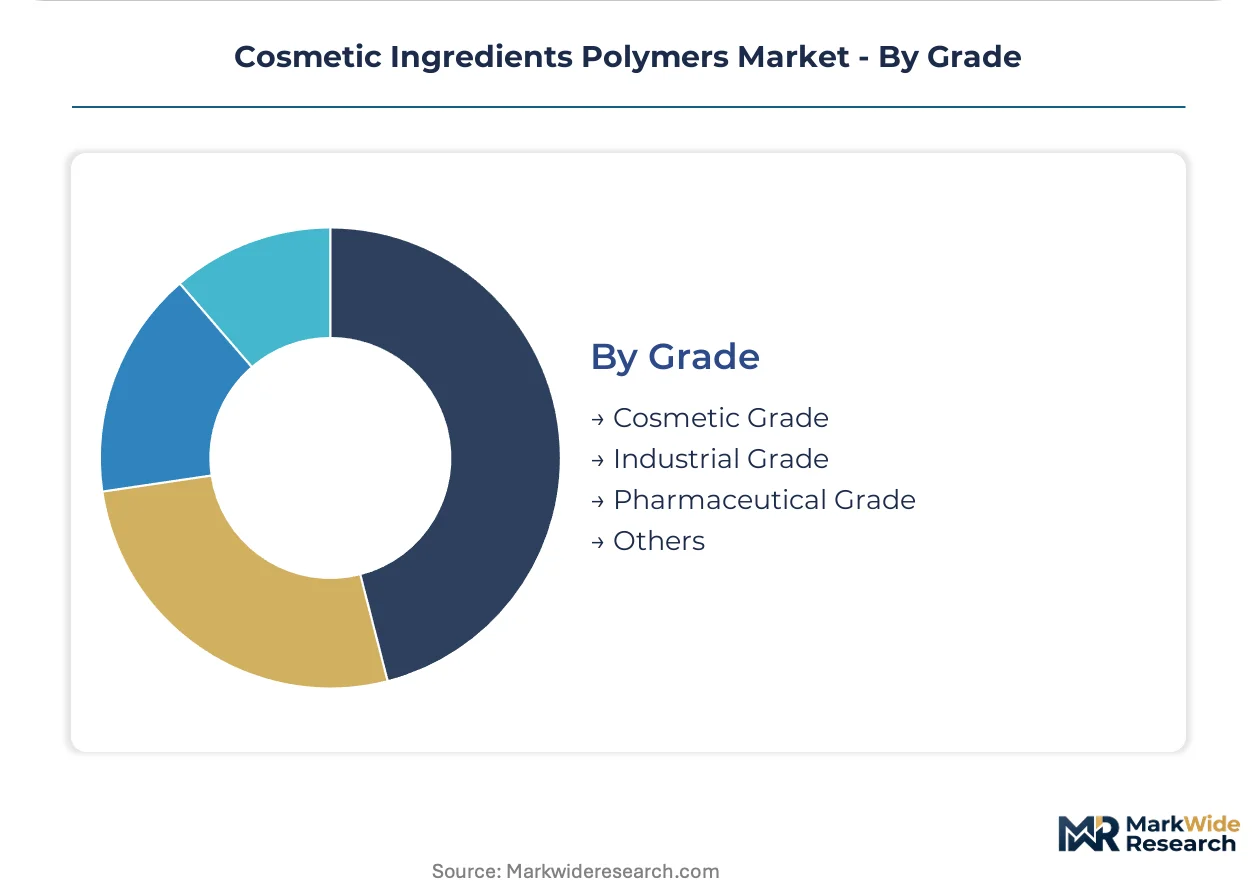
Grade:
Polymer grade reflects the purity levels, manufacturing standards, and regulatory compliance, directly impacting their suitability for various cosmetic applications. Stringent quality controls define the utility and market access for each grade.
- Cosmetic Grade:These polymers meet specific purity and safety standards for direct application in personal care products. Regulatory bodies like the US FDA and the EU's ECHA govern the permissible limits for impurities in cosmetic ingredients.
- Pharmaceutical Grade:Polymers at this level adhere to the highest purity and manufacturing standards, often suitable for medical devices or pharmaceutical applications with skin contact. Their use in cosmetics typically implies superior quality and reduced allergenicity.
- Industrial Grade:These polymers are typically used in non-cosmetic applications, with less stringent purity requirements. Use in personal care is restricted.
- Others:This category encompasses specialized grades or niche polymers tailored for very specific, often emerging, cosmetic applications.
The primary material specification is Cosmetic Grade, while Pharmaceutical Grade commands a premium due to stringent quality demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The regulatory landscape significantly influences the global distribution of polymer production, with compliance costs often driving shifts in manufacturing centers. This dynamic creates opportunities for regions with streamlined approval processes or those specializing in advanced material science. Geographies with established cosmetic industries and high R&D investments continue to lead in polymer innovation and adoption.
South Korea
Demand for advanced polymers in South Korea stems from its innovative K-beauty market and focus on high-performance skincare. The MFDS (Ministry of Food and Drug Safety) strictly regulates cosmetic ingredient safety and efficacy. Seoul's vibrant beauty innovation districts actively foster research and development in novel polymer technologies.
France
France drives demand for premium cosmetic polymers through its luxury beauty brands and stringent formulation standards. The ANSM (national agency for the safety of medicines and health products) and EU's REACH regulation govern chemical substance safety. Cosmetic Valley, centered around Chartres, serves as a major hub for advanced polymer development.
United States
The United States market requires diverse polymers for both mass-market and prestige beauty products, emphasizing performance and safety. The FDA (Food and Drug Administration) provides comprehensive guidelines for cosmetic ingredient approval and labeling. New Jersey and California host significant cosmetic R&D centers, driving material innovation.
China
Expanding consumer demand in China for advanced cosmetic formulations necessitates a wide range of functional polymers. The NMPA (National Medical Products Administration) enforces strict pre-market approval and testing for new cosmetic ingredients. Major cosmetic manufacturing and R&D hubs like Shanghai and Guangzhou are crucial for market access.
Germany
Germany, a leader in specialty chemicals, exhibits strong demand for high-performance and sustainable cosmetic polymers. Compliance with EU's ECHA (European Chemicals Agency) and REACH regulations is paramount for market entry. The Rhine-Main region supports extensive chemical and polymer synthesis for the cosmetics industry.
Cosmetic Ingredients Polymers Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue bio-based and sustainable polymer innovations. The market exhibits a tiered structure with large integrated chemical companies and specialized ingredient suppliers. These archetypes include global chemical conglomerates, specialty chemical providers, and niche bio-material innovators. Strategic partnerships and portfolio diversification are common competitive moves.
On the premium-tier vector, BASF SE, a German chemical giant, leverages its integrated production network to offer a diverse polymer portfolio. The Lubrizol Corporation, a US-based specialty chemical provider, exemplifies expertise in high-performance rheology modifiers and film formers. Evonik Industries AG, a German specialty chemical company, anchors the silicone-based and specialty acrylate polymer segment for unique sensory effects.
| Leading Market Players |
|---|
| Evonik Industries AG |
| The Dow Chemical Co |
| BASF SE |
| Croda International Plc |
| Ashland Inc |
| The Lubrizol Corporation |
| Clariant AG |
| Wacker Chemie |
| Solvay SA |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock prices directly influence the cost structure of synthetic cosmetic polymers, impacting pricing across premium and mass-market formulations. This upstream volatility translates into downstream price adjustments for cosmetic brands.
Pricing Analysis
Raw material cost fluctuations frequently pass through to the final polymer pricing, especially for commodity-grade synthetic options. Pricing stratifies across premium, standard, and economy tiers, influenced by quality grade and volume scale. Regulatory compliance costs and specialized performance attributes also drive price differentiation. Pricing pressure stems from feedstock volatility, particularly impacting high-volume segments. Mass-market skin care brands exhibit higher price sensitivity compared to luxury cosmetic formulators.
Supply Chain Analysis
Stringent regulatory compliance, such as EU's REACH or China's NMPA pre-market approval, acts as a significant gating factor for polymer suppliers. Supply concentrations are evident in Germany, the United States, and China, key manufacturing hubs for specialty chemicals. The industry relies heavily on petrochemical feedstocks and, increasingly, on plant-based gums for natural polymers. Commodity price volatility for crude oil represents a structural supply chain risk. Distribution runs through a network of global chemical conglomerates and specialized ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, where evolving compliance standards actively reshape material science innovation. The EU's REACH regulation, for example, directly drives demand for safer, more sustainable polymer alternatives.
For Market Incumbents: Acquire specialized bio-material innovators to accelerate portfolio diversification into sustainable polymers. Incumbents must invest heavily in R&D for advanced bio-based synthetics to counter regulatory pressure on legacy ingredients. Expanding integrated production networks for naturally derived polymers mitigates future feedstock volatility and defends market share against emerging entrants offering green alternatives.
For New Entrants and Emerging Players: China's NMPA pre-market approval system opens a window for new entrants specializing in novel, pre-approved ingredients. Target emerging markets like Brazil and Mexico with bio-fermented polymers, capitalizing on rising consumer demand for "conscious beauty" products. Focus on developing multifunctional polymers that deliver superior sensory effects and sustainability claims, providing a clear go-to-market advantage.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized expertise in sustainable polymer chemistry meets high market access barriers. Long-term viability remains strong over the next decade due to sustained demand for high-performance and eco-friendly cosmetic ingredients. Target niche bio-material innovators or specialty chemical providers with robust R&D pipelines for acquisition. A signal to watch is the increasing adoption rates of advanced bio-based synthetics in premium skin care formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Bio-Based Synthetics | This initiative addresses performance gaps while meeting consumer and regulatory demand for sustainable ingredients. |
| Capacity Expansion for Natural Polymers | Scaling production of plant-based and bio-fermented materials meets the rising demand for green alternatives. |
| Regulatory Compliance Investment | Proactive investment ensures market access in complex regions and avoids costly penalties for non-compliant materials. |
| Strategic Partnerships for Distribution | Collaborations with local distributors expand market reach, especially in high-growth emerging economies. |
| Portfolio Diversification into Mass Market | Adapting luxury-grade polymers for broader use captures a larger consumer base and drives volume growth. |
Research Approach
Direct dialogue with R&D directors, procurement leads at cosmetic brands, regulatory affairs specialists, and polymer scientists grounded this analysis. This primary research was rigorously validated through extensive secondary data sources. Secondary sources included regulatory filings from REACH and NMPA, industry association reports, patent databases, and relevant company financial statements. Bottom-up and top-down triangulation ensured data accuracy and comprehensive market understanding.
Quantitative models produced volume and value forecasts, extrapolating historical data and incorporating expert consensus over the projection horizon. The analytical framework segmented the market by Product Type, Application, Form, Grade, and distinct regional demand patterns. Compound annual growth rates were derived through regression analysis and market share projections. Key forecast inputs included cosmetic ingredient innovation cycles and anticipated regulatory changes.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of geopolitical instability or sudden, unforeseen regulatory shifts. These forecasts reflect assumptions documented throughout the study. A model refresh is warranted upon material change in global trade policies or key feedstock availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Cosmetic Grade CI 77491 Market
Cosmetic Chemicals
Cosmetic & Toiletry Chemicals Market
Cosmetic Chemicals
Cosmetic Isoparaffins Market
Cosmetic Chemicals
Eyelash Enhancing Agents Market
Cosmetic Chemicals
Hair Lightening Product Market
Cosmetic Chemicals
Hair Gloss Market
Cosmetic Chemicals
Lanolin Nipple Cream Market
Cosmetic Chemicals
Anti-Acne Serum Market
Cosmetic Chemicals
Global Argireline Market
Cosmetic Chemicals
Fractionated Shea Butter in Cosmetics and Personal Care Market
Cosmetic Chemicals
Organic Cosmetic Ingredients Market
Cosmetic Chemicals
Anti-Aging Serums Market
Cosmetic Chemicals
Shea Butter Market
Cosmetic Chemicals
China Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Global Hyaluronic Acid Based Dermal Fillers Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market