
 Glass Abrasives Market | 2026-2036
Glass Abrasives Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Abrasives Market Intelligence
Aerospace manufacturing is pivoting toward finer-grade glass abrasives as airframers tighten surface-roughness tolerances on turbine components. Saint-Gobain leverages its fused mineral expertise to supply aerospace-certified glass bead grades across European and North American certification chains. Tyrolit anchors its position through bonded abrasive integration, offering glass-based media within broader surface-preparation systems. Marco Group International specializes in crushed glass sourcing and distribution, controlling coastal logistics channels that serve shipyard clusters.
Glass abrasives comprise angular or spherical particulate manufactured from post-consumer or post-industrial glass, crushed and screened to mesh sizes ranging from coarse 12-mesh to ultrafine 325-mesh, then applied via pneumatic blasting, centrifugal wheel systems, or vibratory mass-finishing equipment to clean, deburr, texture, or prepare substrates for coating adhesion. Crushed glass commands volume leadership in heavy-duty surface preparation due to its aggressive cutting profile and lower free-silica hazard profile versus mineral slags. Glass beads retain margin concentration in aerospace and electronics finishing, where spherical morphology preserves dimensional tolerances on precision-machined components.
OSHA enforces permissible exposure limits on respirable crystalline silica, pushing metal fabricators and construction contractors toward glass-based substitutes that fall outside the most stringent silica monitoring protocols. The EPA regulates spent abrasive disposal under solid-waste and hazardous-waste frameworks, influencing whether users choose chemically inert glass media to simplify landfill or beneficial-reuse pathways. REACH and RoHS compliance in Europe restricts heavy-metal content in abrasive feedstocks, favoring suppliers with verified recycled-glass supply chains and X-ray fluorescence batch certification. Stakeholders must monitor evolving state-level silica rules and end-user sustainability scorecards that increasingly score abrasive sourcing on circular-economy credentials.
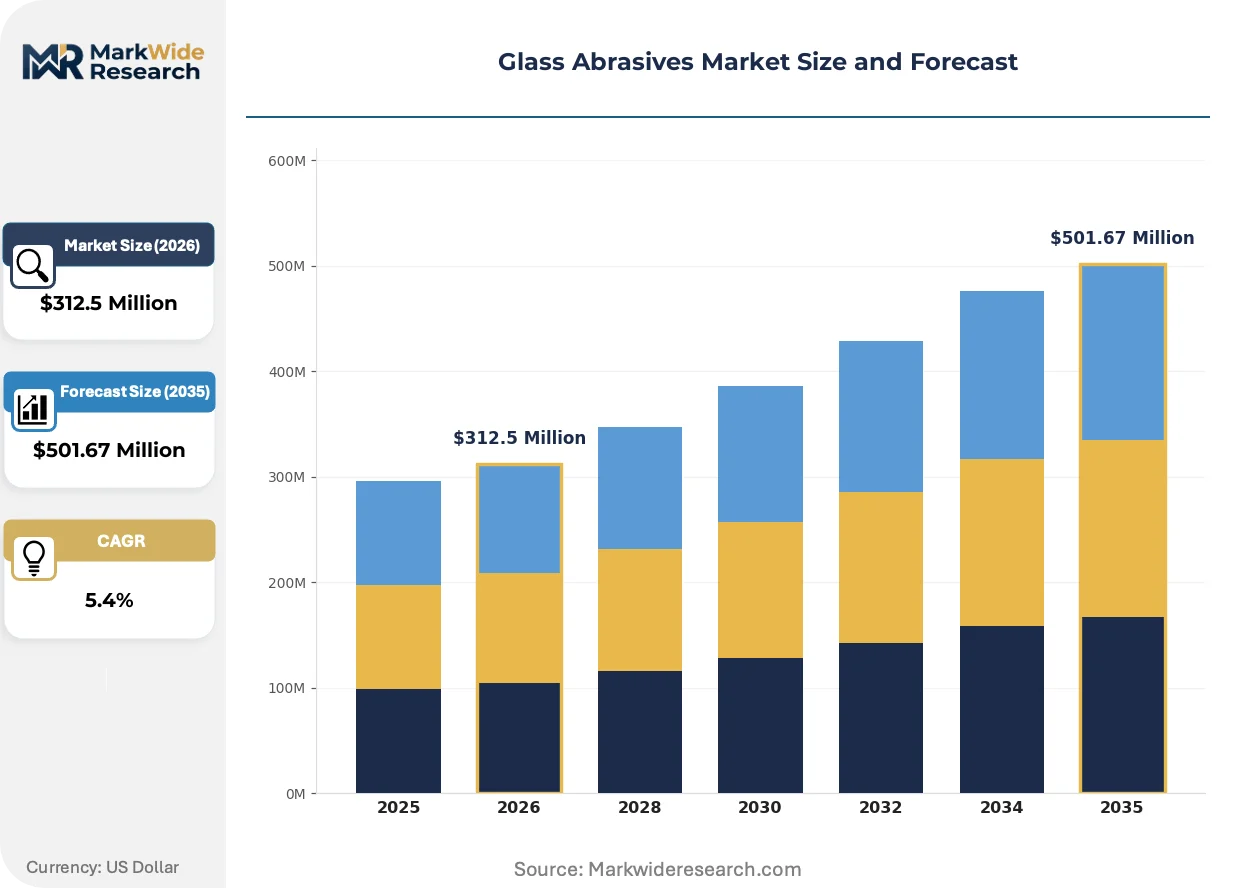
Market Dynamics
OSHA's tightening silica exposure limits are compressing demand for mineral slags and redirecting specification authority toward crushed glass abrasives across North American metal fabrication and shipyard maintenance contracts.
Growth Catalysts
- OSHA permissible exposure limits:Metal fabricators in the United States face stepped-up respirable crystalline silica enforcement, accelerating specification switches to chemically inert crushed glass media that falls outside stringent monitoring protocols.
- Aerospace surface-roughness tolerances:Airframers demand finer-grade spherical glass beads for precision finishing on turbine blades and airframe components, tightening quality certification chains across European and North American supply bases.
- Post-consumer glass feedstock:Municipal recycling programs in Germany concentrate supply of color-sorted cullet, enabling automotive OEMs and Tier-1 suppliers to specify verified recycled-glass abrasives for powertrain component finishing.
Market Restraints
- Natural gas price volatility:Glass bead production requires sustained furnace temperatures that expose manufacturers to input cost swings, compressing margin stability for fused mineral processors.
- Logistics concentration risk:Coastal distribution channels serving shipyard clusters in the Gulf of Mexico and Pacific Northwest create geographic chokepoints that amplify delivery uncertainty during port congestion.
- Aluminum oxide substitution:Heavy-duty surface preparation contractors retain fallback options in fused alumina media, capping pricing power for crushed glass in aggressive cutting applications.
Strategic Opportunities
- Beneficial reuse pathways:EPA solid-waste frameworks favor chemically inert spent glass media for landfill diversion or construction aggregate feedstock, opening circular-economy scoring advantages on end-user sustainability scorecards.
- Electronics precision finishing:Semiconductor and medical device manufacturers specify ultrafine 325-mesh glass beads for delicate deburring operations, expanding addressable market beyond traditional metalworking.
- CE marking convergence:REACH and RoHS compliance requirements restrict heavy-metal content in abrasive feedstocks, rewarding suppliers with X-ray fluorescence batch certification and verified recycled-glass supply chains.
Industry Challenges
- Mesh-size certification timelines:Aerospace and automotive OEMs impose extended qualification periods for new abrasive grades, stretching working capital cycles for producers seeking specification entry.
- Pneumatic blasting system integration:Contractors operating legacy sandblasting equipment face retrofit costs and operator retraining to optimize delivery pressure and media flow rates for angular crushed glass morphology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Abrasives Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crushed Glass, Glass Microbeads, Glass Beads, Glass Powder, Fiberglass, Glass Flakes Application: Surface Preparation, Cleaning, Finishing, Polishing, Deburring, Texturing End User Industry: Metal Fabricators, Marine Coatings, Aerospace Manufacturers, Electronics Assemblers, Construction Contractors, Artisans Packaging Type: Sacks, Bulk Bags, Fiber Drums, Paper Bags, Cartons, Plastic Bags |
| Companies Covered | Tyrolit, Marco Group International, Saint-Gobain, GlassOx Abrasives, Vitro Minerals, 3M, Carborundum Universal Limited, Harsco Minerals, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Abrasives Market Strategic Shifts & Innovations
Specification authority is migrating from procurement departments to environmental compliance officers and sustainability scorecard administrators, reshaping how abrasive suppliers demonstrate feedstock provenance and end-of-life disposal credentials.
Ultrafine 325-mesh glass bead grades are overtaking coarser mineral slags in aerospace turbine blade finishing. Airframers in France and the United States specify these spherical media to preserve dimensional tolerances on precision-machined nickel superalloy components. The shift is compressing addressable volume for angular abrasives in applications where surface roughness parameters now dictate media selection.
REACH authorization procedures for heavy-metal content in industrial feedstocks are tightening batch certification requirements across European supply chains. ECHA oversight is forcing abrasive importers to document X-ray fluorescence testing for every production lot, raising compliance overhead. German automotive OEMs and their Tier-1 suppliers are responding by consolidating procurement around domestic recyclers with verified closed-loop cullet sourcing.
Buyer concentration among national shipyard maintenance contractors is consolidating specification authority into fewer procurement desks. Direct sourcing agreements with coastal logistics specialists are replacing fragmented distributor networks in the United States Gulf Coast cluster. This channel compression is most visible in military vessel refit contracts where long-term abrasive supply agreements now bundle spent media take-back and recycling services.
Glass Abrasives Market Segmentation
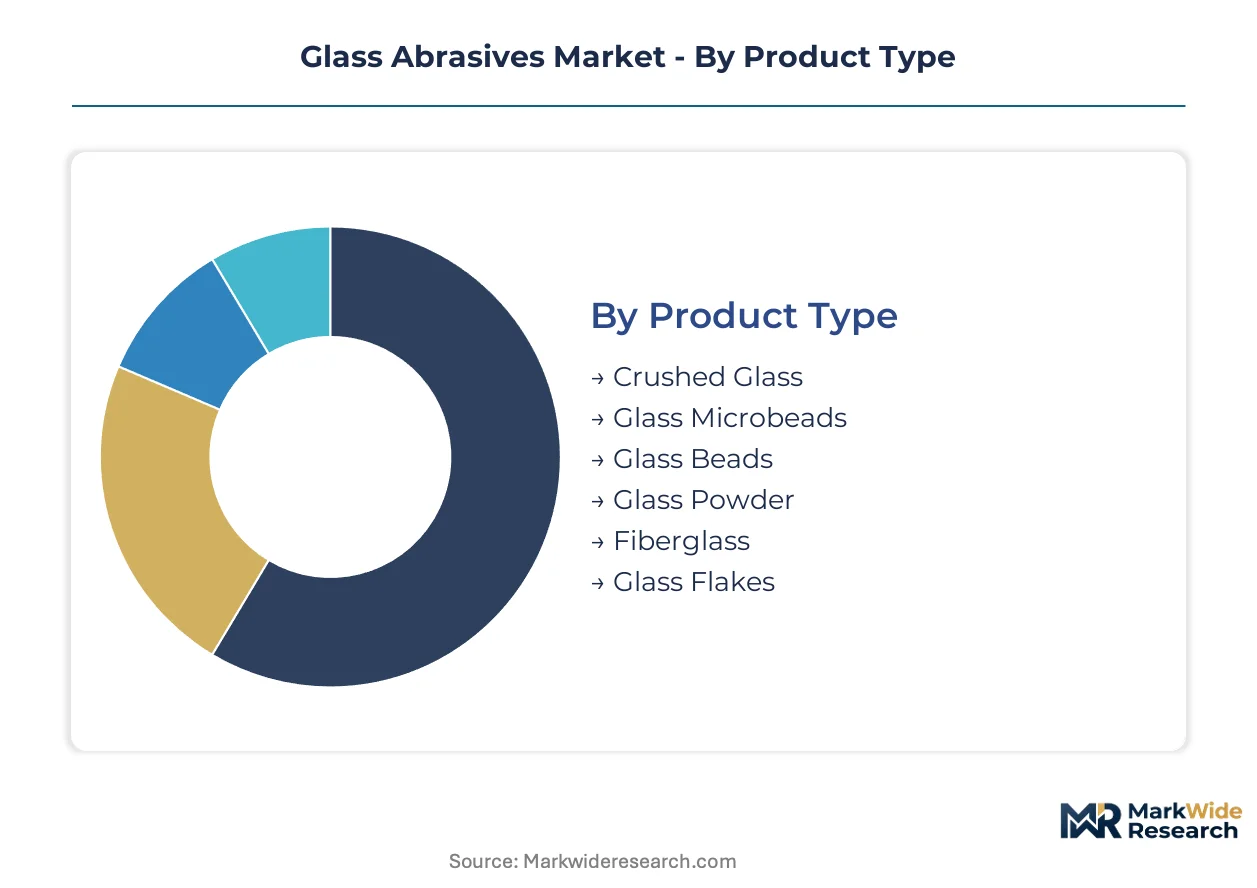
Glass abrasives serve divergent performance requirements across surface preparation intensity levels, from aggressive stock removal to precision dimensional preservation. Segmentation reveals how product morphology, packaging logistics, and end-user compliance obligations reshape procurement patterns and supplier margin structures.
Product Type:
Integration depth varies sharply: crushed glass operates as standalone blasting media, while glass beads embed within precision finishing systems requiring calibrated delivery equipment.
- Crushed Glass:Angular particulate manufactured from post-consumer cullet, screened to 12-80 mesh for aggressive cutting action. Marine coatings contractors in the United States specify this grade for ship hull stripping, driven by OSHA silica substitution mandates that displace mineral slags from blasting yards.
- Glass Beads:Spherical fused soda-lime glass graded 60-325 mesh for peening and dimensional finishing. Aerospace manufacturers in France and Germany demand certified bead lots for turbine blade surface preparation, where tight roughness tolerances override media cost considerations.
- Glass Microbeads:Ultrafine spherical media below 200 mesh for electronics deburring and medical instrument finishing.
- Glass Powder:Sub-325 mesh particulate for precision polishing and lapping compound feedstock.
- Fiberglass:Chopped strand or milled fiber forms for reinforced abrasive wheels and bonded grinding products.
- Glass Flakes:Lamellar particulate for anti-corrosion coatings and reflective pigment applications.
Volume placements concentrate in Crushed Glass; the faster expansion belongs to Glass Beads.
Application:
Cost tier stratification separates commodity surface preparation from premium finishing operations where certification overhead justifies media price multiples.
- Surface Preparation:Heavy-duty substrate cleaning and coating removal via pneumatic or centrifugal blasting. Construction contractors across Gulf Coast shipyards specify crushed glass for structural steel pretreatment, balancing cutting speed against disposal cost advantages under EPA solid-waste frameworks.
- Finishing:Controlled surface modification to achieve specified roughness or aesthetic parameters. Automotive powertrain suppliers in Germany specify glass bead peening for crankshaft stress relief, where OEM qualification protocols lock in supplier relationships across multi-year contracts.
- Cleaning:Contaminant removal without dimensional change, common in restoration and maintenance operations.
- Polishing:Fine surface refinement using progressively finer media grades.
- Deburring:Edge conditioning on machined components, expanding fastest in electronics assembly.
- Texturing:Decorative or functional surface roughening for adhesion promotion.
Revenue pools are deepest in Surface Preparation; margin capture concentrates in Finishing.
End User Industry:
Customer type segmentation maps divergent procurement authority structures, from centralized fleet purchasing to distributed workshop-level specification.
- Metal Fabricators:Structural steel processors and job shops consuming bulk crushed glass for pretreatment. United States fabricators face stepped-up OSHA silica enforcement, redirecting specification authority toward environmental compliance officers who favor chemically inert glass substitutes.
- Aerospace Manufacturers:Airframers and engine OEMs demanding certified spherical beads for superalloy component finishing. French and American turbine producers impose extended qualification timelines that stretch supplier working capital cycles.
- Marine Coatings:Shipyard maintenance contractors and new-build coating applicators.
- Electronics Assemblers:Semiconductor and medical device manufacturers specifying ultrafine grades.
- Construction Contractors:Infrastructure and industrial project operators.
- Artisans:Small-scale restoration, jewelry, and craft applications.
Contract volumes dominate Metal Fabricators; specification stickiness favors Aerospace Manufacturers.
Packaging Type:
Supply concentration in coastal logistics corridors shapes packaging selection, with bulk formats dominating high-volume shipyard clusters and unitized packaging serving distributed fabrication networks.
- Bulk Bags:One-ton flexible intermediate bulk containers for automated blasting systems. Gulf Coast and Pacific Northwest shipyard clusters specify bulk delivery to minimize handling labor and port congestion exposure.
- Sacks:50-pound woven polypropylene units for job-site mobility. Metal fabricators across Midwest industrial corridors favor sack packaging for workshop-scale storage and manual loading flexibility.
- Fiber Drums:Rigid containment for moisture-sensitive microbead grades.
- Paper Bags:Lower-cost option for non-critical crushed glass applications.
- Cartons:Unitized retail and artisan-scale distribution.
- Plastic Bags:Moisture barrier protection for humid climates.
Shipment tonnage clusters in Bulk Bags; packaging diversification concentrates in Sacks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast Opportunity Zones in Louisiana and Texas concentrate shipyard maintenance demand for crushed glass abrasives, while German automotive clusters drive spherical bead specifications through closed-loop cullet supply chains.
United States
OSHA respirable crystalline silica enforcement redirects metal fabricators toward chemically inert crushed glass substitutes. The EPA solid-waste framework favors glass media for landfill diversion, simplifying disposal pathways for construction contractors. Gulf Coast shipyard clusters in Louisiana and Texas specify bulk-format crushed glass for structural steel pretreatment, bundling spent media take-back into long-term supply agreements.
Germany
Automotive OEMs and Tier-1 suppliers specify certified glass bead media for powertrain component finishing, locking in multi-year supplier relationships through qualification protocols. REACH authorization procedures restrict heavy-metal content in abrasive feedstocks, forcing importers to document X-ray fluorescence testing for every production lot. Bavarian automotive clusters concentrate procurement around domestic recyclers with verified closed-loop cullet sourcing from municipal color-sorting programs.
France
Airframers demand ultrafine spherical glass beads for turbine blade surface preparation on nickel superalloy components. ECHA oversight tightens batch certification requirements across European supply chains, raising compliance overhead for abrasive importers. Aerospace manufacturing corridors around Toulouse and Paris specify finer-grade media as surface-roughness tolerances tighten on precision-machined engine components.
China
Industrial surface preparation contractors face stepped-up environmental monitoring on mineral slag disposal, redirecting specification authority toward glass-based substitutes. National standards on construction waste management influence media selection for infrastructure steel pretreatment. Yangtze River Delta fabrication clusters test crushed glass alternatives for shipbuilding and bridge construction applications.
Japan
Electronics assemblers specify ultrafine 325-mesh glass beads for semiconductor and medical device deburring operations. METI circular-economy guidelines score abrasive sourcing on feedstock provenance and end-of-life disposal credentials. Kanto manufacturing corridors around Tokyo concentrate demand for precision finishing media in electronics and precision instrument production.
Glass Abrasives Market Key Industry Players
Top-tier vendors anchor aerospace and automotive certification chains, while mid-scale distributors control coastal logistics corridors serving shipyard clusters. The vendor base stratifies across three tiers: fused mineral specialists with furnace-based bead production, recycled-glass processors with cullet-sorting capabilities, and distribution-centric operators with port-adjacent storage infrastructure. Strategic moves concentrate on backward integration into post-consumer glass feedstock sourcing and geographic expansion through coastal hub acquisition.
Within the premium-tier certification vector, Saint-Gobain leverages its fused mineral expertise to supply aerospace-certified glass bead grades, while Tyrolit anchors its position through bonded abrasive integration. Marco Group International occupies a distribution-focused position, controlling coastal logistics channels that serve shipyard maintenance contractors. These three entities exemplify the dominant competitive archetypes: furnace-based production specialists, integrated surface-preparation system providers, and logistics-centric distributors with port-adjacent concentration.
| Leading Market Players |
|---|
| Tyrolit |
| Marco Group International |
| Saint-Gobain |
| GlassOx Abrasives |
| Vitro Minerals |
| 3M |
| Carborundum Universal Limited |
| Harsco Minerals |
| Robert Bosch GmbH |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between aerospace-qualified spherical beads and commodity crushed glass creates parallel pricing architectures that feed distinct supply chain configurations. German automotive OEMs and Tier-1 suppliers pay premium multiples for REACH-verified bead lots with X-ray fluorescence batch documentation, while Gulf Coast shipyard contractors negotiate bulk-tonnage crushed glass contracts indexed to natural gas furnace costs and port logistics availability.
Pricing Analysis
Short-lead-time premiums apply to aerospace-certified glass bead grades where French and German airframers impose extended qualification timelines that compress supplier working capital cycles. Three-tier pricing structure across premium, standard, and economy levels separates certified aerospace beads from automotive-grade peening media from unclassified construction blasting supply. Price differentiation hinges on XRF certification overhead and closed-loop cullet provenance documentation. Cost compression in commodity crushed glass is intensifying because natural gas price volatility exposes furnace operators to input cost swings. Metal fabricators in the United States Midwest exhibit highest price sensitivity, while aerospace manufacturers in Toulouse and Paris show lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Freight cost concentration in coastal logistics corridors serving Gulf Coast and Pacific Northwest shipyard clusters amplifies delivery uncertainty during port congestion episodes. Supply concentrates in the United States, Germany, and China, with German Bavarian clusters feeding automotive specification chains and Yangtze River Delta fabrication hubs testing crushed glass alternatives. Raw material dependencies draw from municipal color-sorted cullet programs, natural gas for fused bead furnace operations, and soda-lime glass feedstock chemistry. Single-source vulnerability runs through coastal distribution channels where Marco Group International and similar operators control port-adjacent storage infrastructure. Distribution runs through direct sourcing agreements with national shipyard maintenance contractors that bundle spent media take-back services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
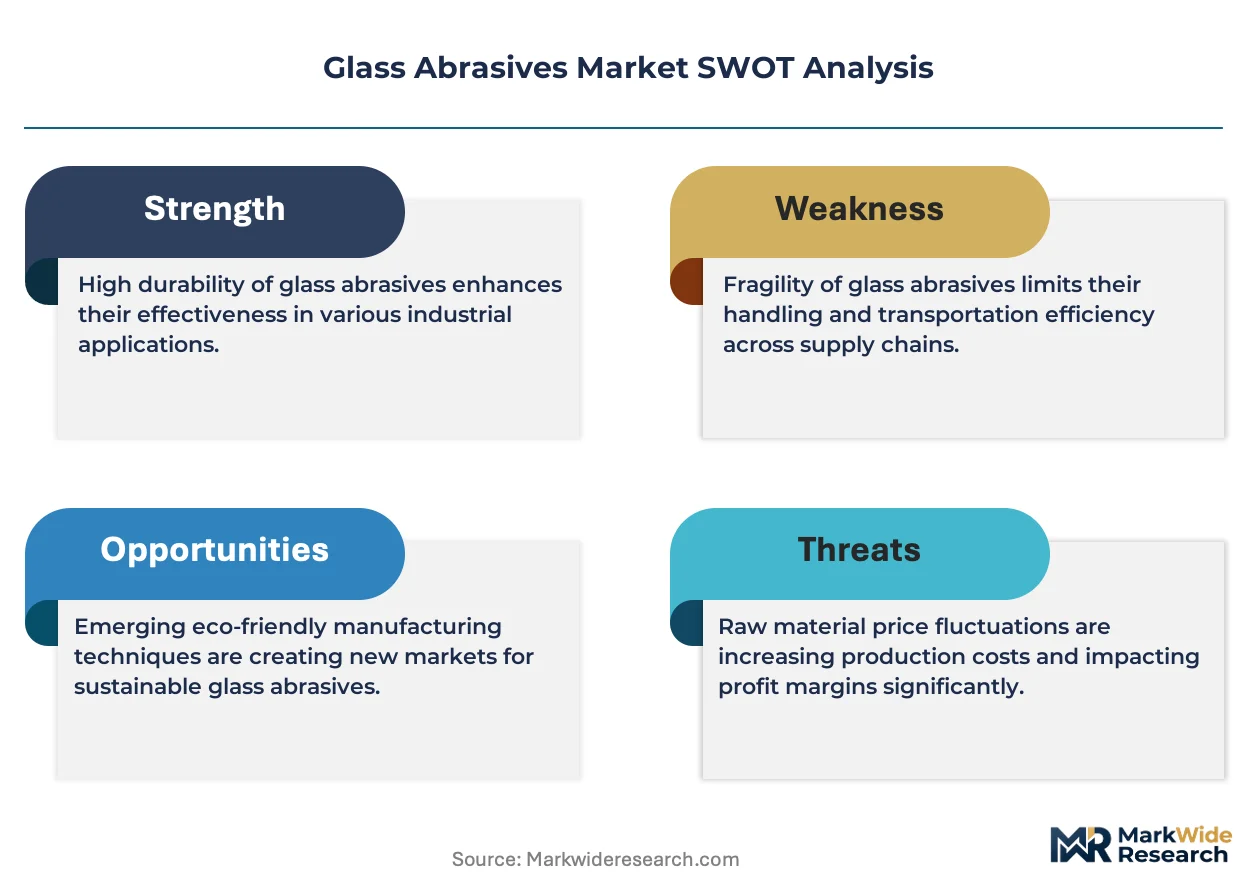
This market operates as a vertical-integration race where furnace-based producers pursue captive control over post-consumer glass feedstock sourcing to secure REACH-compliant cullet supply chains against municipal recycling program competition.
For Market Incumbents: Anticipate aluminum oxide substitution threats in heavy-duty surface preparation by deepening backward integration into verified closed-loop cullet sourcing from German and United States municipal color-sorting programs. Lock in multi-year supply agreements with Gulf Coast shipyard clusters that bundle spent media take-back and recycling services to defend against distributor channel compression. Prioritize X-ray fluorescence batch certification investment to maintain specification authority with French and German aerospace OEMs. For New Entrants and Emerging Players: Enter via ultrafine 325-mesh glass bead production for semiconductor and medical device deburring operations in Japan's Kanto manufacturing corridors, where METI circular-economy scoring creates procurement preference for feedstock-provenance-verified suppliers. Target electronics assemblers specifying precision finishing media for delicate component operations. Pursue partnership routes with domestic recyclers in Germany to access automotive Tier-1 supplier qualification protocols. For Investors and Strategic Acquirers: Exit pathways concentrate in furnace-based production specialists with aerospace certification chains and captive cullet supply agreements. Long-term viability over the analysis window favors suppliers with verified recycled-glass supply chains and XRF batch documentation capabilities. Acquisition target archetype: mid-scale German or United States recyclers with closed-loop municipal sourcing and existing automotive OEM relationships. Watch for OSHA silica enforcement acceleration as inflection indicator for crushed glass substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cullet Sourcing | Captive supply from German municipal color-sorting programs secures REACH-compliant feedstock against competitor access. |
| Aerospace Certification Investment | XRF batch documentation unlocks specification entry with French and German turbine blade finishing supply chains. |
| Coastal Logistics Hub Acquisition | Port-adjacent storage infrastructure in Louisiana and Texas captures Gulf Coast shipyard maintenance contract volumes. |
| Ultrafine Mesh Production Scale-Up | 325-mesh spherical bead capacity addresses semiconductor and medical device deburring demand in Japan's Kanto corridor. |
| Spent Media Take-Back Program | Circular-economy bundling satisfies EPA solid-waste frameworks and sustainability scorecard scoring for end-user procurement. |
Research Approach
Trade databases, ECHA regulatory filings, and SEC 10-K disclosures formed the secondary backbone, supplemented by customs records tracking crushed glass and glass bead import flows into United States, German, and Japanese ports. Primary interviews with furnace operations managers at fused mineral processors, procurement leads at German automotive Tier-1 suppliers, environmental compliance officers at Gulf Coast shipyard contractors, and distribution channel heads at coastal logistics specialists validated secondary findings. Bottom-up and top-down triangulation cross-referenced production capacity estimates against end-use consumption patterns across aerospace, automotive, and marine coatings segments.
Bottom-up modeling built from individual product-grade volume assumptions across crushed glass, glass beads, and microbeads, while top-down verification checked aggregate outputs against trade flow data and industry association estimates. Segmentation dimensions included product morphology, end-use industry, packaging format, and regional production hub clustering. CAGRs were derived from fitted growth curves applied to baseline consumption estimates, incorporating natural gas price volatility scenarios and OSHA enforcement acceleration assumptions as sensitivity inputs.
Revisions become necessary when OSHA silica enforcement timelines accelerate, natural gas price volatility disrupts furnace economics, or REACH authorization procedures expand heavy-metal testing requirements beyond current XRF batch documentation standards. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Super Abrasives Market
Abrasives
Tungsten Carbide Balls Market
Abrasives
Synthetic Abrasives Market
Abrasives
Coated Abrasives Market
Abrasives
Global Ceramic Flap Disc Market
Abrasives
Global Rubber Bonded Abrasive Market
Abrasives
Grinding Wheels Market
Abrasives
Calcined Shale Market
Abrasives
Tungsten Carbide Powder Market
Abrasives
Vitrified Bonded Grinding Wheels Market
Abrasives
Europe Abrasives Market
Abrasives
Fine Sandpaper Market
Abrasives
Metal Abrasives Market
Abrasives
Chemical Deflasher Market
Abrasives
Global Chemical Mechanical Polishing Slurry Market
Abrasives
Abrasive Grains Market