
 Global Cosmetic Pigments Market | 2026-2036
Global Cosmetic Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cosmetic Pigments Market Intelligence
ISO 16128 certification is rotating the competitive landscape by forcing suppliers to demonstrate natural and organic content claims with verifiable data. Merck KGaA leverages its pearlescent technology leadership to sustain premium positioning across European and Asian cosmetic houses. Sun Chemical anchors North American supply through backward integration into effect pigment manufacturing. Sudarshan Chemical Industries Limited competes on cost-efficient organic pigment production from its Indian manufacturing base.
Cosmetic pigments comprise finely ground insoluble particles engineered to deliver color, opacity, shimmer, or fluorescence in beauty formulations, with particle sizes typically ranging from 0.1 to 200 micrometers depending on optical performance requirements. Pearlescent pigments command premium positioning due to their multi-layer titanium dioxide or iron oxide coatings that create interference color effects, while organic pigments face margin compression from rising raw material costs and stricter heavy metal limits. The makeup application segment dominates volume consumption, though skincare represents the fastest-expanding category as tinted moisturizers and color-correcting serums blur traditional category boundaries.
REACH in Europe, FDA color additive regulations in the United States, and China's GB standards collectively determine which pigment chemistries gain market access and which face reformulation mandates. ECHA's ongoing microplastic restriction proposals threaten glitter and certain synthetic mica variants, forcing suppliers to accelerate biodegradable alternatives. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance strategies that satisfy one geography may fail in another, reshaping sourcing decisions and inventory complexity.
Market Dynamics
ISO 16128 certification mandates are compressing supplier margins while rewarding verifiable natural content claims, forcing pigment manufacturers to rebuild analytical capabilities or exit premium tiers entirely.
Growth Catalysts
- Clean beauty procurement:Retailers in Germany and France now require ISO 16128-1 documentation for shelf placement, accelerating certified organic pigment volumes.
- REACH microplastic restrictions:ECHA's pending glitter ban is redirecting R&D budgets toward biodegradable cellulose alternatives with equivalent optical performance.
- Skincare coloration:Tinted sunscreen and color-correcting serum formulations in South Korea are absorbing pearlescent pigments at triple the rate of traditional makeup bases.
Market Restraints
- Titanium dioxide volatility:Feedstock cost swings for anatase and rutile grades are squeezing margins on white and interference pigments.
- Indian supply concentration:Cost-competitive organic pigment production clusters in Maharashtra create single-source vulnerability for mid-tier brands.
- Heavy metal thresholds:FDA's tightened lead and arsenic limits under 21 CFR 73 and 74 are disqualifying legacy iron oxide lots from US import.
Strategic Opportunities
- Brazilian color cosmetics:ANVISA's streamlined cosmetic registration pathways are opening access for effect pigment suppliers previously blocked by documentation barriers.
- Biomimetic structural color:Photonic crystal architectures derived from butterfly-wing nanostructures eliminate dye dependency entirely.
- Direct-to-brand digital sampling:Virtual pigment libraries with spectral data downloads are shortening formulation cycles for indie beauty startups.
Industry Challenges
- ISO 17025 lab accreditation:Third-party verification capacity for natural content claims remains bottlenecked, extending certification timelines by 8-14 months.
- Legacy ERP integration:Batch-level traceability requirements for REACH Article 33 conflict with decades-old manufacturing execution systems at mid-sized European producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cosmetic Pigments Market |
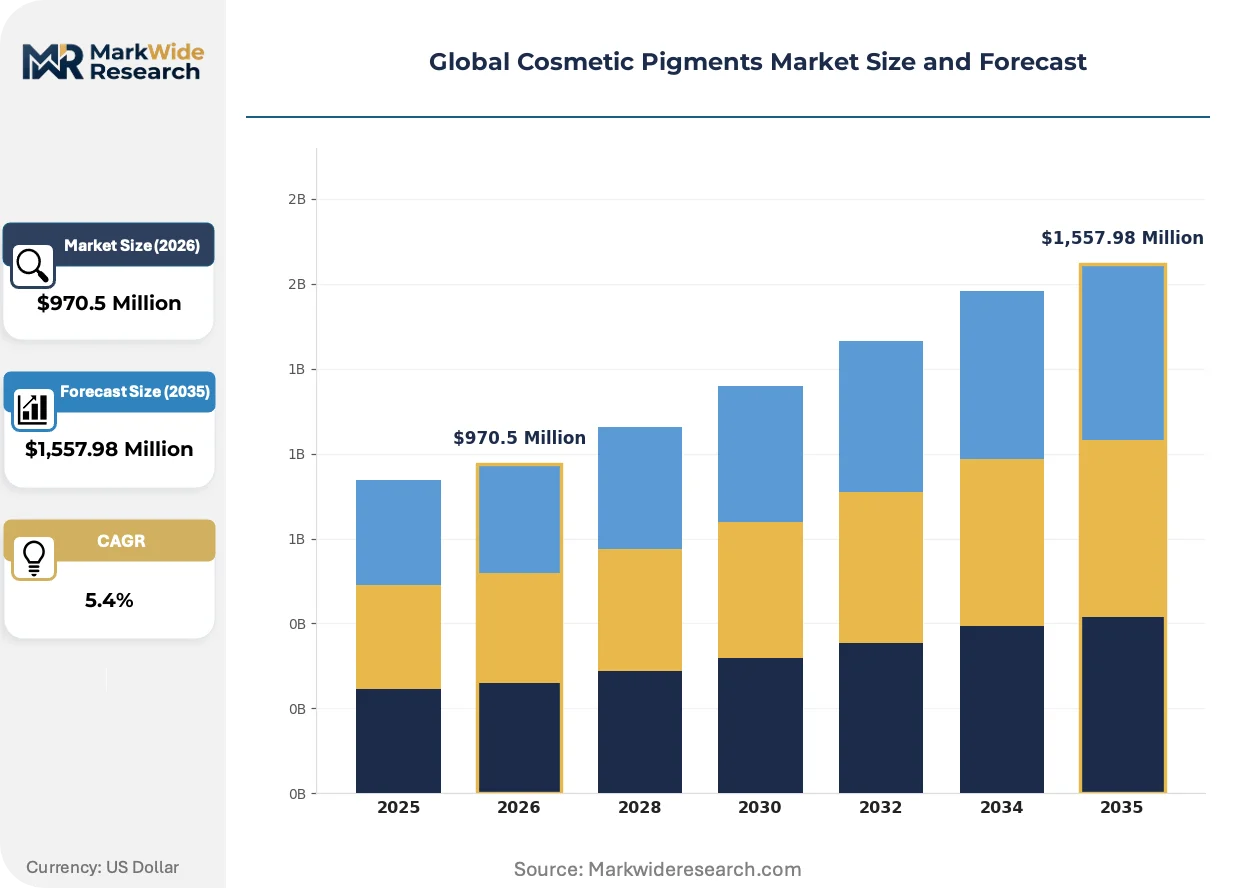
| Market Size in 2026 | $970.5 Million |
| Market Size in 2035 | $1,557.98 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Pigments, Inorganic Pigments, Mica, Pearlescent Pigments, Fluorescent Pigments, Specialty Pigments Application: Makeup, Skincare, Hair Care, Nail Products, Sun Care, Personal Care Products End User: Beauty Salons, Cosmetic Manufacturers, Department Stores, Online Retailers, Pharmacies, Professional Makeup Artists Form: Powder, Liquid, Cream, Gel, Paste, Emulsion |
| Companies Covered | Sun Chemical, Sensient Cosmetic Technologies, Merck KGaA, BASF, Clariant, Sudarshan Chemical Industries Limited, DIC Corporation, Kobo Products, LANXESS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cosmetic Pigments Market Strategic Shifts & Innovations
Biodegradable substrates and regulatory-driven formulation transparency are collapsing traditional supply hierarchies while opening entry points for materials science specialists outside conventional pigment chemistry.
Cellulose-derived glitter from sustainably sourced wood pulp is supplanting conventional PET and PLA microplastics in decorative cosmetic applications. Indie brands in Scandinavia and California are specifying biodegradable alternatives for 100% of new product launches. Merck KGaA and smaller German specialists are capturing premium positioning as conventional Asian glitter manufacturers face ECHA restriction timelines.
REACH microplastic restriction proposals are forcing reformulation of eyeshadow, nail lacquer, and body glitter SKUs across the EU-27. Suppliers with biodegradable alternatives certified by TÜV or equivalent bodies are securing three-year supply commitments from pan-European beauty houses. The restriction timeline compresses most acutely for synthetic mica variants with particle sizes below 5 micrometers.
Clean beauty certification is fragmenting procurement authority between sustainability officers and traditional R&D directors. Sephora Clean and Ulta Conscious Beauty standards now override conventional cost-per-kilo metrics in supplier selection for US prestige brands. The shift concentrates purchasing power with pigment houses maintaining dual ISO 16128 and COSMOS certifications.
Global Cosmetic Pigments Market Segmentation
Cosmetic pigment procurement increasingly stratifies by certification tier and optical performance rather than chemistry alone. Formulators now segment supply bases according to ISO 16128 compliance status, REACH microplastic restrictions, and end-use transparency requirements. This reclassification is compressing legacy supplier margins while elevating specialty houses with verified sustainability credentials.
Product Type:
Pearlescent and interference pigments face the most acute substitution pressure as biodegradable cellulose alternatives achieve optical parity at lower regulatory risk.
- Organic Pigments:Azo and anthraquinone-based colorants deliver high tinctorial strength in lip and eye formulations. Maharashtra-based production clusters supply cost-competitive volumes to mid-tier brands, though tightening heavy metal thresholds under FDA and REACH are disqualifying legacy lots from premium channels.
- Inorganic Pigments:Iron oxides, chromium oxides, and ultramarines provide thermal stability and opacity in foundations and sunscreens. Titanium dioxide feedstock volatility is squeezing margins on white and interference grades, with anatase and rutile cost swings passing through to finished pigment pricing.
- Mica:Naturally occurring potassium aluminum silicate substrates serve as base materials for pearlescent effects.
- Pearlescent Pigments:Multi-layer titanium dioxide or iron oxide coatings on mica or synthetic substrates create interference color effects. South Korean tinted sunscreen and color-correcting serum formulations are absorbing these pigments at triple the rate of traditional makeup bases.
- Fluorescent Pigments:Daylight-visible organic dyes in polymer matrices enable neon and glow effects.
- Specialty Pigments:Photonic crystal architectures and structural colorants eliminate traditional dye dependency entirely.
Inorganic pigments retain volume leadership; specialty pigments hold the steepest expansion curve.
Application:
Cost tier segmentation now separates prestige certification-compliant formulations from mass-market alternatives with divergent purity thresholds.
- Makeup:Color cosmetics including foundation, lipstick, eyeshadow, and blush absorb the majority of pearlescent and organic pigment volumes. ECHA's pending glitter ban is redirecting R&D budgets toward biodegradable cellulose alternatives across eyeshadow and body glitter SKUs.
- Skincare:Tinted moisturizers, color-correcting serums, and tone-up creams are blurring traditional category boundaries. South Korean and Californian indie brands are specifying biodegradable alternatives for all new product launches in this segment.
- Hair Care:Temporary colorants and tinting treatments utilize lower-purity pigment grades.
- Nail Products:Lacquers and gels require solvent-resistant pigment dispersions with fine particle size distribution.
- Sun Care:Tinted mineral sunscreens combine zinc oxide with iron oxide pigments for universal shade matching.
- Personal Care Products:Deodorants, body powders, and oral care items incorporate colorants for aesthetic differentiation.
Makeup commands absolute volume; skincare is climbing the fastest as tinted treatment formats proliferate.
End User:
Customer type determines documentation burden, with cosmetic manufacturers facing the most stringent batch-level traceability requirements under REACH Article 33.
- Beauty Salons:Professional color services require high-strength pigments with rapid development properties.
- Cosmetic Manufacturers:Brand owners and contract manufacturers drive specification authority for ISO 16128 and COSMOS certifications. Third-party verification capacity for natural content claims remains bottlenecked, extending certification timelines by 8-14 months.
- Department Stores:Prestige retail channels prioritize certified clean beauty assortments.
- Online Retailers:Direct-to-consumer brands leverage virtual pigment libraries with spectral data downloads to shorten formulation cycles.
- Pharmacies:Dermocosmetic distribution channels emphasize hypoallergenic and dermatologically tested pigment grades.
- Professional Makeup Artists:Kit-building professionals demand portable, multi-use pigment formats.
Cosmetic manufacturers dominate procurement volume; online retailers are gaining share fastest as indie brand formation accelerates.
Form:
Supply concentration in powder processing creates margin pressure for liquid and emulsion format specialists lacking captive milling capacity.
- Powder:Dry-ground pigments in loose or pressed formats serve color cosmetics and personal care compounding. Legacy ERP integration challenges at mid-sized European producers conflict with batch-level traceability mandates.
- Liquid:Dispersed pigments in solvent or oil vehicles enable direct incorporation into emulsion systems.
- Cream:Pre-dispersed pigment concentrates simplify manufacturing for small-batch formulators.
- Gel:Thixotropic pigment suspensions suit clear cosmetic bases and anhydrous formulations.
- Paste:High-solids dispersions maximize color loading in limited manufacturing steps.
- Emulsion:Water-in-oil or oil-in-water pigment dispersions integrate directly into skincare matrices. Brazilian ANVISA streamlined registration pathways are opening access for effect pigment suppliers previously blocked by documentation barriers.
Powder retains manufacturing dominance; emulsion formats are expanding most quickly as skincare coloration advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH microplastic restrictions and FDA color additive enforcement are fragmenting regional compliance pathways, forcing pigment suppliers to maintain parallel certification portfolios for market access.
United States
Prestige beauty retailers in New York and Los Angeles now mandate ISO 16128 documentation for shelf placement, accelerating certified organic pigment procurement. FDA's tightened lead and arsenic limits under 21 CFR 73 and 74 are disqualifying legacy iron oxide lots from import channels. Sun Chemical anchors North American supply through backward integration into effect pigment manufacturing from its New Jersey operational base.
Germany
ECHA's pending glitter ban is redirecting R&D budgets toward biodegradable cellulose alternatives across eyeshadow and body glitter formulations. Merck KGaA leverages its pearlescent technology leadership to sustain premium positioning across European cosmetic houses from its Darmstadt headquarters. The country's national chemical regulator maintains the strictest microplastic enforcement timeline in the EU-27.
China
Domestic beauty brands in Shanghai and Guangzhou are scaling manufacturing and reducing reliance on foreign pigment supply. GB standards for cosmetic colorants are tightening purity thresholds for imported materials, favoring local certification. The Yangtze River Delta concentration of mid-tier organic pigment producers is absorbing volume previously sourced from Indian competitors.
India
Cost-competitive organic pigment production clusters in Maharashtra supply mid-tier global brands, though rising heavy metal scrutiny is compressing margins. Sudarshan Chemical Industries Limited competes on cost-efficient production from its Mumbai-Pune manufacturing corridor. The country's national standards body is aligning BIS cosmetic pigment specifications with REACH-equivalent thresholds to preserve export access.
South Korea
Tinted sunscreen and color-correcting serum formulations in Seoul are absorbing pearlescent pigments at triple the rate of traditional makeup bases. MFDS cosmetic colorant regulations are accelerating demand for interference-grade titanium dioxide coatings. The Seongnam-Daejeon corridor hosts specialized dispersion facilities serving K-beauty export brands.
Global Cosmetic Pigments Market Key Industry Players
Player mix skews toward diversified chemical conglomerates with captive raw material positions, though mid-sized specialists retain share in certified organic segments. Consolidation pressure concentrates among pearlescent and effect pigment tiers where coating technology barriers exclude new entrants. Three archetypes dominate: multinational pigment houses with backward integration, regional cost-optimized organic producers, and certification-focused specialty suppliers. Capacity expansion and strategic partnerships represent the dominant competitive moves as brands seek dual-sourcing security.
Among Germany-based diversified chemical groups, Merck KGaA and BASF exemplify the multinational archetype with broad technology portfolios spanning pharmaceutical and cosmetic applications. Sun Chemical anchors the North American supply structure as a representative of regional manufacturing concentration with integrated dispersion capabilities. Sudarshan Chemical Industries Limited occupies the cost-optimized specialist position among Maharashtra-based producers serving volume-tier cosmetic brands.
| Leading Market Players |
|---|
| Sun Chemical |
| Sensient Cosmetic Technologies |
| Merck KGaA |
| BASF |
| Clariant |
| Sudarshan Chemical Industries Limited |
| DIC Corporation |
| Kobo Products |
| LANXESS |
| Others |
Cost & Logistics Intelligence
ISO 16128 certification gates both supplier qualification and price differentiation simultaneously, compressing uncertified producers into commodity tiers while elevating verified organic pigment houses to premium positioning. REACH microplastic restrictions and FDA heavy metal enforcement are amplifying this bifurcation, as compliance investments become non-negotiable cost components passed through to brand customers.
Pricing Analysis
Cost-plus contracts with titanium dioxide indexation dominate long-term supply agreements between pigment houses and cosmetic manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 16128-COSMOS dual-certified suppliers from single-certified and uncertified competitors. Pricing pressure stems from anatase and rutile feedstock volatility squeezing margins on white and interference grades. Mass-market brands in India and Southeast Asia exhibit highest price sensitivity, while prestige European and North American houses prioritize certification over unit cost.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints are elevating inbound logistics costs for Indian and Chinese pigment exports to European cosmetic houses. Supply concentrates in Maharashtra, the Yangtze River Delta, and Germany's Darmstadt-Rhein corridor, with raw material dependencies spanning titanium dioxide feedstocks, mica substrates, and cellulose derivatives for biodegradable alternatives. Single-source vulnerability clusters in Indian organic pigment production create disruption risk for mid-tier brands. Distribution runs through direct mill relationships with cosmetic manufacturers, bypassing traditional chemical distributor networks for certified grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cosmetic pigments market is recovering from regulatory compression cyclicality, with ECHA's microplastic restriction timeline and FDA enforcement waves creating pent-up demand for compliant alternatives.
For Market Incumbents: Shield premium positioning by deepening captive titanium dioxide coating capabilities and accelerating TÜV-certified biodegradable cellulose substrate production. Merck KGaA and Sun Chemical demonstrate how backward integration into effect pigment manufacturing defends margin structure against Indian cost competitors. ISO 17025 lab accreditation investments compress certification timelines for brand customers, locking in three-year supply commitments. For New Entrants and Emerging Players: Lead with biomimetic structural color platforms targeting South Korean skincare formulators seeking dye-free alternatives. Brazilian ANVISA's streamlined registration pathways offer the most penetrable geography for effect pigment suppliers previously blocked by documentation barriers. Direct-to-brand digital sampling with spectral data downloads bypasses incumbent distributor relationships and accelerates indie beauty startup acquisition. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underperforming cosmetic pigment divisions lacking ISO 16128 certification infrastructure. Long-term viability centers on dual-certified specialty suppliers with dispersion capabilities in high-growth skincare coloration. Watch ECHA's synthetic mica restriction implementation timeline as inflection indicator for biodegradable alternative demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Dioxide Coating | Sun Chemical's New Jersey captive production anchors North American supply security against import volatility. |
| Biodegradable Cellulose Substrate Certification | TÜV-certified alternatives secure three-year supply commitments from pan-European beauty houses facing ECHA glitter bans. |
| ISO 17025 Lab Accreditation Investment | Third-party verification capacity bottlenecks extend certification timelines by 8-14 months, creating first-mover advantage. |
| Direct-to-Brand Digital Sampling Platform | Virtual pigment libraries with spectral data downloads shorten formulation cycles for California and Scandinavian indie startups. |
| Joint Venture in Yangtze River Delta Dispersion | Chinese domestic brands scaling manufacturing reduce foreign pigment reliance, favoring local certification-aligned partnerships. |
Research Approach
A standing panel of cosmetic formulators, regulatory affairs directors at pigment houses, procurement leads at prestige beauty brands, and sustainability officers at clean beauty retailers provided ongoing calibration across the study period. Primary interviews combined with secondary validation from ECHA restriction proposal documentation, FDA 21 CFR color additive filings, and customs trade data for titanium dioxide and mica substrate flows. Bottom-up volume modeling across product types and applications triangulated against top-down value estimates from disclosed capacity expansions and certification investment patterns.
Consistency checks validated volume and value outputs against external benchmarks including pearlescent pigment absorption rates in South Korean skincare formulations and biodegradable alternative penetration in Scandinavian indie brand launches. Segmentation dimensions spanned product chemistry, application category, certification tier, and regional regulatory cluster. CAGRs derived from regression analysis of historical price-volume relationships and projected compliance-driven substitution elasticities. Industry-specific inputs included ECHA microplastic restriction timeline scenarios and MFDS cosmetic colorant regulation evolution patterns.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity or accelerated biodegradable substrate optical performance improvement would require recalibration. Forecasts reflect assumptions regarding REACH implementation timelines, FDA heavy metal limit adherence, and brand procurement authority shifts toward sustainability officers. Recalibration cycles align with material shifts in ECHA restriction finalization, ISO 16128 revision schedules, and titanium dioxide feedstock contract renegotiation windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Global White Inorganic Pigments Market
Dyes and Pigments
Middle East and Africa Hair Colorants Market
Dyes and Pigments
Riboflavin Pigment Market
Dyes and Pigments
Acid Orange Market
Dyes and Pigments
Copper Chromite Black Pigment Market
Dyes and Pigments
Petroleum-Fuel Dyes and Markers Market
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Indigo Carmine Market
Dyes and Pigments
Reactive Dyes Market
Dyes and Pigments
Titanium Dioxide Color Market
Dyes and Pigments
Acrylic Colors Market
Dyes and Pigments
Algal Pigments Market
Dyes and Pigments
Dyes and Pigments Market
Dyes and Pigments
Color Concentrates Market
Dyes and Pigments
Lithol Rubine BK Market
Dyes and Pigments
Plastic Pigments Market