
 Whitening Ingredients Market | 2026-2036
Whitening Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Whitening Ingredients Market Analytics
Professional dermatology clinics are redrawing demand patterns in the whitening ingredients landscape as consumers shift from over-the-counter self-treatment to supervised clinical protocols. L'Oréal S.A. leverages its dermatological brand portfolio to anchor professional channel penetration across Europe. Shiseido Company, Limited sustains R&D intensity in tyrosinase-inhibitor derivatives through its Tokyo-based innovation hub. Beiersdorf AG differentiates via pharmacy-centric distribution controls in German-speaking markets.
Whitening ingredients comprise bioactive compounds that modulate melanogenesis through enzymatic inhibition, antioxidant pathways, or melanin transfer disruption, typically formulated at concentrations between 2% and 4% for cosmetic-grade applications. Niacinamide occupies the largest volume position due to its tolerability profile and multifunctional skin benefits, while kojic acid represents the fastest-expanding structural category driven by natural-origin positioning. Serum formulations command premium margin pools owing to higher actives loading and per-unit pricing power compared to cream and lotion bases.
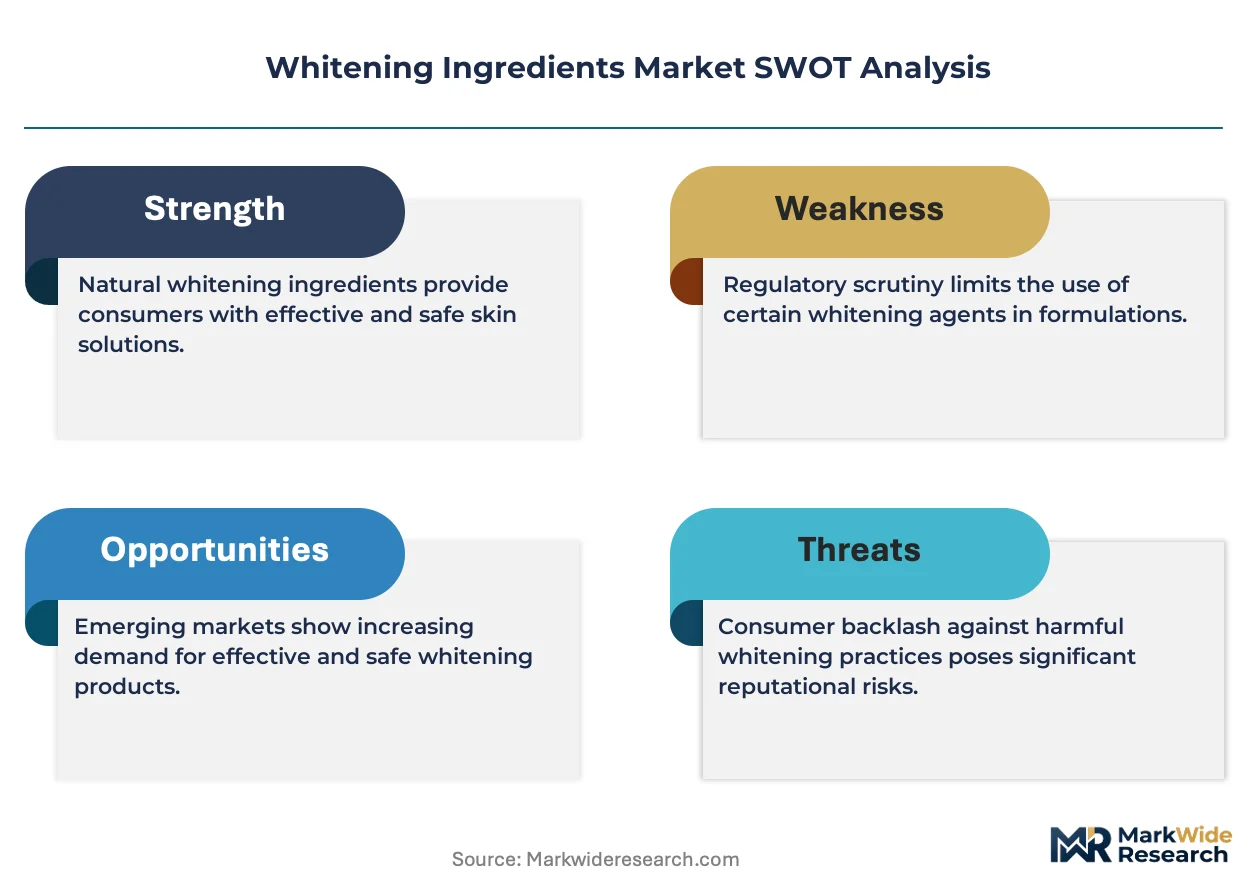
The EU's REACH framework and the FDA's over-the-counter monograph system impose divergent concentration ceilings and safety testing requirements that fragment formulation strategies across jurisdictions. India's CDSCO and South Korea's MFDS maintain distinct approval pathways for quasi-drug whitening claims that shape regional product registration timelines. Stakeholders must monitor regulatory divergence between cosmetic and pharmaceutical classification thresholds as the primary determinant of market access investments.
Market Dynamics
Professional dermatology clinics are consolidating purchasing power as consumers abandon self-directed OTC protocols for supervised clinical treatments, compressing traditional retail channel margins while expanding institutional procurement volumes.
Growth Catalysts
- Seoul-Incheon beauty cluster concentration:South Korea's quasi-drug approval pathway accelerates novel tyrosinase inhibitor commercialization, drawing formulation R&D investment from multinational suppliers.
- REACH regulatory arbitrage:EU concentration limits on hydroquinone create demand migration toward niacinamide and kojic acid alternatives, expanding compliant ingredient portfolios.
- Dermatology clinic channel expansion:Professional treatment protocols institutionalize recurring serum purchases at higher actives loading than consumer retail equivalents.
Market Restraints
- Raw material supply concentration:Kojic acid fermentation feedstock dependence on Chinese citric acid suppliers exposes formulators to input volatility and tariff friction.
- Regulatory fragmentation:Divergent cosmetic-pharmaceutical classification thresholds between FDA OTC monographs and EU REACH force redundant safety dossier preparation.
- Technical efficacy ceiling:Cosmetic-grade concentration limits (2-4%) constrain melanogenesis inhibition compared to prescription-grade alternatives, capping per-protocol outcomes.
Strategic Opportunities
- Indian quasi-drug pathway:CDSCO's distinct whitening claim registration timeline offers first-mover positioning ahead of saturated Northeast Asian markets.
- Biotechnology convergence:Enzymatic synthesis of arbutin derivatives combined with precision fermentation is reducing production costs versus extraction-based sourcing.
- Telemedicine channel integration:Virtual dermatology platforms enable direct-to-patient prescription-strength protocol delivery, bypassing traditional retail distribution.
Industry Challenges
- Formulation stability expertise gap:Tyrosinase inhibitor degradation kinetics require specialized chemist talent scarce outside Japanese and Korean cosmetic science programs.
- Multi-jurisdiction compliance timelines:Parallel MFDS, CDSCO, and FDA filing requirements extend product launch cycles by 18-24 months.
- Clinical substantiation costs:Per-market safety and efficacy dossier preparation consumes 12-15% of R&D budgets for mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whitening Ingredients Market |
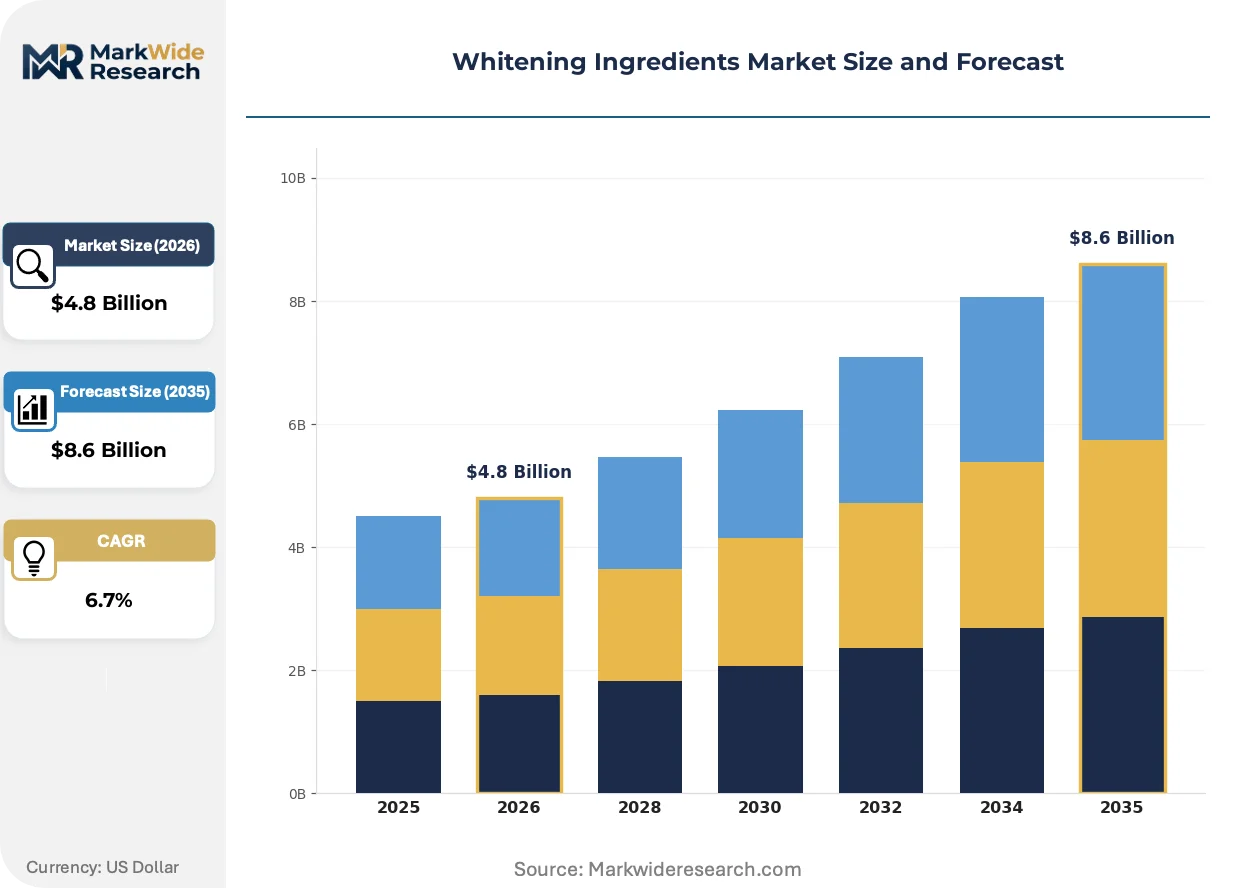
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydroquinone, Arbutin, Kojic Acid, Niacinamide Formulation: Serum, Cream, Gel, Lotion End User: Individuals, Dermatologists, Salons, Clinics Application: Skin Whitening, Age Spot Treatment, Melasma Management, Overall Skin Tone Evenness |
| Companies Covered | Shiseido Company, Limited, Beiersdorf AG, L'Oréal S.A., LG Household & Health Care Ltd., Amorepacific Corporation, Procter & Gamble, Estée Lauder Companies Inc., Sabinsa Corporation, Unilever PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whitening Ingredients Market Evolving Landscape
Liposomal and nano-encapsulation delivery systems are compressing the efficacy gap between cosmetic-grade and prescription-strength formulations, while regulatory pressure on legacy actives accelerates biotechnology-derived alternatives.
Encapsulated niacinamide and kojic acid complexes are miniaturizing active particle size to sub-100 nanometer ranges, enabling deeper epidermal penetration without irritation thresholds. Dermatology clinics in Seoul and Tokyo are adopting these complexes at twice the rate of general cosmetic manufacturers. The technology is miniaturizing the distinction between professional and consumer-grade performance expectations.
EU REACH authorization requirements for novel cosmetic actives are extending safety data obligations to include endocrine disruption screening, forcing reformulation of legacy hydroquinone alternatives. The industrial consequence is a 30% expansion in pre-market toxicology spending for European-bound products. Serum manufacturers targeting German pharmacy channels are responding with accelerated arbutin and tranexamic acid substitution programs.
Subscription-based replenishment models are displacing episodic retail purchasing among high-frequency users, locking in 90-day serum cycles through auto-ship contracts. Direct-to-consumer platforms and clinic-affiliated e-commerce portals are capturing this shift, while traditional department store counters lose replenishment velocity. South Korean beauty platforms and US telemedicine-integrated pharmacies exhibit the highest subscription penetration rates.
Whitening Ingredients Market Segmentation
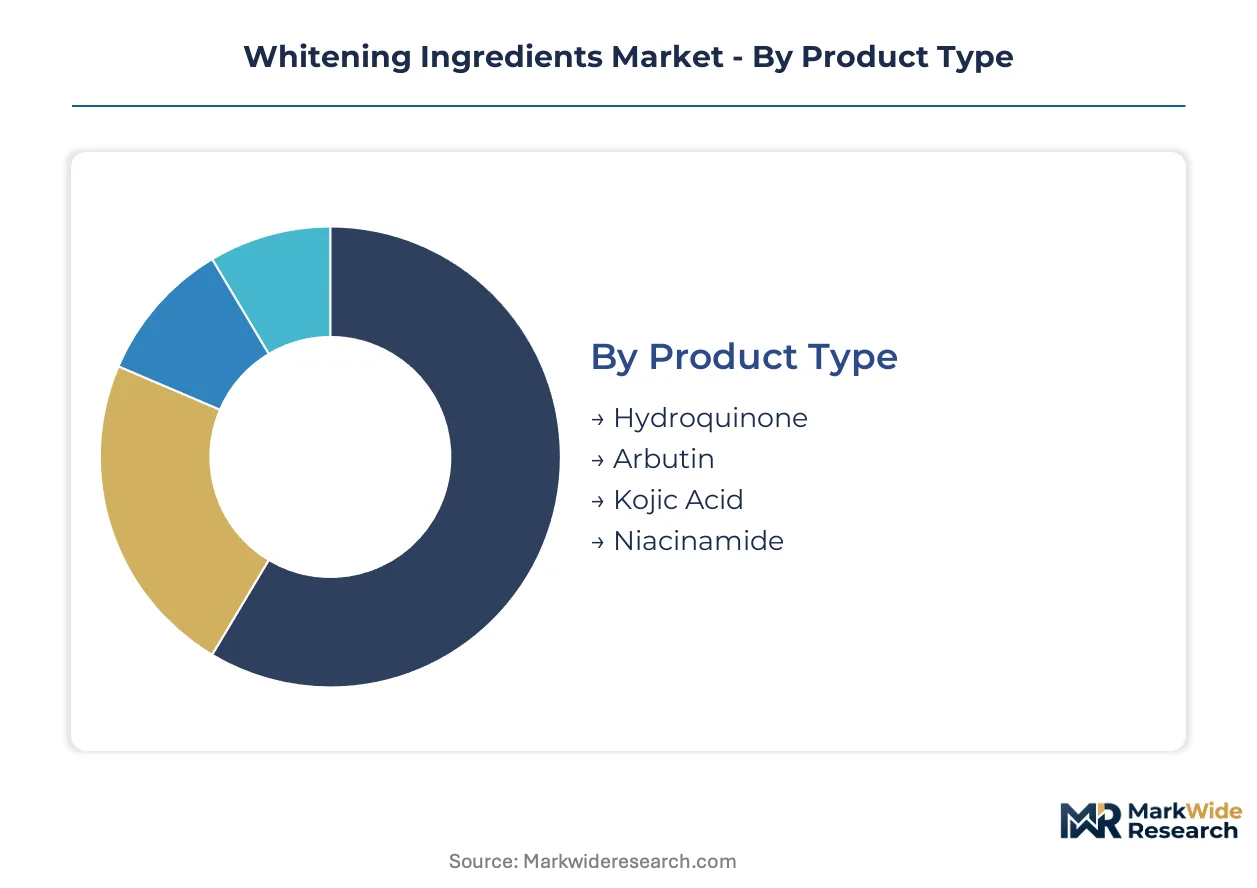
Whitening ingredient manufacturers navigate divergent regulatory ceilings across jurisdictions that dictate permissible concentrations and claim substantiation requirements. Formulation portfolios must align with institutional procurement standards while maintaining retail accessibility, creating tiered product architectures.
Product Type:
REACH concentration limits and FDA OTC monograph thresholds fragment active ingredient deployment strategies across export markets.
- Hydroquinone:Synthetic phenolic compound functioning as potent tyrosinase inhibitor at prescription-grade concentrations. EU REACH bans cosmetic applications above trace limits, compressing demand toward Middle Eastern and select Asian markets where pharmaceutical classification permits supervised deployment.
- Niacinamide:Vitamin B3 derivative inhibiting melanosome transfer with established tolerability at 2-5% cosmetic concentrations. MFDS quasi-drug approvals in South Korea and pharmacy channel dominance in German-speaking markets anchor volume concentration.
- Kojic Acid:Fungal fermentation metabolite with milder inhibition kinetics favored in natural-positioned formulations.
- Arbutin:Glycosylated hydroquinone precursor offering regulatory-compliant alternative with slower melanogenesis suppression kinetics.
Established volume favors niacinamide; emerging adoption favors kojic acid.
Formulation:
Actives loading density and per-unit pricing power stratify margin capture across delivery vehicles.
- Serum:Low-viscosity aqueous or hydroalcoholic matrices enabling 10-20% actives concentration with minimal occlusive interference. Seoul-Incheon dermatology clinics and Tokyo aesthetic medicine chains specify serum protocols at 2.3x retail unit economics versus cream bases.
- Cream:Emulsion-based vehicles incorporating occlusive agents for barrier-compromised skin protocols.
- Gel:Hydrophilic polymer matrices favored in humid climates and oily skin indications.
- Lotion:Lower viscosity emulsions targeting body surface area applications with cost-optimized actives loading.
Premium positioning clusters in serum formulations; volume penetration concentrates in lotion applications.
End User:
Channel migration from self-directed retail to supervised clinical protocols reshapes purchasing authority and specification requirements.
- Dermatologists:Licensed practitioners prescribing compounded or pharmaceutical-grade protocols with documented melanogenesis inhibition outcomes. South Korea's MFDS quasi-drug pathway and India's CDSCO registration framework accelerate professional-grade product availability.
- Clinics:Institutional procurement entities consolidating recurring serum purchases through group purchasing organizations.
- Individuals:Self-directed consumers selecting OTC cosmetic-grade formulations through retail and e-commerce channels.
- Salons:Aesthetic service providers incorporating whitening protocols into treatment menus with lower regulatory scrutiny than medical settings.
Institutional procurement favors dermatologists; channel expansion favors clinics.
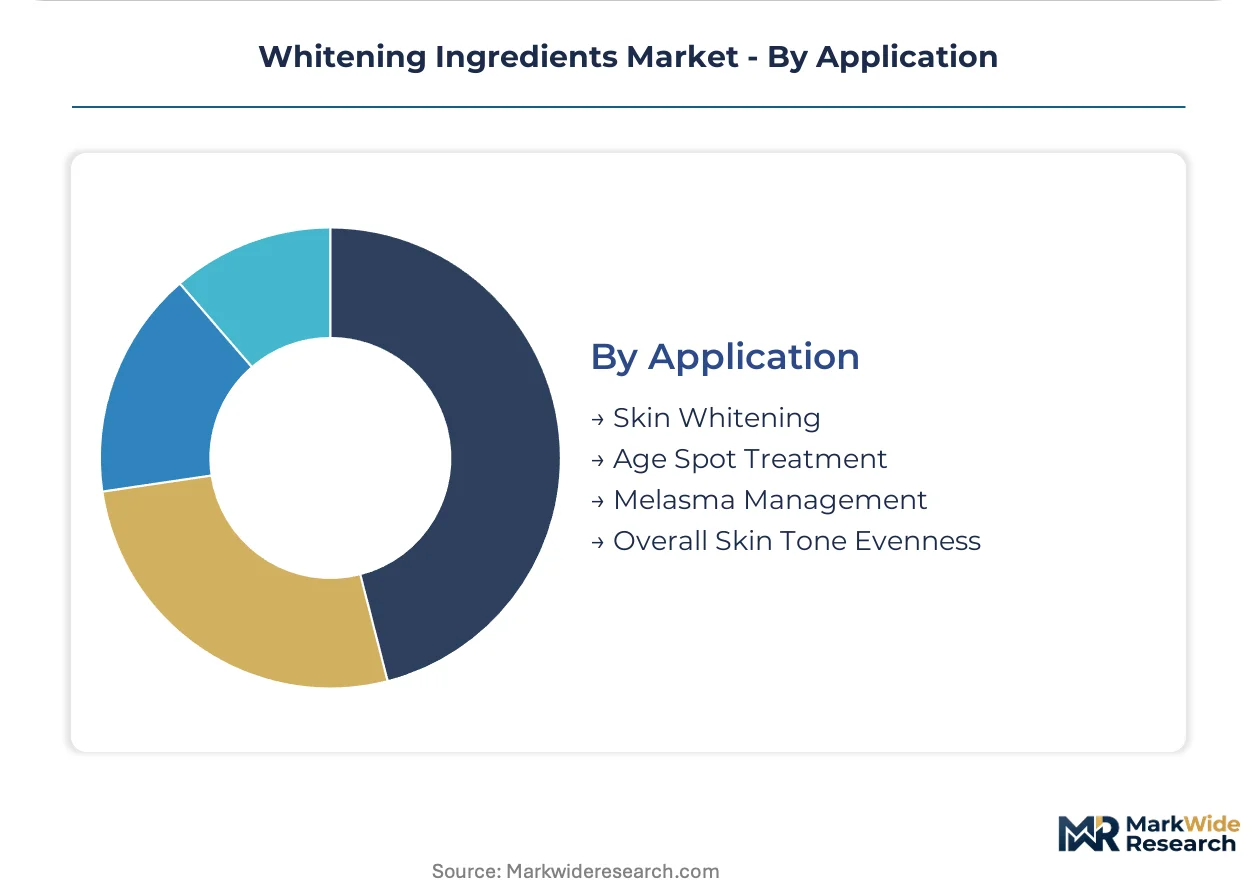
Application:
Clinical indication specificity determines regulatory classification thresholds and substantiation burden across jurisdictions.
- Melasma Management:Hormonally-influenced hyperpigmentation requiring combination protocols with prescription-grade actives. CDSCO's distinct whitening claim pathway in India and MFDS quasi-drug standards in South Korea shape registration strategies for indication-specific formulations.
- Skin Whitening:Generalized melanogenesis reduction claims subject to strictest cosmetic-pharmaceutical boundary enforcement.
- Age Spot Treatment:Solar lentigo targeting with localized application protocols.
- Overall Skin Tone Evenness:Broad cosmetic claims minimizing regulatory classification risk but requiring robust safety dossiers under EU REACH endocrine disruption screening expansions.
Regulatory scrutiny concentrates in skin whitening; clinical validation requirements favor melasma management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea exports active ingredient concentrates to European formulators navigating REACH hydroquinone restrictions. Chinese citric acid fermentation feedstock supplies Japanese and Korean kojic acid manufacturers. Indian CDSCO quasi-drug registrations attract mid-tier suppliers seeking faster approval timelines than saturated Northeast Asian markets.
South Korea
Seoul-Incheon dermatology clinics specify 10-20% actives serum protocols at premium unit economics. MFDS quasi-drug pathway accelerates novel tyrosinase inhibitor commercialization versus pharmaceutical registration timelines. Pangyo Techno Valley houses formulation R&D centers serving both domestic clinic chains and export markets.
Japan
Tokyo-based aesthetic medicine chains adopt nano-encapsulated niacinamide complexes at twice the rate of general cosmetic manufacturers. PMDA maintains distinct cosmetic-pharmaceutical boundaries that shape concentration ceilings for retail versus professional distribution. Osaka-Kobe industrial corridor concentrates precision fermentation capacity for biotechnology-derived arbutin synthesis.
Germany
German-speaking pharmacy channels enforce pharmacy-centric distribution controls that filter non-compliant whitening claims. ECHA REACH authorization extends endocrine disruption screening to novel cosmetic actives, expanding toxicology spending for European-bound products. Düsseldorf-Cologne region anchors Beiersdorf AG's pharmacy channel infrastructure.
United States
Telemedicine-integrated dermatology platforms enable direct-to-patient prescription-strength protocol delivery. FDA OTC monograph system imposes concentration thresholds divergent from EU REACH, fragmenting formulation strategies. California-based direct-to-consumer platforms exhibit highest subscription-based serum replenishment penetration rates.
India
Maharashtra and Gujarat manufacturing zones supply domestic quasi-drug formulators while exporting intermediate actives. CDSCO's distinct whitening claim registration timeline offers first-mover positioning ahead of saturated Northeast Asian markets. Mumbai-Pune corridor concentrates mid-tier supplier R&D facilities targeting professional clinic procurement.
Whitening Ingredients Market Competitive Landscape
Player mix skews toward multinational dermatological brand portfolios with regional specialist challengers. Consolidation concentrates around three to five integrated personal care conglomerates controlling professional channel access. Strategic archetypes include dermatology clinic-focused prescription-grade suppliers, pharmacy-centric quasi-drug formulators, and direct-to-consumer serum specialists. Competitive moves center on biotechnology licensing for fermentation-derived actives and subscription platform integration for recurring revenue capture.
Within the integrated multinational tier, L'Oréal S.A., Shiseido Company, Limited, and Beiersdorf AG occupy positions exemplifying divergent regional channel strategies. L'Oréal S.A. anchors professional channel penetration across European dermatology clinic networks. Shiseido Company, Limited represents sustained R&D intensity in tyrosinase-inhibitor derivatives through Tokyo-based innovation infrastructure. Beiersdorf AG exemplifies pharmacy-centric distribution controls in German-speaking markets.
| Leading Market Players |
|---|
| Shiseido Company, Limited |
| Beiersdorf AG |
| L'Oréal S.A. |
| LG Household & Health Care Ltd. |
| Amorepacific Corporation |
| Procter & Gamble |
| Estée Lauder Companies Inc. |
| Sabinsa Corporation |
| Unilever PLC |
| Others |
Value Network & Pricing Analysis
EU REACH hydroquinone concentration ceilings gate both supplier qualification and price differentiation simultaneously, compressing legacy active margins while expanding compliant-alternative premiums across German pharmacy channels and Seoul dermatology procurement networks.
Pricing Analysis
Prior-generation hydroquinone formulations, current-generation niacinamide complexes, and next-generation nano-encapsulated kojic acid derivatives stratify across three pricing tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under MFDS quasi-drug pathways and volume scale in institutional procurement. Cost compression in standard-tier arbutin sourcing is intensifying because Chinese citric acid feedstock volatility feeds through fermentation economics. Individual retail buyers exhibit highest price sensitivity; Seoul-Incheon dermatology clinics demonstrate lowest sensitivity due to protocol-driven recurring purchase mandates.
Supply Chain Analysis
Port congestion on Shanghai-Rotterdam lanes and container availability constraints on intra-Asia routes elevate inbound logistics costs for European-bound active concentrates. Supply concentrates in China for citric acid fermentation feedstock, South Korea for MFDS-certified quasi-drug formulations, and Japan for precision fermentation-derived arbutin. Kojic acid production draws from Aspergillus oryzae cultures, phosphoric acid pH buffers, and activated carbon purification media. Single-source vulnerability concentrates in Chinese citric acid suppliers exposing Korean and Japanese formulators to tariff friction. Distribution runs through pharmacy-centric wholesale networks in German-speaking markets and direct-to-clinic procurement platforms in South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based serum replenishment services attach recurring revenue layers expanding faster than hardware-equivalent OTC retail sales, converting episodic purchasers into locked 90-day protocol commitments.
For Market Incumbents: Secure backward integration into precision fermentation capacity for arbutin and kojic acid derivatives to insulate margin structures from Chinese citric acid volatility. Defend channel position by deepening pharmacy-centric distribution controls in German-speaking markets against direct-to-consumer platform encroachment. For New Entrants and Emerging Players: Anchor in India's CDSCO quasi-drug registration pathway where approval timelines compress versus saturated Northeast Asian markets. Target mid-tier dermatology clinic procurement in Mumbai-Pune corridor with MFDS-equivalent quality positioning at 15-20% cost advantage. Deploy telemedicine-integrated prescription protocol delivery as primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational personal care conglomerates divesting non-core whitening ingredient divisions under portfolio rationalization pressures. Long-term viability hinges on biotechnology licensing positions and subscription platform infrastructure rather than commodity active sourcing. Monitor MFDS novel tyrosinase inhibitor approval velocity as inflection indicator for professional channel expansion potential.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Licensing Agreement | Precision fermentation partnerships with Osaka-Kobe synthetic biology clusters reduce arbutin production costs versus extraction. |
| Subscription Platform Integration | Auto-ship 90-day serum cycles through Seoul-based beauty platforms lock recurring revenue and displace retail counter velocity. |
| Quasi-Drug Registration Pathway | CDSCO and MFDS approval investments accelerate professional-grade product availability ahead of pharmaceutical timelines. |
| Nano-Encapsulation Capacity Expansion | Sub-100 nanometer particle production lines enable premium serum positioning at 2.3x cream base unit economics. |
| Telemedicine Channel Partnership | Virtual dermatology platform alliances bypass traditional retail distribution for direct-to-patient prescription protocol delivery. |
Research Methodology
Operator-level perspectives from dermatology clinic procurement managers, pharmaceutical regulatory affairs leads, cosmetic formulation R&D directors, and pharmacy channel wholesale buyers anchored the qualitative base. Primary interviews combined with secondary validation from MFDS quasi-drug registration databases, ECHA REACH authorization filings, CDSCO approval records, and customs trade data for citric acid and kojic acid concentrates. Bottom-up active ingredient volume estimates and top-down formulation value projections underwent triangulation across modeling approaches.
Sensitivity analysis tested forecast outputs against regulatory approval timeline variations and raw material price volatility assumptions across the projection horizon. Segmentation dimensions modeled include active ingredient type, formulation vehicle, end-user channel, application indication, and regional regulatory cluster. CAGRs derived from volume trajectory analysis and value-per-unit progression through the forecast period. Industry-specific inputs incorporated MFDS quasi-drug commercialization rates and REACH endocrine disruption screening compliance costs.
Decision-makers should treat outputs as directional under stable regulatory classification thresholds and intact Chinese citric acid supply assumptions; material deviation would warrant model refresh. Specific risk factors include REACH authorization expansions to novel actives, MFDS pathway delays, and tariff escalation on fermentation feedstock imports. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Phosphotungstic Acid Market
Chemicals
Global Photoresist Chemicals Market
Chemicals
Formalin Vials Market
Chemicals
Fluorine Derivatives Market
Chemicals
Vinyl Acetate Market
Chemicals
Quaternium-15 Market
Chemicals
Isopropyl Alcohol (IPA) Market
Chemicals
HATU Market
Chemicals
Para Cresol Market
Chemicals
Sodium Tripolyphosphate (STPP) Market
Chemicals
Silicone Textile Softeners Market
Chemicals
Carbon Tetrabromide Market
Chemicals
Imaging Chemicals and Materials Market
Chemicals
Polyphosphoric Acid (PPA) Market
Chemicals
Isopropanolamine Market
Chemicals
Global Diacetone Alcohol Market