
 India General Surgical Devices Market | 2026-2036
India General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India General Surgical Devices Market Foresight
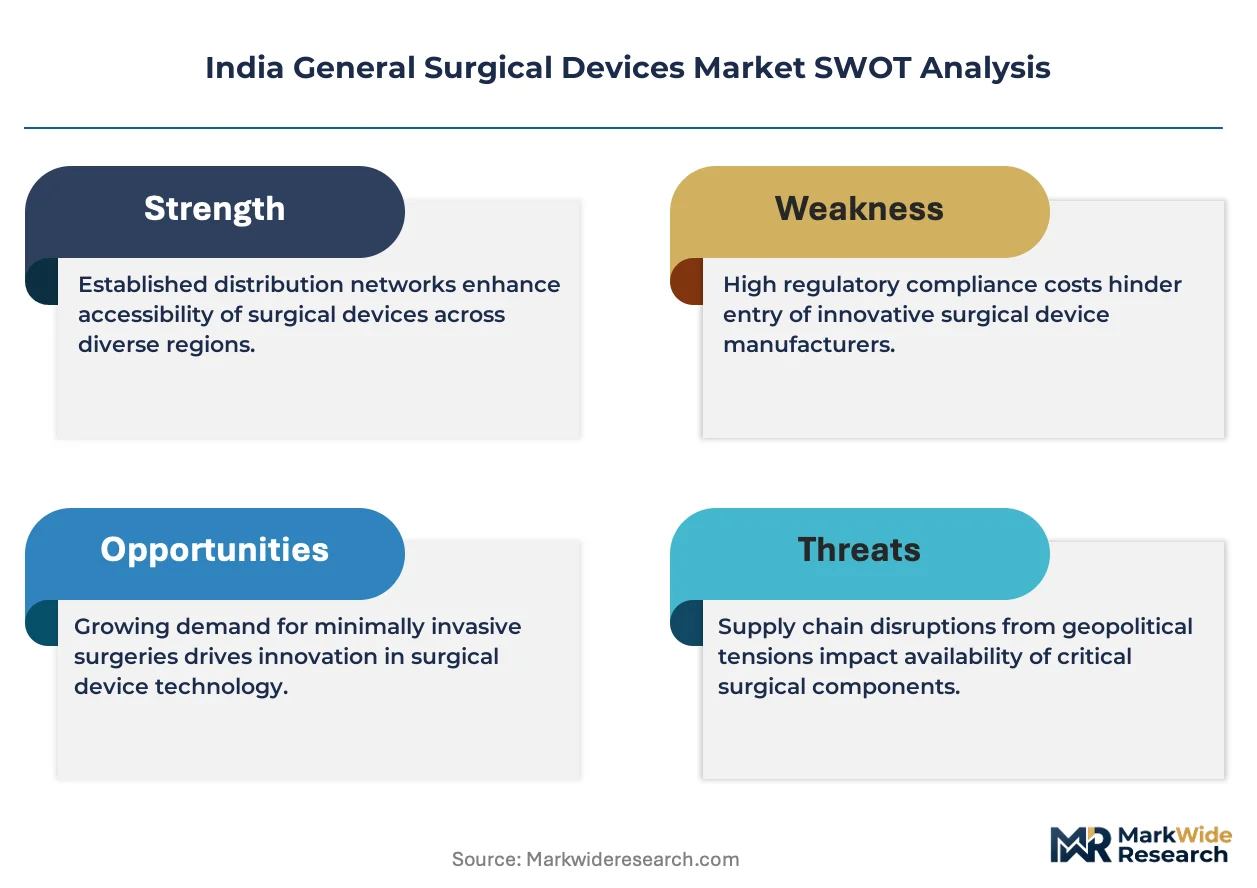
The Medical Devices Rules is rebalancing the cost-of-entry calculus for domestic manufacturers by mandating stricter quality management systems and post-market surveillance. B. Braun SE leverages its established sterilization infrastructure to sustain premium positioning across tertiary care networks. Medtronic plc anchors its competitive stance through deep distribution into government procurement channels, while Smith & Nephew plc specializes in orthopedic surgical instruments for the expanding joint replacement segment.
General surgical devices encompass hand-held instruments, cutting and dissecting tools, grasping and holding instruments, and accessory equipment manufactured from medical-grade stainless steel, titanium alloys, or polymer composites to enable tissue manipulation, hemostasis, and wound closure during operative procedures. Electrosurgical devices and laparoscopic equipment now command disproportionate margin pools as hospitals prioritize minimally invasive surgical capacity over traditional open-procedure toolkits. Among end users, ambulatory surgical centers represent the fastest-growing procurement channel as same-day discharge protocols expand across cardiology and orthopedic day-care units.
CDSCO registration requirements, BIS certification for metallic implants, and the phased implementation of the Drugs and Cosmetics Act amendments collectively shape product standards and market access timelines for both importers and domestic producers. The Quality Council of India's NABH accreditation standards for hospitals further filter device procurement toward ISO-certified suppliers. Stakeholders must monitor how the PLI scheme for medical devices redirects capital toward domestic manufacturing of high-value surgical consumables.
Market Dynamics
The CDSCO's phased tightening of medical device quality norms is compressing market access timelines and forcing domestic manufacturers to absorb sterilization infrastructure investments that multinational competitors already command.
Growth Catalysts
- PLI scheme for medical devices:Production-linked incentives redirect domestic capital toward high-value surgical consumables, narrowing cost gaps with imported alternatives.
- Tier-II and Tier-III city hospital expansion:Surgical capacity additions in secondary urban centers generate fresh procurement volumes outside saturated metropolitan markets.
- Electrosurgical platforms:Hospitals prioritize minimally invasive surgical capacity, elevating margin pools for energy-based cutting and coagulation systems over traditional hand-held instruments.
Market Restraints
- Medical-grade stainless steel price volatility:Input cost swings compress margins for instrument manufacturers locked into government tender pricing cycles.
- CDSCO registration timelines:Extended product approval durations delay market entry for novel devices, favoring incumbents with established dossier libraries.
- Reusable instrument substitution:Cost pressures in public health systems sustain demand for sterilizable metal tools, limiting single-use disposable penetration.
Strategic Opportunities
- NABH-accredited hospital networks:Quality council standards filter procurement toward ISO-certified suppliers, creating tiered access advantages for compliant domestic manufacturers.
- Ambulatory surgical centers:Same-day discharge protocol expansion across cardiology and orthopedic day-care units opens specialized instrument demand.
- Joint replacement segment specialization:Orthopedic surgical instrument customization for rising arthroplasty volumes offers premium positioning outside commodity competition.
Industry Challenges
- Material traceability systems:CDSCO-mandated lot tracking requires ERP upgrades that strain mid-tier manufacturer working capital.
- Biocompatibility certification delays:BIS metallic implant standards demand extended testing protocols that bottleneck product launch schedules.
- Sterilization protocol reconfiguration:Legacy ethylene oxide infrastructure faces replacement pressure from emerging low-temperature hydrogen peroxide systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India General Surgical Devices Market |
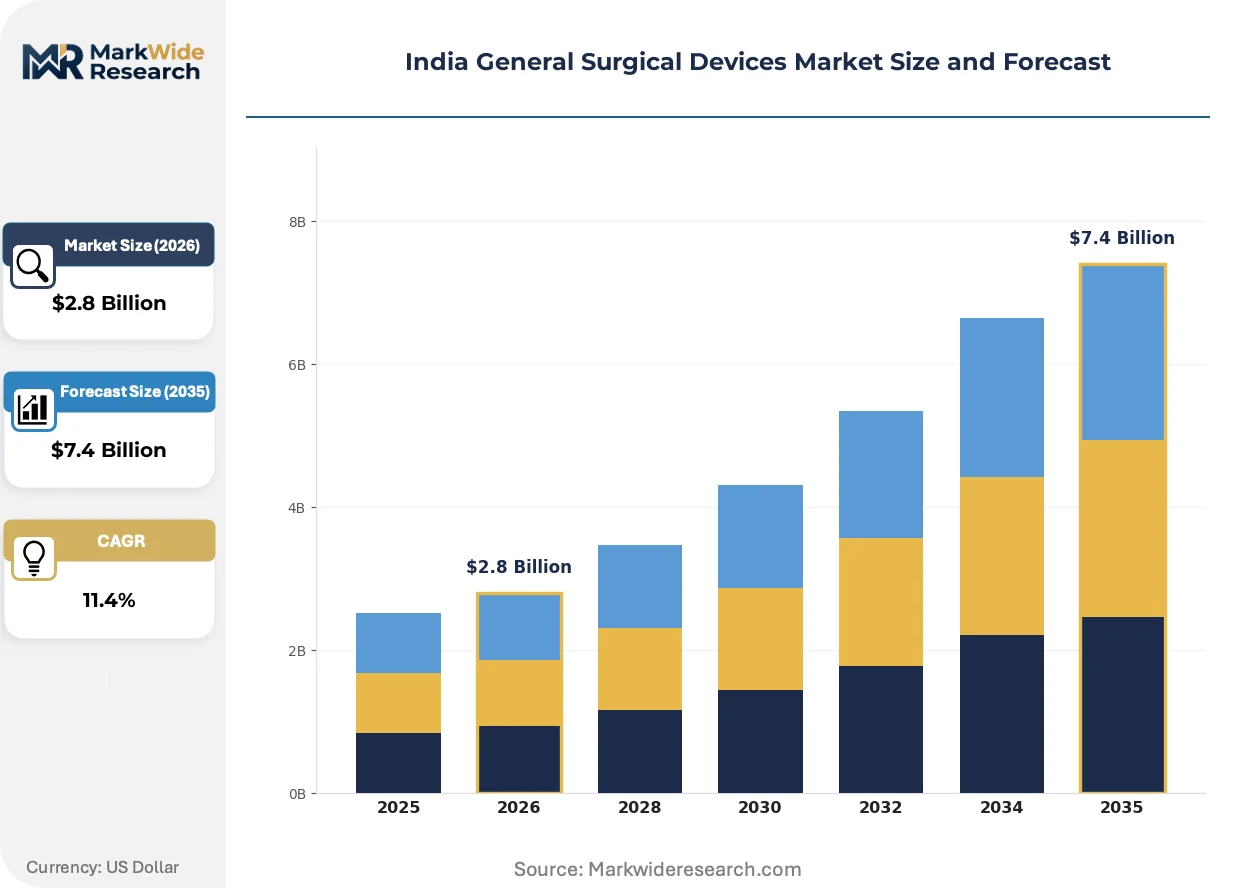
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Sutures, Electrosurgical Devices, Laparoscopic Equipment End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Technology: Minimally Invasive, Robotic-Assisted, Traditional, Imaging Systems Application: Orthopedic Surgery, Cardiovascular Procedures, General Surgery, Neurosurgery |
| Companies Covered | B. Braun SE, Olympus Corporation, Conmed Corporation, 3M Company, Stryker Corporation, Boston Scientific Corporation, Medtronic plc, Smith & Nephew plc, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India General Surgical Devices Market Shifts & Advancements
Technology convergence, regulatory stringency, and procurement model evolution are reconfiguring competitive positioning across India's surgical device landscape. Three distinct forces merit attention.
Polymer composite instrument handles are converging with titanium alloy working tips to reduce surgeon fatigue during prolonged laparoscopic procedures. Corporate hospital chains in Maharashtra and Karnataka are standardizing these hybrid platforms across their operating theaters. The convergence is compressing pure stainless steel market share in premium tertiary care segments while elevating supplier technical qualification barriers.
CDSCO's Medical Devices Rules amendments are mandating post-market surveillance systems that mirror FDA adverse event reporting structures. Domestic manufacturers must now maintain vigilance databases that multinational competitors have operated for decades. The orthopedic implant category faces the steepest compliance curve as BIS certification requirements phase in alongside central regulator mandates.
Corporate hospital procurement committees are consolidating vendor panels and demanding total cost-of-ownership contracting that bundles instruments with sterilization validation and training. Day-care surgical units in Tamil Nadu are pioneering this model, displacing transactional spot-buying from regional distributors. The shift concentrates purchasing power with chains possessing internal biomedical engineering capabilities.
India General Surgical Devices Market Segmentation
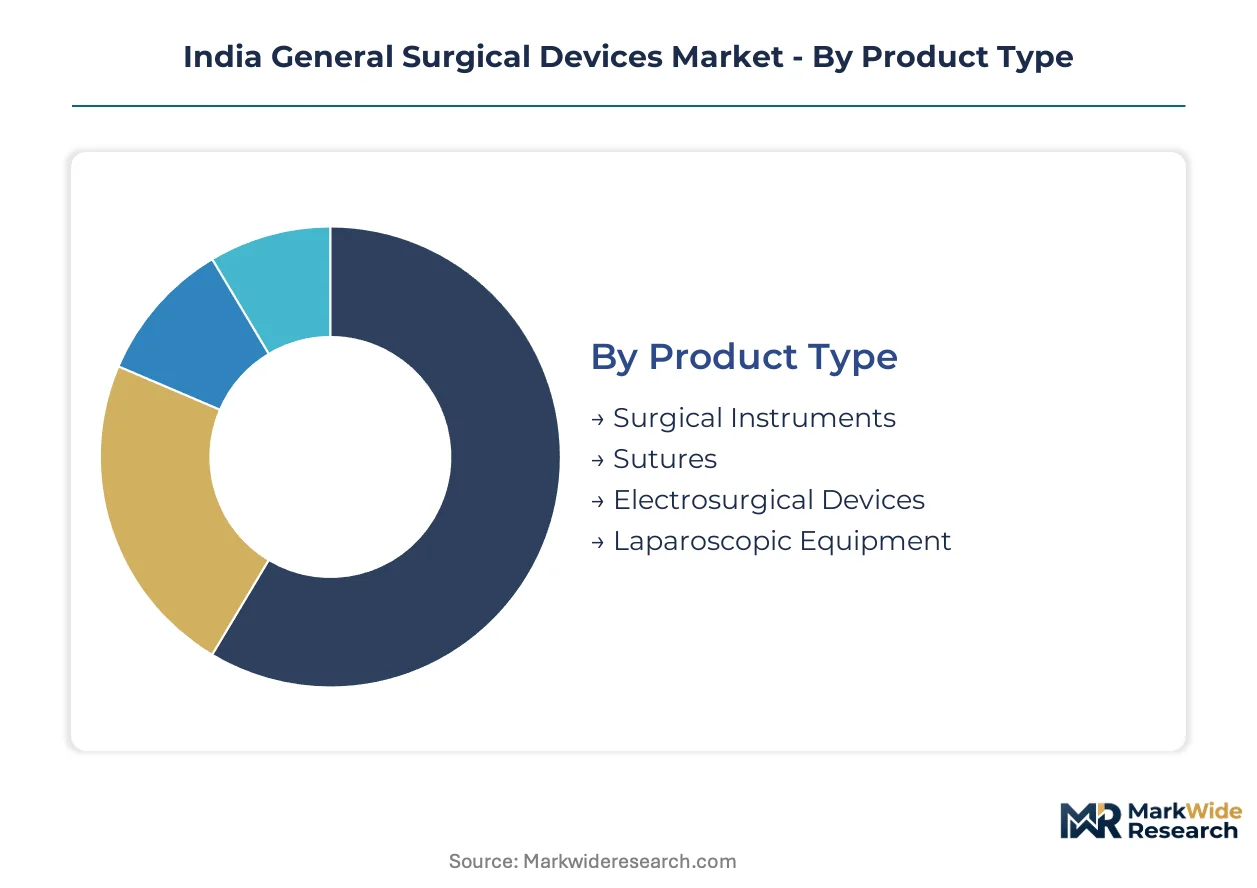
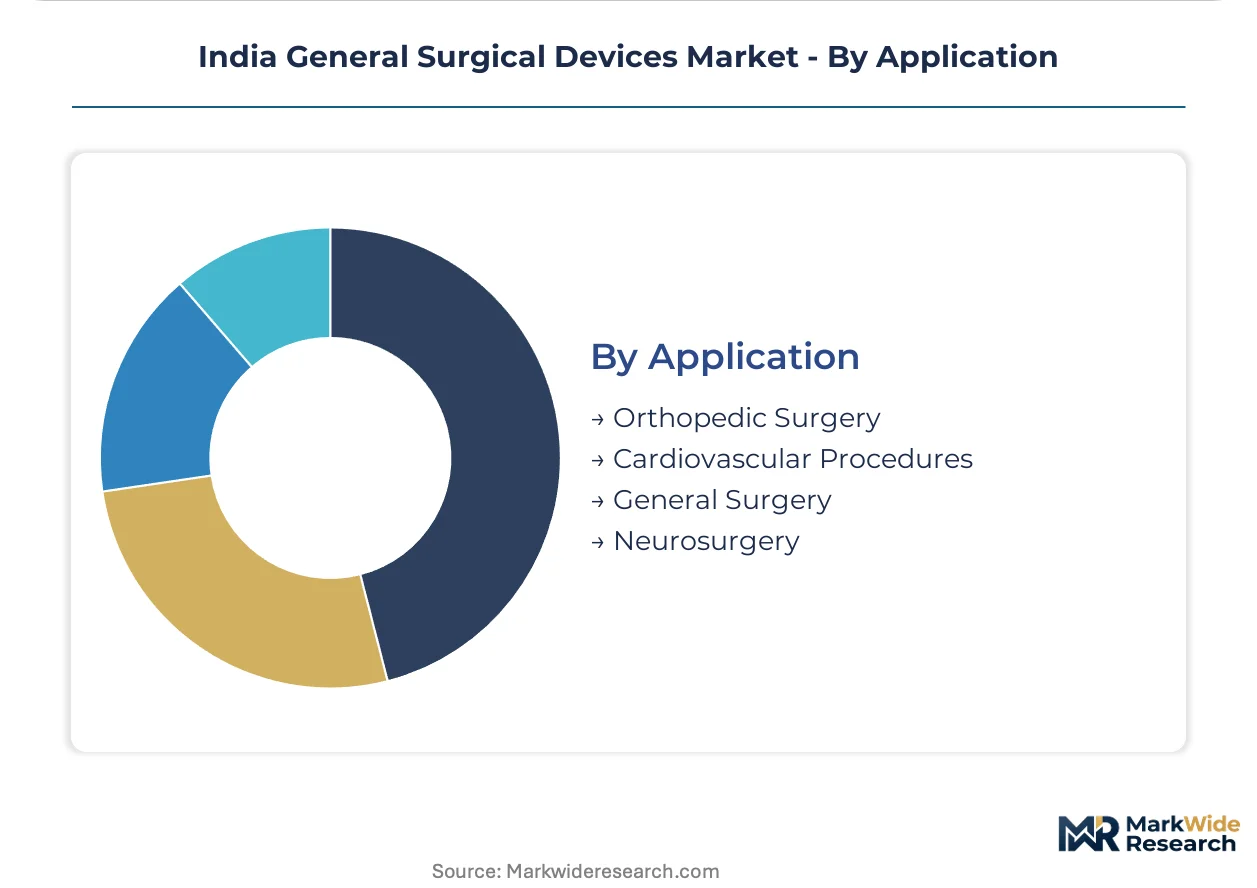
Surgical device procurement in India fragments across four distinct classification axes that reshape vendor qualification requirements and capital deployment priorities. Each segmentation layer imposes different technical certification burdens, sterilization infrastructure demands, and channel access protocols that manufacturers must navigate simultaneously.
Product Type:
Capital intensity varies sharply across this category, with electrosurgical platforms and laparoscopic systems demanding tenfold higher upfront investment than hand-held instrument portfolios.
- Surgical Instruments:Hand-held tools manufactured from medical-grade stainless steel and titanium alloys enable tissue manipulation, hemostasis, and wound closure. Maharashtra and Karnataka hospital chains anchor procurement volumes for reusable instrument sets, though CDSCO sterilization protocol upgrades are compressing margins for mid-tier domestic manufacturers lacking captive autoclave infrastructure.
- Electrosurgical Devices:Energy-based cutting and coagulation systems integrate generator units with disposable electrodes and return pads. Tamil Nadu's corporate hospital networks concentrate demand for these platforms as they expand minimally invasive surgical capacity, prioritizing suppliers with ISO-certified manufacturing and BIS-compliant electrical safety documentation.
- Sutures:Absorbable and non-absorbable wound closure materials span synthetic polymers and natural collagen derivatives. Government medical college tenders in Karnataka sustain volume procurement despite price compression.
- Laparoscopic Equipment:Insufflators, trocars, and optical systems enable minimally invasive abdominal procedures. Tier-II city hospital expansions in Tamil Nadu and Maharashtra are opening new installation opportunities outside saturated metropolitan markets.
Surgical Instruments absorbs the bulk of installed capacity; Laparoscopic Equipment is expanding most quickly.
End User:
Procurement authority concentrates differently across this axis, with corporate hospital chains wielding consolidated purchasing power while government channels fragment across state-level tender processes.
- Hospitals:Tertiary care institutions in Maharashtra, Karnataka, and Tamil Nadu command the largest procurement volumes, with NABH accreditation standards filtering vendor panels toward ISO-certified suppliers. CDSCO registration requirements and extended product approval timelines favor incumbents with established dossier libraries.
- Ambulatory Surgical Centers:Day-care facilities performing same-day discharge procedures across cardiology and orthopedics. These units in Tamil Nadu are pioneering total cost-of-ownership contracting that bundles instruments with sterilization validation, displacing transactional spot-buying from regional distributors.
- Specialty Clinics:Focused outpatient surgical facilities concentrate in urban Karnataka and Maharashtra. Procurement volumes remain fragmented compared to hospital networks.
- Research Institutions:Medical colleges and training hospitals generate demand for educational instrument sets and simulation equipment. Government funding cycles create lumpy procurement patterns.
Hospitals command the dominant share of procurement value; Ambulatory Surgical Centers are climbing the fastest as day-care protocols expand.
Technology:
Adoption maturity spreads unevenly across this axis, with traditional open-surgery tools saturating public health systems while robotic platforms remain confined to premium private networks.
- Minimally Invasive:Laparoscopic and endoscopic techniques reduce tissue trauma and recovery times. Corporate hospital chains in Maharashtra are standardizing these platforms, elevating supplier technical qualification barriers through polymer-titanium hybrid instrument requirements.
- Traditional:Open-procedure toolkits dominate government hospital procurement due to lower capital requirements and reusable metal instrument compatibility with existing sterilization infrastructure.
- Robotic-Assisted:Computer-guided surgical systems with articulated instrument arms. Installation concentrates in select tertiary care networks with dedicated biomedical engineering capabilities.
- Imaging Systems:Intraoperative visualization and navigation technologies. Adoption remains nascent outside premium metropolitan institutions.
Traditional technology retains the largest installed base; Minimally Invasive platforms are gaining share fastest as hospital chains prioritize laparoscopic capacity.
Application:
Procedure volume growth rates diverge across this axis, with orthopedic interventions expanding on demographic drivers while cardiovascular demand reflects epidemiological transition patterns.
- Orthopedic Surgery:Joint replacement and trauma procedures drive demand for specialized cutting guides, reamers, and implant insertion instruments. Arthroplasty volumes are rising fastest in Karnataka and Tamil Nadu, where aging demographics and accident trauma rates sustain procedure growth.
- General Surgery:Abdominal, gastrointestinal, and soft tissue procedures constitute the highest-volume category. Maharashtra's hospital networks anchor procurement for open and laparoscopic general surgery toolkits.
- Cardiovascular Procedures:Cardiac and vascular interventions require specialized sternal saws, vessel clamps, and anastomosis devices. Day-care cardiac units in Tamil Nadu are expanding same-day intervention capacity.
- Neurosurgery:Cranial and spinal procedures demand micro-instruments and precision drilling systems. Procedure volumes remain concentrated in select tertiary referral centers.
General Surgery commands the highest procedure volume; Orthopedic Surgery is expanding most quickly on joint replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pharmaceutical Export Promotion Council's special economic zone incentives in Visakhapatnam and Hyderabad are concentrating domestic manufacturing capacity for high-value surgical consumables. CDSCO's regional office grading system accelerates registration timelines for manufacturers locating in these designated zones. State-level medical device parks in Telangana and Andhra Pradesh now host sterilization infrastructure clusters serving Tier-II hospital networks.
Maharashtra
Mumbai and Pune hospital chains anchor procurement volumes for electrosurgical platforms and laparoscopic systems. The state's Food and Drug Administration enforces CDSCO-mandated post-market surveillance through its zonal offices. The Maharashtra Industrial Development Corporation's medical device park in Aurangabad hosts domestic sterilization infrastructure serving secondary city hospitals.
Karnataka
Bangalore's corporate hospital networks drive demand for polymer-titanium hybrid instruments and minimally invasive surgical capacity. The Karnataka State Drugs Control Organization coordinates with CDSCO on BIS certification enforcement for metallic implants. The Peenya industrial cluster hosts instrument manufacturers supplying government medical college tenders across South India.
Tamil Nadu
Chennai's ambulatory surgical centers pioneer total cost-of-ownership contracting for day-care cardiology and orthopedic units. The Tamil Nadu Medical Services Corporation channels government procurement toward ISO-certified suppliers through centralized tender processes. The Sriperumbudur medical device manufacturing zone supplies sutures and disposable electrodes to hospital networks.
Telangana
Hyderabad's medical technology corridor attracts PLI scheme beneficiaries establishing domestic production of surgical consumables. The Telangana State Industrial Infrastructure Corporation's medical device park offers shared sterilization facilities reducing capital barriers for mid-tier manufacturers. Genome Valley's research institutions generate demand for specialized educational instrument sets.
Gujarat
Ahmedabad and Surat hospital networks expand surgical capacity for trauma and joint replacement procedures. The Gujarat Food and Drug Control Administration implements CDSCO quality norms through its manufacturing inspection protocols. The Sanand medical device cluster hosts stainless steel instrument fabricators serving government hospital tenders across Western India.
India General Surgical Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across India's surgical device landscape. The market structure tilts toward consolidated procurement power as corporate hospital chains narrow vendor panels and demand bundled service contracts. Three archetypes dominate: multinational subsidiaries with established sterilization infrastructure, domestic mid-caps leveraging PLI scheme incentives, and regional distributors transitioning toward manufacturing. Competitive moves concentrate on strategic partnerships with hospital chains and geographic expansion into Tier-II city networks.
Among multinational anchors, B. Braun SE and Medtronic plc exemplify the infrastructure-heavy archetype with established CDSCO registration libraries and captive sterilization protocols. Smith & Nephew plc occupies a specialized position within orthopedic surgical instruments. Domestic competitors cluster around the PLI scheme beneficiary tier, with mid-cap manufacturers in Telangana and Maharashtra medical device parks narrowing cost gaps on high-volume consumables. The competitive terrain rewards suppliers capable of bundling instruments with NABH-compliant sterilization validation and surgeon training programs.
| Leading Market Players |
|---|
| B. Braun SE |
| Olympus Corporation |
| Conmed Corporation |
| 3M Company |
| Stryker Corporation |
| Boston Scientific Corporation |
| Medtronic plc |
| Smith & Nephew plc |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Skilled instrument craftsmen concentrated in Maharashtra's Aurangabad and Karnataka's Peenya industrial belts compress labor-cost differentials into pricing-tier spreads. Tier-II city hospitals access standard-grade stainless steel instruments at 40-60% discounts to polymer-titanium hybrid platforms procured by Mumbai and Bangalore corporate chains.
Pricing Analysis
Short lead-time premiums command 15-25% markups over standard delivery windows in government tender cycles. Three-tier pricing structure across premium, standard, and economy levels segments procurement: ISO-certified electrosurgical platforms with bundled sterilization validation anchor premium tiers; BIS-compliant reusable instrument sets occupy standard positioning; non-certified spot inventory serves price-sensitive public health tenders. Cost compression in economy tiers intensifies because CDSCO-mandated ERP upgrades strain mid-tier manufacturer working capital. Government medical college procurement committees exhibit highest price sensitivity; NABH-accredited corporate hospital chains prioritize total cost-of-ownership over unit pricing.
Supply Chain Analysis
Reverse logistics flows for reusable instrument refurbishment and remanufacturing anchor secondary supply circuits serving public health systems. Manufacturing concentrates in India, Germany, and China, with domestic production expanding under PLI scheme incentives. Supply chains draw from medical-grade stainless steel mills in Gujarat, titanium alloy feedstock from aerospace suppliers, and polymer composite resins from specialty chemical producers. Single-source vulnerability concentrates in ethylene oxide sterilization infrastructure facing replacement pressure from hydrogen peroxide systems. Distribution runs through regional medical device distributors consolidating toward hospital-direct contracting in Tamil Nadu and Maharashtra.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's surgical device sector occupies a technology-transition phase as energy-based electrosurgical platforms displace traditional hand-held metal instruments across minimally invasive procedure volumes.
For Market Incumbents: Deepen captive sterilization infrastructure investments to defend margin position against PLI-subsidized domestic entrants narrowing cost gaps on high-volume consumables. Expand ISO-certified manufacturing capacity in Telangana medical device parks to capture Tier-II city hospital procurement growth. Strengthen surgeon training program bundling to differentiate from spot-buying distributors losing share to total cost-of-ownership contracting.
For New Entrants and Emerging Players: Enter via ambulatory surgical center specialization in Tamil Nadu day-care cardiology and orthopedic units, where procurement consolidation creates vendor panel openings for compliant domestic manufacturers. Target sutures and disposable electrodes as most penetrable product categories given lower BIS certification burdens relative to metallic implants. Pursue hospital-direct partnerships bypassing regional distributor markups.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap domestic manufacturers possessing PLI scheme beneficiary status and captive autoclave infrastructure given CDSCO quality norm tightening. Long-term viability over the next decade hinges on backward integration into medical-grade stainless steel processing and polymer composite molding capabilities. Watch sterilization protocol reconfiguration timelines as inflection indicator for working capital strain among non-compliant targets.
| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Registration Acceleration | Expedited dossier preparation compresses market access timelines against incumbent regulatory libraries. |
| Hospital System Partnership | Direct contracting with Maharashtra and Karnataka corporate chains displaces regional distributor intermediaries. |
| Backward Integration into Sterilization | Captive ethylene oxide or hydrogen peroxide infrastructure satisfies CDSCO-mandated protocol upgrades. |
| Software Companion Development | Electrosurgical generator integration with hospital information systems elevates technical qualification barriers. |
| Reimbursement Strategy | Alignment with Ayushman Bharat package rates unlocks government hospital procurement volumes. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, biomedical engineer consultations, and CDSCO regulatory filings underwrites the qualitative findings. Primary fieldwork engaged hospital procurement managers, GPO contracts specialists, domestic manufacturer operations heads, and sterilization facility engineers across Maharashtra, Karnataka, and Tamil Nadu. Secondary validation drew from CDSCO medical device registration databases, BIS certification records, NABH accreditation directories, and state-level medical college tender disclosures. Bottom-up demand modeling triangulated against top-down industry sizing.
Rate-of-change decomposition segmented volume and value trajectories across the projection horizon by product type, end user, technology, and application dimensions. CAGRs derived from procedure volume elasticity to hospital bed expansion, technology substitution curves for minimally invasive platforms, and pricing dynamics under regulatory cost pass-through. Forecast inputs incorporated PLI scheme capital deployment tracking, CDSCO registration pipeline analysis, and Tier-II city hospital capacity build-out surveys.
Forecast precision tightens around the base case; tail outcomes carry wider variance under CDSCO registration timeline extensions or medical-grade stainless steel price volatility spikes. Assumptions reflect documented hospital procurement committee consolidation trends and sterilization infrastructure replacement cycles. Material deviation in PLI scheme disbursement rates or BIS metallic implant certification delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Middle East and Africa General Surgical Devices Market
Surgical Instruments
Non-Absorbable Sutures Market
Surgical Instruments
Suture Anchor Market
Surgical Instruments
Europe Minimally Invasive Surgery Market
Surgical Instruments
Electrosurgery Market
Surgical Instruments
US Surgical Staplers Market
Surgical Instruments
Skin Graft Blades Market
Surgical Instruments
Cleft Lip and Palate Repair Surgical Instrument Package Market
Surgical Instruments
Global Surgical Catheters Market
Surgical Instruments
Global Bone Wax Market
Surgical Instruments
Surgical Suction Pumps Market
Surgical Instruments
Uro Gynaecological Surgical Devices Market
Surgical Instruments
Medical Tuning Fork Market
Surgical Instruments
Biosurgery Market
Surgical Instruments
Surgical Blades Market
Surgical Instruments
Dermal Curettes Market