
 Wind Powered Water Pumps Market | 2026-2036
Wind Powered Water Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Powered Water Pumps Market Analytics
Chinese wind turbine component manufacturers is broadening the supply base for pump drivetrain assemblies across Asia-Pacific. Aermotor Windmill Company Inc. anchors American heritage branding in mechanical windmill segments for ranch and farm applications. Grundfos Holding A/S leverages its electronics integration expertise to hybridize solar-wind pump controllers. Southern Cross Windmills Pty Ltd dominates Australian pastoral markets with corrosion-resistant designs for arid zone operation.
Wind powered water pumps convert kinetic energy from rotor blades into mechanical or electrical power to lift groundwater or surface water through suction, pressure, or positive displacement mechanisms, typically achieving lift capacities from 5 to 150 meters depending on rotor diameter and wind regime. Submersible pumps now lead product category value due to deeper borehole access requirements in depleting aquifer zones. Agricultural irrigation commands the largest application share, though livestock watering shows faster growth where distributed grazing operations replace centralized trough systems. Horizontal axis technology retains manufacturing scale advantages, while vertical axis designs compete in low-wind-speed environments.
The EPA and USDA jointly influence American market access through groundwater conservation compliance and rural energy program eligibility criteria. India's MNRE off-grid guidelines and BIS pump efficiency standards shape procurement specifications for subsidized rural installations. REACH and CE marking requirements in Europe restrict material compositions in nacelle housings and lubricants. Stakeholders must monitor evolving groundwater extraction caps and renewable energy certificate valuations to align product development with shifting incentive structures.
Market Dynamics
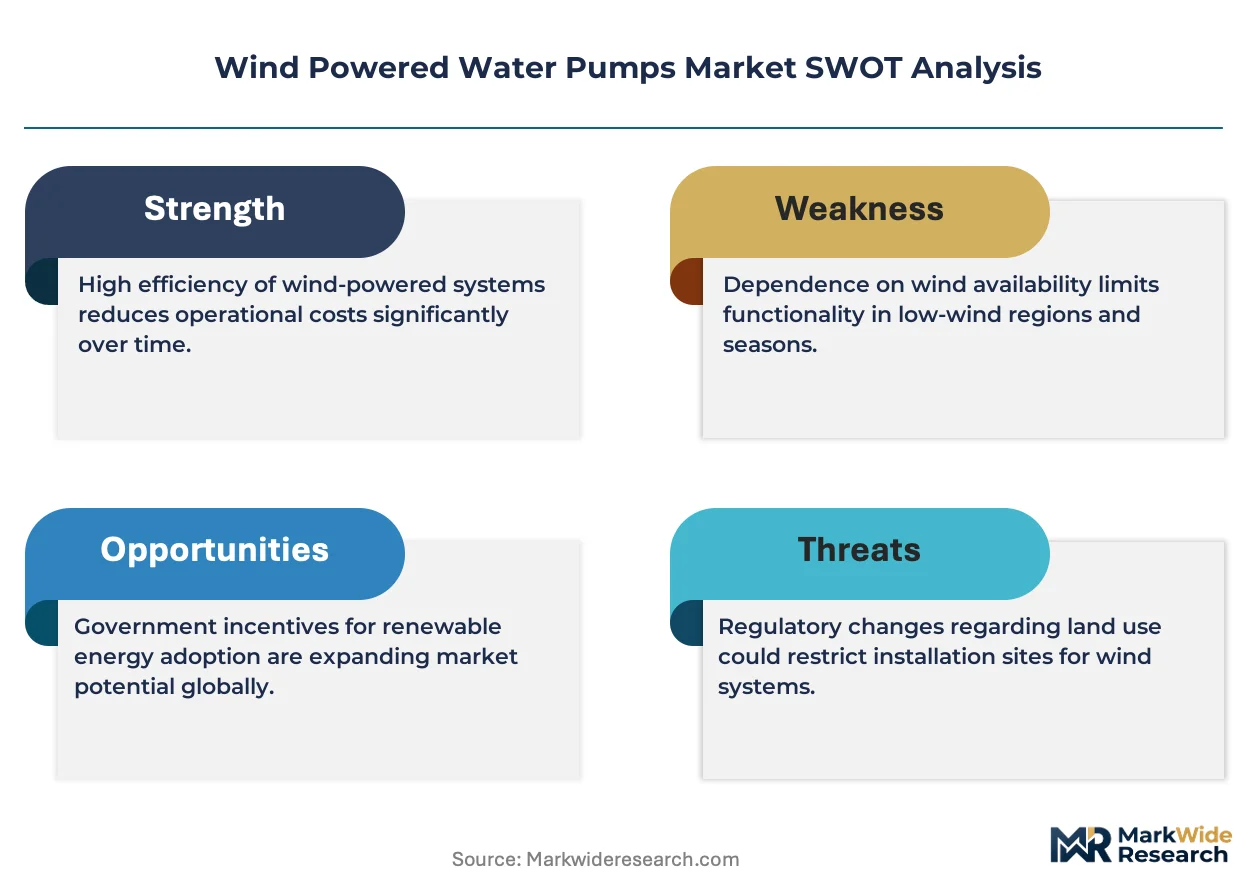
Groundwater depletion across drought-prone agricultural belts is forcing deeper borehole drilling, which mechanically advantages high-lift submersible pump configurations over traditional mechanical windmill designs. This shift compresses the addressable market for legacy surface-pump architectures while expanding specification requirements for rotor diameter and drivetrain torque.
Growth Catalysts
- India's MNRE Off-Grid Guidelines:Subsidized capital cost coverage for wind-solar hybrid pumping stations accelerates deployment across Rajasthan and Gujarat smallholder belts.
- Depleting Aquifer Zones:Deeper water tables in the Ogallala Basin and North China Plain necessitate submersible pump retrofits that match wind rotor output to high-head electric motors.
- Corrosion-Resistant Materials:Glass-reinforced polymer nacelle housings and stainless steel drivetrain components extend operational life in saline groundwater environments.
Market Restraints
- Steel and Rare Earth Input Volatility:Permanent magnet rotor assemblies depend on neodymium supply concentration in Chinese processing facilities.
- Intermittency Mismatch:Wind resource variability requires oversized storage tanks or battery buffers, inflating total installed cost beyond standalone diesel equivalents.
- REACH Compliance Friction:European lubricant and coating restrictions limit supplier pools for sealed-bearing assemblies used in offshore island installations.
Strategic Opportunities
- Sub-Saharan Distributed Grazing:Kenya and Ethiopia pastoral corridors lack grid connectivity but possess consistent low-wind regimes suited to vertical axis designs.
- Solar-Wind Hybrid Controllers:MPPT electronics convergence enables 24-hour pumping cycles that pure wind or pure solar cannot achieve independently.
- USDA Rural Energy for America Program:Guaranteed loan financing for agricultural renewable energy equipment reduces farmer capital barriers in Texas and Oklahoma.
Industry Challenges
- Certification Timeline Compression:BIS pump efficiency testing in India creates 4-6 month procurement delays for subsidized installation windows.
- Legacy Trough Integration:Existing ranch water systems use gravity-fed steel piping incompatible with pressurized submersible outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Powered Water Pumps Market |
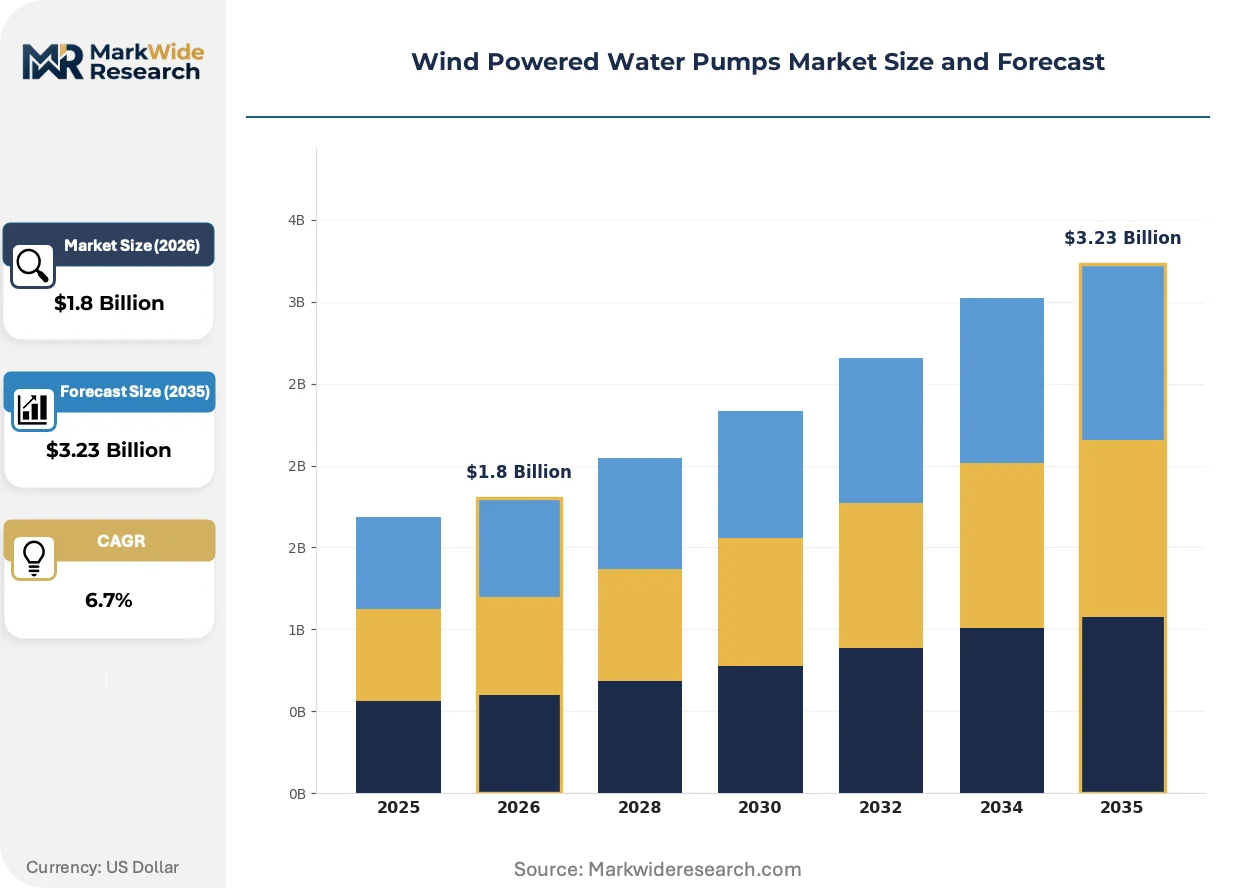
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Pumps, Surface Pumps, Gear Pumps, Diaphragm Pumps Application: Agricultural Irrigation, Livestock Watering, Residential Water Supply, Industrial Usage Technology: Horizontal Axis, Vertical Axis, Positive Displacement, Rotary End User: Agriculture, Rural Communities, Industrial Sector, Environmental Projects |
| Companies Covered | WindEnergy7 LLC, Aermotor Windmill Company Inc., Grundfos Holding A/S, Lone Star Windmill Company LLC, Iron Man Windmill Co. Ltd., SWECO AB, Aquatic Control Inc., Southern Cross Windmills Pty Ltd., Graco Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Powered Water Pumps Market Evolving Landscape
Electrification of drivetrains and digital monitoring integration are displacing purely mechanical windmill architectures across commercial agricultural deployments. These shifts favor suppliers with electronics manufacturing capabilities over traditional metal fabrication specialists.
Direct-drive permanent magnet generators are expanding into medium-scale irrigation cooperatives seeking reduced maintenance intervals. Brazilian soybean operations in Mato Grosso have adopted 10-50kW units for center-pivot supplemental feeds. The technology is expanding into markets previously served by diesel-powered borehole pumps.
EPA groundwater conservation compliance rules now mandate flow metering on all federally subsidized agricultural wells. This requirement forces pump controller manufacturers to integrate data logging and telemetry modules as standard features. Submersible pump suppliers serving the Ogallala Basin have retooled product lines to include cellular-enabled monitoring.
Cooperative procurement aggregations among Indian farmer producer organizations are consolidating specification power previously fragmented across individual smallholders. These bodies now issue tender documents requiring 10-year service contracts and spare parts availability guarantees. The pattern is most visible in Gujarat's groundnut-growing districts where FPOs manage shared borehole assets.
Wind Powered Water Pumps Market Segmentation
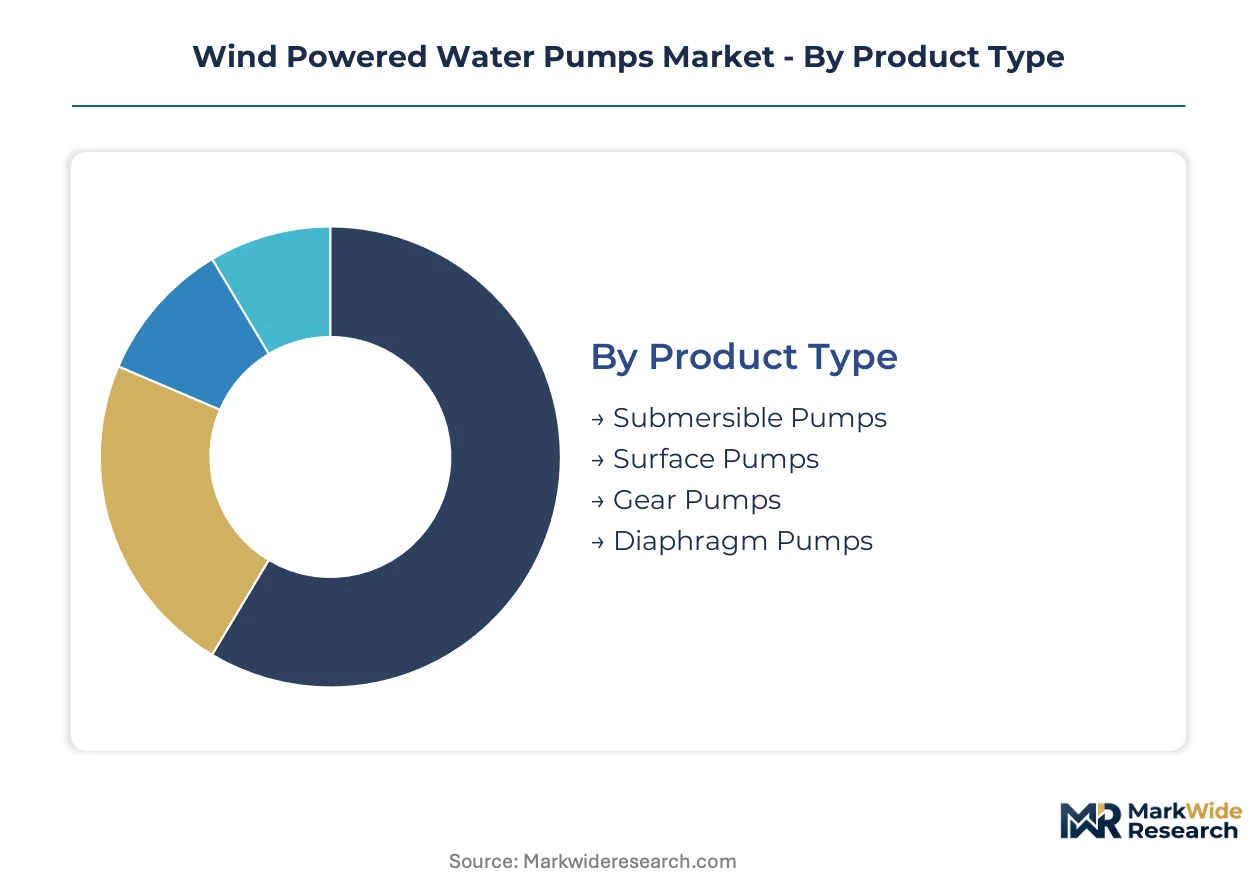
Wind powered water pump configurations diverge sharply by hydraulic duty, mechanical architecture, and purchaser sophistication. Segment boundaries determine supplier R&D allocation and channel strategy.
Product Type:
Volume concentrates in high-lift configurations for deep aquifer access, while surface-mounted architectures serve legacy infrastructure.
- Submersible Pumps:Electric motor-driven units suspended below water level handle heads exceeding 100 meters. Demand clusters in Rajasthan and Gujarat where falling water tables require borehole depths beyond mechanical windmill reach. MNRE subsidy eligibility favors these configurations for new installations.
- Surface Pumps:Suction-lift mechanisms positioned above water level suit shallow wells and river intakes. Texas ranch operations retain these for existing trough gravity-feed systems despite pressure limitations. Capital cost advantages persist where water tables remain stable.
- Gear Pumps:Positive displacement rotary designs deliver precise flow rates for chemical dosing and fertigation integration.
- Diaphragm Pumps:Reciprocating elastomer membrane mechanisms handle abrasive groundwater with minimal wear.
Mature deployment sits with surface pump architectures. Newer deployment is concentrated in submersible configurations for depleting aquifer zones.
Application:
Purchaser economics separate scheduled irrigation operations from intermittent livestock servicing and continuous industrial duty.
- Agricultural Irrigation:Center-pivot and flood irrigation systems demand the highest flow rates and reliability guarantees. Brazilian soybean cooperatives in Mato Grosso deploy 10-50kW hybrid units for supplemental feeding during dry spells. Seasonal load profiles match wind resource variability.
- Livestock Watering:Distributed grazing operations replace centralized trough systems with satellite pumping stations. Kenya's pastoral corridors favor these for mobility and grid independence. Installation scale per site remains below agricultural benchmarks.
- Residential Water Supply:Single-family and small community systems prioritize simplicity over hydraulic performance.
- Industrial Usage:Process water and dust suppression applications require continuous duty ratings and telemetry integration.
Revenue gravity centers on agricultural irrigation. Livestock watering climbs fastest as ranching intensifies in water-stressed rangelands.
Technology:
Rotor orientation and power transmission mechanics determine wind speed thresholds and maintenance intervals.
- Horizontal Axis:Upwind rotor configurations with planetary gearboxes or direct-drive generators dominate manufacturing scale. Australian pastoral markets specify these with corrosion-resistant nacelle housings for saline coastal exposure. Blade pitch regulation extends operational wind speed ranges.
- Vertical Axis:Savonius and Darrieus designs extract torque from omnidirectional wind without yaw mechanisms. Ethiopia's low-wind-speed highlands adopt these where horizontal axis cut-in speeds exceed resource availability. Mechanical simplicity reduces technical service requirements.
- Positive Displacement:Piston and plunger mechanisms deliver constant volume per stroke regardless of head pressure.
- Rotary:Centrifugal and vane impeller designs optimize for high-flow, low-head surface water applications.
Horizontal axis manufacturing scale advantages persist. Vertical axis adoption accelerates in marginal wind resource zones.
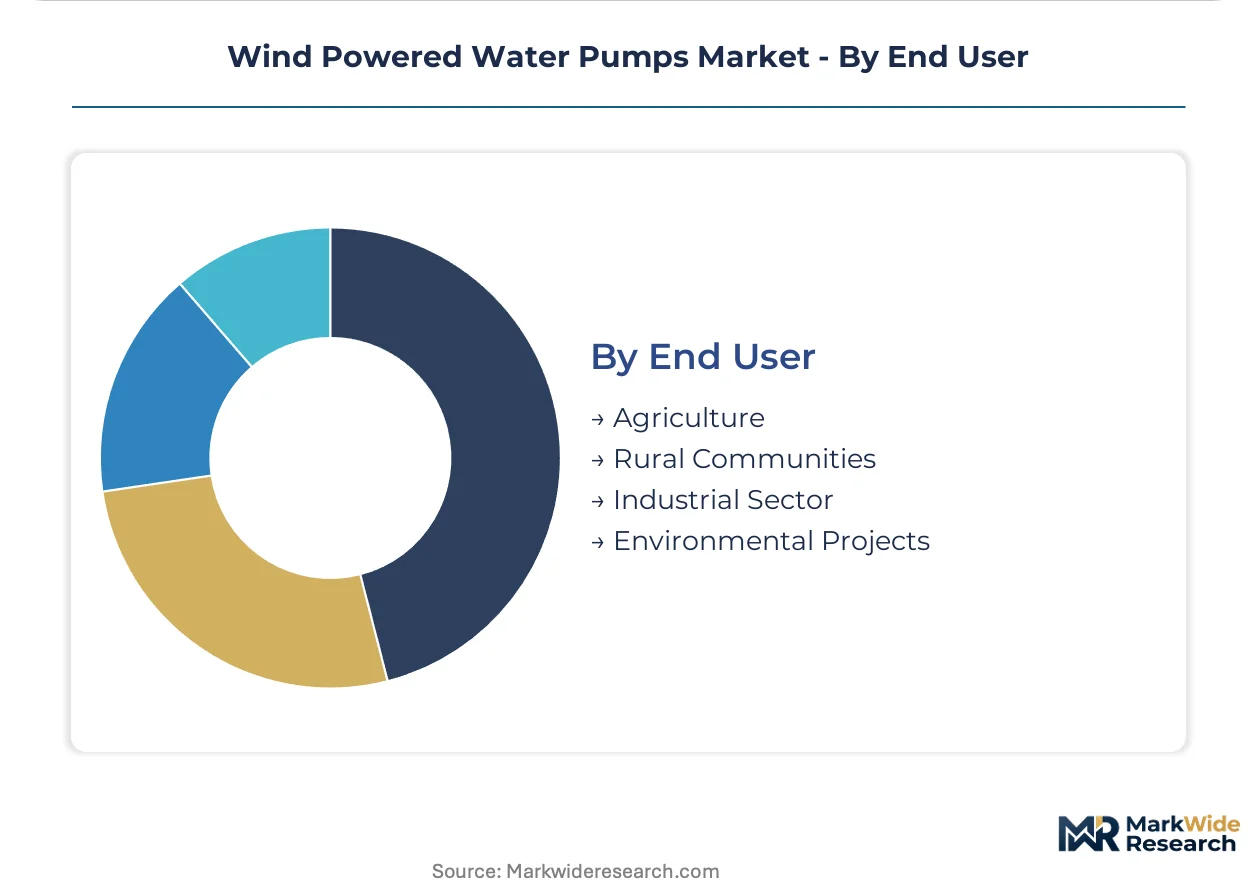
End User:
Procurement sophistication ranges from subsidized smallholder programs to corporate sustainability mandates.
- Agriculture:Large-scale farming operations and cooperative aggregations specify 10-year service contracts and spare parts guarantees. Gujarat farmer producer organizations consolidate tender power for shared borehole assets. Capital cost sensitivity yields to total lifecycle reliability concerns.
- Rural Communities:Off-grid villages and dispersed settlements prioritize capital cost minimization over hydraulic efficiency. Sub-Saharan Africa's electrification gaps sustain demand for purely mechanical architectures. Maintenance skill scarcity favors simplicity.
- Industrial Sector:Mining and processing operations integrate wind pumping into renewable energy certificate strategies.
- Environmental Projects:Wetland restoration and groundwater recharge programs specify low-impact installations with minimal civil works.
Institutional procurement maturity distinguishes agricultural cooperatives. Rural community deployment expands through development finance channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium processing concentration in Chinese refineries anchors rotor assembly supply chains for wind pump drivetrains across Asia-Pacific manufacturing clusters. This feedstock geography shapes regional deployment patterns and procurement strategies for permanent magnet generators.
India
Rajasthan's falling water tables drive submersible pump retrofits beyond mechanical windmill reach. MNRE off-grid guidelines subsidize capital costs for wind-solar hybrid stations in Gujarat's groundnut belts. Farmer producer organizations in Saurashtra consolidate tender specifications requiring decade-long service contracts.
United States
Texas and Oklahoma ranch operations retain surface pumps for legacy trough gravity-feed systems despite aquifer depletion. USDA Rural Energy for America Program guarantees loan financing for agricultural renewable equipment. Ogallala Basin producers retrofit cellular-enabled telemetry modules to meet EPA groundwater conservation compliance.
Australia
Pastoral corridors in Queensland and Western Australia specify corrosion-resistant nacelle housings for saline coastal exposure. Horizontal axis designs dominate manufacturing scale for arid zone operation. Southern Cross Windmills anchors heritage branding in mechanical segments for remote station watering.
Brazil
Mato Grosso soybean cooperatives deploy 10-50kW hybrid units for center-pivot supplemental irrigation during dry spells. Direct-drive permanent magnet generators displace diesel-powered borehole pumps in expanding agricultural frontiers. Seasonal wind resource variability matches crop water demand curves.
Kenya
Pastoral corridors in northern rangelands lack grid connectivity but possess consistent low-wind regimes suited to vertical axis designs. Distributed grazing operations replace centralized trough systems with satellite pumping stations. Development finance channels sustain deployment through rural electrification gaps.
Wind Powered Water Pumps Market Competitive Landscape
Global majors compete with regional champions across electronics integration and mechanical heritage segments. The vendor base stratifies between diversified pump manufacturers with controller expertise and specialized windmill fabricators serving ranching traditions. Three archetypes dominate: integrated electronics specialists, corrosion-resistant arid-zone engineers, and heritage mechanical windmill builders. Competitive moves center on solar-wind hybrid controller convergence and backward integration into permanent magnet supply chains.
Within the heritage mechanical tier, Aermotor Windmill Company Inc. and Southern Cross Windmills Pty Ltd exemplify regional anchoring strategies in American ranch and Australian pastoral markets respectively. Among diversified pump manufacturers, Grundfos Holding A/S occupies a position representing electronics integration capabilities that enable hybrid system architectures. These three entities illustrate how competitive positioning diverges between mechanical simplicity for remote maintenance and digital sophistication for grid-adjacent cooperatives.
| Leading Market Players |
|---|
| WindEnergy7 LLC |
| Aermotor Windmill Company Inc. |
| Grundfos Holding A/S |
| Lone Star Windmill Company LLC |
| Iron Man Windmill Co. Ltd. |
| SWECO AB |
| Aquatic Control Inc. |
| Southern Cross Windmills Pty Ltd. |
| Graco Inc. |
| Others |
Value Network & Pricing Analysis
Permanent magnet motor winding specialists in Jiangsu province anchor labor-cost differentials that widen pricing-tier spreads between economy mechanical windmills and premium hybrid-electric systems. This workforce geography compresses margins on entry-level units while sustaining premium capture for integrated controller manufacturers.
Pricing Analysis
Warranty and service-bundling configurations separate premium offerings from stripped capital-equipment sales across the market. Three-tier pricing structure across premium, standard, and economy levels tracks rotor diameter and telemetry inclusion, with MNRE-subsidized Indian procurement showing highest price sensitivity and Australian pastoral cooperatives least. Pricing pressure stems from steel input volatility and rare earth magnet cost swings, forcing economy-tier suppliers toward shorter warranty periods.
Supply Chain Analysis
Single-source vulnerability sits with Chinese neodymium processing facilities that feed permanent magnet rotor assemblies for drivetrain manufacturers. Component sourcing draws from China for rare earth refining, India for wound stator production, and Denmark for pump controller electronics. Tariff exposure on magnet imports threatens margin stability for hybrid-system assemblers. Distribution runs through agricultural equipment dealers in mature markets and government procurement channels in subsidized deployment zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent magnet supply concentration props pricing power for integrated manufacturers, while mechanical windmill fabricators face capacity constraints on skilled metalworking labor in heritage production regions.
For Market Incumbents: Hedge against solar-only competitor encroachment by securing captive neodymium supply through offtake agreements with Chinese refiners. Add controller assembly capacity in Gujarat to capture MNRE subsidy procurement windows. Certification investment in BIS efficiency testing accelerates subsidy eligibility timelines. For New Entrants and Emerging Players: Begin with Kenya's pastoral corridor distributed grazing segment, where low-wind vertical axis designs face minimal incumbent presence. Target Ethiopian highland agricultural cooperatives seeking mechanical simplicity over electronic sophistication. Go-to-market through development finance channel partnerships rather than direct farmer sales. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid controller specialists given solar-wind MPPT convergence catalysts. Long-term viability favors suppliers with in-house magnet sourcing and electronics integration capabilities. Watch USDA Rural Energy for America Program funding authorization as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Supply | Captive neodymium sourcing insulates margins from Chinese export quota volatility. |
| Solar-Wind Hybrid Controller Development | MPPT electronics convergence enables 24-hour pumping cycles for agricultural cooperatives. |
| Corrosion-Resistant Materials Transition | Glass-reinforced polymer housings extend operational life in Australian saline groundwater zones. |
| Farmer Producer Organization Channel Partnerships | Gujarat FPO tender aggregation consolidates specification power for shared borehole assets. |
| Cellular Telemetry Module Integration | EPA groundwater compliance mandates data logging as standard feature for Ogallala Basin retrofit sales. |
Research Methodology
Independent corroboration across pump controller manufacturers, agricultural cooperative procurement officers, and rare earth magnet distributors underwrites the qualitative findings. Primary interviews with wind turbine drivetrain engineers, MNRE subsidy program administrators, and pastoral zone development finance officers combined with secondary validation from customs trade data, MNRE deployment statistics, and EIA agricultural energy consumption surveys. Bottom-up installation tracking and top-down renewable equipment spend analysis triangulate volume estimates.
Comparable-period anchoring to historical MNRE subsidy disbursement cycles and USDA Rural Energy for America Program loan origination patterns shaped the forecast window calibration. The analysis models segmentation across pump configuration type, application duty cycle, rotor orientation technology, and end-user procurement sophistication. CAGRs derive from trend extrapolation adjusted for policy incentive phase-out schedules and aquifer depletion trajectories. Wind resource variability coefficients and hybrid system adoption curves feed projection sensitivity.
Underlying measurement precision varies by segment; subsidized Indian installation data carries tighter precision than informal sub-Saharan deployment tracking. Forecasts reflect documented assumptions on policy continuity and groundwater extraction regulation evolution. Technology substitution risk from solar-only systems and rare earth supply disruption represent primary revision triggers. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Electrostatic Coalescers Market
Pumps and Control Devices
Membrane Pump Market
Pumps and Control Devices
Liquid Dispensing Pump Market
Pumps and Control Devices
Europe Subsea Pumps Market
Pumps and Control Devices
Automatic Water Level Controller Market
Pumps and Control Devices
Europe Centrifugal Pumps Market
Pumps and Control Devices
Latin America Pumps Market
Pumps and Control Devices
Cryogenic Process Pumps Market
Pumps and Control Devices
Marine Pump Market
Pumps and Control Devices
Latin America Centrifugal Pumps Market
Pumps and Control Devices
North America Axial Flow Pump Market
Pumps and Control Devices
Middle East and Africa Positive Displacement Pumps Market
Pumps and Control Devices
Chemical Metering Pumps Market
Pumps and Control Devices
Glycol Pumps Market
Pumps and Control Devices
Turbomolecular Pumps Market
Pumps and Control Devices
Global Pumps Market