
 Circulators Market | 2026-2036
Circulators Market Size, Share, and Industry Trends Forecast 2026-2036
Circulators Market Analytics
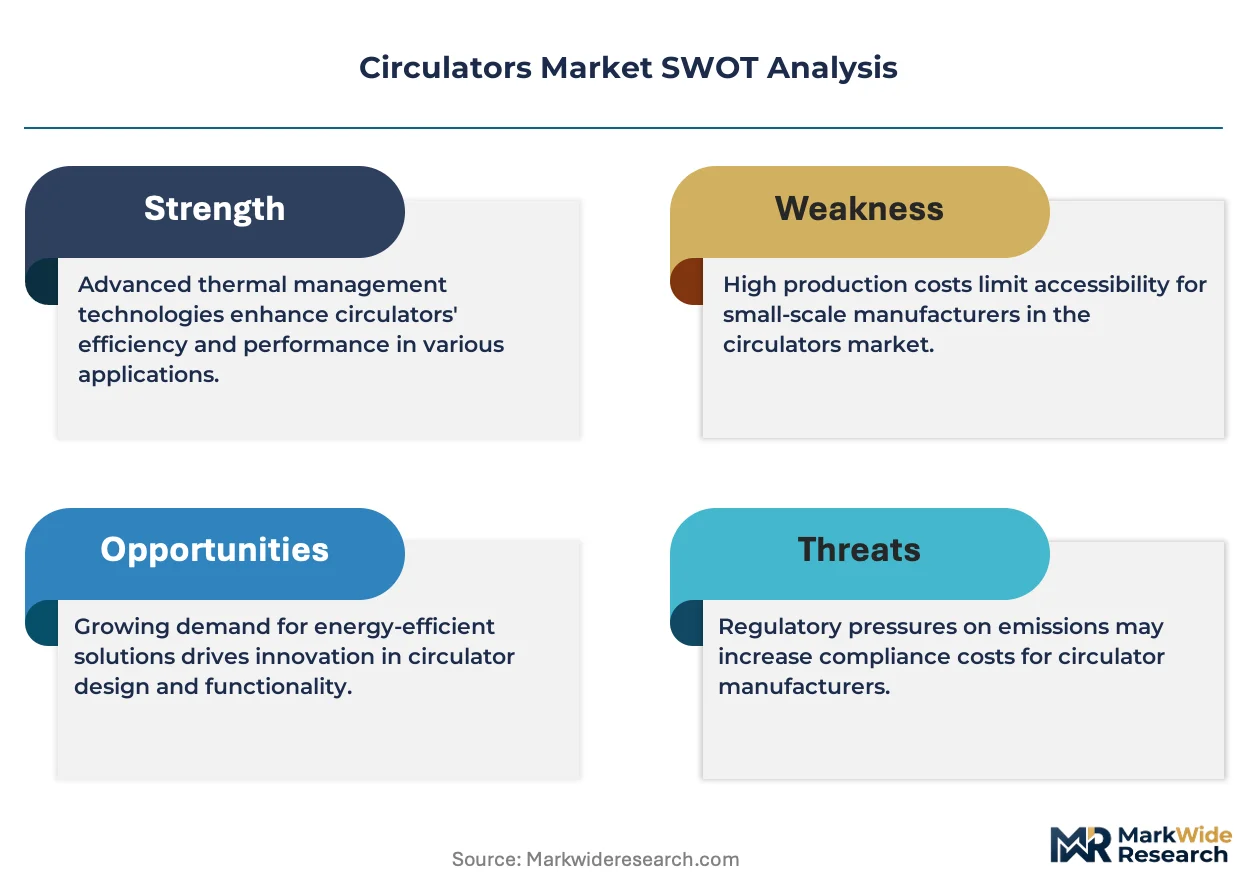
Commercial building operators are redrawing procurement priorities toward energy-efficient retrofit systems over new construction specifications. Grundfos leverages its vertical integration into permanent-magnet motor production to control cost structures across European and North American channels. Wilo SE anchors its position through deep R&D investment in smart pump controls that integrate with building management platforms. Armstrong Fluid Technology differentiates via specialized offerings in high-temperature industrial process applications where reliability premiums command sustained pricing power.
Circulators are sealed pumping devices engineered to move fluids in closed-loop systems at specified head pressures and flow rates, typically constructed with cast iron or stainless steel housings and driven by fractional-horsepower motors to maintain thermal or hydraulic equilibrium. Centrifugal designs dominate volume due to their simple impeller geometry and broad compatibility with water-glycol mixtures, while magnetic drive technology captures expanding share in chemical transfer and pharmaceutical process control where zero-leakage containment is mandatory. Electric motor variants sustain the largest installed base, though pneumatic actuation retains niche dominance in explosion-rated oil and gas field applications where spark hazards prohibit standard electrification.
The European Ecodesign Directive and F-Gas Regulation enforce escalating minimum efficiency indices and refrigerant containment standards that force OEMs to redesign hydraulic sections and motor-drive packages. In the United States, DOE pump efficiency standards and ASHRAE 90.1 building codes constrain catalog offerings and compress margins on non-compliant legacy models. China's GB energy-labeling program and NMPA process-equipment certifications create layered compliance burdens for multinational suppliers serving pharmaceutical and food safety end users. Stakeholders must monitor regulatory divergence between efficiency-first European frameworks and safety-centric North American codes when configuring product portfolios for cross-border deployment.
Market Dynamics
The European Union's Ecodesign Directive is forcing synchronous motor designs out of circulation, compelling manufacturers to reengineer hydraulic sections around permanent-magnet architectures and integrated variable-frequency drives to maintain market access.
Growth Catalysts
- District heating modernization:Germany's industrial corridor is replacing aging wet-rotor units with high-head magnetic drive circulators for thermal distribution network efficiency gains.
- F-Gas Regulation compliance:Refrigeration circuit OEMs are sourcing hermetic circulators with enhanced sealing integrity to meet tightening containment standards across EU member states.
- Permanent-magnet motor adoption:The shift from asynchronous to electronically commutated motors is cutting energy consumption in commercial HVAC retrofit programs.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium and dysprosium processing capacity clusters in China, exposing European and North American motor manufacturers to input cost volatility and geopolitical supply risk.
- Cast iron foundry capacity erosion:Shutdowns of traditional metalcasting operations in the United States and Germany are lengthening lead times for pump housing procurement.
- Technical limitation in high-temperature sealing:Elastomer compatibility above 150°C restricts magnetic drive adoption in certain chemical process applications where packed gland designs persist.
Strategic Opportunities
- Smart building integration:Circulator OEMs embedding BACnet and Modbus protocols can capture specification share in intelligent building management platform rollouts.
- Pharmaceutical process control:Zero-leakage magnetic drive technology is penetrating biologics manufacturing where containment assurance commands premium positioning.
- India's PLI scheme for efficiency equipment:Domestic production incentives for high-efficiency motors create localized manufacturing pathways for multinational pump suppliers.
Industry Challenges
- Electronics-embedded hydraulic engineering talent:The convergence of power electronics and fluid mechanics requires cross-trained design engineers that traditional pump manufacturers struggle to recruit.
- Multi-jurisdiction certification timelines:Securing concurrent UL, CE, and GB mark approvals for new variable-speed product families extends time-to-revenue by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Circulators Market |
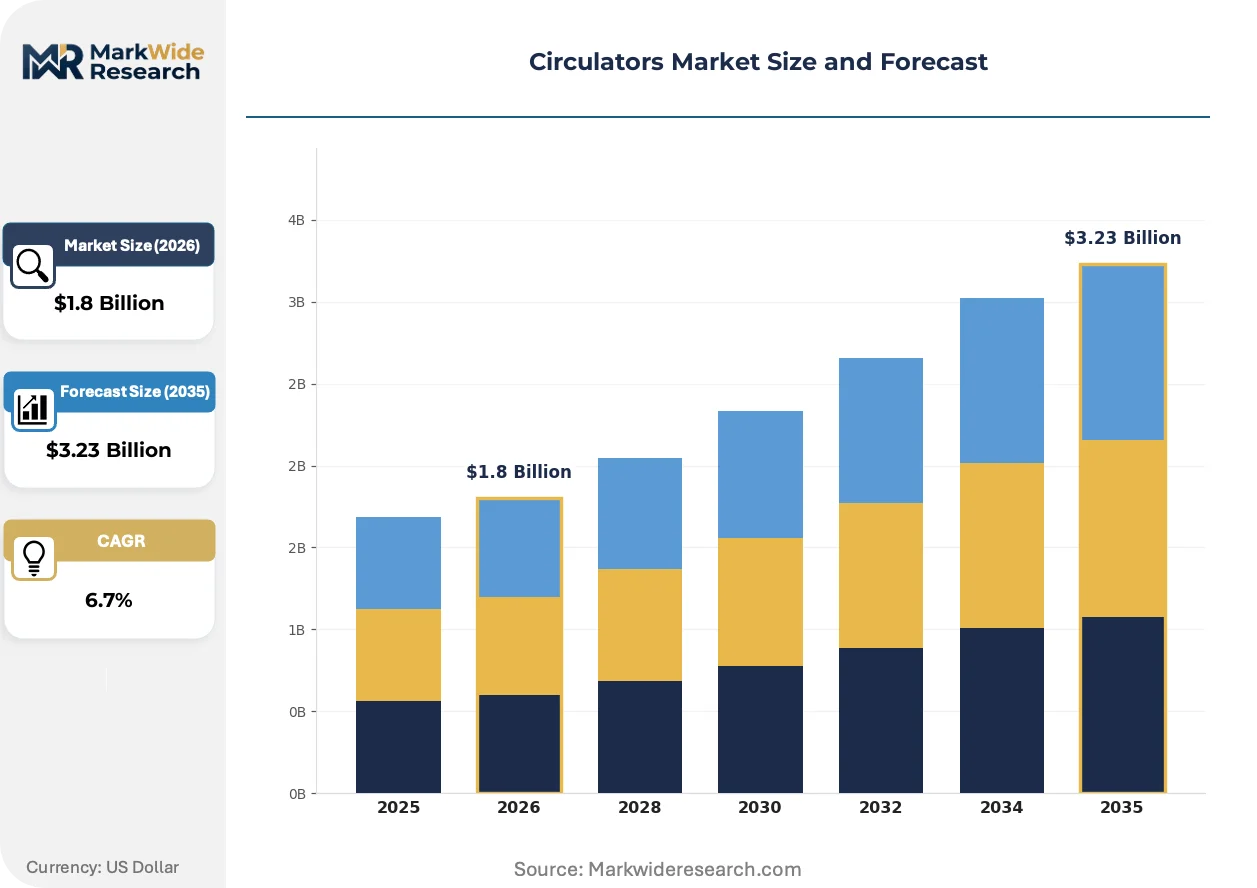
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal, Positive Displacement, Rotary, Gear End User: Pharmaceuticals, Food & Beverage, Oil & Gas, Power Generation Technology: Magnetic Drive, Electric, Pneumatic, Hydraulic Application: Cooling Systems, Process Control, Water Treatment, Chemical Transfer |
| Companies Covered | Grundfos, Wilo SE, Armstrong Fluid Technology, Taco Comfort Solutions, Xylem Inc, KSB, Flowserve, Pentair, Sulzer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Circulators Market Evolving Landscape
Digitalization of fluid systems is collapsing the distinction between mechanical pumping hardware and intelligent edge devices, with sensor-integrated circulators now generating operational data that reshapes service relationships and procurement evaluation criteria.
Permanent-magnet synchronous motors with integrated variable-frequency drives are displacing conventional induction motor configurations across commercial heating and cooling applications. Building operators in Scandinavia and Germany are specifying these units for retrofit installations where energy metering requirements are strict. The technology is displacing legacy fixed-speed catalogs, compressing margins on non-compliant asynchronous models and forcing distributors to clear obsolete inventory.
The EU F-Gas Regulation is tightening refrigerant containment standards for hermetic circulators used in heat pumps and refrigeration circuits. OEMs must redesign sealing systems and validation protocols to maintain market access. Heat pump manufacturers serving residential and light commercial segments are accelerating qualification of compliant circulator suppliers to avoid product line discontinuation.
Outcome-based service contracting is restructuring buyer-supplier relationships in institutional and industrial accounts. Facility managers in healthcare and data center verticals are unbundling equipment purchase from lifecycle performance guarantees, favoring vendors with predictive maintenance platforms. This shift is most pronounced in Germany and the Netherlands where energy service company frameworks are mature.
Circulators Market Segmentation
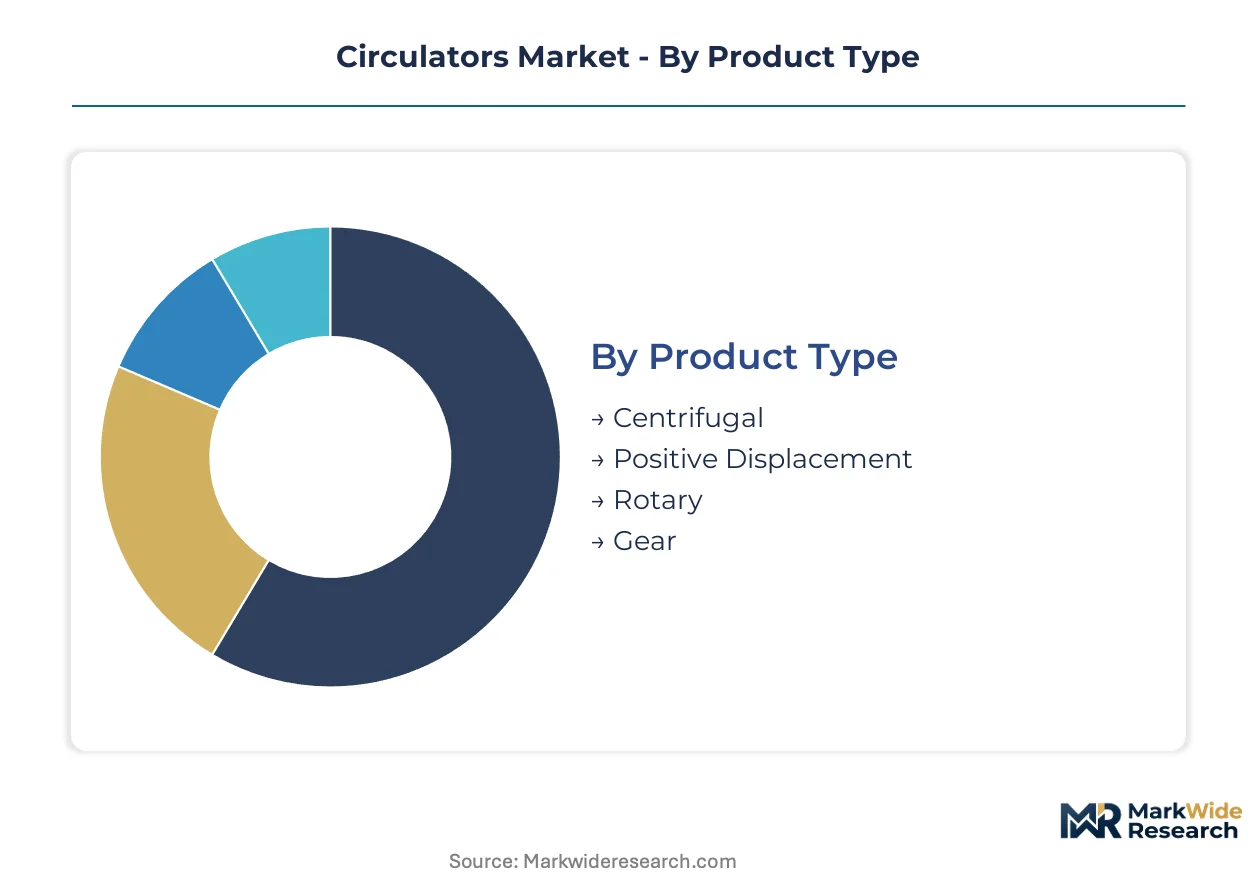
Circulator procurement patterns diverge sharply across product architectures, with permanent-magnet designs capturing retrofit specifications while conventional induction motors defend replacement part revenue. Technology selection increasingly hinges on regulatory efficiency mandates rather than upfront capital cost.
Product Type:
Centrifugal variants dominate domestic replacement cycles across Germany and the Netherlands, while positive displacement and rotary designs serve export-led process industries in chemical manufacturing corridors.
- Centrifugal:Simple impeller geometry enables broad compatibility with water-glycol mixtures across commercial HVAC systems. Demand concentrates in German district heating network upgrades where wet-rotor replacements require minimal piping modification.
- Positive Displacement:Delivers precise volumetric flow control for high-viscosity fluids and slurry handling. Food & beverage processors in Denmark and Sweden specify these units for hygienic transfer applications where shear-sensitive product integrity is paramount.
- Rotary:Lobe and vane configurations handle abrasive media in industrial wastewater streams.
- Gear:Compact displacement pumps serve lubrication circuits and hydraulic power packs.
Centrifugal commands the established base. The steepest expansion runs through positive displacement.
End User:
Cost tier stratification separates premium-specification pharmaceutical installations from price-sensitive power generation procurement, with food & beverage and oil & gas occupying intermediate positions.
- Pharmaceuticals:Zero-leakage containment requirements drive magnetic drive adoption in biologics manufacturing suites. European facilities under EMA oversight demand validated sealing protocols for sterile process loops.
- Food & Beverage:Hygienic design standards and clean-in-place compatibility dominate specification criteria. German dairy processors and Dutch brewing operations prioritize 3-A sanitary certifications for product contact surfaces.
- Oil & Gas:Explosion-rated pneumatic actuation retains dominance in upstream field applications.
- Power Generation:Large-scale cooling water and boiler feed systems emphasize mean-time-between-failure metrics.
Pharmaceuticals anchor premium pricing tiers. Food & beverage is climbing fastest on clean-label manufacturing investments.
Technology:
Volume concentration favors electric motor variants, though magnetic drive and pneumatic technologies defend specialized niches where safety or containment premiums override efficiency considerations.
- Magnetic Drive:Hermetic sealing eliminates mechanical shaft penetration through the pressure boundary. Chemical processors in Germany's industrial corridor specify these units for hazardous fluid transfer under REACH compliance frameworks.
- Electric:Permanent-magnet synchronous motors with integrated variable-frequency drives displace asynchronous configurations. Scandinavian building operators specify electronically commutated variants for strict energy metering retrofit programs.
- Pneumatic:Compressed air actuation persists in explosion-rated oil and gas field environments.
- Hydraulic:Fluid power transmission serves mobile equipment and high-torque industrial positioning.
Electric technology holds the volume base. Magnetic drive is expanding most quickly on containment assurance premiums.
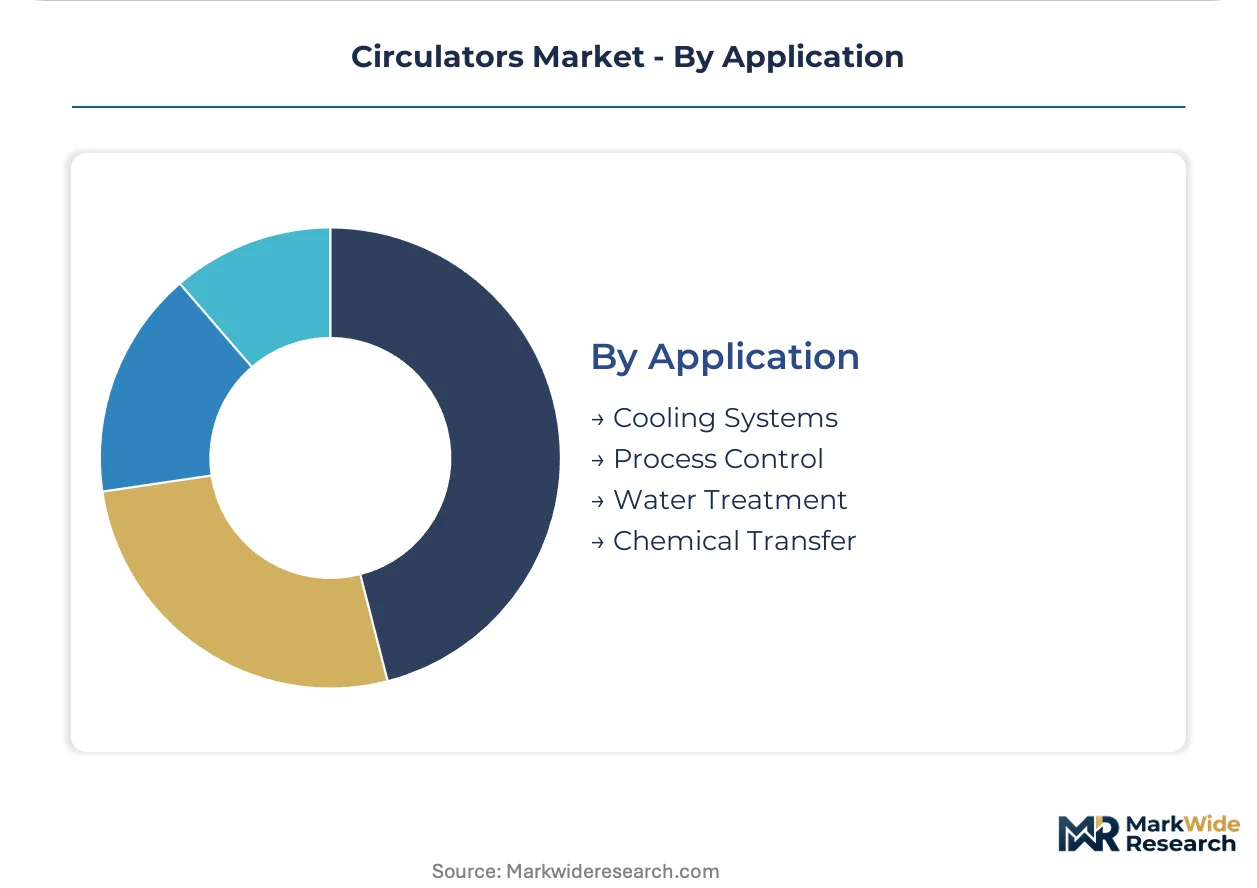
Application:
Customer type differentiation separates institutional facility managers seeking lifecycle performance guarantees from industrial operators prioritizing throughput reliability.
- Cooling Systems:Closed-loop thermal management circuits in data centers and commercial buildings. German and Dutch facility managers specify smart pump controls with BACnet integration for intelligent building platform compatibility.
- Process Control:Precise flow regulation in continuous manufacturing environments. Pharmaceutical bioreactor feed systems demand pulsation-free delivery with validated calibration protocols.
- Water Treatment:Municipal and industrial filtration, disinfection, and desalination circuits.
- Chemical Transfer:Aggressive fluid handling in specialty chemical and petrochemical production.
Cooling systems command the installed base. Process control is gaining share fastest on pharmaceutical capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pump manufacturers export permanent-magnet circulator units to Scandinavian district heating operators and North American commercial retrofit contractors, establishing a transatlantic trade corridor anchored by Hamburg and Rotterdam port logistics.
United States
Commercial building retrofit programs in Chicago and New York Metro are accelerating specification of variable-speed circulator units. DOE pump efficiency standards and ASHRAE 90.1 building codes constrain catalog offerings and compress margins on non-compliant legacy models. Texas and California facility managers prioritize smart pump controls with BACnet integration for intelligent building platform compatibility.
Germany
District heating network modernization across the industrial corridor demands high-head magnetic drive circulators for thermal distribution efficiency gains. The Ecodesign Directive forces synchronous motor designs out of circulation, compelling reengineering around permanent-magnet architectures. Bavarian and North Rhine-Westphalia process industries specify zero-leakage containment for chemical transfer under REACH compliance frameworks.
China
Domestic pharmaceutical and food safety end users create layered compliance burdens for multinational suppliers under GB energy-labeling and NMPA process-equipment certifications. Yangtze River Delta manufacturing clusters absorb rare-earth magnet processing capacity for motor production. Sichuan-Chongqing industrial zones are expanding magnetic drive adoption in biologics manufacturing suites.
India
The PLI scheme for efficiency equipment creates localized manufacturing pathways for high-efficiency motor production. Maharashtra and Gujarat pharmaceutical corridors are qualifying hermetic circulator suppliers for sterile process loops under CDSCO oversight. Karnataka facility managers specify electronically commutated variants for strict energy metering retrofit programs in Bengaluru tech campuses.
Netherlands
Randstad region facility managers unbundle equipment purchase from lifecycle performance guarantees under mature energy service company frameworks. Dutch brewing operations in Brabant prioritize 3-A sanitary certifications for product contact surfaces in clean-in-place compatible installations. Eindhoven Region data centers specify sensor-integrated circulators for operational data generation reshaping procurement evaluation criteria.
Circulators Market Competitive Landscape
Player mix skews toward vertically integrated European specialists with captive permanent-magnet motor production and diversified global fluid-handling conglomerates with broad pump portfolios. Market structure concentrates around three strategic archetypes: integrated motor-pump specialists commanding retrofit specification share, full-line fluid-handling conglomerates leveraging distribution breadth, and process-application specialists defending premium niches through containment assurance. Dominant competitive moves include backward integration into rare-earth magnet supply chains and geographic expansion through localized manufacturing incentives.
Within the integrated specialist tier, Grundfos and Wilo SE exemplify the permanent-magnet motor-pump combination archetype, while Armstrong Fluid Technology occupies a position among process-application specialists. These three anchors represent contrasting strategic postures: Danish and German integrated players with upstream control over motor production, and a North American specialist differentiated through high-temperature industrial positioning rather than scale-driven HVAC volume.
| Leading Market Players |
|---|
| Grundfos |
| Wilo SE |
| Armstrong Fluid Technology |
| Taco Comfort Solutions |
| Xylem Inc |
| KSB |
| Flowserve |
| Pentair |
| Sulzer |
| Others |
Value Network & Pricing Analysis
Permanent-magnet synchronous motor substitution for asynchronous induction designs is redrawing procurement geography toward rare-earth processing clusters in China while compressing margins on legacy motor-pump combinations across European distribution channels. Buyers face stepped cost structures as efficiency mandates eliminate lower-tier alternatives, forcing specification upgrades that tether pricing power to magnet supply security.
Pricing Analysis
Fixed-speed asynchronous circulators, variable-speed permanent-magnet units, and emerging integrated smart pump systems occupy distinct pricing strata with widening gaps between generations. Three-tier pricing structure across premium magnetic drive, standard electronically commutated, and economy induction motor levels reflects certification grade differentiation and BACnet protocol integration. Cost compression in economy-tier induction models is intensifying because Ecodesign Directive phase-outs strand distributor inventory. Pharmaceutical and data center facility managers show lowest price sensitivity due to containment assurance and uptime guarantee requirements, while municipal procurement in price-sensitive Southern European markets resists premium positioning.
Supply Chain Analysis
Inventory buffers for cast iron pump housings have thinned considerably as foundry capacity contracted across Germany and the United States. Neodymium magnet processing concentrates in China, with secondary winding and motor assembly anchored in Germany and Denmark. Raw material dependencies span rare-earth oxides, silicon steel laminations, and specialized elastomer sealing compounds. Single-source vulnerability in Chinese magnet supply exposes European OEMs to export restriction risk. Distribution runs through Hamburg and Rotterdam port logistics to serve Scandinavian district heating contractors and North American commercial retrofit specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The circulators market is experiencing high-growth disruption as permanent-magnet motor technology and EU Ecodesign Directive efficiency mandates simultaneously obsolete legacy product architectures and create premium capture opportunities for compliant suppliers.
For Market Incumbents: Consolidate backward integration into rare-earth magnet supply chains through offtake agreements with Chinese processors or alternative sourcing development in Vietnam and Australia. Acquire distressed foundry capacity in Eastern Europe to secure cast iron housing supply against further German and US capacity erosion. Channel control through exclusive distribution partnerships with energy service companies in the Netherlands and Germany defends retrofit specification share against emerging smart pump competitors.
For New Entrants and Emerging Players: Differentiate on pharmaceutical containment assurance by qualifying magnetic drive designs under EMA sterile process validation protocols, bypassing established HVAC incumbents in the fastest-expanding application vertical. Target India's Maharashtra pharmaceutical corridor through CDSCO-qualification partnerships with domestic engineering procurement contractors. White-space penetration in Bengaluru tech campus energy metering retrofits offers lower competitive density than saturated European district heating markets.
For Investors and Strategic Acquirers: The EU F-Gas Regulation reshapes the acquisition landscape by devaluing non-hermetic circulator portfolios and elevating targets with validated refrigerant containment engineering. Long-term viability favors suppliers with cross-certified variable-speed product families spanning UL, CE, and GB marks, compressing time-to-revenue for multinational deployment. The signal to watch is CDSCO qualification timeline acceleration in India, indicating which multinationals have successfully navigated layered compliance burdens and localized manufacturing incentives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Secures neodymium processing capacity against Chinese export restriction exposure for European motor production. |
| Smart Pump Control Platform Development | Captures BACnet and Modbus integration specifications in German and Dutch intelligent building management rollouts. |
| Pharmaceutical Containment Validation Investment | Unlocks EMA-sterile process loop qualifications commanding premium positioning in biologics manufacturing suites. |
| Localized Manufacturing Under India's PLI Scheme | Establishes domestic high-efficiency motor production pathways for Maharashtra and Gujarat pharmaceutical corridors. |
| Foundry Capacity Acquisition in Eastern Europe | Restores cast iron housing supply security eroded by German and US metalcasting operation shutdowns. |
Research Methodology
Operator-level perspectives from facility managers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this circulators market assessment. Primary interviews with district heating network operators in Germany, pharmaceutical process engineers in Denmark, and commercial building retrofit contractors in the United States combined with secondary validation from SEC 10-K filings, customs trade data, Ecodesign Directive implementation reports, and ASHRAE 90.1 code documentation. Bottom-up unit shipment estimates across centrifugal, positive displacement, and magnetic drive technologies triangulated against top-down market value reconstruction.
Sensitivity analysis tested forecast robustness across rare-earth price volatility scenarios, Ecodesign Directive phase-out acceleration assumptions, and district heating modernization budget trajectories. Segmentation dimensions modeled include product architecture, end-use vertical, motor technology type, and application function across the projection horizon. CAGRs derived from regression analysis of historical efficiency equipment adoption curves, adjusted for regulatory mandate inflection timing and replacement cycle dynamics in commercial HVAC and industrial process control.
Material uncertainties — rare-earth supply disruption, foundry capacity further erosion, and multi-jurisdiction certification timeline extension — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding Ecodesign Directive enforcement consistency and F-Gas Regulation containment standard adoption rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Fluid Transfer System Market
Pumps and Control Devices
India Industrial Pump Market
Pumps and Control Devices
Subsea Pumping System Market
Pumps and Control Devices
Rotary Vane Vacuum Pump Market
Pumps and Control Devices
Southeast Asia Submersible Pumps Market
Pumps and Control Devices
Europe Centrifugal Pumps Market
Pumps and Control Devices
Sea Water Injection Pumps Market
Pumps and Control Devices
Heating Tape Market
Pumps and Control Devices
Seawater Cooling Pumps Market
Pumps and Control Devices
Air Compressor Controller Market
Pumps and Control Devices
Progressing Cavity Pump Market
Pumps and Control Devices
Vane Pump Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
High Power Air Pump Market
Pumps and Control Devices
Pumps and Trigger Spray Market
Pumps and Control Devices
Grease Pump Market