
 Global Smart Pumps Market | 2026-2036
Global Smart Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Pumps Market Foresight
ISO 50001 energy management certification is reorganizing competitive hierarchies in fluid equipment supply. Grundfos Holding A/S leverages its integrated manufacturing footprint to dominate premium centrifugal configurations. Xylem Inc. competes through predictive analytics platforms that anchor recurring service revenue. Emerson Electric Co. differentiates via embedded sensor architectures that extend hardware lifecycle value.
Smart pumps are electronically controlled fluid transfer devices with integrated variable frequency drives, pressure transducers, and digital communication protocols that modulate flow rates against real-time system demand. They eliminate energy losses from throttling valves and fixed-speed motors in continuous-process industries. Centrifugal pumps lead installed base volumes but predictive analytics capabilities capture disproportionate margin pools through software subscriptions. IoT integration is the fastest-expanding technology layer as municipal utilities mandate remote diagnostics for critical infrastructure.
The EPA sets minimum efficiency standards under the Clean Water Act that govern municipal procurement specifications, while the EU F-Gas Regulation restricts refrigerant-based sealing technologies in certain pump categories. China's GB standards through SAMR enforce domestic energy labeling that conditions market access for imported equipment. Stakeholders must monitor how fragmented national certification regimes reshape sourcing strategies and localization requirements.
Market Dynamics
Variable frequency drive integration with cloud-based diagnostics is compressing equipment replacement cycles while municipal procurement specifications now mandate predictive maintenance capabilities as baseline requirements.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant restrictions on sealing technologies are accelerating replacement of legacy pump infrastructure across European water treatment facilities.
- IoT-enabled condition monitoring:Real-time vibration analysis and energy consumption tracking are becoming standard in German municipal retrofits.
- China's GB standards through SAMR:Domestic energy labeling requirements are conditioning market access and driving localization of smart pump manufacturing.
Market Restraints
- Semiconductor supply concentration:Variable frequency drive production depends on chip fabrication concentrated in Taiwan and South Korea.
- Copper and rare earth magnet volatility:Permanent magnet motor costs fluctuate with dysprosium and neodymium price swings.
- Legacy infrastructure lock-in:Existing fixed-speed motor installations in US municipal networks create high switching costs.
Strategic Opportunities
- India's AMRUT 2.0 scheme:Urban water mission funding is creating procurement windows for intelligent pumping stations in tier-2 cities.
- Predictive analytics software layering:Recurring revenue from pump health monitoring is displacing one-time hardware margins.
- Edge computing convergence:On-device AI inference is enabling real-time flow optimization without cloud dependency.
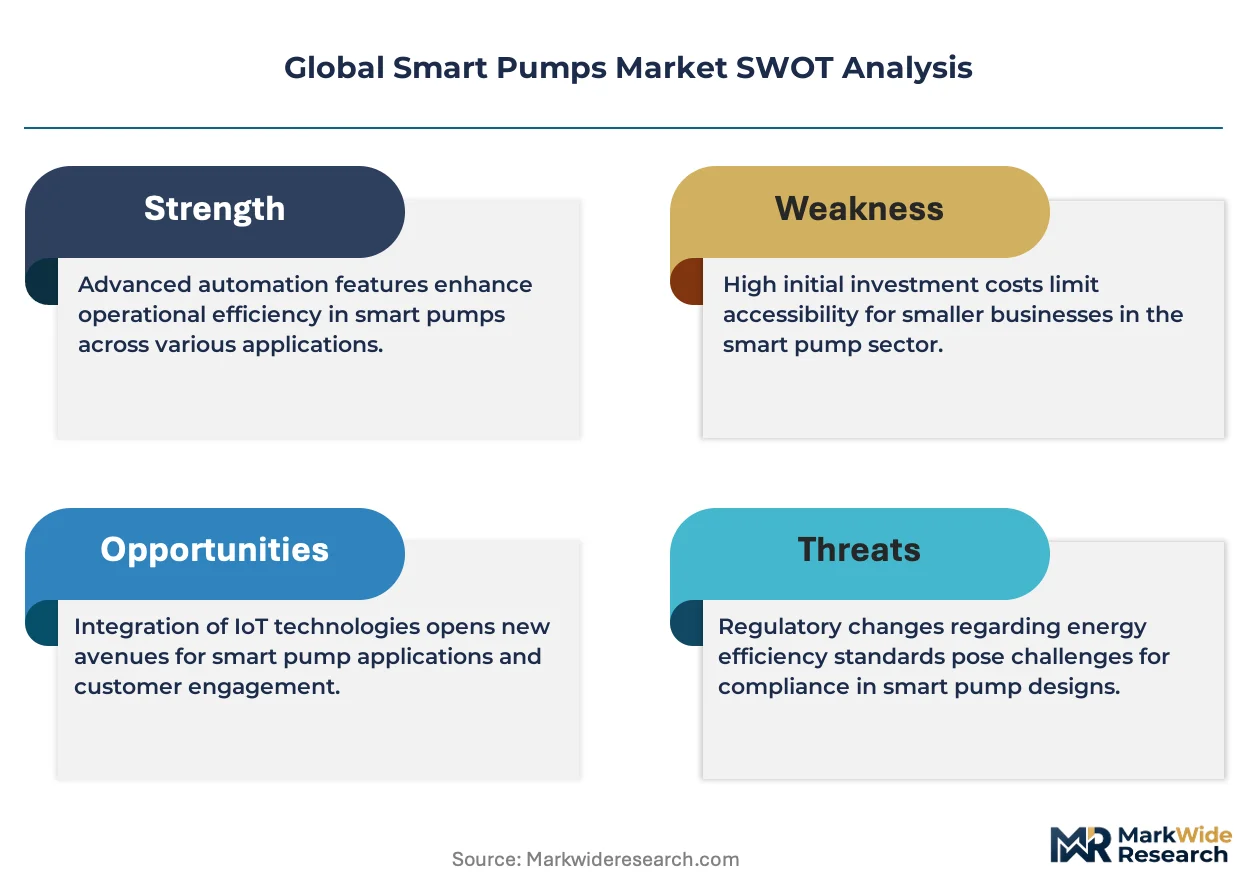
Industry Challenges
- ISO 50001 certification timelines:Energy management system audits create 12-18 month sales cycle extensions for industrial accounts.
- Cyber-physical security integration:IT-OT convergence demands skills scarce in traditional pump OEM engineering teams.
- Multi-protocol interoperability:BACnet, Modbus, and proprietary fieldbus standards fragment system integration requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Pumps Market |
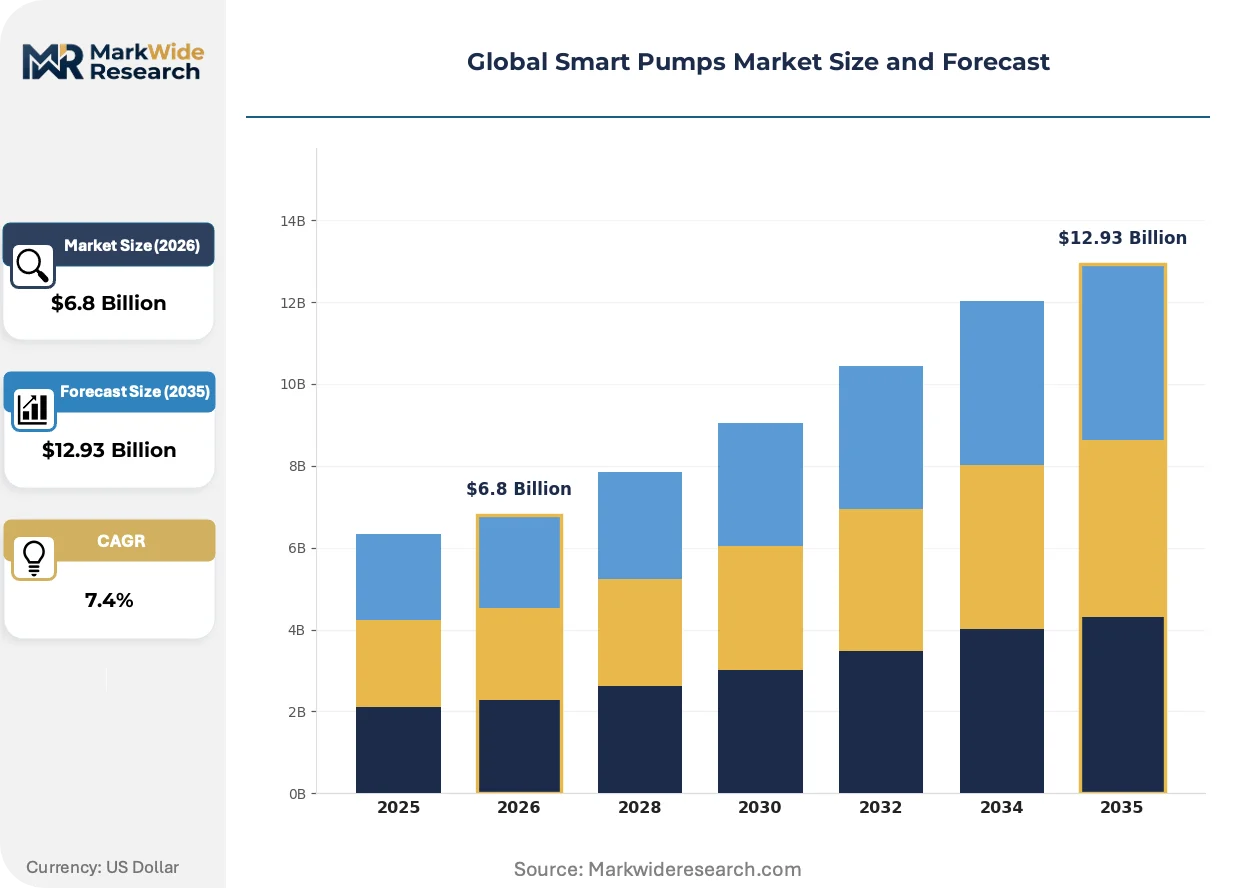
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peristaltic Pumps, Diaphragm Pumps, Centrifugal Pumps, Gear Pumps, Piston Pumps Technology: IoT Integration, Wireless Communication, Embedded Sensors, Remote Monitoring, Predictive Analytics Application: Water Treatment, Chemical Processing, Pharmaceuticals Manufacturing, Food & Beverage Production, Oil & Gas Extraction End User Industry: Municipal Utilities, Chemical Plants, Biopharmaceutical Firms, Food Processing Companies, Petroleum Operators |
| Companies Covered | Grundfos Holding A/S, Xylem Inc., Sulzer Ltd., Flowserve Corporation, Wilo SE, ITT Inc., KSB SE & Co. KGaA, Emerson Electric Co., ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Pumps Market Shifts & Advancements
Digital twin modeling is compressing commissioning timelines while embedded sensor architectures are extending hardware lifecycle value through condition-based maintenance contracts.
Magnetic bearing technology is eliminating mechanical seal wear and enabling dry-running capability in wastewater applications. Municipal utilities in Denmark and the Netherlands are specifying magnetic levitation pumps for critical lift stations. This frictionless architecture is displacing conventional oil-lubricated bearing systems in high-duty-cycle installations.
EPA energy efficiency mandates under the Clean Water Act are tightening minimum performance specifications for municipal procurement. Equipment suppliers must now submit certified test data to the Department of Energy compliance database. US water authorities are responding by bundling smart pump retrofits with SCADA upgrades to meet integrated efficiency targets.
Performance-based service agreements are replacing traditional capital purchase models in industrial water management. End-users in chemical processing and food manufacturing now contract for guaranteed flow rates and energy consumption ceilings. This shift is most pronounced in Germany where EPC firms bundle pumping infrastructure with 10-year operational guarantees.
Global Smart Pumps Market Segmentation
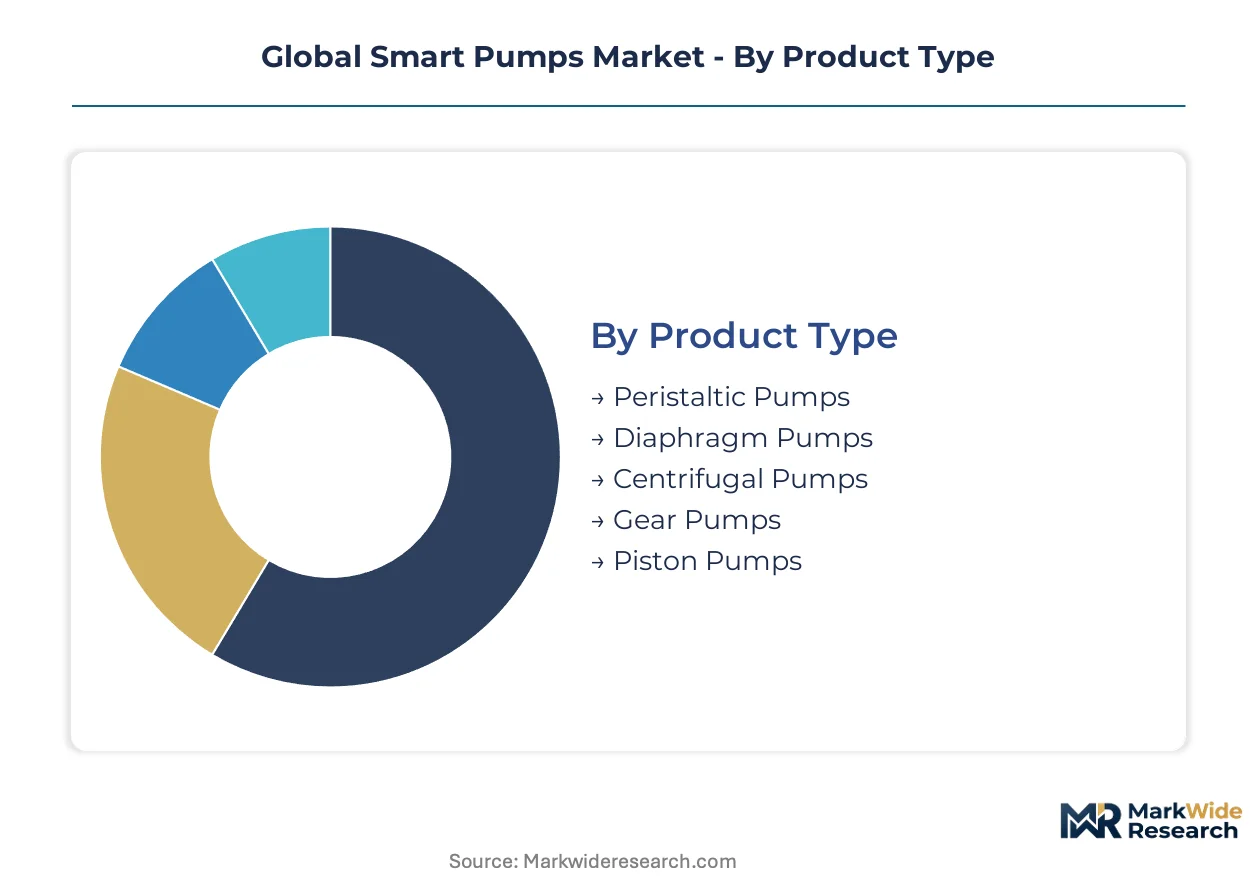
Smart pump segmentation reveals how regulatory pressure and application specificity fragment procurement specifications across jurisdictions. Equipment suppliers must align product architectures with distinct compliance regimes, energy efficiency tiers, and connectivity standards that vary by end-use environment.
Product Type:
EPA energy efficiency mandates under the Clean Water Act and EU F-Gas refrigerant restrictions create divergent equipment specifications across centrifugal and positive displacement categories.
- Centrifugal Pumps:Radial flow impeller designs with integrated variable frequency drives dominate municipal water distribution networks. German utilities specify these configurations for AMRUT-equivalent retrofits requiring ISO 50001-aligned energy performance certification.
- Peristaltic Pumps:Hose compression mechanisms eliminate product contamination in pharmaceutical fluid transfer. Biopharmaceutical facilities in Switzerland and the United States specify these for GMP-compliant batch processing where seal integrity is critical.
- Diaphragm Pumps:Air-operated double-diaphragm architectures handle abrasive slurries in chemical processing plants.
- Gear Pumps:Positive displacement meshing delivers precise volumetric flow for viscous food processing applications.
- Piston Pumps:Reciprocating plunger designs generate high-pressure output for oilfield injection operations.
Centrifugal pumps handle the majority of throughput; peristaltic pumps are gaining share fastest in regulated pharmaceutical environments.
Technology:
Cost tier stratification separates premium predictive analytics platforms from baseline connectivity modules in municipal procurement frameworks.
- IoT Integration:Cloud-connected pump controllers with MQTT protocols enable centralized fleet management across distributed water treatment assets. Chinese GB standards through SAMR mandate this capability for imported equipment market access.
- Predictive Analytics:Machine learning algorithms trained on vibration spectra and thermal signatures forecast bearing failures before catastrophic shutdown. German EPC firms bundle these subscriptions with 10-year operational guarantees in chemical processing contracts.
- Embedded Sensors:MEMS accelerometers and pressure transducers provide real-time condition data at the device edge.
- Remote Monitoring:SCADA-integrated dashboards aggregate pump performance across municipal lift station networks.
- Wireless Communication:LoRaWAN and cellular modems eliminate cabling infrastructure in retrofit installations.
IoT integration commands the widest installed base; predictive analytics exhibits the steepest margin expansion trajectory as recurring revenue displaces hardware sales.
Application:
Volume concentration in water treatment reflects municipal infrastructure age and regulatory enforcement intensity across national jurisdictions.
- Water Treatment:Raw water intake, filtration backwash, and disinfection chemical dosing depend on flow-modulating pump systems. US water authorities bundle smart retrofits with SCADA upgrades to meet EPA integrated efficiency targets under the Clean Water Act.
- Pharmaceuticals Manufacturing:WFI (water for injection) and CIP (clean-in-place) systems demand sanitary pump configurations with full material traceability. FDA validation requirements drive specification rigor in US and EU manufacturing facilities.
- Chemical Processing:Corrosive fluid handling and precise additive injection shape pump material selection.
- Food & Beverage Production:Hygienic design standards govern CIP-compatible pump architectures in dairy and beverage plants.
- Oil & Gas Extraction:Artificial lift and injection applications require high-pressure tolerant configurations.
Water treatment absorbs the greatest equipment volume; pharmaceuticals manufacturing shows the most rapid specification escalation as quality regulations tighten.
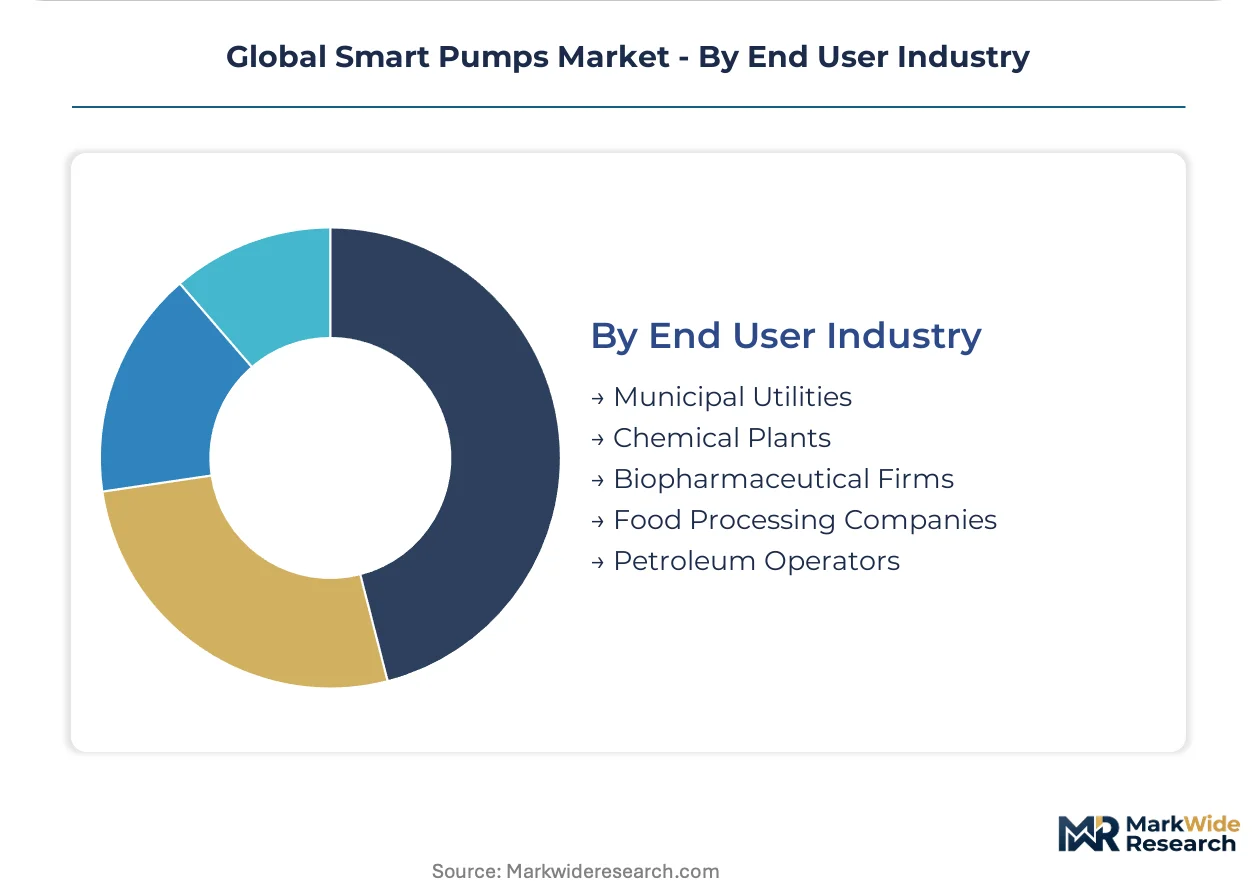
End User Industry:
Customer type determines procurement authority structure, with municipal utilities favoring open tender processes and industrial operators negotiating direct OEM relationships.
- Municipal Utilities:Public water authorities issue bonded financing for infrastructure modernization with 20-30 year asset lifecycles. India's AMRUT 2.0 scheme is creating procurement windows for intelligent pumping stations in tier-2 cities.
- Biopharmaceutical Firms:Quality assurance departments specify equipment with full validation documentation packages. FDA and EMA inspection readiness drives premium positioning for compliant pump suppliers.
- Chemical Plants:Process engineering teams prioritize chemical compatibility and energy consumption metrics.
- Food Processing Companies:Operations managers balance sanitation requirements against total cost of ownership.
- Petroleum Operators:Production engineers select pumps for harsh environment durability and remote operability.
Municipal utilities represent the largest addressable equipment base; biopharmaceutical firms are expanding most quickly as cell and gene therapy manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal utilities in Germany, China, and the United States account for the dominant share of procurement volume as infrastructure age and regulatory enforcement intensity concentrate buyer authority in these jurisdictions.
United States
EPA energy efficiency mandates under the Clean Water Act govern municipal procurement specifications for water treatment facilities. US water authorities bundle smart pump retrofits with SCADA upgrades to meet integrated efficiency targets. The Great Lakes region and California Central Valley show concentrated retrofit activity as aging networks face replacement deadlines.
Germany
ISO 50001 energy management certification reorganizes competitive hierarchies for industrial fluid equipment supply. The EU F-Gas Regulation restricts refrigerant-based sealing technologies in certain pump categories. Municipal utilities in the Ruhr industrial cluster and Bavarian manufacturing belt specify predictive maintenance capabilities as baseline requirements.
China
GB standards through SAMR enforce domestic energy labeling that conditions market access for imported equipment. The country's dual carbon goals accelerate replacement of fixed-speed motor installations in municipal networks. Yangtze River Delta cities including Shanghai and Suzhou drive procurement volume for intelligent pumping stations.
India
AMRUT 2.0 scheme funding creates procurement windows for intelligent pumping stations in tier-2 cities. The Central Electricity Authority mandates efficiency standards for municipal water infrastructure. Maharashtra and Gujarat industrial corridors show accelerating demand as urban water missions expand beyond metropolitan centers.
Denmark
Magnetic bearing technology specifications are tightening for critical lift stations in wastewater applications. Danish municipal utilities lead European adoption of frictionless pump architectures. Copenhagen's integrated water management district serves as a reference site for condition-based maintenance contract structures.
Global Smart Pumps Market Competitive Landscape
Player mix skews toward integrated manufacturing conglomerates with captive drive technology and specialized fluid equipment vendors with predictive analytics platforms. Market structure exhibits tiered concentration with premium centrifugal configurations dominated by vertically integrated European and North American firms. Two strategic archetypes prevail: hardware-integrated manufacturers leveraging economies of scale in motor and impeller production, and software-anchored specialists capturing recurring revenue through pump health monitoring subscriptions. Dominant competitive moves include strategic partnerships between pump OEMs and cloud infrastructure providers, plus geographic expansion through localized assembly facilities to satisfy national certification requirements.
Within the integrated manufacturing tier, Grundfos Holding A/S and KSB SE & Co. KGaA exemplify European conglomerates with captive supply chains spanning motor winding to cloud-connected controllers. Xylem Inc. occupies a position representing the analytics-anchored archetype, with its US-based corporate structure indicating North American headquarters concentration. Emerson Electric Co. sits within the industrial automation conglomerate category, its electric equipment heritage suggesting embedded sensor architecture capabilities. These three firms collectively illustrate how competitive positioning fragments across hardware integration depth versus software service intensity.
| Leading Market Players |
|---|
| Grundfos Holding A/S |
| Xylem Inc. |
| Sulzer Ltd. |
| Flowserve Corporation |
| Wilo SE |
| ITT Inc. |
| KSB SE & Co. KGaA |
| Emerson Electric Co. |
| ABB Ltd. |
| Others |
Supply & Pricing Matrix
Long-term service contracts with copper and rare earth indexation clauses lock in component access while capping margin volatility for pump OEMs serving municipal utilities. These arrangements tie hardware pricing to London Metal Exchange benchmarks and dysprosium spot markets, transferring commodity risk to end-users through adjustable maintenance fees.
Pricing Analysis
Cost-plus contracts with quarterly rare earth indexation dominate municipal procurement frameworks above ten thousand units annually. Three-tier pricing structure across premium, standard, and economy levels separates ISO 50001-certified configurations from baseline efficiency tiers and non-connected legacy replacements. Cost compression in economy-tier centrifugal units is intensifying because Chinese GB standards through SAMR accelerate localization requirements. Municipal utilities in Germany exhibit lowest price sensitivity due to bonded financing structures, while tier-2 Indian cities under AMRUT 2.0 face strict capital expenditure ceilings.
Supply Chain Analysis
Inventory buffers for variable frequency drive controllers stretched to twenty-six weeks following semiconductor allocation constraints in Taiwan and South Korea. Permanent magnet motor production draws from Chinese rare earth processing and Malaysian magnet fabrication, with copper winding supply anchored in Chilean concentrate and German wire drawing. Single-source vulnerability concentrates in Taiwan semiconductor foundries serving VFD chip demand. Distribution runs through authorized OEM service centers and EPC contractor direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive analytics software subscriptions are expanding faster than hardware shipments as municipal utilities mandate remote diagnostics. This service-attach layer converts capital expenditure into operational budgets while generating recurring revenue streams.
For Market Incumbents: Consolidate sensor architecture capabilities through captive MEMS accelerometer sourcing or exclusive foundry partnerships. Lock in municipal fleet management contracts with ten-year operational guarantees before EPC firms bundle competing offerings. Threat substitution from edge-computing startups with on-device AI inference demands rapid certification investment in ISO 50001-aligned energy management systems. For New Entrants and Emerging Players: Lead with wireless retrofit modules for legacy fixed-speed installations in US municipal networks where switching costs block full system replacement. Target India's tier-2 cities under AMRUT 2.0 scheme funding where specification standards remain fluid. Go-to-market through EPC contractor partnerships rather than direct utility sales cycles. For Investors and Strategic Acquirers: Capital is best deployed toward software-anchored specialists with established predictive maintenance subscription bases rather than hardware-integrated manufacturers facing commodity margin compression. Long-term viability over the next decade hinges on recurring revenue share exceeding forty percent of total contract value. Watch for inflection when EPA mandates predictive capability as baseline municipal procurement requirement.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Analytics Platform Launch | Machine learning subscriptions displace one-time hardware margins in German chemical processing contracts. |
| Localized Assembly Facility Expansion | Chinese GB standards through SAMR condition market access on domestic manufacturing presence. |
| Magnetic Bearing Technology Licensing | Danish wastewater utilities specify frictionless architectures for critical lift station reliability. |
| Long-term Service Agreement Restructuring | Performance-based contracts with guaranteed energy ceilings capture municipal operational budgets. |
| Edge Computing Module Integration | On-device AI inference enables real-time flow optimization without cloud dependency in remote installations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA compliance databases, EU F-Gas regulatory filings, SAMR certification registries, and municipal procurement records. Interviews with water utility engineering directors, EPC contractor procurement leads, pump OEM aftermarket service heads, and industrial plant maintenance managers informed demand-side assumptions. Bottom-up unit shipment estimates triangulated against top-down energy efficiency mandate penetration models.
Segmentation dimensions modeled include pump architecture type, connectivity technology tier, end-use application environment, and customer procurement authority structure across the analysis window. CAGRs derived from regression analysis of historical efficiency standard adoption curves and infrastructure replacement cycle timing. Forecast inputs incorporate rare earth price volatility scenarios and semiconductor allocation constraint persistence.
Forecasts assume regulatory continuity in EPA Clean Water Act enforcement, EU F-Gas refrigerant restrictions, and Chinese GB standard implementation; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Glycol Pumps Market
Pumps and Control Devices
Residential Pumps Market
Pumps and Control Devices
Industrial Pumps Market
Pumps and Control Devices
Centrifugal Pump Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
India Industrial Pump Market
Pumps and Control Devices
API 610 Pumps Market
Pumps and Control Devices
Worm Pumps Market
Pumps and Control Devices
Membrane Pump Market
Pumps and Control Devices
Global Hydrocyclone Market
Pumps and Control Devices
Plunger Pumps Market
Pumps and Control Devices
Rental Industrial Pump Market
Pumps and Control Devices
Southeast Asia Submersible Pumps Market
Pumps and Control Devices
Hydraulic Dosing Pump Market
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Water Pump Market