
 Global Industrial Submersible Pumps Market | 2026-2036
Global Industrial Submersible Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Submersible Pumps Market Foresight
EU F-Gas Regulation is consolidating the cost-of-entry calculus for pump manufacturers serving European industrial cooling and refrigeration applications. Grundfos Holding A/S leverages its integrated motor-pump manufacturing footprint to sustain margin resilience across energy-efficiency tiers. Xylem Inc. anchors its competitive position through digital monitoring platforms that extend service revenue streams beyond hardware sales. KSB SE & Co. KGaA dominates large-scale vertical turbine installations for municipal water authorities navigating stricter leakage targets.
Industrial submersible pumps are sealed motor-pump units designed to operate fully immersed in fluid, typically handling flow rates from 10 to 5,000 cubic meters per hour at heads exceeding 800 meters, with cast iron or stainless steel housings protecting against corrosion in aggressive media. Their primary purpose is to transfer liquids from deep wells, sumps, or submerged reservoirs without suction lift limitations. Radial flow configurations capture the deepest margin pools in mining dewatering applications where abrasion resistance commands premium pricing. Electric motor driven technology leads unit shipments while solar powered variants represent the fastest-expanding installation category in off-grid agricultural and remote oil field settings.
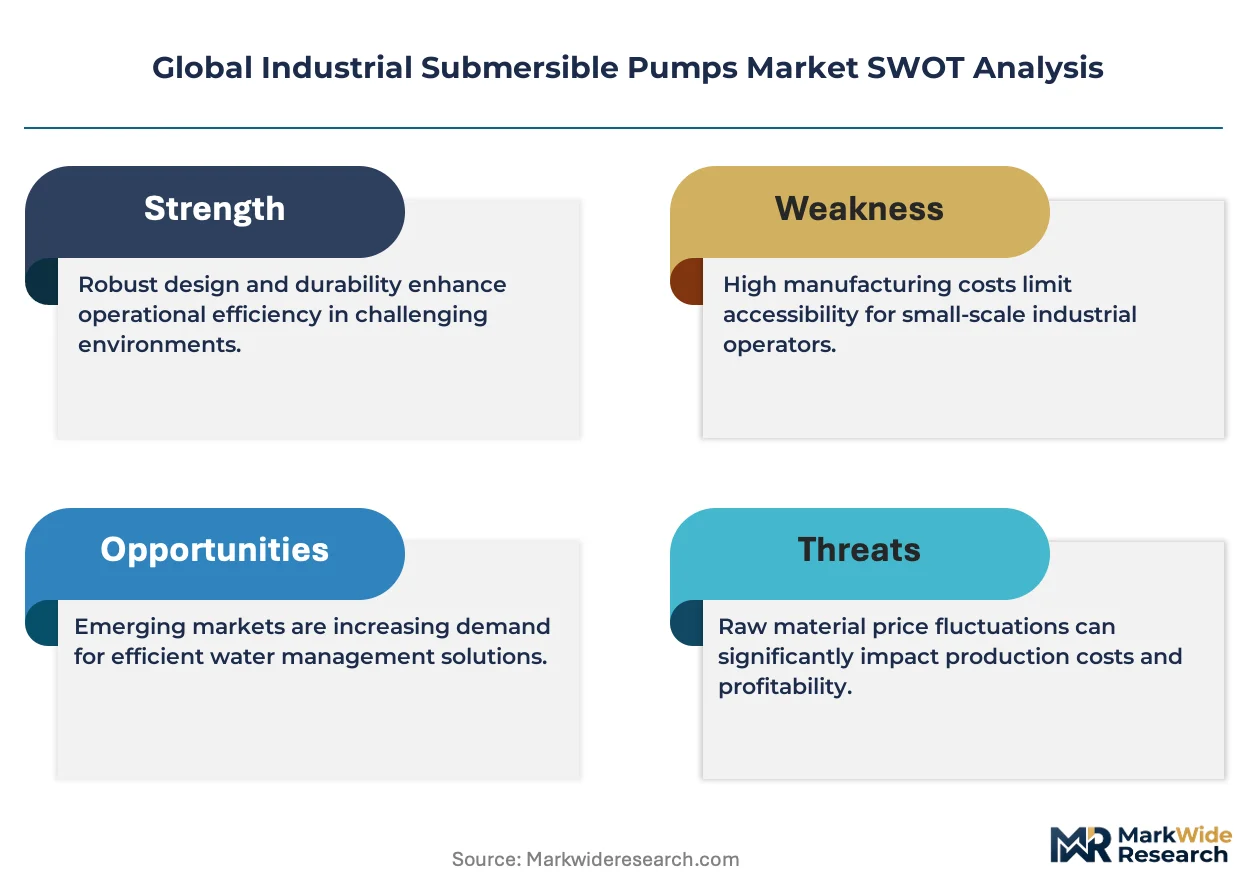
EPA effluent guidelines under the Clean Water Act shape product specifications for US wastewater treatment deployments, while REACH compliance in Europe restricts seal and coating chemistries available to manufacturers. China's MEE enforces groundwater extraction permits that directly constrain pump sizing and duty cycles in industrial zones. Stakeholders must monitor how fragmented national efficiency testing protocols affect cross-border certification costs and service interoperability.
Market Dynamics
The EU Urban Wastewater Treatment Directive's tightened discharge standards are forcing utilities across Germany, France, and Italy to replace aging surface-mounted installations with sealed submersible systems capable of handling variable solids loads and corrosive effluent streams.
Growth Catalysts
- Solar photovoltaic integration:Off-grid agricultural networks in Kenya and rural India are bypassing diesel dependency through DC-powered submersible arrays paired with variable frequency drives.
- REACH-compliant seal chemistries:European pump manufacturers are reformulating elastomer compounds to eliminate restricted phthalates and heavy metal stabilizers in potable water applications.
- Mining dewatering intensity:Chilean and Peruvian copper operations are deepening pit excavations beyond 800 meters, necessitating higher-head radial flow configurations with abrasion-resistant hardened impellers.
Market Restraints
- Copper and rare earth magnet volatility:Permanent magnet motor costs fluctuate with Chinese export quota adjustments, compressing margins on premium efficiency tiers.
- Cast iron foundry concentration:Seventy percent of corrosion-resistant housing production clusters in Shandong and Hebei provinces, creating single-source vulnerability for Western OEMs.
- Technical limitation in high-temperature media:Standard insulation classes degrade above 140°C, excluding submersible designs from geothermal brine extraction and thermal power plant condensate handling.
Strategic Opportunities
- Indonesian archipelago water security:Jakarta's coastal groundwater subsidence crisis is accelerating municipal investment in deep-well submersible infrastructure with saltwater intrusion barriers.
- IIoT-enabled predictive maintenance:Vibration and temperature sensors embedded in motor windings are converging with cloud analytics platforms to monetize uptime guarantees.
- US Inflation Reduction Act incentives:Domestic content bonuses for federally funded water infrastructure are reshoring assembly operations to Texas and Ohio manufacturing corridors.
Industry Challenges
- Submersible motor rewind specialization:Declining apprenticeship pipelines in electromechanical repair are extending field service response times for critical municipal installations.
- IEC 60034-2-3 efficiency testing harmonization:Disparate national protocols for submersible motor rating points are inflating certification costs for multi-territory product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Submersible Pumps Market |
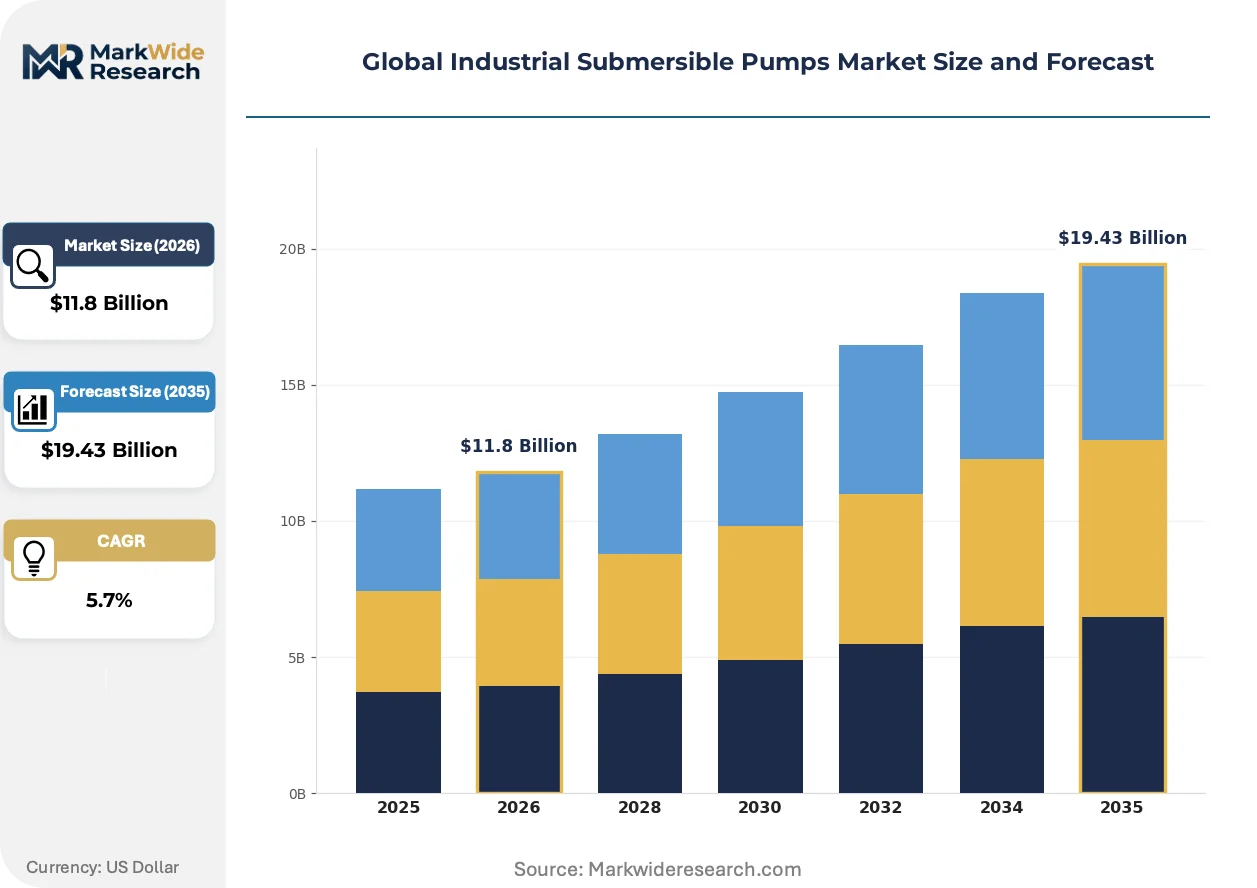
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $19.43 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial Flow, Mixed Flow, Radial Flow, Vertical Turbine Technology: Hydraulic, Electric Motor Driven, Diesel Engine Driven, Solar Powered Application: Water & Wastewater Treatment, Mining Operations, Oil & Gas Extraction, Irrigation Systems, Chemical Processing End User: Power Plants, Construction Firms, Agricultural Operators, Marine Facilities |
| Companies Covered | Xylem Inc., Grundfos Holding A/S, KSB SE & Co. KGaA, Sulzer Ltd., Atlas Copco AB, Wilo SE, Flowserve Corporation, Ebara Corporation, Weir Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Submersible Pumps Market Shifts & Advancements
Digital twin technology and advanced material science are compressing product development cycles while redefining performance benchmarks across municipal, agricultural, and extractive end-uses.
Permanent magnet synchronous motor technology is integrating rare-earth rotor designs with sensorless vector control to eliminate mechanical seals in high-head applications. Mining operators in Western Australia and the Atacama Desert are deploying these configurations for continuous-duty dewatering at depths exceeding conventional induction motor thermal limits. The technology is integrating efficiency gains of eight to twelve percentage points against legacy squirrel-cage alternatives, forcing incumbent manufacturers to reengineer stator lamination geometries.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling seal manufacturers to validate fluorocarbon-free alternatives for wastewater exposure. German pump OEMs face twelve-to-eighteen-month requalification timelines for new elastomer compounds in potable water contact applications. Municipal procurement specifications in Denmark and the Netherlands now mandate full material disclosure downstream to coating and gasket tier-two suppliers.
Performance-based service contracting is displacing traditional unit-sale-plus-spares models among North American municipal water authorities. Chicago, Houston, and Phoenix utilities now structure ten-to-fifteen-year agreements around guaranteed availability metrics rather than capital equipment ownership. The shift concentrates vendor risk in remote monitoring infrastructure and field service density, favoring suppliers with established regional parts depots over import-dependent competitors.
Global Industrial Submersible Pumps Market Segmentation
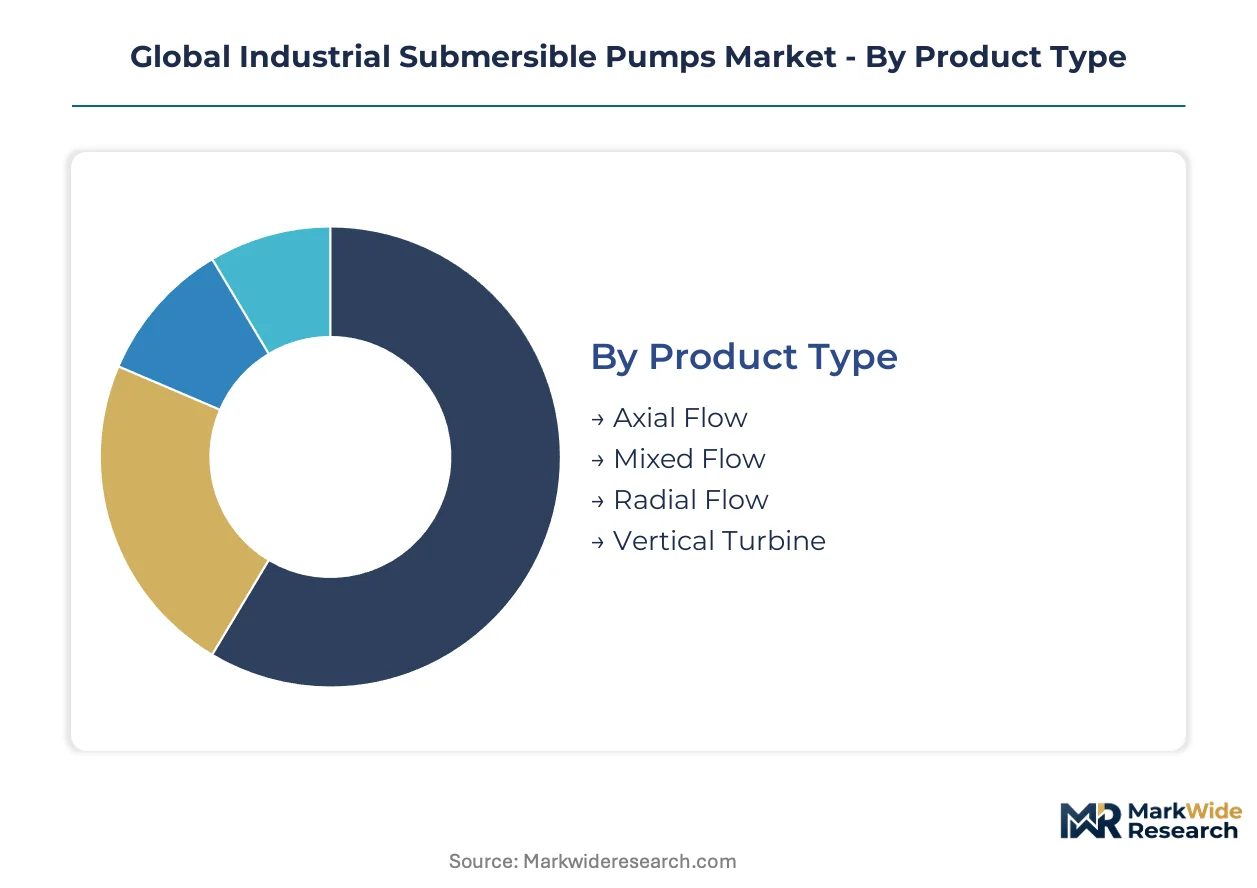
Industrial submersible pumps serve radically different duty cycles across extraction, treatment, and distribution networks. Product architecture, power source, and end-use severity create distinct margin pools that manufacturers must navigate simultaneously.
Product Type:
Impeller geometry dictates where each configuration commands pricing power versus commodity competition.
- Radial Flow:High-head designs with enclosed impellers handle abrasive slurries in Chilean copper pit dewatering beyond 800 meters depth. Mining operators pay premiums for hardened metallurgy that extends mean time between overhauls in continuous-duty cycles.
- Vertical Turbine:Multi-stage bowl assemblies serve Indonesian municipal deep-well installations combating Jakarta's saltwater intrusion. Procurement specifications increasingly mandate stainless steel construction for potable water contact.
- Axial Flow:Low-head high-volume propeller designs dominate flood control and stormwater bypass systems.
- Mixed Flow:Intermediate geometries balance head and flow for agricultural drainage and raw water intake structures.
Radial flow leads volumes today; vertical turbine is gaining share fastest.
Technology:
Power source selection separates operating cost predictability from capital expenditure sensitivity among buyers.
- Electric Motor Driven:Squirrel-cage induction and permanent magnet synchronous configurations handle the majority of installed base across German wastewater utilities and US municipal water authorities. Efficiency regulations under IEC 60034-2-3 are forcing stator redesigns that favor integrated motor-pump OEMs.
- Solar Powered:DC submersible arrays paired with variable frequency drives are displacing diesel gensets across Kenyan agricultural networks and rural Indian irrigation cooperatives. Capital subsidies from national renewable energy agencies are compressing payback periods below three years.
- Hydraulic:Turbine-driven units operate in explosive atmospheres where electrical ignition risks preclude standard motors.
- Diesel Engine Driven:Portable configurations serve emergency dewatering and construction site dewatering where grid connectivity is absent.
Electric motor driven leads volumes today; solar powered climbs the fastest.
Application:
Fluid characteristics and regulatory exposure determine specification stringency and service attach rates.
- Mining Operations:Abrasion-resistant radial flow pumps with tungsten carbide impeller coatings manage acidic pit dewatering in Western Australian iron ore and Atacama Desert copper extraction. Depth progression beyond conventional limits is accelerating permanent magnet motor adoption.
- Water & Wastewater Treatment:Sealed submersible designs with grinder mechanisms handle variable solids loads under tightened EU Urban Wastewater Treatment Directive standards across German, French, and Italian utilities.
- Oil & Gas Extraction:ESP systems handle artificial lift in mature onshore fields and offshore platform sumps.
- Irrigation Systems:Solar-powered borehole pumps serve groundwater-dependent agricultural zones in India where extraction permits are tightening.
- Chemical Processing:Hastelloy and titanium-housed units resist corrosive process fluids in specialty manufacturing.
Mining operations lead volumes today; water & wastewater treatment is expanding most quickly.
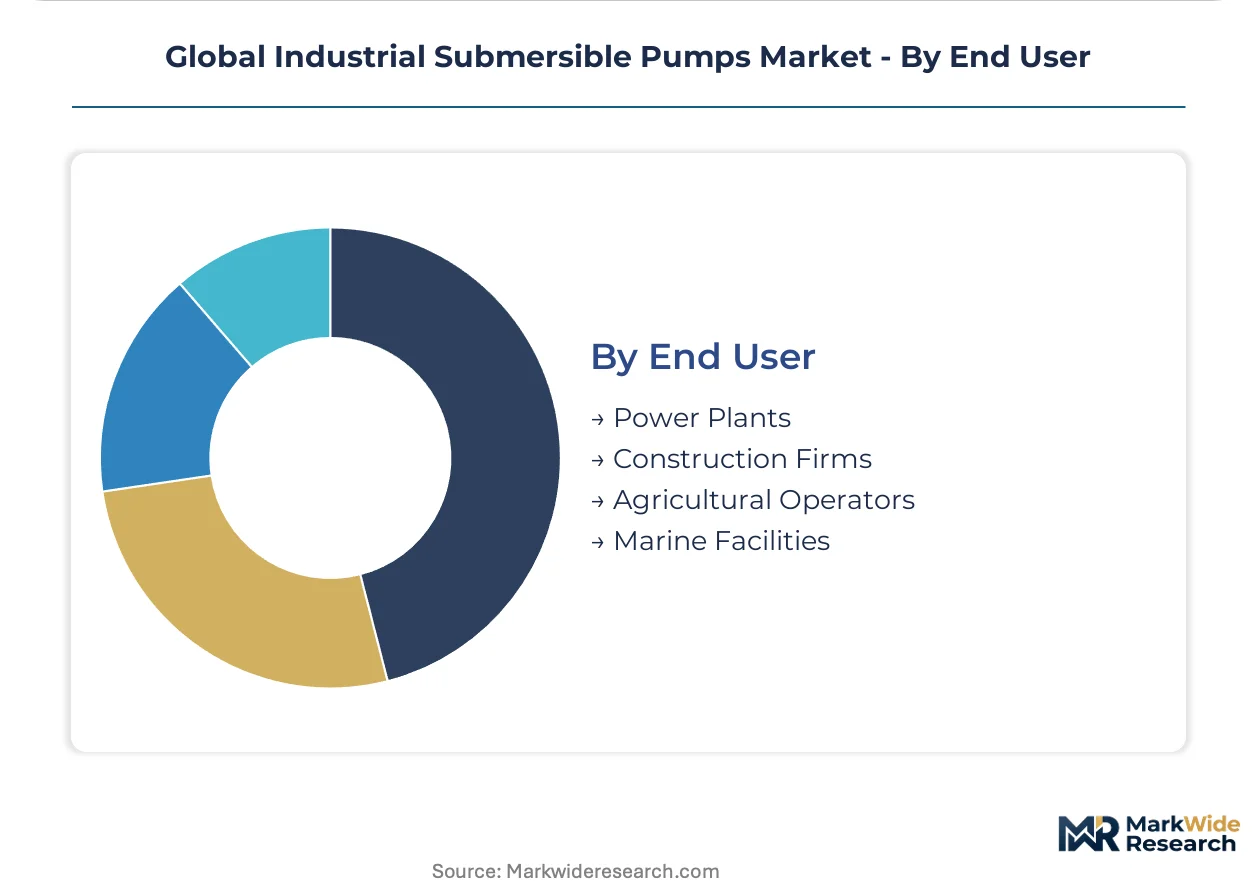
End User:
Procurement sophistication and lifecycle cost visibility vary sharply across buyer categories.
- Agricultural Operators:Fragmented smallholder cooperatives in Kenya and India prioritize first-cost minimization and diesel displacement through solar retrofit kits. Dealer networks and microfinance availability shape purchase decisions more than technical specifications.
- Power Plants:Thermal and nuclear facilities specify canned motor pumps for primary coolant and condensate extraction where leakage tolerance approaches zero. Chinese MEE permitting constrains groundwater extraction for cooling tower makeup.
- Construction Firms:Rental-oriented buyers favor portable diesel dewatering units for foundation and tunnel projects.
- Marine Facilities:Ballast and bilge applications require corrosion-resistant bronze or super-duplex construction.
Agricultural operators lead volumes today; power plants command the steepest pricing tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German electromechanical engineering expertise and Chinese foundry labor pools anchor regional supply capabilities. Danish pump design heritage and Japanese precision manufacturing add specialized technical depth. Brazilian mining operations and Indian agricultural demand complete the geographic demand matrix.
Germany
Ruhr Valley wastewater utilities and Bavarian industrial zones drive replacement cycles for sealed submersible systems. The EU Urban Wastewater Treatment Directive mandates upgraded discharge standards that favor corrosion-resistant pump architectures. Stuttgart-based engineering clusters coordinate REACH-compliant seal qualification timelines for potable water applications.
China
Shandong and Hebei province foundries supply seventy percent of global cast iron pump housings. The Ministry of Ecology and Environment enforces groundwater extraction permits that constrain industrial pump sizing in manufacturing corridors. Yangtze River Delta municipal authorities deploy deep-well vertical turbine installations for urban water security.
United States
EPA effluent guidelines under the Clean Water Act shape specifications for municipal wastewater treatment deployments. Texas and Ohio manufacturing corridors attract reshoring assembly operations incentivized by Inflation Reduction Act domestic content bonuses. Chicago, Houston, and Phoenix utilities pioneer performance-based service contracting with availability guarantees.
India
Gujarat and Maharashtra industrial corridors face tightening groundwater extraction regulations that limit pump duty cycles. National renewable energy agency subsidies compress solar-powered submersible payback periods below three years for agricultural cooperatives. Karnataka irrigation networks deploy DC-powered borehole arrays paired with variable frequency drives.
Chile
Atacama Desert copper operations deepen pit excavations beyond 800 meters, necessitating abrasion-resistant radial flow configurations. Mining dewatering intensity commands premium pricing for hardened impeller metallurgy. Antofagasta regional authorities coordinate infrastructure investment for extractive industry water management.
Global Industrial Submersible Pumps Market Competitive Landscape
The competitive structure tilts toward integrated motor-pump manufacturers with captive foundry capacity and digital service platforms. European and Japanese incumbents dominate premium efficiency tiers through stator lamination expertise and sensor integration. Three archetypes prevail: full-stack OEMs controlling upstream metallurgy, digital-native challengers monetizing predictive maintenance, and regional fabricators serving cost-sensitive agricultural segments. Consolidation pressures favor M&A targeting IIoT capabilities and geographic expansion into Indonesian and Indian municipal markets.
Within the integrated manufacturing tier, Grundfos Holding A/S and Xylem Inc. exemplify divergent strategic postures. The Danish entity represents captive motor-pump production with margin resilience across energy-efficiency tiers. The US-based firm anchors competitive positioning through cloud-connected monitoring platforms that extend revenue beyond hardware transactions. KSB SE & Co. KGaA occupies a position serving large-scale vertical turbine demand from municipal water authorities confronting leakage reduction mandates.
| Leading Market Players |
|---|
| Xylem Inc. |
| Grundfos Holding A/S |
| KSB SE & Co. KGaA |
| Sulzer Ltd. |
| Atlas Copco AB |
| Wilo SE |
| Flowserve Corporation |
| Ebara Corporation |
| Weir Group PLC |
| Others |
Supply & Pricing Matrix
Municipal procurement specifications mandating REACH-compliant seal chemistries and permanent magnet motor efficiency tiers are forcing manufacturers to absorb requalification costs or pass them downstream, stratifying vendor tiers by certification depth and captive metallurgy control.
Pricing Analysis
The bundled-vs-unbundled service split separates capital-equipment vendors from availability-guarantee providers across North American municipal water authorities. Three-tier pricing structure across premium, standard, and economy levels tracks motor efficiency class, with IEC 60034-2-3 IE4/IE5 tiers commanding substantial premiums over induction-motor baselines. Cost compression in mid-tier electric configurations is intensifying because permanent magnet rare-earth magnet volatility compresses margins on premium efficiency tiers. Agricultural cooperatives in Kenya and India exhibit highest price sensitivity, prioritizing first-cost minimization in solar retrofit decisions, while German wastewater utilities demonstrate lowest sensitivity due to lifecycle-cost procurement mandates.
Supply Chain Analysis
Dual-sourcing requirements from Western OEMs are fragmenting procurement across Shandong and Hebei province foundries for cast iron housings, Japanese stator lamination specialists, and German seal compounders. Raw material dependencies center on rare-earth magnet feedstock from Chinese processing facilities, copper winding stock, and corrosion-resistant stainless steel grades. Single-source vulnerability concentrates in Shandong-Hebei foundry clusters, where seventy percent of global corrosion-resistant housing production creates geographic concentration risk. Distribution runs through authorized dealer networks for agricultural segments and direct municipal contracting for large-scale vertical turbine installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by the shift from unit-sale procurement to performance-based service contracting with availability guarantees across Chicago, Houston, and Phoenix utilities.
For Market Incumbents: Extend digital monitoring platform penetration to monetize uptime guarantees and lock in ten-to-fifteen-year municipal contracts before sensorless vector control technology commoditizes permanent magnet advantages. Defend against solar-powered challengers by integrating DC submersible arrays into bundled agricultural offerings. Prioritize captive foundry capacity in Texas and Ohio corridors to capture Inflation Reduction Act domestic content bonuses. For New Entrants and Emerging Players: Capture Indonesian municipal deep-well vertical turbine demand as Jakarta's saltwater intrusion crisis accelerates infrastructure investment outside incumbent service footprints. Target Kenyan and rural Indian agricultural networks where solar retrofit kits face minimal brand loyalty and microfinance availability shapes purchase decisions more than technical specifications. Pursue dealer network partnerships over direct sales to overcome established parts depot density. For Investors and Strategic Acquirers: Asymmetric upside sits with IIoT-native challengers possessing predictive maintenance platforms but lacking manufacturing scale, as performance-based contracting concentrates vendor risk in remote monitoring infrastructure. The five-to-ten year viability window favors acquisition targets with established cloud analytics capabilities and regional service density in underserved Indonesian and Indian municipal markets. Watch for inflection in IEC 60034-2-3 efficiency testing harmonization progress, where protocol consolidation would deflate multi-territory certification cost barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Integration | IE4/IE5 efficiency tiers command pricing premiums against legacy induction alternatives across German utilities. |
| IIoT Predictive Maintenance Platform | Cloud-connected vibration and temperature sensors monetize uptime guarantees beyond hardware transactions. |
| REACH-Compliant Seal Requalification | Twelve-to-eighteen-month elastomer validation timelines create certification moats for qualified European OEMs. |
| Solar Array Distribution Partnership | DC-powered submersible retrofit kits leverage Kenyan and Indian renewable energy agency subsidies. |
| Domestic Content Assembly Reshoring | Texas and Ohio manufacturing corridors capture Inflation Reduction Act bonuses for federally funded water infrastructure. |
Research Methodology
Multiple input streams — technical interviews with maintenance directors and plant engineers at mining and wastewater facilities, procurement discussions with municipal water authority contracting officers, and aftermarket service consultations with regional parts depot managers — were reconciled against customs records for cast iron and stainless steel pump housing trade flows, SEC 10-K filings from listed pump manufacturers, and IEC efficiency certification databases. Bottom-up unit shipment estimates by product type and power source were triangulated against top-down value projections derived from disclosed contract values in municipal procurement disclosures.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through segmented modeling of radial flow, vertical turbine, axial flow, and mixed flow configurations by electric motor driven, solar powered, hydraulic, and diesel engine driven technologies. CAGRs were derived from fitted growth curves applied to disclosed installation data from German wastewater utilities, Chilean mining operators, and Indian agricultural cooperatives. Industry-specific forecast inputs incorporated groundwater extraction permit constraints under China's MEE and EU Urban Wastewater Treatment Directive upgrade cycles.
Copper and rare-earth magnet price volatility, Chinese export quota adjustments for permanent magnet materials, and fragmentation in national efficiency testing protocols are the dominant revision risks to modeled outputs. Deviation in rare-earth supply availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Centrifugal Pump Market
Pumps and Control Devices
Positive Displacement (PD) Sanitary Pumps Market
Pumps and Control Devices
Centrifugal Pumps Machines Market
Pumps and Control Devices
Dewatering Pumps Market
Pumps and Control Devices
Subsea Pumps Market
Pumps and Control Devices
Electrostatic Coalescers Market
Pumps and Control Devices
Global Hydraulic Submersible Pump Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market
Pumps and Control Devices
Intelligent Pump Market
Pumps and Control Devices
US Industrial Pump Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
Double Suction Pump Market
Pumps and Control Devices
APAC Positive Displacement Pumps Market
Pumps and Control Devices
Europe Positive Displacement Pumps Market
Pumps and Control Devices
Asia Pacific Submersible Pump Market
Pumps and Control Devices
End Suction Pump Market