
 Industrial ASME B73.1 Centrifugal Pumps Market | 2026-2036
Industrial ASME B73.1 Centrifugal Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial ASME B73.1 Centrifugal Pumps Market Insights
Aftermarket service revenue is reconfiguring margin pools away from original equipment sales toward lifecycle contracts and spare parts fulfillment. Flowserve Corporation leverages its global service network to capture recurring maintenance spend across refinery and chemical installations. KSB SE & Co. KGaA anchors its position through backward integration into precision casting and proprietary hydraulic engineering. Sulzer Ltd differentiates via advanced coatings and condition monitoring systems that extend mean time between overhauls.
Industrial ASME B73.1 centrifugal pumps are horizontal, end-suction, single-stage pumps built to dimensional interchangeability and minimum performance standards under ASME B73.1, typically handling temperatures from minus 29 degrees Celsius to 260 degrees Celsius with discharge sizes from 25 mm to 300 mm. These pumps transfer corrosive, abrasive, or high-temperature process fluids in continuous-duty industrial environments where ANSI dimensional interchangeability reduces inventory and maintenance complexity. Stainless steel and cast iron material segments dominate installed bases, though duplex stainless configurations are gaining traction in chloride-rich chemical service. Horizontal configurations occupy the largest share of replacement demand, while vertical designs are expanding in constrained footprint installations. Chemical processing and water treatment applications generate the highest absolute unit volumes, with oil and gas procurement tilting toward API-integrated packages rather than pure B73.1 specifications.
ASME B73.1 itself shapes product geometry, flange drilling, and bearing frame dimensions, while EPA leak detection and repair rules drive demand for enhanced mechanical seal systems and secondary containment. OSHA process safety management standards mandate documented pump integrity programs in covered chemical facilities, creating compliance-driven replacement cycles. Buyers must weigh total cost of ownership against first cost as efficiency regulations and carbon accounting pressures intensify scrutiny on pump energy consumption and fugitive emissions.
Market Dynamics
EPA leak detection and repair rules are compressing replacement cycles for mechanical seal systems across US Gulf Coast chemical corridors, forcing buyers to prioritize total cost of ownership calculations over first-cost procurement.
Growth Catalysts
- OSHA Process Safety Management:Mandated pump integrity documentation in covered chemical facilities creates compliance-driven replacement demand for ASME B73.1 compliant units.
- Texas and Louisiana petrochemical expansion:New ethylene and derivative capacity additions are pulling ANSI-standard pump packages into front-end engineering designs.
- Duplex stainless steel adoption:Chloride-rich chemical service environments are specifying super-duplex configurations that extend mean time between failures.
Market Restraints
- Specialized foundry concentration:Precision casting capacity for complex pump housings concentrates in select US Midwest and German supplier bases, creating lead time vulnerability.
- API 610 substitution:Oil and gas procurement committees are specifying heavier-duty API standards over B73.1 for high-pressure hydrocarbon service.
- Nickel alloy input volatility:Duplex and super-duplex material costs fluctuate with London Metal Exchange pricing, compressing margin predictability for engineered-to-order pumps.
Strategic Opportunities
- Condition monitoring convergence:Vibration and temperature sensor integration with cloud analytics platforms is digitizing aftermarket service revenue streams.
- Secondary containment mandates:EPA rules on fugitive emissions are creating retrofit demand for seal support systems and containment hardware.
- Water treatment infrastructure:Municipal and industrial wastewater facilities in the Ohio River Valley are specifying B73.1 pumps for corrosive effluent handling.
Industry Challenges
- Hydraulic engineering talent scarcity:Specialized pump design expertise is concentrating at established manufacturers, constraining new entrant technical capabilities.
- ASME code revision lag:Update cycles for B73.1 dimensional and performance standards create certification timeline uncertainty for product development pipelines.
- Legacy system integration:Brownfield chemical plants require custom adapter configurations to interface new ANSI pumps with existing piping and foundation layouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial ASME B73.1 Centrifugal Pumps Market |
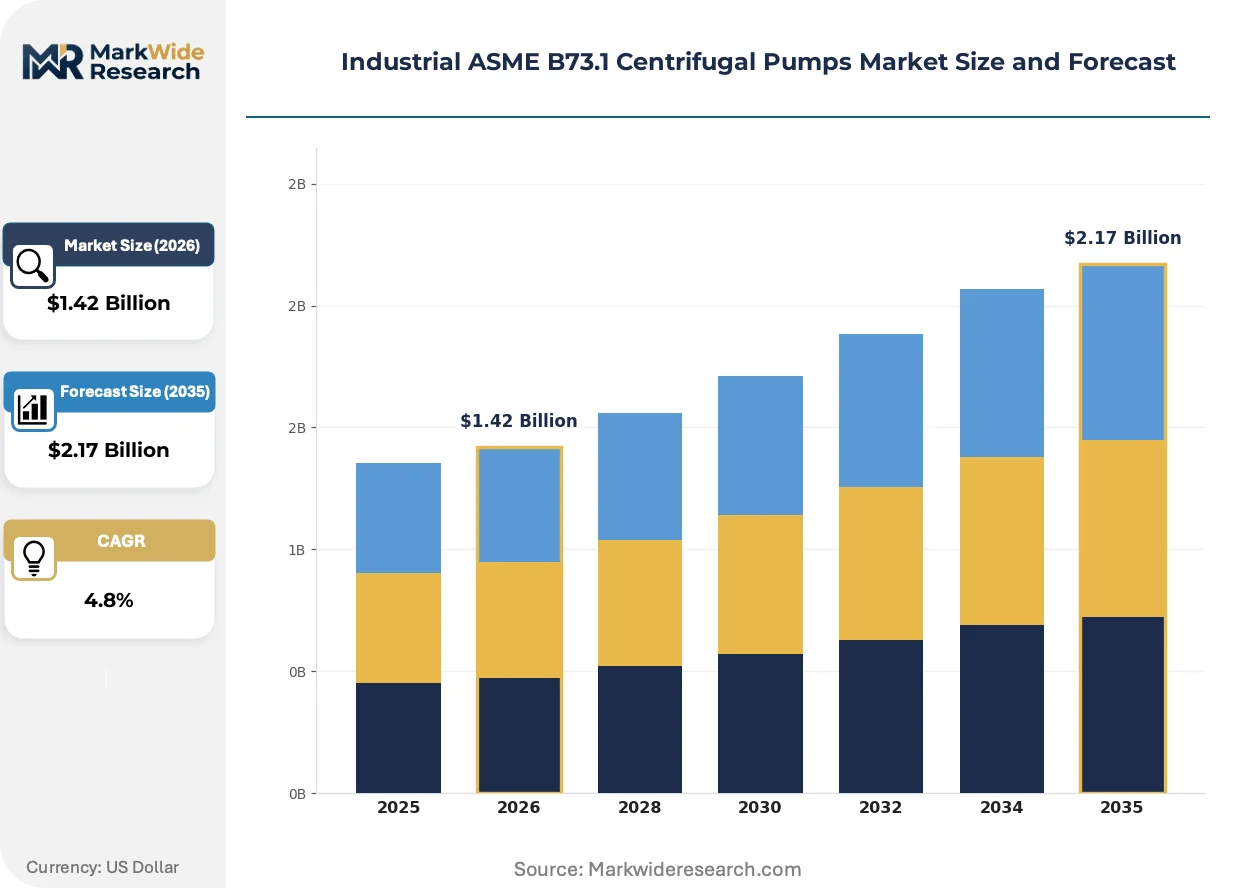
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Stage, Multi-Stage, Vertical, Horizontal Application: Chemical Processing, Water Treatment, Oil & Gas, Pulp & Paper End User: Manufacturing, Energy, Water & Wastewater, Construction Material: Cast Iron, Stainless Steel, Bronze, Plastic |
| Companies Covered | Flowserve Corporation, KSB SE & Co. KGaA, Sulzer Ltd, Grundfos Holding A/S, Xylem Inc., Ruhrpumpen Group, Pentair, Ebara Corporation, Torishima Pump Mfg. Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial ASME B73.1 Centrifugal Pumps Market Trends and Innovations
Digital instrumentation is embedding intelligence directly into rotating equipment, converting pumps from passive fluid handlers into data-generating assets that enable predictive maintenance and energy optimization.
Smart seal monitoring systems is digitizing fugitive emissions tracking in real time. Chemical processors in the Houston Ship Channel are retrofitting existing B73.1 installations with wireless transmitters that stream seal chamber pressure and temperature to centralized reliability dashboards. This instrumentation layer is compressing unplanned outage frequency while generating recurring software and sensor replacement revenue for service providers.
EPA emissions enforcement is tightening mechanical seal specification requirements. The 2024 leak detection and repair rule amendments are mandating enhanced seal support systems with barrier fluid pressure monitoring for pumps handling volatile organic compounds above threshold quantities. Refinery and chemical complex operators are responding by consolidating procurement around seal vendors with documented compliance histories.
Lifecycle contracting is displacing transactional spare parts purchasing. Large chemical processors are unbundling aftermarket spend into long-term service agreements that cover predictive diagnostics, scheduled overhauls, and guaranteed availability metrics. This procurement evolution is most visible among integrated petrochemical operators along the US Gulf Coast, where total cost of ownership models now dominate capital project justification.
Industrial ASME B73.1 Centrifugal Pumps Market Segmentation
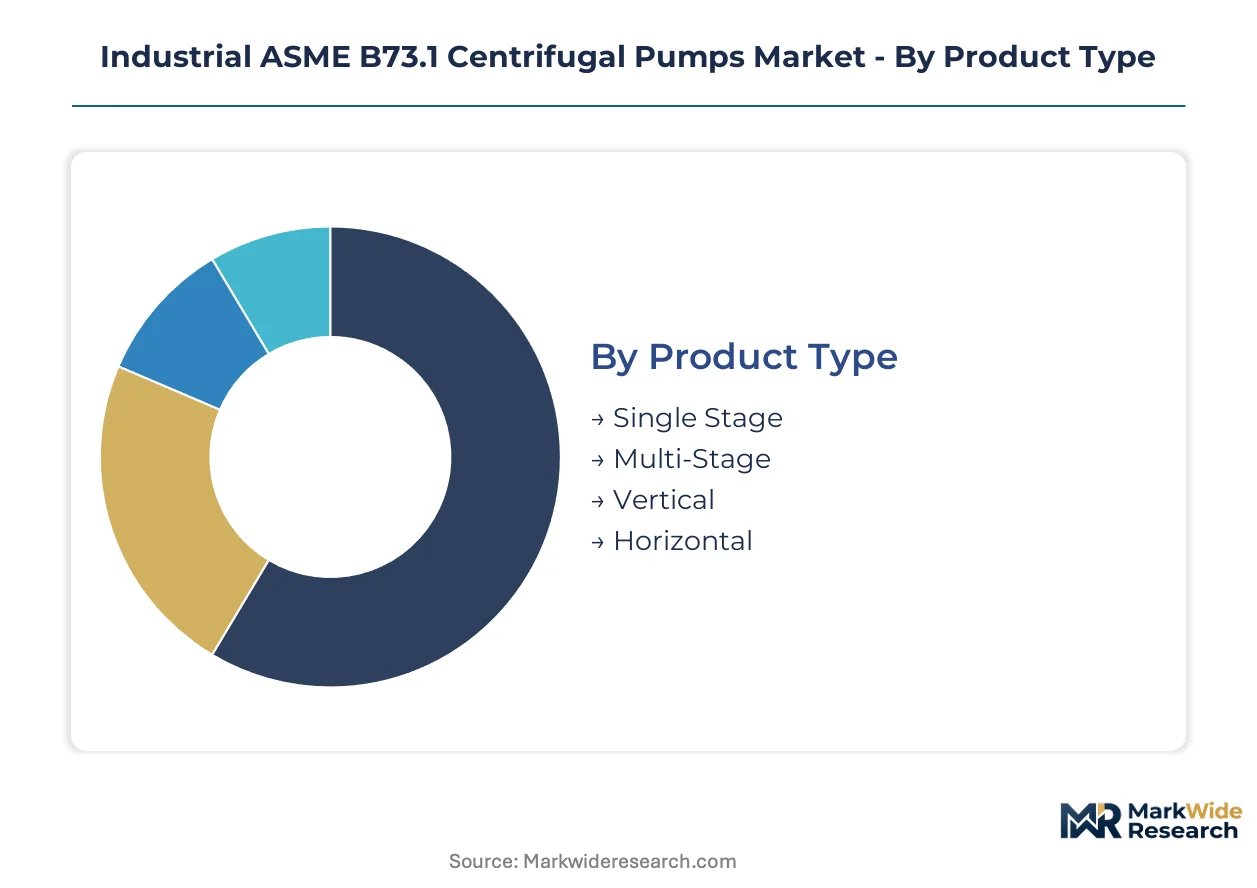
Segmentation in the Industrial ASME B73.1 centrifugal pumps market reveals divergent replacement cycles and margin profiles. Material selection and configuration geometry drive procurement patterns across chemical processing corridors and water treatment infrastructure.
Product Type:
Replacement velocity varies sharply by configuration complexity, with single-stage units turning over fastest due to standardized bearing assemblies and widespread dimensional interchangeability.
- Single Stage:End-suction designs with one impeller dominate chemical transfer duty. Texas and Louisiana petrochemical facilities specify these for light hydrocarbon and corrosive fluid handling where ASME dimensional standards minimize spare parts inventory.
- Multi-Stage:Higher head applications require stacked impeller configurations with interstage diffusers. These pumps concentrate in boiler feed and high-pressure water treatment service where energy recovery justifies elevated first cost.
- Vertical:Inline designs with motor mounted above pump save footprint in constrained installations. Municipal wastewater facilities in the Ohio River Valley specify vertical configurations for sump and pit applications.
- Horizontal:Split-case and end-suction arrangements anchor the installed base across refinery tank farm and process unit applications. These configurations dominate aftermarket service revenue pools.
Horizontal pumps dominate installed base. Vertical configurations are where expansion concentrates in brownfield retrofit projects.
Application:
End-use concentration determines specification stringency, with chemical processing demanding the most rigorous material certification and emissions compliance documentation.
- Chemical Processing:Corrosive fluid transfer in continuous-duty environments requires ASME B73.1 dimensional interchangeability to reduce maintenance complexity. EPA leak detection rules compress replacement cycles for mechanical seal systems in covered facilities.
- Water Treatment:Municipal and industrial effluent handling specifies ANSI-standard pumps for abrasive and chlorinated water service. Ohio River Valley infrastructure investment is pulling duplex stainless configurations into procurement specifications.
- Oil & Gas:Hydrocarbon service procurement increasingly specifies API 610 over B73.1 for high-pressure applications. Remaining B73.1 demand concentrates in terminal and light product transfer duty.
- Pulp & Paper:Black liquor and bleaching chemical applications require corrosion-resistant materials. These mills specify stainless steel and duplex configurations for extended mean time between failures.
Chemical processing dominates installed base. Water treatment is where expansion concentrates as infrastructure replacement cycles accelerate.
End User:
Customer type shapes contracting structure, with integrated energy operators driving lifecycle service agreements while municipal water authorities prioritize first-cost procurement.
- Manufacturing:Process industries including specialty chemicals and food processing specify B73.1 pumps for hygienic and corrosive fluid transfer. These buyers balance ANSI interchangeability against total cost of ownership calculations.
- Energy:Refinery and petrochemical operators consolidate procurement around vendors with documented EPA compliance histories. Lifecycle contracting is displacing transactional spare parts purchasing among integrated Gulf Coast operators.
- Water & Wastewater:Municipal authorities specify horizontal end-suction designs for raw water intake and effluent discharge. Federal infrastructure funding is accelerating replacement demand across aging treatment facilities.
- Construction:Building services and temporary dewatering applications represent lower-specification demand. These buyers prioritize availability and first cost over extended service intervals.
Energy sector dominates installed base. Water & wastewater is where expansion concentrates as federal funding flows into infrastructure replacement.
Material:
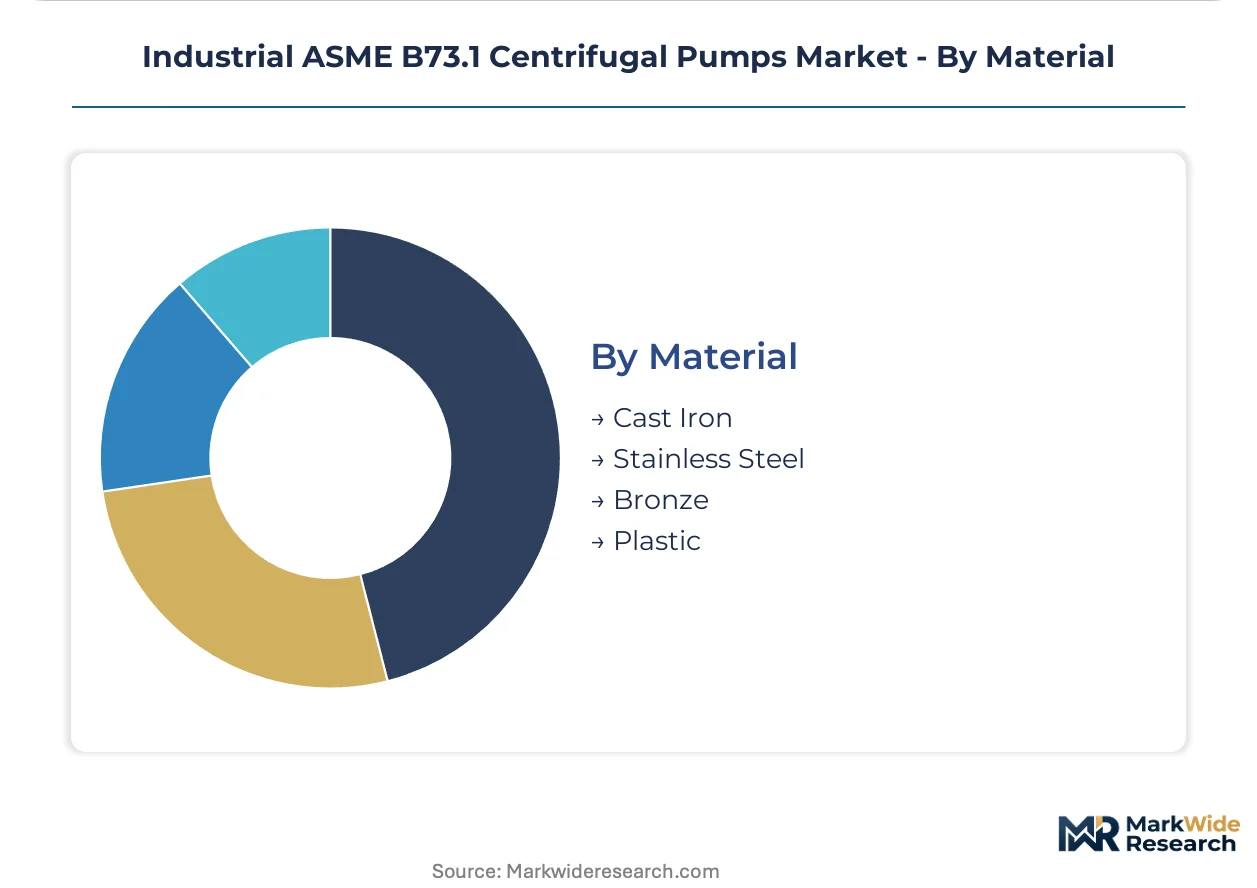
Material selection tracks fluid aggressiveness and chloride concentration, with super-duplex specifications gaining traction in seawater and brine service despite nickel alloy price volatility.
- Cast Iron:Standard material for water handling and non-corrosive process fluids. Municipal water treatment facilities in the Ohio River Valley specify cast iron for cost-sensitive raw water and effluent applications.
- Stainless Steel:Austenitic grades dominate chemical processing installed bases for moderate corrosive service. These alloys balance corrosion resistance against machinability for complex impeller geometries.
- Bronze:Naval bronze and aluminum bronze specifications concentrate in seawater and marine applications. These materials resist dezincification in chloride-rich environments where stainless steels suffer pitting.
- Plastic:Fluoropolymer and thermoplastic configurations handle highly aggressive acids and bases. Specialty chemical producers specify plastic-lined pumps for extreme pH service beyond metallic material limits.
Stainless steel dominates installed base. Duplex and super-duplex configurations are where expansion concentrates in chloride-rich chemical service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the US Gulf Coast exhibit the lowest price elasticity, prioritizing lifecycle costs and EPA compliance documentation over first-cost procurement. European purchasers demonstrate moderate elasticity, balancing ASME interchangeability against energy efficiency regulations. Asian buyers, particularly in emerging chemical corridors, remain most sensitive to initial capital outlay.
United States
Texas and Louisiana petrochemical corridors are expanding ethylene and derivative capacity, pulling ANSI-standard pump packages into front-end engineering designs. EPA leak detection and repair rules compress replacement cycles for mechanical seal systems in covered facilities. The Houston Ship Channel chemical complex is retrofitting existing installations with wireless seal monitoring transmitters.
Germany
Specialty chemical producers in the Rhine-Ruhr industrial zone specify duplex stainless configurations for chloride-rich process environments. REACH chemical registration requirements and the EU Green Deal carbon accounting framework intensify scrutiny on pump energy consumption and fugitive emissions. BASF's Ludwigshafen complex anchors demand for precision-cast pump housings with documented material traceability.
China
Coastal chemical parks in Zhejiang and Jiangsu provinces are modernizing effluent handling infrastructure under MEE environmental enforcement campaigns. GB standards alignment with ASME dimensional specifications facilitates import substitution for critical process pumps. The Ningbo Petrochemical Economic and Technological Development Zone is consolidating procurement around vendors with localized casting capabilities.
India
Gujarat's Dahej and Mundra chemical corridors are expanding chlor-alkali and specialty chemical capacity, specifying B73.1 pumps for corrosive brine and acid handling. BIS certification requirements for pressure equipment create compliance-driven vendor qualification timelines. Reliance Industries' Jamnagar complex is driving demand for super-duplex material configurations in seawater cooling applications.
Saudi Arabia
Jubail Industrial City and Yanbu petrochemical complexes are expanding downstream derivative production under Vision 2030 economic diversification mandates. The country's national environmental regulator enforces fugitive emissions standards that align with EPA leak detection protocols. SABIC's manufacturing affiliates are consolidating lifecycle service contracts for rotating equipment maintenance.
Industrial ASME B73.1 Centrifugal Pumps Market Competitive Landscape
Integrated full-line suppliers and specialized precision-casting houses split the market along the dimension of service network breadth versus material engineering depth. The competitive structure concentrates around three strategic archetypes: global pump system integrators with captive service infrastructure, European precision foundries with backward integration into hydraulic engineering, and Asian fabricators competing on lead time compression. Dominant competitive moves include geographic expansion through distribution partnerships and technology licensing arrangements for seal support systems.
Among the integrated full-line suppliers, Flowserve Corporation and KSB SE & Co. KGaA exemplify the global service network archetype, anchoring positions through lifecycle contracting capabilities. Sulzer Ltd occupies a position within the precision-engineering tier, representing specialized competence in advanced coatings and condition monitoring integration. These three companies collectively illustrate the competitive tension between scale-driven aftermarket capture and technology-led mean-time-between-overhaul extension.
| Leading Market Players |
|---|
| Flowserve Corporation |
| KSB SE & Co. KGaA |
| Sulzer Ltd |
| Grundfos Holding A/S |
| Xylem Inc. |
| Ruhrpumpen Group |
| Pentair |
| Ebara Corporation |
| Torishima Pump Mfg. Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
US Midwest and German precision foundries concentrate casting capacity for complex pump housings, anchoring margin pools in aftermarket service tiers rather than original equipment transactions. Nickel alloy price volatility on the London Metal Exchange feeds directly into duplex stainless configurations, compressing predictability for engineered-to-order pumps while lifecycle contracts stabilize revenue for integrated service providers.
Pricing Analysis
Aftermarket service revenue drives lifetime value across installed bases, with spare parts fulfillment and predictive maintenance contracts generating recurring streams that offset transactional equipment margins. Three-tier pricing structure across premium, standard, and economy levels separates API-integrated packages from pure B73.1 specifications and basic water handling units. Cost compression in super-duplex material tiers is intensifying because London Metal Exchange nickel pricing feeds directly into chloride-rich chemical service configurations. Municipal water authorities exhibit highest price sensitivity, prioritizing first-cost procurement, while integrated Gulf Coast petrochemical operators demonstrate lowest elasticity.
Supply Chain Analysis
Upstream nickel alloy and precision casting feedstocks draw from US Midwest foundries, German engineering centers, and emerging Asian fabricators. Duplex stainless steel, cast iron, and specialized bronze alloys rest on concentrated metallurgical supplier bases. Single-source vulnerability concentrates in complex housing castings requiring ASME-certified dimensional tolerances. Distribution runs through OEM-direct channels for large chemical processors and authorized distributor networks for municipal and industrial replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASME B73.1 dimensional interchangeability functions as a platform standard, creating ecosystem lock-in where seal system vendors, condition monitoring providers, and aftermarket service networks compete for attachment revenue.
For Market Incumbents: Harden lifecycle contracting capabilities against API 610 substitution threats in oil and gas procurement committees. Deepen backward integration into precision casting to secure lead time advantages as foundry capacity concentrates. Anchor EPA compliance documentation as a switching cost for covered chemical facilities. For New Entrants and Emerging Players: Pursue Ohio River Valley water treatment infrastructure as the most penetrable expansion corridor, where federal funding accelerates replacement cycles without incumbent service network saturation. Target vertical pump configurations for constrained footprint brownfield retrofits. Lead with cloud-integrated condition monitoring as a differentiated go-to-market wedge. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision foundries and regional pump assemblers lacking captive aftermarket infrastructure. Five-to-ten year viability hinges on consolidation of service networks around EPA-compliant seal system vendors. Watch EPA leak detection rule enforcement intensity as the inflection signal for compliance-driven replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captures foundry margin and secures ASME-certified dimensional tolerance control. |
| Lifecycle Service Contract Expansion | Converts transactional spare parts revenue into predictable recurring streams. |
| Condition Monitoring Platform Integration | Embeds vibration and temperature sensors with cloud analytics for predictive maintenance. |
| Seal Support System Compliance Certification | Documents EPA leak detection rule adherence as a procurement selection criterion. |
| Regional Distribution Partnership Expansion | Extends aftermarket reach into Ohio River Valley water treatment infrastructure. |
Research Methodology
Operator-level perspectives from plant maintenance directors, OEM procurement teams, aftermarket service heads, and chemical facility reliability engineers anchored the qualitative base. Primary fieldwork combined with secondary validation from customs and trade data, American Chemistry Council sector reports, SEC 10-K filings, and ASME code documentation. Bottom-up unit economics triangulated against top-down sector expenditure estimates.
Scenario-bracketing framed projections across the analysis window, with segmentation modeled by material grade tier, end-use application, configuration geometry, and regional petrochemical corridor. CAGRs derived from installed base turnover rates, capacity expansion pipelines, and regulatory compliance cycle compression. Energy efficiency regulations and EPA emissions enforcement intensity served as demand-side forecast inputs.
Sensitivities concentrate around London Metal Exchange nickel price volatility, ASME code revision timelines, and EPA rule enforcement intensity. Forecasts reflect documented assumptions regarding replacement cycle compression and lifecycle contracting adoption trajectories. Cross-checking against American Chemistry Council capital expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Submersible Pumps Market
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Radial Split Pump Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Residential Pumps Market
Pumps and Control Devices
Dispensing Pump Market
Pumps and Control Devices
Split Casing Pump Market
Pumps and Control Devices
Electrostatic Coalescers Market
Pumps and Control Devices
Plunger Pumps Market
Pumps and Control Devices
Double Suction Pump Market
Pumps and Control Devices
Global Heavy Duty Pumps Market
Pumps and Control Devices
Brine Tanks Market
Pumps and Control Devices
Global Reciprocating Pumps Market
Pumps and Control Devices
Industrial Pumps Market
Pumps and Control Devices
Solar Pump Market