
 Valve Grinder Market | 2026-2036
Valve Grinder Market Size, Share, and Industry Trends Forecast 2026-2036
Valve Grinder Market Analytics
Automation in precision finishing is tilting valve grinder design toward CNC-controlled platforms with integrated measurement feedback. Chris Marine leverages its marine engine heritage to anchor specialized grinder architectures for large-bore applications. Kemet competes through advanced abrasive system integration that extends process consistency across batch sizes. Ludwig Hunger Werkzeug- und Maschinenfabrik GmbH dominates European distribution with precision spindle technology that sustains tight concentricity tolerances in high-cycle environments.
A valve grinder is a machine tool engineered to recondition valve faces and seats through abrasive material removal, typically achieving surface finishes below 0.4 micrometers Ra and angular tolerances within 0.5 degrees to ensure proper sealing in combustion engines. The equipment serves engine remanufacturing, maintenance depots, and performance workshops where dimensional restoration of valvetrain components prevents compression loss and premature failure. Stationary grinders command the largest installed base due to throughput advantages in production settings, while CNC grinding represents the fastest-expanding technology segment as shops replace manual skill dependency with repeatable programmable cycles. Electric grinders maintain broad penetration across automotive rebuilders and repair shops where power infrastructure is standardized, whereas pneumatic variants retain footholds in aerospace facilities where spark-resistant operation remains critical.
OSHA machine guarding standards and EPA workplace particulate regulations shape grinder enclosure design and dust collection integration in the United States. CE marking under EU machinery directives and REACH compliance for abrasive material composition govern market access across European manufacturing and service sectors. Stakeholders must monitor how evolving ISO precision standards for remanufactured engine components redirect capital allocation between manual upgrade paths and full CNC platform investments.
Market Dynamics
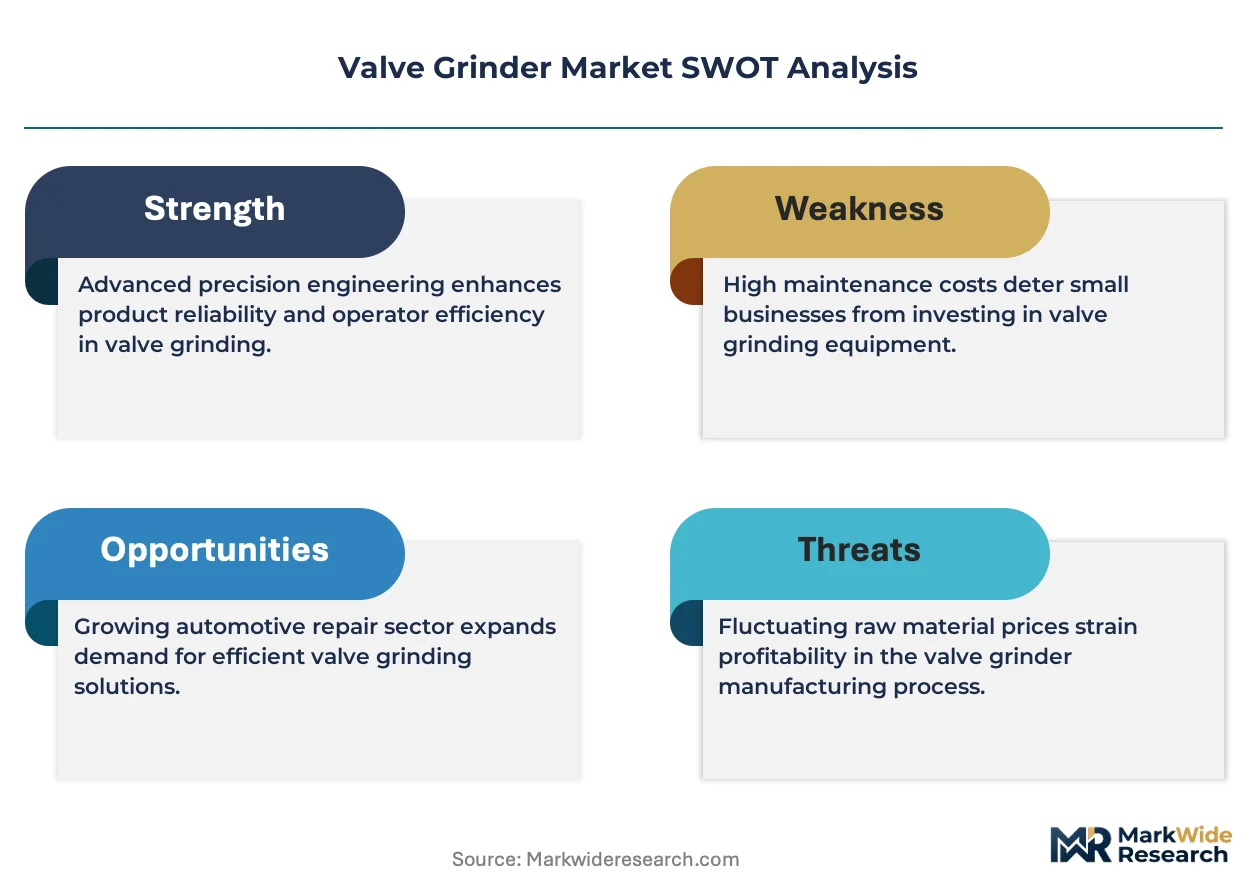
CNC-controlled grinding platforms are compressing the skill premium that manual operators once commanded, redistributing value from labor arbitrage toward capital-intensive precision automation in engine remanufacturing facilities.
Growth Catalysts
- EPA workplace particulate regulations:Mandated dust collection integration in United States machine shops accelerates replacement of unenclosed legacy grinders with sealed CNC systems that capture silica and metallic fines at source.
- Automotive engine remanufacturing:Tightening OEM warranty standards for rebuilt powertrains in Germany and China drive precision equipment upgrades as rebuilders face compression loss liability from sub-micron tolerance failures.
- Superabrasive wheel materials:Cubic boron nitride and diamond-impregnated grinding wheels extend batch consistency and reduce dressing cycles, lowering per-unit processing costs in high-volume valve service centers.
Market Restraints
- CNC platform capex intensity:Fully automated valve grinding cells require capital outlays that exclude smaller independent rebuilders from precision-tier competition, concentrating demand among fleet-scale operators.
- Abrasive supply concentration:Synthetic diamond and CBN substrate production clusters in limited manufacturing geographies, exposing grinder OEMs to raw material availability shocks and price volatility pass-through.
- Manual skill extinction:The generational attrition of experienced hand-grinding technicians creates a bottleneck for shops attempting hybrid upgrade paths that retain legacy equipment alongside CNC additions.
Strategic Opportunities
- India automotive aftermarket:Underpenetrated engine remanufacturing infrastructure in commercial vehicle hubs like Chennai and Pune presents first-mover positioning for precision grinder distributors before domestic precision standards mature.
- EU Green Deal remanufacturing incentives:Circular economy subsidies for component restoration over replacement create demand tailwinds for valve grinding services as OEMs seek carbon footprint reductions in scope three emissions.
- IoT-enabled predictive maintenance:Convergence of spindle vibration monitoring and cloud-based wear analytics allows grinder OEMs to unbundle after-sales service into subscription revenue streams.
Industry Challenges
- CNC programming competency gaps:Engine rebuilders struggle to recruit operators capable of G-code optimization and in-process measurement calibration, forcing equipment suppliers to absorb training costs or simplify HMI architectures.
- ISO precision certification timelines:Remanufactured component traceability requirements under evolving ISO standards delay shop accreditation and freeze capital deployment until compliance documentation matures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Valve Grinder Market |
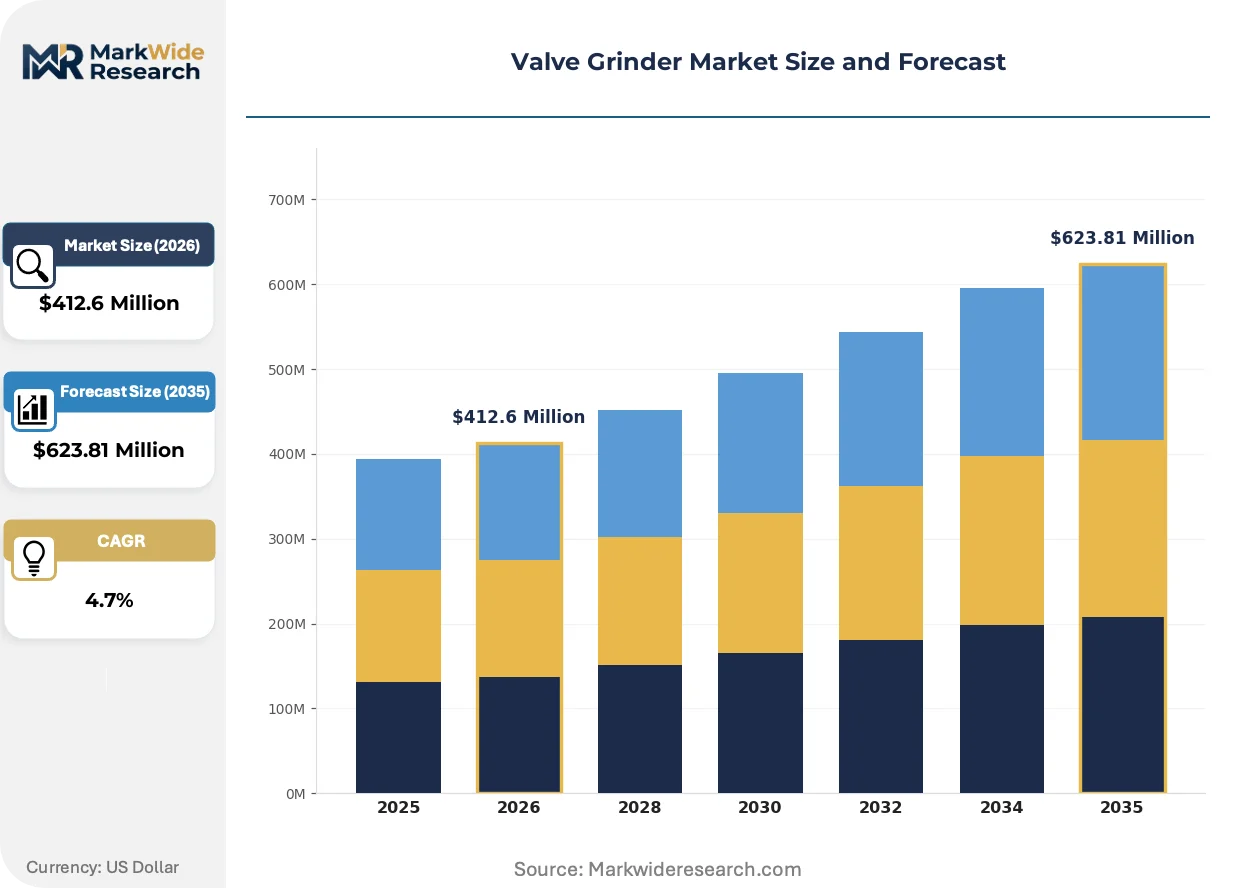
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $623.81 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Grinders, Stationary Grinders, Pneumatic Grinders, Electric Grinders End User: Automotive Rebuilders, Manufacturing Plants, Repair Shops, Aerospace Facilities Technology: Manual Grinding, CNC Grinding, Automated Grinding, Laser Grinding Application: Engine Overhauls, Maintenance Services, Performance Enhancements, Industrial Repair |
| Companies Covered | Jamieson Equipment, ACE Machine Tools, Wolf Electric Tools, AZ Machine Tools, Chris Marine, Kemet, COMEC, Ludwig Hunger Werkzeug- und Maschinenfabrik GmbH, Goodson Tools & Supplies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Valve Grinder Market Evolving Landscape
Automation architectures are collapsing the traditional trade-off between throughput and precision, enabling batch-size-one production economics that manual grinding benches cannot replicate.
Closed-loop in-process gauging systems with sub-micron feedback resolution are rendering obsolete the post-process inspection stations that previously bottlenecked valve grinding workflows. High-volume automotive rebuilders in Germany and the United States are retrofitting these systems to existing CNC platforms rather than purchasing greenfield equipment. The elimination of offline quality verification compresses floor space requirements and reduces work-in-process inventory by removing buffer stocks awaiting inspection release.
REACH compliance for abrasive material composition is forcing grinder manufacturers to reformulate bonded wheels and eliminate specific resin systems that previously dominated European supply chains. The industrial consequence extends beyond material substitution to require redesigned wheel retention interfaces and modified dressing protocols. Engine remanufacturing facilities in EU member states are absorbing these compliance costs through accelerated depreciation schedules rather than passing price increases to fleet customers.
Buyer consolidation among national automotive aftermarket distributors is compressing the independent dealer network that historically moved mid-market grinding equipment. Large distributor groups in the United States now demand exclusive territorial arrangements and volume rebate structures that marginalize smaller OEMs. This channel restructuring is most visible in the Southwest and Midwest regions where regional parts chains have merged into national procurement platforms with standardized equipment specifications.
Valve Grinder Market Segmentation
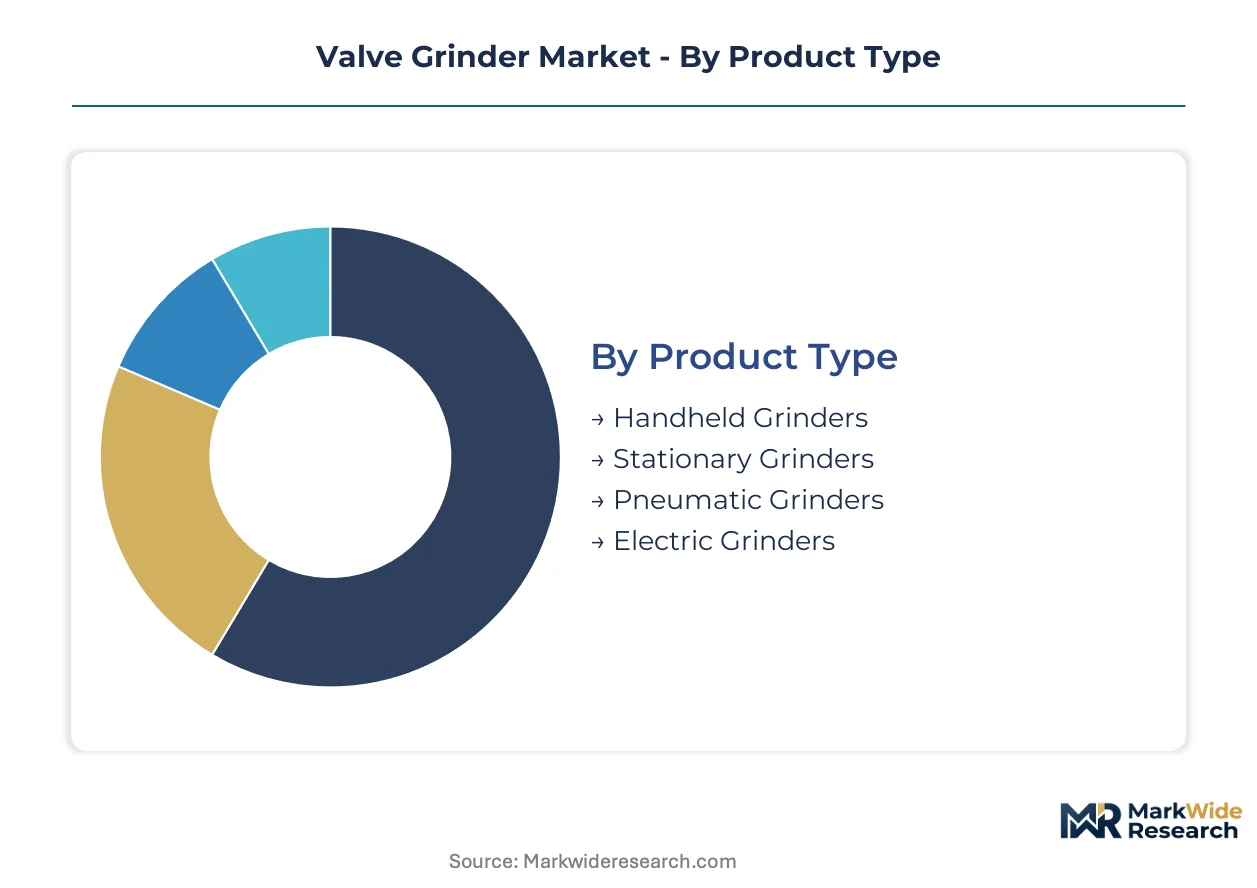
Valve grinder procurement patterns diverge sharply across operational contexts, with capital intensity and precision requirements dictating technology choices. Equipment specifications must align with regulatory compliance burdens and workforce skill availability in each end-use environment.
Product Type:
Mature workshop infrastructure favors established power configurations, while emerging electrification standards reshape equipment replacement cycles.
- Stationary Grinders:Fixed-position machines anchor high-throughput engine remanufacturing lines with rigid spindle assemblies that maintain concentricity below 2 micrometers across extended duty cycles. Demand concentrates in Germany and the United States where fleet-scale rebuilders process cylinder heads in centralized facilities. EPA workplace particulate regulations accelerate enclosure upgrades that capture metallic fines at source.
- Electric Grinders:Corded and cordless electric platforms dominate automotive rebuilders and independent repair shops where standardized power infrastructure eliminates compressed air dependency. OSHA machine guarding standards in United States facilities mandate interlocked wheel guards and emergency stop integration that pneumatic alternatives often lack.
- Handheld Grinders:Portable units serve field maintenance depots and mobile service operations requiring valve seat touch-up without bench-mounted equipment.
- Pneumatic Grinders:Compressed-air platforms retain aerospace facility penetration where spark-resistant operation prevents ignition hazards in fuel-vapor environments.
Stationary grinders retain volume leadership; CNC-compatible electric platforms hold the steepest expansion curve.
End User:
Customer scale determines automation feasibility, with warranty liability exposure driving precision tier selection.
- Automotive Rebuilders:Engine remanufacturing specialists operate the densest installed base of CNC grinding platforms as OEM warranty standards tighten compression loss liability. Germany and China host the most concentrated demand where remanufactured powertrain certification requirements mandate sub-micron tolerance documentation.
- Repair Shops:Independent service facilities balance equipment cost against job mix variability, often retaining manual benches for occasional valve work while outsourcing precision grinding to specialized contractors.
- Manufacturing Plants:Original equipment engine producers integrate valve grinding into transfer lines with automated part handling and statistical process control feedback.
- Aerospace Facilities:Aircraft engine maintenance depots specify pneumatic or explosion-proof electric grinders where ATEX compliance governs hazardous area classification.
Automotive rebuilders command the largest equipment footprint; aerospace facilities pursue the most specialized precision specifications.
Technology:
Skill dependency versus capital efficiency defines the migration path from manual benches to programmable platforms.
- CNC Grinding:Computer-numerical-control platforms eliminate operator variance through programmable dressing cycles and in-process gauging feedback that maintains angular tolerances within 0.5 degrees. High-volume shops in Germany retrofit closed-loop measurement systems to existing machines rather than acquiring greenfield equipment.
- Manual Grinding:Hand-controlled bench units persist in low-volume operations and developing markets where technician expertise substitutes for capital investment, though generational skill attrition constrains expansion.
- Automated Grinding:Fully automated cells with robotic part handling serve tier-one suppliers requiring unattended operation across extended production shifts.
- Laser Grinding:Thermal material removal technologies address superalloy valve components where conventional abrasive wear rates prove uneconomical.
Manual grinding retains installed base dominance; CNC platforms gain share fastest as labor arbitrage compresses.
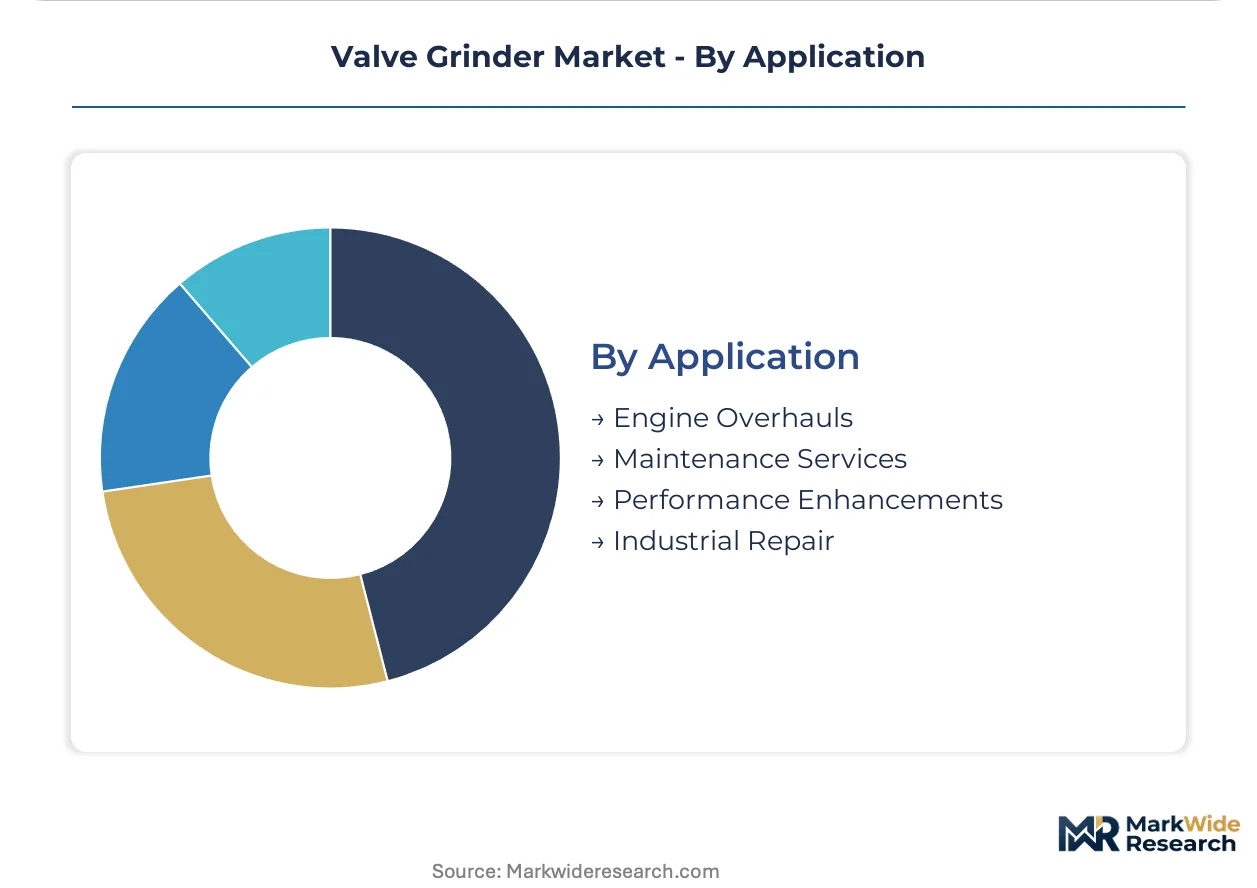
Application:
Service intensity and component value determine acceptable processing cost thresholds.
- Engine Overhauls:Complete powertrain reconstruction demands precision valve reconditioning to restore compression ratios and emissions compliance, with remanufacturing facilities in China absorbing REACH-compliant abrasive cost increases through accelerated depreciation.
- Maintenance Services:Preventive and corrective maintenance programs prioritize turnaround speed over absolute precision, favoring portable equipment for in-situ valve seat restoration.
- Performance Enhancements:Racing and high-performance engine builders specify multi-angle valve seat profiles that CNC platforms reproduce with repeatability manual grinding cannot match.
- Industrial Repair:Stationary engine and compressor maintenance extends equipment life in mining, marine, and power generation applications where component replacement lead times disrupt operations.
Engine overhauls anchor equipment utilization; performance enhancement applications command the highest precision tier premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet-scale automotive rebuilders concentrate precision valve grinding demand in Germany, China, and the United States, where dense machine tool ecosystems and tightening remanufacturing standards sustain capital investment cycles.
United States
Automotive aftermarket distributors consolidate procurement power across the Southwest and Midwest, demanding standardized CNC specifications from equipment suppliers. OSHA machine guarding standards and EPA workplace particulate regulations accelerate replacement of unenclosed legacy grinders with sealed systems capturing metallic fines. Detroit-area rebuilders retrofit closed-loop measurement systems to existing platforms rather than acquiring greenfield equipment.
Germany
OEM warranty standards for rebuilt powertrains mandate sub-micron tolerance documentation, compressing demand toward precision-tier CNC platforms. CE marking under EU machinery directives and REACH compliance for abrasive material composition govern market access across manufacturing and service sectors. Stuttgart and Munich host concentrated engine remanufacturing facilities absorbing compliance costs through accelerated depreciation schedules.
China
Commercial vehicle engine remanufacturing infrastructure expands in Shanghai and Beijing as domestic precision standards mature. GB standards and MIIT industrial policy guide machine tool qualification protocols for automotive component restoration. Yangtze River Delta rebuilders process cylinder heads in centralized facilities where CNC grinding displaces manual methods fastest.
India
Underpenetrated engine remanufacturing infrastructure in Chennai and Pune presents first-mover positioning for precision grinder distributors. BIS certification requirements and PLI scheme incentives for automotive component manufacturing reshape capital allocation toward automated finishing equipment. Tamil Nadu commercial vehicle hubs absorb REACH-compliant abrasive cost increases through fleet-scale depreciation strategies.
Japan
Aerospace maintenance depots in Nagoya and Tokyo specify pneumatic or explosion-proof electric grinders where ATEX compliance governs hazardous area classification. METI industrial standards and JIS precision specifications anchor quality protocols for aircraft engine valve reconditioning. Chubu region facilities balance spark-resistant operation requirements against throughput demands in turbine maintenance workflows.
Valve Grinder Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where distributor consolidation favors scale-capable OEMs while niche specialists retain premium positioning through precision spindle technology. The vendor base separates into three strategic archetypes: marine engine heritage specialists, abrasive system integrators, and precision spindle technology providers. Dominant competitive moves include geographic expansion through exclusive territorial arrangements and technology licensing partnerships that accelerate CNC platform deployment without full R&D burden.
Among European precision equipment fabricators, Ludwig Hunger Werkzeug- und Maschinenfabrik GmbH and Chris Marine occupy positions within the premium-tier specialist segment, while Kemet exemplifies the abrasive system integration archetype. Zhengzhou Shuli Machinery Co., Ltd. represents Chinese scale-capable fabrication, and Goodson Tools & Supplies anchors North American aftermarket distribution. These five entities collectively illustrate the geographic and functional segmentation structuring competitive positioning across marine, automotive, and aerospace end-use environments.
| Leading Market Players |
|---|
| Jamieson Equipment |
| ACE Machine Tools |
| Wolf Electric Tools |
| AZ Machine Tools |
| Chris Marine |
| Kemet |
| COMEC |
| Ludwig Hunger Werkzeug- und Maschinenfabrik GmbH |
| Goodson Tools & Supplies |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta grinding wheel manufacturing clusters anchor global superabrasive supply, translating synthetic diamond and CBN substrate availability into tiered equipment pricing power for CNC platform OEMs serving automotive rebuilders.
Pricing Analysis
Cost-plus contracts with quarterly indexation to synthetic diamond and cubic boron nitride spot markets dominate precision grinder procurement between rebuilders and equipment suppliers. Three-tier pricing structure across premium CNC platforms, mid-market electric units, and economy manual benches separates ISO-certified precision documentation from basic functionality. Pricing pressure stems from REACH-compliant abrasive reformulation costs that OEMs absorb rather than pass to fleet-scale buyers. Independent repair shops exhibit highest price sensitivity, while Germany-based engine remanufacturers prioritize tolerance certification over capital expenditure minimization.
Supply Chain Analysis
Tariff exposure between China and the United States disrupts superabrasive wheel component flows that grinder OEMs depend on for CBN and diamond-impregnated product lines. Synthetic substrate production concentrates in China, Germany, and Japan, with grinding spindle assemblies sourcing from precision fabricators in Taiwan and Switzerland. Single-source vulnerability around high-purity synthetic diamond growth chambers creates bottleneck risk for European grinder manufacturers. Distribution runs through consolidated national aftermarket distributor networks that demand exclusive territorial arrangements and volume rebate structures marginalizing smaller equipment suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Valve grinder procurement is tilting toward platform economics as CNC interoperability standards and cloud-based predictive maintenance ecosystems reshape buyer loyalty from equipment vendors to integrated workflow providers.
For Market Incumbents: Harden spindle technology differentiation through precision concentricity patents that sustain sub-2-micron tolerances against emerging Asian CNC platform competitors. Absorb REACH-compliant abrasive reformulation costs via accelerated depreciation partnerships with fleet-scale rebuilders rather than ceding share to low-cost manual grinder alternatives. Channel control remains the critical defensive lever as national distributor consolidation compresses independent dealer networks across the United States Midwest.
For New Entrants and Emerging Players: Build out IoT-enabled predictive maintenance subscription architectures that unbundle after-sales service from equipment sales, targeting India's underpenetrated Chennai and Pune commercial vehicle hubs before domestic precision standards mature. Field-portable valve seat restoration equipment for mining and marine maintenance depots offers the most penetrable white-space segment. Go-to-market execution should anchor on distributor partnerships with existing automotive aftermarket platforms rather than greenfield sales infrastructure.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with neglected precision grinding divisions lacking CNC platform refresh cycles. Long-term viability across the analysis window hinges on subscription revenue attach rates from spindle vibration monitoring and cloud-based wear analytics. The signal to watch is GB standards maturation in China that triggers replacement demand for manual grinding benches in Yangtze River Delta remanufacturing facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| CNC Platform Integration | Closed-loop in-process gauging retrofits compress German rebuilder floor space requirements. |
| Superabrasive Wheel Backward Integration | Captive CBN substrate production insulates Ludwig Hunger from raw material availability shocks. |
| IoT Predictive Maintenance Launch | Spindle vibration monitoring subscriptions transform Chris Marine's marine service revenue mix. |
| REACH-Compliant Abrasive Reformulation | Eliminated resin systems force Kemet to redesign wheel retention interfaces for EU rebuilders. |
| India Distribution Partnership | Exclusive territorial arrangements with Tamil Nadu aftermarket platforms lock out competitor entry. |
Research Methodology
Desk research of customs trade databases, machine tool industry association filings, and EPA enforcement records preceded structured interviews with engine remanufacturing facility managers, CNC grinding platform engineers, automotive aftermarket distributor procurement heads, and precision spindle technology specialists. Secondary validation drew from OSHA regulatory guidance documents, EU machinery directive implementation reports, and REACH substance restriction databases. Bottom-up equipment shipment data triangulated against top-down automotive rebuilder capital expenditure surveys to anchor market sizing.
Forecast assumptions held fixed: EPA particulate enforcement intensity, EU Green Deal remanufacturing subsidy continuity, and GB standards adoption trajectory in China. Variables stress-tested included synthetic diamond price volatility bands and CNC operator wage inflation across Germany and the United States. Segmentation modeling spanned product type, end-user scale, technology tier, and application intensity dimensions. CAGR derivation weighted historical replacement cycle patterns against retrofit versus greenfield investment splits reported by high-volume automotive rebuilders.
Stress conditions across abrasive material cost bands, distributor consolidation velocity, and generational skill attrition rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including REACH regulatory expansion, MIIT industrial policy shifts, and OSHA machine guarding standard updates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Lined Valves Market
Valves
Pneumatic Slide Gates Market
Valves
Middle East and Africa Industrial Valves Market
Valves
Global Fluid Management Systems Market
Valves
Steam Trap Valve Market
Valves
Electro Pneumatic Positioner Market
Valves
Global Globe Valve Market
Valves
Aerospace Valves Market
Valves
Pup Joint Market
Valves
Rising Stem Ball Valve Market
Valves
Construction Valve Seat Insert Market
Valves
Global Plug Valve Market
Valves
Liner Regulators Market
Valves
Vaneometer Market
Valves
Emergency Venting System Market
Valves
Global Valve Positioners Market