
 Submersible Pumps for Mining Sector Market | 2026-2036
Submersible Pumps for Mining Sector Market Size, Share, and Industry Trends Forecast 2026-2036
Submersible Pumps for Mining Sector Market Outlook
Australia's Pilbara iron ore expansion is fragmenting procurement patterns across the Asia-Pacific mining belt. Ebara Corporation anchors its position through backward integration into stainless steel casting for corrosion-resistant pump housings. The Weir Group differentiates via slurry handling expertise honed in Canadian oil sands applications. Xylem leverages digital monitoring platforms that reduce unplanned downtime in Chilean copper operations.
Submersible pumps for mining are hermetically sealed centrifugal units designed to operate fully immersed in slurry or groundwater, typically handling solids up to 120 millimeters and heads exceeding 600 meters for deep pit dewatering. These systems prevent flooding, enable continuous ore extraction, and manage acidic mine drainage that would otherwise halt operations. Slurry pumps capture the largest margin pool due to abrasive wear part replacement cycles, while electric submersible technology dominates installed base because of grid reliability in established mining districts. Dewatering pumps represent the fastest-growing application segment as open-pit operations deepen below water tables across Latin America and Africa.
EPA enforcement of Clean Water Act discharge limits shapes product specifications for US-based coal and hardrock operators, while Australia's Department of Industry, Science and Resources mandates progressive rehabilitation bonds that elevate pump reliability requirements. ISO 9001 and API 610 compliance increasingly gate supplier qualification for tier-one mining houses. Stakeholders must weigh total lifecycle cost against upfront capital outlay as energy efficiency standards tighten and remote monitoring becomes a baseline procurement criterion.
Market Dynamics
Deepening open-pit operations below water tables across Latin America and Africa are forcing continuous capital redeployment toward high-head dewatering infrastructure. The structural pressure to maintain ore extraction continuity while managing acidic mine drainage is compressing replacement cycles and elevating reliability specifications.
Growth Catalysts
- EPA Clean Water Act enforcement:Stricter discharge limits for US coal and hardrock operators mandate sealed motor designs that eliminate environmental leakage risks.
- Underground copper expansion:Chilean gold and copper operations require high-head systems exceeding 600 meters to manage flooding in deepening shafts.
- Pilbara iron ore basin development:Australia's pit flooding risks necessitate continuous pumping investment across multiple concurrent expansion projects.
Market Restraints
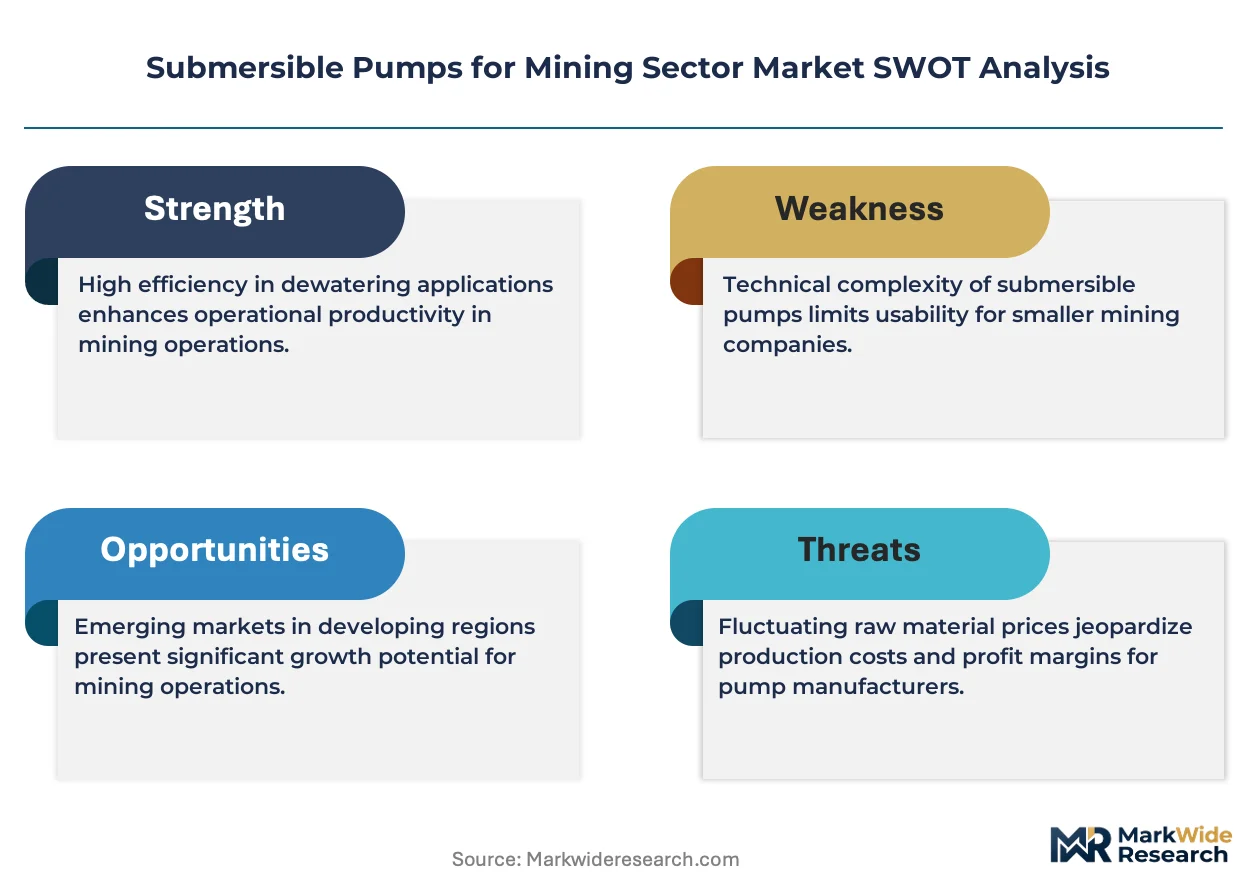
- Abrasive wear part replacement cycles:Slurry pump components face accelerated degradation from ore particulate loading, elevating total lifecycle costs beyond initial capital outlay tolerance.
- Stainless steel casting supply concentration:Corrosion-resistant pump housing production clusters in East Asian foundries, exposing procurement to freight volatility and trade policy friction.
- Grid reliability dependency:Electric submersible technology dominance in established mining districts creates vulnerability where power infrastructure remains underdeveloped.
Strategic Opportunities
- Digital monitoring platform convergence:Integration of vibration analysis with predictive maintenance algorithms creates aftermarket service revenue streams.
- African copperbelt underpenetration:Zambian and Congolese operations below 400 meters depth lack adequate dewatering infrastructure relative to extraction targets.
- Progressive rehabilitation bond requirements:Australia's Department of Industry mandates elevate pump reliability specifications, favoring suppliers with demonstrated mean-time-between-failure performance.
Industry Challenges
- ISO 9001 and API 610 certification timelines:Tier-one mining house qualification gates extend supplier onboarding by 18-24 months, compressing competitive response windows.
- Remote monitoring integration complexity:Legacy pump installations lack sensor infrastructure, requiring costly retrofit programs to meet baseline procurement criteria.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Submersible Pumps for Mining Sector Market |
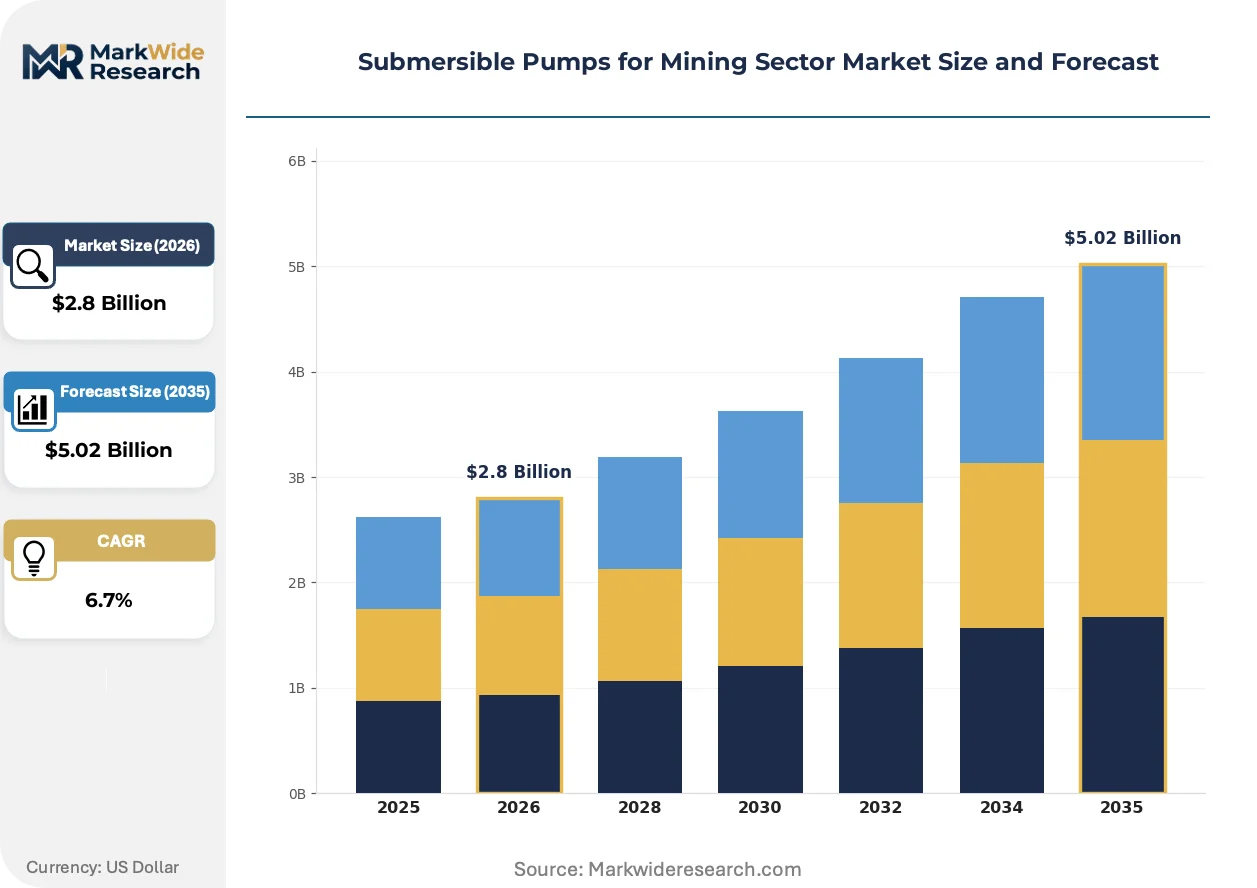
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slurry Pumps, Dewatering Pumps, Sewage Pumps, Hydraulic Submersible Pumps Application: Groundwater Extraction, Wastewater Handling, Mineral Processing, Surface Water Management Technology: Electric Submersible, Hydraulic Submersible, Solar-Powered, Pneumatic Submersible End User: Mining Operators, Construction Companies, Environmental Agencies, Resource Extraction Firms |
| Companies Covered | Ebara Corporation, The Weir Group, Xylem, Atlas Copco, Tsurumi Manufacturing, KSB Group, Sulzer Ltd, Grundfos, Flowserve Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Submersible Pumps for Mining Sector Market Strategic Shifts
Pump system architecture is undergoing fundamental redesign as operational depth requirements outpace conventional centrifugal performance envelopes. Equipment specifications now prioritize energy efficiency verification and real-time condition telemetry as standard procurement elements.
Ceramic-matrix composite impeller coatings are collapsing abrasive wear rates in slurry applications. Chilean copper operators are retrofitting existing pump trains with these surfaces during scheduled maintenance windows. The technology is collapsing replacement part demand curves and compressing aftermarket revenue timing for traditional casting suppliers.
REACH substance restrictions on hexavalent chromium plating are forcing European suppliers to accelerate tungsten carbide thermal spray adoption. The industrial consequence is elevated capital equipment cost structures for corrosion-resistant coatings. Slurry handling applications in Nordic mining operations are most affected, with procurement specifications now explicitly excluding legacy plating processes.
Service contract unbundling is fragmenting traditional full-wrap maintenance agreements. Mining operators in Australia's Pilbara region are separating predictive analytics subscriptions from physical repair labor, creating discrete procurement categories. This pattern is most visible among iron ore majors seeking to internalize diagnostic capabilities while outsourcing component replacement execution.
Submersible Pumps for Mining Sector Market Segmentation
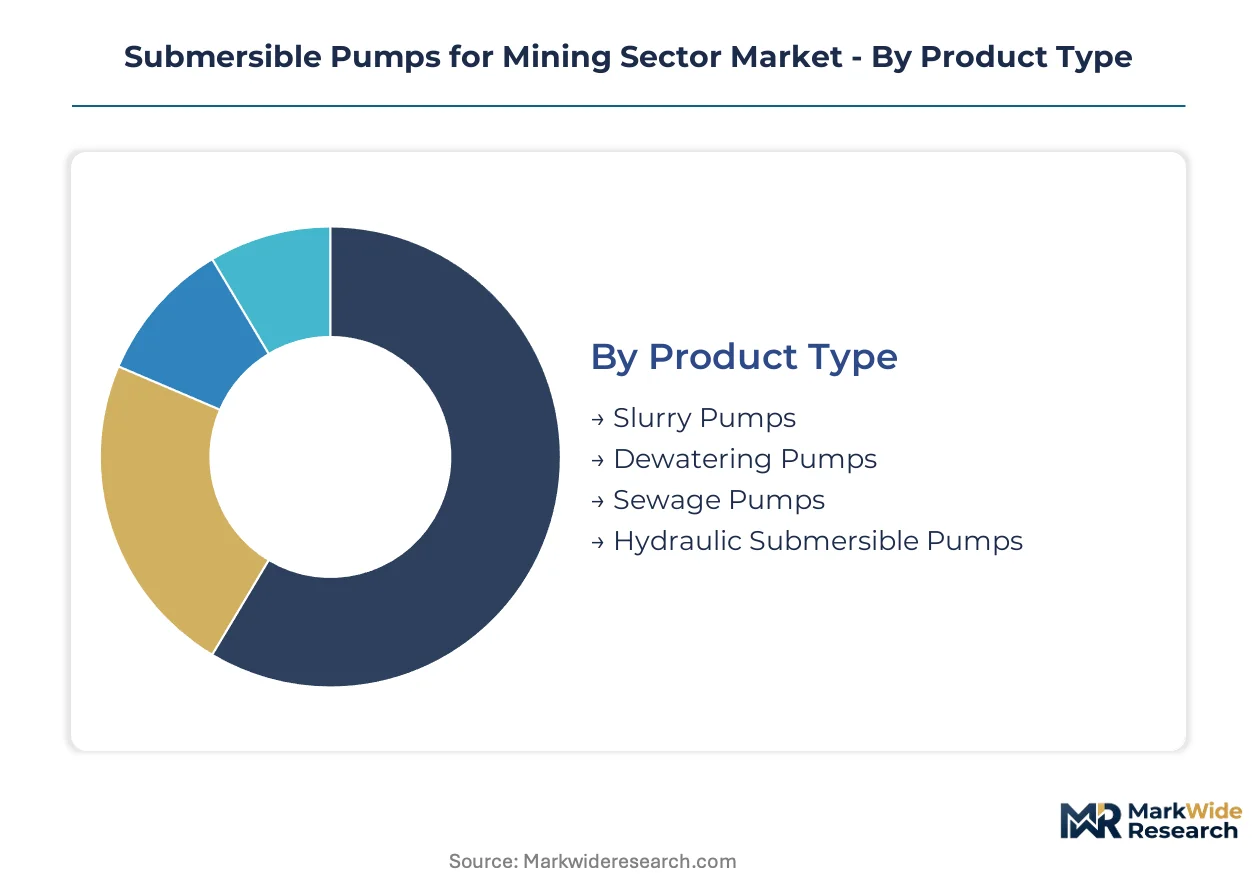
Submersible pump procurement patterns diverge sharply across operational contexts. Replacement cycles, energy infrastructure availability, and ore body chemistry dictate technology selection more than upfront capital cost.
Product Type:
Slurry pumps turn over fastest due to abrasive wear, while dewatering systems run longer but face pressure from deepening pit requirements.
- Slurry Pumps:These hermetically sealed units handle ore-laden fluids with solids up to 120 millimeters, utilizing hardened impellers and volutes against abrasive degradation. Chilean copper concentrators drive replacement demand as tailings density accelerates wear part consumption. The segment commands the largest margin pool through recurring component sales.
- Dewatering Pumps:High-head centrifugal designs exceeding 600 meters of lift address groundwater infiltration in open-pit and underground operations. Australia's Pilbara iron ore basin anchors procurement volume where pit flooding risks intensify with excavation depth. This category is expanding most quickly as Latin American and African operations descend below water tables.
- Sewage Pumps:Specialized units manage sanitary and process waste streams in remote camp infrastructure and processing facilities. Portable configurations dominate temporary construction phases.
- Hydraulic Submersible Pumps:Engine-driven alternatives deploy where electrical grid reliability remains inadequate, particularly in early-stage exploration and remote African copperbelt development.
Slurry pumps dominate installed base. Dewatering pumps are where expansion concentrates.
Application:
Cost tier separation is pronounced: groundwater extraction commands premium pricing for reliability, while surface water management competes on capital efficiency.
- Groundwater Extraction:Continuous dewatering of active excavation zones requires redundant pump trains with automatic failover capability. High-head electric submersibles predominate in established mining districts with stable grid supply.
- Wastewater Handling:Acidic mine drainage treatment demands corrosion-resistant metallurgy and sealed motor designs to prevent environmental release. EPA Clean Water Act enforcement elevates specifications for US hardrock operators.
- Mineral Processing:Slurry transfer between crushing, grinding, and flotation circuits consumes the highest pump horsepower per ton of ore processed.
- Surface Water Management:Seasonal rainfall diversion and pit rim drainage utilize lower-specification equipment with intermittent duty cycles.
Groundwater extraction commands the steepest price premiums. Wastewater handling is tightening specifications fastest.
Technology:
Volume concentration favors electric submersible technology where grid infrastructure exists, while hydraulic and solar alternatives address supply gaps.
- Electric Submersible:Grid-tied permanent magnet motor designs achieve highest efficiency across the 50-500 kilowatt range. Chilean state copper company Codelco standardizes on these for underground operations with reliable power supply.
- Hydraulic Submersible:Diesel power pack flexibility suits exploration phases and grid-constrained geographies including Zambian Copperbelt greenfield sites.
- Solar-Powered:Photovoltaic-driven units with battery storage address dewatering needs at remote satellite pits where transmission extension is uneconomical.
- Pneumatic Submersible:Compressed air operation provides intrinsic safety in gassy underground environments where electrical ignition risks are prohibitive.
Electric submersible technology anchors the revenue base. Solar-powered configurations are gaining share fastest in off-grid applications.
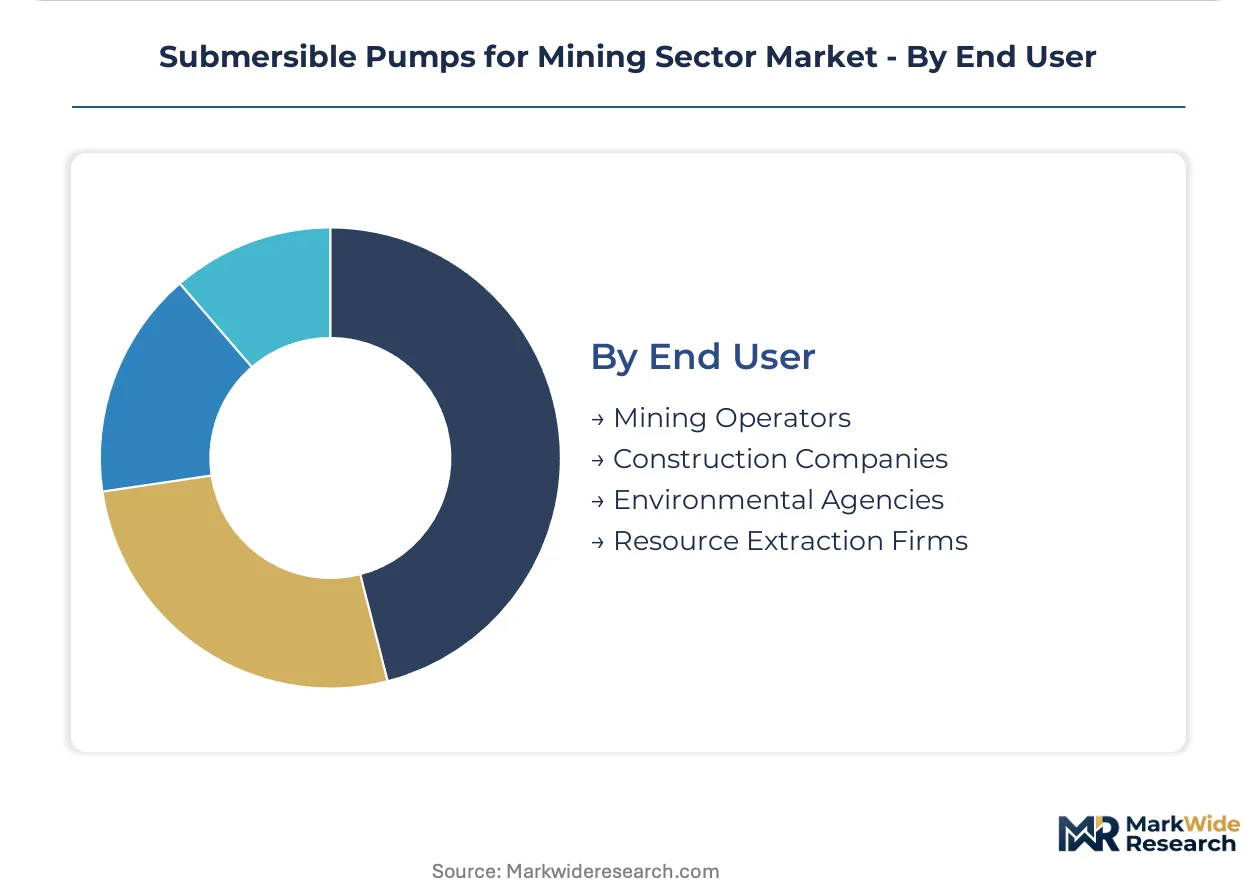
End User:
Customer type determines procurement sophistication: mining operators prioritize total lifecycle cost, while construction companies emphasize capital discipline.
- Mining Operators:Tier-one diversified miners specify ISO 9001 and API 610 compliance as baseline qualification, with predictive maintenance subscriptions increasingly required. BHP and Rio Tinto in Australia's Pilbara region unbundle service contracts to internalize diagnostics.
- Construction Companies:Project-based procurement favors rental and lease arrangements over ownership, with equipment redeployment across sequential contracts.
- Environmental Agencies:Regulatory-driven remediation projects specify sealed motor designs and continuous monitoring to demonstrate discharge compliance.
- Resource Extraction Firms:Junior miners and specialty operators balance capital constraints against reliability requirements through refurbished equipment and extended warranty negotiations.
Mining operators concentrate procurement volume. Environmental agencies are tightening compliance requirements fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corrosion-resistant pump housing production clusters heavily in East Asian foundries, exposing procurement networks to freight volatility and trade policy friction. Mining operators in Chile, Australia, and the United States absorb the highest per-unit landed costs when sourcing these critical components.
Chile
Underground copper and gold operations in the Atacama and Antofagasta regions drive demand for high-head dewatering systems exceeding 600 meters. Chile's Ministry of Mining enforces strict environmental closure bonds that elevate pump reliability specifications. Codelco's Chuquicamata and El Teniente complexes anchor procurement volume for sealed motor designs.
Australia
The Pilbara iron ore basin necessitates continuous pumping investment across multiple concurrent expansion projects by BHP and Rio Tinto. The Department of Industry, Science and Resources mandates progressive rehabilitation bonds that compress replacement cycles. Perth-based engineering clusters coordinate procurement for remote Western Australian operations.
United States
EPA enforcement of Clean Water Act discharge limits shapes product specifications for Appalachian coal and Western hardrock operators. Stricter rules mandate sealed motor designs that eliminate environmental leakage risks. Arizona's copper belt and Nevada's gold districts concentrate procurement for wastewater handling applications.
China
Domestic coal mining and rare earth extraction drive volume demand for electric submersible technology in Shanxi and Inner Mongolia. The Ministry of Ecology and Environment tightens mine water discharge standards under evolving GB standards. Jiangsu and Zhejiang foundry clusters supply corrosion-resistant castings to domestic and export markets.
South Africa
Deep platinum and gold operations in the Bushveld Complex and Witwatersrand Basin require high-head dewatering infrastructure below 400 meters. The Department of Mineral Resources and Energy enforces water use licensing that elevates pump efficiency requirements. Johannesburg engineering firms coordinate procurement for remote Northern Cape and Limpopo projects.
Submersible Pumps for Mining Sector Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in casting and coating supply. The vendor base separates into three strata: diversified industrial conglomerates with mining divisions, pure-play pump manufacturers with backward integration into metallurgy, and regional fabrication shops serving aftermarket replacement. Consolidation pressures intensify as tier-one mining houses unbundle service contracts and internalize diagnostic capabilities. Competitive moves center on ceramic-matrix composite coating adoption and predictive maintenance platform deployment.
Within the diversified industrial tier, Ebara Corporation and The Weir Group exemplify contrasting geographic anchors—Japanese and British origins respectively—while occupying similar positions as full-system providers. Xylem represents the digital-native archetype, having built monitoring platforms as core offerings rather than aftermarket attachments. These three entities illustrate how specialization in slurry handling, corrosion-resistant metallurgy, or telemetry integration creates defensible positioning against commodity fabrication competition.
| Leading Market Players |
|---|
| Ebara Corporation |
| The Weir Group |
| Xylem |
| Atlas Copco |
| Tsurumi Manufacturing |
| KSB Group |
| Sulzer Ltd |
| Grundfos |
| Flowserve Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in East Asian stainless steel foundries is compressing casting margins and forcing pump housing suppliers toward extended payment terms and volume-based discounting. This utilization dynamic simultaneously elevates buyer leverage in procurement negotiations while squeezing tier-two fabricators unable to secure captive metallurgy supply.
Pricing Analysis
EPA Clean Water Act enforcement dictates the pricing tier structure across the North American mining pump market. Three-tier pricing stratifies across API 610-certified premium systems, ISO 9001-compliant standard units, and economy-grade equipment for temporary dewatering applications. Price differentiation hinges on corrosion-resistant metallurgy grade and predictive maintenance bundling. Cost compression in the standard tier is intensifying because ceramic-matrix composite coatings are collapsing aftermarket part demand. Junior mining operators exhibit highest price sensitivity, while tier-one diversified miners prioritize mean-time-between-failure performance over capital outlay.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate procurement contracts as foundries absorb working capital pressure to maintain capacity utilization. Corrosion-resistant pump housing production clusters in China, Japan, and South Korea. Supply chains draw from nickel-alloy ingots, ceramic coating precursors, and permanent magnet motor components. Single-source vulnerability concentrates in Jiangsu and Zhejiang casting clusters exposed to freight volatility. Distribution runs through Perth-based engineering hubs for Australian Pilbara operations, Santiago technical offices for Chilean copper majors, and Johannesburg procurement centers for Southern African platinum and gold producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The submersible pump market rewards suppliers who control metallurgical casting capacity and predictive maintenance telemetry integration. Scarce in-house ceramic-matrix composite coating expertise separates margin leaders from commodity fabricators facing replacement cycle compression.
For Market Incumbents: Build predictive maintenance platform moats by unbundling diagnostic subscriptions from physical repair labor. Deepen backward integration into stainless steel casting to secure corrosion-resistant housing supply against East Asian trade friction. Invest in ISO 9001 and API 610 certification maintenance as tier-one mining houses tighten supplier qualification gates. Defensive positioning requires accelerating ceramic coating adoption before aftermarket revenue curves collapse further. For New Entrants and Emerging Players: Establish a beachhead in Zambian and Congolese copperbelt operations below 400 meters depth where dewatering infrastructure lags extraction targets. Target solar-powered submersible configurations for remote African satellite pits lacking grid extension economics. Pursue hydraulic submersible specialization for exploration-phase contracts where diesel power pack flexibility outweighs electric efficiency. Go-to-market traction requires partnering with Johannesburg or Perth engineering clusters for aftermarket service reach. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier pump manufacturers with captive foundry capacity and demonstrated Codelco or BHP qualification history. Long-term viability favors suppliers who have internalized ceramic coating expertise ahead of REACH-driven hexavalent chromium plating obsolescence. Watch for inflection signals in Australian progressive rehabilitation bond enforcement tightening, which would accelerate replacement cycle compression and favor reliability-proven incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Matrix Composite Coating Adoption | Chilean copper operators are retrofitting pump trains during maintenance windows, collapsing traditional wear part demand curves. |
| Predictive Maintenance Platform Deployment | Xylem's vibration analysis integration reduces unplanned downtime in Codelco underground operations, creating recurring revenue streams. |
| Backward Integration into Stainless Steel Casting | Ebara Corporation's captive metallurgy supply insulates procurement from East Asian foundry concentration risks and freight volatility. |
| API 610 Certification Investment | Tier-one mining houses including BHP and Rio Tinto mandate this qualification as baseline procurement criteria, extending competitive moats. |
| Solar-Powered Configuration Development | Photovoltaic-driven units with battery storage address dewatering needs at remote Zambian satellite pits where grid extension is uneconomical. |
Study Parameters
The analysis maps slurry pumps, dewatering systems, sewage pumps, and hydraulic submersible configurations, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary interviews with mining operators in Chile's Atacama region, Australia's Pilbara basin, and South Africa's Bushveld Complex were cross-referenced against customs and trade data, SEC filings from diversified industrial conglomerates, Department of Industry technical standards, and EPA enforcement records. Bottom-up equipment installation tracking and top-down mining capital expenditure analysis were triangulated to reconcile volume estimates.
Forecasts assume constant regulatory enforcement intensity across the analysis window, with copper and iron ore price trajectories held within historical volatility bands. Segmentation modeling incorporated product type, application context, technology architecture, and end-user procurement sophistication. CAGRs were derived from equipment replacement cycle analysis and pit depth progression curves in Latin American and African operations. Key inputs included Codelco dewatering infrastructure budgets, BHP Pilbara expansion timelines, and Zambian copperbelt electrification project pipelines.
Sensitivities concentrate around EPA Clean Water Act enforcement escalation, Australian progressive rehabilitation bond recalibration, and ceramic-matrix composite coating adoption velocity. Forecasts reflect documented assumptions regarding grid reliability in established mining districts and stainless steel casting capacity utilization in East Asian foundries. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Latin America Positive Displacement Pumps Market
Pumps and Control Devices
Global Reciprocating Pumps Market
Pumps and Control Devices
Positive Displacement (PD) Sanitary Pumps Market
Pumps and Control Devices
Centrifugal Water Pump Market
Pumps and Control Devices
Jetting Pumps Market
Pumps and Control Devices
Water Pump Market
Pumps and Control Devices
Solar Water Pump Market
Pumps and Control Devices
Water Desalination Pumps Market
Pumps and Control Devices
Europe Submersible Pump Market
Pumps and Control Devices
Hydraulic Pumps Market
Pumps and Control Devices
Industrial Aerators Market
Pumps and Control Devices
Fuel Feed Pumps Market
Pumps and Control Devices
Global Positive Displacement (PD) Pumps Market
Pumps and Control Devices
Automatic Tube Cleaning System Market
Pumps and Control Devices
Liquid Dispensing Pump Market
Pumps and Control Devices
Water Intake Screens Market