
 Mixed Flow Pump Market | 2026-2036
Mixed Flow Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Mixed Flow Pump Market Analytics
China's industrial pump manufacturing belt is reshaping competitive dynamics in the mixed flow pump sector. Sulzer Ltd leverages its Swiss engineering heritage to dominate high-specification vertical pump installations for desalination plants. Grundfos Holding A/S anchors its position through backward integration into permanent magnet motor technology, cutting energy losses across its submersible range.
A mixed flow pump combines axial and radial flow principles, operating at specific speeds between 4,200 and 9,000 rpm to move large fluid volumes against moderate heads. Its impeller geometry generates a diagonal discharge pattern suited to flood control, drainage, and raw water intake applications where suspended solids tolerance matters. Horizontal pumps occupy the mature replacement segment in municipal water systems, while submersible pumps capture the fastest growth in offshore oilfield seawater lift duties. Dry installation configurations command premium margins in chemical processing environments where hazardous fluid containment drives specification stringency.
EPA efficiency standards under the Clean Water Act shape product design requirements for US municipal procurement, while REACH compliance in Europe restricts seal material chemistries in cantilever pump assemblies. China's GB 19762 pump energy efficiency grades force domestic manufacturers toward higher-specific-speed designs. Stakeholders must monitor how IEC 60034-30-1 efficiency class migrations will redefine minimum acceptable performance thresholds across export markets.
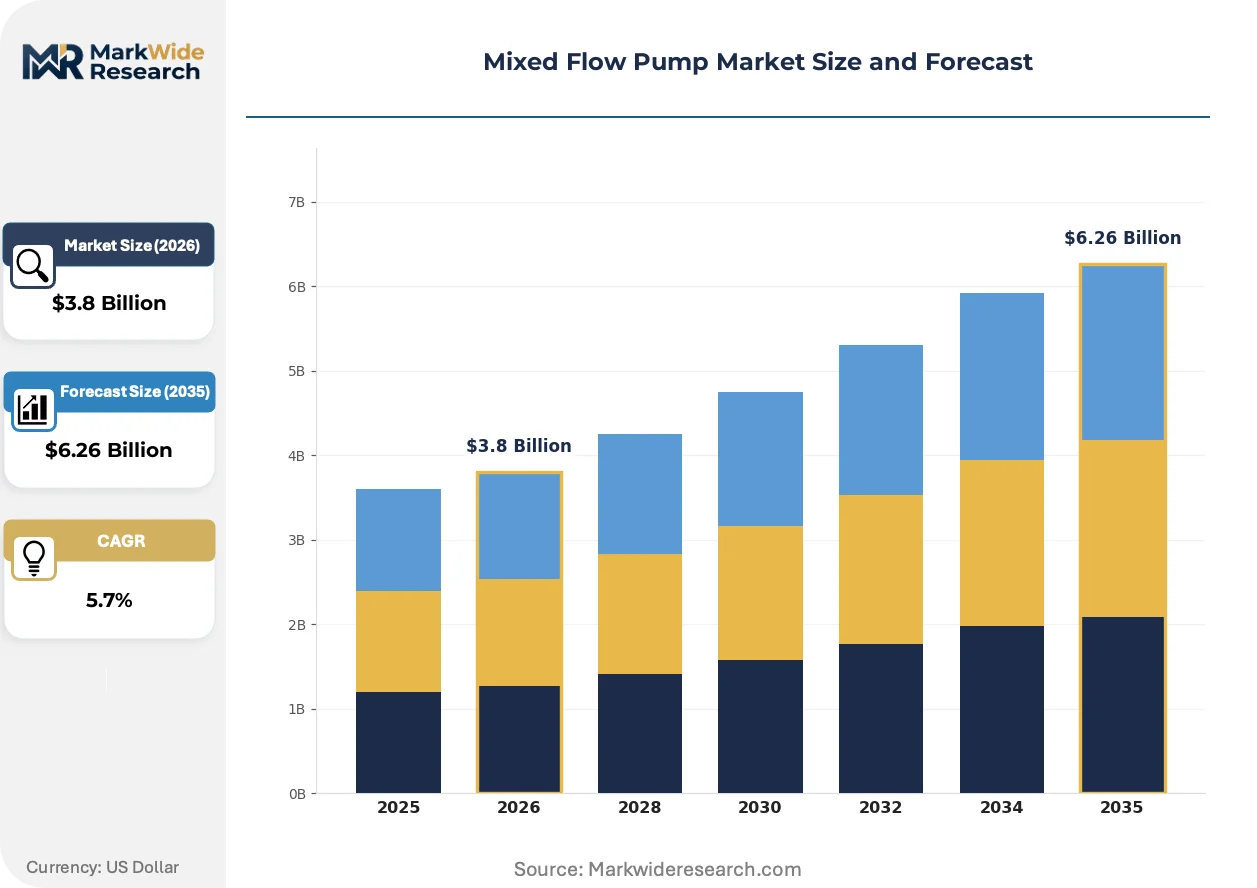
Market Dynamics
The EU Ecodesign Directive is compressing the installed base of low-efficiency mixed flow pumps while India's agricultural modernization corridors generate replacement demand for higher-specific-speed designs.
Growth Catalysts
- REACH compliance mandates:European chemical processors are retrofitting cantilever pump assemblies with compliant seal materials, forcing hardware refresh cycles across industrial water intake facilities.
- Desalination capacity expansion:Saudi Arabia and UAE utilities are procuring vertical mixed flow units for seawater reverse osmosis pre-treatment, prioritizing corrosion-resistant metallurgy.
- GB 19762 efficiency grades:China's domestic pump manufacturers are redesigning impeller geometries to meet Grade 1 and 2 thresholds, accelerating technology transfer from state-backed research institutes.
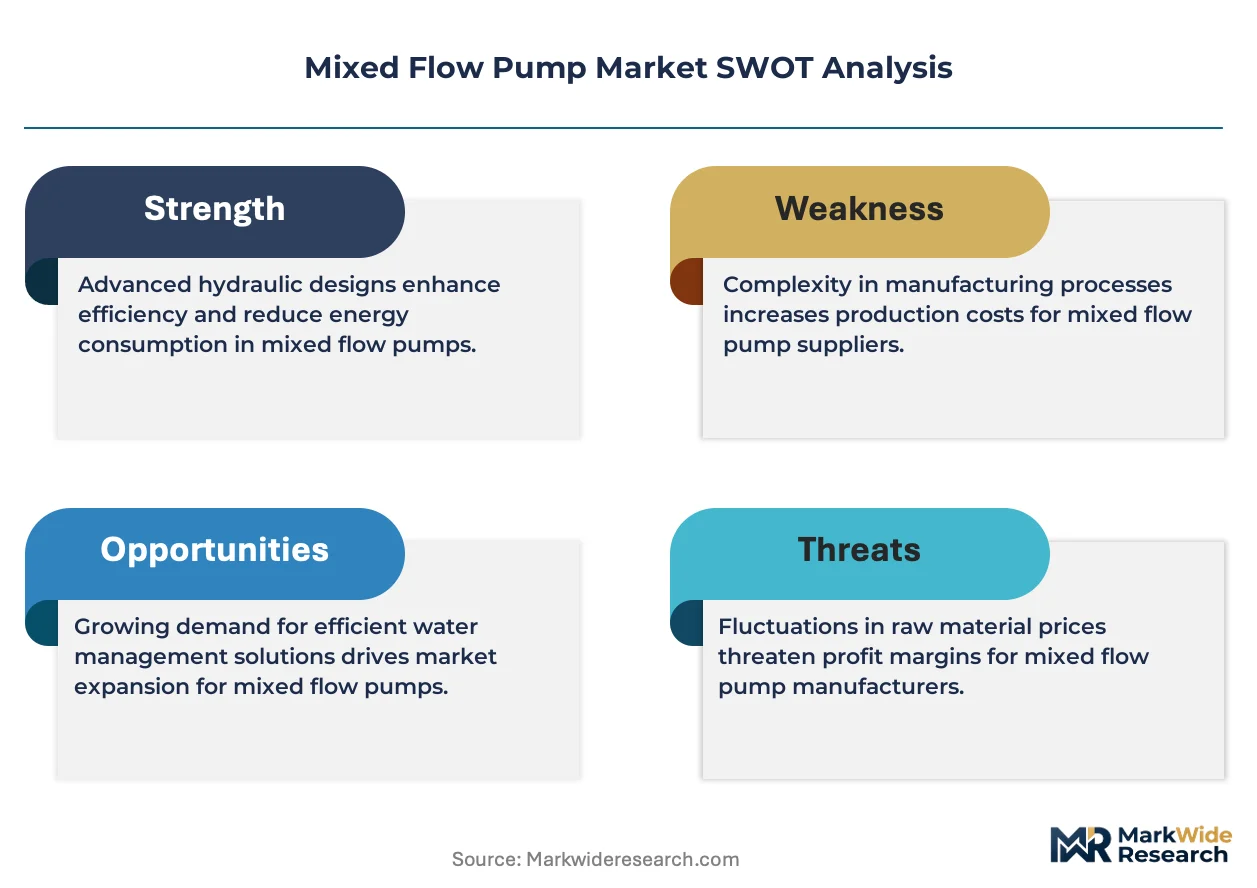
Market Restraints
- Permanent magnet motor supply concentration:Rare earth processing capacity clusters in China's Jiangxi and Inner Mongolia provinces, exposing non-Chinese pump OEMs to input cost volatility and export quota risks.
- Cast iron and stainless steel price cycles:Foundry energy costs in Germany and Italy have compressed margins for standard-duty horizontal pump configurations.
- Submersible cable technical limitations:Polymer jacket degradation in high-salinity offshore oilfield environments restricts deployment depth and duty cycles for seawater lift applications.
Strategic Opportunities
- Vietnam's Mekong Delta irrigation:State-funded agricultural mechanization programs are creating first-time demand for flood control drainage pumps in provinces previously served by traditional axial flow designs.
- Permanent magnet synchronous motor convergence:Integration with variable frequency drives is enabling part-load efficiency gains that match pump curves to fluctuating raw water intake volumes.
- EU Green Deal industrial decarbonization incentives:Carbon border adjustment mechanisms are rewarding pump system upgrades that reduce lifecycle energy consumption in water treatment utilities.
Industry Challenges
- Computational fluid dynamics talent scarcity:Impeller design optimization requires specialized simulation expertise that concentrates in Swiss and German engineering consultancies, constraining in-house R&D expansion.
- IEC 60034-30-1 IE4 certification timelines:Motor efficiency class migrations are extending product validation cycles and delaying market entry for redesigned pump-motor packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mixed Flow Pump Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Pumps, Vertical Pumps, Submersible Pumps, Cantilever Pumps End Use Industry: Water Treatment, Oil & Gas, Agriculture, Chemical Processing Installation Type: Dry Installation, Wet Installation, Semi-Wet Installation, Portable Installation Capacity: Low Capacity, Medium Capacity, High Capacity, Customized Capacity |
| Companies Covered | Sulzer Ltd, Xylem Inc, Grundfos Holding A/S, Flowserve Corporation, Pentair plc, Kubota Corporation, Franklin Electric, Ebara Corporation, Kirloskar Brothers Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mixed Flow Pump Market Evolving Landscape
Computational modeling and materials science are converging to redefine hydraulic efficiency boundaries in mixed flow pump design. Three developments are compressing traditional performance trade-offs between specific speed, solids handling, and energy consumption.
Composite-reinforced metallic impellers are hybridizing structural properties of cast stainless steel with weight reduction benefits of polymer matrix materials. Offshore platform operators in the North Sea are specifying these hybrid designs for seawater lift duties where corrosion fatigue historically limited service intervals. The technology is hybridizing the procurement calculus between capital cost and lifecycle maintenance exposure.
EPA efficiency standards under the Clean Water Act are tightening minimum performance requirements for municipal water system procurements above 75 horsepower. US utilities in California and Texas are now specifying pumps that exceed baseline Energy Star thresholds by 8-12 percentage points. The regulation is compressing the viable supplier base to manufacturers with captive motor design capabilities.
Performance-based service contracts are displacing traditional spare parts and maintenance agreements in European industrial water treatment. End-users in Germany's chemical processing belt are contracting guaranteed availability metrics rather than purchasing pumps outright. Dutch and Belgian distributors are restructuring field service organizations to capture recurring revenue from uptime guarantees.
Mixed Flow Pump Market Segmentation
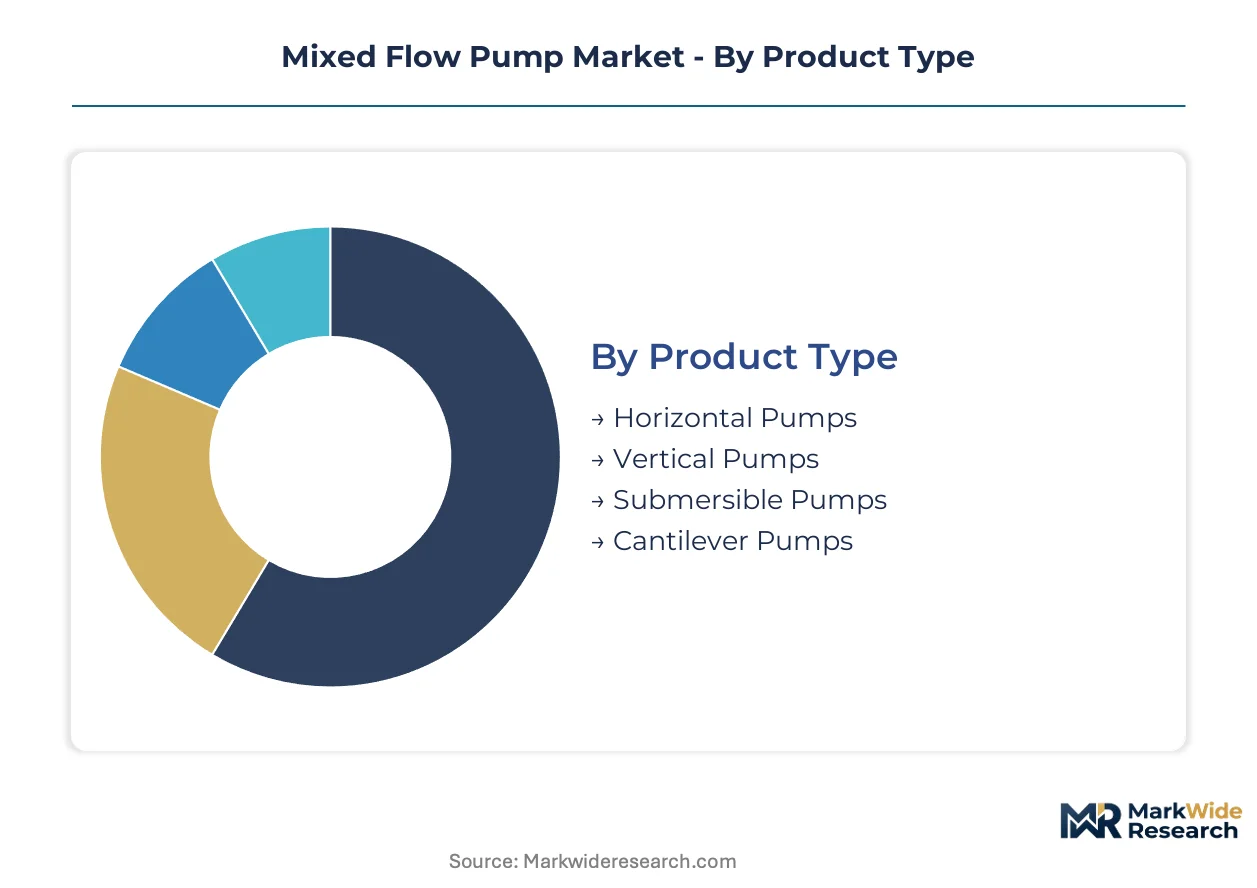
Mixed flow pump specification diverges sharply across duty cycles, fluid chemistry, and site constraints. Procurement teams segment requirements by hydraulic performance envelope, metallurgical compatibility, and maintenance accessibility before selecting configurations.
Product Type:
Maturity spreads unevenly across the mechanical configuration spectrum, with dry-mounted architectures dominating replacement schedules while submersible designs capture greenfield capital deployment.
- Horizontal Pumps:Split-case or end-suction configurations with bearings on both sides of the impeller suit above-grade pump houses with crane access. Municipal water utilities in legacy US infrastructure corridors specify these for ease of seal replacement without wet-well dewatering.
- Vertical Pumps:Column-suspended designs with motors mounted at grade level drive deep-set intake applications. Desalination pre-treatment facilities in Saudi Arabia and UAE procurement frameworks prioritize these for corrosion-resistant metallurgy in seawater exposure.
- Submersible Pumps:Integrated motor-pump units eliminate shaft alignment maintenance. Offshore platform operators in the North Sea deploy these for seawater lift where deck space constraints prohibit dry-pit construction.
- Cantilever Pumps:Bearingless designs with overhung impellers handle slurry and abrasive fluids. Chemical processors under REACH compliance mandates retrofit these with compliant seal materials to satisfy ECHA substance restrictions.
Horizontal pumps retain volume leadership in municipal replacement cycles; submersible pumps hold the steepest expansion curve in offshore oilfield seawater duties.
End Use Industry:
Application intensity varies by fluid volume requirements, solids tolerance thresholds, and energy cost exposure across industrial verticals.
- Water Treatment:Raw water intake, filtration backwash, and tertiary discharge duties demand high specific-speed designs. EPA Clean Water Act efficiency standards above 75 horsepower compress supplier eligibility to manufacturers with captive motor capabilities.
- Oil & Gas:Produced water reinjection and seawater flooding operations require corrosion-resistant alloys. GB 19762 efficiency grades in China force domestic operators toward Grade 1 pump-motor packages for new field developments.
- Agriculture:Flood control and irrigation drainage in India's Gujarat and Punjab corridors drive demand for solids-tolerant impeller geometries. State-funded mechanization programs expand procurement of higher-specific-speed units.
- Chemical Processing:Hazardous fluid containment specifications command premium margins for dry installation configurations. EU Ecodesign Directive minimum efficiency requirements accelerate hardware refresh cycles across German and Belgian processing belts.
Water treatment absorbs the largest equipment volume; agriculture climbs fastest on India's modernization corridor investments.
Installation Type:
Site civil works and containment risk determine capex-opex trade-offs between submerged and dry-pump architectures.
- Dry Installation:Pump houses with ventilation and spill containment suit chemical processing environments. Premium margins reflect hazardous fluid secondary containment requirements and OSHA process safety compliance.
- Wet Installation:Submerged motor-pump units eliminate suction lift limitations. Polymer jacket degradation in high-salinity offshore environments restricts deployment depth for seawater lift applications.
- Semi-Wet Installation:Motors at grade with hydraulic drives below waterline split maintenance accessibility from fluid exposure. Dutch water utilities favor these for polder drainage where fluctuating water tables complicate fixed elevations.
- Portable Installation:Skid-mounted or trailer configurations enable emergency flood response. Vietnam's Mekong Delta irrigation programs create first-time demand for mobile drainage assets in provinces previously served by fixed axial flow designs.
Dry installation commands the highest unit margins; portable configurations gain share fastest on climate adaptation infrastructure spending.
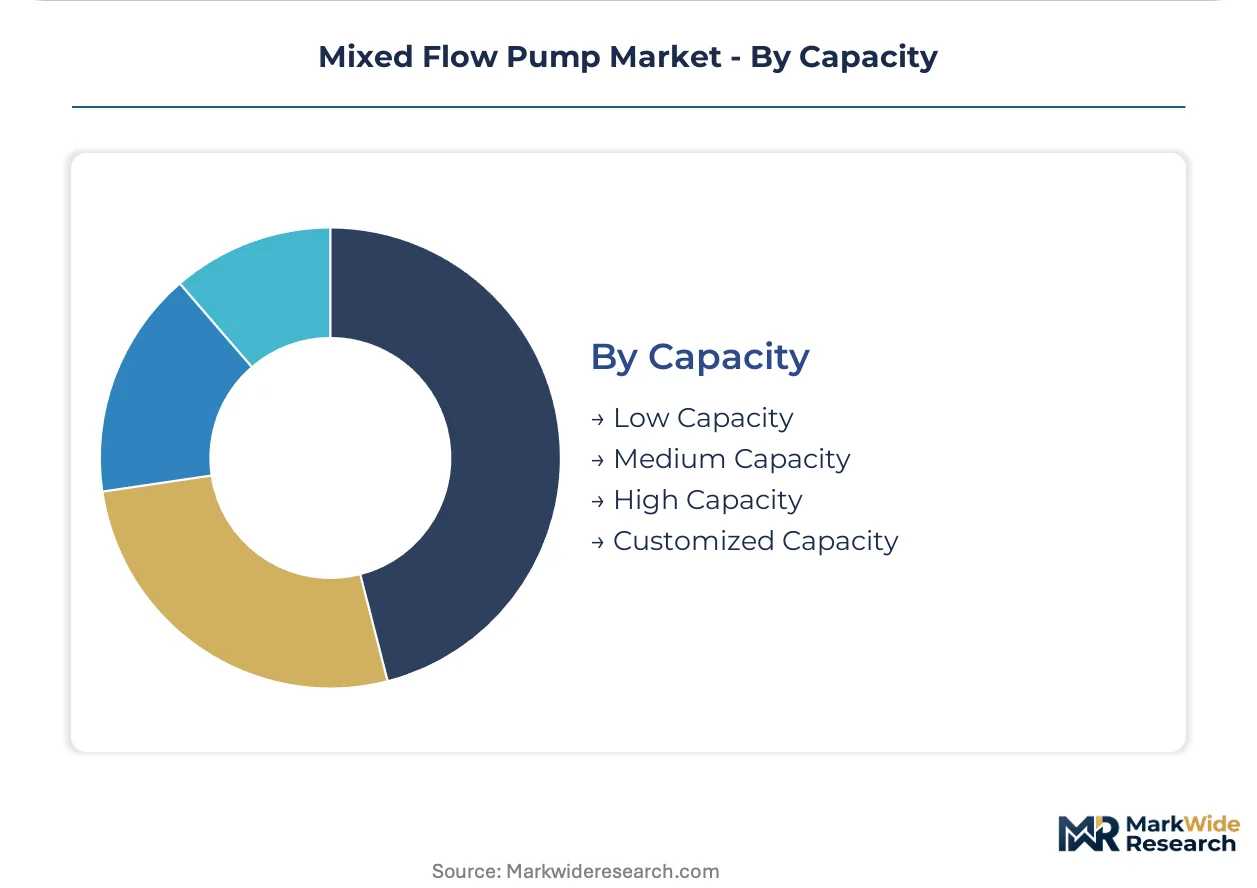
Capacity:
Scale economies and customization intensity segment manufacturing workflows between standardized castings and engineered-to-order hydraulic sections.
- Low Capacity:Cast iron or thermoplastic housings serve residential and light commercial drainage. Foundry energy costs in Germany and Italy compress margins for these commodity configurations.
- Medium Capacity:Standardized stainless steel impellers balance corrosion resistance with production volume. Municipal utilities in Southeast Asia expand procurement of these units for distribution network upgrades.
- High Capacity:Fabricated or cast alloy hydraulic sections with computational fluid dynamics-optimized vanes. Permanent magnet synchronous motor integration enables part-load efficiency matching to fluctuating raw water intake volumes.
- Customized Capacity:Engineered-to-order designs for unique head-flow combinations. IEC 60034-30-1 IE4 certification timelines extend validation cycles for these specialized pump-motor packages.
Medium capacity dominates unit shipments; customized capacity expands most quickly on desalination and offshore project specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA efficiency standards under the Clean Water Act anchor procurement requirements in the United States, while China's GB 19762 grades and the EU Ecodesign Directive collectively reshape manufacturing specifications across three major production zones.
United States
Municipal water utilities in California and Texas drive specification shifts above 75 horsepower thresholds. EPA Clean Water Act mandates compress supplier eligibility to manufacturers with captive motor design capabilities. Los Angeles County water districts now procure pumps exceeding Energy Star baselines by 8-12 percentage points.
China
Industrial pump manufacturing concentrates in Jiangsu and Zhejiang provinces where state-funded mechanization accelerates technology transfer. GB 19762 efficiency grades force domestic manufacturers toward Grade 1 and Grade 2 impeller geometries. Shanghai-based research institutes partner with foundries to optimize higher-specific-speed designs for agricultural modernization.
Germany
Chemical processors in the Rhine-Ruhr belt retrofit cantilever pump assemblies under REACH compliance mandates. EU Ecodesign Directive minimum efficiency requirements accelerate hardware refresh cycles across industrial water intake facilities. Bavarian engineering consultancies concentrate computational fluid dynamics expertise for impeller optimization.
India
Agricultural modernization corridors in Gujarat and Punjab generate replacement demand for solids-tolerant impeller geometries. State-funded mechanization programs expand procurement of higher-specific-speed units for flood control drainage. Tamil Nadu water treatment utilities adopt medium-capacity stainless steel configurations for distribution network upgrades.
Saudi Arabia
Seawater reverse osmosis pre-treatment facilities procure vertical mixed flow units with corrosion-resistant metallurgy. Utilities prioritize Grade 316L and duplex stainless steel specifications for Red Sea exposure. Jubail Industrial City desalination complexes anchor regional demand for premium-duty vertical pump configurations.
Mixed Flow Pump Market Competitive Landscape
Swiss-German engineering specialists and integrated motor-pump manufacturers split the market between premium specification and energy efficiency vectors. The installed base consolidates around three strategic archetypes: European heritage engineering houses, Asian scale fabricators with captive foundry capacity, and motor-integrated system specialists. Competitive moves center on backward integration into permanent magnet motor technology and computational fluid dynamics talent acquisition from specialized consultancies.
Among heritage European engineering houses, Sulzer Ltd and Grundfos Holding A/S exemplify divergent positioning strategies. Sulzer anchors the high-specification vertical pump segment for desalination and chemical processing applications. Grundfos represents the motor-integrated system archetype through upstream control over permanent magnet technology. Japanese fabricators Ebara Corporation and Kubota Corporation occupy positions in the corrosion-resistant alloy and agricultural mechanization vectors respectively.
| Leading Market Players |
|---|
| Sulzer Ltd |
| Xylem Inc |
| Grundfos Holding A/S |
| Flowserve Corporation |
| Pentair plc |
| Kubota Corporation |
| Franklin Electric |
| Ebara Corporation |
| Kirloskar Brothers Limited |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor's freight cost volatility transmits directly into landed price spreads between Asian fabricators and European engineering houses, compressing margin buffers for standard-duty horizontal pump configurations while amplifying premium capture for corrosion-resistant vertical units specified by Red Sea desalination utilities.
Pricing Analysis
Geographic price spreads of 15-25 percentage points separate Jiangsu-manufactured commodity castings from Swiss-engineered vertical pump packages for seawater reverse osmosis pre-treatment. Three-tier pricing structure across premium, standard, and economy levels stratifies by metallurgical grade and IEC 60034-30-1 efficiency certification tier. Cost compression in the standard-duty segment intensifies because foundry energy costs in Germany and Italy have eliminated margin cushion. Municipal water utilities in legacy US infrastructure corridors exhibit highest price sensitivity, while offshore platform operators in the North Sea demonstrate lowest sensitivity due to lifecycle maintenance exposure calculus.
Supply Chain Analysis
Export-control restrictions on permanent magnet synchronous motor technology limit technology transfer from state-backed Chinese research institutes to non-domestic pump OEMs, concentrating rare earth processing capacity in Jiangxi and Inner Mongolia provinces. Foundry operations in China, Germany, and Italy supply cast stainless steel hydraulic sections; permanent magnet motors and specialized seal materials draw from concentrated upstream nodes. Single-source vulnerability in rare earth magnet supply exposes non-Chinese manufacturers to quota risk and input cost volatility. Distribution runs through authorized distributors with field service capabilities for aftermarket parts and maintenance contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mixed flow pump market functions as a defensive-moat sector where regulatory entrenchment through efficiency certification requirements creates substantial switching costs for municipal and industrial procurement teams.
For Market Incumbents: Entrench market position by acquiring computational fluid dynamics talent from Bavarian engineering consultancies to accelerate impeller optimization cycles, and by establishing captive permanent magnet motor production to insulate against rare earth supply disruption from Jiangxi province concentration. The threat of Chinese domestic manufacturers achieving Grade 1 GB 19762 certification parity demands preemptive investment in higher-specific-speed design capabilities.
For New Entrants and Emerging Players: Build out specialized service capabilities for performance-based uptime contracting in Germany's chemical processing belt, where incumbent distributors are restructuring field organizations to capture recurring revenue. Vietnam's Mekong Delta irrigation programs represent the most penetrable geography, with state-funded mechanization creating first-time demand for mobile drainage assets. A go-to-market angle anchored in portable installation configurations with rapid deployment protocols bypasses entrenched municipal procurement relationships.
For Investors and Strategic Acquirers: Engineering consultancies with captive CFD simulation expertise and established relationships with Swiss-German heritage pump manufacturers represent the priority acquisition archetype. Long-term viability rests on regulatory ratchet effects from EU Ecodesign Directive and EPA Clean Water Act efficiency standards that compress viable supplier bases. The signal to monitor is IEC 60034-30-1 IE4 certification timeline acceleration, which would extend validation cycles and favor incumbents with established testing infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Motors | Captive motor production insulates against Jiangxi rare earth quota volatility and GB 19762 compliance acceleration. |
| CFD Talent Acquisition from Specialized Consultancies | Bavarian engineering expertise concentration constrains in-house R&D expansion without external capability injection. |
| Performance-Based Service Contract Expansion | Dutch and Belgian distributors restructuring field organizations around uptime guarantees displace traditional spare parts revenue models. |
| Corrosion-Resistant Metallurgy Investment | Jubail Industrial City desalination complexes anchor regional demand for Grade 316L and duplex stainless steel specifications. |
| Portable Installation Configuration Development | Vietnam's Mekong Delta irrigation programs create first-time demand for mobile drainage assets in climate adaptation infrastructure. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal water utility procurement managers, offshore platform maintenance directors, chemical processing plant engineers, agricultural mechanization program officers, and pump distributor field service heads. Secondary validation drew from EPA Clean Water Act regulatory filings, EU Ecodesign Directive implementation guidance, China's GB 19762 efficiency grade documentation, customs trade data for pump and motor imports, and SEC 10-K disclosures from listed industrial equipment manufacturers. Bottom-up unit shipment estimates by configuration type and top-down market sizing by end-use industry were triangulated to converge on value estimates.
Calibration against historical efficiency standard adoption curves and documented technology transfer timelines from state-backed research institutes anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, installation architecture, end-use industry vertical, capacity tier, and regional regulatory cluster. CAGRs were derived from regression analysis of procurement volume patterns against efficiency mandate implementation schedules. Industry-specific forecast inputs incorporated documented desalination capacity expansion pipelines and India's agricultural modernization corridor investment flows.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-subsidized Chinese manufacturers to capture Grade 1 certification parity ahead of schedule would shift outcomes beyond modeled bounds. Material shifts in rare earth export quota policy or IEC 60034-30-1 efficiency class migration timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Asia Pacific Vacuum Pumps Market
Pumps and Control Devices
Flow Back Equipment Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Electric Oil Pump Market
Pumps and Control Devices
Seawater Cooling Pumps Market
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Membrane Pump Market
Pumps and Control Devices
Rental Industrial Pump Market
Pumps and Control Devices
Canned Motor Pumps Market
Pumps and Control Devices
Liquid Dispensing Pump Market
Pumps and Control Devices
Radial Split Pump Market
Pumps and Control Devices
Global Diaphragm Pump Market
Pumps and Control Devices
Hydraulic Dosing Pump Market
Pumps and Control Devices
Centrifugal Pump Market
Pumps and Control Devices
Global Hydraulic Metering Pump Market
Pumps and Control Devices
Global Hydrocyclone Market