

High Precision Microfluidic Pump Market Size, Share, and Industry Trends Forecast 2026-2036
High Precision Microfluidic Pump Market Insights
Buyer concentration in pharmaceutical manufacturing is decoupling from traditional research laboratory procurement patterns as contract drug developers multiply across Asia and Eastern Europe. Harvard Apparatus leverages its heritage in syringe pump design to sustain premium positioning in North American academic markets. Bürkert competes through fluid control integration that extends its valve expertise into pump architectures. Dolomite Microfluidics anchors its position in droplet microfluidics applications where chip-pump integration commands technical loyalty.
High precision microfluidic pumps deliver volumetric flow control within nanoliter-to-microliter ranges, typically achieving accuracy below one percent variation through piezoelectric actuation or pressure-driven displacement mechanisms. These devices enable reproducible fluid handling in analytical instruments, point-of-care diagnostic platforms, and automated laboratory workflows. Syringe pumps occupy the largest installed base owing to straightforward calibration and broad chemical compatibility, while piezoelectric pumps capture the fastest expansion as miniaturization demands intensify in portable diagnostic devices. Pressure driven technology dominates current revenue owing to mature controller ecosystems, though acoustic methods are displacing legacy approaches in cell handling applications where shear sensitivity governs viability.
FDA 21 CFR Part 820 quality system requirements and EU MDR conformity obligations shape product development cycles, particularly for pumps destined for drug delivery or in-vitro diagnostic integration. ISO 10993 biocompatibility testing and REACH substance restrictions further constrain material selection for wetted components. Stakeholders must monitor evolving EPA per- and polyfluoroalkyl substance regulations that threaten fluoropolymer tubing supply chains central to chemical resistance claims.
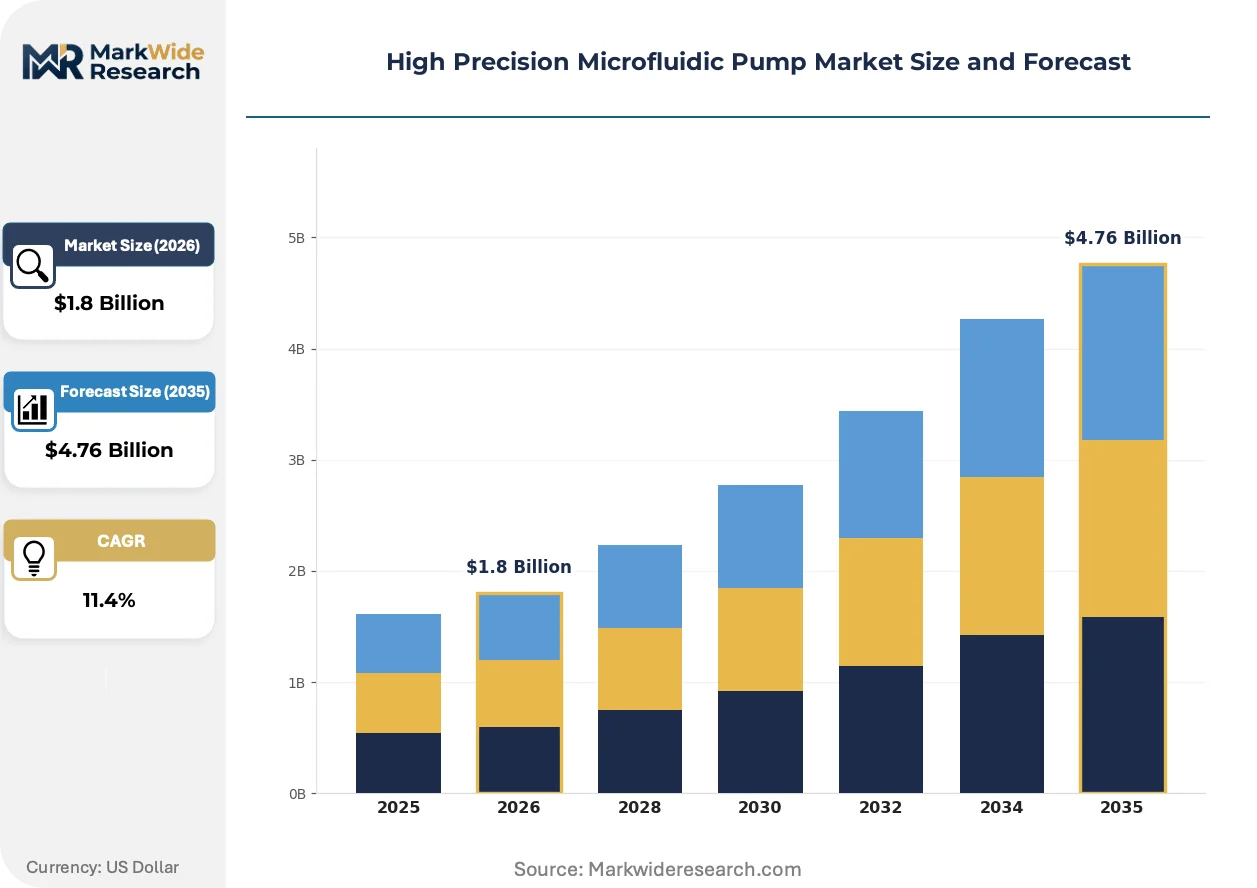
Market Dynamics
Pharmaceutical contract manufacturers are consolidating procurement authority away from decentralized R&D labs, creating volume concentration that rewards pump suppliers capable of ISO 13485-certified mass production over bespoke academic configurations.
Growth Catalysts
- EU MDR Conformity Pressure:Stricter in-vitro diagnostic device classification is forcing manufacturers to source medical-grade pumps with validated quality systems, eliminating uncertified suppliers from the vendor pool.
- Cell Therapy Manufacturing:Shear-sensitive bioprocessing for CAR-T and stem cell therapies is expanding demand for piezoelectric displacement mechanisms that maintain viability through precise flow control.
- Baden-Württemberg Precision Cluster:German engineering concentration around Stuttgart and Karlsruhe supplies both domestic pharmaceutical automation and export markets across Switzerland and Austria.
Market Restraints
- Fluoropolymer Supply Vulnerability:EPA per- and polyfluoroalkyl substance restrictions threaten tubing supply chains central to chemical resistance claims in wetted components.
- Piezoelectric Ceramic Concentration:Lead zirconate titanate actuator materials depend on concentrated rare earth processing capabilities in East Asian supply nodes.
- ISO 10993 Testing Burden:Extended biocompatibility validation timelines for new elastomer formulations delay product launches by 18-24 months in regulated diagnostic applications.
Strategic Opportunities
- Point-of-Care Miniaturization:Portable diagnostic platforms in India and Brazil require compact pressure-driven pumps with integrated controller electronics for decentralized testing infrastructure.
- Acoustic Droplet Ejection:Convergence of surface acoustic wave physics with microfluidic channel design enables contact-free cell handling for high-value biopharmaceutical screening workflows.
- US IRA Domestic Manufacturing Incentives:Production tax credits for pharmaceutical supply chain reshoring create procurement preference for FDA-registered pump assembly facilities.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:Recruitment of engineers combining fluid mechanics expertise with embedded systems firmware development lags behind product roadmap requirements.
- Legacy Instrument Integration:Retrofitting piezoelectric pumps into existing HPLC and mass spectrometry workflows requires proprietary adapter development that fragments R&D resources.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Precision Microfluidic Pump Market Trends and Innovations
Active flow control architectures are displacing passive capillary systems as pharmaceutical automation demands real-time process analytical technology integration.
Piezoelectric micro-diaphragm pumps with silicon-Pyrex bonded chambers are automating nanoliter dosing in automated compound management systems. Contract research organizations in Massachusetts and North Carolina are deploying these units at scale for high-throughput screening libraries. The technology is automating previously manual pipetting workflows while compressing compound consumption volumes by an order of magnitude.
REACH substance restriction proposals targeting perfluorinated compounds are forcing material substitutions in pump seals and tubing. German and Swiss pump manufacturers are accelerating validation of perfluoroelastomer alternatives ahead of anticipated ECHA authorization sunset dates. Diagnostic instrument OEMs are most affected, with several redesigning fluidic manifolds to accommodate thermoplastic elastomer compatibility.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships for standard syringe pump configurations. Academic medical centers in Texas and California are channeling volume through shared service agreements that bundle maintenance and calibration. This concentration is most visible in NIH-funded research institutions where administrative cost reduction mandates favor multi-year supplier contracts over spot purchases.
High Precision Microfluidic Pump Market Segmentation
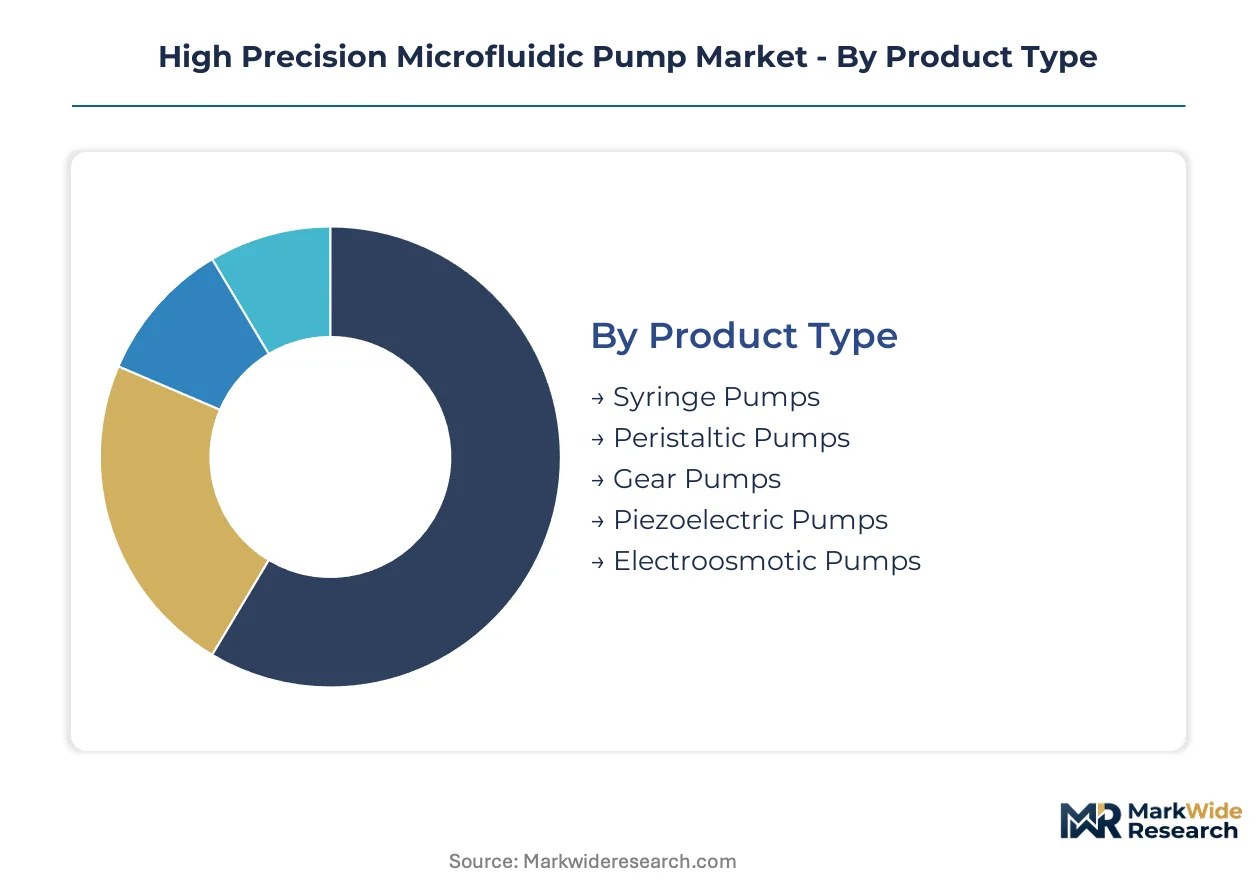
Pump selection in this market hinges on reconciling flow precision requirements with regulatory compliance burdens. Segmentation reveals how technical specifications diverge across end-use contexts, from mass-produced drug delivery systems to bespoke research configurations.
Product Type:
Syringe pumps dominate installed base volume while piezoelectric architectures command premium positioning in miniaturized applications.
- Syringe Pumps:These displacement mechanisms achieve sub-microliter accuracy through stepper motor-driven plunger actuation against calibrated glass barrels. Pharmaceutical manufacturers in Germany and Switzerland specify these for validated drug filling lines where traceable calibration certificates satisfy FDA 21 CFR Part 820 requirements.
- Piezoelectric Pumps:Ceramic actuator-driven diaphragm displacement enables nanoliter resolution within millimeter-scale form factors. Point-of-care diagnostic developers in India and Brazil are integrating these for portable glucose monitoring and infectious disease testing platforms where battery constraints prohibit larger motor assemblies.
- Peristaltic Pumps:Roller occlusion of elastomer tubing delivers chemically inert fluid paths without wetted seals.
- Gear Pumps:Meshed micro-machined rotors provide continuous flow without pulsation artifacts.
- Electroosmotic Pumps:Electric field-driven ionic mobility eliminates mechanical moving parts entirely.
Today's leader: Syringe Pumps. Tomorrow's challenger: Piezoelectric Pumps.
Technology:
Mature pressure-driven controllers face displacement from acoustic methods in cell-sensitive bioprocessing workflows.
- Pressure Driven:Regulated gas or liquid head pressure delivers flow through proportional valve modulation, leveraging decades of PID controller refinement. Environmental testing laboratories in the United States rely on these systems for automated groundwater and air sampling protocols where EPA methodology compliance demands reproducible flow profiles.
- Acoustic:Surface acoustic wave generation enables contact-free droplet manipulation with negligible shear stress. CAR-T cell therapy manufacturers in Massachusetts and North Carolina are adopting acoustic transfer for gentle cell washing steps that preserve viability through critical expansion phases.
- Centrifugal:Rotating impeller architectures scale flow rates beyond microfluidic regimes.
- Magnetic:Lorentz force actuation of ferrofluid plugs enables valveless pumping.
- Thermal:Bubble expansion and collapse cycles generate pulsatile flow in chip-integrated formats.
Pressure Driven retains the broadest applicability. Acoustic methods are climbing the fastest in high-value biopharmaceutical segments.
Application:
Drug delivery applications concentrate procurement authority while chemical analysis maintains steady replacement demand.
- Drug Delivery:Implantable and wearable infusion systems require pumps meeting ISO 10993 biocompatibility and ISO 13485 quality system standards. Contract manufacturers in Ireland and Puerto Rico are scaling automated assembly lines for insulin patch pumps and subcutaneous infusion devices.
- Chemical Analysis:Chromatography and mass spectrometry workflows demand pulse-free flow stability for reproducible retention times. Quality control laboratories in Baden-Württemberg deploy these for pharmaceutical raw material verification under EU GMP Annex 15 computerized system validation.
- Biotechnology Research:Academic and CRO settings prioritize configurability over regulatory certification.
- Environmental Testing:Field-deployable pumps must withstand temperature cycling and particulate contamination.
- Food Safety:Pathogen detection and allergen screening applications require cleanable fluidic paths.
Drug Delivery commands the steepest expansion trajectory. Chemical Analysis provides the most stable recurring revenue base.
End User:
Procurement centralization favors suppliers with medical-grade certification over research-oriented configurability.
- Pharmaceutical Manufacturers:These buyers enforce vendor qualification protocols including audit rights, batch records, and change control notification. FDA-registered facilities in North Carolina and Massachusetts require pump suppliers to maintain device master files and participate in supplier corrective action request processes.
- Research Laboratories:Academic institutions prioritize open communication protocols and modular upgrade paths. NIH-funded centers in Texas and California are consolidating purchases through shared service agreements that bundle calibration and preventive maintenance.
- Quality Control Labs:These users demand documented measurement uncertainty and traceable calibration chains.
- Agricultural Biotech Firms:Seed treatment and crop protection formulation testing drives demand for chemically resistant wetted materials.
Pharmaceutical Manufacturers concentrate purchasing power. Research Laboratories retain influence over technology roadmaps through early adoption cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision engineering talent clusters in southwestern Germany anchor European pump manufacturing, while pharmaceutical contract manufacturing expansion across multiple geographies is redistributing procurement authority.
United States
CAR-T cell therapy manufacturers in Massachusetts and North Carolina drive demand for shear-sensitive piezoelectric pumps. FDA 21 CFR Part 820 quality system requirements enforce validated supplier relationships for drug delivery integration. The NIH-funded research corridor in Greater Boston sustains academic procurement through shared service agreements bundling calibration and maintenance.
Germany
Pharmaceutical automation OEMs in Baden-Württemberg specify ISO 13485-certified syringe pumps for validated filling lines. EU MDR conformity obligations eliminate uncertified suppliers from medical device vendor pools. The precision engineering cluster around Stuttgart and Karlsruhe exports fluidic components to Swiss and Austrian diagnostic instrument manufacturers.
Switzerland
Swissmedic-regulated device manufacturers demand traceable calibration chains for implantable infusion systems. REACH substance restrictions on perfluorinated compounds accelerate validation of perfluoroelastomer alternatives in pump seals. The Basel pharmaceutical automation corridor integrates German pump assemblies into continuous manufacturing lines for biologics.
India
Point-of-care diagnostic developers in Maharashtra and Karnataka integrate compact pressure-driven pumps for portable glucose monitoring. CDSCO medical device rules tighten quality system expectations for Class B and C pump integrations. The Pune-Bengaluru medtech corridor scales decentralized testing infrastructure for infectious disease screening.
Japan
METI-supported bioprocessing initiatives expand piezoelectric pump adoption for regenerative medicine manufacturing. PMDA quality management system ordinances align with MHLW pharmaceutical machinery guidelines. The Kansai region's analytical instrument manufacturers source precision fluidic components for chromatography and mass spectrometry workflows.
High Precision Microfluidic Pump Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three strategic archetypes: fluid control conglomerates extending valve expertise into pump architectures, microfluidics-native specialists commanding technical loyalty in chip-integrated applications, and laboratory equipment heritage brands sustaining premium positioning in academic markets. Consolidation through strategic partnerships and portfolio diversification into adjacent diagnostic consumables represent dominant competitive moves as procurement centralization favors multi-product suppliers.
Within the heritage laboratory equipment tier, Harvard Apparatus occupies a position exemplifying syringe pump design authority in North American academic markets. Bürkert anchors the fluid control conglomerate archetype, its valve expertise extending into integrated pump architectures for pharmaceutical automation. Dolomite Microfluidics represents the microfluidics-native specialist, occupying technical loyalty in droplet generation applications where chip-pump integration governs purchasing decisions.
| Leading Market Players |
|---|
| Chemyx |
| New Era Instruments |
| Antylia Scientific |
| Dolomite Microfluidics |
| Fluigent |
| Harvard Apparatus |
| Bürkert |
| Cellix |
| Elveflow |
| Others |
Pricing and Supply Chain Analysis
Lead zirconate titanate ceramic feedstock pricing cascades through piezoelectric pump manufacturing tiers, compressing margins at the economy end while ISO 13485-certified suppliers in Baden-Württemberg defend premium positioning through validated quality systems.
Pricing Analysis
Capacity additions in India and Brazil are reshaping price floors for pressure-driven portable pumps, forcing established suppliers to differentiate through after-sales calibration bundling. Three-tier pricing structure across premium, standard, and economy levels separates FDA-registered drug delivery integrators from research-grade configurators. Cost compression in standard-tier syringe pumps intensifies because contract manufacturers in Eastern Europe consolidate procurement through multi-year GPO agreements. Academic medical centers exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize certification tier over unit cost.
Supply Chain Analysis
Refurbishment flows for precision syringe drives concentrate in Massachusetts and North Carolina, extending asset life for NIH-funded research institutions. Manufacturing draws from Germany, Switzerland, and Japan for precision-machined fluidic manifolds, with wetted elastomer sourcing anchored in specialized compounders near Stuttgart. Single-source vulnerability in lead zirconate titanate ceramics from East Asian processing nodes threatens actuator supply continuity. Distribution runs through authorized service partners embedding calibration capabilities at pharmaceutical contract manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Premium-tier shift toward medical-grade certified pumps expands margin capture as ISO 10993 testing burdens eliminate uncertified competitors from drug delivery vendor pools.
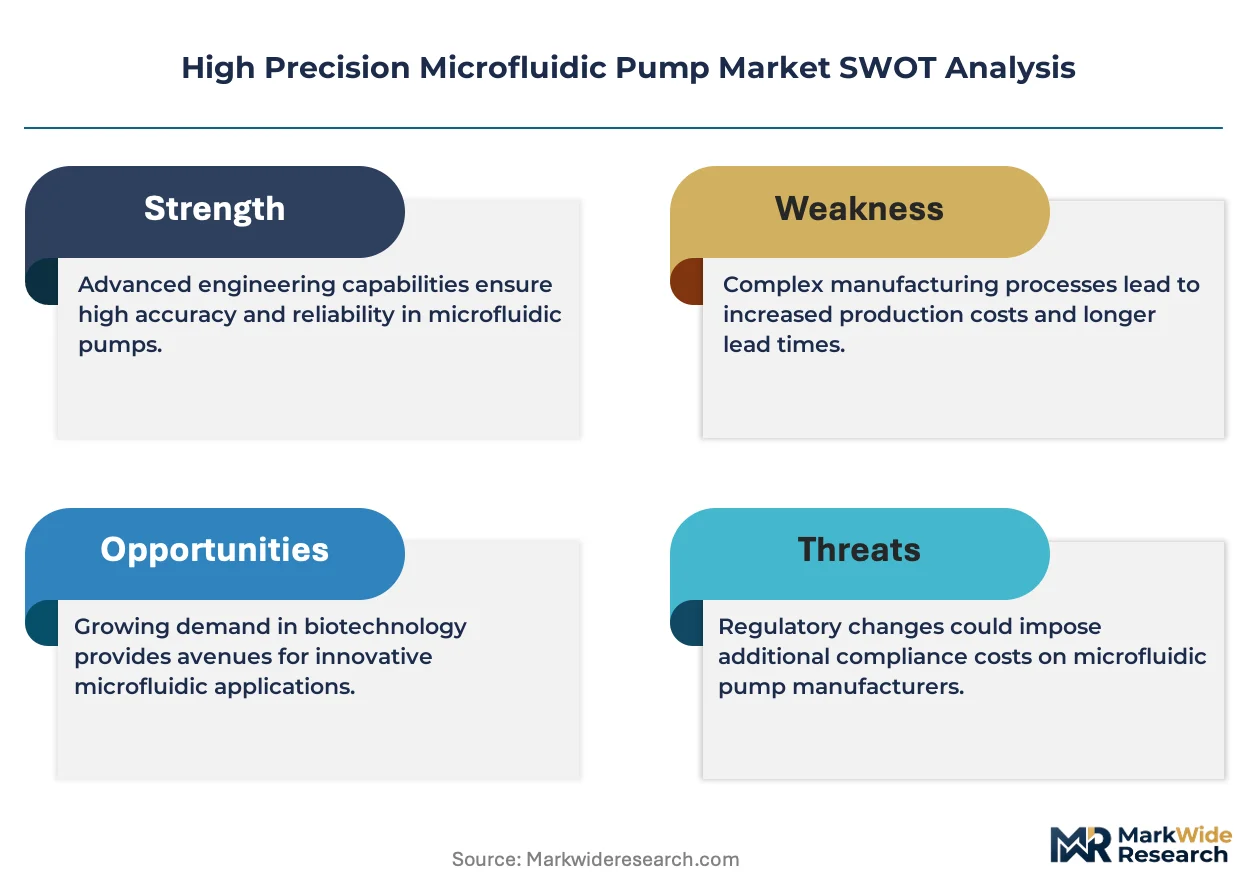
For Market Incumbents: Anticipate fluoropolymer tubing substitution mandates by accelerating perfluoroelastomer validation ahead of ECHA authorization sunsets. Backward integration into ceramic actuator sourcing mitigates East Asian supply node concentration. Defend positioning through captive ISO 13485 audit rights and batch record traceability systems that emerging entrants cannot replicate. For New Entrants and Emerging Players: Capture acoustic droplet ejection white space in CAR-T manufacturing workflows where shear-sensitive bioprocessing demands outstrip incumbent piezoelectric capacity. Point-of-care miniaturization in Maharashtra and Karnataka offers the most penetrable geography, with CDSCO Class B certification requirements still evolving. Go-to-market through diagnostic OEM design-in partnerships bypasses established channel relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with microfluidics-native specialists commanding technical loyalty in chip-pump integrated applications. Long-term viability favors acquisition targets with droplet generation IP and silicon-Pyrex bonding capabilities rather than legacy syringe pump heritage. Monitor EPA per- and polyfluoroalkyl substance enforcement actions as inflection indicator for material substitution-driven redesign cycles.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Validates supplier status for EU MDR drug delivery device classifications. |
| Perfluoroelastomer Material Validation | Anticipates REACH substance restrictions on fluorinated pump seals. |
| Acoustic Droplet Ejection Development | Captures CAR-T cell therapy manufacturing demand for shear-free handling. |
| Point-of-Care Miniaturization Partnership | Integrates compact pressure-driven pumps into CDSCO-regulated diagnostic platforms. |
| Calibration Service Bundling | Locks academic medical center procurement through shared service agreements. |
Research Methodology
Bottom-up pharmaceutical manufacturer procurement modeling reconciled against top-down precision fluidic component production tracking forms the analytical core of this study. Primary interviews with biomedical engineers, GPO contracts managers, regulatory affairs leads, and diagnostic instrument OEM procurement teams combined with secondary validation against FDA 510(k) filings, EMA medical device registrations, ISO 13485 certification databases, and REACH authorization timelines. Triangulation between demand-side volume aggregation and supply-side capacity verification ensures cross-validated outputs.
Input-output matrices map piezoelectric actuator material flows through pump assembly stages across the projection horizon. Segmentation dimensions span pump mechanism type, actuation technology, regulatory certification tier, end-use application, and geographic manufacturing cluster. CAGRs derive from installed base replacement cycles and net new adoption in cell therapy bioprocessing. Forecast inputs incorporate EPA per- and polyfluoroalkyl substance regulatory trajectory and EU MDR in-vitro diagnostic reclassification implementation pace.
Fluoropolymer supply disruption, East Asian ceramic processing node concentration, and ISO 10993 testing timeline extension are the dominant revision risks to modeled outputs. Practitioners should monitor ECHA authorization sunset schedules and EPA enforcement guidance for early signals of material substitution-driven demand shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.