
 Rotary Vane Vacuum Pump Market | 2026-2036
Rotary Vane Vacuum Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Vane Vacuum Pump Market Analytics
Modular pump-motor-controller bundling is consolidating buyer preference across mid-scale industrial sites. Atlas Copco leverages integrated vacuum station architectures to anchor large-fleet contracts in European process industries. Busch Vacuum Solutions sustains technology leadership through specialized oil-sealed platforms for chemical processing. Pfeiffer Vacuum differentiates via precision dry-type systems that dominate semiconductor cleanroom specifications.
A rotary vane vacuum pump employs eccentrically mounted vanes sliding within a cylindrical rotor cavity to compress and evacuate gas volumes, typically achieving ultimate pressures from 0.1 to 0.001 mbar depending on stage count and sealing medium. These machines serve as foundational vacuum generation equipment across laboratory research, industrial automation, and medical equipment applications where reliable roughing or process vacuum is required. Oil-sealed variants retain dominant installed base share due to mature cost structures and broad pressure-range coverage, while dry-type configurations capture fastest growth in electronics and food packaging end users seeking contamination-free operation. Intelligent monitoring technology segments expand as predictive maintenance architectures displace reactive service models in continuous-process environments.
EPA emissions guidelines in the United States and REACH chemical restrictions in Europe compel manufacturers to reformulate sealing oils and reduce hydrocarbon discharge from oil-sealed installations. Japan's METI energy-efficiency benchmarks and China's GB standards for industrial equipment further shape product certification requirements and market access conditions. Stakeholders must weigh dry-type capital premiums against lifecycle compliance costs when specifying platforms for regulated process environments.
Market Dynamics
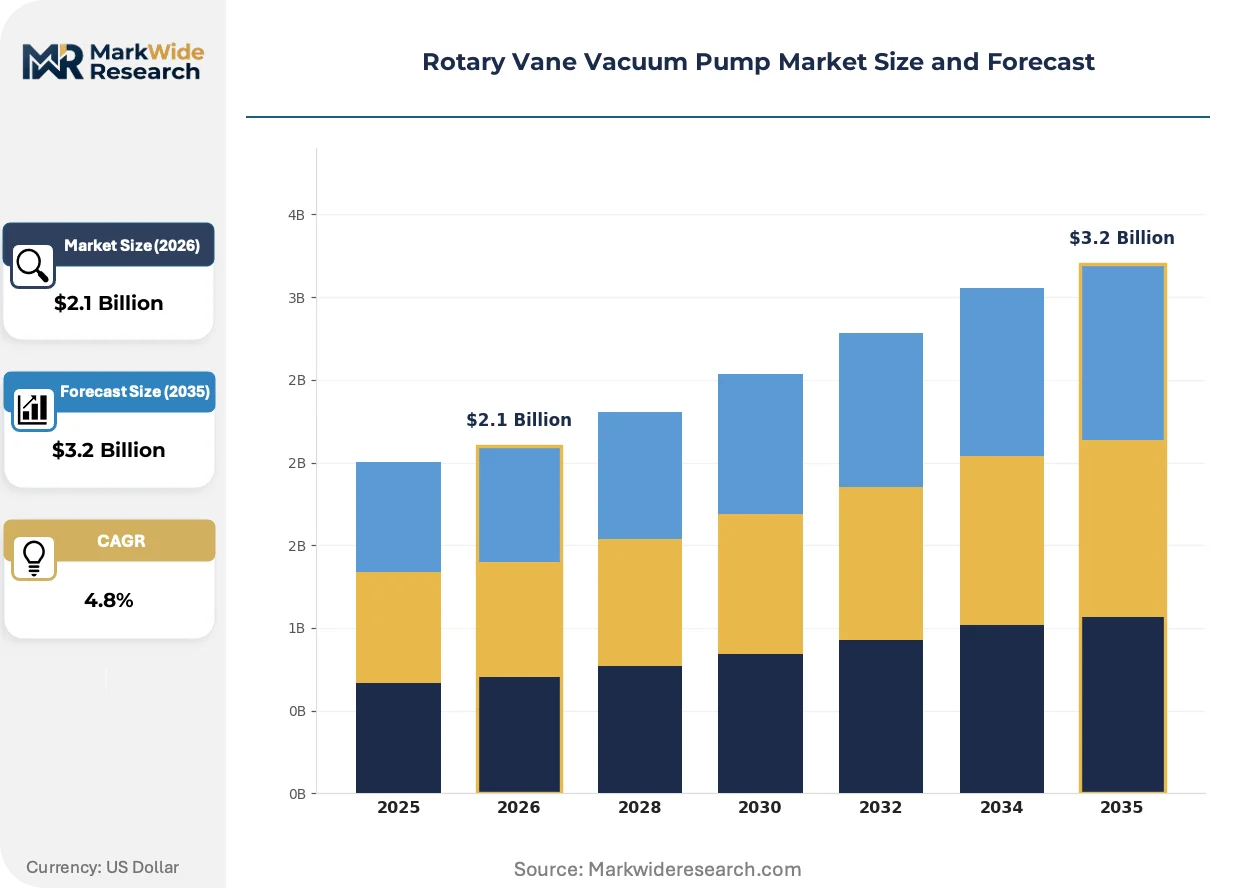
Semiconductor fabrication capacity expansion in East Asia is compressing procurement cycles for oil-sealed rotary vane systems, while dry-type variants capture specification share in contamination-sensitive process environments. This dual-track demand pattern is restructuring supplier order books and R&D allocation.
Growth Catalysts
- East Asian semiconductor buildout:Fabrication facilities across Taiwan, South Korea, and China's Yangtze River Delta are expanding roughing pump installations for wafer processing chambers.
- REACH chemical restrictions:European hydrocarbon discharge limits are accelerating reformulation of sealing oils and migration paths toward dry-type architectures.
- Intelligent monitoring integration:Predictive maintenance architectures are displacing reactive service models in continuous-process chemical and pharmaceutical installations.
Market Restraints
- Specialized metallurgy concentration:High-grade rotor castings and vane materials concentrate among German and Japanese specialty foundries, creating input bottlenecks.
- Dry-type capital premium:Oil-free rotary vane systems command 40-60% higher first-cost outlays versus comparable oil-sealed units, extending payback periods.
- Ultimate pressure limitations:Single-stage dry vane configurations face fundamental compression ratio constraints below 0.1 mbar, restricting addressable applications.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO-compliant active pharmaceutical ingredient facilities present untapped demand for contamination-free vacuum generation.
- Food packaging barrier films:Modified atmosphere packaging lines are specifying oil-free roughing pumps to eliminate hydrocarbon migration risks.
- Japan METI energy benchmarks:Efficiency certification requirements are creating preference premiums for variable-speed drive integration and heat recovery systems.
Industry Challenges
- Vacuum tribology expertise gap:Specialized knowledge of vane-to-housing friction dynamics and seal degradation modeling remains concentrated among aging specialist engineers.
- Legacy control system integration:Fieldbus protocol fragmentation between PROFINET, EtherNet/IP, and proprietary architectures complicates retrofit installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Vane Vacuum Pump Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Stage, Two Stage, Dry Type, Oil-Sealed End User: Electronics, Chemical Processing, Food Packaging, Healthcare Application: Laboratory Research, Industrial Automation, Vacuum Packaging, Medical Equipment Technology: Electric Drive, Pneumatic Control, Mechanical Assembly, Intelligent Monitoring |
| Companies Covered | Atlas Copco, Busch Vacuum Solutions, Gardner Denver, Pfeiffer Vacuum, Becker Pumps, Pneumofore, ULVAC, Tuthill, Zhejiang VALUE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Vane Vacuum Pump Market Evolving Landscape
Dry compression architectures are overtaking oil-sealed dominance in specification-sensitive verticals, while regulatory pressure on hydrocarbon emissions accelerates sealing medium innovation. Service model unbundling is redistributing value capture between OEMs and independent providers.
Permanent magnet synchronous motor integration is overtaking conventional induction drive configurations in mid-duty rotary vane platforms. Semiconductor cleanroom operators and pharmaceutical lyophilization facilities are specifying these packages for part-load efficiency gains. The technology is compressing energy consumption curves and enabling tighter pressure control bandwidths.
EPA emissions guidelines and REACH chemical restrictions are compelling reformulation of mineral-based sealing oils and installation of closed-loop oil recovery systems. Hydrocarbon discharge limits are tightening fastest in German process industries and US chemical manufacturing corridors. Oil-sealed pump suppliers are responding with synthetic ester alternatives and catalytic exhaust treatment modules.
Aftermarket service unbundling is fragmenting traditional OEM maintenance monopolies in European industrial clusters. Third-party vacuum service specialists are capturing pump overhaul and spare parts supply through reverse-engineered vane and seal kits. This pattern is most visible in Germany's Ruhr industrial region and northern Italy's packaging machinery belt.
Rotary Vane Vacuum Pump Market Segmentation
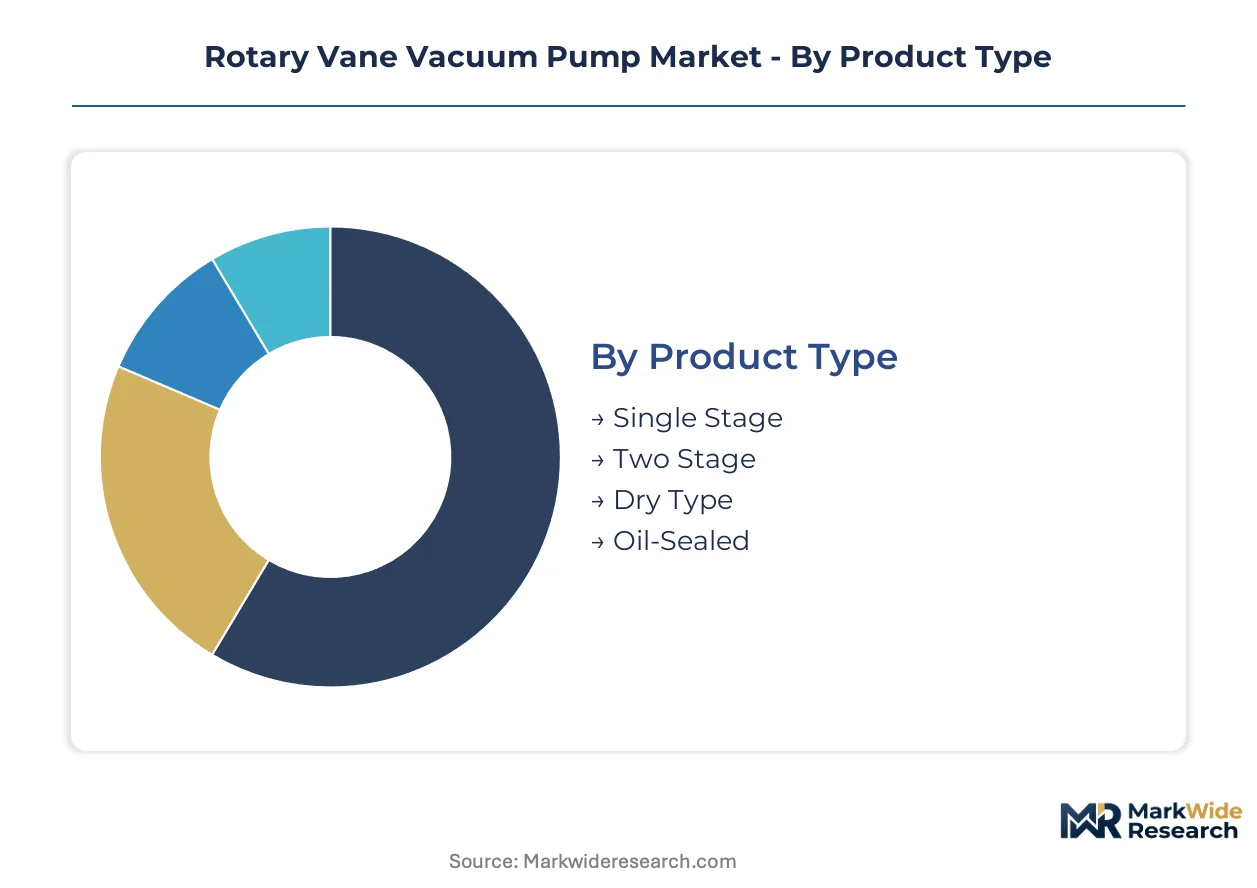
Rotary vane vacuum pump procurement decisions hinge on pressure specification, contamination tolerance, and duty cycle intensity. Buyers segment requirements across product architecture, end-use environment, and control technology to match capital deployment with operational constraints.
Product Type:
Technical specification and sealing medium define the core differentiation axis in pump architecture selection.
- Oil-Sealed:Mineral or synthetic lubricant fills the compression chamber to seal clearances, cool contact surfaces, and achieve ultimate pressures below 0.001 mbar in two-stage configurations. Semiconductor fabrication facilities in Taiwan and South Korea specify these for wafer handling roughing duty where base pressure performance outweighs hydrocarbon contamination risks.
- Dry Type:Carbon or polymer composite vanes operate without liquid sealing medium, eliminating oil backstreaming and exhaust treatment requirements. Pharmaceutical lyophilization suites and food packaging lines in Germany's process industries specify dry architectures where product contamination triggers regulatory non-compliance.
- Single Stage:One compression cycle delivers ultimate pressures around 0.1 mbar, suiting general industrial roughing and vacuum holding applications.
- Two Stage:Tandem rotor cavities in series achieve deeper vacuum for analytical instrumentation and electron microscopy backing pumps.
Oil-Sealed leads on scale; Dry Type leads on momentum.
End User:
Contamination sensitivity and process certification requirements reshape vendor selection across vertical markets.
- Electronics:Semiconductor wafer processing and flat-panel display manufacturing demand particulate-free vacuum environments. South Korean memory fabs specify oil-sealed roughing pumps for etch chamber evacuation, while dry variants capture lithography tool backing applications.
- Chemical Processing:Aggressive vapor streams and solvent recovery operations require corrosion-resistant materials and sealed exhaust systems. German chemical manufacturers face REACH-mandated hydrocarbon discharge limits that favor dry-type or closed-loop oil-sealed installations.
- Food Packaging:Modified atmosphere packaging lines specify oil-free roughing to prevent hydrocarbon migration into barrier films.
- Healthcare:Sterile manufacturing and diagnostic equipment applications prioritize contamination control and validated cleaning protocols.
Electronics commands the largest procurement volumes; Food Packaging shows the steepest specification shift toward dry architectures.
Application:
Duty cycle intensity and pressure stability requirements determine pump sizing and control system complexity.
- Industrial Automation:Continuous-duty material handling and robotic systems require robust mechanical construction and thermal management. Automotive parts vacuum forming lines in Japan's manufacturing belt specify two-stage oil-sealed units with heat recovery for energy efficiency compliance under METI benchmarks.
- Laboratory Research:Intermittent operation and analytical precision demand low vibration, minimal backstreaming, and rapid cycling capability. University and corporate R&D facilities across China's Yangtze River Delta specify single-stage dry pumps for rotary evaporator backing.
- Vacuum Packaging:High-cycle throughput operations prioritize reliability and rapid pump-down times.
- Medical Equipment:Diagnostic and therapeutic devices require validated performance and regulatory documentation for FDA or EMA submissions.
Industrial Automation anchors revenue concentration; Laboratory Research is expanding most quickly with R&D facility buildouts.
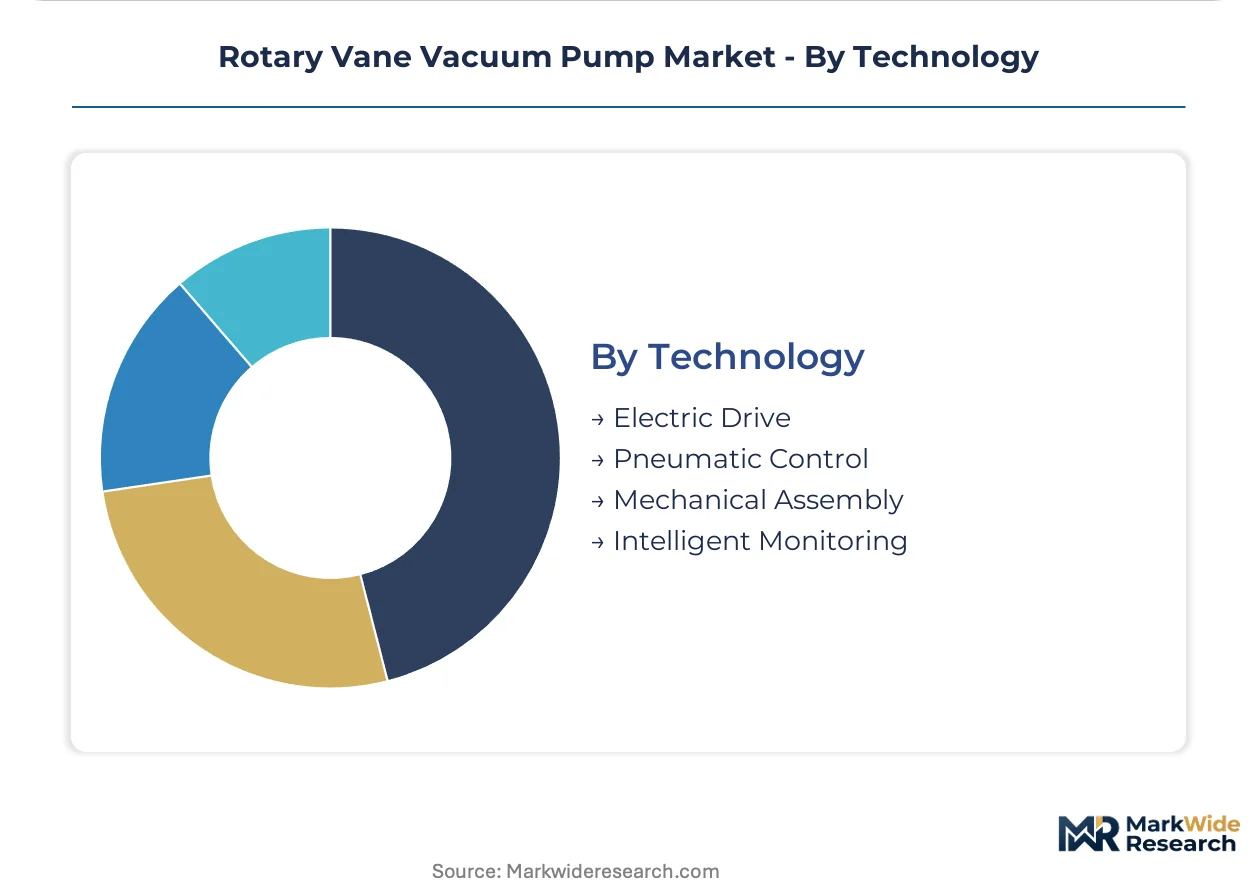
Technology:
Control architecture and drive integration differentiate efficiency performance and maintenance predictability.
- Intelligent Monitoring:Embedded vibration sensors, temperature telemetry, and oil condition analytics enable predictive maintenance scheduling. Continuous-process chemical installations in Germany's Ruhr region specify these architectures to minimize unplanned downtime in multi-pump redundant configurations.
- Electric Drive:Permanent magnet synchronous motors with variable frequency control deliver part-load efficiency gains. Pharmaceutical facilities specify these for lyophilization cycles with varying gas loads.
- Pneumatic Control:Compressed air logic systems serve explosion-hazard environments where electrical spark risks are prohibited.
- Mechanical Assembly:Conventional fixed-speed induction motor drives retain cost advantage in intermittent-duty applications with stable load profiles.
Electric Drive dominates current installations; Intelligent Monitoring is gaining share fastest as predictive service models displace reactive maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering houses pioneered rotary vane vacuum pump commercialization in the early twentieth century, establishing precision foundry and tribology expertise that persists in contemporary supply chains. Manufacturing gravity has since dispersed across East Asian semiconductor corridors and North American process industries.
Germany
REACH chemical restrictions under ECHA oversight compel reformulation of mineral-based sealing oils across Ruhr industrial region chemical processors. German process manufacturers face tightening hydrocarbon discharge limits that accelerate migration toward dry-type architectures. Bavaria's specialty foundries concentrate high-grade rotor castings and vane materials, creating input bottlenecks for global pump assembly.
China
Yangtze River Delta fabrication facilities expand roughing pump procurement for wafer processing chambers, compressing delivery cycles for oil-sealed systems. GB standards for industrial equipment certification shape product access conditions and energy-efficiency benchmarks. Shanghai and Suzhou manufacturing clusters anchor domestic pump assembly capacity serving semiconductor and flat-panel display fabs.
Japan
METI energy-efficiency benchmarks create preference premiums for variable-speed drive integration and heat recovery systems in continuous-process installations. Japanese specialty foundries concentrate corrosion-resistant metallurgy expertise for chemical processing applications. Chubu region automotive parts vacuum forming lines specify two-stage oil-sealed units with heat recovery for compliance.
United States
EPA emissions guidelines compel installation of closed-loop oil recovery systems and catalytic exhaust treatment modules in chemical manufacturing corridors. FDA-regulated pharmaceutical facilities prioritize contamination control in sterile manufacturing applications. Texas and Gulf Coast petrochemical clusters specify corrosion-resistant pump architectures for aggressive vapor stream handling.
South Korea
Memory fab expansion in Pyeongtaek and Yongin drives specification of oil-sealed roughing pumps for etch chamber evacuation. MFDS pharmaceutical manufacturing standards elevate contamination-free vacuum generation requirements in biologics production. Busan-Ulsan industrial belt concentrates demand for intelligent monitoring architectures in multi-pump redundant configurations.
Rotary Vane Vacuum Pump Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with vacuum technology divisions. Consolidation pressure concentrates order books among firms offering integrated vacuum station architectures and predictive maintenance platforms. Three archetypes dominate: European engineering conglomerates with process industry anchoring, Asian precision manufacturers with electronics sector specialization, and North American industrial diversification plays. Capacity expansion and technology licensing represent the dominant competitive moves across the landscape.
Among European engineering houses, Atlas Copco and Busch Vacuum Solutions exemplify the diversified conglomerate archetype with integrated system offerings. Pfeiffer Vacuum occupies a position within the precision technology tier serving contamination-sensitive specifications. These three firms anchor the premium-product vector through differentiated architectures spanning oil-sealed, dry-type, and intelligent monitoring configurations.
| Leading Market Players |
|---|
| Atlas Copco |
| Busch Vacuum Solutions |
| Gardner Denver |
| Pfeiffer Vacuum |
| Becker Pumps |
| Pneumofore |
| ULVAC |
| Tuthill |
| Zhejiang VALUE |
| Others |
Value Network & Pricing Analysis
Specialty alloy price indices for high-grade rotor castings cascade through three distinct pricing tiers in the rotary vane vacuum pump market, compressing margins at the economy tier while premium dry-type configurations absorb input volatility through contamination-sensitive buyer budgets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates intelligent monitoring dry-type systems from conventional oil-sealed units and basic mechanical assemblies. Certification grade under METI efficiency benchmarks and ISO 14644 cleanroom compliance drive 25-40% spreads between adjacent tiers. Cost compression in the economy tier intensifies as Chinese domestic manufacturers expand Yangtze River Delta assembly capacity. Semiconductor fabs in South Korea show least price sensitivity; packaging machinery OEMs in northern Italy exhibit highest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale semiconductor fab procurement, while distributor networks serve fragmented industrial automation demand. German and Japanese specialty foundries concentrate high-grade rotor castings and carbon-composite vane materials. Supply rests on corrosion-resistant metallurgy expertise, synthetic ester sealing oil formulations, and precision machining capacity. Single-source vulnerability concentrates in Bavaria's foundry cluster for aerospace-grade castings. Distribution runs through regional technical distributors with service bundling capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where dry-type specification shifts in pharmaceutical and food packaging verticals reward premium positioning over volume harvesting.
For Market Incumbents: To counter aftermarket service unbundling by third-party specialists, anchor large-fleet contracts through integrated vacuum station architectures with predictive maintenance platforms. Deepen captive supply of carbon-composite vane materials through backward integration into Japanese specialty foundry partnerships. For New Entrants and Emerging Players: REACH chemical restrictions in Germany open a window for dry-type system penetration in chemical processing corridors where hydrocarbon discharge limits accelerate migration from oil-sealed legacy installations. Target India's CDSCO-compliant pharmaceutical manufacturing clusters with contamination-free vacuum generation offerings. Lead with total cost of ownership positioning against first-cost-focused domestic competitors. For Investors and Strategic Acquirers: Consolidation pressure builds where intelligent monitoring technology fragments between proprietary OEM platforms and open-architecture third-party providers. Five-to-ten year viability favors precision dry-type specialists with semiconductor cleanroom validation over commodity oil-sealed assemblers. Monitor specification share shifts in food packaging barrier film applications as inflection indicator for dry-type adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Foundry Capacity | Captive supply of high-grade rotor castings from German and Japanese metallurgy clusters secures input cost control. |
| Intelligent Monitoring Platform Launch | Predictive maintenance architectures displace reactive service models in German Ruhr chemical processing installations. |
| Dry-Type Product Line Expansion | Oil-free configurations capture specification share in REACH-regulated European process industries. |
| Joint Venture in Yangtze River Delta | Local assembly capacity addresses compressed delivery cycles for Taiwan and South Korean semiconductor fabs. |
| Heat Recovery System Certification | METI energy-efficiency compliance creates preference premiums in Japanese automotive parts vacuum forming. |
Research Methodology
Direct dialogue with vacuum pump procurement managers at semiconductor fabs, maintenance directors in chemical processing plants, OEM technical buyers, and aftermarket service specialists grounded qualitative insights. Secondary validation drew from EPA emissions filings, ECHA REACH substance databases, METI efficiency benchmark disclosures, and customs trade records for vacuum pump classifications. Bottom-up unit economics triangulated against top-down industry production capacity estimates across the analysis window.
Segment-level outputs for oil-sealed versus dry-type architectures, single-stage versus two-stage configurations, and intelligent monitoring versus conventional control systems derived from installed base modeling and replacement cycle analysis. CAGRs emerged from regression against semiconductor capital expenditure cycles, pharmaceutical facility buildout rates, and regulatory compliance cost trajectories. Forecast inputs incorporated REACH enforcement timelines, METI benchmark revision schedules, and Yangtze River Delta fabrication capacity announcements.
Revisions become necessary when semiconductor capital expenditure cycles shift, REACH enforcement intensity changes, or dry-type technology cost curves steepen beyond modeled trajectories. Forecasts reflect documented assumptions regarding regulatory implementation timelines and technology substitution elasticities. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Solar Pump Inverter Market
Pumps and Control Devices
Global Lobe Pumps Market
Pumps and Control Devices
Latin America Centrifugal Pumps Market
Pumps and Control Devices
Progressing Cavity Pump Market
Pumps and Control Devices
Wind Powered Water Pumps Market
Pumps and Control Devices
APAC Positive Displacement Pumps Market
Pumps and Control Devices
Magnetic Drive Pumps Market
Pumps and Control Devices
Global Reciprocating Pumps Market
Pumps and Control Devices
Bubble Membrane Disc Diffuser Market
Pumps and Control Devices
Industrial Vacuum Pumps Market
Pumps and Control Devices
Spin-On Hydraulic Filter Market
Pumps and Control Devices
Global Pumps Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Global Compressor Control Systems Market
Pumps and Control Devices
Global Positive Displacement (PD) Pumps Market
Pumps and Control Devices
Package Pumping Station Market