
 Urea Fertilizers Market | 2026-2036
Urea Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Urea Fertilizers Market Analysis
Middle Eastern ammonia-urea producers is decoupling from European natural gas pricing, creating arbitrage opportunities for export-oriented capacity. CF Industries Holdings, Inc. leverages its Louisiana and Iowa nitrogen complexes to dominate North American inland distribution. Yara International ASA anchors its European position through carbon-capture integration at Dutch and Norwegian plants. SABIC competes on scale from its Saudi Arabian feedstock-advantaged sites.
Urea fertilizer is a synthetic nitrogen product containing approximately 46% nitrogen by weight, manufactured through the Bosch-Haber process combining ammonia and carbon dioxide under high pressure to form solid carbamide granules or prills; its primary function is to deliver concentrated, water-soluble nitrogen to crops for vegetative growth and protein synthesis. Granular urea leads volume globally due to superior handling characteristics and blending compatibility with phosphate and potash fertilizers, while slow-release urea commands premium positioning as environmental regulations tighten around nitrate runoff and volatilization losses. Agricultural crops absorb the dominant share of urea consumption, though horticultural plants represent a higher-margin outlet where precision application and specialty formulations justify elevated pricing.
The EPA enforces Clean Air Act ammonia emission standards that constrain urea manufacturing and application practices in the United States, while India's FSSAI and CEA monitor fertilizer quality and energy inputs under the national nutrient subsidy framework. REACH and the EU Green Deal's Farm-to-Fork targets are accelerating product registration requirements and carbon intensity disclosures for urea sold into European food production systems. Stakeholders must track how carbon border adjustment mechanisms and evolving national subsidy schemes reshape competitive access across import-dependent consuming regions.
Market Dynamics
Natural gas price decoupling between Middle Eastern feedstock hubs and European industrial consumers is redrawing competitive boundaries for ammonia-urea producers, while India's nutrient-based subsidy regime concentrates procurement volume in government tenders.
Growth Catalysts
- Controlled-Release Formulation Mandates:The European Union's F-Gas Regulation and Farm-to-Fork Strategy tighten ammonia emission ceilings, compelling manufacturers to develop polymer-coated and stabilized urea products that reduce volatilization losses.
- India's Nutrient-Based Subsidy Framework:The government's NBS program sustains large-volume procurement for rice-wheat intensive cropping systems, locking in predictable offtake from domestic and import suppliers.
- Carbon Capture Integration:Dutch and Norwegian producers are embedding carbon capture at ammonia plants, positioning low-carbon urea for premium access under emerging carbon border adjustment mechanisms.
Market Restraints
- Natural Gas Feedstock Volatility:European ammonia-urea complexes remain exposed to TTF hub pricing swings, compressing margins when spot gas exceeds long-term contract levels secured by Middle Eastern competitors.
- Single-Geography Supply Concentration:Over half of globally traded urea originates from fewer than ten mega-complexes in the Persian Gulf, creating disruption risk from regional logistics bottlenecks or export policy shifts.
- Nitrate Runoff Substitution:Liquid UAN and anhydrous ammonia compete for spring application windows in North American corn production, particularly where precision injection equipment is already deployed.
Strategic Opportunities
- Sub-Saharan African Market Development:Fertilizer use rates below 20 kilograms per hectare in countries like Nigeria and Ethiopia present expansion potential for blended urea products tailored to maize and cassava systems.
- Enhanced-Efficiency Product Premiums:Nitrification and urease inhibitor coatings command 15-25% price lifts over commodity grades, capturing value from environmental compliance requirements in watershed-sensitive regions.
- Digital Agronomy Integration:Variable-rate application platforms paired with soil sensor networks enable precision urea dosing, opening subscription service models alongside physical product sales.
Industry Challenges
- Process Safety Engineering Talent Scarcity:Ammonia plant operations require specialized expertise in high-pressure synthesis loop management, with retirement waves thinning experienced operator ranks in mature producing regions.
- Emissions Certification Timeline Compression:EU Green Deal carbon intensity disclosure requirements demand verified lifecycle data from feedstock extraction through granulation, straining existing audit and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urea Fertilizers Market |
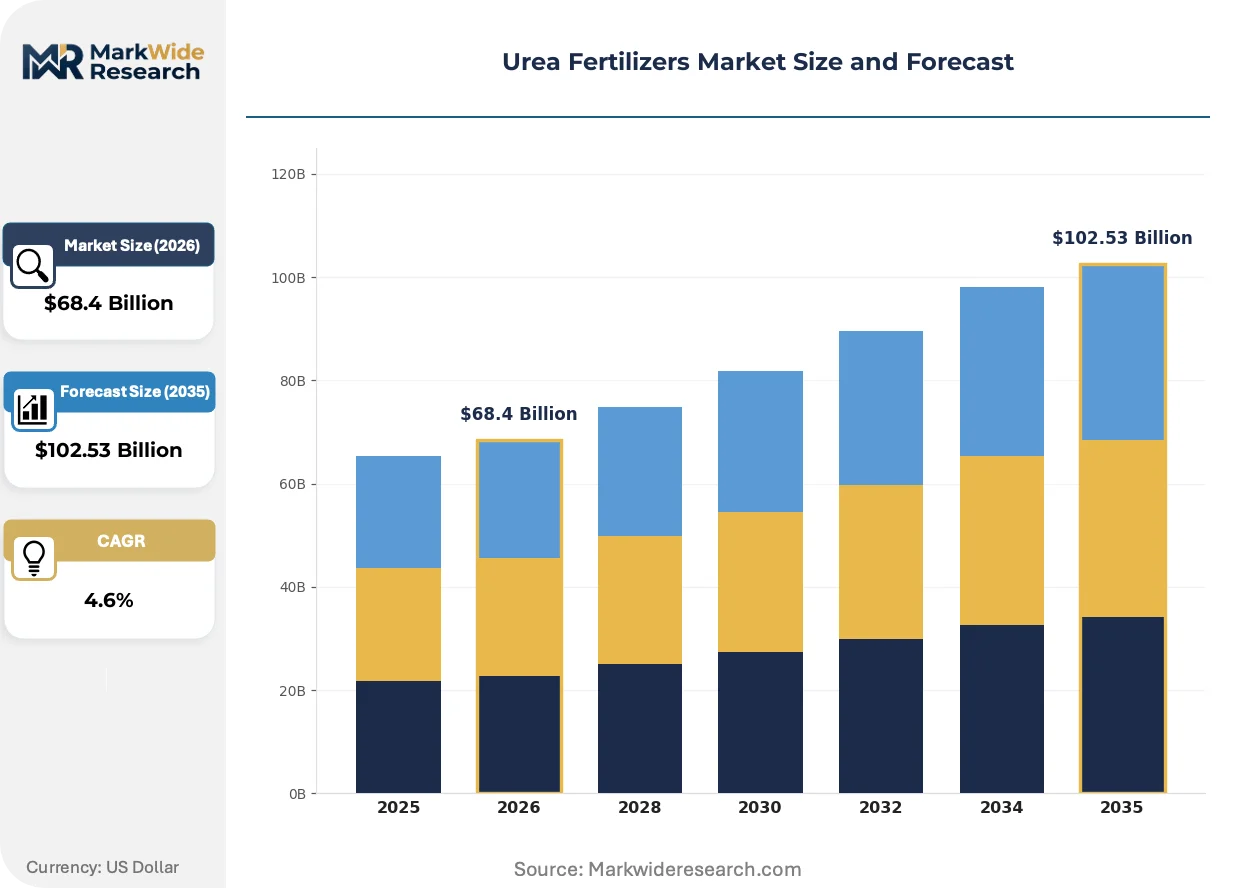
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $102.53 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular Urea, Prilled Urea, Liquid Urea, Slow-Release Urea Application: Agricultural Crops, Horticultural Plants, Turf Grass, Ornamental Plants End User: Farmers, Agricultural Cooperatives, Retail Outlets, Exporters Distribution Channel: Direct Sales, Online Retail, Wholesale Distributors, Agricultural Supply Stores |
| Companies Covered | CF Industries Holdings, Inc., Pupuk Indonesia (Persero), Yara International ASA, SABIC, Nutrien Ltd, OCI, Qatar Fertiliser Company, Koch Fertilizer LLC, Acron Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urea Fertilizers Market Emerging Trajectories
Product formulation and application technology are converging to address nitrogen use efficiency targets, with regulatory pressure and farm economics jointly steering investment priorities across the value chain.
Stabilized urea incorporating nitrification inhibitors is rewriting application protocols for no-till corn systems. Farmers in the US Corn Belt are adopting split-application programs that delay nitrogen release until peak vegetative uptake stages. This chemistry is compressing the historical preference for single-pass fall anhydrous ammonia, particularly where cover crop integration complicates spring field access.
REACH registration expansions under the EU Green Deal's Farm-to-Fork targets now require carbon footprint declarations for urea sold into food production systems. Manufacturers must document emissions from natural gas extraction through final granulation, reshaping supplier qualification criteria for European distributors. Dutch importers are already screening Middle Eastern cargoes on certified carbon intensity scores, creating tiered market access conditions.
Grain handlers and cooperatives are consolidating procurement authority previously dispersed across individual farm operations. Large-scale buying pools in Iowa and Illinois now negotiate directly with nitrogen complex operators, displacing traditional wholesale distributor markups. This concentration is most visible in the US Midwest, where 5,000-hectare-plus operations increasingly contract for delivered product rather than spot terminal purchases.
Urea Fertilizers Market Segmentation
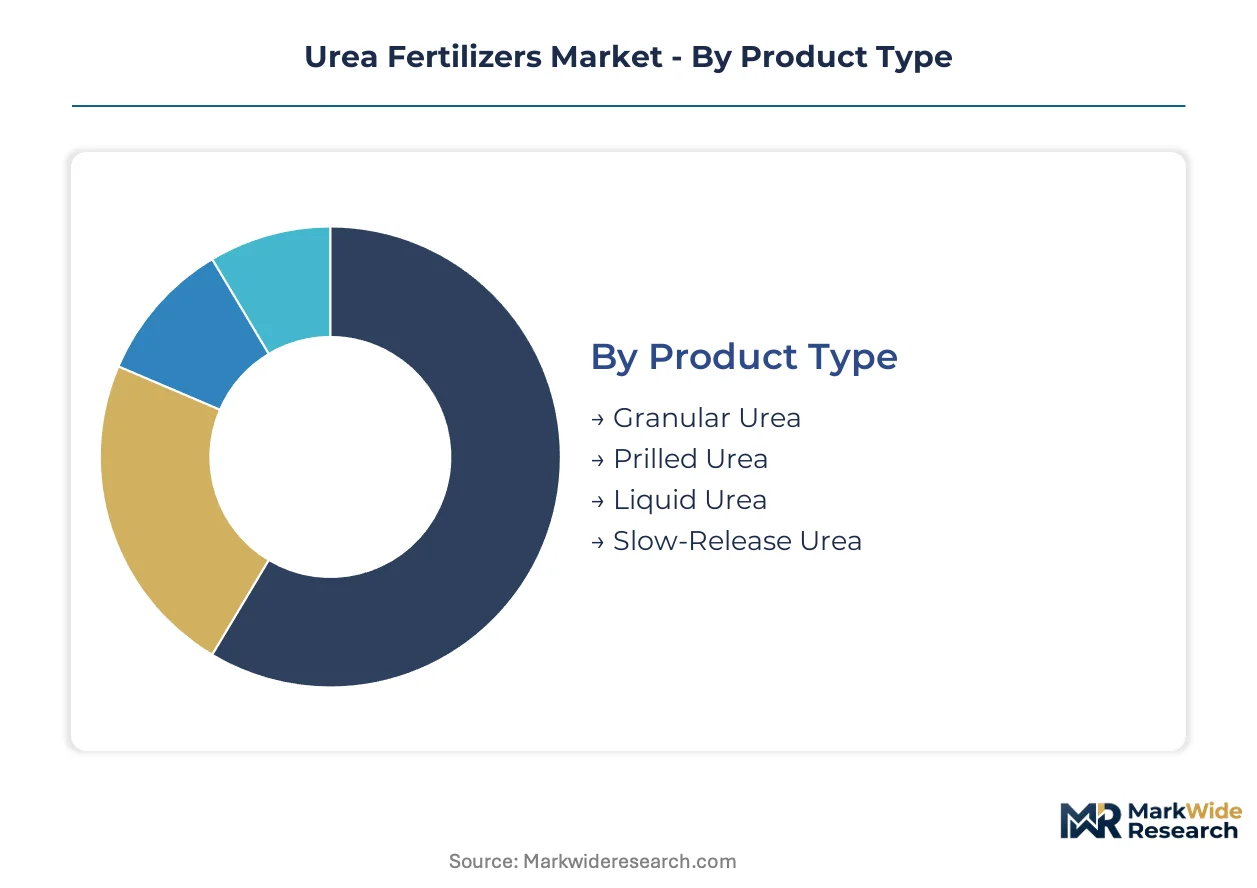
Urea fertilizers fragment across physical form, crop target, and procurement channel. Each dimension carries distinct margin structures and regulatory exposure that reshape supplier positioning and farmer choice architecture.
Product Type:
Standardization dominates commodity grades while controlled-release variants command formulation premiums and environmental compliance value.
- Granular Urea:Solid carbamide formed into dense, spherical particles between 2-4 millimeters diameter. Grain handlers across Iowa and Illinois negotiate direct procurement contracts for this grade, displacing wholesale distributor layers in the US Corn Belt. Leading the category by volume: Granular Urea. Growing fastest: Slow-Release Urea.
- Prilled Urea:Smaller, porous spheres produced through spray-cooling of molten urea, prized for rapid dissolution in irrigation systems. Rice-wheat intensive systems in India absorb prilled volumes through government nutrient-based subsidy tenders, locking in predictable offtake.
- Liquid Urea:Concentrated aqueous solution enabling foliar application and fertigation integration. Specialty vegetable producers in California and Florida adopt this form for precision nitrogen timing in high-value cropping.
- Slow-Release Urea:Polymer-coated or inhibitor-stabilized formulations extending nitrogen availability across 6-12 week windows. REACH registration expansions under EU Green Deal Farm-to-Fork targets now mandate carbon intensity disclosures, filtering supplier access to Dutch and German distributors.
Physical form selection tracks equipment compatibility and labor constraints more than nitrogen economics alone.
Application:
Revenue concentration tilts toward bulk commodity crops while margin capture concentrates in specialty horticultural outlets.
- Agricultural Crops:Maize, wheat, and rice systems absorb the dominant volume share, with North American corn belt farmers expanding application rates per hectare. EPA Clean Air Act ammonia emission standards constrain both manufacturing and field application practices across US production zones.
- Horticultural Plants:Precision greenhouse and nursery operations justify elevated pricing through specialty formulations and micronutrient co-blending. Protected cultivation clusters in the Netherlands and Spain drive demand for water-soluble grades with low biuret content.
- Turf Grass:Golf course and sports field maintenance programs favor slow-release chemistry to sustain visual quality without frequent reapplication. Municipal procurement in Saudi Arabia and UAE golf developments sources this segment.
- Ornamental Plants:Floriculture and landscape nursery channels absorb smaller volumes at premium positioning. Containerized production systems in Colombia and Kenya export markets specify coated urea for controlled flowering cycles.
Application segmentation separates volume-driven commodity supply from value-capture specialty channels.
End User:
Procurement authority is consolidating from dispersed farm-level purchasing toward pooled negotiating power.
- Farmers:Individual operators below 500 hectares remain price-takers in spot terminal markets, though precision agriculture adoption is fragmenting this tier by technology sophistication.
- Agricultural Cooperatives:Consolidated buying pools across 5,000-hectare-plus operations in the US Midwest now contract directly with nitrogen complex operators. CF Industries leverages its Louisiana and Iowa complexes to capture this concentrated demand.
- Retail Outlets:Regional farm supply chains blend urea with phosphate and potash for customized NPK formulations. Indian FSSAI and CEA quality monitoring under national nutrient subsidy frameworks constrains product registration.
- Exporters:Trading houses arbitrage between Middle Eastern feedstock-advantaged production and import-dependent consuming regions. SABIC's Saudi Arabian mega-complexes anchor this channel through scale economics.
End user structure is displacing traditional wholesale layers as scale concentrates procurement authority.
Distribution Channel:
Channel economics diverge between physical infrastructure dominance and digital platform emergence.
- Direct Sales:Nitrogen complex operators contract delivered product with large-scale buyers, eliminating intermediary markups. Yara International anchors European direct sales through carbon-capture integrated Dutch and Norwegian plants.
- Online Retail:E-procurement platforms enable price transparency and consolidated ordering for mid-scale operators. Indian government fertilizer portals channel subsidized urea through digital allocation systems.
- Wholesale Distributors:Traditional bulk handlers retain relevance in fragmented farm structures and import-dependent markets. Persian Gulf origin cargoes flow through Rotterdam and Singapore hub distributors.
- Agricultural Supply Stores:Last-mile retail maintains local blending services and credit extension. Sub-Saharan African markets below 20 kilograms per hectare fertilizer use rates depend on this channel for market development.
Channel selection tracks farm scale, credit access, and blending service requirements across geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural gas feedstock availability anchors urea production economics across key consuming geographies. Feedstock-advantaged Middle Eastern producers export into import-dependent agricultural zones, while regional manufacturing clusters respond to distinct regulatory and subsidy frameworks.
United States
Corn belt farmers in Iowa and Illinois are expanding per-hectare urea application rates for maize production. The EPA enforces Clean Air Act ammonia emission standards that constrain both manufacturing and field application practices. CF Industries operates nitrogen complexes in Louisiana and Iowa to serve concentrated Midwest demand.
India
Rice-wheat intensive cropping systems in Punjab and Haryana sustain large-volume urea procurement through government tenders. The FSSAI and CEA monitor fertilizer quality and energy inputs under the national nutrient-based subsidy framework. Prilled urea flows through government allocation portals to smallholder farms across the Indo-Gangetic Plain.
Netherlands
Carbon-capture integration at ammonia plants positions Dutch producers for premium access under emerging carbon border adjustment mechanisms. REACH registration expansions under the EU Green Deal's Farm-to-Fork targets mandate carbon intensity disclosures for urea sold into food production systems. Rotterdam serves as a distribution hub screening Middle Eastern cargoes on certified carbon scores.
Saudi Arabia
Mega-complexes in the Eastern Province leverage feedstock advantages to anchor global export volumes. SABIC operates scale-driven production sites supplying import-dependent consuming regions. Gulf-origin cargoes flow through Singapore and Rotterdam hub distributors to reach fragmented African and Asian markets.
Brazil
Soybean and maize producers in Mato Grosso and Paraná depend on imported urea for bulk nitrogen application. The national agricultural regulator monitors fertilizer quality standards for domestic distribution. Port terminals in Santos and Paranaguá handle transshipment from Middle Eastern and North African suppliers.
Urea Fertilizers Market Vendor Landscape
Global majors compete with regional champions across feedstock access and distribution reach. The vendor base concentrates around integrated ammonia-urea complexes with captive natural gas supply or pipeline access. Three archetypes dominate: Middle Eastern feedstock-advantaged exporters, North American inland distributors with river and rail networks, and European carbon-capture integrated producers serving premium compliance markets. Capacity expansion and carbon intensity certification represent the dominant competitive moves reshaping supplier positioning.
Within the feedstock-advantaged tier, SABIC and Qatar Fertiliser Company anchor Middle Eastern export supply. CF Industries Holdings, Inc. and Yara International ASA occupy positions across North American and European demand clusters respectively. These named entities exemplify the scale and integration thresholds required to compete in an environment where natural gas economics and emissions certification increasingly filter market access.
| Leading Market Players |
|---|
| CF Industries Holdings, Inc. |
| Pupuk Indonesia (Persero) |
| Yara International ASA |
| SABIC |
| Nutrien Ltd |
| OCI |
| Qatar Fertiliser Company |
| Koch Fertilizer LLC |
| Acron Group |
| Others |
Supply Flow & Price Mechanics
Government procurement programs in India anchor the dominant pricing model through nutrient-based subsidy tenders that cap farmgate prices while absorbing feedstock volatility. This concentration of buying power compresses margins for import-dependent suppliers while rewarding scale producers with captive natural gas access.
Pricing Analysis
Service bundling separates contract terms in this market, with delivered-product agreements including logistics and storage against spot terminal purchases where farmers assume handling costs. Three-tier pricing structure across premium, standard, and economy levels reflects carbon intensity certification grades and inhibitor coating sophistication. Cost compression in commodity grades is intensifying because Middle Eastern feedstock-advantaged producers decouple from European gas pricing. Smallholder farmers in government-subsidized systems exhibit highest price sensitivity, while specialty horticultural buyers tolerate 15-25% premiums for enhanced-efficiency formulations.
Supply Chain Analysis
Dual-sourcing mandates from European distributors now require qualified suppliers from both Middle Eastern and North African origins to mitigate disruption risk. Production gravity centers on Saudi Arabia, Qatar, and Russia, with ammonia-urea complexes drawing from associated gas fields and pipeline networks. Feedstock dependency rests on natural gas supply security, ammonia synthesis catalyst availability, and polymer coating chemicals for controlled-release grades. Single-source vulnerability concentrates in Persian Gulf mega-complexes where export policy shifts or logistics bottlenecks cascade through global trade flows. Distribution runs through Rotterdam and Singapore hub terminals for transshipment to fragmented African and Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into ammonia synthesis and carbon capture infrastructure defines the competitive race in this market, with producers pursuing upstream control over feedstock costs and downstream premium positioning through emissions certification.
For Market Incumbents: To counter margin compression from Middle Eastern feedstock-advantaged exporters, CF Industries and Yara International should deepen carbon capture integration at Dutch and Norwegian plants while locking long-term offtake contracts with consolidated Midwest buying pools. Capacity addition in Louisiana and Iowa reinforces inland distribution dominance against import competition. For New Entrants and Emerging Players: Digital agronomy platforms offering variable-rate application subscriptions represent the most penetrable wedge for technology-first entrants, targeting mid-scale operators below 5,000 hectares lacking precision agriculture infrastructure. Sub-Saharan African markets below 20 kilograms per hectare fertilizer use rates offer white-space expansion for blended urea products tailored to maize systems. Partnership with regional agricultural supply stores enables last-mile credit extension and blending services. For Investors and Strategic Acquirers: The window for entry favors carbon-capture integrated producers with verified lifecycle emissions data qualifying for EU Green Deal premium access. Long-term viability hinges on positioning for carbon border adjustment mechanisms tightening supplier qualification criteria. Watch for inflection in Dutch importer screening intensity on certified carbon intensity scores as the signal for tiered market access crystallization.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Yara International's Dutch plants secure premium EU market access under Farm-to-Fork carbon disclosure mandates. |
| Backward Integration into Ammonia | CF Industries' Louisiana complexes lock in feedstock cost advantages against volatile TTF hub pricing. |
| Long-term Supply Agreement | Consolidated Iowa buying pools contract directly with nitrogen complex operators, displacing wholesale markups. |
| Enhanced-Efficiency Product Launch | Polymer-coated urea formulations capture 15-25% price lifts from watershed-sensitive regulatory zones. |
| Joint Venture for African Market Development | Partnerships with Nigerian distributors address under-20 kg/hectare fertilizer gaps in maize production systems. |
Methodological Framework
Document review covered trade flow databases, SEC 10-K filings from nitrogen complex operators, and EU ETS emissions registries, complemented by interviews with plant operations managers, procurement leads at agricultural cooperatives, distribution channel partners, and regulatory affairs directors at fertilizer manufacturers. Secondary validation drew from customs data, Fertiliser Association of India consumption reports, and EPA Clean Air Act enforcement records. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Market sizing outputs reflect segmentation across physical form, crop target, and procurement channel dimensions, with growth trajectories derived from feedstock cost differential analysis and regulatory compliance timeline assessment across the projection horizon. Modeled inputs incorporated natural gas price spread persistence between Middle Eastern and European hubs, plus carbon intensity certification adoption curves in EU member states.
Several conditions sit outside the modeled scope, including sovereign export policy shifts in major producing nations, breakthroughs in biological nitrogen fixation technology, and extreme weather disruptions to planting windows in key consuming regions. Deviation in EU carbon border adjustment implementation timing or subsidy regime stability in India would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
United States Specialty Fertilizer Market
Fertilizers
Middle East and Africa Fertilizers Market
Fertilizers
Fertilizer Spreader Market
Fertilizers
Calcium Ammonium Nitrate Market
Fertilizers
Global Specialty Fertilizer Market
Fertilizers
Middle East and Africa Specialty Fertilizer Market
Fertilizers
Global Nitrogenous Fertilizer Market
Fertilizers
China Specialty Fertilizer Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
Global Fertilizers Market
Fertilizers
Blue-Green Algae Fertilizer Market
Fertilizers
Global Controlled Release Fertilizer Market
Fertilizers
Global Urea Market
Fertilizers
Chelate Fertilizer Market
Fertilizers
Enhanced Efficiency Fertilizer Market