
 North America Sweet Potatoes Market | 2026-2036
North America Sweet Potatoes Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sweet Potatoes Market Analytics
Buyer concentration across North American food service channels is rebalancing as regional restaurant chains and institutional buyers fragment procurement away from legacy distributors. Nash Produce leverages its Carolina-based growing network to sustain year-round supply contracts with processors. Ham Farms anchors its position through specialized storage infrastructure that extends seasonal availability. Scott Farms Inc competes via direct-to-retail packaging formats that bypass traditional wholesaler markups.
Sweet potatoes are starchy root vegetables from Ipomoea batatas, typically containing fifteen to twenty percent carbohydrates and notable beta-carotene content, harvested mechanically before curing at eighty-five degrees Fahrenheit to convert starches to sugars for enhanced flavor and shelf stability. Fresh product type dominates volume throughput but carries thinner margins due to perishability and freight exposure, while dehydrated formats concentrate value through extended shelf life and reduced logistics burden. Frozen segments serve the fastest-growing demand pool as food manufacturers seek pre-processed inputs for fry and puree applications.
The USDA's Agricultural Marketing Service administers grading standards that shape processor procurement premiums, while FDA Food Safety Modernization Act rules mandate hazard controls from field through packing. State-level organic certification programs in California and North Carolina layer additional compliance thresholds for premium channel access. Stakeholders must monitor evolving traceability mandates and water-use regulations that threaten to reshape cost structures across southeastern growing regions.
Market Dynamics
Buyer fragmentation across North American food service channels is dismantling legacy distributor lock-in, while FDA Food Safety Modernization Act traceability mandates force upstream capital deployment into field-to-fork tracking infrastructure.
Growth Catalysts
- USDA National Organic Program:Premium channel access rewards certified growers with procurement premiums from retail and food service buyers seeking clean-label positioning.
- Quick-service chain menu expansion:Operators from regional burger chains to institutional cafeterias are embedding sweet potato fries and purees as permanent fixtures rather than seasonal limited-time offers.
- Mechanized curing technology:Controlled-environment storage at eighty-five degrees Fahrenheit extends seasonal availability and converts starches to sugars for enhanced flavor profiles that command price premiums.
Market Restraints
- Southeastern production concentration:North Carolina and Mississippi processing clusters create geographic vulnerability to weather shocks and water-use regulatory tightening.
- Perishability cost burden:Fresh product formats incur freight exposure and shrinkage losses that compress margins below dehydrated and frozen alternatives.
- Input cost volatility:Fertilizer and diesel price swings directly impact field operations where mechanical harvesting and curing infrastructure requires sustained fuel and nutrient inputs.
Strategic Opportunities
- Canadian retail penetration:Underdeveloped direct-to-retail packaging formats in Ontario and Quebec grocery channels offer whitespace for US-based processors with cold-chain logistics capabilities.
- Frozen pre-processed inputs:Food manufacturers seeking fry and puree applications represent the fastest-growing demand pool for value-added formats with extended shelf stability.
- California state organic certification:Layered compliance thresholds create dual-certified supply access to West Coast premium channels with distinct consumer willingness-to-pay profiles.
Industry Challenges
- Traceability system integration:Field-to-packing hazard controls require capital-intensive digitization of harvest records and lot tracking that strains smaller grower operations.
- Water-use compliance timelines:State-level regulations in southeastern growing regions threaten to reshape cost structures before infrastructure adaptation can occur.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sweet Potatoes Market |
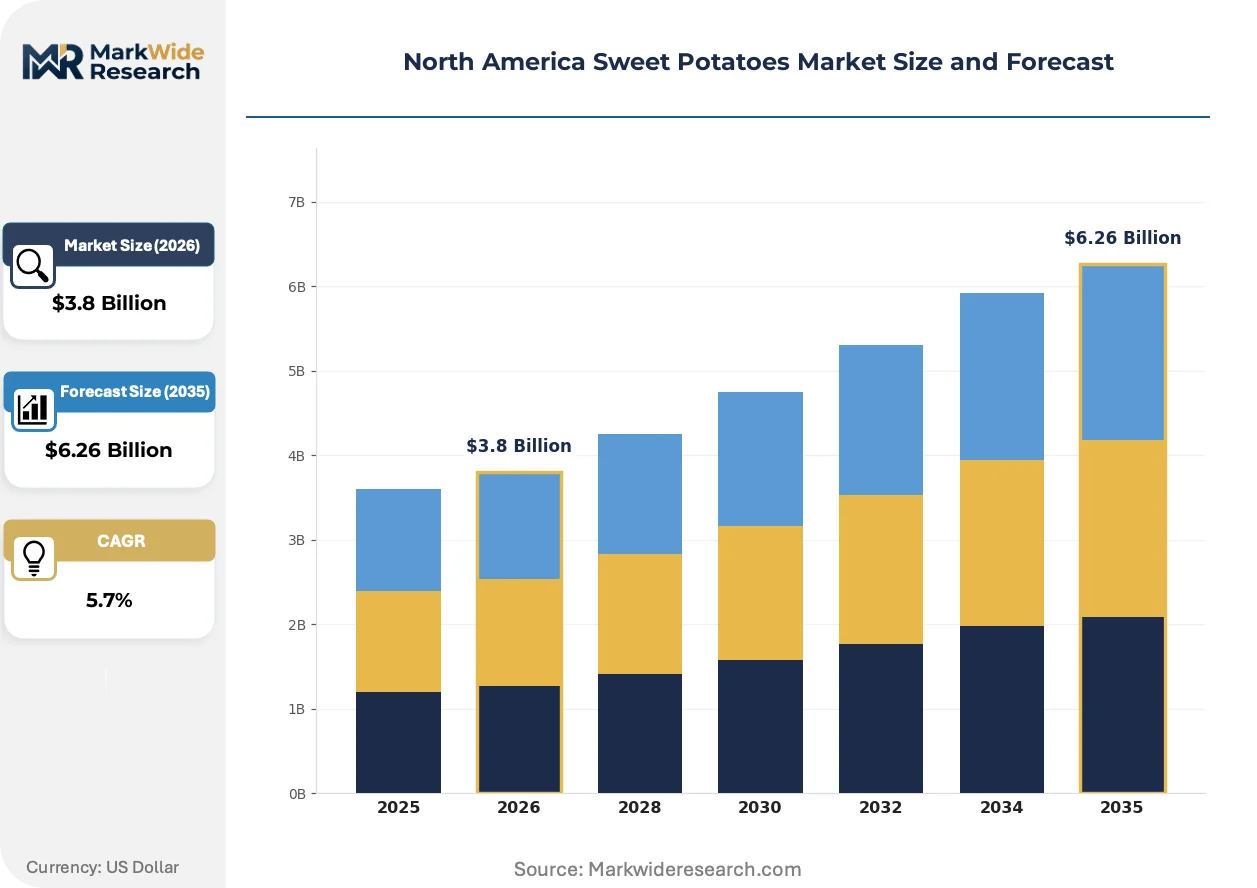
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Frozen, Canned, Dehydrated Packaging Type: Bags, Boxes, Bulk, Pallets Distribution Channel: Supermarkets, Online Retail, Farmers' Markets, Wholesalers End User: Household, Food Service, Food Processing, Export |
| Companies Covered | Conagra Brands, Inc., Nash Produce, Ham Farms, Dole Food Company, Inc., A.V. Thomas Produce, Jackson Farming Company, Black Gold Farms, Scott Farms Inc, Topashaw Farms, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sweet Potatoes Market Evolving Landscape
Processing technology and supply chain digitization are compressing traditional seasonality constraints while regulatory traceability mandates accelerate capital deployment into integrated field-to-fork systems.
Controlled-atmosphere storage and automated sorting systems are modularizing the post-harvest value chain. Mid-scale processors in North Carolina and Mississippi are adopting these technologies to extend availability windows and reduce labor dependency. The technology is modularizing what were previously integrated seasonal operations into year-round supply modules that can be contracted separately.
The FDA Food Safety Modernization Act's traceability rules are mandating electronic record-keeping from field through packing. Processor procurement premiums now flow preferentially to growers with digitized lot-tracking infrastructure. Fresh product segments face the steepest compliance burden due to shorter shelf life and higher velocity through multiple handling points.
Food service procurement is fragmenting away from legacy broadline distributors toward direct contracts with regional processors. Institutional buyers in K-12 and healthcare channels are bypassing traditional wholesaler markups to secure volume commitments with Carolina-based growing networks. This pattern concentrates most visibly in the southeastern United States where processing capacity clusters enable shorter logistics loops.
North America Sweet Potatoes Market Segmentation
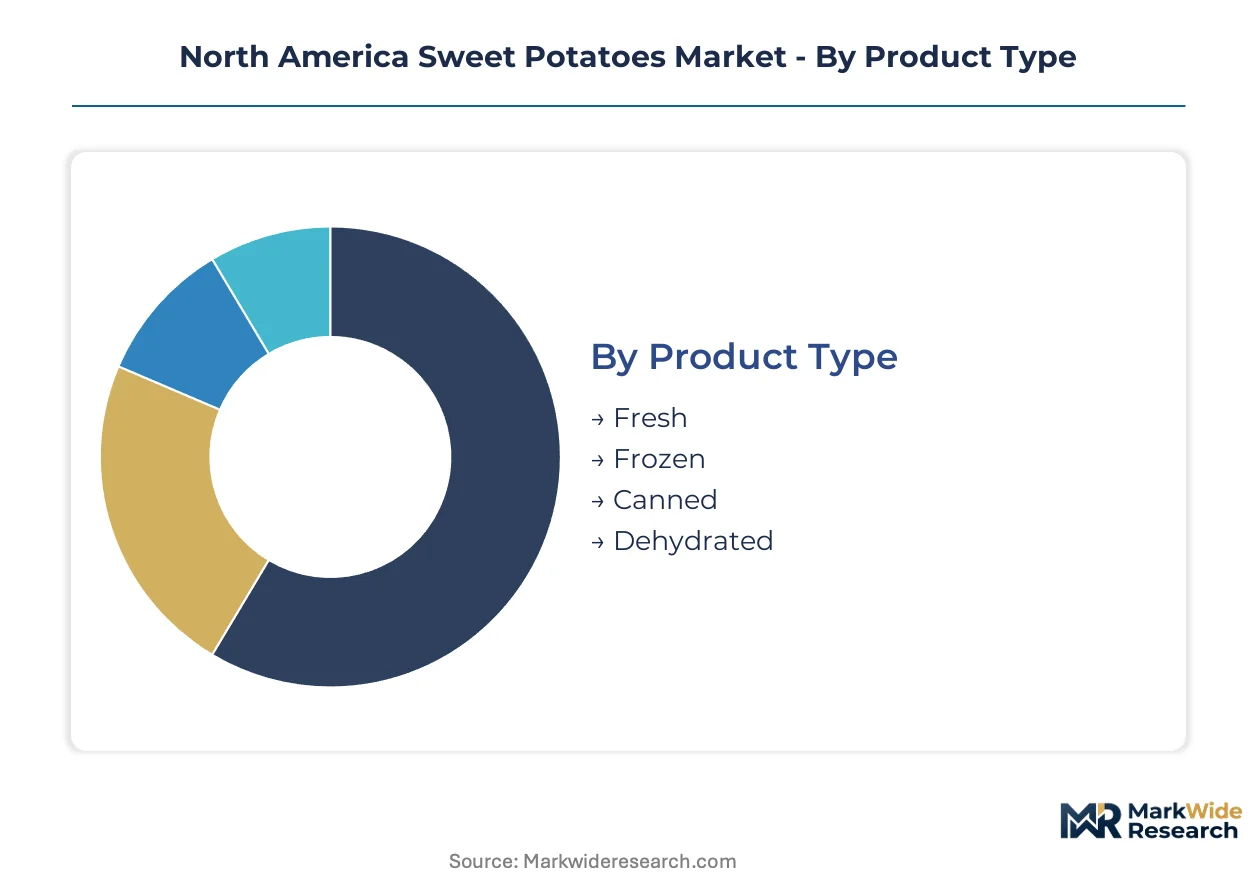
Sweet potato value chains fragment across four critical dimensions that determine margin capture and logistics burden. Product format and packaging configuration shape perishability exposure, while distribution channel selection locks in customer price sensitivity and volume scale.
Product Type:
Volume throughput concentrates in fresh formats, while value-added processing commands premium positioning through shelf-life extension.
- Fresh:Field-harvested roots undergo mechanical curing at eighty-five degrees Fahrenheit to convert starches to sugars, yielding fifteen to twenty percent carbohydrate content with enhanced flavor stability. North Carolina and Mississippi processing clusters anchor regional throughput, though perishability compresses margins below processed alternatives.
- Frozen:Pre-processed fries and purees serve quick-service chains and food manufacturers seeking year-round supply continuity without curing infrastructure. This segment climbs the fastest as institutional buyers fragment procurement toward direct processor contracts.
- Canned:Shelf-stable formats target institutional cafeterias and emergency food programs with extended ambient storage.
- Dehydrated:Flakes and flour concentrates reduce logistics burden for ingredient manufacturers in bakery and pet food channels.
Mature deployment sits with Fresh. Newer deployment is concentrated in Frozen.
Packaging Type:
Cost tier stratification separates retail-ready units from bulk commodity flows, with mid-scale processors investing in automated sorting to bridge the gap.
- Bags:Consumer-facing poly or mesh units dominate direct-to-retail channels, commanding price premiums through branded presentation and portion control.
- Boxes:Corrugated containers balance protection with cube efficiency for wholesale club and food service distributors.
- Bulk:Loose-load formats minimize unit packaging cost for processors with captive curing and storage infrastructure.
- Pallets:Unitized loads optimize freight economics for high-volume institutional contracts and export consolidation.
Established infrastructure serves Bulk. Investment flows concentrate in Bags.
Distribution Channel:
Customer type fragmentation is dismantling legacy broadline distributor lock-in, with regional processors capturing margin through direct contracting.
- Supermarkets:Grocery chains in Ontario and Quebec present whitespace for US-based processors with cold-chain logistics capabilities and retail-ready packaging.
- Online Retail:Direct-to-consumer subscription models and meal-kit integrations bypass traditional wholesaler markups, though last-mile costs constrain viability outside dense urban corridors.
- Farmers' Markets:Localized sales channels support premium pricing for certified organic product from Carolina-based growing networks.
- Wholesalers:Legacy broadline distributors retain volume in K-12 and healthcare institutional channels, though procurement officers increasingly seek direct contracts.
Volume leadership remains with Wholesalers. Share gains concentrate in Online Retail.
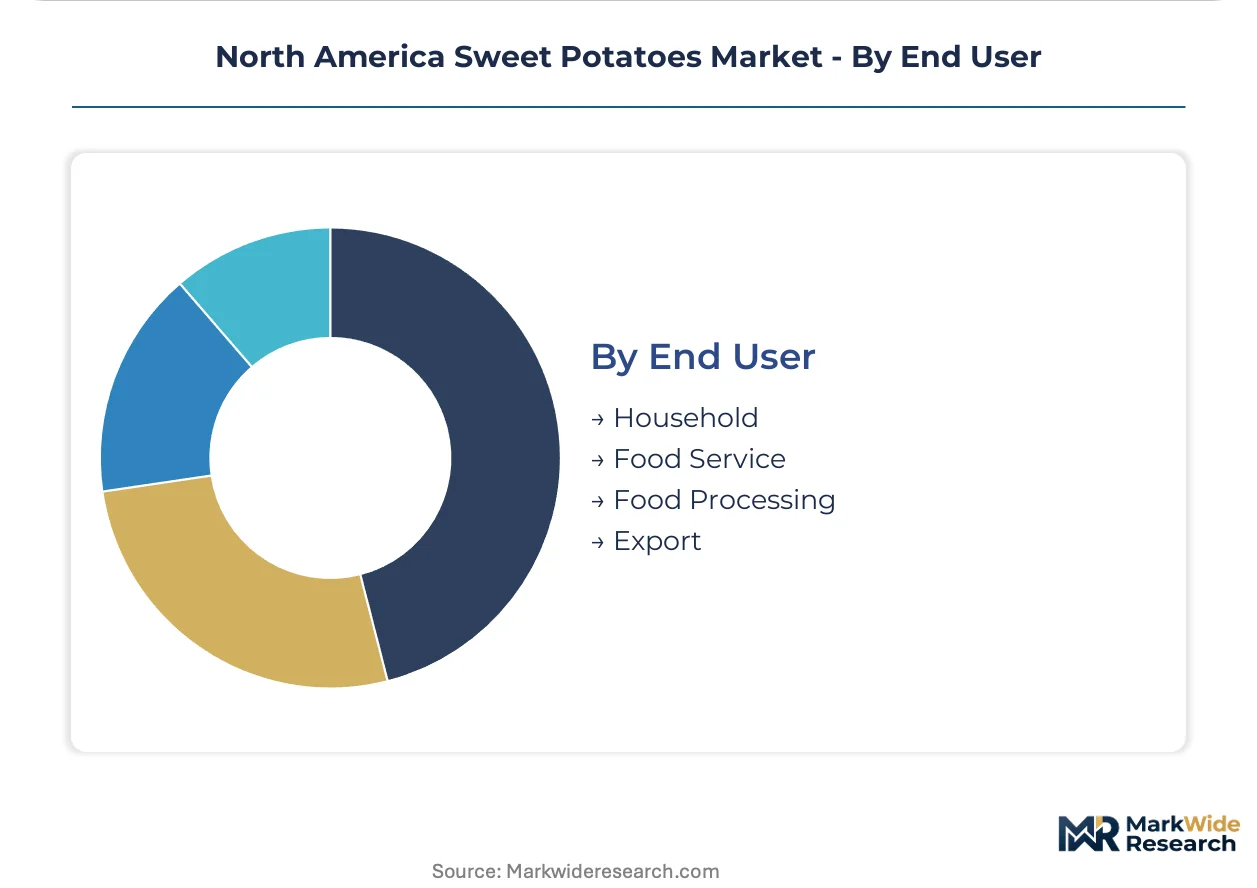
End User:
Application diversity spans raw ingredient through finished plate, with food manufacturing representing the steepest expansion trajectory for pre-processed inputs.
- Household:Retail consumers drive seasonal demand peaks around holidays, with preference shifting toward pre-washed and microwave-ready convenience formats.
- Food Service:Quick-service chains embed sweet potato fries and purees as permanent menu fixtures, fragmenting procurement away from legacy distributors toward regional processors.
- Food Processing:Manufacturers of fry, flake, and puree applications represent the fastest-growing demand pool for value-added formats with extended shelf stability and reduced labor dependency.
- Export:Canadian retail penetration and select offshore markets absorb surplus from southeastern US production clusters.
Traditional concentration sits with Household. Capacity expansion targets Food Processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food service procurement concentrates most visibly in the southeastern United States, where processing infrastructure clusters anchor North American throughput. Canadian retail channels present underdeveloped whitespace for cross-border expansion. Mexican production zones supply seasonal counter-cyclical volume to balance US harvest windows.
United States
Quick-service chains and institutional cafeterias drive procurement volume from North Carolina and Mississippi processing clusters. The USDA's National Organic Program and FDA Food Safety Modernization Act traceability rules tighten compliance requirements across field-to-fork operations. Carolina-based growing networks sustain year-round supply contracts through specialized curing infrastructure that converts starches to sugars.
Canada
Ontario and Quebec grocery channels show underdeveloped penetration for direct-to-retail packaging formats from US processors. Health Canada and the Canadian Food Inspection Agency administer import standards and cold-chain logistics requirements for fresh produce. Toronto and Montreal distribution hubs absorb cross-border volume seeking whitespace positioning in premium retail segments.
Mexico
Seasonal production from Sinaloa and Michoacán growing zones supplies counter-cyclical volume during US winter months. The Secretariat of Agriculture and Rural Development (SADER) oversees phytosanitary export certifications for North American trade integration. Guadalajara and Mexico City processing corridors concentrate dehydration and canning capacity for ingredient manufacturing channels.
North America Sweet Potatoes Market Competitive Landscape
Carolina-based producers anchor one tier; Mississippi and diversified food conglomerates hold differentiated positions through scale or vertical integration. The vendor base fragments across regional growing networks and national packaged-food portfolios. Three strategic archetypes dominate: specialized curing-and-storage operators, direct-to-retail packaging specialists, and diversified agribusiness conglomerates with multi-commodity portfolios. Capacity expansion and backward integration into captive growing networks constitute the dominant competitive moves.
Within the specialized regional network tier, Nash Produce and Ham Farms exemplify Carolina-based operators leveraging localized infrastructure. Conagra Brands, Inc. occupies a position representing diversified packaged-food conglomerates with multi-channel distribution capabilities. Scott Farms Inc anchors the direct-to-retail packaging archetype, bypassing traditional wholesaler markups through branded consumer-facing formats.
| Leading Market Players |
|---|
| Conagra Brands, Inc. |
| Nash Produce |
| Ham Farms |
| Dole Food Company, Inc. |
| A.V. Thomas Produce |
| Jackson Farming Company |
| Black Gold Farms |
| Scott Farms Inc |
| Topashaw Farms |
| Others |
Value Network & Pricing Analysis
Mechanized harvesting crews concentrated in North Carolina and Mississippi processing clusters drive labor-cost differentials that widen spreads between premium certified-organic tiers and economy-grade bulk formats. Perishability exposure in fresh segments compresses margins below frozen and dehydrated alternatives, while controlled-atmosphere curing infrastructure at eighty-five degrees Fahrenheit enables price premiums through extended seasonal availability.
Pricing Analysis
Volume throughput concentrates in fresh formats with thinner margins, while value-added frozen and dehydrated segments capture premium positioning through shelf-life extension. Three-tier pricing structure across premium certified-organic, standard food-grade, and economy processing tiers reflects USDA National Organic Program certification status and volume scale. Pricing pressure stems from input cost volatility in fertilizer and diesel that directly impacts field operations. Quick-service chains show least price sensitivity for pre-processed frozen inputs, while institutional K-12 buyers exhibit highest sensitivity to per-unit delivered cost.
Supply Chain Analysis
Reverse-logistics flows for perished fresh product and packaging returns from retail channels concentrate cost recovery challenges in Carolina-based growing networks. Supply concentrates in the United States, Mexico, and Canada with seasonal counter-cyclical volume from Sinaloa and Michoacán balancing US harvest windows. Raw material dependencies center on seed stock, curing fuel, and corrugated packaging inputs. Single-source vulnerability to weather shocks in southeastern production clusters threatens supply continuity. Distribution runs through direct processor contracts that fragment procurement away from legacy broadline distributors toward regional operators with captive curing infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled-atmosphere storage and automated sorting systems are displacing legacy seasonal curing operations, compressing traditional availability constraints while digitized lot-tracking infrastructure replaces paper-based traceability compliance.
For Market Incumbents: Deepen backward integration into captive seed stock and specialized curing infrastructure to defend margin position against input cost volatility and water-use regulatory tightening. Secure dual USDA National Organic Program and California state organic certification to access West Coast premium channels with distinct willingness-to-pay profiles. Lock in multi-year direct contracts with quick-service chains to reduce exposure to distributor price compression.
For New Entrants and Emerging Players: Enter via underdeveloped Canadian retail penetration in Ontario and Quebec grocery channels where direct-to-retail packaging formats from US processors show whitespace positioning. Target frozen pre-processed input segments serving food manufacturers seeking fry and puree applications with extended shelf stability. Pursue cold-chain logistics partnerships with Toronto and Montreal distribution hubs as the primary go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized curing-and-storage operators given FDA Food Safety Modernization Act traceability mandates that force capital deployment into digitized field-to-fork infrastructure. Long-term viability favors regional processors with modular year-round supply capabilities and direct food service contracting relationships. Monitor water-use compliance timelines in southeastern growing regions as the critical inflection signal for cost structure reshaping.
| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Storage Deployment | Extends seasonal availability windows and reduces labor dependency in Carolina processing clusters. |
| Dual Organic Certification Investment | Unlocks premium channel access under USDA National Organic Program and California state programs. |
| Direct-to-Retail Packaging Expansion | Bypasses traditional wholesaler markups through branded consumer-facing formats in Canadian markets. |
| Frozen Pre-Processed Input Scale-Up | Serves quick-service chains and food manufacturers seeking year-round supply continuity. |
| Digitized Traceability Infrastructure | Captures FDA Food Safety Modernization Act compliance premiums through electronic lot-tracking systems. |
Research Methodology
Independent corroboration across grower-processor interviews, food service procurement officer discussions, and regulatory compliance officer consultations underwrites the qualitative findings. Primary fieldwork engaged sweet potato farm operators, controlled-atmosphere storage facility managers, quick-service chain menu development executives, and institutional cafeteria procurement directors. Secondary validation drew from USDA Agricultural Marketing Service grading standards, FDA Food Safety Modernization Act guidance documents, state-level organic certification records, and trade flow databases. Bottom-up volume estimates from regional processing clusters triangulate against top-down demand aggregation across food service and retail channels.
Rate-of-change decomposition across product format evolution, packaging configuration shifts, and distribution channel fragmentation anchors the analytical framework over the projection horizon. Segmentation dimensions span fresh versus frozen versus dehydrated formats, bulk versus retail-ready packaging, and direct processor contracts versus legacy wholesale distribution. CAGRs derive from modeled volume trajectories by segment calibrated against historical production data and buyer procurement pattern shifts. Industry-specific inputs include mechanized curing technology adoption curves and water-use regulatory compliance cost estimates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under severe weather shocks in southeastern growing regions or accelerated water-use restrictions. Practitioners should monitor FDA traceability rule implementation timelines and state-level water allocation decisions for early signals of supply cost restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Hydroponic Vegetable Market
Vegetables
Europe Flowers and Ornamental Plants Market
Vegetables
Sweet Potatoes Market
Vegetables
India Greenhouse Horticulture Market
Vegetables
Asia-Pacific Peas Market
Vegetables
Turkey Greenhouse Horticulture Market
Vegetables
Fresh Mushroom Market
Vegetables
Cabbages and Other Brassicas Market
Vegetables
Greenhouse Bell Pepper Market
Vegetables
North America Microgreens Market
Vegetables
Canada Greenhouse Horticulture Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
Garden Cress Market
Vegetables
Zimbabwe Fruits and Vegetables Market
Vegetables
Australia Greenhouse Horticulture Market
Vegetables
Netherlands Greenhouse Horticulture Market