
 Africa Specialty Fertilizer Market | 2026-2036
Africa Specialty Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Specialty Fertilizer Market Outlook
Buyer concentration among large-scale commercial farming operations is rebalancing as mid-size agricultural cooperatives multiply across East and West Africa. Yara International ASA leverages its coastal blending facilities to serve import-dependent markets, while OCP Group anchors phosphate supply through its integrated Moroccan mining and processing complex. Omnia Holdings Limited differentiates via precision agriculture services bundled with liquid fertilizer sales.
Africa specialty fertilizers comprise value-added nutrient formulations—controlled-release coatings, chelated micronutrients, or liquid concentrates—that deliver targeted, efficient plant nutrition beyond conventional NPK bulk products. These formulations typically incorporate polymer-coated urea, humic acid complexes, or microbial inoculants to address specific soil deficiencies and crop physiological stages. Controlled Release Fertilizers command premium positioning where labor scarcity limits split-application schedules, while Liquid Fertilizers gain traction among irrigated horticulture zones seeking fertigation compatibility. Biofertilizers occupy a nascent but policy-favored niche as governments subsidize microbial alternatives to reduce import bills.
South Africa's Department of Agriculture, Land Reform and Rural Development enforces fertilizer registration under the Fertilizers, Farm Feeds, Seeds and Remedies Act, while Nigeria's Standards Organisation of Nigeria mandates product certification for all imported blends. The African Union's 2024 soil health commitments are reshaping national subsidy programs toward balanced and micronutrient-inclusive formulations. Stakeholders must track how rapidly evolving national fertilizer subsidy registries redirect procurement specifications toward specialty grades.
Market Dynamics
Soil depletion across East African commercial farming belts is forcing rapid substitution toward micronutrient-enriched formulations, compressing traditional bulk NPK procurement cycles and rewiring distributor inventory priorities toward precision-grade products.
Growth Catalysts
- The African Union's Fertilizer and Soil Health Summit outcomes:Public procurement mandates across member states now favor balanced formulations with micronutrient inclusion, redirecting subsidy flows from conventional bulk toward specialty grades.
- Water-soluble and foliar application systems:Irrigated horticulture zones in Nigeria and Ethiopia are adopting fertigation-compatible concentrates to optimize labor-scarce growing seasons.
- Controlled-release polymer coatings:Large-scale operations facing labor constraints are deploying coated urea to reduce split-application schedules and improve nutrient use efficiency.
Market Restraints
- Phosphate supply concentration:Moroccan mining and processing complexes anchor regional phosphate availability, creating single-source dependency for P-based specialty blends.
- Import cost volatility:Currency fluctuations against dollar-denominated raw material contracts inflate landed costs for micronutrient chelates and polymer inputs.
- Limited domestic blending infrastructure:Coastal concentration of formulation facilities lengthens inland distribution legs and elevates working capital requirements for upcountry distributors.
Strategic Opportunities
- Mid-size agricultural cooperatives:East and West Africa's multiplying cooperative structures represent underserved demand nodes between smallholder collectives and estate-scale buyers.
- Biofertilizer subsidy channels:National programs subsidizing microbial inoculants to reduce import bills create policy-favored entry paths for domestic production partnerships.
- Precision agriculture bundling:Soil testing and variable-rate application services bundled with liquid fertilizer sales open recurring revenue streams beyond commodity product margins.
Industry Challenges
- Agronomic advisory capacity gaps:Extension services lack personnel trained in micronutrient deficiency diagnostics and prescription blending protocols.
- Registration timeline compression:South Africa's Fertilizers, Farm Feeds, Seeds and Remedies Act and Nigeria's SON certification requirements create multi-month approval bottlenecks for new formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Specialty Fertilizer Market |
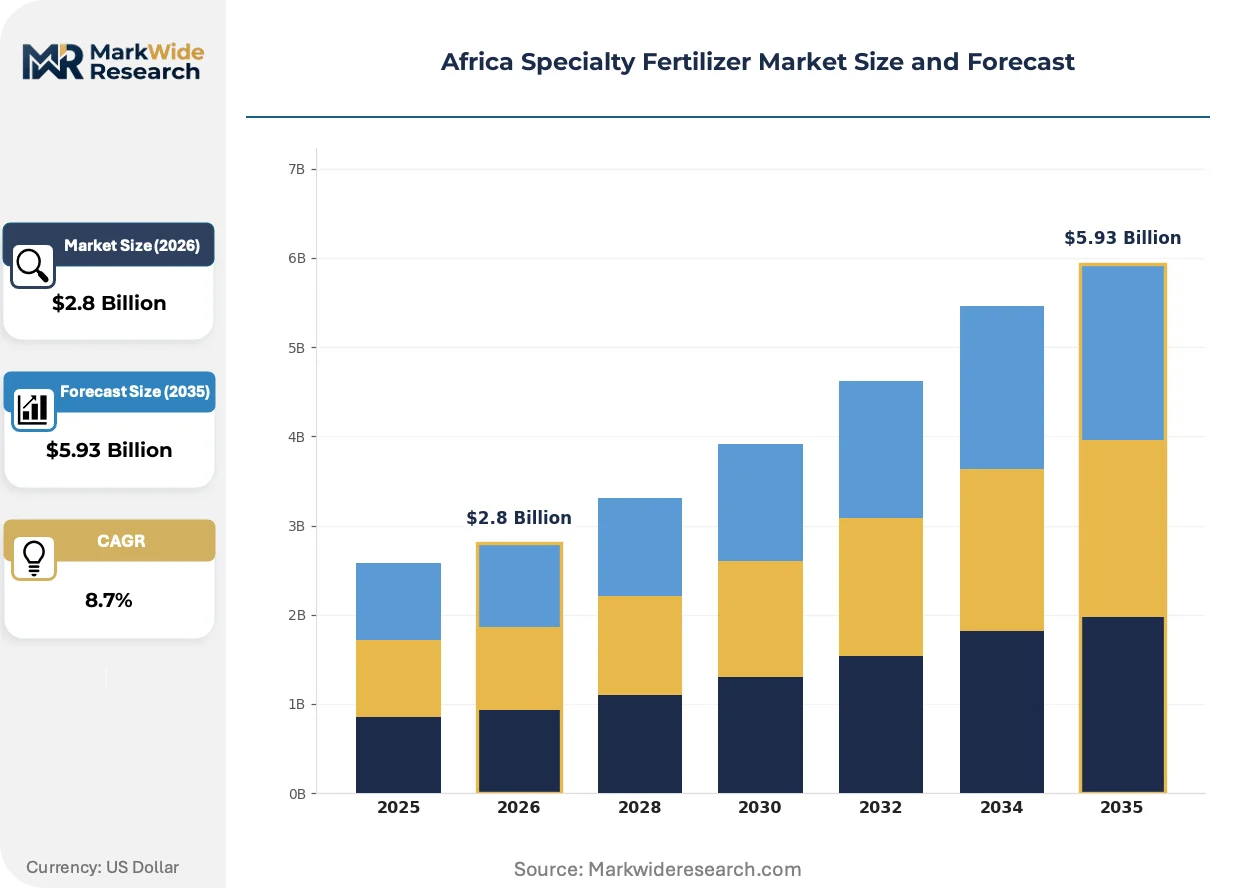
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Controlled Release Fertilizers, Liquid Fertilizers, Biofertilizers, Organic Fertilizers Application: Crops, Horticulture, Soil Amendments, Turf Management End User: Commercial Farmers, Agricultural Cooperatives, Retailers, Garden Centers Distribution Channel: Online Retail, Direct Sales, Agricultural Supply Stores, Wholesale Distributors |
| Companies Covered | SABIC Agri-Nutrients Co., Omnia Holdings Limited, Yara International ASA, Golden Fertilizer Company Limited, Dangote Fertilizer, OCP Group, K+S Aktiengesellschaft, Indorama Eleme Fertilizer & Chemicals, ICL Group Ltd, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Specialty Fertilizer Market Strategic Shifts
Specialty fertilizer markets across Africa are experiencing rapid product-format diversification as soil health diagnostics improve and irrigation infrastructure expands, creating pressure on legacy bulk distribution networks to adapt.
Polymer-coated controlled-release formulations are rewriting application economics for labor-constrained operations. These coatings meter nitrogen release across crop growth stages, eliminating multiple top-dressing passes. Estate managers in Kenya's tea and coffee zones are adopting coated urea at accelerated rates. The technology is compressing seasonal labor demand peaks and enabling larger effective farm sizes per permanent workforce.
South Africa's Department of Agriculture, Land Reform and Rural Development enforces registration under the Fertilizers, Farm Feeds, Seeds and Remedies Act, while Nigeria's Standards Organisation of Nigeria mandates SON certification for all imported blends. These frameworks are elevating compliance costs for new market entrants and favoring established registrants with existing dossiers. Mid-scale blenders are responding through regional registration arbitrage, centralizing formulation in South Africa for re-export to Common Market for Eastern and Southern Africa members.
Buyer aggregation through agricultural cooperatives is displacing individual smallholder purchasing across East African highland zones. Cooperative procurement officers now negotiate volume-based pricing for micronutrient-inclusive blends previously accessible only to estate operations. This channel shift is visible most acutely in Ethiopia's Oromia region, where cooperative unions have captured substantial share of fertilizer offtake previously fragmented across millions of individual transactions.
Africa Specialty Fertilizer Market Segmentation
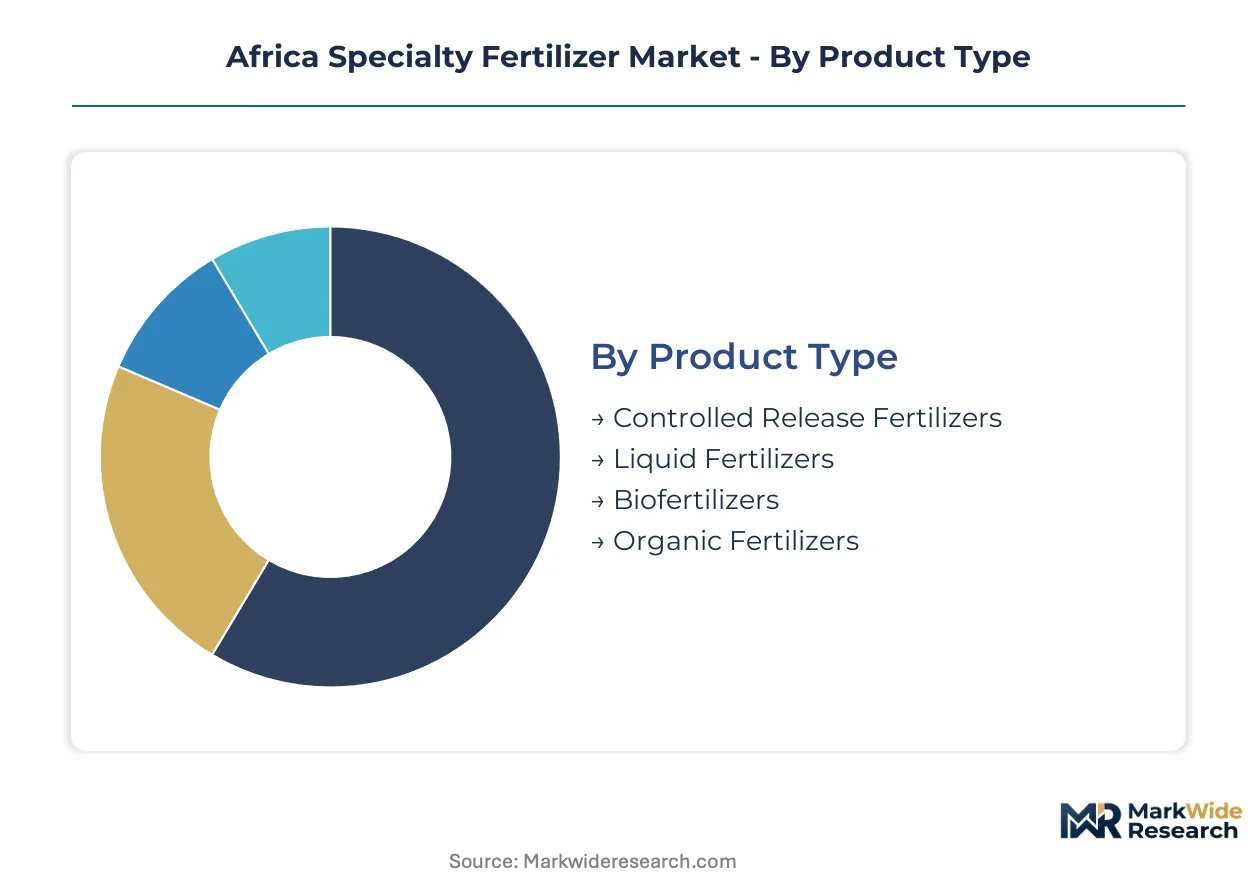
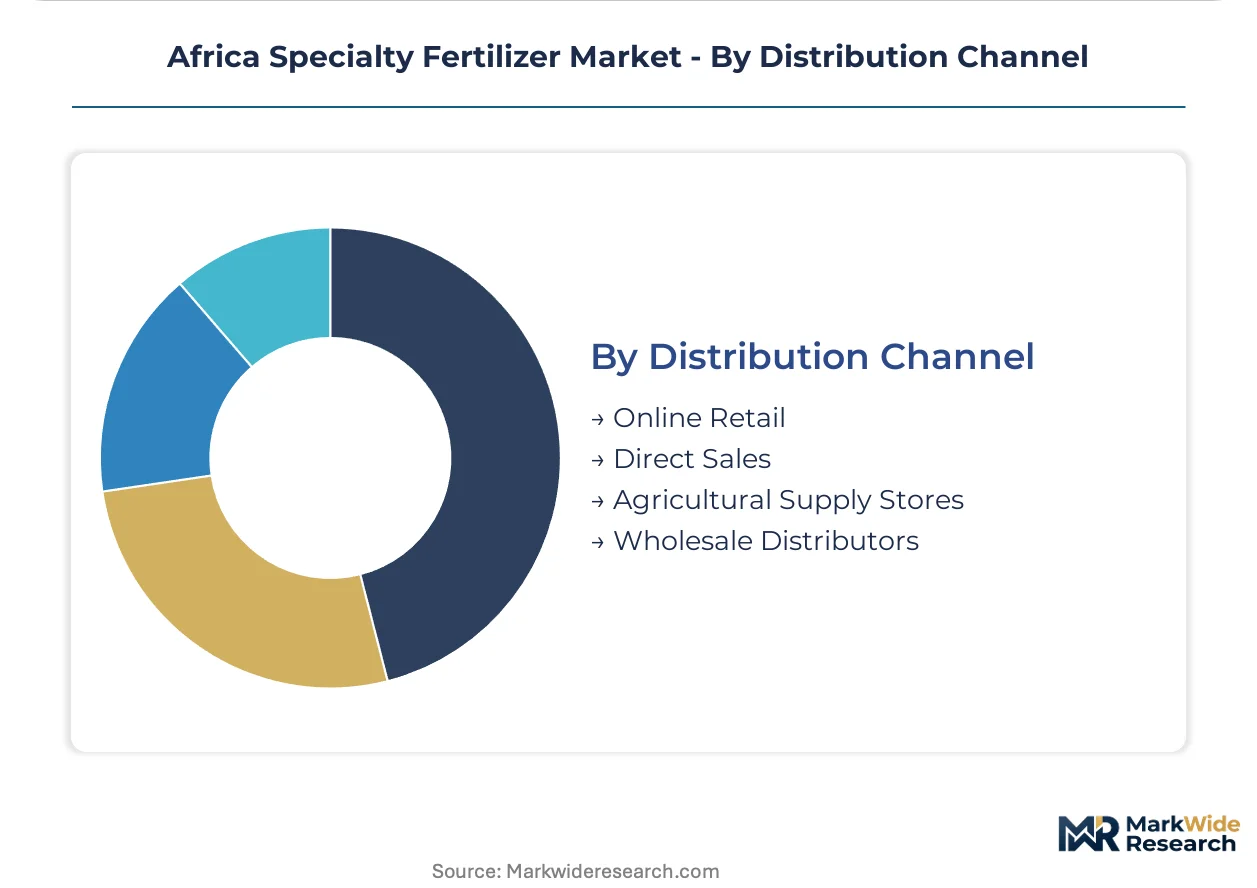
Specialty fertilizer segmentation across Africa reflects divergent agronomic requirements, infrastructure maturity, and buyer sophistication levels. Product format selection determines application economics, while channel structure shapes working capital burdens and technical advisory access.
Product Type:
Polymer coating chemistry and microbial formulation science define the technology frontier, with nutrient delivery precision separating premium tiers from commodity alternatives.
- Controlled Release Fertilizers:Polymer-coated urea and sulfur-coated formulations meter nitrogen release across 30-120 day windows, eliminating multiple top-dressing passes. Labor-scarce estate operations in Kenya's tea and coffee zones deploy these coatings to compress seasonal workforce peaks and expand effective farm scale per permanent employee.
- Liquid Fertilizers:Water-soluble concentrates and foliar suspensions enable fertigation compatibility in irrigated horticulture belts. Nigeria's northern vegetable zones and Ethiopia's Rift Valley flower farms drive demand for these formulations where drip infrastructure permits precise nutrient injection.
- Biofertilizers:Microbial inoculants containing nitrogen-fixing rhizobia or phosphate-solubilizing bacteria occupy a policy-favored niche as governments subsidize domestic production to reduce import dependency.
- Organic Fertilizers:Composted manure and vermicompost blends serve certified organic export operations and domestic niche markets with premium positioning constraints.
Mature deployment sits with Controlled Release Fertilizers on large estates. Newer deployment is concentrated in Biofertilizers where subsidy channels accelerate farmer trials.
Application:
End-use intensity varies sharply with crop value density and irrigation access, creating four distinct demand profiles across African farming systems.
- Crops:Row crop applications—maize, wheat, soybean—dominate volume offtake but command thinner margins due to price-sensitive smallholder procurement and bulk-oriented subsidy programs.
- Horticulture:High-value fruit and vegetable production in Morocco's Souss Valley and Senegal's Niayes zone demands micronutrient precision and fertigation compatibility, generating premium pricing tolerance.
- Soil Amendments:Humic acid complexes and gypsum-based conditioners address specific pH and structure deficiencies in degraded commercial farming belts, particularly across Zambia's copperbelt acid soils.
- Turf Management:Golf course and sports field maintenance in South Africa's urban centers sustains import-dependent demand for specialized slow-release formulations with aesthetic performance specifications.
Volume concentration remains in Crops. Margin expansion is climbing the fastest in Horticulture.
End User:
Buyer scale and technical capacity determine formulation complexity tolerance, with procurement centralization reshaping channel economics.
- Commercial Farmers:Estate-scale operations with in-house agronomy staff purchase direct from blenders, specifying custom micronutrient packages based on soil test results and crop physiological targets.
- Agricultural Cooperatives:Aggregating mid-scale growers across Ethiopia's Oromia region and Kenya's Rift Valley, these unions negotiate volume pricing for micronutrient-inclusive blends previously accessible only to estate buyers.
- Retailers:Rural agro-dealer networks stock fast-moving NPK grades with limited specialty inventory due to working capital constraints and demand uncertainty.
- Garden Centers:Urban consumer outlets in South African metros and Nigerian cities serve hobbyist segments with small-pack foliar feeds and ornamental-specific formulations.
Procurement consolidation is accelerating fastest among Agricultural Cooperatives. Direct technical relationships persist with Commercial Farmers.
Distribution Channel:
Channel selection trades transport cost efficiency against inventory risk and advisory proximity, with coastal-inland logistics shaping viable options.
- Direct Sales:Blender-to-farm relationships dominate estate procurement, eliminating distributor margins and enabling just-in-time delivery aligned with planting calendars.
- Wholesale Distributors:Regional warehousing networks bridge coastal formulation facilities to inland farming belts, carrying inventory risk for upcountry dealer networks.
- Agricultural Supply Stores:Dealer cooperatives and independent retailers provide last-mile access with limited technical advisory capacity.
- Online Retail:E-commerce platforms emerging in South Africa and Nigeria serve urban garden centers and remote commercial operations with courier-delivered small packs.
Working capital efficiency favors Direct Sales at scale. Geographic expansion is gaining share fastest through Wholesale Distributors building upcountry warehouse networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Nigeria and Ethiopia as water-soluble and foliar adoption accelerates. South Africa's regulatory infrastructure shapes regional compliance benchmarks. East African commercial farming belts drive micronutrient-enriched formulation growth.
Nigeria
Northern vegetable zones deploy fertigation-compatible liquid concentrates during labor-scarce growing seasons. The Standards Organisation of Nigeria mandates SON certification for all imported blends, elevating compliance costs for new entrants. Kano and Kaduna states anchor demand nodes where drip irrigation infrastructure permits precise nutrient injection into high-value horticulture.
Ethiopia
The Rift Valley flower farms drive premium-grade water-soluble fertilizer consumption for export-oriented rose production. National subsidy programs redirect procurement toward balanced formulations with micronutrient inclusion. Oromia region cooperative unions have captured substantial fertilizer offtake share previously fragmented across millions of individual smallholder transactions.
South Africa
Department of Agriculture, Land Reform and Rural Development enforces registration under the Fertilizers, Farm Feeds, Seeds and Remedies Act. Urban golf course and sports field maintenance in Johannesburg and Cape Town sustains import-dependent demand for specialized slow-release formulations. Coastal blending facilities serve as formulation hubs for re-export to Common Market for Eastern and Southern Africa members.
Kenya
Tea and coffee estate managers adopt polymer-coated urea at accelerated rates to compress seasonal workforce peaks. The African Union's 2024 soil health commitments reshape national subsidy programs toward micronutrient-inclusive grades. Nyeri and Kericho highland zones represent densest commercial farming demand for controlled-release coatings.
Morocco
OCP Group anchors regional phosphate availability through integrated mining and processing complexes. National programs subsidize microbial inoculants to reduce import dependency, creating policy-favored entry paths for biofertilizer production. Souss Valley horticulture operations demand micronutrient precision for export-oriented fruit and vegetable production.
Africa Specialty Fertilizer Market Competitive Environment
Moroccan producers anchor phosphate supply tier; South African and Norwegian specialists hold coastal blending and precision agriculture positions. Market structure reflects concentrated upstream mining integrated with regional formulation networks. Three archetypes dominate: integrated phosphate miners with captive raw material access, coastal blenders serving import-dependent markets, and precision service bundlers combining soil diagnostics with liquid product sales. Competitive moves center on backward integration into phosphate rock and strategic partnerships with agricultural cooperatives for distribution reach.
Within the integrated mining tier, OCP Group exemplifies upstream control over regional phosphate availability. Yara International ASA represents coastal blending specialists leveraging maritime logistics for import-dependent East and West African markets. Omnia Holdings Limited occupies the precision agriculture bundler position, combining technical advisory services with liquid fertilizer distribution. These three companies illustrate how geographic positioning and capability configuration shape competitive differentiation across the continent's specialty fertilizer value chain.
| Leading Market Players |
|---|
| SABIC Agri-Nutrients Co. |
| Omnia Holdings Limited |
| Yara International ASA |
| Golden Fertilizer Company Limited |
| Dangote Fertilizer |
| OCP Group |
| K+S Aktiengesellschaft |
| Indorama Eleme Fertilizer & Chemicals |
| ICL Group Ltd |
| Others |
Value Chain & Pricing Dynamics
Phosphate rock pricing indices from Moroccan mining complexes cascade through African specialty fertilizer value chains, compressing margins on P-dependent micronutrient blends while elevating premiums for polymer-coated formulations that reduce application labor costs.
Pricing Analysis
Volume concentrates in commodity NPK grades traded through national subsidy tenders, while margin accrues to controlled-release coatings and liquid concentrates serving estate-scale horticulture. Price differentiation hinges on certification grade under Nigeria's SON regime and volume scale negotiated by Ethiopian cooperative unions. Cost compression in bulk blends is intensifying because currency depreciation against dollar-denominated phosphate contracts inflates landed input costs. Smallholder collectives remain most price-sensitive, whereas Kenya's tea estates accept premium positioning for labor-saving coated urea.
Supply Chain Analysis
Empty polymer coating drums and spent microbial inoculant containers flow back to coastal blending facilities for refurbishment, creating reverse logistics networks that inland distributors rarely replicate. Manufacturing concentrates in Morocco, South Africa, and Nigeria, with OCP Group anchoring phosphate supply and Yara's coastal plants serving import-dependent East African markets. Raw material flows draw from sulfuric acid processors, polymer resin suppliers, and chelated micronutrient importers. Single-source vulnerability sits with Moroccan phosphate rock. Distribution runs through regional wholesale networks bridging coastal formulation to upcountry agricultural cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer-coated controlled-release technologies are displacing conventional split-application schedules across African estate farming, compressing procurement cycles for legacy bulk NPK while opening premium positioning for precision-grade formulations.
For Market Incumbents: Extend backward integration into phosphate mining or captive polymer coating supply to defend against Moroccan supply concentration and currency-driven input cost volatility. Deepen technical advisory capacity through soil diagnostics partnerships with Ethiopian cooperative unions, converting product sales into recurring precision agriculture service contracts that lock in offtake volumes. For New Entrants and Emerging Players: Agricultural cooperatives in East Africa's highland zones represent the most penetrable channel, with Oromia region unions aggregating mid-scale grower demand previously fragmented across millions of individual transactions. Enter through biofertilizer subsidy programs in Nigeria and Morocco, where policy-favored domestic production partnerships reduce import dependency and accelerate farmer trial adoption. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision agriculture bundlers with established soil testing capabilities in South Africa, where regulatory infrastructure under the Fertilizers, Farm Feeds, Seeds and Remedies Act creates multi-month approval bottlenecks that protect incumbent registrants. Monitor cooperative procurement officer training programs as an inflection indicator for channel power consolidation away from estate-scale direct sales.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Mining | OCP Group's captive Moroccan reserves demonstrate how upstream control insulates margin from raw material currency volatility. |
| Precision Agriculture Service Bundling | Omnia Holdings combines soil diagnostics with liquid fertilizer sales to convert commodity transactions into recurring revenue streams. |
| Cooperative Channel Partnership | Ethiopia's Oromia unions aggregate mid-scale demand, displacing fragmented smallholder procurement with volume-negotiated micronutrient blends. |
| Biofertilizer Subsidy Alignment | Morocco's national microbial inoculant programs create policy-favored entry paths that reduce import dependency exposure. |
| Regional Registration Arbitrage | South Africa's Fertilizers Act compliance enables re-export to COMESA members, centralizing formulation in regulatory-efficient hubs. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving fertilizer blenders, cooperative procurement officers, estate agronomists, and agricultural extension directors. Secondary sources included African Union soil health summit documentation, South Africa's Department of Agriculture registration databases, Nigeria's SON certification records, and phosphate trade flow statistics. Bottom-up demand estimates from crop-specific application rates reconciled with top-down market sizing through import value triangulation.
Data-stream reconciliation across shipment volumes, subsidy disbursement records, and cooperative offtake reports calibrated segment-level projections. Modeled dimensions spanned product format, crop application intensity, buyer scale tier, and regional infrastructure maturity. CAGRs derived from trend extrapolation of import growth trajectories, adjusted for subsidy program redirections and irrigation expansion timelines. Forecast inputs incorporated labor scarcity indices for estate operations and cooperative formation rates in highland zones.
Several conditions sit outside the modeled scope, including abrupt currency devaluations, African Union mandate implementation delays, and climate-induced planting calendar disruptions. Forecasts reflect assumptions regarding subsidy continuity and cooperative governance stability. Practitioners should monitor cooperative procurement officer training completion rates and drip irrigation installation subsidies for early signals of channel and technology adoption inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Global Phosphatic Fertilizers Market
Fertilizers
Fertilizer Tester Market
Fertilizers
India Organic Fertilizer Market
Fertilizers
Slow Release NPK Fertilizer Market
Fertilizers
Blue-Green Algae Fertilizer Market
Fertilizers
Europe Fertilizers Market
Fertilizers
Brazil Fertilizers Market
Fertilizers
France Fertilizer Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Compound Fertilizer Market
Fertilizers
Egypt Fertilizer Market
Fertilizers
Africa Micronutrient Fertilizer Market
Fertilizers
Enhanced Efficiency Fertilizer Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
Boron Fertilizers Market
Fertilizers
Organic Fertilizers Market