
 Global Liquid Fertilizer Market | 2026-2036
Global Liquid Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liquid Fertilizer Market Outlook
Controlled-release coating technology and fertigation automation is tilting liquid fertilizer deployment toward precision delivery systems. Nutrien Ltd. leverages its integrated retail network to dominate North American distribution channels. Yara International ASA anchors its position through deep R&D intensity in specialty nitrate formulations. ICL Group specializes in potassium and phosphate liquid blends for protected cropping environments.
Liquid fertilizer comprises nutrient solutions dissolved or suspended in aqueous carriers, typically formulated with nitrogen, phosphorus, and potassium at concentrations ranging from 20-40% total nutrient weight, designed for soil drenching, foliar spray, or drip irrigation delivery to optimize plant uptake efficiency. The urea-ammonium nitrate segment leads volume due to its cost position and compatibility with broadacre spraying equipment, while hydroponics application represents the fastest-expanding demand pool as controlled-environment agriculture scales. Multi-nutrient formulations command margin premiums over single-nutrient products by reducing application passes and labor costs for commercial growers.
The EPA regulates liquid fertilizer storage and spill containment under the Clean Water Act, while the EU Green Deal's nutrient loss reduction targets are forcing reformulation toward stabilized nitrogen products. Brazil's national fertilizer regulator mandates import quality certifications that shape product registration timelines for foreign suppliers. Stakeholders must monitor how carbon border adjustment mechanisms and Scope 3 emissions accounting reshape sourcing decisions across major agricultural economies.
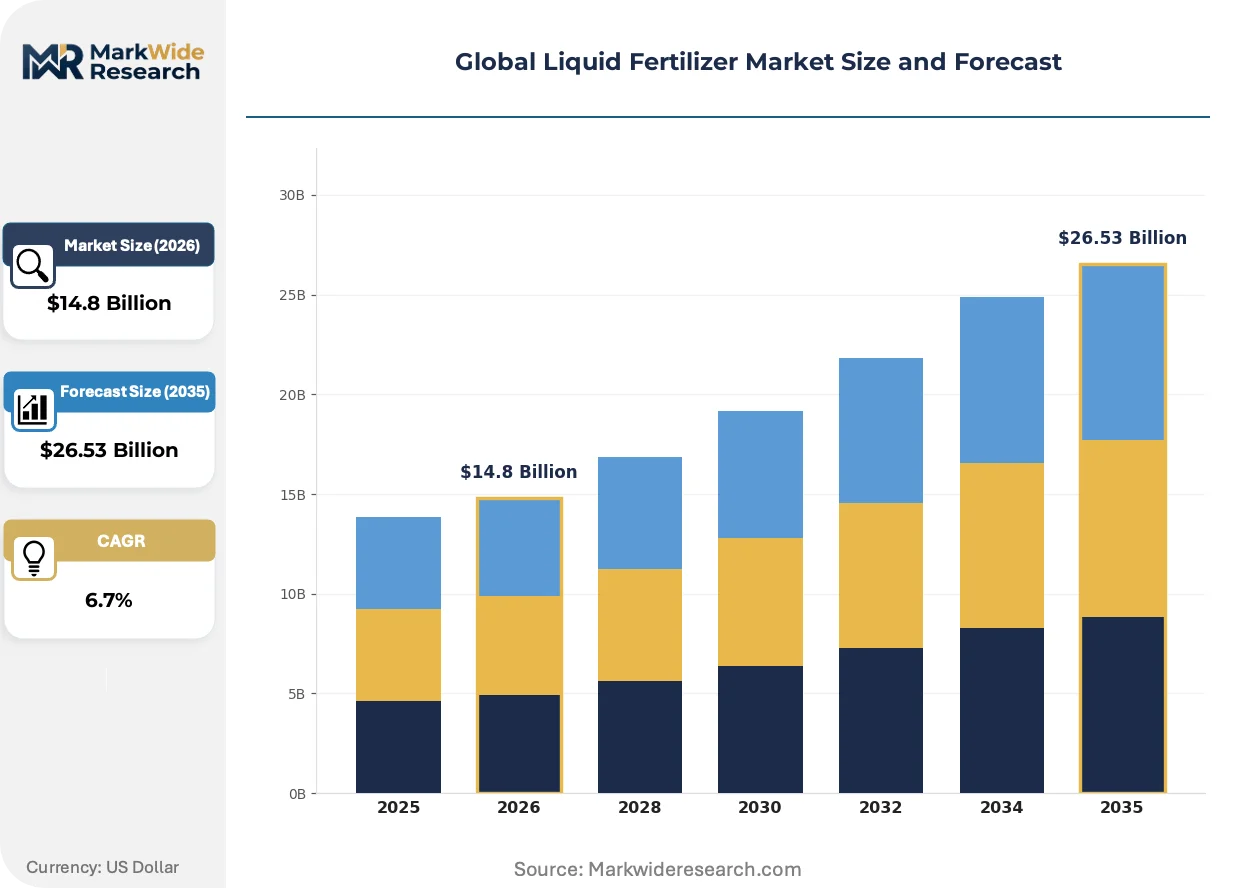
Market Dynamics
Precision fertigation infrastructure is compressing application cycles and forcing wholesale reformulation of nitrogen stabilization chemistry across major agricultural economies.
Growth Catalysts
- EU Green Deal nutrient-loss mandates:The Farm to Fork Strategy's 50% reduction targets for nutrient losses are compelling farmers toward stabilized liquid nitrogen products that minimize volatilization and leaching.
- Brazilian Cerrado intensification:Center-pivot irrigation expansion across Mato Grosso and Goiás is embedding liquid fertilizer directly into soybean and corn production systems at scale.
- Controlled-release coating advances:Polymer-encapsulated urea formulations are extending nutrient availability windows and reducing application frequency for commercial row-crop operations.
Market Restraints
- Anhydrous ammonia price volatility:Feedstock cost swings tied to natural gas benchmarks in the US Gulf and Russian supply disruptions are compressing blender margins and destabilizing contract pricing.
- Russian-Belarusian supply concentration:Potash and phosphate raw material dependencies on Black Sea corridor logistics create persistent disruption risk for European and Brazilian compounders.
- Soil microbiome degradation concerns:Repeated high-salinity liquid applications in China's Shandong and Hebei provinces are triggering regulatory scrutiny of long-term soil health impacts.
Strategic Opportunities
- Indian micro-irrigation penetration:Pradhan Mantri Krishi Sinchayee Yojana subsidies are accelerating drip system deployment in Maharashtra and Gujarat, opening fertigation-grade liquid demand from subsistence holdings.
- Carbon farming credit stacking:Australia's Emissions Reduction Fund and California's Cap-and-Trade Program are creating verified carbon credit revenue streams for precision nitrogen management adopters.
- Biostimulant-liquid convergence:Amino acid and seaweed extract co-formulations with NPK solutions are commanding premium positioning in Spain's Almería greenhouse cluster and the Netherlands' high-tech glasshouse sector.
Industry Challenges
- Fertigation equipment calibration expertise:Variable-rate injection system maintenance and nozzle optimization require specialized agronomic engineering talent scarce in Argentina's Pampas and Ukraine's Black Earth regions.
- Import registration timeline compression:ANVISA's fertilizer quality certification protocols in Brazil and India's FCO registration requirements are extending product launch cycles by 18-24 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liquid Fertilizer Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, Ammonium Nitrate, Potassium Nitrate, Calcium Nitrate Application: Agricultural Fields, Horticulture, Turf & Ornamental, Hydroponics Formulation: Single Nutrient, Multi Nutrient, Organic, Inorganic End User: Farmers, Agricultural Cooperatives, Distributors, Retailers |
| Companies Covered | Nutrien Ltd., Yara International ASA, ICL Group, CF Industries Holdings, Inc., The Mosaic Company, IFFCO, K+S Aktiengesellschaft, EuroChem Group, AgroLiquid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liquid Fertilizer Market Strategic Shifts
Real-time soil sensing and autonomous application systems are collapsing the feedback loop between nutrient detection and delivery, forcing chemistry suppliers to integrate with digital agriculture platforms or face disintermediation.
Nano-encapsulated nitrogen formulations using layered double hydroxide clay matrices are rendering obsolete conventional urea-ammonium nitrate blends in high-value specialty crop segments. Large-scale citrus and avocado producers in California's Central Valley and Chile's Valparaíso region are retrofitting sprayers for sub-micron droplet delivery. The technology is rendering obsolete the historical trade-off between application frequency and nutrient use efficiency that structured liquid fertilizer economics for decades.
REACH authorization requirements for polymer stabilizers and the EU F-Gas Regulation's phase-down schedules are forcing reformulation of controlled-release coating chemistries toward bio-based alternatives. Compounders must resubmit dossiers for existing product registrations, compressing R&D timelines and raising compliance costs. Specialty nitrate producers with in-house polymer research capabilities in Germany and the Netherlands are capturing displaced volume from importers lacking European technical infrastructure.
Consolidated procurement through agricultural cooperatives and input financing platforms is displacing traditional dealer networks in North America's Corn Belt and Australia's wheat-sheep zones. Farmers are aggregating volume commitments through digital tender platforms that pit blenders against each other on delivered-price contracts. The pattern is most pronounced in Iowa and Illinois, where cooperative buying groups now control over half of liquid nitrogen volume, extracting price transparency and service bundling concessions previously unavailable to dispersed growers.
Global Liquid Fertilizer Market Segmentation
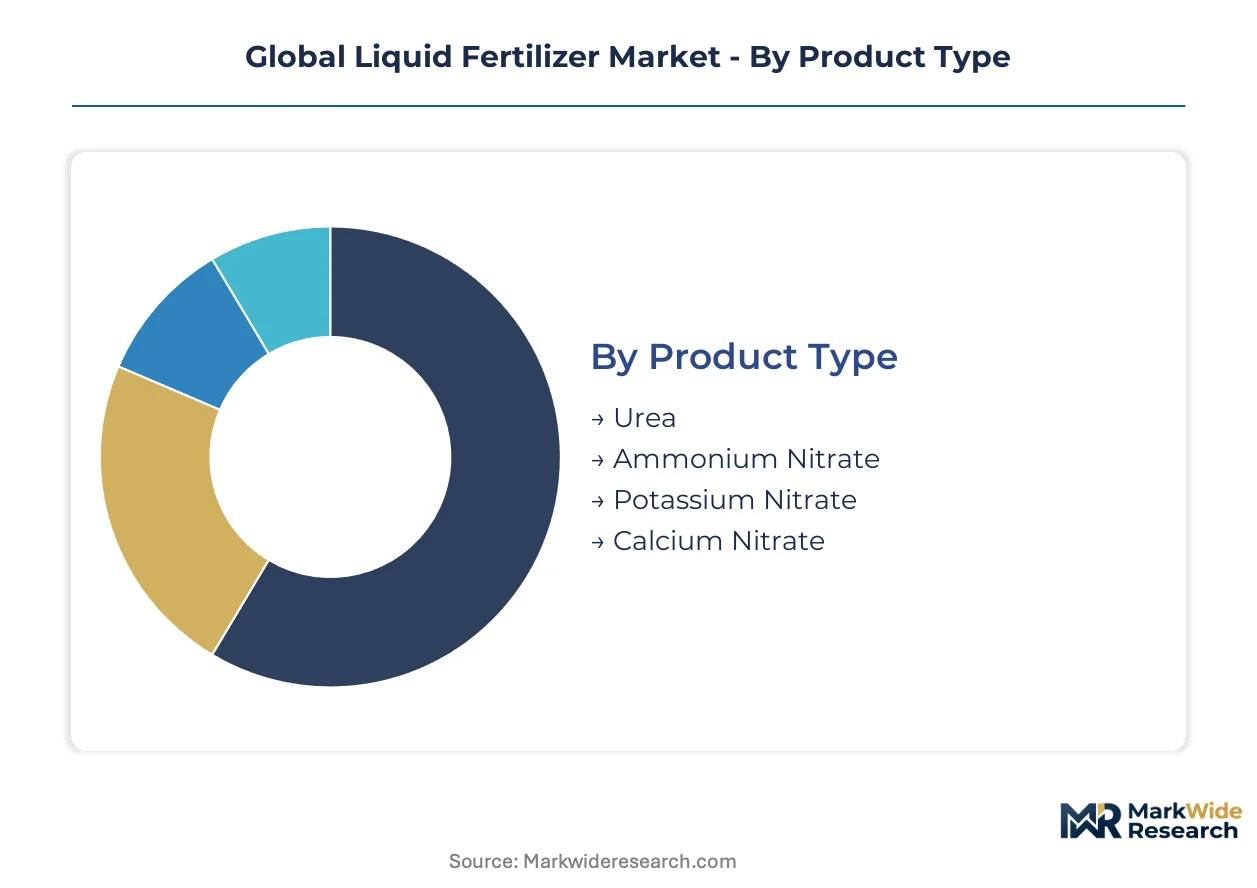
Liquid fertilizer segmentation reveals how formulation chemistry and delivery infrastructure shape procurement patterns. Product categories align with distinct agronomic workflows, from broadacre spraying to precision fertigation systems.
Product Type:
Mature commodity chemistries dominate volume, while specialty nitrates command margin premiums in high-value cropping systems.
- Urea:The most widely deployed nitrogen source, typically formulated as urea-ammonium nitrate solutions with 28-32% nitrogen content. Brazilian soybean operations in Mato Grosso embed UAN into center-pivot irrigation systems at scale. Cost position and equipment compatibility sustain its throughput leadership across row-crop geographies.
- Ammonium Nitrate:High-solubility formulations deliver rapid nitrogen availability for foliar and soil applications. European wheat producers under EU Green Deal nutrient-loss mandates are shifting toward stabilized ammonium nitrate variants to reduce volatilization. The segment captures premium positioning where environmental compliance tightens.
- Potassium Nitrate:Dual-nutrient chemistry supplies nitrogen and potassium without chloride sensitivity. Greenhouse tomato operations in Spain's Almería cluster specify potassium nitrate for drip irrigation to manage salinity.
- Calcium Nitrate:Water-soluble calcium source prevents blossom-end rot in fruiting crops. California strawberry producers deploy calcium nitrate through drip lines during peak fruit development windows.
Urea handles the majority of throughput; calcium nitrate is the fastest mover on share.
Application:
Application segments stratify by infrastructure intensity, from rain-fed broadacre to fully controlled environments.
- Agricultural Fields:Large-scale row-crop deployment via ground sprayers and aerial application. US Corn Belt operations combine liquid nitrogen with herbicide passes to reduce field traffic. Volume concentration reflects mechanized farming scale.
- Horticulture:Protected cropping systems in the Netherlands and Belgium demand precise nutrient dosing for substrate-grown vegetables. pH-buffered formulations prevent root zone acidity fluctuations in recirculating hydroponics.
- Turf & Ornamental:Golf course superintendents and landscape contractors apply foliar feeds for rapid color response. Slow-release nitrogen stabilizers extend greening duration between applications.
- Hydroponics:Fully soilless systems require complete nutrient solutions with balanced EC and pH parameters. Vertical farming operations in Singapore and the UAE specify hydroponics-grade liquids for closed-loop water management.
Agricultural fields absorb the dominant volume share; hydroponics climbs the fastest as controlled-environment agriculture scales.
Formulation:
Formulation complexity determines blending economics and application labor requirements.
- Single Nutrient:Dedicated nitrogen, phosphorus, or potassium solutions allow growers to customize ratios through tank mixing. Australian broadacre wheat farmers blend single-nutrient liquids to match soil test recommendations.
- Multi Nutrient:Pre-blended NPK solutions reduce field passes and mixing errors. Indian sugarcane cooperatives in Maharashtra specify multi-nutrient formulations to streamline labor during peak planting windows.
- Organic:Plant-derived and animal-waste-based liquids certified for organic production systems. German biodynamic vineyards source organic liquid fertilizers to maintain certification compliance.
- Inorganic:Synthetic mineral salts dissolved in aqueous carriers for maximum nutrient concentration and cost efficiency. Chinese greenhouse operators in Shandong province favor inorganic formulations for high-yield tomato production.
Multi-nutrient formulations capture expanding share through labor savings; organic liquids show steepest expansion trajectory on a small base.
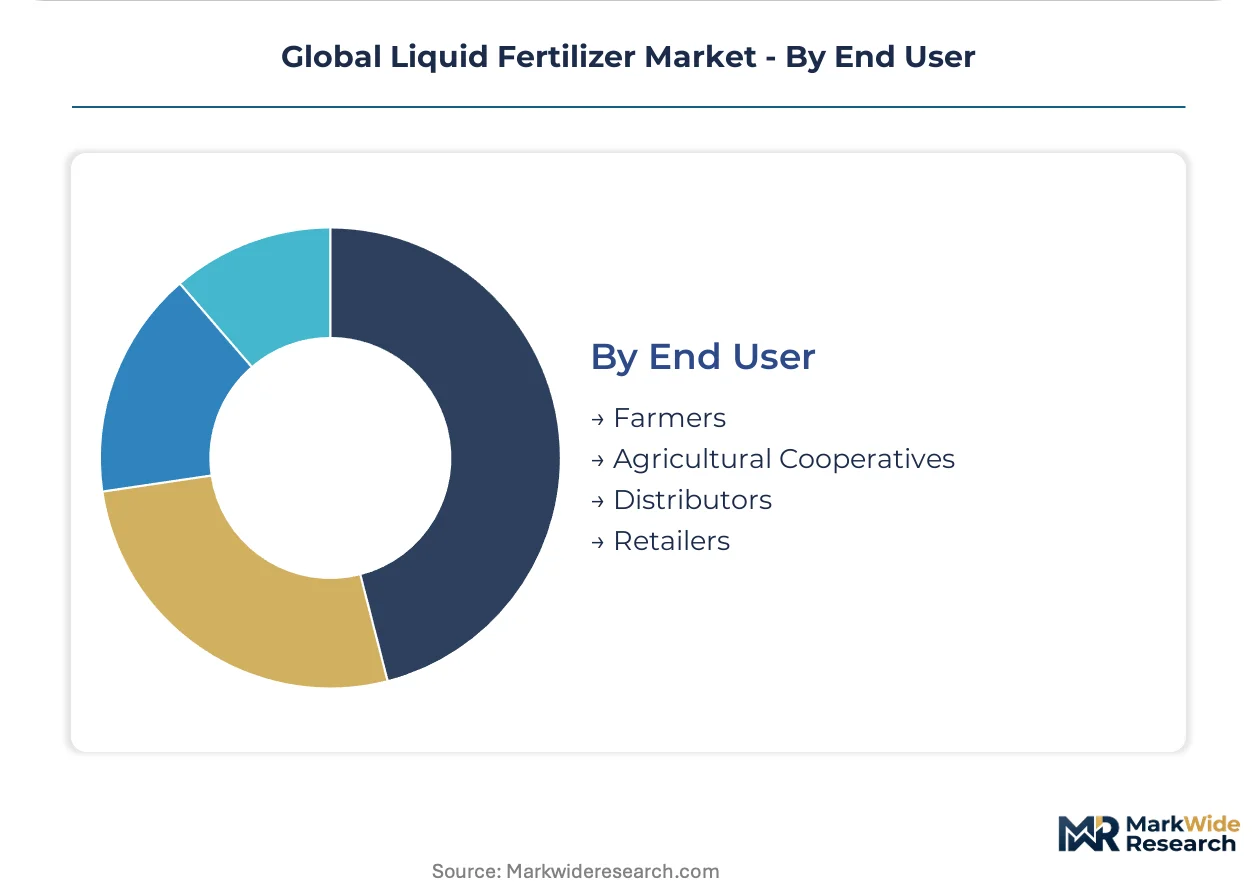
End User:
Procurement channels are consolidating around cooperative buying power and integrated retail networks.
- Farmers:Direct purchasers managing input decisions for owned or leased land. Argentine soybean growers in the Pampas region negotiate liquid nitrogen contracts tied to commodity price hedges.
- Agricultural Cooperatives:Member-owned aggregators pooling volume for price leverage. Iowa and Illinois cooperatives now control majority liquid nitrogen procurement in their service territories.
- Distributors:Regional wholesalers managing logistics and storage for blender networks. Ukrainian distributors navigate Black Sea corridor disruptions to maintain compounder supply.
- Retailers:Point-of-sale agronomists bundling fertilizer with seed and crop protection. Brazilian rural retailers extend input financing to soybean producers through harvest-backed credit.
Agricultural cooperatives are capturing procurement share fastest; farmers remain the foundational demand source across all geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in liquid fertilizer track the divergence between import-dependent agricultural economies and feedstock-rich manufacturing hubs. Brazil and India absorb the largest import volumes, while the United States and Russia maintain structural export surpluses in nitrogen intermediates.
Brazil
Center-pivot irrigation expansion across Mato Grosso and Goiás embeds liquid fertilizer directly into soybean-corn rotation systems. ANVISA's import quality certification protocols extend product registration timelines for foreign suppliers. The Cerrado region's intensive fertigation infrastructure now represents the densest deployment of liquid nitrogen injection systems outside the US Corn Belt.
United States
Large-scale row-crop operations in Iowa and Illinois consolidate procurement through cooperative buying groups controlling majority liquid nitrogen volume. EPA storage and spill containment rules under the Clean Water Act shape terminal infrastructure investments. The Gulf Coast's ammonia pipeline network feeds blender operations across the Corn Belt with cost-advantaged urea-ammonium nitrate feedstock.
India
Pradhan Mantri Krishi Sinchayee Yojana subsidies accelerate drip system deployment in Maharashtra and Gujarat, opening fertigation-grade liquid demand from smallholder holdings. FCO registration requirements extend product launch cycles for new market entrants. Sugar cooperatives in western Maharashtra specify multi-nutrient formulations to streamline peak-season labor constraints.
China
Greenhouse operators in Shandong province favor inorganic formulations for high-yield tomato production, though repeated high-salinity applications trigger regulatory scrutiny of soil microbiome impacts. The Ministry of Ecology and Environment monitors nutrient runoff in the Yangtze and Yellow River basins. Shandong and Hebei provinces concentrate the country's protected cropping liquid fertilizer consumption.
Germany
Specialty nitrate producers with in-house polymer research capabilities capture displaced volume from importers lacking European technical infrastructure. REACH authorization requirements for polymer stabilizers force reformulation of controlled-release coating chemistries. The Netherlands-Germany corridor hosts the densest cluster of greenhouse liquid fertilizer formulators serving northwest European protected cropping.
Global Liquid Fertilizer Market Competitive Environment
On the supply side, the industry is consolidating around integrated nutrient majors with captive feedstock positions and regional blending networks. Mid-scale compounders compete through formulation specialization and proximity to high-value horticulture clusters. Two strategic archetypes dominate: integrated majors controlling ammonia-to-retail value chains, and regional specialists commanding premium positioning in protected cropping segments. Competitive intensity centers on backward integration into ammonia supply and forward integration into precision application services.
Among integrated nutrient majors, Nutrien Ltd. and Yara International ASA occupy positions exemplifying scale-driven archetypes with retail network density. ICL Group represents the specialty formulation vector, anchoring potassium and phosphate liquid blend expertise for protected cropping environments. These three entities illustrate the structural divergence between commodity nitrogen throughput players and margin-focused specialty compounders.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| Yara International ASA |
| ICL Group |
| CF Industries Holdings, Inc. |
| The Mosaic Company |
| IFFCO |
| K+S Aktiengesellschaft |
| EuroChem Group |
| AgroLiquid |
| Others |
Value Chain & Pricing Dynamics
Natural gas price volatility in the US Gulf and Russian supply corridors determines both margin compression across nitrogen tiers and the geographic reconfiguration of ammonia sourcing networks. Buyers face widening spreads between contract-indexed and spot-indexed formulations as feedstock instability feeds through blender economics.
Pricing Analysis
Large-scale cooperative buyers anchor a contract-based long-term offtake structure across the Corn Belt and Brazilian Cerrado. Three-tier pricing structure across premium stabilized-nitrogen, standard UAN blends, and economy single-nutrient solutions differentiates on certification grade and volume scale. Cost compression in economy tiers is intensifying because natural gas benchmark swings transmit directly into urea-ammonium nitrate production economics. Smallholder farmers in India's Maharashtra and Gujarat exhibit highest price sensitivity, while greenhouse operators in the Netherlands' Westland cluster prioritize nutrient precision over unit cost.
Supply Chain Analysis
Extended payment terms from Brazilian rural retailers and supply-chain finance facilities through North American agricultural cooperatives shape working capital dynamics across the value chain. Ammonia production concentrates in the United States, Russia, and Trinidad and Tobago, with nitrogen upgrading distributed to regional compounding hubs. The supply chain draws from phosphate rock deposits in Morocco and potash reserves in Canada and Belarus. Single-source vulnerability around Black Sea corridor logistics persists for European compounders. Distribution runs through integrated retail networks in North America and cooperative aggregators in South America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquid fertilizer market is recovering from cyclical trough conditions as Brazilian soybean acreage expansion and EU Green Deal compliance investments restock channel inventories.
For Market Incumbents: Insulate margin structures through backward integration into ammonia production and captive polymer coating capabilities. Nutrien Ltd. and Yara International ASA demonstrate how retail network density buffers against commodity nitrogen price swings. Prioritize certification pre-positioning for EU REACH authorization timelines to capture displaced import volume. For New Entrants and Emerging Players: Establish a beachhead in India's Maharashtra drip-irrigation corridor where PMKSY subsidies accelerate fertigation adoption among underserved smallholders. Target biostimulant-liquid co-formulation demand in Spain's Almería greenhouse cluster where premium positioning commands sustainable margin. Deploy agronomic engineering partnerships to overcome equipment calibration expertise gaps. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down schedules and REACH polymer stabilizer authorizations reshape the acquisition landscape toward European technical infrastructure owners. Five-to-ten year viability favors specialty nitrate compounders with in-house R&D capabilities over pure-play nitrogen traders. Monitor ANVISA registration timeline compression in Brazil as inflection indicator for foreign supplier displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Production | Captive feedstock supply from US Gulf pipeline networks insulates blender margins from natural gas volatility. |
| Controlled-Release Coating R&D Investment | Polymer encapsulation capabilities in Germany and the Netherlands capture EU Green Deal compliance premiums. |
| Precision Fertigation Service Bundling | Variable-rate injection partnerships with Brazilian center-pivot operators lock in multi-year liquid nitrogen contracts. |
| Biostimulant Co-Formulation Development | Amino acid and seaweed extract integration commands premium positioning in Almería and Westland greenhouse clusters. |
| Digital Procurement Platform Deployment | Iowa and Illinois cooperative tender systems extract price transparency from blender competition. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with agronomic engineers at fertigation equipment manufacturers, procurement leads at Brazilian agricultural cooperatives, technical R&D directors at European specialty nitrate producers, and channel managers at North American retail networks. Secondary validation drew from EPA Clean Water Act enforcement records, EU Farm to Fork Strategy implementation reports, ANVISA fertilizer registration databases, and SEC 10-K filings from listed nutrient majors. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Calibration against historical nitrogen consumption patterns and ammonia capacity utilization rates anchored the projection framework. Segmentation dimensions spanned product chemistry tier, application infrastructure intensity, formulation complexity, and end-user procurement channel. CAGRs were derived from trend extrapolation moderated by regulatory inflection points and feedstock cost cycle assumptions. Forecast inputs incorporated center-pivot irrigation deployment rates in Mato Grosso and drip system penetration in Maharashtra.
Sensitivities concentrate around natural gas benchmark trajectories, Black Sea logistics stability, and EU authorization timeline compression. Forecasts reflect documented assumptions regarding Brazilian acreage expansion and Indian subsidy continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Global Starter Fertilizers Market
Fertilizers
Global Micronutrient Fertilizer Market
Fertilizers
Global Foliar Fertilizer Market
Fertilizers
United States Fertilizers Market
Fertilizers
Fertilizer Tester Market
Fertilizers
Vietnam Biofertilizer Market
Fertilizers
Russia Specialty Fertilizer Market
Fertilizers
Boron Fertilizers Market
Fertilizers
Italy Water Soluble Fertilizer Market
Fertilizers
Crop Micronutrients Market
Fertilizers
Europe Fertilizers Market
Fertilizers
Nitrogen Nutrients Market
Fertilizers
South America Micronutrient Fertilizer Market
Fertilizers
Argentina Fertilizer Market
Fertilizers
Neem-Based Fertilizers Market
Fertilizers
Africa Micronutrient Fertilizer Market