
 France Fertilizer Market | 2026-2036
France Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
France Fertilizer Market Insights
Specialty-grade nitrogen formulations is unwinding conventional commodity dynamics across French agriculture. Yara France SAS leverages its coastal import infrastructure to sustain cost-competitive ammonia supply chains. Groupe Roullier anchors premium micronutrient blending through its Brittany-based research campus. EuroChem Agro France competes on phosphate origin flexibility, sourcing from multiple mining jurisdictions to navigate price volatility.
Fertilizer denotes chemically or organically derived soil amendments supplying essential macronutrients—nitrogen, phosphorus, and potassium—alongside secondary and trace elements, with formulations specified by N-P-K ratios, solubility rates, and application compatibility for specific crop systems. These inputs correct soil deficiencies, enhance yield density, and support plant metabolic functions across France's diverse agricultural zones. Organic fertilizers capture expanding margin pools as vineyard and orchard operators pursue residue-free certification chains, while controlled-release fertilizers lead growth in high-value horticultural segments where precision dosing reduces leaching losses. Granular forms dominate volume throughput in cereal production, though liquid formulations gain share in mechanized spraying operations across the Paris Basin.
ANSM oversees fertilizer product safety assessments, while the EU Green Deal's nutrient reduction targets and France's national Ecophyto plan constrain synthetic nitrogen deployment rates. ECHA's REACH framework governs additive chemistries, and the F-Gas Regulation shapes greenhouse gas accounting for ammonia production facilities. Stakeholders must monitor carbon border adjustment mechanisms and low-carbon ammonia certification schemes as they recalibrate sourcing strategies and capital allocation priorities.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing synthetic nitrogen deployment rates while specialty-grade formulations capture margin pools in French viticulture and horticulture. This regulatory tightening is rewiring procurement patterns across the Paris Basin cereal belt and southwestern maize regions.
Growth Catalysts
- Ecophyto Plan Mandates:France's national pesticide and nutrient reduction program creates certified demand for controlled-release fertilizers that minimize leaching losses in vineyard operations.
- Champagne-Ardenne Specialty Expansion:Controlled-release formulations are penetrating high-value horticultural segments where precision dosing supports residue-free certification chains.
- Carbon Border Adjustment Mechanism:The EU's CBAM creates competitive advantage for low-carbon ammonia producers sourcing renewable hydrogen for French fertilizer manufacturing.
Market Restraints
- Natural Gas Price Volatility:Ammonia production costs fluctuate with European benchmark pricing, squeezing margins for nitrogen fertilizer manufacturers without coastal import infrastructure.
- Phosphate Rock Concentration:Moroccan and Russian mining jurisdictions dominate upstream phosphate supply, exposing French blenders to geopolitical disruption risks.
- REACH Registration Burden:ECHA's additive chemistry compliance timelines extend product development cycles for novel micronutrient formulations.
Strategic Opportunities
- Loire Valley Vineyard Conversion:Organic and biodynamic certification growth creates demand for residue-free fertilizer inputs in premium wine production zones.
- Low-Carbon Ammonia Certification:Renewable hydrogen-derived nitrogen fertilizers command premium positioning under emerging EU climate labeling schemes.
- Liquid Formulation Mechanization:Precision spraying equipment adoption in the Paris Basin enables higher-margin liquid fertilizer penetration versus granular commodity products.
Industry Challenges
- Soil Science Talent Scarcity:Agronomic expertise in precision nutrient management lags behind controlled-release technology deployment rates in French cooperative extension networks.
- Legacy Equipment Retrofit Costs:Cereal producers face capital intensity in adapting storage and application infrastructure for stabilized nitrogen formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Fertilizer Market |
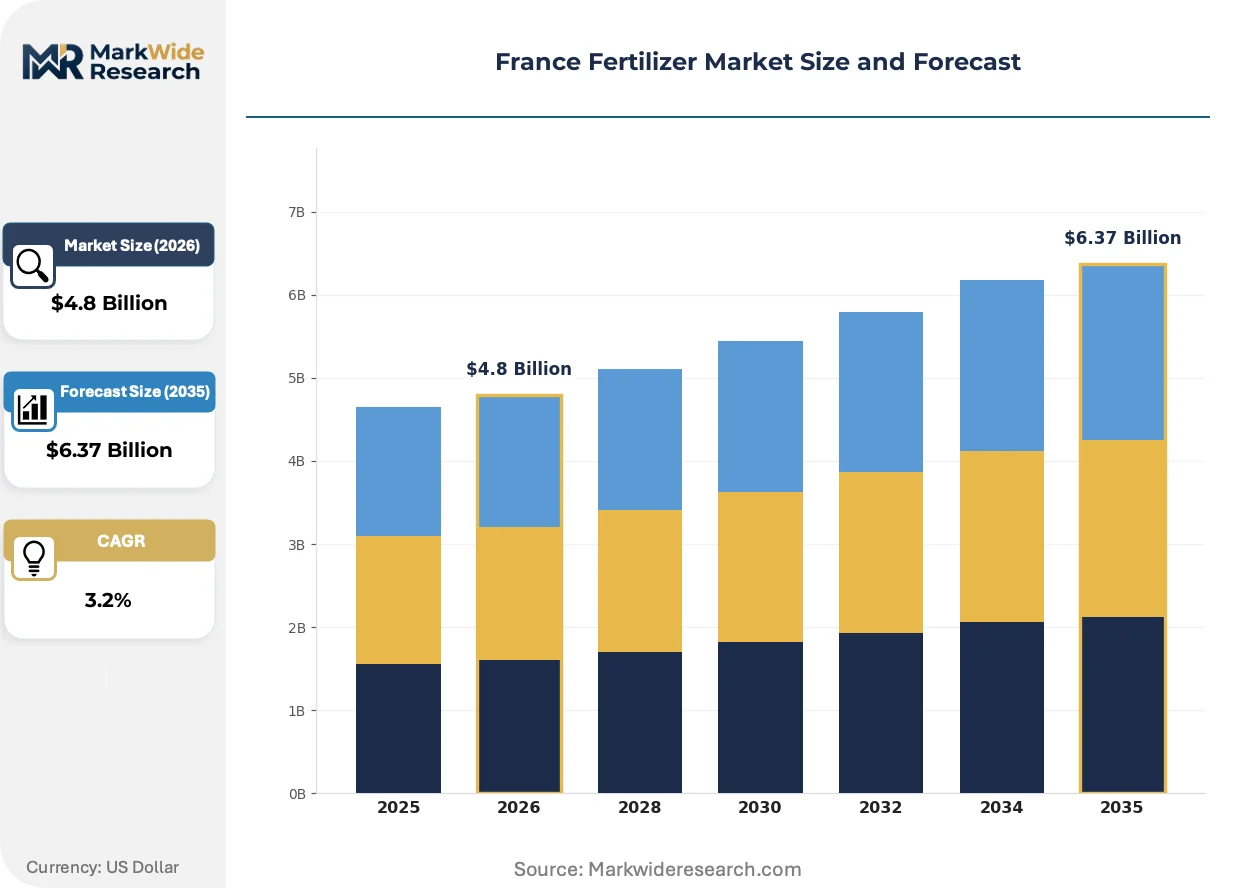
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.37 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Fertilizers, Inorganic Fertilizers, Controlled-Release Fertilizers, Liquid Fertilizers Application: Agricultural, Horticultural, Turf & Ornamental, Industrial Form: Granular, Powder, Liquid, Pellets Distribution Channel: Direct Sales, Distributors, Online Retail, Agricultural Cooperatives |
| Companies Covered | PLANTIN, SOCACO International Biopost, Yara France SAS, ICL France, OCI Nitrogen, Groupe Roullier, GERMIFLOR – LAUTIER, EuroChem Agro France, Fertiberia Sarl, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Fertilizer Market Trends and Innovations
Biostimulant integration and digital nutrient mapping are converging to displace blanket-rate synthetic application across French agricultural zones. These shifts favor precision agriculture service providers over commodity fertilizer distributors.
Controlled-release polymer coatings are displacing conventional urea in high-value crop segments. Vineyard operators in Burgundy and Alsace are adopting stabilized nitrogen formulations at accelerated rates. This displacement is compressing commodity nitrogen margins while expanding specialty formulation pools.
France's national Ecophyto plan tightens nutrient management standards through mandatory reduction targets. The regulation forces cooperative purchasing groups to requalify product portfolios toward certified low-leaching alternatives. Northern France's cereal belt faces the steepest compliance recalibration as catchment area restrictions tighten.
Buyer aggregation through agricultural cooperatives is consolidating procurement power across the Paris Basin. Traditional distributor networks face disintermediation as direct manufacturer-cooperative contracts expand. This concentration is most visible in maize-growing regions of southwestern France where volume scale enables formula customization.
France Fertilizer Market Segmentation
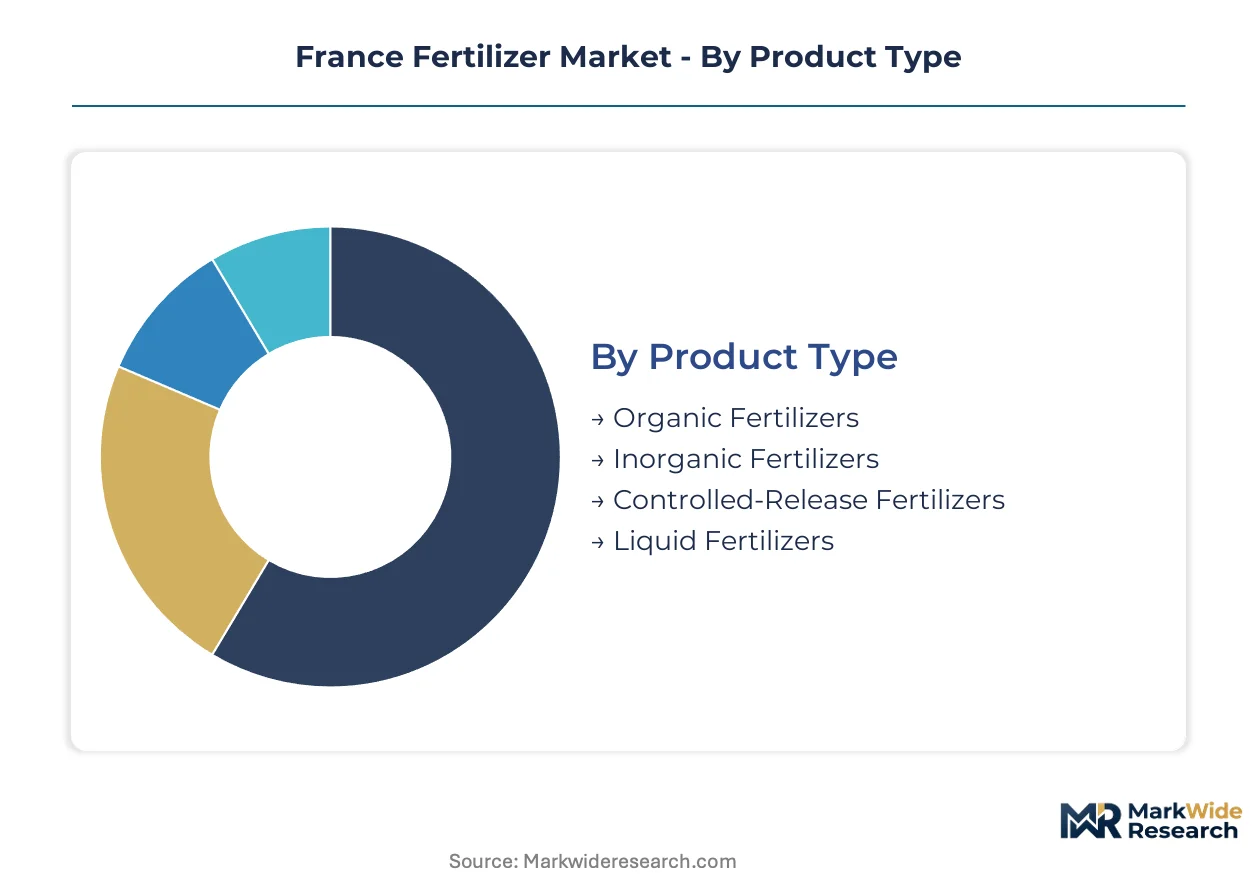
Fertilizer demand in France fragments across product chemistry, crop application, physical form, and procurement channel. Each segmentation axis reveals distinct margin structures and competitive dynamics shaped by the EU Green Deal's nutrient reduction mandates.
Product Type:
Inorganic fertilizers dominate domestic volume throughput through the Paris Basin cereal belt, while organic and controlled-release formulations concentrate export-led premium positioning toward vineyard and specialty crop operators.
- Inorganic Fertilizers:Synthetic nitrogen, phosphate, and potassium compounds manufactured via ammonia synthesis and phosphate rock processing. Demand concentrates in northern France's cereal belt where cooperative purchasing groups favor cost-competitive bulk supply chains for wheat and barley production.
- Controlled-Release Fertilizers:Polymer-coated or stabilized formulations that meter nutrient release over extended periods. Vineyard operators in Champagne-Ardenne and the Loire Valley are expanding procurement of these inputs to meet Ecophyto plan leaching reduction targets while sustaining yield density in high-value wine production.
- Organic Fertilizers:Derived from composted animal manure, plant residues, or processed organic waste streams. Biodynamic certification growth in Burgundy drives residue-free input demand.
- Liquid Fertilizers:Soluble or suspension concentrates designed for mechanized foliar or soil application. Southwestern maize regions adopt these for precision spraying compatibility.
Inorganic fertilizers hold the largest share; momentum sits with controlled-release formulations.
Application:
Cost tier differentiation separates commodity-scale agricultural deployment from premium horticultural and turf segments where certification requirements command input price premiums.
- Agricultural:Field crop production spanning cereals, oilseeds, protein crops, and forage systems across the Paris Basin and southwestern France. Granular nitrogen and compound fertilizers dominate procurement through cooperative networks facing Ecophyto compliance pressure.
- Horticultural:Protected cultivation, nursery stock, and high-value open-field vegetable production. Controlled-release and liquid micronutrient formulations penetrate this segment fastest where precision dosing supports residue-free certification chains.
- Turf & Ornamental:Golf course, sports field, and landscape maintenance applications. Slow-release nitrogen specifications dominate technical purchasing criteria.
- Industrial:Non-agricultural uses including water treatment, mining, and chemical manufacturing feedstocks. Phosphate and sulfur-based compounds concentrate demand here.
Agricultural applications absorb the greatest volume; horticultural inputs climb the fastest on margin expansion.
Form:
Volume throughput favors granular and powder forms in mechanized broadcast operations, while liquid adoption accelerates where precision equipment investment enables higher-margin application economics.
- Granular:Hard, uniform prills or pellets engineered for mechanical spreading equipment. Northern France's cereal belt relies on these for urea and compound fertilizer deployment at scale.
- Liquid:Aqueous solutions or suspensions compatible with injection or foliar spraying systems. Southwestern maize regions lead conversion as precision agriculture service providers displace commodity distributors.
- Powder:Fine-ground materials for bulk blending or dissolution. Specialty micronutrient premixes favor this form.
- Pellets:Compressed organic or compound materials for controlled-release or localized placement. Vineyard row applications drive niche demand.
Granular forms command the greatest volume; liquid formulations gain share fastest through mechanization.
Distribution Channel:
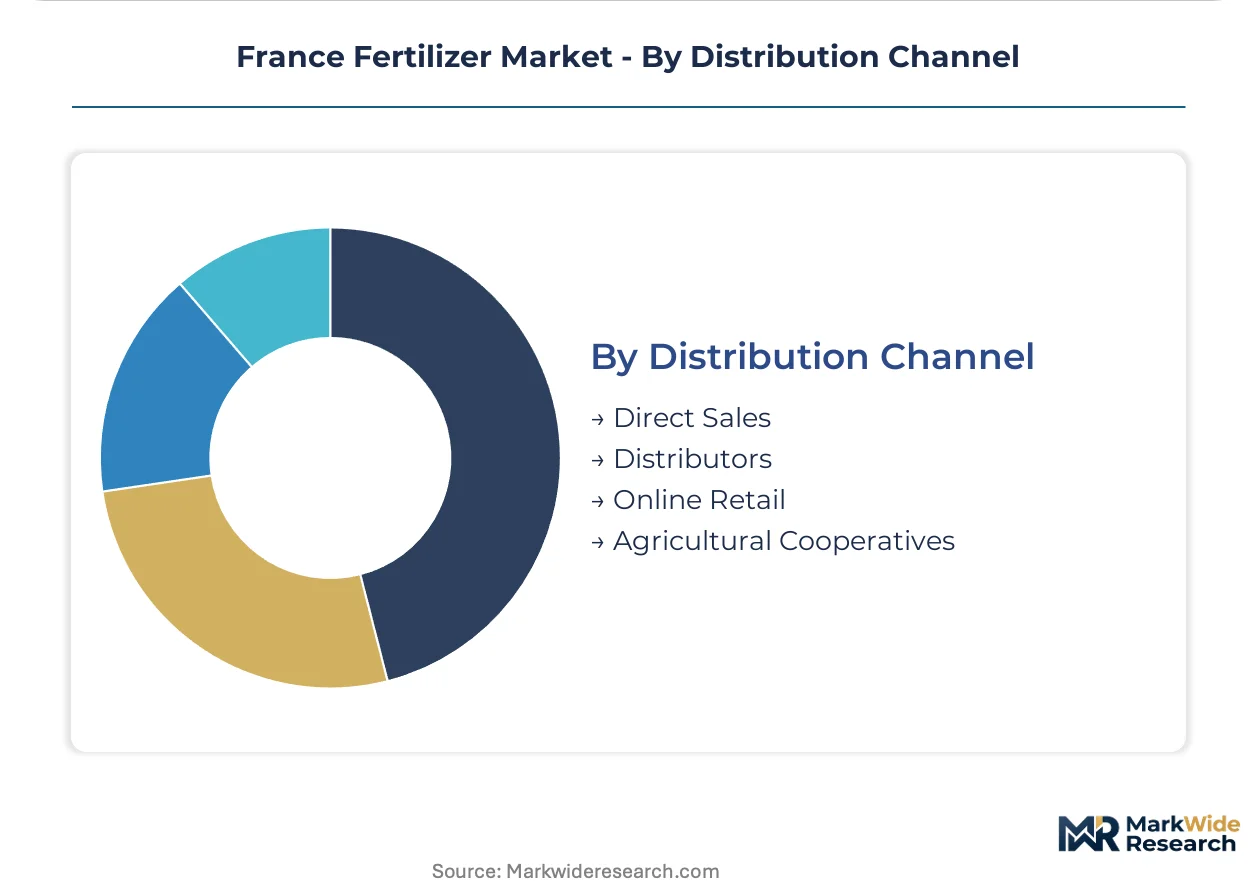
Customer type concentration is rewiring channel economics as agricultural cooperatives consolidate procurement power and disintermediate traditional distributor networks.
- Agricultural Cooperatives:Member-owned purchasing groups aggregating volume for formula customization and direct manufacturer negotiation. Southwestern France's maize cooperatives exemplify this consolidation.
- Distributors:Independent or manufacturer-aligned wholesale networks maintaining regional inventory and technical service capabilities. These intermediaries face margin compression from cooperative and direct channel expansion.
- Direct Sales:Manufacturer-to-grower contracts for large-scale operations or specialty formulation development. Champagne-Ardenne vineyard estates increasingly source controlled-release products through this channel.
- Online Retail:Digital platforms serving smallholder and hobby farmer segments with packaged fertilizer products. Urban periphery horticulturalists drive this channel's expansion.
Agricultural cooperatives hold the largest share; online retail expands most quickly at the segment's fringe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France exports nitrogen and compound fertilizers to neighboring EU agricultural markets, with Belgium, Germany, and Spain absorbing the majority of cross-border volume. Trade flows concentrate through northern port infrastructure and Rhine corridor distribution networks.
Île-de-France
Paris Basin cereal cooperatives aggregate procurement for wheat and barley production at scale. The EU Green Deal's nutrient reduction targets force cooperative purchasing groups toward certified low-leaching formulations. Precision agriculture service providers in the Beauce region displace traditional distributor networks through direct manufacturer contracts.
Hauts-de-France
Coastal import infrastructure at Dunkirk and Le Havre anchors ammonia supply chains for nitrogen fertilizer manufacturing. The F-Gas Regulation shapes greenhouse gas accounting for regional production facilities. Lille-based blending operations serve northern cereal belt demand through mechanized granular distribution networks.
Grand Est
Champagne-Ardenne vineyard estates drive controlled-release fertilizer adoption for residue-free certification compliance. France's Ecophyto plan mandates leaching reduction targets across the Marne Valley catchment area. Reims-based technical service providers specialize in precision nutrient mapping for high-value horticultural segments.
Centre-Val de Loire
Loire Valley specialty crop operators expand organic and biodynamic certification programs. ANSM oversees fertilizer product safety assessments for regional vineyard input suppliers. Tours-based cooperatives blend micronutrient formulations for premium wine production zones.
Nouvelle-Aquitaine
Southwestern maize regions adopt liquid fertilizer formulations compatible with precision spraying equipment. The EU's Carbon Border Adjustment Mechanism creates competitive pressure for low-carbon ammonia sourcing. Bordeaux-area agricultural cooperatives consolidate procurement power through volume-scale direct manufacturer negotiations.
France Fertilizer Market Competitive Landscape
Listed leaders compete with private specialists across capital access and portfolio flexibility dimensions. The vendor base clusters around three structural tiers: coastal import-dependent ammonia producers, Brittany-based micronutrient research campuses, and phosphate-origin-flexible blenders sourcing across multiple mining jurisdictions. Strategic archetypes include integrated nitrogen manufacturers, specialty formulation developers, and cooperative-aligned distributors. Capacity expansion and portfolio diversification toward controlled-release products represent the dominant competitive moves reshaping positioning.
Within the coastal infrastructure tier, Yara France SAS and EuroChem Agro France exemplify import-dependent ammonia supply strategies. Groupe Roullier occupies a position among research-anchored specialty formulators. These three entities represent distinct competitive archetypes: nitrogen manufacturing scale, phosphate sourcing flexibility, and premium micronutrient development capability.
| Leading Market Players |
|---|
| PLANTIN |
| SOCACO International Biopost |
| Yara France SAS |
| ICL France |
| OCI Nitrogen |
| Groupe Roullier |
| GERMIFLOR – LAUTIER |
| EuroChem Agro France |
| Fertiberia Sarl |
| Others |
Pricing and Supply Chain Analysis
Coastal ammonia import capacity at Dunkirk and Le Havre anchors nitrogen fertilizer manufacturing economics across northern France, concentrating production scale among port-adjacent operators while inland blenders absorb higher delivered cost bases. This infrastructure asymmetry stratifies pricing power between coastal integrated producers and regional compounders dependent on trucked ammonia deliveries from Rotterdam or Wilhelmshaven.
Pricing Analysis
Current-generation controlled-release polymer coatings command 40-60% premiums over conventional urea prills, while legacy commodity nitrogen faces persistent margin compression from natural gas benchmark volatility. Three-tier pricing structure across premium specialty, certified standard, and bulk economy levels reflects Ecophyto compliance grading rather than pure chemistry differentiation. Pricing pressure stems from Moroccan phosphate rock contract renegotiations and renewable hydrogen ammonia certification premiums. Agricultural cooperatives in the Paris Basin exhibit acute price sensitivity on commodity nitrogen, whereas Champagne-Ardenne vineyard estates prioritize residue-free certification over unit cost.
Supply Chain Analysis
Morocco, Russia, and Saudi Arabia dominate upstream phosphate rock extraction, while Trinidad and Tobago, Qatar, and Algeria anchor ammonia feedstock liquefaction for European import. French blenders draw from this dual-hemisphere sourcing matrix, with nitrogen resting on coastal terminal throughput and phosphate tethered to long-haul bulk shipping contracts. Single-source vulnerability concentrates in Moroccan phosphate rock offtake agreements, where OCP Group contractual terms set regional benchmark pricing. Distribution runs through agricultural cooperative storage silos in the Paris Basin, bypassing traditional distributor markups through direct manufacturer negotiation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France fertilizer market is recovering from cyclical trough conditions as natural gas benchmark normalization and Ecophyto compliance deadlines restock cooperative purchasing pipelines. This recovery is underpinned by mandatory nutrient reduction targets forcing product portfolio refresh cycles.
For Market Incumbents: Compound defensive positioning through backward integration into renewable hydrogen ammonia sourcing to secure CBAM-advantaged supply chains, while accelerating controlled-release formulation R&D at Brittany research campuses to outpace cooperative technical service buildout. The threat of direct manufacturer-cooperative disintermediation demands channel control investments in precision agriculture digital platforms. For New Entrants and Emerging Players: Anchor in Loire Valley biodynamic certification demand as the most penetrable white-space segment, where residue-free input supply chains remain fragmented among small organic blenders. Target vineyard estate direct sales channels with micronutrient customization capabilities, leveraging ANSM product safety assessment navigation as a go-to-market differentiator against commodity distributors lacking regulatory affairs depth. For Investors and Strategic Acquirers: Research-anchored specialty formulators with captive micronutrient IP represent the highest-conviction acquisition archetype for long-term viability across the EU Green Deal implementation window. Monitor low-carbon ammonia certification scheme adoption rates as the critical inflection signal for competitive positioning resets among nitrogen manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Hydrogen | Secures CBAM-compliant ammonia supply for coastal nitrogen manufacturing at Dunkirk. |
| Controlled-Release Polymer R&D Expansion | Captures Ecophyto-mandated vineyard demand in Champagne-Ardenne and Loire Valley. |
| Direct Cooperative Contracting | Disintermediates distributor networks in southwestern France maize procurement zones. |
| Biodynamic Certification Input Development | Addresses residue-free premium positioning in Burgundy and Alsace wine production. |
| Precision Agriculture Platform Partnership | Integrates fertilizer dosing with vineyard nutrient mapping services in Grand Est. |
Research Methodology
Initial hypotheses were tested against primary input from fertilizer plant managers, agricultural cooperative procurement leads, vineyard technical directors, and ANSM regulatory affairs specialists and refined through secondary validation against customs trade data, Fertilizers Europe industry reports, EU Green Deal policy documentation, and ECHA REACH registration databases. Bottom-up volume modeling triangulated with top-down macroeconomic scenario analysis anchored forecast outputs.
Variance decomposition across product type, application segment, physical form, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and price elasticity assumptions, with nitrogen fertilizer demand elasticity to wheat futures and phosphate rock contract lag structures serving as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal implementation and natural gas price stabilization; material deviation in Moroccan phosphate export policy or renewable hydrogen cost curves would warrant model refresh. Recalibration cycles align with material shifts in Ecophyto mandate enforcement timelines and CBAM carbon border adjustment phase-in schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Brazil Micronutrient Fertilizer Market
Fertilizers
North America Specialty Fertilizer Market
Fertilizers
EMEA Secondary Macronutrients Market
Fertilizers
Africa Potash Fertilizer Market
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market
Fertilizers
South America Fertilizers Market
Fertilizers
Russia Micronutrient Fertilizer Market
Fertilizers
Global Potash Fertilizer Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
Sulfur Fertilizer Market
Fertilizers
United States Micronutrient Fertilizer Market
Fertilizers
Fertilizer Additives Market
Fertilizers
Mineral Fertilizers Market
Fertilizers
Global Liquid Fertilizer Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Global Micronutrient Fertilizer Market