
 Global Green Fertilizers Market | 2026-2036
Global Green Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Green Fertilizers Market Analysis
Specialty crop producers and carbon-conscious grain traders are bifurcating demand away from commodity urea buyers. Yara International ASA leverages its Norwegian renewable ammonia pilot to anchor European supply chains for certified low-carbon products. CF Industries Holdings, Inc. competes through Gulf Coast electrolyzer partnerships that sustain cost parity targets for green ammonia exports. Nutrien Ltd. dominates North American distribution infrastructure, positioning its retail network to capture premium-tier agronomy contracts.
Green fertilizers comprise nitrogen, phosphorus, and potassium compounds manufactured with renewable energy-derived hydrogen or biomass-captured nutrients, achieving carbon footprints below 0.5 kg CO2 equivalent per kilogram of ammonia. Their primary purpose is to maintain crop yield parity while satisfying Scope 3 emissions accounting for food processors and export-oriented farms. Granular formulations command the largest volume share due to compatibility with existing spreader equipment, though liquid products attract greenhouse and precision-farming operators seeking fertigation integration. Agricultural cooperatives represent the fastest-growing distribution channel as member-owned buying groups aggregate carbon-credit eligible purchases.
The EU Green Deal and REACH frameworks mandate emissions disclosures for imported fertilizers, reshaping product standards and market access for non-European suppliers. The EPA and USDA jointly influence US adoption through biofuel crop incentives that reward low-carbon input verification. Stakeholders must monitor hydrogen subsidy regimes and certification body alignment across the EU, North America, and India to secure offtake contracts.
Market Dynamics
Renewable hydrogen feedstock conversion is restructuring ammonia production economics, forcing incumbent nitrogen manufacturers to choose between asset retrofitting and market exit as carbon border adjustments reshape trade flows.
Growth Catalysts
- EU Green Deal carbon border mechanism:Import tariffs on high-carbon fertilizers are redirecting procurement toward certified low-carbon suppliers, accelerating facility conversions in Germany and the Netherlands.
- Biomethane-powered Haber-Bosch units:Agricultural cooperatives in Denmark and France are aggregating demand for bio-based ammonia, creating offtake certainty for pilot-scale producers.
- Scope 3 emissions accounting:Food processors and grain traders are mandating verified low-carbon inputs, pulling specialty crop producers toward green nitrogen procurement contracts.
Market Restraints
- Electrolyzer capital intensity:Proton exchange membrane electrolysis systems require sustained green hydrogen subsidies to achieve cost parity with steam methane reforming.
- Nordic supply concentration:Renewable ammonia pilot capacity clusters in Norway and Iceland, creating geographic single-point vulnerability for European offtake security.
- Grid electricity price volatility:German and Spanish industrial power tariffs fluctuate with renewable intermittency, compressing green ammonia margin predictability.
Strategic Opportunities
- Indian PLI scheme for electrolyzer manufacturing:Domestic production incentives could localize green hydrogen equipment supply, reducing import dependency for ammonia producers.
- Precision fertigation systems:Greenhouse operators in the Netherlands and Belgium are integrating liquid green ammonia into closed-loop irrigation, opening premium pricing tiers.
- US IRA hydrogen production tax credits:Gulf Coast ammonia exporters can capture subsidy stacking across production and carbon capture, improving export competitiveness.
Industry Challenges
- Renewable hydrogen certification lag:Misalignment between TÜV, ISCC, and CertifHy standards creates duplicate auditing burdens for cross-border shipments.
- Ammonia cracking infrastructure gaps:Downstream conversion facilities for maritime fuel applications remain underdeveloped, limiting offtake diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Green Fertilizers Market |
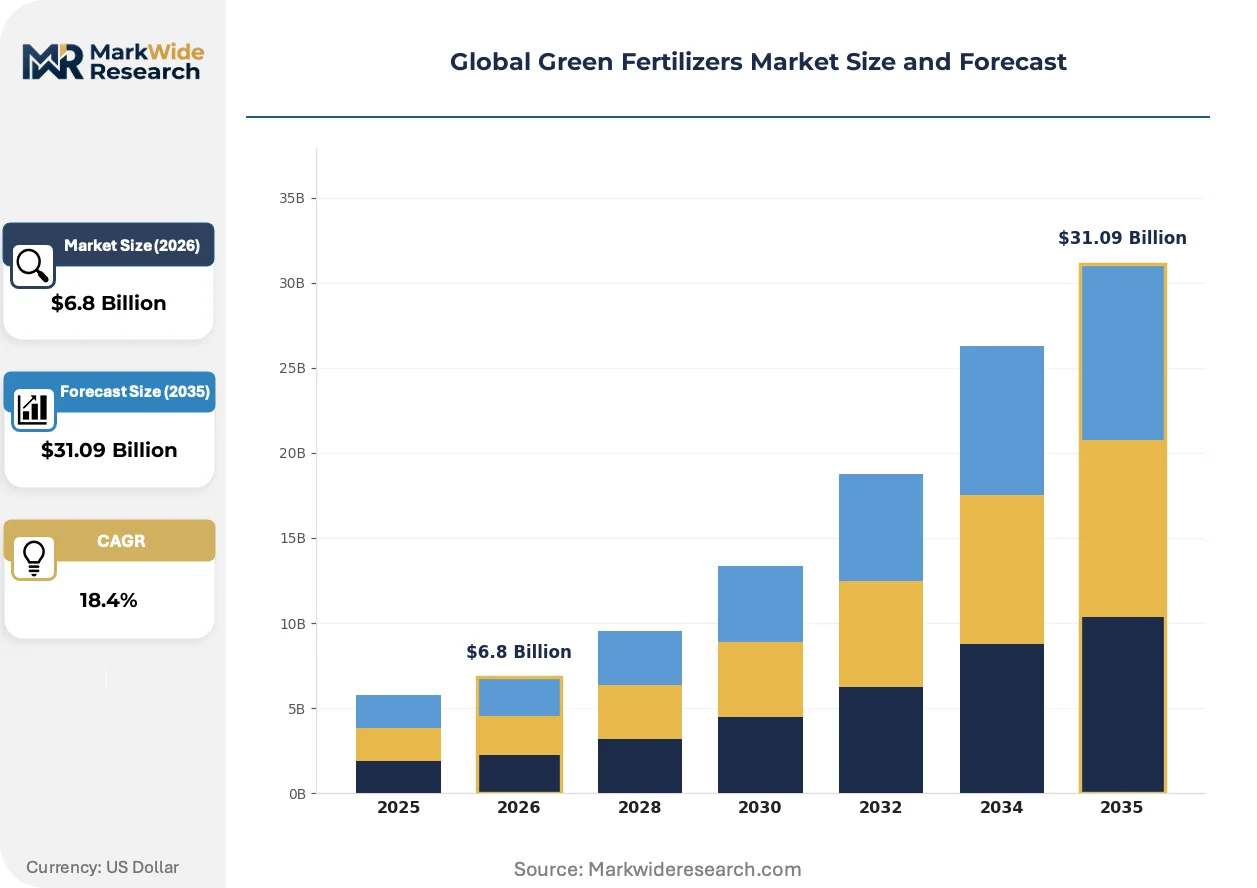
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Fertilizers, Biofertilizers, Natural Amendments, Mineral-based Fertilizers Application: Agricultural Fields, Horticulture, Landscaping, Gardening Form: Granular, Liquid, Powder, Pelletized Distribution Channel: Online Sales, Retail Stores, Agricultural Cooperatives, Direct Sales |
| Companies Covered | Yara International ASA, CF Industries Holdings, Inc., Nutrien Ltd., OCI Global, BASF SE, Fertiberia S.A., Tata Chemicals Ltd., Siemens Energy AG, Nel Hydrogen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Green Fertilizers Market Emerging Trajectories
Electrification of ammonia synthesis is disrupting century-old production paradigms, while digital traceability systems and novel distribution partnerships are reconfiguring how low-carbon nitrogen reaches farm gate.
Solid oxide electrolysis technology is fragmenting the dominant alkaline electrolysis pathway for green hydrogen production. Dutch and German engineering firms are deploying modular SOE units adjacent to existing ammonia plants, enabling phased retrofitting without full facility shutdowns. This technology is fragmenting capital deployment timelines, allowing producers to scale hydrogen capacity incrementally rather than committing to billion-euro greenfield investments.
REACH framework amendments are mandating full lifecycle carbon disclosure for fertilizer imports into European Economic Area markets. The regulation forces non-European suppliers to secure third-party verification or face market exclusion, compressing compliance timelines for North African and Middle Eastern exporters. Specialty crop distributors in Germany are responding by pre-qualifying suppliers against ISCC PLUS certification standards.
Carbon-credit stacking is altering contract structures between agricultural cooperatives and green ammonia producers. Danish and Swedish buying groups now negotiate bundled agreements covering verified emissions reductions plus renewable energy certificates, displacing simple commodity purchasing. This behavioral shift concentrates procurement authority within larger cooperative entities, marginalizing smaller independent distributors.
Global Green Fertilizers Market Segmentation
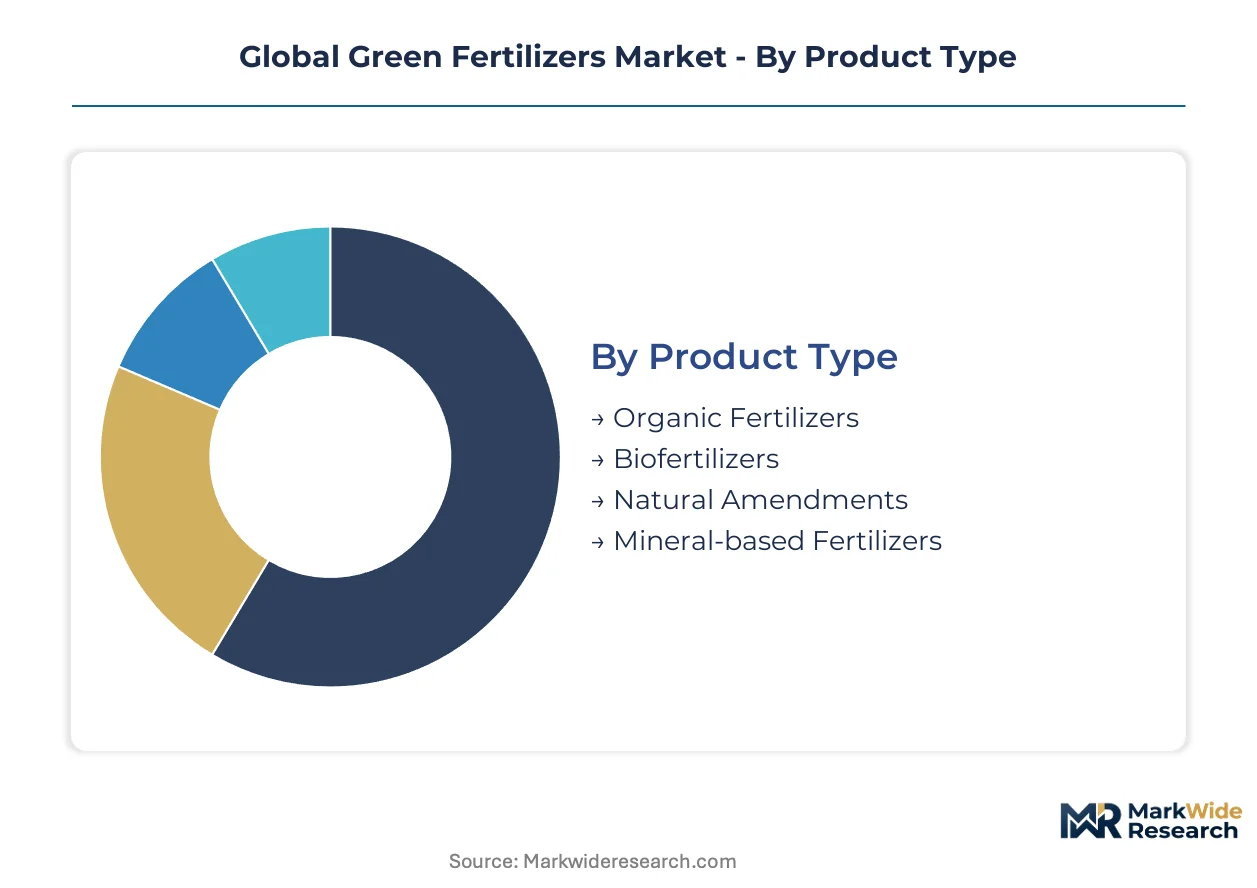
Segmentation in green fertilizers reveals how carbon accounting rules and application-specific performance requirements fragment procurement decisions. Buyers prioritize different attributes—certification grade for export-oriented grain operations, solubility rates for precision fertigation, or cooperative pricing for member-owned farms—creating distinct margin architectures across each dimension.
Product Type:
Margin pools concentrate in nitrogen compounds where renewable hydrogen feedstock conversion commands certification premiums, while phosphorus and potassium segments compete on biomass sourcing traceability.
- Organic Fertilizers:Composted plant and animal matter formulations deliver slow-release nitrogen with verified carbon sequestration co-benefits. Specialty crop producers in Germany and the Netherlands specify these for EU Green Deal compliance, though batch-to-batch nutrient variability constrains broadacre adoption.
- Biofertilizers:Microbial inoculants fix atmospheric nitrogen or solubilize soil phosphorus without fossil-derived chemical synthesis. Demand clusters in India where the PLI scheme for electrolyzer manufacturing indirectly supports ancillary green input industries, and where smallholder rice cultivation favors low-capital biological alternatives.
- Natural Amendments:Rock phosphate, green sand, and other mined materials processed without chemical alteration.
- Mineral-based Fertilizers:Synthetic NPK compounds manufactured with renewable hydrogen or biomass-captured nutrients achieving sub-0.5 kg CO2e per kilogram ammonia.
The dominant share belongs to Mineral-based Fertilizers, while Biofertilizers is closing the gap fastest.
Application:
Application-driven segmentation tracks how carbon disclosure requirements penetrate differently across cultivation scales and crop value tiers.
- Agricultural Fields:Broadacre grain and oilseed operations purchase certified low-carbon nitrogen to satisfy Scope 3 emissions accounting for food processors and export-oriented traders. Danish and Swedish agricultural cooperatives aggregate member demand into multi-year offtake contracts, displacing commodity urea procurement.
- Horticulture:High-value fruit and vegetable cultivation requires precise nutrient delivery with residue-sensitive chemistry. Greenhouse operators in Belgium and the Netherlands integrate liquid green ammonia into closed-loop irrigation systems, opening premium pricing tiers unavailable to open-field applications.
- Landscaping:Turf management and ornamental plantings with sustainability mandates from municipal procurement.
- Gardening:Consumer retail packaging emphasizing organic certification and local sourcing claims.
Agricultural Fields command volume leadership, though Horticulture generates the steepest margin expansion trajectory.
Form:
Physical formulation determines equipment compatibility and precision agriculture integration depth.
- Granular:Spreader-compatible prills and granules dominate existing mechanized application infrastructure. German ammonia producers retrofit Haber-Bosch units for renewable hydrogen while maintaining granular output specifications, preserving downstream equipment investments across the farm base.
- Liquid:Ammonia solutions and suspensions enable fertigation integration and variable-rate application. Precision farming operators in Spain and Italy specify liquid green ammonia for drip irrigation systems where nutrient placement accuracy directly correlates with yield optimization.
- Powder:Fine-ground materials for specialized soil amendment and hydroponic applications.
- Pelletized:Compressed formulations for controlled-release and reduced dust handling.
Granular formulations retain the dominant share, while Liquid is gaining share fastest.
Distribution Channel:
Channel structure reflects consolidation pressures from carbon-credit aggregation and digital traceability requirements.
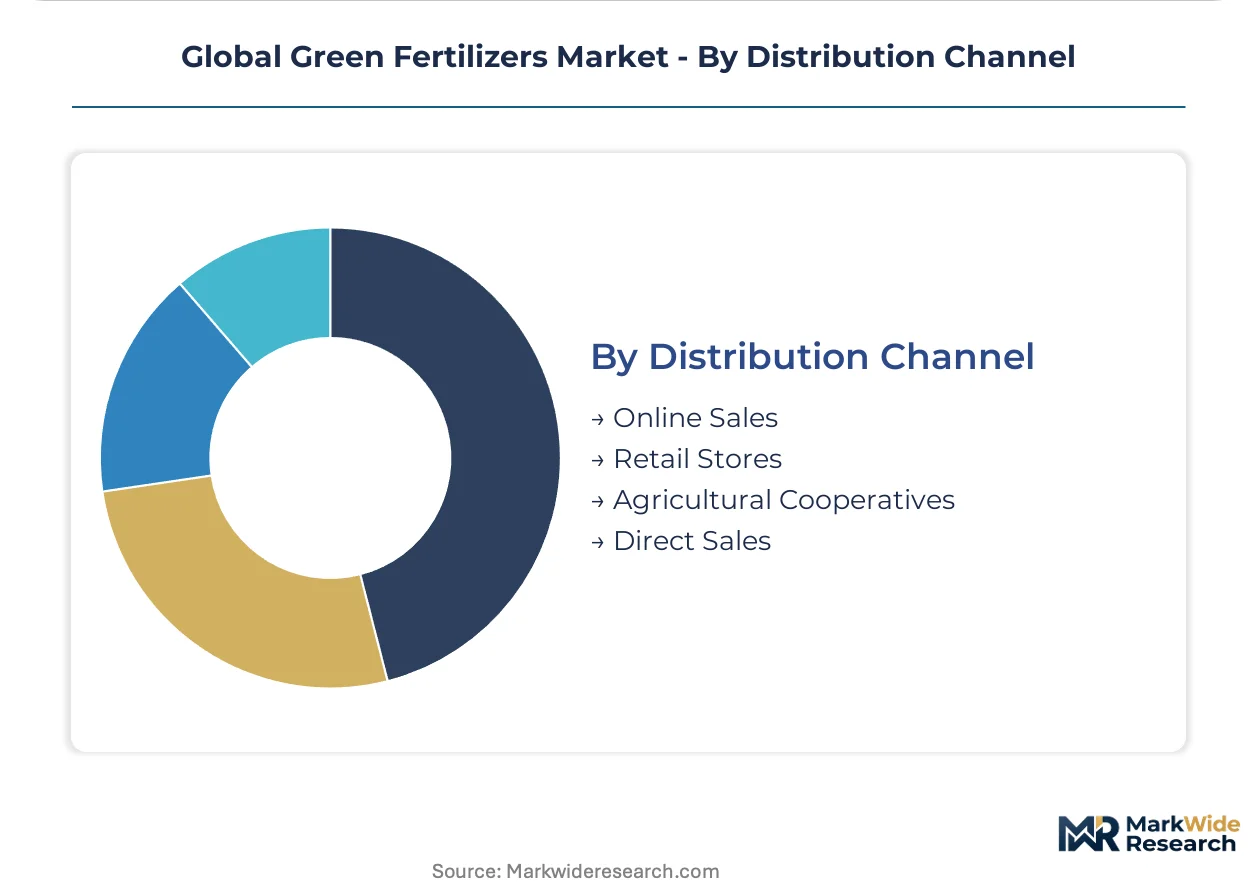
- Agricultural Cooperatives:Member-owned buying groups aggregate carbon-credit eligible purchases and negotiate bundled agreements covering verified emissions reductions plus renewable energy certificates. Danish and Swedish cooperatives now displace independent distributors through concentrated procurement authority.
- Direct Sales:Producer-to-farm contracts for large-scale certified low-carbon offtake. Yara International ASA anchors European supply chains through Norwegian renewable ammonia pilot output delivered directly to cooperative processing facilities.
- Online Sales:Digital platforms with batch-level carbon footprint documentation for specialty crop producers.
- Retail Stores:Branded packaged goods for gardening and small-scale horticulture segments.
The dominant share belongs to Agricultural Cooperatives, while Direct Sales is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam ammonia terminal and connected hydrogen pipeline network underwrites Northwest Europe's role as the primary demand aggregation point for certified low-carbon nitrogen products.
Germany
Industrial power tariffs and carbon border adjustment mechanisms pull specialty crop producers toward verified low-carbon procurement contracts. The EU Green Deal mandates emissions disclosures for imported agricultural inputs, compressing compliance timelines for conventional suppliers. The Ruhr industrial corridor hosts retrofitted Haber-Bosch facilities converting to renewable hydrogen feedstock.
United States
Gulf Coast electrolyzer partnerships and IRA hydrogen production tax credits sustain cost parity targets for green ammonia export capacity. The EPA and USDA jointly influence adoption through biofuel crop incentives rewarding low-carbon input verification. Texas and Louisiana industrial clusters anchor carbon capture and hydrogen hub development for nitrogen manufacturing.
India
The PLI scheme for electrolyzer manufacturing localizes green hydrogen equipment supply, reducing import dependency for ammonia producers. Smallholder rice cultivation favors biofertilizer alternatives where capital constraints limit synthetic nitrogen adoption. Gujarat and Maharashtra host pilot-scale renewable ammonia projects targeting domestic fertilizer security.
Netherlands
Greenhouse operators integrate liquid green ammonia into closed-loop irrigation systems, opening premium pricing tiers unavailable to open-field applications. REACH framework amendments mandate full lifecycle carbon disclosure for fertilizer imports into European Economic Area markets. The Port of Rotterdam serves as the primary entry point for certified low-carbon nitrogen products.
Norway
Abundant hydropower resources enable renewable ammonia pilot production at cost structures competitive with fossil-derived alternatives. Nordic supply concentration creates geographic single-point vulnerability for European offtake security. The Herøya industrial park clusters electrolyzer and ammonia synthesis capacity for export-oriented production.
Global Green Fertilizers Market Vendor Landscape
Concentration sits with integrated nitrogen manufacturers possessing captive renewable hydrogen supply or secured offtake partnerships. The vendor base spans three tiers: multinational chemical conglomerates with global distribution infrastructure, regional ammonia specialists retrofitting existing assets, and electrolyzer technology providers licensing equipment packages. Strategic moves center on facility retrofitting commitments and certification body alignment to secure multi-year cooperative procurement contracts.
Within the integrated nitrogen tier, Yara International ASA and CF Industries Holdings, Inc. exemplify divergent geographic anchoring strategies for renewable ammonia supply. Nutrien Ltd. occupies a position bridging North American distribution scale with retail network proximity to carbon-conscious grain operations. These three entities represent the archetype of incumbent nitrogen manufacturers navigating feedstock transition economics.
| Leading Market Players |
|---|
| Yara International ASA |
| CF Industries Holdings, Inc. |
| Nutrien Ltd. |
| OCI Global |
| BASF SE |
| Fertiberia S.A. |
| Tata Chemicals Ltd. |
| Siemens Energy AG |
| Nel Hydrogen |
| Others |
Supply Flow & Price Mechanics
Ninety-day ammonia inventory buffers at Rotterdam terminals concentrate pricing power among Northwest European terminal operators while compressing margin visibility for importers facing EU Green Deal carbon border adjustments. This lead-time structure forces non-European suppliers to absorb certification costs or surrender market access, amplifying the leverage of domestic retrofitted producers in Germany and the Netherlands.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between agricultural cooperatives and certified producers, with price differentiation driven by ISCC PLUS certification grade and volume scale. Premium tiers command substantial markups for verified sub-0.5 kg CO2e ammonia, while economy-grade biofertilizers face price erosion from Indian PLI scheme cost compression. Specialty crop producers in Denmark exhibit lowest price sensitivity due to Scope 3 compliance mandates, whereas smallholder rice operators in India prioritize capital minimization over certification premiums.
Supply Chain Analysis
Strategic stockpile preferences among German agricultural cooperatives contrast with just-in-time liquid ammonia delivery systems adopted by Dutch greenhouse operators. Supply concentrates in Norway, Iceland, and Germany for renewable hydrogen feedstock, with raw material dependencies on electrolyzer stacks, renewable power purchase agreements, and biomethane supply contracts. Single-source vulnerability from Nordic pilot capacity clusters threatens European offtake security. Distribution runs through agricultural cooperatives aggregating carbon-credit eligible purchases, displacing independent distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating within agricultural cooperatives as Danish and Swedish member-owned groups displace fragmented independent distributors through multi-year bundled procurement contracts.
For Market Incumbents: Consolidate electrolyzer partnerships along the Gulf Coast to secure IRA hydrogen production tax credit stacking and defend against emerging modular SOE technology providers. Retrofit existing Haber-Bosch assets in the Ruhr corridor before carbon border adjustments harden, anchoring captive renewable hydrogen supply through Norwegian hydropower offtake agreements. For New Entrants and Emerging Players: ISCC PLUS certification fast-track through German specialty crop distributors offers the most penetrable entry vector, bypassing entrenched cooperative procurement blocks. Liquid green ammonia for precision fertigation in Belgian and Dutch greenhouse operations presents white-space demand with premium pricing tolerance absent from commodity grain markets. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded conventional ammonia assets requiring feedstock transition capital. Five-to-ten year viability hinges on hydrogen subsidy regime durability rather than technology cost curves alone. Watch for TÜV-CertifHy standard alignment as the inflection signal triggering cross-border shipment scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Partnership Formation | CF Industries' Gulf Coast alliances anchor cost parity for green ammonia exports against Norwegian hydropower competitors. |
| Haber-Bosch Facility Retrofitting | German producers in the Ruhr corridor preserve downstream equipment investments while converting to renewable hydrogen feedstock. |
| ISCC PLUS Certification Investment | Pre-qualification against REACH framework amendments secures market access for non-European suppliers facing carbon disclosure mandates. |
| Agricultural Cooperative Integration | Yara International's direct delivery to Danish processing facilities concentrates procurement authority within member-owned buying groups. |
| Biomethane Supply Contracting | French and Danish cooperatives aggregate demand for bio-based ammonia, creating offtake certainty for pilot-scale producers. |
Methodological Framework
A spread of perspectives from ammonia plant engineers, agricultural cooperative procurement directors, electrolyzer technology providers, and regulatory affairs specialists at certification bodies converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against EU ETS transaction databases, SEC 10-K filings from nitrogen manufacturers, REACH framework amendment texts, and Indian PLI scheme implementation circulars. Bottom-up capacity buildout schedules triangulated against top-down carbon border adjustment revenue projections.
Segmentation dimensions modeled span product type, application, physical form, and distribution channel across the projection horizon. CAGRs derived from electrolyzer cost curve trajectories, renewable power tariff forecasts, and agricultural commodity price elasticity assumptions. Industry-specific inputs include hydrogen subsidy regime durability assessments and certification body alignment timelines between TÜV, ISCC, and CertifHy standards.
Decision-makers should treat outputs as directional under sustained EU Green Deal implementation and IRA hydrogen credit extension; material deviation would warrant model refresh. Forecasts reflect assumptions around carbon border adjustment enforcement intensity and Nordic renewable ammonia capacity scaling. Revision becomes warranted when biomethane supply constraints or grid electricity price volatility cross thresholds disrupting green ammonia margin predictability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Crop Micronutrients Market
Fertilizers
North America Micronutrient Fertilizers Market
Fertilizers
North America Specialty Fertilizer Market
Fertilizers
Urea Fertilizers Market
Fertilizers
South America Specialty Fertilizer Market
Fertilizers
North America Fertilizers Market
Fertilizers
North America Liquid Fertilizers Market
Fertilizers
Indonesia Fertilizer Market
Fertilizers
Vietnam Biofertilizer Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
Potash Market
Fertilizers
Global Urea Market
Fertilizers
Potassium Thiosulfate Fertilizer Market
Fertilizers
Middle East and Africa Micronutrient Fertilizer Market
Fertilizers
Africa Potash Fertilizer Market
Fertilizers
Fertilizer Tester Market