
 Asia-Pacific Organic Fertilizer Market | 2026-2036
Asia-Pacific Organic Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Organic Fertilizer Market Insights
India's Gujarat corridor is rewriting capacity dynamics for organic fertilizer supply across South Asia. Coromandel International Ltd leverages its coastal manufacturing footprint to dominate compost and manure blending for agricultural cooperatives. Gujarat Narmada Valley Fertilizers & Chemicals Ltd anchors granular production through backward integration into captive biogas digesters. Kiwa Biotech specializes in microbial inoculant formulations that differentiate liquid fertilizer portfolios for nursery end users.
Asia-Pacific organic fertilizer comprises plant or animal-derived matter processed through aerobic composting, anaerobic digestion, or enzymatic fermentation to deliver nitrogen, phosphorus, and potassium with soil-conditioning organic carbon. These inputs restore microbial biomass and cation exchange capacity in intensively cultivated tropical and subtropical soils. Compost leads product type revenue due to established municipal waste-to-fertilizer infrastructure across Indian and Chinese processing clusters. Liquid form captures the fastest growth trajectory as drip irrigation penetration rises in Australian horticulture and Vietnamese horticulture belts. Agricultural fields remain the dominant application channel, though organic farming certification programs are shifting margin pools toward verified supply chains serving export-oriented cooperatives.
India's FSSAI organic food standards, China's GB standards for organic-inorganic compound fertilizers, and Australia's TGA-equivalent agricultural chemical registration frameworks collectively tighten contaminant thresholds and traceability requirements. Compliance costs favor scaled manufacturers with in-house laboratory certification over informal compost producers. Stakeholders must monitor regulatory divergence between ASEAN harmonization talks and national bio-inputs registries to anticipate cross-border formulation approval timelines.
Market Dynamics
FSSAI organic certification mandates in India and China's MIIT bio-manufacturing directives are compressing informal compost channels while accelerating capital deployment into laboratory-verified production infrastructure across the Indo-Gangetic Plain and Yangtze Delta processing clusters.
Growth Catalysts
- FSSAI Organic Food Standards:India's mandatory certification for organic food exports is pulling wheat-rice systems toward verified compost and manure protocols, eliminating unregistered suppliers from cooperative procurement pools.
- Drip Irrigation Expansion:Australian horticulture and Vietnamese fruit belts are absorbing liquid microbial inoculants at accelerating rates as precision fertigation hardware penetrates smallholder cooperatives.
- MIIT Fermentation Directives:China's industrial policy is channeling upgrade capital into anaerobic digester retrofits, tightening effluent standards while expanding biogas-to-fertilizer output capacity.
Market Restraints
- Municipal Feedstock Volatility:Compost manufacturers depend on segregated organic waste streams that remain inconsistent across Indian and Chinese municipal collection systems, forcing buffer stockpiling.
- Laboratory Certification Costs:FSSAI and GB standards compliance requires in-house heavy metal and pathogen testing infrastructure that informal producers cannot finance, concentrating supply among scaled operators.
- Synthetic-Organic Price Gaps:Urea and DAP subsidies in India and China maintain artificial price floors that compress organic fertilizer margins in price-sensitive staple crop segments.
Strategic Opportunities
- Myanmar and Cambodia Underpenetration:These Mekong Basin markets lack domestic certification infrastructure, creating first-mover openings for Indian and Vietnamese exporters with FSSAI-equivalent laboratory protocols.
- Export Cooperative Channel Development:Direct contracting between compost manufacturers and EU-bound organic rice cooperatives is bypassing traditional agrochemical distributor markups.
- Biogas Digestate Integration:Convergence of anaerobic digestion for renewable energy and organic fertilizer production is enabling circular economy positioning for industrial livestock operations.
Industry Challenges
- Microbiologist Talent Scarcity:Formulation of stable microbial inoculants requires specialized fermentation expertise that remains concentrated in Chinese and Korean research institutes.
- Legacy Soil Testing Integration:Organic carbon and cation exchange capacity protocols do not align with existing NPK-focused extension services, forcing parallel farmer education investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Organic Fertilizer Market |
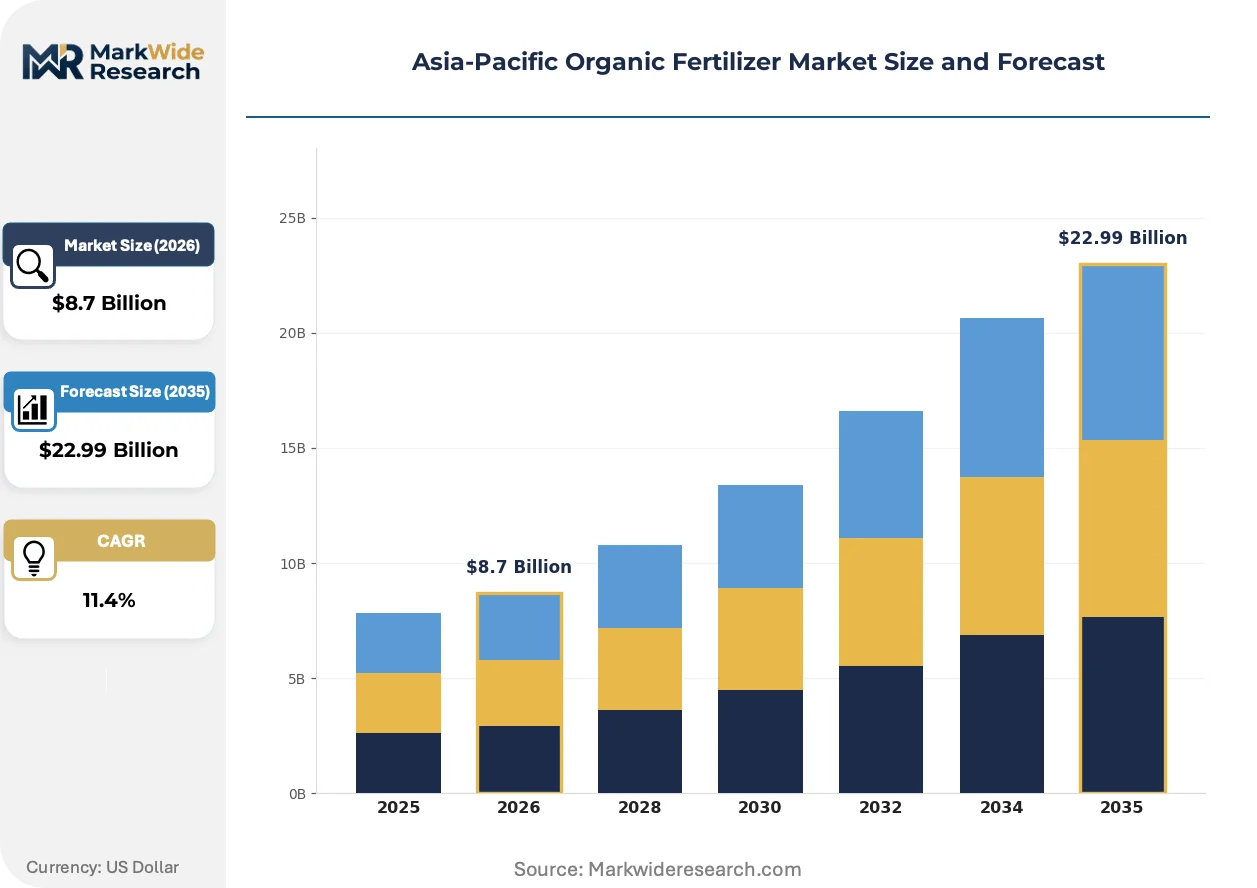
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compost, Manure, Seaweed Extract, Bone Meal Application: Agricultural Fields, Horticulture, Landscaping, Organic Farming Form: Granular, Liquid, Powder, Pelleted End User: Farmers, Nurseries, Agricultural Cooperatives, Garden Centers |
| Companies Covered | Coromandel International Ltd, Genliduo Bio-tech Corporation Ltd, Gujarat Narmada Valley Fertilizers & Chemicals Ltd, Gujarat State Fertilizers & Chemicals Ltd, Swaroop Agrochemical Industries, Shandong Nongda Fertilizer Sci & Tech Co Ltd, National Fertilizers Limited, Tata Chemicals Ltd, Kiwa Biotech, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Organic Fertilizer Market Trends and Innovations
Digital soil microbiome mapping and blockchain traceability layers are overlaying physical fertilizer production with data services that recast competitive advantage around verification speed rather than commodity tonnage.
Enzymatic fermentation of agricultural residues is virtualizing traditional composting timelines, compressing six-month aerobic cycles into fourteen-day batch processes. Vietnamese and Thai cassava processors are adopting these systems to manage starch waste liabilities. The technology is virtualizing capital efficiency benchmarks for mid-scale organic fertilizer entrants previously locked out by land-intensive windrow operations.
China's GB standards for organic-inorganic compound fertilizers are tightening contaminant thresholds for heavy metals and plastic residues, forcing municipal waste-to-fertilizer plants to install secondary sorting and washing lines. The regulation most acutely affects compost producers serving peri-urban vegetable belts around Shanghai and Guangzhou, where processors are retrofitting eddy current separators and hydrocyclone washing stages.
Certification-driven procurement consolidation is concentrating buyer power among export-oriented organic cooperatives that demand batch-level laboratory documentation. Traditional village-level compost aggregators are losing position to integrated manufacturers with captive laboratory capacity. This pattern is most visible in India's Maharashtra and Karnataka grape and pomegranate belts, where European supermarket chain compliance requirements filter down to input specifications.
Asia-Pacific Organic Fertilizer Market Segmentation
Segmentation in organic fertilizers separates commodity compost from premium microbial inoculants, each commanding distinct margin structures and certification requirements. Manufacturers align production infrastructure to specific segment velocity—slow-turn compost versus fast-cycle liquid formulations—to optimize capital deployment across the Asia-Pacific processing corridor.
Product Type:
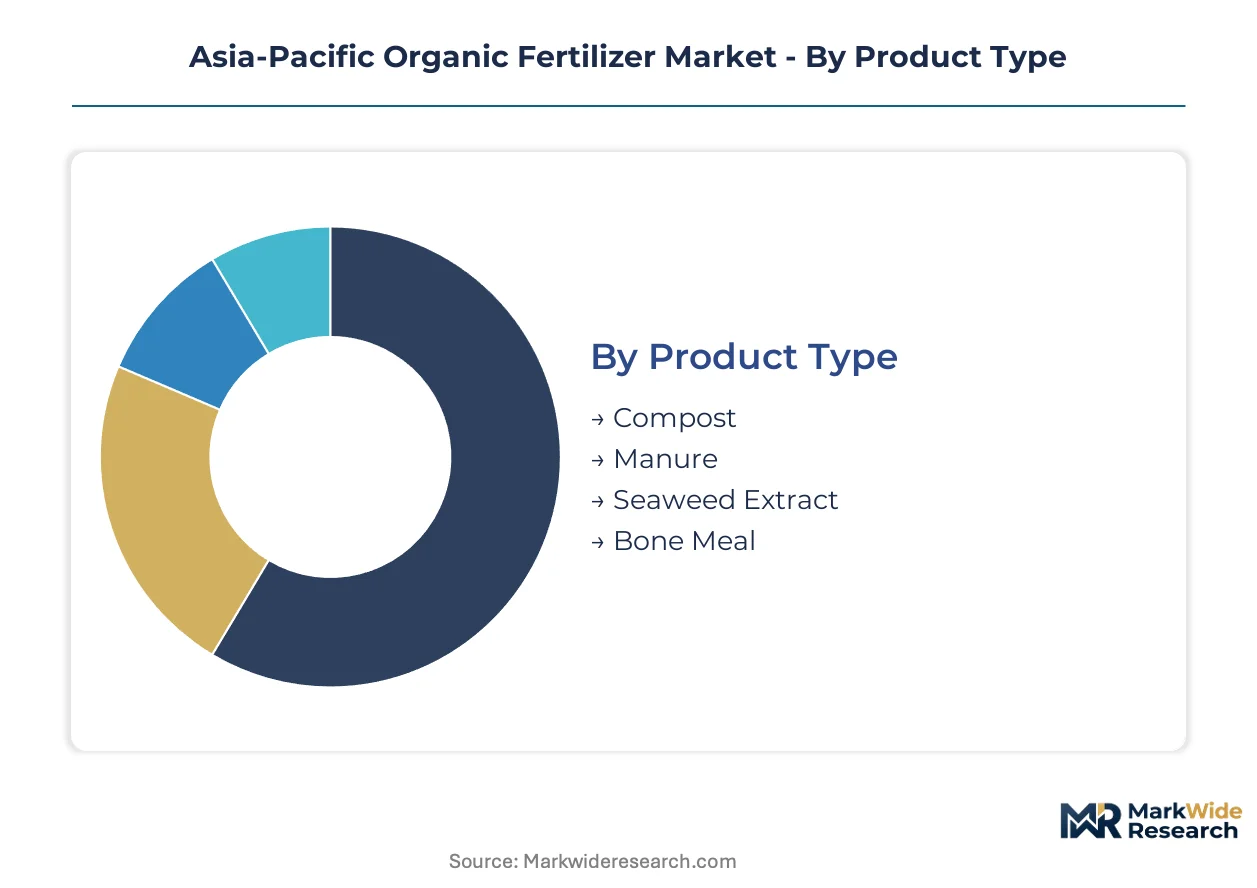
Cycle times vary dramatically: aerobic composting demands six-month maturation windows while enzymatic fermentation compresses production into fourteen-day batches, reshaping working capital intensity across segment portfolios.
- Compost:Decomposed organic matter from municipal green waste and agricultural residues, stabilized through thermophilic aerobic processing. Demand clusters in India's Indo-Gangetic Plain wheat-rice systems where FSSAI certification mandates displace unregistered suppliers. Municipal feedstock agreements in Chinese Yangtze Delta clusters anchor volume supply.
- Manure:Animal waste processed through anaerobic digestion or aerobic composting to stabilize pathogens and concentrate nutrients. Procurement concentrates among Indian dairy cooperatives in Gujarat and Haryana, driven by biogas digestate integration with renewable energy targets.
- Seaweed Extract:Marine biomass hydrolysates supplying cytokinins and micronutrients for high-value horticulture.
- Bone Meal:Steamed animal bones providing slow-release phosphorus for organic farming certification compliance.
Compost dominates installed base. Seaweed extract is where expansion concentrates.
Application:
Cost tier separation is pronounced: agricultural field applications compete on delivered cost per nutrient unit while horticulture commands three-to-five-fold premiums for batch-traceable formulations.
- Agricultural Fields:Broadacre staple crop systems requiring bulk nutrient replenishment with soil conditioning benefits. India's wheat-rice belt and China's northeastern corn-soy regions absorb granular compost and manure at scale, constrained by synthetic fertilizer subsidy gaps.
- Horticulture:Fruit, vegetable, and ornamental production demanding precision nutrition and residue-free certification. Australian viticulture and Vietnamese dragon fruit belts drive liquid microbial inoculant uptake through drip irrigation integration.
- Landscaping:Turf establishment and amenity planting in urban greening projects across Chinese tier-one cities.
- Organic Farming:Certified operations bound by third-party audit protocols for EU and North American export markets.
Agricultural fields anchor volume throughput. Horticulture captures margin expansion.
Form:
Application method dictates form selection: broadcasting equipment favors granular and pelleted formats while precision fertigation infrastructure absorbs liquid concentrates.
- Granular:Compost and manure processed into uniform particles for mechanical spreading compatibility. Chinese GB standards for organic-inorganic compounds drive quality upgrades in peri-urban Shanghai and Guangzhou processing clusters.
- Liquid:Microbial inoculants and fermented extracts designed for fertigation and foliar application. Australian horticulture and Vietnamese fruit cooperatives are climbing the fastest adoption curve as drip hardware penetrates smallholder systems.
- Powder:Fine-ground bone meal and dried compost for blending into custom substrate mixes.
- Pelleted:Compacted organic matter with controlled-release coatings for export logistics efficiency.
Granular commands installed equipment base. Liquid is gaining share fastest.
End User:
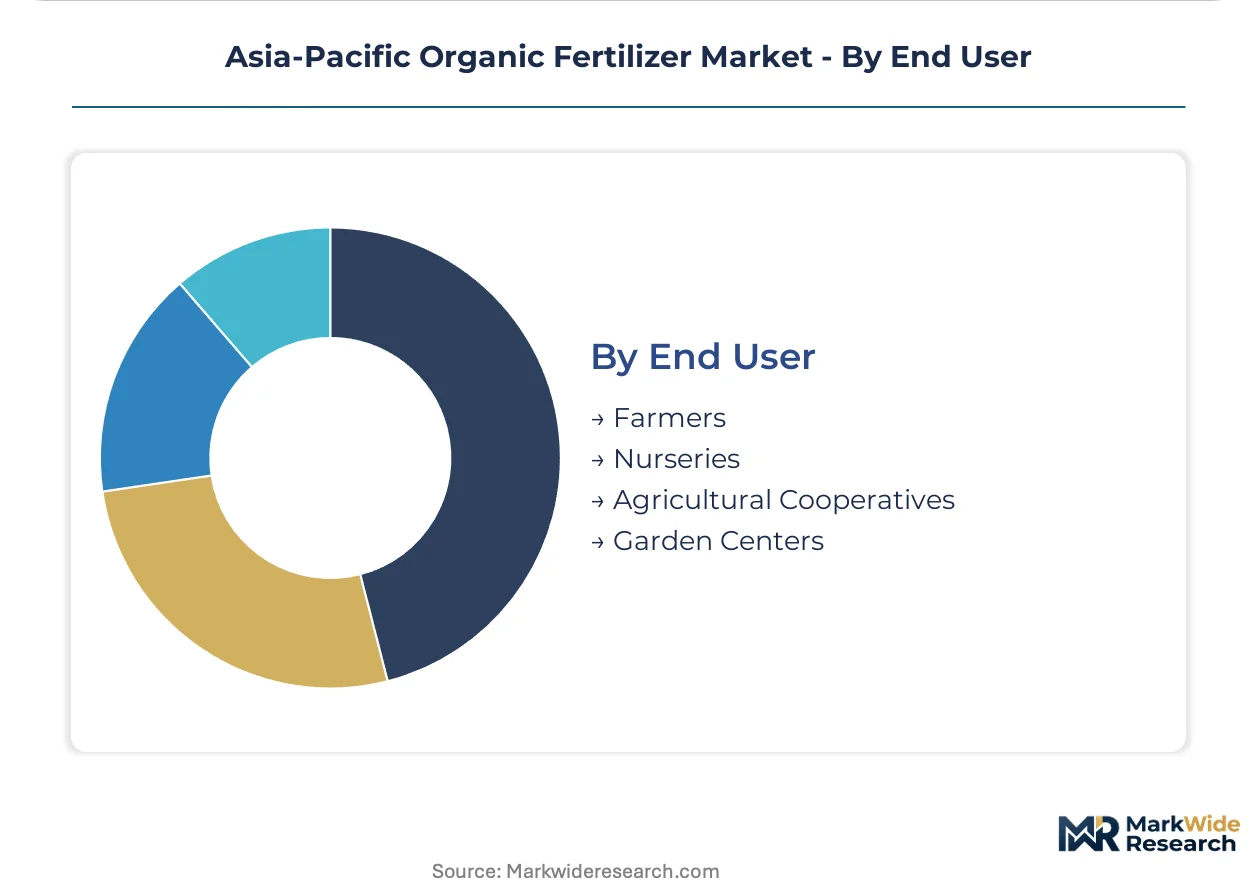
Customer type determines procurement protocol: individual farmers transact through village aggregators while export cooperatives demand laboratory documentation at batch level.
- Farmers:Individual smallholders and estate owners purchasing through dealer networks or direct manufacturer relationships. Price sensitivity in Indian staple crop segments limits organic adoption without certification premiums.
- Agricultural Cooperatives:Consolidated buying entities serving export-oriented organic operations. Maharashtra and Karnataka grape cooperatives bypass traditional distributors through direct compost manufacturer contracts to meet European supermarket chain compliance.
- Nurseries:Specialized propagation operations requiring sterile, consistent substrate formulations.
- Garden Centers:Retail channels for consumer packaged organic fertilizers in Australian and Japanese urban markets.
Agricultural cooperatives concentrate procurement volume. Nurseries represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kolkata Port Complex and Yangtze River Delta container terminals underwrite Asia-Pacific organic fertilizer trade flows, connecting Indian compost processors to Vietnamese horticulture belts and Chinese fermentation clusters to Australian viticulture cooperatives.
India
FSSAI organic certification mandates pull wheat-rice systems in Punjab and Haryana toward verified compost protocols, eliminating unregistered village suppliers from cooperative procurement pools. Gujarat Narmada Valley Fertilizers anchors granular production through captive biogas digesters in the Narmada corridor. The Indo-Gangetic Plain processing clusters concentrate municipal waste-to-fertilizer infrastructure serving Delhi-NCR peri-urban vegetable belts.
China
MIIT bio-manufacturing directives accelerate anaerobic digester retrofits across Jiangsu and Zhejiang provinces, tightening effluent standards while expanding biogas-to-fertilizer output. GB standards for organic-inorganic compound fertilizers force Shanghai and Guangzhou processors to install eddy current separators and hydrocyclone washing stages. Yangtze Delta fermentation technology clusters supply enzymatic processing equipment to Vietnamese cassava processors.
Australia
Drip irrigation penetration in Riverina and Murray-Darling horticulture belts absorbs liquid microbial inoculants at accelerating rates as precision fertigation hardware reaches smallholder cooperatives. TGA-equivalent agricultural chemical registration frameworks tighten batch-level traceability requirements for export-oriented organic wine producers. Victoria's nursery propagation operations drive sterile substrate formulation demand from liquid fertilizer specialists.
Vietnam
Dragon fruit and mango export cooperatives in Mekong Delta provinces adopt liquid concentrates through drip irrigation integration, bypassing traditional granular distribution channels. Cassava starch processors in Tay Ninh and Binh Phuoc deploy fourteen-day enzymatic fermentation systems to manage waste liabilities. The absence of domestic certification infrastructure creates first-mover openings for FSSAI-equivalent Indian exporters.
Thailand
Biogas digestate integration with renewable energy targets concentrates processing capacity in Nakhon Ratchasima and Khon Kaen livestock corridors. Cassava and sugarcane residue enzymatic fermentation virtualizes capital efficiency benchmarks for mid-scale entrants previously locked out by land-intensive windrow operations. Bangkok-peri-urban vegetable belts absorb municipal compost under tightening contaminant protocols.
Asia-Pacific Organic Fertilizer Market Competitive Landscape
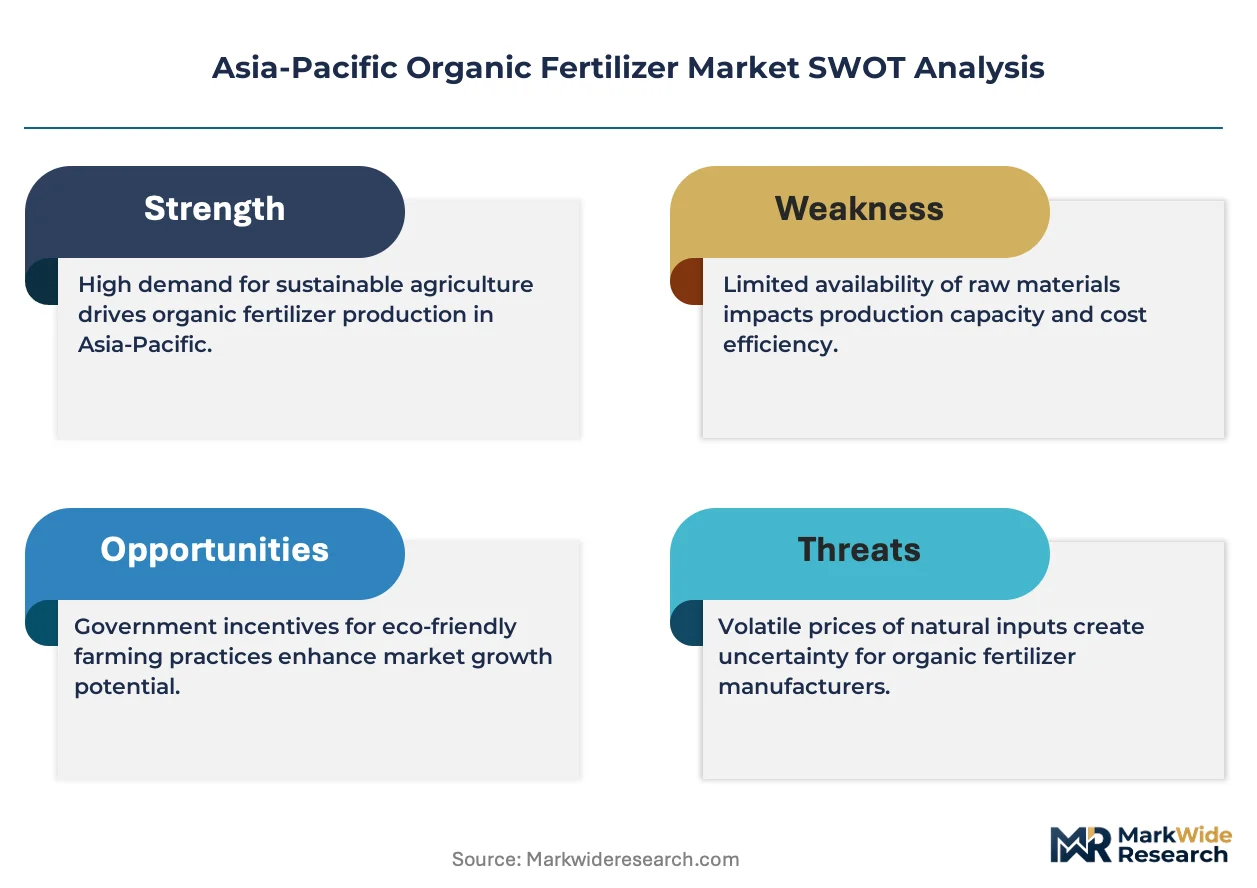
Platform integrators command the system tier; component specialists sit upstream supplying fermentation technology and microbial inoculant formulations. Supply concentrates among scaled manufacturers with in-house laboratory certification capacity, displacing informal compost aggregators from cooperative procurement channels. Three archetypes dominate: state-affiliated fertilizer incumbents with backward integration into captive biogas infrastructure, coastal blending specialists leveraging port logistics for export cooperative contracts, and microbial formulation specialists serving nursery propagation operations. Competitive moves center on direct contracting with export-oriented organic cooperatives and enzymatic fermentation technology licensing to mid-scale processors.
Among Indian state-affiliated entities, Coromandel International Ltd, Gujarat Narmada Valley Fertilizers & Chemicals Ltd, and National Fertilizers Limited occupy positions anchoring granular compost and manure production for agricultural cooperative procurement pools. Chinese fermentation technology specialists including Genliduo Bio-tech Corporation Ltd and Shandong Nongda Fertilizer Sci & Tech Co Ltd represent the equipment and process licensing tier supplying enzymatic systems to Vietnamese and Thai processors. Kiwa Biotech exemplifies the microbial inoculant formulation archetype differentiating liquid portfolios for nursery end users.
| Leading Market Players |
|---|
| Coromandel International Ltd |
| Genliduo Bio-tech Corporation Ltd |
| Gujarat Narmada Valley Fertilizers & Chemicals Ltd |
| Gujarat State Fertilizers & Chemicals Ltd |
| Swaroop Agrochemical Industries |
| Shandong Nongda Fertilizer Sci & Tech Co Ltd |
| National Fertilizers Limited |
| Tata Chemicals Ltd |
| Kiwa Biotech |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta fermentation technology clusters anchor regional capacity dynamics, translating concentrated enzymatic processing expertise into pricing leverage over Vietnamese and Thai mid-scale processors dependent on equipment licensing. Downward cost pressure from Chinese state-affiliated manufacturers with captive biogas infrastructure compresses margins for Indian coastal blending specialists serving agricultural cooperatives.
Pricing Analysis
Volume-discount tiering structures stratify across FSSAI-certified premium batches, standard granular compost for domestic wheat-rice systems, and economy-grade municipal waste derivatives for peri-urban vegetable belts. Price differentiation hinges on laboratory certification depth and geographic delivery radius to Indo-Gangetic Plain states. Cost compression in the economy tier intensifies because synthetic urea and DAP subsidies in India and China maintain artificial price floors. Agricultural field applications exhibit highest price sensitivity, while export-oriented organic cooperatives absorb three-to-five-fold premiums for batch-traceable horticulture formulations.
Supply Chain Analysis
Export-control regime angles on fermentation biotechnology from Chinese MIIT directives limit technology transfer to Vietnamese and Thai processors, constraining enzymatic capacity expansion outside Yangtze Delta licensing networks. Geographic supply concentration centers on India, China, and Vietnam. Raw material flows draw from municipal organic waste streams, dairy cooperative manure aggregations, and cassava starch processing residues. Single-source vulnerability runs through Chinese equipment licensing for fourteen-day enzymatic systems. Distribution runs through Kolkata Port Complex and Yangtze River Delta container terminals connecting compost processors to horticulture belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific organic fertilizer market exhibits cyclical recovery characteristics tied to FSSAI certification mandate enforcement cycles in India, which periodically compress informal supply channels and redirect procurement toward verified manufacturers.
For Market Incumbents: Harden laboratory certification infrastructure against FSSAI and GB standards escalation by installing in-house heavy metal and pathogen testing capacity that informal aggregators cannot replicate. Deepen backward integration into captive biogas digesters to secure feedstock cost predictability against municipal waste stream volatility.
For New Entrants and Emerging Players: Establish a beachhead in Myanmar and Cambodia by deploying FSSAI-equivalent laboratory protocols where domestic certification infrastructure remains absent. Target liquid microbial inoculant formulations for Vietnamese dragon fruit cooperatives adopting drip irrigation, bypassing entrenched granular distribution channels through direct fertigation hardware bundling.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzymatic fermentation equipment licensors with recurring licensing revenue from Vietnamese and Thai cassava processors over capital-intensive compost operators. Long-term viability rests on circular economy convergence between renewable energy biogas targets and organic fertilizer output. The signal to watch is MIIT directive expansion into additional provincial jurisdictions beyond Jiangsu and Zhejiang.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Biogas Infrastructure | Gujarat Narmada Valley Fertilizers anchors granular production through digesters linked to renewable energy targets. |
| Laboratory Certification Capacity Expansion | In-house FSSAI and GB standards compliance displaces informal compost aggregators from cooperative procurement pools. |
| Enzymatic Fermentation Technology Licensing | Chinese equipment specialists monetize process IP through recurring fees from Vietnamese cassava processors. |
| Direct Export Cooperative Contracting | Maharashtra grape cooperatives bypass traditional distributors to meet European supermarket chain compliance requirements. |
| Liquid Microbial Inoculant Portfolio Development | Kiwa Biotech differentiates through sterile substrate formulations for Australian nursery propagation operations. |
Research Methodology
Initial hypotheses were tested against primary input from compost plant managers, agricultural cooperative procurement leads, FSSAI certification auditors, and biogas project developers and refined through secondary validation against customs trade data, MIIT policy directives, FSSAI regulatory filings, and municipal waste processing statistics. Bottom-up volume estimates from individual processing facility capacities were triangulated against top-down demand projections from certified organic acreage expansion.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling segmentation dimensions including product type, application channel, form factor, and end-user procurement protocol. CAGRs were derived from segment-level growth trajectories weighted by revenue contribution. Industry-specific forecast inputs incorporated FSSAI certification penetration rates and drip irrigation hardware adoption curves in Vietnamese horticulture belts.
Macroeconomic conditions sit as an overlay; deviation in synthetic fertilizer subsidy levels or municipal waste collection efficiency would shift the trajectory. Forecasts reflect underlying assumptions about regulatory enforcement continuity and technology licensing access. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Nano Fertilizer Market
Fertilizers
Enhanced Efficiency Fertilizer Market
Fertilizers
Boron Fertilizers Market
Fertilizers
United States Specialty Fertilizer Market
Fertilizers
Chelated Micronutrient Fertilizers Market
Fertilizers
Europe Fertilizers Market
Fertilizers
Africa Fertilizers Market
Fertilizers
Russia Micronutrient Fertilizer Market
Fertilizers
Russia Specialty Fertilizer Market
Fertilizers
Global NPK Fertilizer Market
Fertilizers
Brazil Micronutrient Fertilizer Market
Fertilizers
North America Fertilizers Market
Fertilizers
Potash Market
Fertilizers
Nitrogen Fertilizer Additives Market
Fertilizers
Middle East and Africa Micronutrient Fertilizer Market
Fertilizers
Fertilizer Spreader Market