
 Global Smartphone Display Panel Market | 2026-2036
Global Smartphone Display Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smartphone Display Panel Market Foresight
Flagship smartphone OEM procurement is shifting toward flexible OLED and foldable panels as device makers differentiate through form factor innovation. Samsung Display dominates flexible OLED supply through captive capacity and external customer relationships. BOE Technology Group competes aggressively in rigid OLED and LTPO backplane segments. Japan Display Inc. specializes in LCD automotive crossover applications while sustaining smaller-scale smartphone panel production.
A smartphone display panel is an optoelectronic module combining thin-film transistor backplanes, organic or liquid crystal emissive layers, polarizers, and cover glass, typically manufactured through photolithography, chemical vapor deposition, and precision lamination processes to render visual output under touch input. AMOLED and LTPO OLED segments command margin pools due to premium pricing on high-refresh-rate flagship devices. LCD persists in entry-level and white-label handset supply where cost thresholds override performance specifications. Foldable display shipments represent the fastest-expanding technological feature category as mechanical durability and crease minimization improve.
China's MIIT enforces GB standards on display energy efficiency and electromagnetic compatibility, while South Korea's METI coordinates domestic supply chain resilience policies for OLED materials. REACH in Europe restricts hazardous substances in display manufacturing, pushing substrate and phosphor reformulation. Stakeholders must monitor LTPO capacity expansion timelines, foldable yield rates, and regional subsidy shifts to calibrate procurement and capital deployment decisions.
Market Dynamics
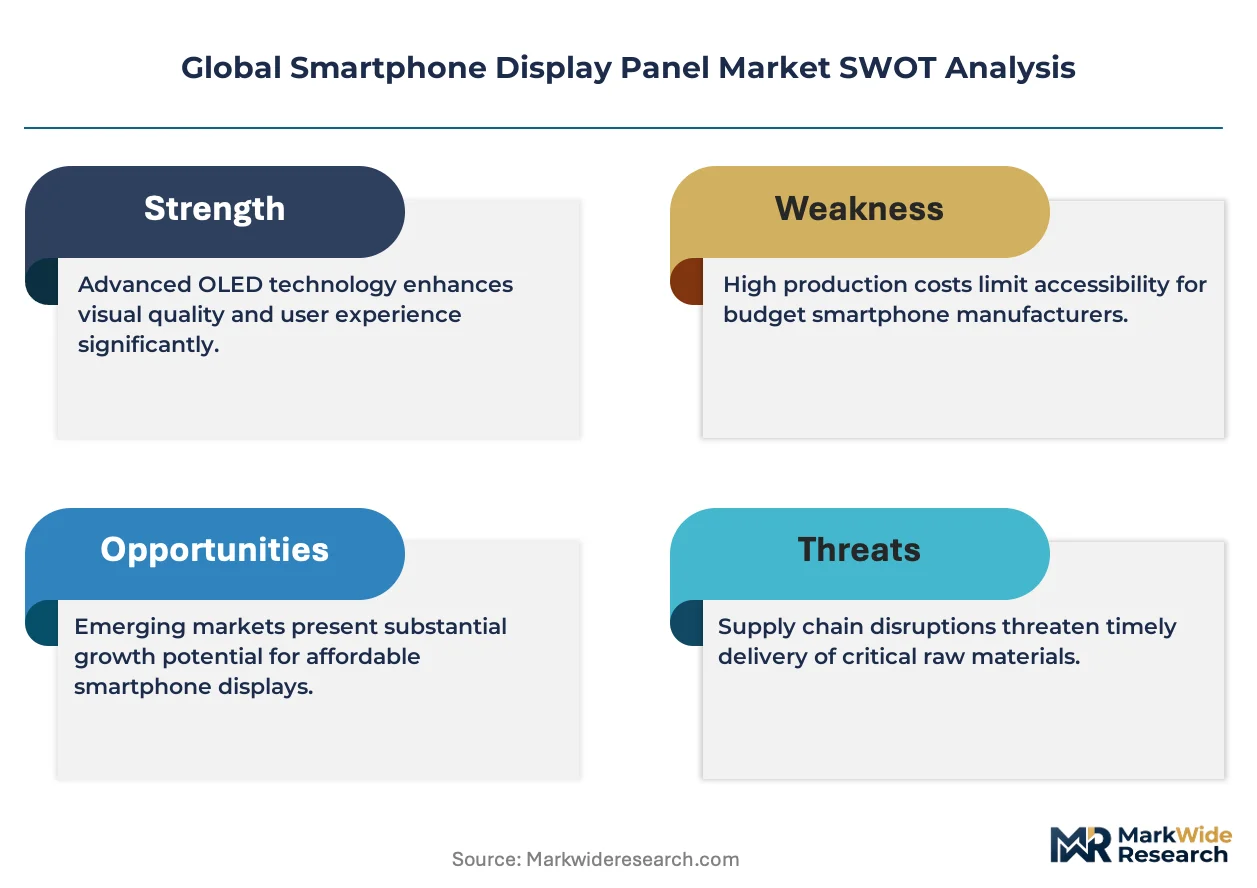
Flexible OLED capacity expansion is compressing LCD procurement volumes as flagship OEMs eliminate rigid display tiers entirely. Samsung Display and BOE Technology Group are absorbing legacy LCD fab assets to convert toward LTPO backplane production, reshaping supplier economics across the value chain.
Growth Catalysts
- EU RoHS material restrictions:Tightened limits on cadmium and lead phosphors are accelerating substrate reformulation toward indium gallium zinc oxide alternatives, opening procurement windows for compliant material suppliers.
- LTPO backplane technology:Variable refresh-rate capability is extending battery endurance in 5G handsets, pulling demand from static-refresh rigid OLED and LCD alternatives in premium device tiers.
- Vietnam assembly cluster expansion:Downstream smartphone final assembly concentration near Hanoi and Ho Chi Minh City is shortening logistics loops for panel-to-device integration, reducing working capital requirements for module suppliers.
Market Restraints
- Driver IC supply concentration:Taiwan and South Korea foundries control advanced semiconductor lithography for display driver integrated circuits, creating single-source vulnerability for OLED module assemblers.
- Foldable mechanical durability limits:Polyimide substrate fatigue and hinge-interface delamination constrain device lifespan warranties, suppressing consumer replacement confidence in ultra-premium price bands.
- EU REACH compliance costs:Substance of very high concern screening for rare earth phosphors and polarizer adhesives is extending qualification timelines by 8-14 months for non-EU material suppliers.
Strategic Opportunities
- India PLI scheme incentives:Production-linked incentive disbursements for display module assembly are attracting panel finishing investments from Chinese and Korean suppliers seeking tariff-advantaged export platforms.
- Automotive display crossover:Smartphone OLED process knowledge transfers directly to center-stack and instrument cluster applications, opening adjacent revenue pools for panel makers with automotive qualification capabilities.
- Under-display camera integration:Camera-integrated OLED panels eliminate notched or punched display cutouts, enabling full-screen form factors that command 15-25% panel price premiums from flagship OEMs.
Industry Challenges
- LTPO thin-film transistor yield management:Low-temperature polycrystalline oxide deposition uniformity remains below commercial targets at Gen 6 fab scale, constraining output ramp schedules and capital efficiency metrics.
- Foldable cover glass certification timelines:UTG (ultra-thin glass) and CPI (colorless polyimide) stack qualification for 200,000-fold durability standards extends product development cycles by 10-16 months.
- Legacy LCD fab conversion capex intensity:Retooling a-Si TFT lines toward oxide semiconductor backplanes requires $800 million to $1.2 billion per fab, straining balance sheets of mid-tier panel suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smartphone Display Panel Market |
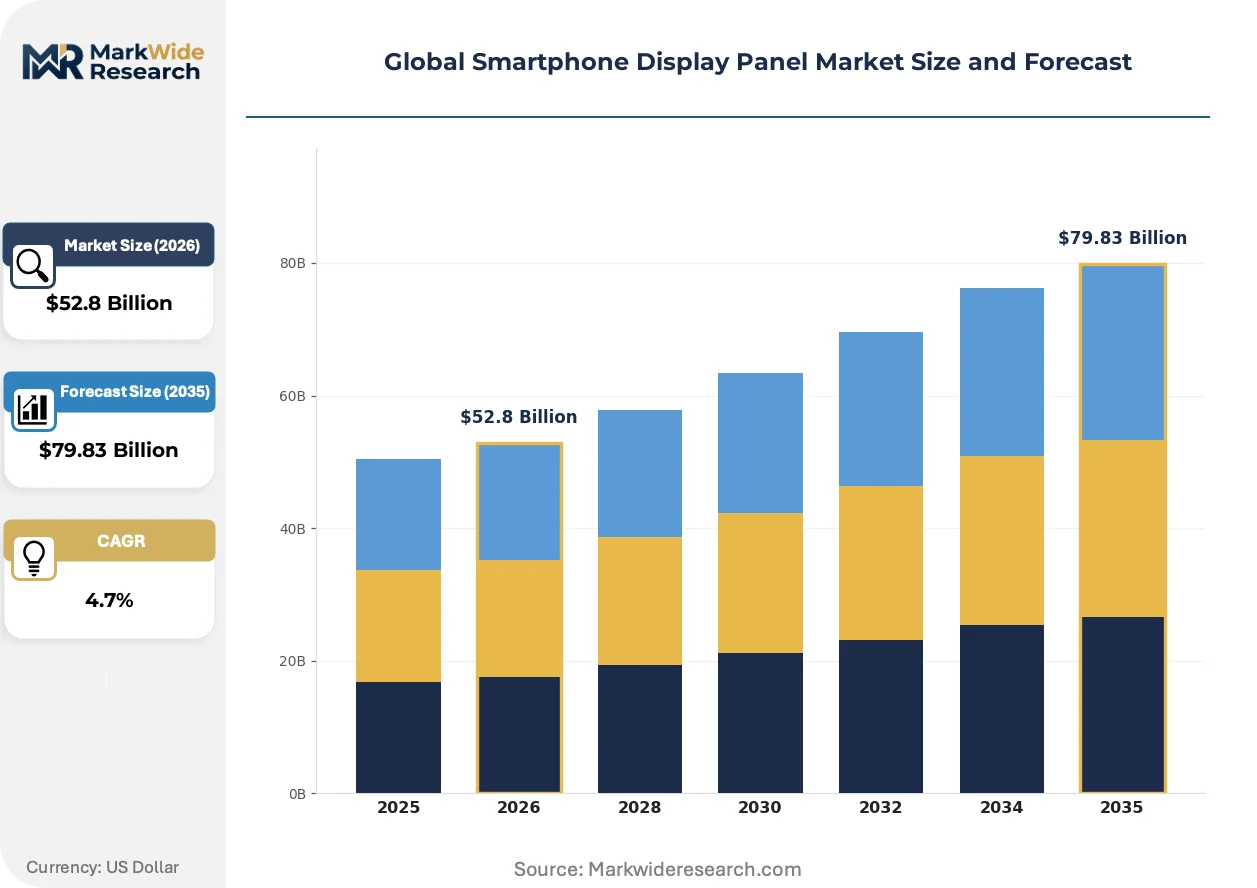
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $79.83 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, OLED, AMOLED, Mini-LED Technological Feature: Touchscreen, Foldable, High Refresh Rate, HDR End User: OEMs, Aftermarket Providers, Retailers, Distributors Sales Channel: Online, Offline, Direct Sales, Third-Party Resellers |
| Companies Covered | CSOT (China Star Optoelectronics Technology), Tianma, Samsung Display, Sharp Corporation, HKC, LG Display, Visionox Technology, Japan Display Inc., BOE Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smartphone Display Panel Market Shifts & Advancements
Display technology roadmaps are converging on form-factor differentiation as the primary vector for OEM margin capture, compressing specification competition around refresh rate and brightness into secondary positioning.
Tandem OLED architectures are absorbing blue-light degradation risk through dual-emissive layer construction, extending panel operational lifespan by 40-60% over conventional single-stack designs. Flagship smartphone OEMs in South Korea and China are specifying tandem structures for 2025-2026 device generations. This technology is absorbing the premium positioning previously occupied by microLED prototypes, delaying that platform's commercialization timeline by 24-36 months.
China's MIIT GB standards on display energy efficiency are mandating power consumption ceilings for smartphones sold domestically, forcing panel suppliers to prioritize LTPO and dynamic frequency scaling in product planning. The industrial consequence is accelerated phase-out of LTPS rigid OLED capacity in favor of oxide backplane alternatives. Domestic Chinese OEMs are responding fastest, with premium tier portfolios already 70-80% LTPO-compliant versus 35-45% for export-focused competitors.
Direct procurement relationships between smartphone OEMs and panel makers are displacing traditional distributor-mediated component sourcing in high-volume tiers. Module specifications are now co-developed through quarterly technology roadmap alignment sessions rather than annual contract negotiations. This pattern is most visible in China and Vietnam, where BOE, Visionox, and Tianma maintain resident engineering teams at major OEM headquarters to compress design iteration cycles.
Global Smartphone Display Panel Market Segmentation
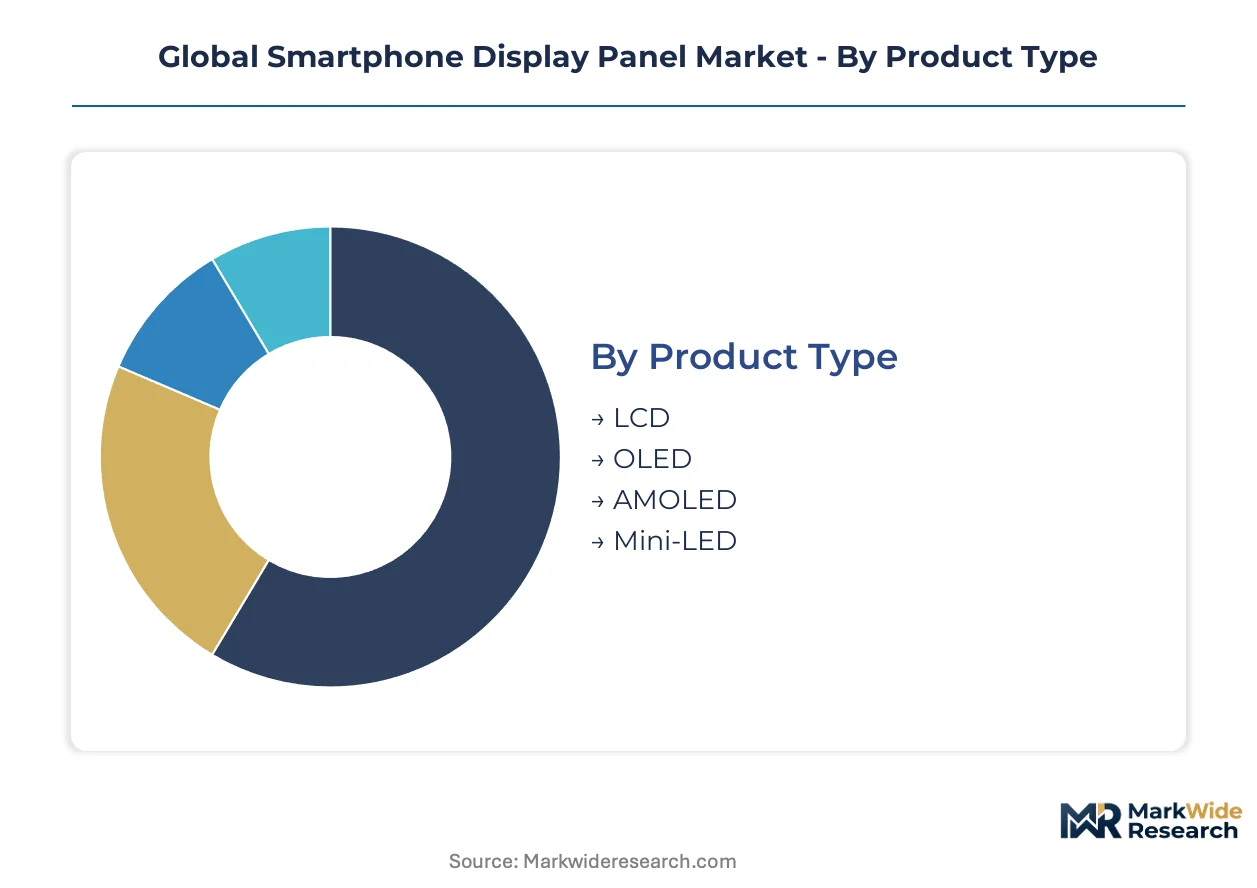
Smartphone display panel procurement decisions cascade through four distinct lenses: underlying display physics, interactive capabilities, buyer identity, and fulfillment pathway. Each segmentation axis reveals divergent margin structures and qualification requirements that reshape supplier economics.
Product Type:
Price-to-performance thresholds drive panel selection across device tiers, with backplane technology and emissive layer chemistry determining power efficiency and manufacturing yield.
- LCD:A-Si and LTPS backplane liquid crystal modules persist in entry-level handset supply where cost floors dominate procurement criteria. Demand concentrates in India and Southeast Asia assembly hubs serving sub-$150 retail price bands, constrained by EU RoHS phosphor reformulation timelines.
- OLED:Organic light-emitting diode panels with rigid glass substrates occupy mid-tier smartphone positioning. South Korean and Chinese OEMs source these for $200-$400 devices, balancing color saturation against burn-in risk warranties.
- AMOLED:Active-matrix OLED with thin-film transistor backplanes enables per-pixel illumination control for deeper blacks and variable refresh implementation. Flagship procurement from Samsung Electronics and Apple absorbs premium Gen 6 fab output, with LTPO variants commanding steepest price premiums.
- Mini-LED:Local dimming zone backlight arrays applied to LCD architectures deliver contrast approaching OLED without organic degradation. Niche adoption concentrates in gaming-focused handset sub-brands seeking 1000+ nit peak brightness specifications.
AMOLED leads on scale; Mini-LED leads on momentum among emerging technology categories.
Technological Feature:
Functional differentiation now outweighs raw display specifications in OEM marketing positioning, compressing refresh rate and resolution into baseline expectations rather than premium anchors.
- Touchscreen:Projected capacitive sensor layers laminated directly to display modules constitute universal smartphone implementation. In-cell and on-cell integration variants from TPK Holding and GIS dominate supply for Chinese and Vietnamese OEM assembly lines.
- Foldable:Polyimide substrate and ultra-thin glass stacks enabling mechanical articulation across 200,000+ fold cycles. Samsung Display and BOE supply these for Galaxy Z and Mate series devices, with crease visibility and hinge durability remaining unresolved consumer friction points.
- High Refresh Rate:120Hz and 144Hz panel controllers with adaptive frequency scaling extend battery endurance during static content viewing. Gaming handset specialists in China specify these for competitive multiplayer positioning.
- HDR:High dynamic range certification requiring 1000+ nit sustained brightness and 10-bit color depth processing. Premium tier validation from Dolby and HDR10+ compliance gates access to flagship device bill-of-materials.
Touchscreen integration leads on scale; foldable form factors lead on momentum as mechanical reliability improves.
End User:
Procurement authority and volume concentration determine contract structure, with direct OEM relationships displacing distributor-mediated sourcing in high-tier supply.
- OEMs:Original equipment manufacturers with annual device volumes exceeding 10 million units negotiate quarterly technology roadmap alignment and resident engineering support. Samsung Electronics, Apple, Xiaomi, and OPPO maintain direct procurement teams co-located at panel maker headquarters.
- Aftermarket Providers:Independent repair networks and refurbished device specialists source replacement panels through secondary distribution. Quality variance and warranty limitations constrain addressable market expansion.
- Retailers:Carrier-owned retail channels and electronics superstores procure replacement displays for in-house repair services. Verizon and Best Buy operate certified repair programs with authorized parts sourcing.
- Distributors:Regional component wholesalers aggregate fragmented demand from smaller OEMs and repair shops. Inventory risk and price volatility compress margins in this channel tier.
OEM direct procurement leads on scale; aftermarket providers lead on momentum as right-to-repair regulations expand.
Sales Channel:
Logistics configuration and working capital requirements vary sharply across fulfillment pathways, with geographic proximity to assembly clusters determining channel viability.
- Online:B2B procurement platforms and manufacturer-direct portals enable spot purchasing for development samples and low-volume production. Alibaba and panel maker proprietary systems serve smaller OEMs without dedicated sourcing teams.
- Offline:Physical component markets in Shenzhen and Seoul facilitate inspection-based purchasing for quality-sensitive applications. Cash-and-carry transactions dominate legacy procurement patterns.
- Direct Sales:Long-term supply agreements with quarterly volume commitments and price renegotiation clauses. Samsung Display and BOE maintain dedicated account teams for top-tier OEM relationships.
- Third-Party Resellers:Authorized distributors with regional warehousing and technical support capabilities. Avnet and Arrow Electronics maintain smartphone display inventory for North American and European OEM access.
Direct sales leads on scale; online channels lead on momentum as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting display panel fabrication toward jurisdictions with streamlined environmental compliance and concentrated downstream assembly ecosystems. Panel makers are relocating finishing capacity to exploit cost-of-compliance gaps between mature and emerging manufacturing jurisdictions.
China
Domestic OEM procurement from Xiaomi and OPPO absorbs Gen 6 AMOLED fab output in Beijing and Chengdu. MIIT enforces GB standards on display energy efficiency and electromagnetic compatibility. The Yangtze River Delta cluster around Shanghai and Suzhou hosts BOE and Visionox oxide backplane production lines serving premium smartphone tiers.
South Korea
Samsung Electronics and Apple source flexible OLED exclusively from domestic Gen 6 facilities. METI coordinates supply chain resilience policies for OLED precursor materials and driver IC localization. The Gyeonggi-do corridor between Seoul and Incheon concentrates Samsung Display LTPO capacity and materials supplier ecosystems.
Vietnam
Downstream smartphone final assembly expansion near Hanoi and Ho Chi Minh City shortens logistics loops for panel-to-device integration. The country's Ministry of Industry and Trade administers preferential tax treatment for display module finishing investments. Samsung Electronics and Foxconn operate billion-unit-scale assembly plants requiring just-in-time panel delivery.
India
PLI scheme disbursements for display module assembly are attracting Chinese and Korean suppliers seeking tariff-advantaged export platforms. The Ministry of Electronics and Information Technology administers production-linked incentive thresholds. Gujarat and Uttar Pradesh sub-regions host emerging panel finishing investments adjacent to smartphone OEM assembly operations.
United States
Apple's procurement authority shapes specification roadmaps for premium OLED tiers through direct supplier co-development. The FCC regulates electromagnetic emissions from display-integrated touch controllers. California-based OEM engineering teams coordinate quarterly technology alignment with Asian panel maker headquarters.
Global Smartphone Display Panel Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive supply arrangements dominating premium tiers and merchant sales characterizing mid-market procurement. The vendor base concentrates among five vertically integrated fabricators controlling Gen 6 oxide backplane capacity. Two strategic archetypes define competitive positioning: Korea-headquartered flexible OLED specialists with captive customer relationships, and China-based scale players competing on rigid OLED and LTPO cost structures. Capacity conversion and direct OEM co-development partnerships constitute the dominant competitive moves reshaping supplier economics.
Within the Korea-headquartered specialist tier, Samsung Display and LG Display occupy positions defined by flexible OLED technology leadership and long-term supply agreements with flagship OEMs. Among China-based scale fabricators, BOE Technology Group exemplifies the merchant-market archetype competing across rigid OLED, LTPO, and LCD conversion segments. CSOT and Tianma sit within the emerging capacity tier, representing the next wave of oxide backplane investment targeting domestic OEM procurement and India PLI-advantaged export platforms.
| Leading Market Players |
|---|
| CSOT (China Star Optoelectronics Technology) |
| Tianma |
| Samsung Display |
| Sharp Corporation |
| HKC |
| LG Display |
| Visionox Technology |
| Japan Display Inc. |
| BOE Technology Group |
| Others |
Supply & Pricing Matrix
Indium gallium zinc oxide precursor costs cascade through AMOLED substrate fabrication into tiered panel pricing, with South Korean and Chinese material suppliers commanding premium positioning against legacy phosphor alternatives facing EU RoHS compliance deadlines.
Pricing Analysis
Distributor margins compress as direct OEM procurement displaces traditional channel intermediaries in high-volume smartphone display tiers. Pricing stratifies across premium LTPO, standard rigid OLED, and economy LCD tiers based on backplane technology complexity and refresh-rate capability. Cost compression in entry-level LCD segments intensifies due to Vietnam and India assembly cluster proximity requirements. Aftermarket repair providers exhibit highest price sensitivity, while flagship OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
India's PLI scheme domestic-content thresholds are redirecting panel finishing investments toward Gujarat and Uttar Pradesh sub-regions, reshaping procurement geography for export-bound smartphone assembly. Supply concentrates in China, South Korea, and Vietnam where Gen 6 oxide backplane fabrication and downstream module integration operate at scale. The supply chain draws from rare earth phosphor deposits, driver IC foundry output in Taiwan, and ultra-thin glass substrates from Japanese specialty glassmakers. Single-source vulnerability in advanced semiconductor lithography for display driver integrated circuits creates structural risk. Distribution runs through direct sales agreements with quarterly volume commitments for tier-one OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in LTPO backplane transitions and foldable panel premiums, with tandem OLED architectures absorbing blue-light degradation risk while extending operational lifespan.
For Market Incumbents: Lock in LTPO capacity allocations through captive supply agreements with Samsung Electronics and Apple before oxide backplane yield improvements democratize access. Defend against BOE Technology Group's merchant-market expansion by deepening resident engineering presence at Chinese OEM headquarters. Prioritize automotive display crossover qualifications to diversify revenue pools beyond handset procurement cycles.
For New Entrants and Emerging Players: Aftermarket repair networks and refurbished device specialists represent underserved buyer archetypes with expanding right-to-repair regulatory tailwinds. White-space availability concentrates in India PLI-advantaged module finishing and secondary distribution for sub-tier OEMs lacking direct panel maker relationships. Enter through certified parts sourcing partnerships with carrier-owned retail channels seeking vertical integration into in-house repair services.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier panel suppliers face $800 million to $1.2 billion legacy LCD fab conversion capex requirements without balance sheet capacity. Long-term viability favors oxide backplane specialists with automotive qualification capabilities and foldable mechanical durability IP. Acquisition target archetypes include driver IC design houses facing foundry concentration risk and UTG substrate specialists with 200,000-fold certification timelines. Monitor LTPO yield rate inflections at Gen 6 scale as capital efficiency signal.
| Strategic Initiative | Industry Significance |
|---|---|
| LTPO Backplane Capacity Expansion | Variable refresh-rate capability extends battery endurance in 5G handsets from Samsung and Apple. |
| Automotive Display Qualification | Smartphone OLED process knowledge transfers to center-stack applications for Tier 1 suppliers. |
| Under-Display Camera Integration | Camera-integrated OLED panels enable full-screen form factors commanding panel price premiums. |
| India PLI Scheme Participation | Tariff-advantaged export platforms attract Chinese and Korean panel finishing investments. |
| Tandem OLED Architecture Deployment | Dual-emissive layer construction extends panel lifespan by 40-60% over single-stack designs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with display panel procurement directors, OLED materials R&D leads, smartphone OEM supply chain managers, and driver IC foundry planners with secondary validation against SEC filings, customs trade databases, MIIT GB standard disclosures, and ECHA REACH substance screening records. Bottom-up fab capacity modeling and top-down OEM bill-of-materials analysis provided triangulation anchors.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation modeling spanning display physics type, backplane technology tier, end-user procurement authority, and geographic fulfillment pathway. CAGRs derived from capacity expansion timelines, yield improvement curves, and OEM device shipment patterns. Foldable panel durability certification timelines and LTPO deposition uniformity metrics served as technology-specific forecast inputs.
Underlying measurement precision varies by segment; AMOLED and LTPO tiers carry tighter precision than legacy LCD given concentrated supplier disclosure practices. Forecasts reflect assumptions around oxide backplane yield maturation, EU RoHS compliance timelines, and India PLI disbursement continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global Next Generation Display Market
Display Technologies
Display Control and Management System Market
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
Capacitive Touch Screen Market
Display Technologies
North America Computer Monitor Market
Display Technologies
Head Up Display Market
Display Technologies
OLED Laptops Market
Display Technologies
Multimedia Projectors Market
Display Technologies
Middle East and Africa Transparent Conductive Films Market
Display Technologies
Glasses Free 3D Display Market
Display Technologies
Interferometric Modulator Display Market
Display Technologies
Glass-Free HD 3D Display Market
Display Technologies
Wireless Display Market
Display Technologies
Digital Kiosk Display Market
Display Technologies
Polarizing Film for Displays Market
Display Technologies
Vietnam Digital Signage Market