
 North America Computer Monitor Market | 2026-2036
North America Computer Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
North America Computer Monitor Market Analytics
Modular docking-monitor bundles is repositioning procurement patterns across corporate IT departments. Dell Technologies Inc. leverages its direct enterprise sales channel to anchor large-scale deployment contracts. HP Inc. competes through integrated workstation-monitor ecosystems that reduce cable clutter and IT support overhead. Samsung Group differentiates by supplying high-refresh panels to gaming peripheral integrators seeking display-PC bundle partnerships.
Computer monitors are electro-optical display devices that convert video signals into visible images through liquid crystal, organic light-emitting diode, or cathode ray tube technologies, with specifications including refresh rates, color gamut coverage, and pixel density determining suitability for text rendering, video editing, or interactive gaming. LED panels dominate volume shipments due to manufacturing scale and cost efficiency, while OLED displays represent the fastest-growing product type as creative professionals prioritize color accuracy and infinite contrast ratios. Gaming usage commands premium pricing through specialized refresh rates and adaptive sync technologies, whereas educational procurement emphasizes 24-inch to 27-inch screen sizes for classroom density constraints.
The U.S. EPA ENERGY STAR program and California's electronic waste recycling regulations shape minimum efficiency standards and end-of-life compliance costs for manufacturers selling across North America. FCC electromagnetic interference certification requirements govern wireless-enabled smart monitor connectivity modules entering U.S. distribution channels. Stakeholders must monitor evolving state-level right-to-repair legislation that could mandate component accessibility and extend product lifecycles.
Market Dynamics
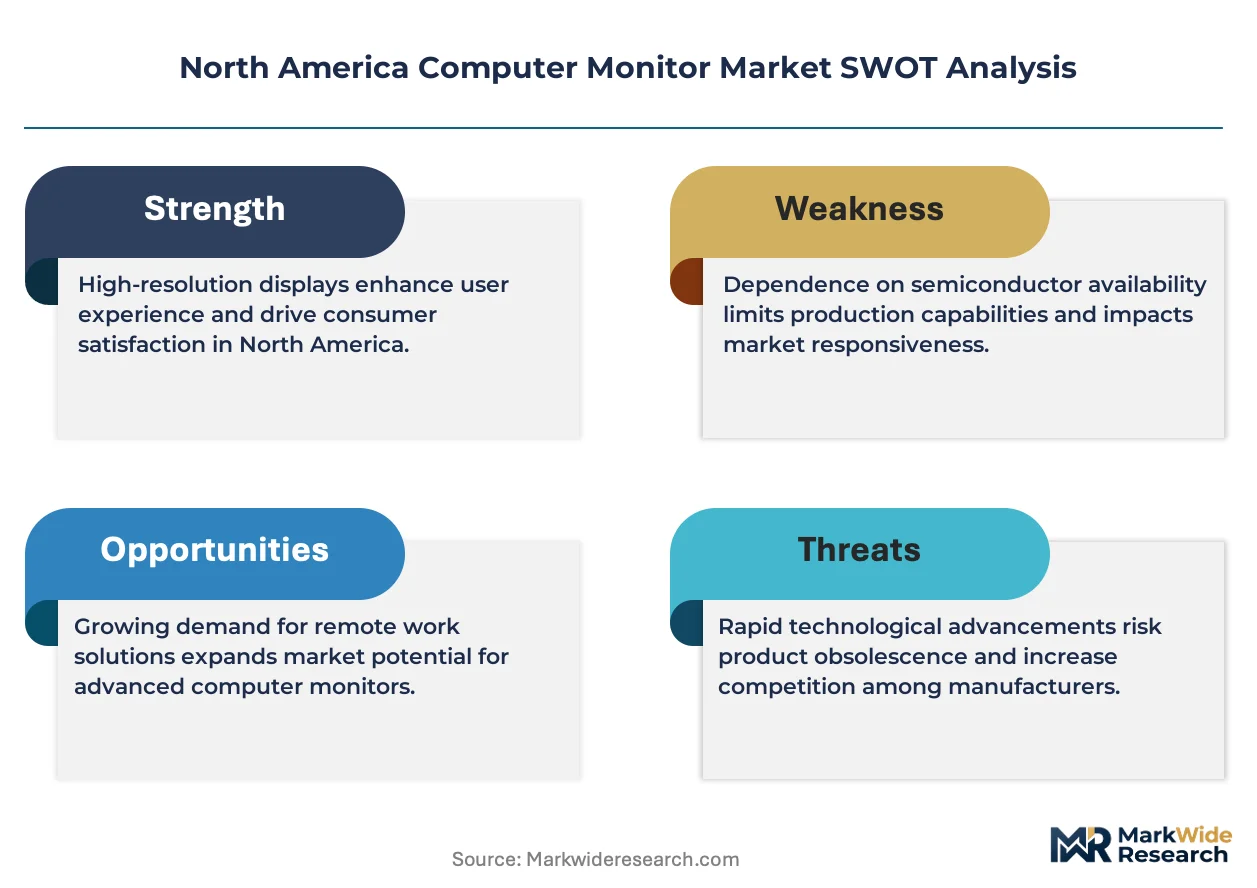
Enterprise procurement of color-accurate displays is accelerating as healthcare and finance sectors compress refresh cycles to support remote diagnostic workflows and trading floor visualization. The U.S. EPA ENERGY STAR specification and California's electronic waste recycling regulations are forcing manufacturers to redesign power architectures and end-of-life logistics.
Growth Catalysts
- Healthcare digitization:Radiology departments and surgical planning units require DICOM-calibrated displays for diagnostic accuracy, driving replacement of legacy CRT and early LED panels in hospital systems across the U.S. and Canada.
- California SB-20 e-waste directives:State-level extended producer responsibility mandates compel manufacturers to establish closed-loop recycling networks, creating competitive differentiation for compliant suppliers.
- OLED penetration in creative verticals:Post-production studios and color grading suites prioritize infinite contrast ratios and true black levels for HDR mastering workflows.
Market Restraints
- Panel input cost volatility:Glass substrate and rare-earth phosphor prices fluctuate with energy costs in Taiwanese and Korean manufacturing clusters, compressing margin predictability for display assemblers.
- FCC certification timelines:Wireless-enabled smart monitors face electromagnetic interference testing bottlenecks that delay product launches by four to six months.
- Smartphone and tablet substitution:Mobile-first knowledge workers in smaller enterprises bypass dedicated monitor purchases for docked mobile device setups.
Strategic Opportunities
- Texas corridor demand concentration:Austin and Dallas tech sector employment density supports premium ultrawide and curved monitor adoption for software development and data science workflows.
- Right-to-repair legislative tailwinds:New York's Digital Fair Repair Act creates openings for modular component suppliers and third-party maintenance networks.
- AI-assisted display calibration:Convergence of on-device machine learning and colorimeter hardware enables automated white-point matching across multi-monitor arrays.
Industry Challenges
- Color science talent scarcity:Display manufacturers compete for optical engineers capable of tuning gamma curves and uniformity correction algorithms for professional-grade panels.
- Legacy VGA and DVI integration:Industrial and government buyers require backward compatibility with analog video infrastructure, adding BOM complexity and firmware maintenance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Computer Monitor Market |
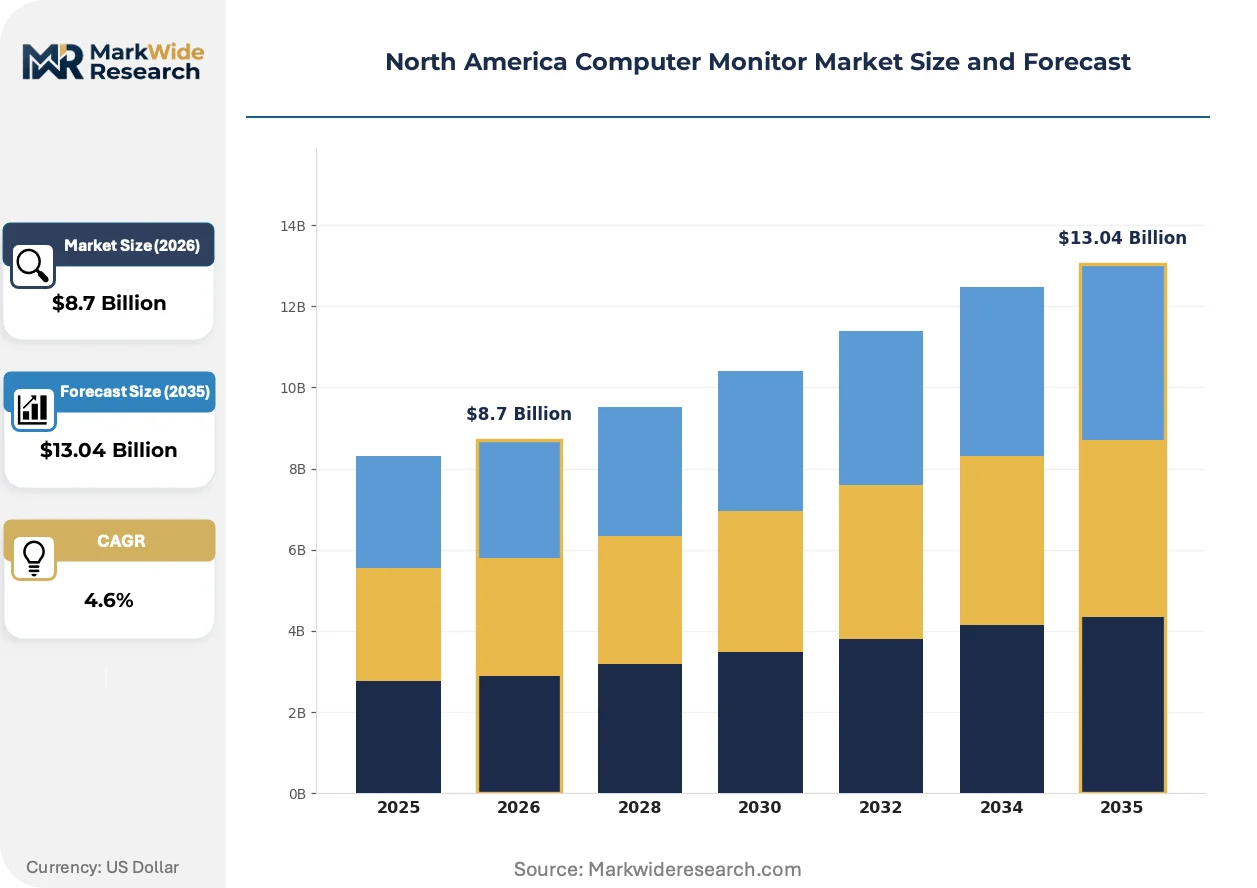
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, LED, OLED, CRT Usage Type: Gaming, Professional, Educational, Home Office Screen Size: 24-Inch, 27-Inch, 32-Inch, 43-Inch Connectivity: HDMI, DisplayPort, VGA, USB-C |
| Companies Covered | HP Inc., Dell Technologies Inc., Lenovo Group Limited, Samsung Group, Apple Inc., LG Electronics Inc., Acer Inc., AsusTek Computer Inc., ViewSonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Computer Monitor Market Evolving Landscape
Display technology architectures are fragmenting across specialized use cases rather than converging on universal specifications. Three distinct trajectories now define competitive positioning.
Mini-LED backlighting with local dimming zones is modularizing high-dynamic-range performance into mid-tier price bands. Corporate IT departments in financial services are adopting these panels at twice the pace of general enterprise refresh cycles. This modularization is compressing the premium display tier and forcing OLED suppliers to defend position through faster refresh rates and burn-in warranties.
The U.S. EPA ENERGY STAR Version 8.1 specification tightens standby power limits and introduces on-mode efficiency metrics for displays above 30 inches. Manufacturers must redesign power supply units and backlight drivers to maintain certification eligibility. Large-format commercial signage and conference room displays face the steepest compliance cost increases, pushing some suppliers toward uncertified gray-market channels.
Corporate buyers are consolidating vendor relationships through docking-monitor bundles that reduce cable clutter and IT support tickets. Dell and HP direct sales teams are displacing traditional distribution for enterprise contracts above 500 units. The U.S. Pacific Northwest and Texas corridor show the highest concentration of this procurement pattern, where tech sector density justifies dedicated account management and custom SKU development.
North America Computer Monitor Market Segmentation
Display procurement across North America fragments along technical specifications and deployment contexts. Procurement teams align refresh cycles with specific use-case demands rather than pursuing universal hardware standards.
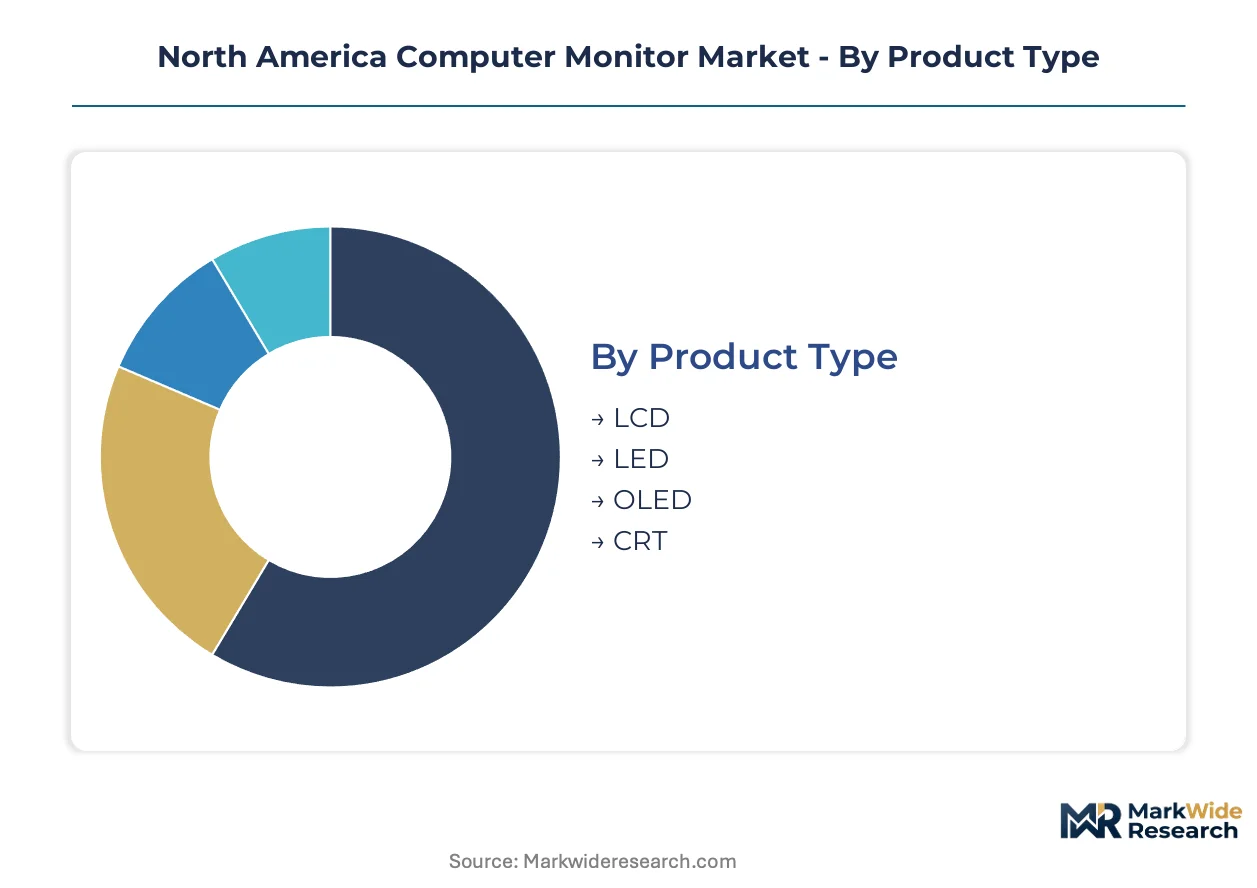
Product Type:
Panel technology determines color accuracy, power consumption, and end-of-life compliance costs under California SB-20 directives.
- LED:Liquid crystal displays with edge-lit or direct-lit backlighting dominate volume shipments through manufacturing scale and cost efficiency. Enterprise IT departments in Texas and the Pacific Northwest specify these panels for general office deployment where ENERGY STAR compliance reduces operating overhead.
- OLED:Organic light-emitting diode panels deliver infinite contrast ratios and true black levels through self-emissive pixel architecture. Post-production studios in Los Angeles and Toronto prioritize OLED for HDR color grading workflows where DICOM calibration and uniformity correction justify premium procurement.
- LCD:Legacy cold-cathode fluorescent lamp backlit panels persist in government and industrial installations requiring backward compatibility with analog infrastructure. Federal agencies and municipal utilities specify LCD for existing VGA and DVI integration without full infrastructure replacement.
- CRT:Cathode ray tube displays survive in specialized medical imaging and legacy industrial control systems where electromagnetic interference tolerance and scan-rate flexibility outweigh replacement costs. Niche maintenance contracts support remaining installed base.
Mature deployment sits with LED. Newer deployment is concentrated in OLED.
Usage Type:
Application context dictates refresh rate requirements, color gamut specifications, and warranty terms.
- Professional:Color-accurate displays for video editing, CAD visualization, and financial trading require factory calibration and uniformity guarantees. Healthcare radiology departments and investment banking trading floors in New York and Chicago drive replacement of legacy panels with DICOM-calibrated alternatives.
- Gaming:High-refresh panels with adaptive sync technology command premium pricing through specialized GPU synchronization. Esports venues and streaming content creators in Austin and Seattle adopt 240Hz and 360Hz specifications where motion clarity determines competitive performance.
- Home Office:General productivity displays emphasize 24-inch to 27-inch screen sizes for residential space constraints. Remote knowledge workers in suburban markets prioritize USB-C connectivity for single-cable laptop docking.
- Educational:K-12 and higher education procurement emphasizes durability, anti-glare coatings, and standardized screen sizes for classroom density. School districts in California and Texas specify 24-inch panels for computer lab standardization and reduced IT support burden.
Volume concentration rests with Home Office. Steepest expansion trajectory belongs to Professional.
Screen Size:
Display diagonal determines panel yield rates, shipping logistics, and desk footprint constraints.
- 27-Inch:The productivity sweet spot balances pixel density with ergonomic viewing distance for spreadsheet and document work. Corporate refresh cycles in U.S. enterprise and Canadian government standardize on this dimension for cubicle and open-plan deployment.
- 32-Inch:Larger format panels support split-screen multitasking and video conferencing visibility without dual-monitor complexity. Software development teams and data science workstations in the Pacific Northwest specify 32-inch 4K panels for code review and visualization workflows.
- 24-Inch:Compact footprint suits educational computer labs, call center floor plans, and space-constrained home offices. School districts and BPO operations in Texas and Florida prioritize this dimension for density optimization.
- 43-Inch:Large-format displays serve conference room presentation and digital signage applications where visibility across meeting tables matters. Corporate headquarters and hospitality venues in major metropolitan markets adopt these for hybrid meeting equity.
Procurement volume clusters at 27-Inch. Premium expansion concentrates at 32-Inch.
Connectivity:
Physical interface standards determine cable ecosystem compatibility and docking station interoperability.
- HDMI:The consumer electronics standard dominates residential and hospitality procurement through universal source device compatibility. Home office and entertainment-focused buyers prioritize HDMI for gaming console and media player integration.
- USB-C:Single-cable video, data, and power delivery is displacing legacy multi-cable setups in enterprise environments. Corporate IT departments in tech-dense markets specify USB-C for reduced cable clutter and simplified hot-desking protocols.
- DisplayPort:PC-centric digital interface supports higher bandwidth for high-refresh and high-resolution panels. Gaming and professional workstation buyers specify DisplayPort for adaptive sync and multi-stream transport capabilities.
- VGA:Analog 15-pin connector persists in legacy industrial control, government, and education infrastructure where full system replacement is capital-constrained. Maintenance contracts and adapter procurement support remaining installed base.
Legacy deployment persists with VGA. Transition momentum concentrates in USB-C.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in Texas and Washington State concentrate enterprise procurement through state tax abatements tied to tech sector employment density. Federal CHIPS Act incentives further channel display-related R&D into designated semiconductor corridors.
United States
Healthcare digitization and financial trading floor upgrades drive DICOM-calibrated display procurement across hospital systems and investment banks. The EPA ENERGY STAR Version 8.1 specification tightens standby power limits for displays above 30 inches, forcing power supply redesigns. The Pacific Northwest corridor anchors premium ultrawide adoption for software development workflows.
Canada
Federal procurement standardization and provincial healthcare IT modernization sustain steady replacement cycles for color-accurate panels. Health Canada coordinates with the EPA on aligned efficiency benchmarks for cross-border product eligibility. Toronto and Vancouver post-production studios prioritize OLED panels for HDR mastering in film and television workflows.
Mexico
Nearshoring manufacturing investments and BPO sector expansion create demand for 24-inch to 27-inch productivity displays in call center and back-office operations. Mexican federal energy efficiency programs adopt ENERGY STAR-equivalent standards for imported electronics. The Bajío Region and Northern Border States concentrate assembly operations supplying North American distribution channels.
North America Computer Monitor Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price bands. Market structure shows moderate consolidation with enterprise direct sales displacing traditional distribution for contracts above 500 units. Three archetypes dominate: integrated workstation ecosystem providers, panel technology specialists, and enterprise direct-sales operators. Competitive moves center on docking-monitor bundle development and strategic partnerships with GPU vendors for adaptive sync certification.
Among diversified technology conglomerates, HP Inc., Dell Technologies Inc., and Samsung Group occupy distinct positioning vectors. HP exemplifies the integrated workstation-monitor ecosystem approach through bundled procurement reducing IT support overhead. Dell anchors enterprise direct-channel dominance with custom SKU development for tech-dense corridors. Samsung represents panel technology verticalization supplying high-refresh components to gaming peripheral integrators seeking display-PC bundle partnerships.
| Leading Market Players |
|---|
| HP Inc. |
| Dell Technologies Inc. |
| Lenovo Group Limited |
| Samsung Group |
| Apple Inc. |
| LG Electronics Inc. |
| Acer Inc. |
| AsusTek Computer Inc. |
| ViewSonic Corporation |
| Others |
Value Network & Pricing Analysis
Glass substrate and rare-earth phosphor costs from Taiwanese and Korean manufacturing clusters flow downstream through panel assemblers into three-tier pricing structures across premium, standard, and economy levels. OLED panels absorb the steepest input volatility, while LED volume production spreads fixed costs across enterprise procurement contracts in Texas and the Pacific Northwest.
Pricing Analysis
Cost-down pressure on mid-tier LED panels accelerates because glass substrate yield rates fluctuate with energy costs in Korean foundries. Three-tier pricing structure across premium, standard, and economy levels separates DICOM-calibrated medical displays from general office panels and entry-level educational units. Certification tier under EPA ENERGY STAR Version 8.1 creates price premiums for displays above 30 inches. Educational procurement in California and Texas shows highest price sensitivity, while healthcare radiology departments prioritize diagnostic accuracy over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Dell and HP enterprise procurement teams mandate qualified panel suppliers in both Taiwan and South Korea to mitigate single-source vulnerability. Display manufacturing draws from glass substrates produced in Korean and Taiwanese clusters, driver ICs from Chinese packaging facilities, and rare-earth phosphors processed in Japanese chemical plants. Tariff exposure on Chinese-assembled components creates margin unpredictability for brands without captive upstream capacity. Distribution runs through direct enterprise sales channels displacing traditional IT distribution for contracts above 500 units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Computer Monitor Market sits in an active transition from LED to OLED dominance as creative professionals and healthcare diagnosticians prioritize infinite contrast ratios and true black levels for HDR workflows.
For Market Incumbents: Lock in enterprise direct-channel relationships through custom SKU development for tech-dense corridors like Austin and Seattle. Secure backward integration into panel supply through strategic partnerships with Korean and Taiwanese foundries to defend against input cost volatility. Prioritize DICOM calibration certification for healthcare verticals where radiology digitization accelerates replacement cycles. For New Entrants and Emerging Players: Launch via USB-C docking-monitor bundle partnerships targeting remote knowledge workers in suburban markets seeking single-cable laptop connectivity. White-space opportunity concentrates in AI-assisted display calibration hardware for multi-monitor arrays in software development workflows. Avoid direct competition with Dell and HP in enterprise contracts above 500 units; instead target creative professional segments through direct-to-creator channels. For Investors and Strategic Acquirers: New York's Digital Fair Repair Act enforcement is the leading indicator that modular component suppliers and third-party maintenance networks will capture value from extended product lifecycles. Acquisition target archetype: specialized colorimeter hardware firms with on-device machine learning calibration capabilities. Long-term viability hinges on positioning for right-to-repair legislative expansion across additional states.| Strategic Initiative | Industry Significance |
|---|---|
| Mini-LED Backlighting Modularization | Compresses HDR performance into mid-tier price bands for financial services IT departments. |
| USB-C Docking-Monitor Bundle Development | Reduces cable clutter and IT support tickets in Pacific Northwest tech corridor deployments. |
| OLED Burn-in Warranty Extension | Defends premium positioning against Mini-LED encroachment in post-production studio segments. |
| AI-Assisted Display Calibration | Enables automated white-point matching across multi-monitor arrays for data science workflows. |
| Right-to-Repair Modular Design | Creates competitive differentiation under New York's Digital Fair Repair Act compliance requirements. |
Research Methodology
Multi-period observation of panel technology adoption curves, ENERGY STAR certification timelines, and enterprise procurement cycle compression anchored the trend analysis, supplemented by interviews with display technology product managers, hospital biomedical engineers, corporate IT procurement officers, and post-production facility technical directors. Secondary validation drew from EPA ENERGY STAR specification documents, FCC electromagnetic interference filings, California SB-20 e-waste directive implementation records, and SEC 10-K disclosures from diversified technology conglomerates. Bottom-up shipment estimates by panel technology and screen size triangulated against top-down enterprise IT spending surveys.
Segment-weighting across product type, usage category, screen size, and connectivity standard determined value allocation throughout the forecast period. CAGRs were derived from fitted growth curves applied to historical procurement patterns and projected replacement cycle acceleration in healthcare and finance verticals. Forecast inputs incorporated panel yield rate assumptions from Korean and Taiwanese manufacturing clusters and state-level right-to-repair legislative adoption timelines.
Panel input cost volatility, FCC certification timeline delays, and smartphone substitution rates for mobile-first knowledge workers are the dominant revision risks to the outlook. Deviation in glass substrate energy cost trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Portable Video Wall Market
Display Technologies
Low Power Next Generation Display Market
Display Technologies
Global Display Market
Display Technologies
Head-Mounted Display Market
Display Technologies
Global OLED Market
Display Technologies
Video Projector Market
Display Technologies
Collaboration Display Market
Display Technologies
Interactive Display Market
Display Technologies
Microdisplay Market
Display Technologies
OLED Panel Market
Display Technologies
Global Wearable Display Market
Display Technologies
Electronic Display Market
Display Technologies
Display Glass Substrate Market
Display Technologies
Automotive LCD Display Market
Display Technologies
Backlit Displays Market
Display Technologies
Foldable Display Market