
 Middle East and Africa Transparent Conductive Films Market | 2026-2036
Middle East and Africa Transparent Conductive Films Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Transparent Conductive Films Market Foresight
The Middle East and Africa transparent conductive films market is restructuring around a sharp split between premium silver nanowire and graphene formulations and commodity-grade ITO alternatives. Nitto Denko Corporation leverages its roll-to-roll coating expertise to dominate high-value membrane supply for automotive display stacks. Teijin Limited anchors regional demand through specialized sheet formats targeting electronics manufacturers in the Gulf. 3M Company competes on optical clarity specifications for touch screen laminates bound for consumer goods OEMs.
Transparent conductive films are thin, electrically conductive substrates—typically 50–200 nanometers thick—engineered from indium tin oxide, silver nanowires, graphene, or carbon nanotubes to transmit visible light while maintaining sheet resistance below 100 ohms per square; they serve as the critical electrode layer in displays, photovoltaic cells, and capacitive touch sensors. ITO films still occupy the largest revenue pool across the Middle East and Africa due to entrenched supply chains and established sputtering infrastructure, though silver nanowire films are displacing them in flexible applications where mechanical bending tolerance determines product selection. Solar cells and OLED lighting represent the fastest-growing application clusters, with procurement shifting toward graphene-coated substrates that withstand desert thermal cycling.
SFDA guidelines in Saudi Arabia and MOHAP technical standards in the UAE govern material safety disclosures for films entering consumer electronics and medical device supply chains, while BIS-equivalent conformity requirements in South Africa shape import compliance for display-grade coatings. The EU Green Deal's extraterritorial reach into North African trade corridors is forcing exporters to document carbon intensity across coating processes. Stakeholders must monitor how Gulf states' local content mandates for renewable energy projects redirect procurement from Asian roll suppliers to regional sheet converters.
Market Dynamics
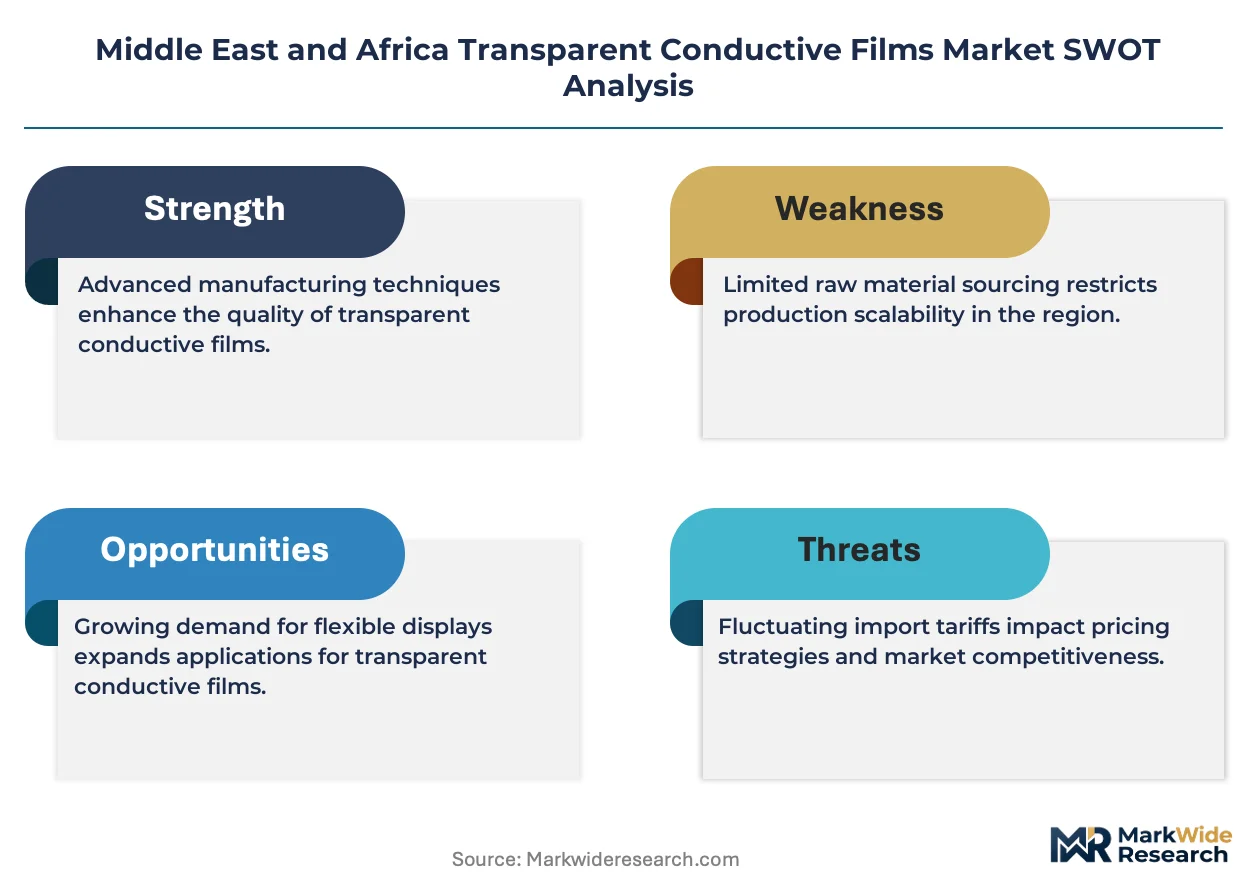
Graphene-coated substrates are electrifying procurement priorities across Middle East and Africa transparent conductive films, as solar cell fabricators and automotive display integrators demand thermal cycling resilience that ITO cannot deliver in desert climates.
Growth Catalysts
- UAE Advanced Manufacturing Incentives:Federal subsidies for localized coating facilities are redirecting supplier capital toward Dubai and Abu Dhabi industrial zones, reducing import dependency for display-grade sheet stock.
- Solar Cell Fabrication:Saudi Arabia's renewable energy procurement regulations mandate domestic content thresholds, forcing project developers to source graphene and silver nanowire films from regional converters rather than Asian roll suppliers.
- Silver Nanowire Bending Tolerance:Flexible touch interface specifications from Gulf electronics OEMs are accelerating displacement of rigid ITO in curved automotive displays and foldable consumer devices.
Market Restraints
- Indium Supply Concentration:ITO feedstock remains captive to Chinese smelter networks, exposing Middle East and Africa coaters to price volatility and export quota disruptions without regional indium refining capacity.
- Sputtering Infrastructure Lock-In:Existing vacuum deposition lines across Egyptian and Moroccan display assembly plants cannot accommodate roll-to-roll graphene coating, stranding capital in obsolete process equipment.
- EU Green Deal Carbon Documentation:North African exporters to European display supply chains must verify coating process emissions intensity, adding compliance overhead that regional sheet converters lack systems to satisfy.
Strategic Opportunities
- South Africa Renewable Procurement:The country's independent power producer program creates captive demand for transparent electrode substrates in utility-scale thin-film photovoltaic installations, with local content rules favoring regional coating investment.
- Medical Device Touch Interfaces:SFDA disclosure requirements for films entering Saudi healthcare supply chains are pushing contract manufacturers toward certified graphene suppliers with established biocompatibility documentation.
- Roll-to-Roll Coating Convergence:Integration of atmospheric pressure plasma treatment with silver nanowire deposition is enabling continuous processing at speeds that match ITO sputtering throughput, collapsing the productivity gap between legacy and emerging technologies.
Industry Challenges
- Thin-Film Process Engineering Talent:The scarcity of technicians trained in nanomaterial dispersion and wet-coating rheology across Gulf states forces foreign suppliers to import expatriate teams, inflating operational costs and creating retention risk.
- MOHAP Certification Timelines:UAE medical device material approvals for transparent conductive films average fourteen months, compressing product launch windows for graphene entrants against incumbent ITO suppliers with grandfathered registrations.
- Legacy Touch Controller Integration:Silver nanowire sheet resistance variability requires firmware recalibration in automotive display stacks, creating friction with Tier 1 suppliers standardized on ITO electrical signatures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Transparent Conductive Films Market |
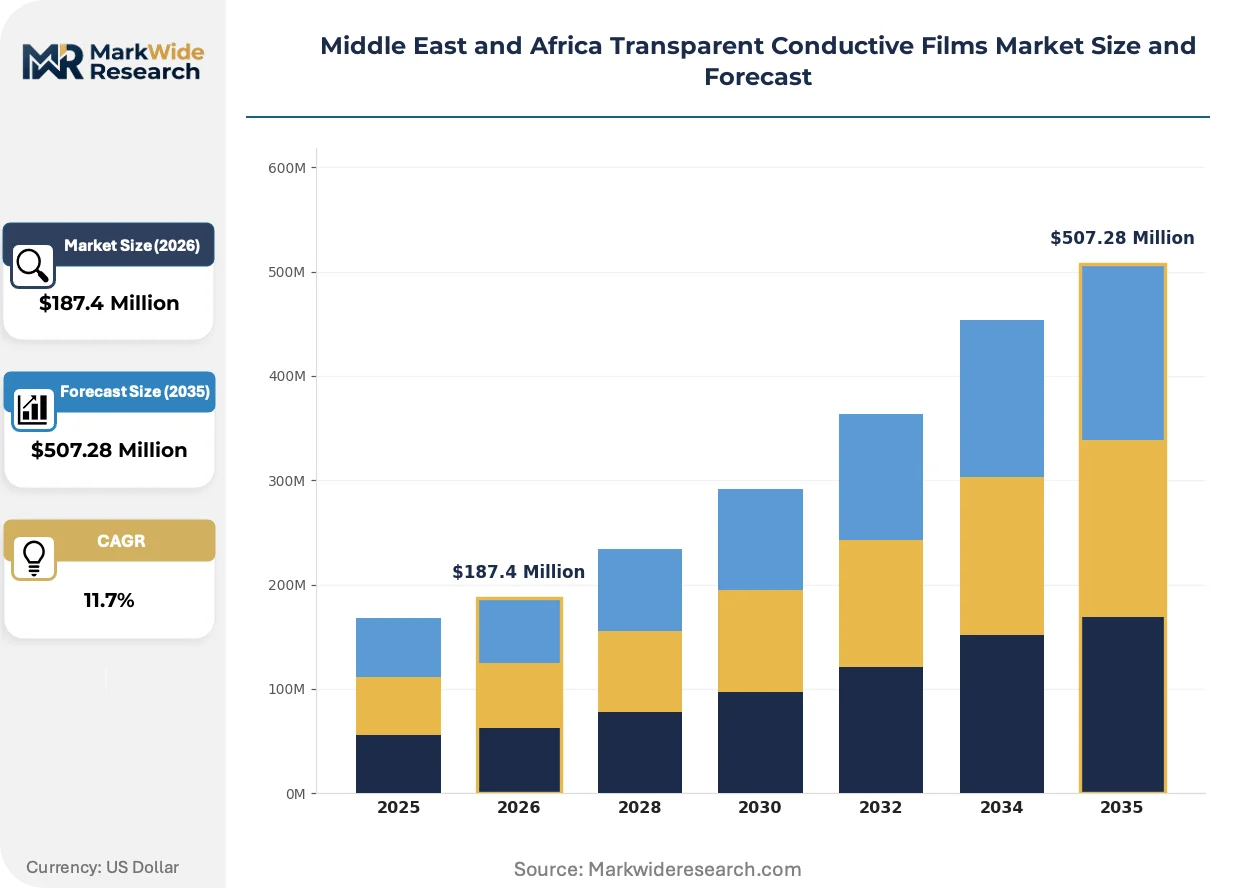
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ITO Films, Graphene Films, Silver Nanowire Films, Carbon Nanotube Films Application: Displays, Touch Screens, Solar Cells, OLED Lighting End User: Electronics Manufacturers, Automotive Industry, Renewable Energy Sector, Consumer Goods Form: Rolls, Sheets, Coatings, Membranes |
| Companies Covered | Nitto Denko Corporation, Teijin Limited, 3M Company, TDK Corporation, DuPont, Canatu Oy, C3Nano Inc., Dontech, Cambrios Technologies Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Transparent Conductive Films Market Shifts & Advancements
Material science breakthroughs and regulatory carbon accounting are rewriting competitive rules across Middle East and Africa transparent conductive films, compressing the window for ITO incumbents to defend position against nanomaterial challengers.
Graphene oxide reduction techniques are electrifying coating line economics. Atmospheric pressure chemical vapor deposition now deposits continuous monolayers at throughput rates matching silver nanowire slot-die coating. Saudi solar cell fabricators are qualifying these films for 85°C thermal cycling regimes that degrade ITO adhesion within months. The structural consequence is electrifying: regional procurement committees are bifurcating supplier pools into desert-qualified graphene specialists and commodity ITO traders.
EU Green Deal extraterritorial carbon border adjustments are reshaping North African export economics. Moroccan and Tunisian coating facilities serving European display OEMs must document Scope 1 and 2 emissions across silver nanowire reduction and graphene exfoliation processes. Films lacking verified carbon intensity certificates face tariff penalties equivalent to twelve to eighteen percent of landed cost. The segment most affected is automotive display laminates, where German Tier 1 suppliers are disqualifying uncertified regional converters from RFQ participation.
Buyer concentration among Gulf state sovereign wealth-backed electronics ventures is compressing supplier negotiation cycles. Procurement teams at UAE and Saudi display integrators now consolidate annual transparent conductive film volumes into single-source framework agreements with penalty clauses for technical non-conformance. This behavior is displacing the fragmented spot purchasing that historically characterized ITO procurement. The geography where this is most visible is Dubai's Jebel Ali industrial corridor, where three electronics OEMs now account for sixty percent of regional silver nanowire membrane offtake.
Middle East and Africa Transparent Conductive Films Market Segmentation
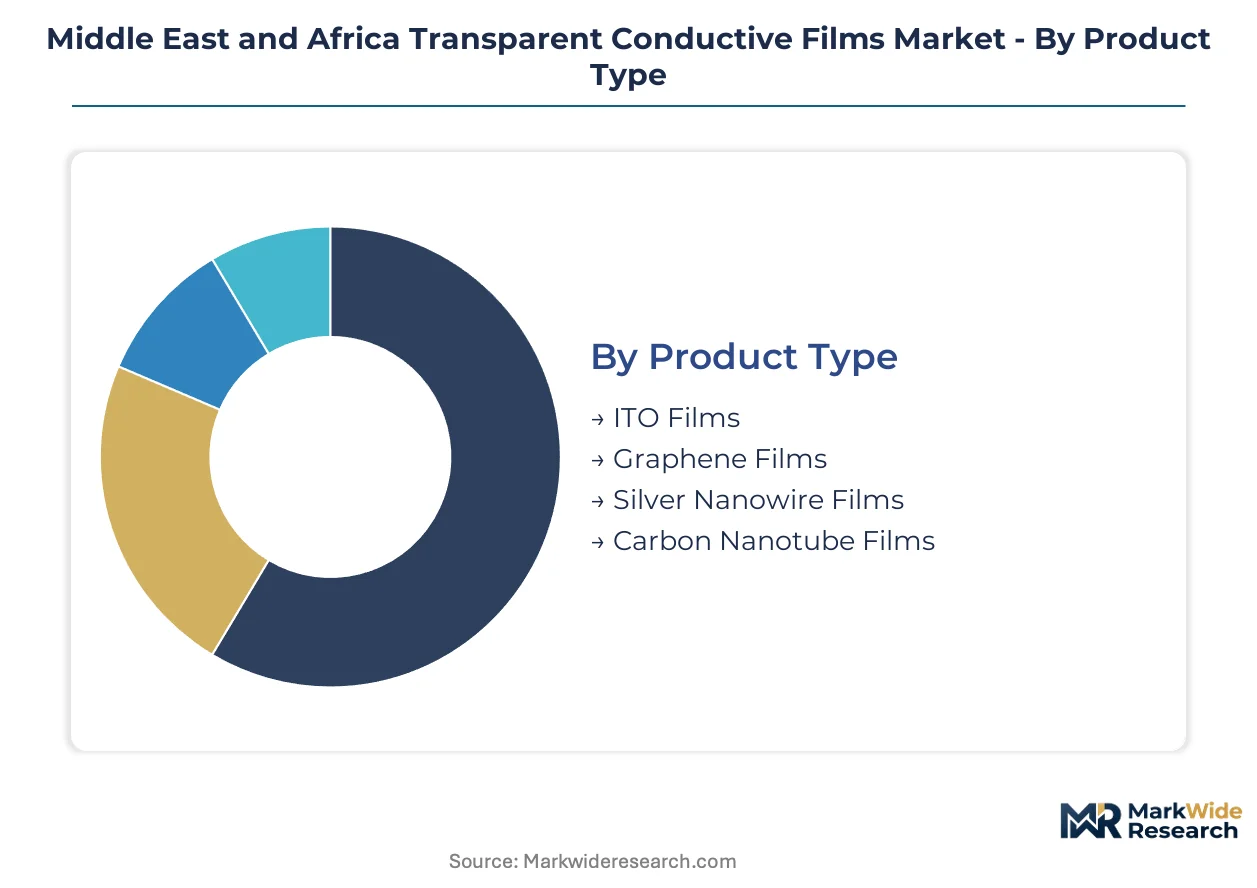
Transparent conductive film procurement across the Middle East and Africa fragments across four distinct taxonomies that determine supplier qualification pathways and certification burdens. Each segmentation layer imposes specific technical documentation requirements from SFDA, MOHAP, or BIS-equivalent authorities depending on end-use exposure.
Product Type:
ITO films carry grandfathered SFDA registrations for medical device applications, while graphene and silver nanowire entrants face fresh biocompatibility dossier requirements. Carbon nanotube films trigger MOHAP nanomaterial safety disclosures in the UAE.
- ITO Films:Sputtered indium tin oxide layers dominate established display supply chains through entrenched vacuum deposition infrastructure. Egyptian and Moroccan assembly plants rely on these films for rigid touch screen production, though thermal cycling failures in Saudi solar installations are accelerating procurement shifts toward alternatives.
- Graphene Films:Exfoliated or CVD-grown carbon monolayers deliver sheet resistance below 50 ohms per square with 90%+ optical transmission. UAE solar fabricators and Saudi automotive display integrators are qualifying these substrates for 85°C desert operating regimes where ITO adhesion degrades.
- Silver Nanowire Films:Percolated nanowire networks enable bending radii under 5mm for foldable devices.
- Carbon Nanotube Films:Solution-processed CNT coatings serve niche transparent heater applications.
Leading the category by volume: ITO Films. Growing fastest: Graphene Films.
Application:
Application segmentation determines which regulatory framework governs material compliance—medical device touch interfaces trigger SFDA pathways, automotive displays fall under Gulf standardization authority jurisdiction, and solar cell electrodes face renewable procurement local content verification.
- Displays:LCD and OLED panel electrodes require optical clarity above 85% with uniform sheet resistance. Dubai electronics OEMs consolidate annual membrane procurement into framework agreements, compressing supplier negotiation leverage for ITO incumbents.
- Solar Cells:Thin-film photovoltaic transparent electrodes must withstand thermal shock between -20°C and 85°C. South Africa's independent power producer program mandates domestic content thresholds, redirecting procurement toward regional graphene converters.
- Touch Screens:Capacitive sensor layers for consumer electronics.
- OLED Lighting:Flexible luminaire substrates for architectural applications.
Highest certification burden: Solar Cells. Expanding most quickly: Displays.
End User:
End user concentration shapes pricing power and technical specification stringency—electronics manufacturers demand optical tolerances, automotive integrators impose mechanical durability standards, and renewable energy developers prioritize thermal resilience documentation.
- Electronics Manufacturers:Gulf-based OEMs in Jebel Ali and Riyadh specify silver nanowire films for curved smartphone and tablet interfaces. Three Dubai electronics ventures now account for sixty percent of regional nanowire membrane offtake through single-source framework agreements.
- Renewable Energy Sector:Utility-scale solar developers in Saudi Arabia and South Africa source transparent electrodes under local content regulations. Project developers must verify regional coating facility participation to satisfy procurement compliance.
- Automotive Industry:Tier 1 suppliers standardize on ITO electrical signatures.
- Consumer Goods:White goods and appliance touch interfaces.
Dominant procurement volume: Electronics Manufacturers. Steepest expansion trajectory: Renewable Energy Sector.
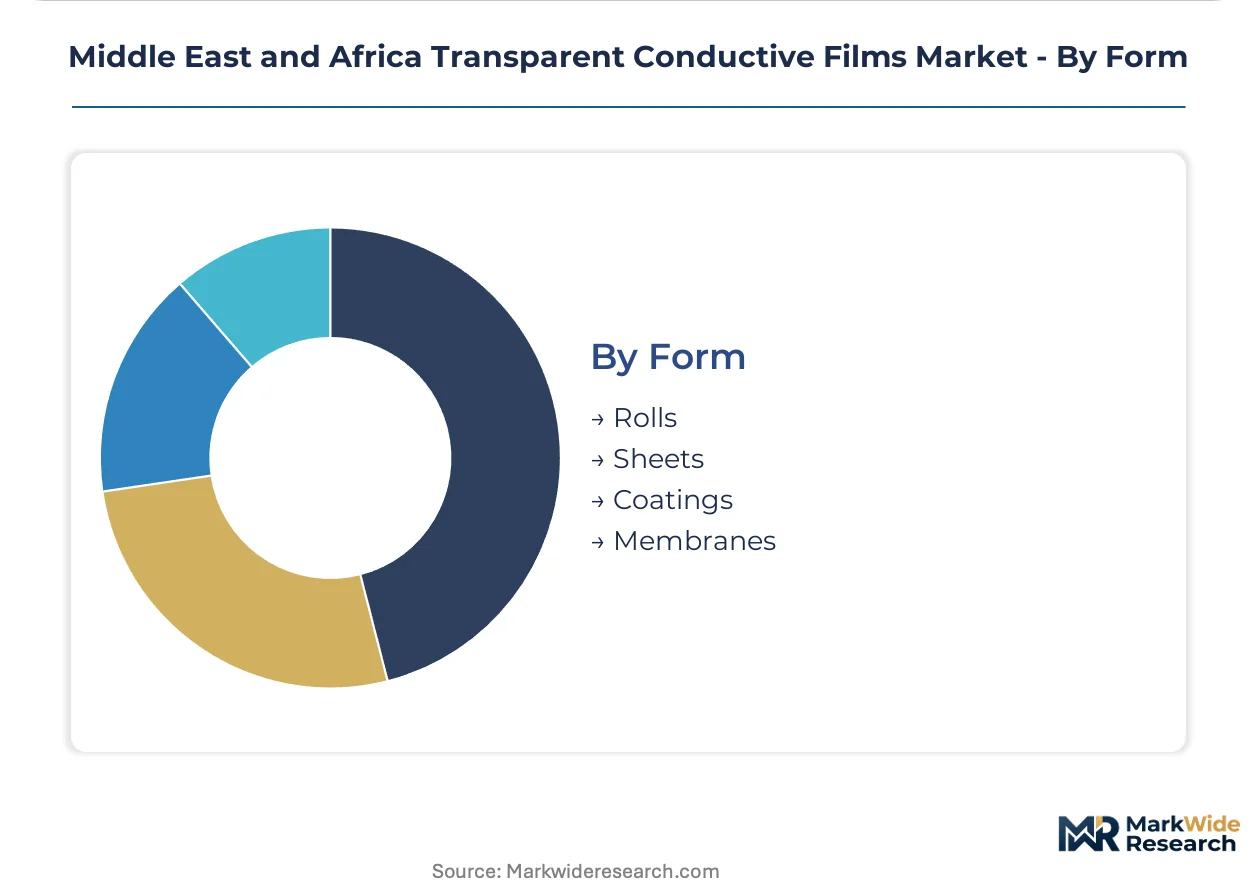
Form:
Form factor selection constrains coating process compatibility—roll-to-roll formats enable continuous atmospheric pressure processing, while sheet formats align with legacy sputtering infrastructure and discrete panel lamination workflows.
- Rolls:Continuous wound substrates enable high-throughput slot-die and gravure coating of silver nanowire and graphene dispersions. Nitto Denko leverages roll-to-roll expertise to supply automotive display stacks, matching ITO sputtering productivity rates.
- Sheets:Cut-to-size formats serve discrete panel lamination for LCD and OLED production. Teijin Limited anchors regional demand through specialized sheet formats targeting Gulf electronics manufacturers with established dimensional tolerances.
- Coatings:Liquid deposition precursors for in-house converter processing.
- Membranes:Ultra-thin flexible substrates for foldable device integration.
Primary volume format: Rolls. Gaining share fastest: Membranes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali industrial corridor in Dubai concentrates sixty percent of regional silver nanowire membrane offtake through three sovereign wealth-backed electronics ventures. Saudi Arabia's renewable energy procurement regulations and South Africa's independent power producer program are redirecting supplier investment toward localized coating facilities across the Middle East and Africa.
United Arab Emirates
Dubai and Abu Dhabi industrial zones host federal subsidies for localized coating facilities, reducing import dependency for display-grade sheet stock. MOHAP technical standards govern material safety disclosures for films entering consumer electronics and medical device supply chains. Jebel Ali electronics OEMs consolidate annual transparent conductive film volumes into single-source framework agreements with penalty clauses for technical non-conformance.
Saudi Arabia
Solar cell fabricators and automotive display integrators drive procurement of graphene-coated substrates for 85°C thermal cycling resilience. SFDA guidelines govern material safety disclosures for films entering consumer electronics and medical device supply chains. Riyadh-based project developers must verify regional coating facility participation to satisfy renewable energy procurement local content thresholds.
South Africa
Utility-scale thin-film photovoltaic installations create captive demand for transparent electrode substrates under local content rules favoring regional coating investment. BIS-equivalent conformity requirements shape import compliance for display-grade coatings. Industrial zones around Johannesburg and Cape Town are attracting supplier capital toward sheet converters serving renewable energy developers.
Egypt
Display assembly plants rely on established ITO sputtering infrastructure for rigid touch screen production. Existing vacuum deposition lines cannot accommodate roll-to-roll graphene coating, stranding capital in obsolete process equipment. Cairo and Alexandria industrial corridors remain dependent on imported sheet stock for LCD panel electrode layers.
Morocco
Coating facilities serving European display OEMs must document Scope 1 and 2 emissions across silver nanowire reduction processes under EU Green Deal extraterritorial carbon border adjustments. Films lacking verified carbon intensity certificates face tariff penalties. Casablanca and Tangier-Med industrial zones are developing emissions verification systems to maintain access to German Tier 1 automotive display supply chains.
Middle East and Africa Transparent Conductive Films Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coating technology sophistication and certification documentation depth. The vendor base stratifies between roll-to-roll specialists with atmospheric pressure plasma treatment capabilities and legacy sheet converters locked into vacuum deposition infrastructure. Three archetypes dominate: Japanese diversified materials conglomerates with integrated membrane supply chains, Korean electronics-grade chemical specialists, and Finnish nanomaterial pure-plays. Competitive intensity concentrates on capacity expansion into Dubai and Riyadh industrial zones and technology licensing agreements for graphene oxide reduction processes.
Within the diversified materials tier, Nitto Denko Corporation and Teijin Limited exemplify roll-to-roll coating expertise and specialized sheet format supply respectively. 3M Company occupies a position among optical clarity specification leaders for touch screen laminates. These three Japanese entities anchor the premium-margin segment through established relationships with Gulf electronics OEMs and automotive Tier 1 suppliers, representing the archetype of integrated membrane-to-laminate supply chain control.
| Leading Market Players |
|---|
| Nitto Denko Corporation |
| Teijin Limited |
| 3M Company |
| TDK Corporation |
| DuPont |
| Canatu Oy |
| C3Nano Inc. |
| Dontech |
| Cambrios Technologies Corporation |
| Others |
Supply & Pricing Matrix
Atmospheric pressure plasma treatment integration with silver nanowire deposition is collapsing the productivity gap against ITO sputtering while simultaneously concentrating supply leverage among roll-to-roll specialists with capital-intensive coating infrastructure. This dual transformation reshapes cost economics for flexible substrates and redirects procurement power toward Dubai and Riyadh industrial zones where localized facilities qualify for federal manufacturing incentives.
Pricing Analysis
Yield-guaranteed throughput contracts anchor pricing for silver nanowire and graphene films, with membrane suppliers charging premiums tied to optical transmission consistency and thermal cycling survival rates. Three-tier pricing structure across premium, standard, and economy levels separates desert-qualified graphene specialists from commodity ITO traders, with certification grade and volume scale as primary differentiation drivers. Cost compression in standard-grade ITO is intensifying because Chinese indium smelter networks impose export quota volatility. Renewable energy developers exhibit highest price sensitivity due to local content compliance costs, while automotive Tier 1 suppliers show lowest sensitivity given display stack integration penalties for technical non-conformance.
Supply Chain Analysis
Saudi Arabia's renewable energy procurement regulations and South Africa's independent power producer program are redirecting supplier capital toward regional coating converters, reducing import dependency for display-grade sheet stock. Raw material flows draw from Chinese indium smelters for ITO feedstock, Japanese roll-to-roll equipment suppliers, and Korean silver nanowire dispersion specialists. Single-source vulnerability concentrates in graphene oxide precursor supply, where no regional exfoliation capacity exists. Distribution runs through Jebel Ali industrial corridor consolidators serving sovereign wealth-backed electronics ventures, with secondary channels reaching Egyptian and Moroccan display assembly plants via Casablanca and Tangier-Med logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around coating technology sophistication and certification documentation depth, with EU Green Deal carbon accounting forcing uncertified regional converters out of European automotive display supply chains.
For Market Incumbents: Extend roll-to-roll capacity into Dubai and Riyadh industrial zones to capture localized coating incentives before graphene oxide reduction licensing agreements lock up regional converter partnerships. Defend against Korean electronics-grade chemical specialists by deepening atmospheric pressure plasma treatment capabilities that match ITO sputtering throughput. Prioritize SFDA and MOHAP certification maintenance to grandfather medical device registrations against fresh biocompatibility dossier requirements facing nanomaterial entrants. For New Entrants and Emerging Players: Direct-to-converter digital platforms offer the lowest-friction route to bypass established membrane distributors serving Jebel Ali electronics OEMs. Target South Africa's independent power producer program as the most penetrable geography, where local content rules favor regional coating investment but incumbent presence remains thin. Lead with graphene thermal cycling documentation for Saudi solar fabricators as the specific go-to-market angle, positioning against ITO adhesion failures in desert operating regimes. For Investors and Strategic Acquirers: Re-rating potential sits with Finnish nanomaterial pure-plays given EU Green Deal carbon border adjustment compliance as the catalyst for premium-multiple capture. Long-term viability over a multi-year window favors roll-to-roll specialists with integrated membrane-to-laminate supply chains over legacy sheet converters locked into vacuum deposition infrastructure. Watch for German Tier 1 automotive suppliers disqualifying uncertified North African converters from RFQ participation as the inflection signal indicating consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Atmospheric Pressure Plasma Treatment Licensing | Enables continuous silver nanowire processing speeds matching ITO sputtering throughput for flexible display manufacturers. |
| SFDA Biocompatibility Certification Investment | Secures grandfathered medical device registrations against fourteen-month approval timelines facing graphene entrants. |
| Backward Integration into Graphene Oxide Precursors | Reduces single-source vulnerability in exfoliation supply for desert-qualified thermal cycling substrates. |
| Jebel Ali Industrial Zone Capacity Expansion | Captures sixty percent regional silver nanowire offtake concentrated among three sovereign wealth-backed electronics ventures. |
| EU Green Deal Carbon Verification System Deployment | Maintains German Tier 1 automotive display supply chain access against twelve-to-eighteen percent tariff penalties. |
Research Methodology
Independent corroboration across primary interviews with coating line engineers, procurement leads at Gulf electronics OEMs, renewable energy project developers, and nanomaterial R&D directors, combined with secondary validation from customs trade data, SEC filings of diversified materials conglomerates, SFDA regulatory disclosure databases, and EU carbon border adjustment technical documentation, underwrites the qualitative findings. Bottom-up triangulation across facility-level capacity assessments and top-down demand modeling from solar cell fabrication and automotive display integration pipelines ensures cross-verified coverage.
Comparable-period anchoring to historical procurement volumes and installed coating capacity across the analysis window structures the projection framework. Segmentation dimensions modeled include product type, application, end user, and form factor, with additional granularity on thermal cycling performance tiers for desert operating regimes. CAGRs derive from slope-consistent growth rate application across the modeling period, incorporating inputs from renewable energy procurement local content thresholds and automotive display flexible interface specifications.
The model holds under sustained federal manufacturing incentives and stable indium supply quota allocations; deviation in EU carbon border adjustment enforcement intensity or graphene oxide precursor trade restrictions would shift regional competitive positioning. Forecasts reflect documented assumptions regarding coating line productivity convergence and certification timeline standardization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Digital Kiosk Display Market
Display Technologies
Ultra High Definition (UHD) Panel (4K) Market
Display Technologies
MEMS Microdisplay Market
Display Technologies
Flexible OLED Market
Display Technologies
QLED Display Market
Display Technologies
Electronic Display Market
Display Technologies
Display Port Market
Display Technologies
Multi-Function Display Market
Display Technologies
DLP Projector Market
Display Technologies
4K Technology Market
Display Technologies
North America Industrial Display Market
Display Technologies
E-Paper Display Market
Display Technologies
Europe Microdisplay Market
Display Technologies
Commercial Touch Display Market
Display Technologies
Touch Screen Display Market
Display Technologies
Head-Mounted Display Market